
 Global Acrylic Fibers Market | 2026-2036
Global Acrylic Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acrylic Fibers Market Foresight
Polymer engineering talent is bifurcating between legacy wet-spinning operations and advanced gel-spinning facilities, creating a two-speed labor market across major production bases. Aksa Akrilik Kimya Sanayii A.S. anchors Turkey's export-oriented acrylic fiber complex through integrated acrylonitrile-to-yarn operations. Dralon GmbH leverages German process engineering to sustain premium modacrylic output for protective clothing applications. Sinopec dominates captive feedstock access across its Chinese acrylic fiber network, competing on scale rather than specialty grades.
Acrylic fibers are synthetic polymers composed primarily of acrylonitrile monomer units, typically manufactured through wet spinning or dry spinning processes to achieve deniers between 1.5 and 15 for textile applications, prized for wool-like hand feel and colorfastness in apparel and furnishing end uses. Modacrylic variants containing 35-85% acrylonitrile deliver inherent flame resistance without halogenated additives, positioning this segment at the premium margin pool as protective clothing procurement tightens. Standard acrylic occupies the volume leadership position across textile fabrics and home furnishings, though bi-component fibers are gaining share in carpet backing where dimensional stability commands pricing power. Wet spinning technology leads installed capacity globally, while gel spinning remains confined to ultra-high-performance applications with limited throughput scaling.
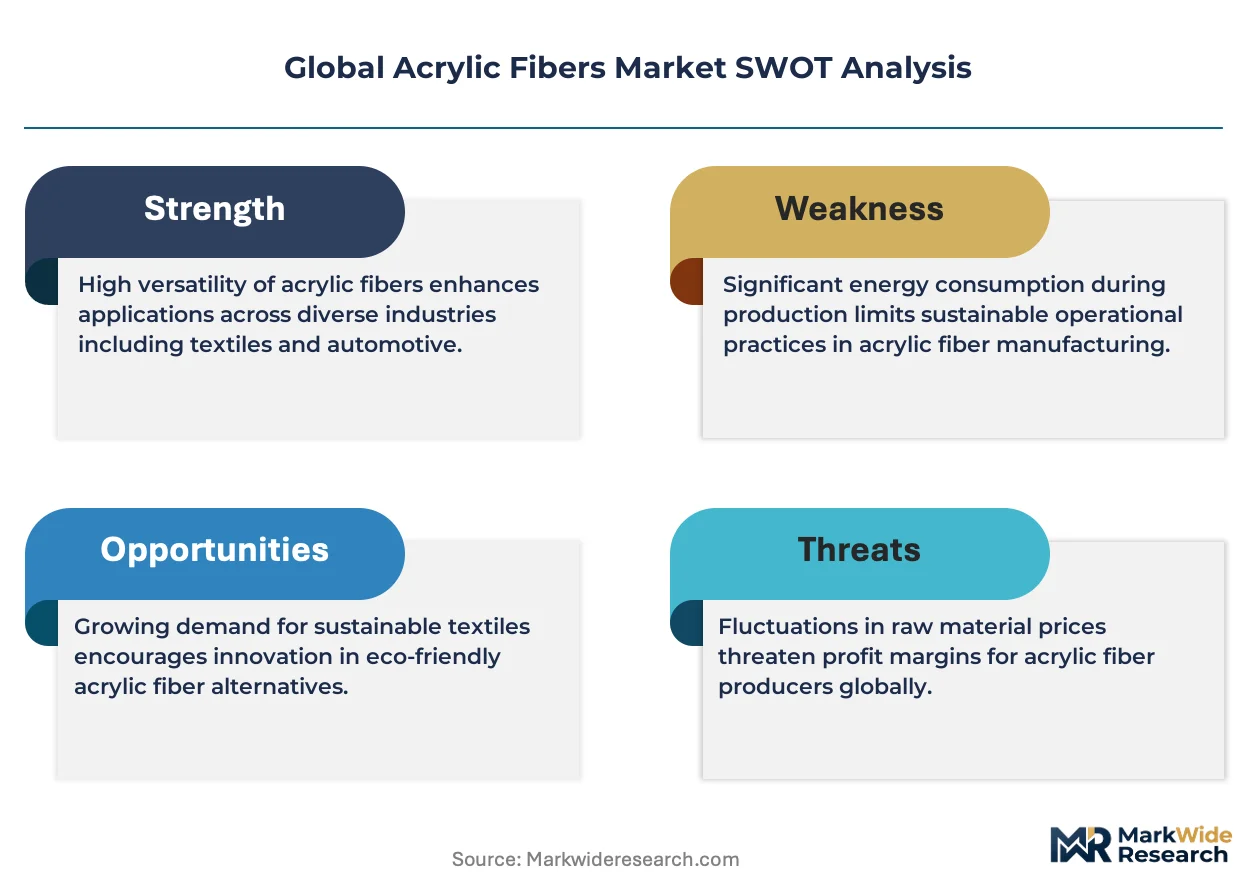
ECHA's REACH restrictions on acrylonitrile handling and residual monomer thresholds directly elevate compliance costs for European acrylic fiber producers, compressing margins on standard grades. China's MEE enforces wastewater discharge standards that force solvent recovery investments at wet-spinning plants, particularly around the Yangtze River Delta manufacturing cluster. Stakeholders must monitor regulatory divergence between EU chemical safety frameworks and China's dual carbon enforcement pathways, as misaligned compliance timelines threaten cross-border supply continuity for modacrylic and standard acrylic alike.
Market Dynamics
Flame-resistant modacrylic specifications are tightening procurement standards across industrial protective clothing, forcing fiber producers to certify against diverging national safety protocols while standard acrylic margins compress from feedstock volatility.
Growth Catalysts
- Industrial PPE Mandates:OSHA enforcement of flame-resistant clothing standards in US oilfield and electrical utility sectors is accelerating modacrylic uptake for inherent thermal protection without chemical additives.
- REACH Chemical Compliance:ECHA's residual monomer thresholds for acrylonitrile handling are pushing European producers toward closed-loop solvent recovery, inadvertently favoring larger integrated operations with capital for environmental controls.
- Bi-component Carpet Backing:Gel-spun sheath-core constructions delivering dimensional stability under humidity cycling are capturing specification share from bulked continuous filament in commercial flooring installations.
Market Restraints
- Acrylonitrile Price Volatility:Propylene-ammonia feedstock cost swings transmit directly to acrylic fiber margin structures, squeezing non-integrated spinners without captive acrylonitrile supply.
- Wet-Spinning Capacity Concentration:Legacy solvent-based production clusters in China's Yangtze River Delta face MEE wastewater discharge enforcement that threatens regional supply continuity during environmental inspection campaigns.
- Polyester Substitution in Apparel:Improved PET microfiber hand-feel engineering and lower unit economics are displacing standard acrylic in mid-market sweater and fleece applications.
Strategic Opportunities
- Mexico Nearshoring Corridor:Apparel manufacturers serving US retailers are relocating cut-and-sew operations, creating demand for acrylic yarn supply within USMCA tariff-preferred territory.
- EU Green Deal Procurement:Public sector protective clothing tenders incorporating lifecycle carbon thresholds favor modacrylic's inherent flame resistance over halogenated cotton treatments requiring chemical-intensive finishing.
- Digital Textile Printing Compatibility:Cationic-dyeable acrylic variants engineered for inkjet receptivity are opening specification channels in short-run fashion and customized furnishing fabrics.
Industry Challenges
- Gel-Spinning Talent Scarcity:Polymer engineering expertise for ultra-high-molecular-weight fiber production remains concentrated at a handful of research-intensive facilities, constraining capacity expansion for performance grades.
- Cross-Border Certification Timelines:Divergent flame-resistance testing protocols between NFPA 2112 in North America and EN ISO 14116 in Europe extend product validation cycles for protective clothing exporters.
- Solvent Recovery Capital Intensity:Wet-spinning plants require significant infrastructure investment for dimethylformamide capture and purification to meet tightening MEE and REACH discharge standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acrylic Fibers Market |
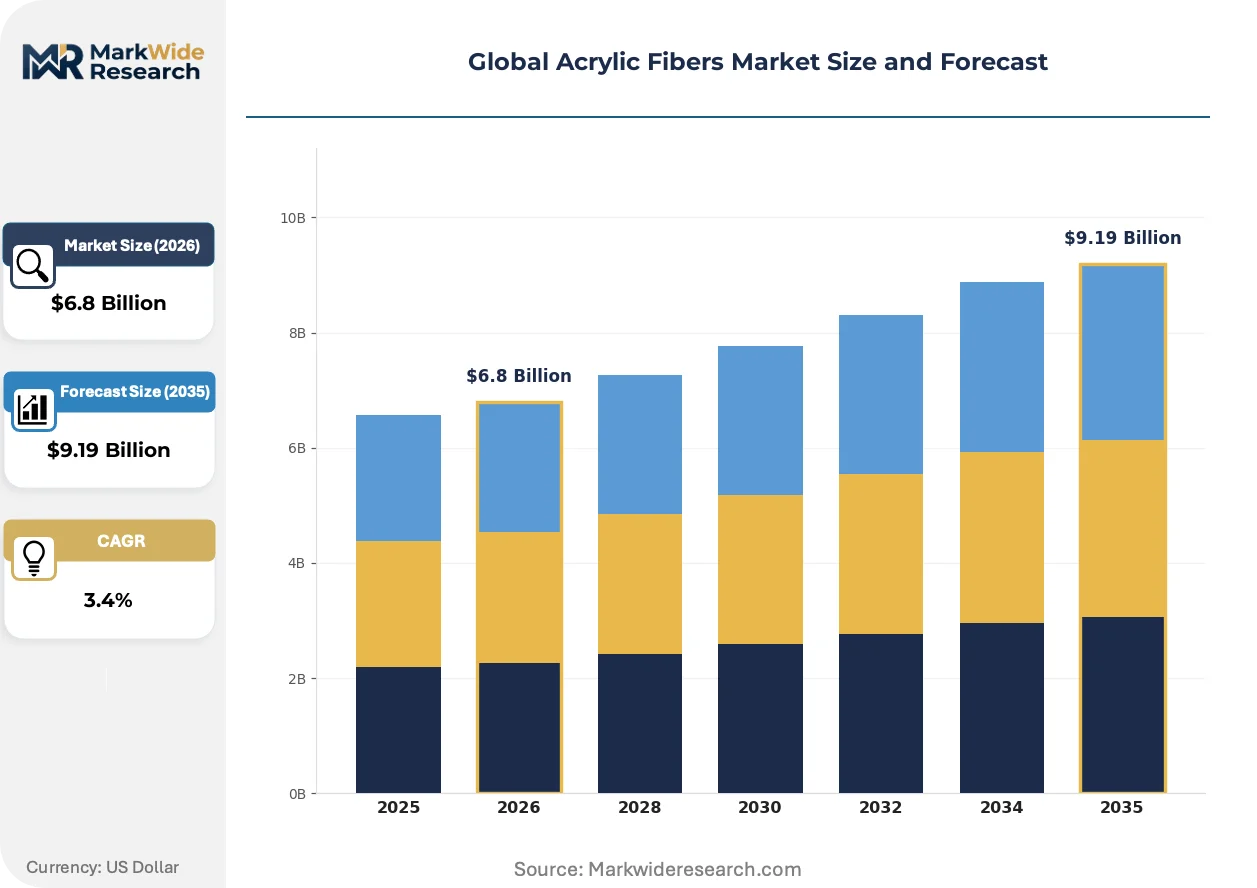
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Acrylic, Modacrylic, Carbon Fiber Reinforced, Ultra-Fine, Bi-Component, Cellulose Acetate Technology: Wet Spinning, Dry Spinning, Gel Spinning, Electrospinning, Melt Spinning, Solution Spinning Application: Textile Fabrics, Home Furnishings, Automotive Interiors, Filtration Media, Protective Clothing, Upholstery End User: Apparel Manufacturers, Furniture Producers, Automotive Component Makers, Industrial Equipment Suppliers, Personal Protective Equipment Makers, Carpet Manufacturers |
| Companies Covered | Formosa Plastics Corporation, Indian Acrylics Limited, Aksa Akrilik Kimya Sanayii A.S., Kaneka Corporation, Exlan Japan Co. Ltd., Aditya Birla Group, Sinopec, Pasupati Acrylon Limited, Dralon GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acrylic Fibers Market Shifts & Advancements
Acrylic fiber manufacturing is bifurcating between commodity volume operations and specialized protective-grade production, with process technology and regulatory certification becoming the primary axes of competitive differentiation rather than scale alone.
Recycled-content acrylic is fragmenting raw material sourcing strategies across the industry. Post-industrial polymer recovery from textile cutting waste and polymerization off-spec material is gaining specification traction in European furnishing fabrics. Brands with science-based targets are adopting mass-balance certified feedstock, compressing virgin acrylonitrile demand in premium apparel segments while standard grades remain price-sensitive.
China's GB standards evolution for industrial protective clothing is accelerating modacrylic technical development timelines. SAMR enforcement of flame-resistance testing protocols is raising barriers for imported protective fabrics. Domestic Chinese producers are investing in acrylonitrile copolymer formulations to meet both GB 8965.1 and export-market dual certification requirements.
Specification-driven procurement is consolidating buyer power among industrial distributors and rental laundry operators. Oilfield service companies and utility contractors are consolidating protective clothing spend through national account structures, displacing fragmented local uniform suppliers. This concentration is most visible in North American energy corridors where total-cost-of-ownership calculations now dominate fiber selection decisions.
Global Acrylic Fibers Market Segmentation
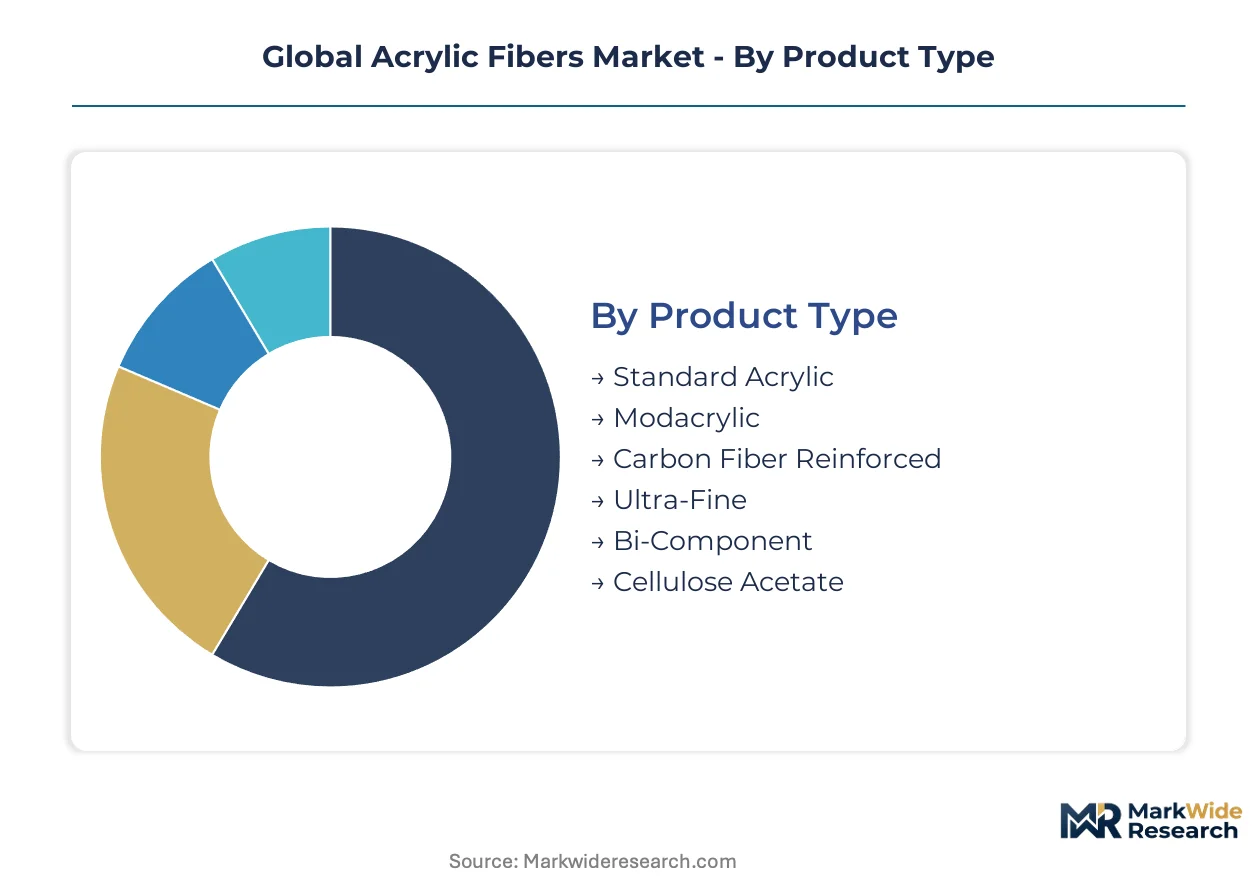
Acrylic fiber segmentation reflects divergent compliance burdens and performance premiums across regulatory jurisdictions. Producers must align product portfolios with ECHA's chemical handling protocols, OSHA's protective clothing mandates, and China's evolving GB standards simultaneously.
Product Type:
ECHA's REACH residual monomer thresholds and OSHA's flame-resistant clothing standards are bifurcating product development roadmaps between commodity grades and certified protective variants.
- Standard Acrylic:Composed of at least 85% acrylonitrile monomer units, this grade delivers wool-like hand feel and superior colorfastness for apparel and furnishing applications. Textile fabric mills in Turkey and Mexico concentrate procurement for knitwear and fleece production, though polyester microfiber substitution is compressing margins in mid-market sweater segments.
- Modacrylic:Containing 35-85% acrylonitrile with comonomer modifications, this variant provides inherent flame resistance without halogenated additives. Personal protective equipment makers in the US oilfield and electrical utility sectors are tightening procurement specifications against NFPA 2112 and EN ISO 14116 protocols, positioning modacrylic at the premium margin pool.
- Carbon Fiber Reinforced:Hybrid constructions blending acrylic precursors with carbon fiber for structural composite applications.
- Ultra-Fine:Sub-denier filaments engineered for synthetic fur and high-pile textile simulations.
- Bi-Component:Sheath-core constructions delivering dimensional stability in carpet backing under humidity cycling.
- Cellulose Acetate:Cellulosic-acrylic blends for specialized filtration and medical textile applications.
Standard acrylic handles the majority of throughput; modacrylic is climbing the fastest on share as protective clothing procurement tightens.
Technology:
Capital intensity for environmental controls is concentrating production scale among integrated operators with captive solvent recovery infrastructure.
- Wet Spinning:The dominant installed capacity globally, using dimethylformamide solvent baths to coagulate acrylic polymer into continuous filaments. China's Yangtze River Delta manufacturing cluster hosts concentrated wet-spinning operations, where MEE wastewater discharge enforcement is forcing multimillion-dollar solvent capture investments during environmental inspection campaigns.
- Dry Spinning:Evaporative solvent removal producing higher-tenacity fibers for technical textile applications. European producers leverage German process engineering expertise at Dralon GmbH facilities to sustain premium modacrylic output with closed-loop dimethylformamide recovery meeting REACH compliance.
- Gel Spinning:Ultra-high-molecular-weight fiber production for performance applications with limited throughput scaling.
- Electrospinning:Nanofiber membrane production for filtration media and medical barriers.
- Melt Spinning:Solvent-free extrusion for modified acrylic copolymers with reduced thermal sensitivity.
- Solution Spinning:Alternative solvent systems for specialty fiber geometries and surface modifications.
Wet spinning commands the dominant share of installed capacity; gel spinning carries the steepest expansion trajectory in performance-grade segments.
Application:
End-use specifications are fragmenting procurement channels between fashion-driven apparel cycles and industrial safety certification timelines.
- Textile Fabrics:Knitwear, fleece, and woven apparel applications leveraging acrylic's bulk and warmth retention. Apparel manufacturers serving US retailers are relocating cut-and-sew operations to Mexico's nearshoring corridor, creating demand for acrylic yarn supply within USMCA tariff-preferred territory.
- Home Furnishings:Upholstery, drapery, and decorative fabric applications prized for colorfastness and soil resistance. European furnishing fabric brands with science-based targets are adopting mass-balance certified recycled-content feedstock, compressing virgin acrylonitrile demand in premium segments.
- Automotive Interiors:Headliner, seat fabric, and carpet applications requiring UV stability and abrasion resistance.
- Filtration Media:Industrial air and liquid filtration using electrospun nanofiber layers.
- Protective Clothing:Industrial PPE leveraging modacrylic's inherent flame resistance for oilfield, electrical utility, and chemical processing sectors.
- Upholstery:Contract and residential furniture covering applications.
Textile fabrics maintain volume leadership; protective clothing is gaining share fastest as OSHA enforcement accelerates.
End User:
Buyer concentration among industrial distributors and rental laundry operators is consolidating specification power in protective clothing procurement.
- Personal Protective Equipment Makers:Industrial safety garment producers certifying against diverging national protocols. Oilfield service companies and utility contractors are consolidating protective clothing spend through national account structures, displacing fragmented local uniform suppliers.
- Apparel Manufacturers:Fashion and casual wear producers facing polyester substitution pressure in mid-market sweater segments.
- Furniture Producers:Residential and contract upholstery operations sourcing for durability and stain resistance specifications.
- Automotive Component Makers:Tier-1 and Tier-2 suppliers integrating interior textile systems.
- Industrial Equipment Suppliers:Filtration and separation technology OEMs.
- Carpet Manufacturers:Commercial and residential flooring producers adopting bi-component acrylic backing for dimensional stability.
Apparel manufacturers represent the largest demand block; personal protective equipment makers are expanding most quickly on specification-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH enforcement anchors European acrylic fiber compliance architecture, while OSHA mandates and China's MEE wastewater standards shape parallel regulatory tracks across the major production geographies.
United States
OSHA's flame-resistant clothing standards drive modacrylic procurement across oilfield and electrical utility sectors. NFPA 2112 certification requirements tighten specification barriers for protective garment imports. Houston-Gulf Coast petrochemical corridors concentrate acrylonitrile feedstock supply for integrated fiber producers serving industrial PPE makers.
Germany
Closed-loop solvent recovery investments respond to ECHA's residual monomer thresholds for dimethylformamide handling. EU Green Deal procurement criteria favor modacrylic's inherent flame resistance in public sector protective clothing tenders. Dralon GmbH leverages German process engineering expertise at facilities sustaining premium modacrylic output for technical textile applications.
China
MEE wastewater discharge enforcement forces multimillion-dollar solvent capture investments at Yangtze River Delta wet-spinning plants. SAMR's evolving GB standards for industrial protective clothing accelerate domestic modacrylic technical development timelines. Sinopec dominates captive feedstock access across its integrated acrylonitrile-to-fiber network.
Turkey
Export-oriented textile fabric mills concentrate acrylic yarn procurement for knitwear and fleece production serving European retailers. Aksa Akrilik Kimya Sanayii A.S. anchors integrated acrylonitrile-to-yarn operations through Bursa-Izmir manufacturing corridors. REACH compliance requirements for EU-bound exports elevate environmental control investments across Turkish production bases.
Mexico
USMCA tariff-preferred territory attracts apparel manufacturers relocating cut-and-sew operations from Asian supply bases. Nearshoring corridors around Puebla and Querétaro generate demand for acrylic yarn supply serving US retailer specifications. OSHA-aligned protective clothing standards for cross-border industrial operations sustain modacrylic specification channels.
Global Acrylic Fibers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in acrylic fiber supply architecture. Captive acrylonitrile access distinguishes scale operators from non-integrated spinners exposed to propylene-ammonia feedstock volatility. Three archetypes populate the competitive terrain: petrochemical conglomerates with backward integration, specialty modacrylic producers with certification depth, and regional export-oriented spinners. Capacity consolidation and solvent recovery infrastructure deployment constitute the dominant competitive moves as environmental compliance costs escalate.
Among integrated petrochemical players, Formosa Plastics Corporation and Sinopec exemplify scale-driven archetypes with captive feedstock control. Dralon GmbH occupies a position within the specialty tier, representing German process engineering concentration in premium modacrylic production. Aksa Akrilik Kimya Sanayii A.S. anchors the export-oriented segment, exemplifying Turkish vertical integration from acrylonitrile through finished yarn for textile fabric markets.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Indian Acrylics Limited |
| Aksa Akrilik Kimya Sanayii A.S. |
| Kaneka Corporation |
| Exlan Japan Co. Ltd. |
| Aditya Birla Group |
| Sinopec |
| Pasupati Acrylon Limited |
| Dralon GmbH |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day acrylonitrile inventory cycles at wet-spinning plants concentrate pricing power with integrated producers holding captive feedstock, while non-integrated spinners absorb margin compression from propylene-ammonia volatility.
Pricing Analysis
Geographic price spreads between Turkish export yarn and Chinese standard-grade bulk deliveries widen during propylene-ammonia feedstock volatility, compressing non-integrated spinner margins. Three-tier pricing structure across modacrylic protective grades, standard textile acrylic, and economy furnishing fiber separates certification-burdened producers from commodity spinners. Price differentiation hinges on REACH compliance costs and NFPA 2112 certification depth. Cost compression in standard acrylic intensifies because polyester microfiber substitution erodes wool-like hand-feel premiums. Apparel manufacturers serving US retailers exhibit highest price sensitivity; oilfield PPE rental operators show lowest sensitivity due to total-cost-of-ownership procurement models.
Supply Chain Analysis
Dimethylformamide solvent inventory buffers at Yangtze River Delta wet-spinning plants face MEE inspection-triggered supply disruptions, forcing buyers toward Turkish and German alternative sourcing. Production concentrates in China, Turkey, and Germany, with each hub serving distinct specification tiers. Acrylonitrile supply rests on propylene-ammonia cracker outputs, dimethylformamide solvent availability, and comonomer vinylidene chloride access for modacrylic variants. Single-source vulnerability concentrates in China's Yangtze River Delta environmental enforcement corridors. Distribution runs through textile yarn merchants in Turkey, industrial fabric distributors in Germany, and direct mill relationships in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic fiber market sits in a cyclical recovery phase as industrial PPE procurement accelerates post-regulatory enforcement tightening across OSHA and SAMR jurisdictions.
For Market Incumbents: Secure captive acrylonitrile supply through backward integration or long-term offtake agreements to defend against propylene-ammonia margin compression. Deepen solvent recovery infrastructure investments to preempt REACH and MEE enforcement escalation. Consolidate specification power through dual NFPA 2112 and EN ISO 14116 certification for modacrylic protective grades.
For New Entrants and Emerging Players: Anchor in Mexico's nearshoring corridor where USMCA tariff preferences and OSHA-aligned protective clothing standards create specification entry points. Target bi-component carpet backing segments where dimensional stability premiums exceed commodity acrylic margin structures. Pursue digital textile printing compatibility as a go-to-market angle for cationic-dyeable acrylic variants in short-run fashion applications.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because environmental compliance capital intensity favors scaled integrated operators over fragmented non-integrated spinners. Acquisition target archetype: mid-cap Turkish or Chinese wet-spinning assets with latent modacrylic conversion capability and existing EU-bound export relationships. Monitor SAMR GB 8965.1 enforcement timelines as the signal to watch for protective clothing demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile | Captive feedstock access insulates margin structures from propylene-ammonia volatility at non-integrated competitors. |
| Closed-Loop Solvent Recovery Deployment | Dimethylformamide capture infrastructure satisfies ECHA REACH residual monomer thresholds and MEE wastewater standards. |
| Dual Certification Investment | NFPA 2112 and EN ISO 14116 qualification opens specification channels across US oilfield and European utility PPE procurement. |
| Nearshoring Corridor Capacity Addition | Mexico manufacturing footprint captures USMCA tariff-preferred demand from apparel manufacturers relocating from Asia. |
| Recycled-Content Feedstock Adoption | Mass-balance certified post-industrial polymer recovery aligns with EU Green Deal procurement criteria for furnishing fabrics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with polymer engineering directors, wet-spinning plant managers, protective clothing procurement leads at oilfield service companies, and textile yarn merchants; and secondary validation through customs trade databases, ECHA REACH substance dossiers, SEC chemical sector filings, and SAMR GB standard evolution notices. Bottom-up capacity modeling triangulated against top-down end-use demand segmentation.
Across the analysis window, projections integrated grade-tier splits between modacrylic protective variants and standard textile acrylic, technology-based segmentation across wet-spinning and dry-spinning capacity, and geographic production hub clustering. CAGRs derived from elasticity-adjusted demand curves for industrial PPE, furnishing fabric, and apparel end-uses. Key inputs included acrylonitrile feedstock cost trajectories, MEE enforcement intensity indices, and polyester substitution elasticity parameters.
Decision-makers should treat outputs as directional under stable propylene-ammonia feedstock cost assumptions and continued OSHA enforcement trajectories; material deviation in environmental inspection intensity or protective clothing procurement consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Global High Performance Fibers Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Short Cut Polyester Fiber Market
Synthetic Fibers
High Temperature Fiber Market
Synthetic Fibers
Staple Fibers Market
Synthetic Fibers
Spandex Fiber Market
Synthetic Fibers
Designer Fiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
North America Aramid Fiber Market
Synthetic Fibers
Americas Spandex Market
Synthetic Fibers
Polybenzoxazole Fibers Market
Synthetic Fibers
High End Synthetic Suede Market
Synthetic Fibers
Polyester Straps Market
Synthetic Fibers
Nylon Tire Cord Fabrics Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market