
 High Performance Polyester Market | 2026-2036
High Performance Polyester Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Polyester Market Analysis
Aftermarket technical service revenue is reconfiguring margin pools away from commodity fiber sales toward application engineering support. Invista leverages its polymer science heritage to sustain premium positioning in industrial yarn grades. Kolon Industries anchors its competitiveness through backward integration into purified terephthalic acid production. Toray Industries differentiates via carbon fiber hybridization expertise that extends polyester performance boundaries.
High performance polyester denotes engineered thermoplastic polymers, primarily polyethylene terephthalate and polybutylene terephthalate variants, manufactured through solid-state polymerization to achieve intrinsic viscosity above 0.8 dL/g and tenacity exceeding 7.5 grams per denier for load-bearing industrial applications. These materials serve as structural reinforcements, barrier membranes, and dimensionally stable substrates across sectors requiring chemical resistance combined with mechanical integrity. Polyethylene terephthalate dominates volume due to mature recycling infrastructure, while high tenacity polyester captures expanding margin pools in geotextile and tire cord applications where failure tolerance is minimal. Polybutylene terephthalate leads growth in automotive electrical connectors as voltage architectures rise, with polyester blends occupying an intermediate value position between cost and performance optimization.
EPA industrial emissions standards and OSHA workplace exposure limits shape US manufacturing compliance costs for solvent-based coating techniques, while REACH substance restrictions in Europe constrain certain catalyst residues in polymerization processes. China's SAMR enforces GB standards for flame retardancy in construction-grade industrial fabrics, creating divergent certification burdens for exporters. Stakeholders must monitor regulatory divergence between jurisdictions as it determines which recycling process technologies and coating formulations qualify for premium market access without reformulation penalties.
Market Dynamics
Automotive lightweighting mandates are pulling high tenacity polyester into structural composites at unprecedented rates, rewiring supply relationships away from commodity fiber traders toward application engineering partners.
Growth Catalysts
- EPA industrial emissions standards:US solvent-based coating restrictions are accelerating waterborne and hot-melt adhesive adoption for polyester lamination, expanding addressable applications in barrier membranes.
- Tire cord reinforcement:Electric vehicle torque demands are intensifying specifications for dimensionally stable polyester substrates in high-performance tire constructions.
- Yangtze River Delta:China's fiber-to-fabric integration depth in this manufacturing cluster is compressing lead times for industrial textile converters serving geotechnical applications.
Market Restraints
- Purified terephthalic acid volatility:Crude oil-linked paraxylene feedstock costs transmit directly into high tenacity polyester margin compression without pricing power recovery mechanisms.
- REACH substance restrictions:ECHA constraints on antimony-based catalyst residues in polymerization processes are forcing European producers into costly process requalification.
- Aramid fiber substitution:Meta-aramid and para-aramid alternatives are capturing premium ballistic and aerospace applications where temperature tolerance exceeds polyester thermal limits.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for technical textiles are attracting greenfield industrial yarn capacity to serve underpenetrated South Asian infrastructure markets.
- GB standards flame retardancy:China's SAMR construction-grade fabric mandates are creating certified-supplier premiums for compliant polyester membrane producers.
- Carbon fiber hybridization:Toray's composite expertise convergence with thermoplastic polyester matrices is opening automotive structural panels previously reserved for thermoset epoxies.
Industry Challenges
- Solid-state polymerization technicians:Intrinsic viscosity control expertise is scarce as veteran operators retire without sufficient apprenticeship pipeline replacement.
- REACH-GB dual certification:Divergent European and Chinese substance testing timelines are extending product qualification cycles for multinational suppliers.
- Legacy DCS integration:Brownfield polymerization plants face control system modernization friction when retrofitting Industry 4.0 quality monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Polyester Market |
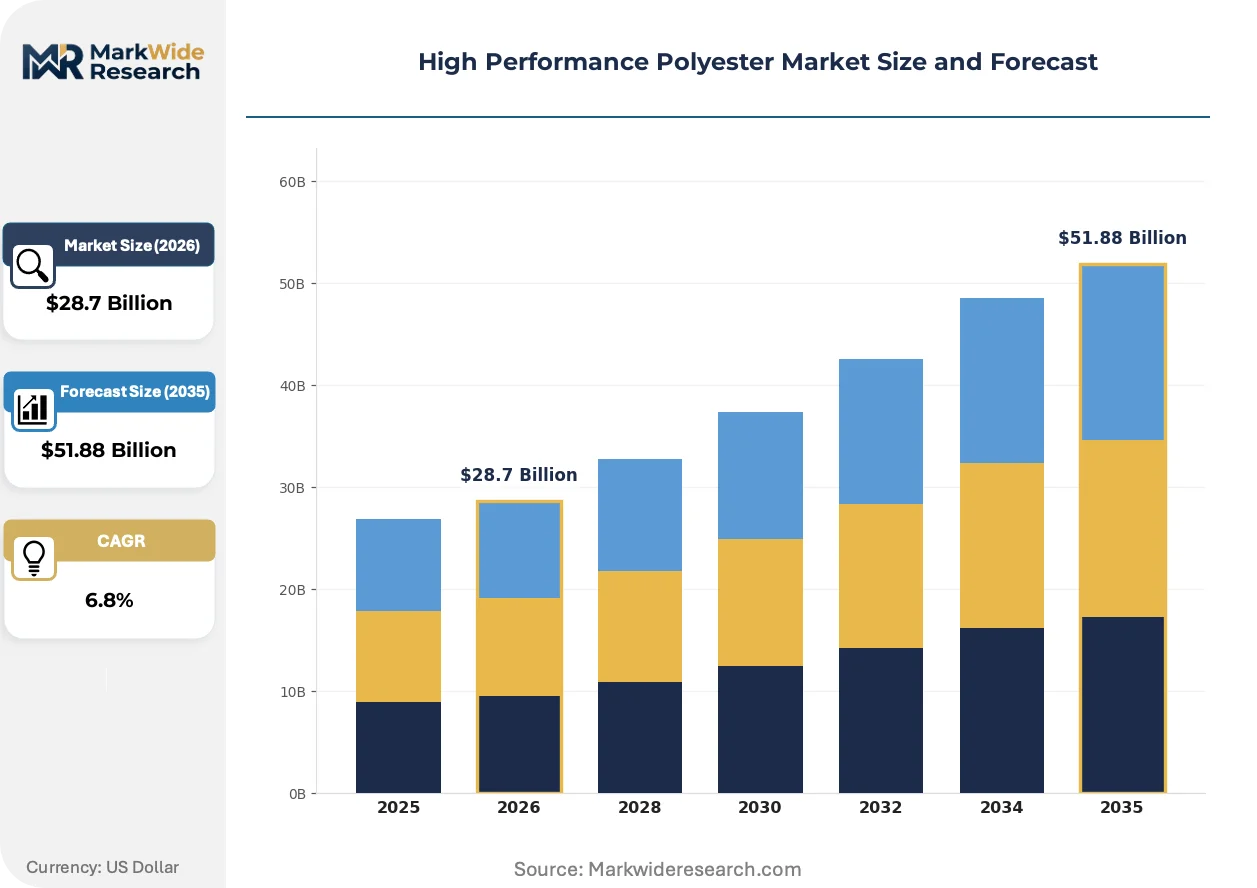
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Terephthalate, Polybutylene Terephthalate, Polyester Blends, High Tenacity Polyester Application: Textiles, Automotive Interiors, Industrial Fabrics, Packaging End User: Aerospace, Consumer Goods, Automotive, Construction Technology: Recycling Process, Fiber Production, Coating Techniques, Weaving Methods |
| Companies Covered | Invista, Kolon Industries, Toray Industries, Reliance Industries, Indorama Ventures, Teijin Limited, Milliken & Company, MMI Textiles, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Polyester Market Emerging Trajectories
Process analytical technology is digitizing quality control across polymerization stages, compressing batch release cycles while tightening viscosity specification bands for high tenacity grades.
Inline rheometry combined with near-infrared spectroscopy is digitizing real-time molecular weight monitoring during solid-state polymerization. Automotive composite laminators in Germany and Japan are adopting these systems fastest. Quality deviation detection is digitizing scrap reduction and enabling just-in-sequence supply to tier-one structural component molders.
REACH substance restrictions on antimony catalyst residues are forcing European producers toward titanium-based and germanium-based polymerization alternatives. Reformulation qualification costs are concentrating certified supply among integrated producers with captive analytical capabilities. High tenacity industrial yarn for geotextile applications faces the steepest compliance burden given failure tolerance requirements.
Buyer concentration among tier-one automotive suppliers is compressing procurement cycles from annual tenders to quarterly price-volume negotiations. Direct mill relationships are displacing distributor intermediaries for high volume tire cord and safety belt specifications. This channel consolidation is most advanced in Germany's Baden-Württemberg automotive supplier belt and China's Jiangsu province manufacturing corridor.
High Performance Polyester Market Segmentation
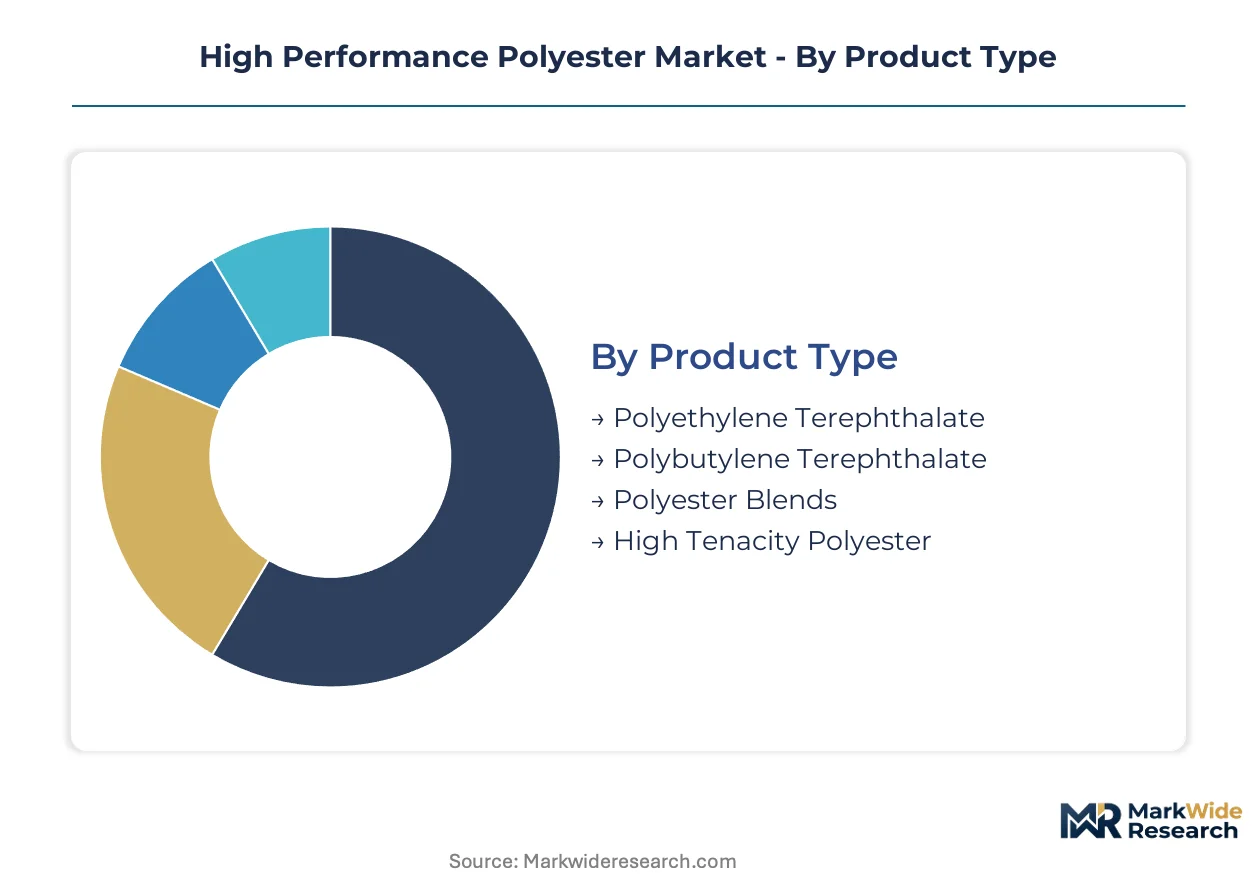
High performance polyester segmentation reveals divergent margin architectures across polymer chemistry, application engineering intensity, and certification burden. Understanding these fault lines clarifies where technical differentiation commands sustainable pricing power versus commodity exposure.
Product Type:
The use-case spectrum spans load-bearing industrial reinforcement through precision-molded electrical components, with viscosity specifications and thermal thresholds determining competitive boundaries.
- Polyethylene Terephthalate:Solid-state polymerization yields intrinsic viscosity above 0.8 dL/g for tire cord and geotextile reinforcement. Demand concentrates in China's Yangtze River Delta where fiber-to-fabric integration supports just-in-sequence supply to automotive tier-ones.
- Polybutylene Terephthalate:Superior dimensional stability and electrical insulation properties suit high-voltage automotive connector housings. German and Japanese automotive suppliers are pulling this grade into 800V EV architectures as voltage tolerances intensify.
- Polyester Blends:Cost-performance intermediates combining PET mechanical properties with modified thermal behavior.
- High Tenacity Polyester:Tenacity exceeding 7.5 grams per denier for safety-critical applications with minimal failure tolerance.
The dominant share belongs to Polyethylene Terephthalate, while Polybutylene Terephthalate is closing the gap fastest.
Application:
Cost tier stratification separates specification-grade industrial fabrics from commodity packaging films, with coating and lamination investments determining margin capture.
- Textiles:High tenacity industrial yarns for safety belts and harnesses requiring REACH and GB dual certification. European producers face ECHA antimony catalyst restrictions that force titanium-based reformulation investments.
- Automotive Interiors:Dimensionally stable substrates for seat fabrics and headliners where lightweighting mandates intensify polyester penetration against polypropylene.
- Industrial Fabrics:Geotextile and architectural membrane applications with the steepest compliance burden for flame retardancy certification.
- Packaging:Barrier films and rigid containers leveraging mature recycling infrastructure.
Industrial Fabrics commands premium pricing through certification barriers, while Automotive Interiors is expanding most quickly as EV platforms proliferate.
End User:
Customer type concentration among tier-one suppliers compresses procurement cycles and displaces distributor intermediaries for volume specifications.
- Automotive:Tier-one structural component molders in Baden-Württemberg and Jiangsu province drive quarterly price-volume negotiations. Toray's carbon fiber hybridization expertise opens thermoplastic composite panels previously reserved for epoxy thermosets.
- Construction:China's SAMR enforces GB flame retardancy standards for certified membrane premiums.
- Aerospace:Meta-aramid substitution limits polyester to non-structural interior applications where thermal limits are less severe.
- Consumer Goods:Apparel and home textiles with recycled content mandates from EU Green Deal circular economy requirements.
Automotive dominates procurement volume, while Construction is climbing the fastest on infrastructure stimulus in South Asia.
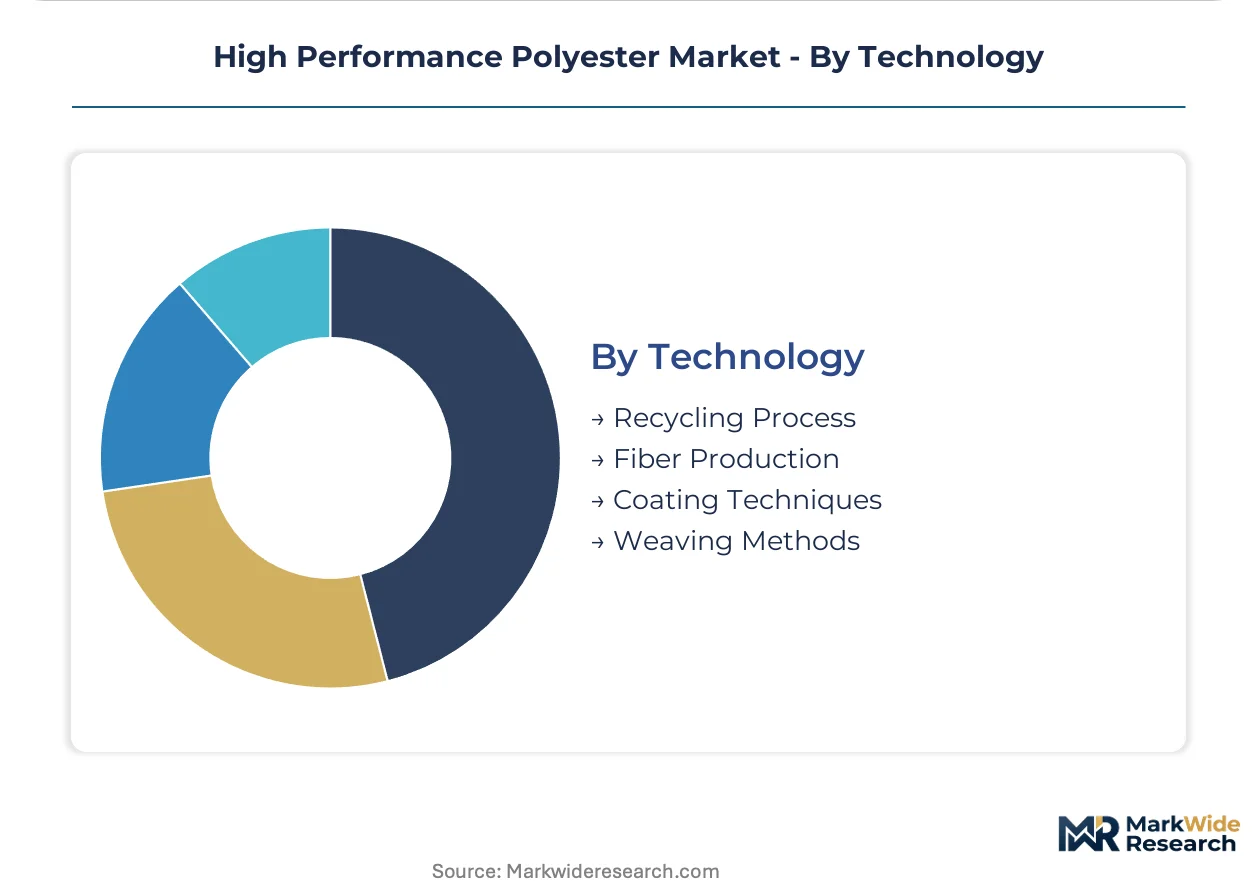
Technology:
Process maturity separates digitized polymerization control from legacy batch operations, with analytical technology investments determining specification band tightness.
- Fiber Production:Solid-state polymerization with inline rheometry and near-infrared spectroscopy enables real-time molecular weight monitoring. German and Japanese automotive composite laminators adopt these quality systems fastest.
- Recycling Process:Chemical and mechanical routes for post-industrial and post-consumer feedstock qualification.
- Coating Techniques:Waterborne and hot-melt adhesive adoption accelerates as EPA solvent restrictions tighten.
- Weaving Methods:Technical textile construction for load-bearing industrial fabric specifications.
Fiber Production anchors quality differentiation, while Recycling Process is gaining share fastest on brand owner circularity commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High tenacity polyester supply concentrates in integrated manufacturing corridors where polymerization, spinning, and fabric finishing co-locate. China's Yangtze River Delta anchors global capacity, while European and North American producers defend specification-grade positions through certification depth.
China
Automotive lightweighting mandates and geotextile infrastructure deployment pull high viscosity PET into structural applications. SAMR enforces GB flame retardancy standards for construction-grade industrial fabrics. Jiangsu province's fiber-to-fabric integration compresses lead times for just-in-sequence supply to tier-one automotive molders.
Germany
Baden-Württemberg's automotive supplier belt drives quarterly procurement cycles for tire cord and safety belt specifications. ECHA REACH restrictions on antimony catalyst residues force titanium-based polymerization reformulation investments. Inline rheometry adoption digitizes quality control for composite laminators serving structural panel applications.
United States
EPA industrial emissions standards accelerate waterborne adhesive adoption for polyester lamination in barrier membranes. OSHA workplace exposure limits shape solvent-based coating compliance costs. Southeast manufacturing corridors attract tire cord capacity to serve domestic EV platform proliferation.
Japan
METI carbon neutrality targets pull polyester into thermoplastic composite panels previously reserved for epoxy thermosets. JIS standards govern industrial yarn quality specifications for export markets. Chubu region polymerization plants retrofit Industry 4.0 monitoring to tighten viscosity specification bands.
India
PLI scheme production-linked incentives attract greenfield industrial yarn capacity for underpenetrated South Asian infrastructure markets. BIS technical textile standards create certified-supplier premiums for compliant membrane producers. Gujarat and Maharashtra textile corridors deepen backward integration into purified terephthalic acid production.
High Performance Polyester Market Vendor Landscape
Integrated petrochemical conglomerates and specialized fiber producers split the market along capability depth lines. Consolidation pressures concentrate specification-grade supply among producers with captive polymerization and analytical certification infrastructure. Three archetypes dominate: backward-integrated PTA producers, carbon fiber hybridization specialists, and recycled-content platform operators. Competitive moves center on dual REACH-GB certification attainment and solid-state polymerization technician apprenticeship pipeline development.
Within the integrated chemical conglomerate tier, Invista, Kolon Industries, and Toray Industries exemplify divergent positioning strategies. Invista leverages polymer science heritage to sustain premium positioning in industrial yarn grades. Kolon Industries anchors competitiveness through upstream control over purified terephthalic acid production. Toray Industries occupies a hybridization-specialist position where carbon fiber expertise extends polyester performance boundaries into automotive structural applications.
| Leading Market Players |
|---|
| Invista |
| Kolon Industries |
| Toray Industries |
| Reliance Industries |
| Indorama Ventures |
| Teijin Limited |
| Milliken & Company |
| MMI Textiles |
| DuPont |
| Others |
Supply Flow & Price Mechanics
China's Yangtze River Delta manufacturing cluster concentrates purified terephthalic acid supply and fiber-to-fabric integration, anchoring margin capture downstream in application engineering services rather than commodity fiber trading. REACH-GB dual certification burdens and solid-state polymerization technician scarcity concentrate pricing power among integrated producers with captive analytical capabilities.
Pricing Analysis
Aftermarket technical service revenue drives lifetime value as application engineering support displaces commodity fiber trading in margin pools. Three-tier pricing structure across certified-grade, specification-grade, and commodity-grade levels reflects certification burden divergence, with REACH-GB dual-certified industrial yarn commanding substantial premiums. Pricing pressure stems from crude oil-linked paraxylene feedstock volatility transmitting directly into high tenacity polyester without pricing power recovery mechanisms. Tier-one automotive suppliers in Germany and China exhibit lowest price sensitivity due to just-in-sequence supply requirements, while packaging film converters face highest sensitivity to resin cost swings.
Supply Chain Analysis
Contract manufacturing concentration resides with integrated petrochemical conglomerates operating captive polymerization and spinning assets across China, Germany, and the United States. Raw material dependencies center on purified terephthalic acid, paraxylene feedstocks, and antimony-based or titanium-based polymerization catalysts. Supply chain risk concentrates in single-source vulnerability for solid-state polymerization equipment and specialized rheometry quality systems. Distribution runs through direct mill relationships displacing distributor intermediaries for tire cord and safety belt specifications, with channel consolidation most advanced in Baden-Württemberg and Jiangsu province.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Application engineering service contracts expand faster than commodity fiber sales, repositioning this market as a service-attach opportunity where technical support bundling sustains margin architecture.
For Market Incumbents: Harden certification depth by investing in dual REACH-GB analytical capabilities that concentrate supply among integrated producers. Anchor competitiveness through backward integration into purified terephthalic acid production, mitigating paraxylene feedstock volatility exposure. Defend against aramid fiber substitution in temperature-critical applications by accelerating carbon fiber hybridization R&D. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-supported technical textiles corridor, where production-linked incentives attract greenfield capacity for underpenetrated South Asian infrastructure markets. Target geotextile applications with GB flame retardancy certification premiums as the most penetrable segment given compliance burden concentration. Lead with recycled-content platform positioning to capture EU Green Deal circular economy mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mid-cap fiber producers lacking captive polymerization infrastructure. Long-term viability favors integrated producers with solid-state polymerization expertise and apprenticeship pipeline investments. Watch titanium-based catalyst reformulation adoption rates as inflection indicator for European producer cost structure divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PTA Production | Kolon Industries demonstrates how upstream control over purified terephthalic acid insulates margin compression from paraxylene volatility. |
| Dual REACH-GB Certification Investment | European producers face ECHA antimony restrictions while China's SAMR enforces GB flame retardancy standards for construction-grade membranes. |
| Solid-State Polymerization Apprenticeship Pipeline | Veteran operator retirement without replacement threatens intrinsic viscosity control expertise central to high tenacity grade quality. |
| Carbon Fiber Hybridization Partnership | Toray Industries extends polyester performance boundaries into automotive structural panels previously reserved for thermoset epoxies. |
| Inline Rheometry Quality System Deployment | German and Japanese automotive composite laminators adopt real-time molecular weight monitoring fastest for just-in-sequence supply. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across solid-state polymerization plant managers, tier-one automotive supplier procurement leads, technical textile distribution channel partners, and industrial fabric R&D directors. Secondary validation drew from customs and trade data, ACC and Cefic chemical industry reports, SEC 10-K filings from listed petrochemical conglomerates, and SAMR GB standards documentation. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic indicators to ensure segmentation coherence.
Calibration across the analysis window employed multi-dimensional segmentation by polymer chemistry grade, end-use industry intensity, certification burden tier, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating EV platform penetration rates and infrastructure stimulus deployment timelines. Industry-specific forecast inputs included automotive lightweighting mandate compliance schedules and geotextile deployment curves tied to South Asian infrastructure investment.
Stress conditions across paraxylene feedstock price bands, REACH substance restriction timelines, and solid-state polymerization technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory divergence persistence and recycling process technology maturation. Quarterly review of titanium-based catalyst adoption rates, tier-one automotive procurement cycle compression, and India PLI scheme capacity allocation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Synthetic Fibers
Polyester Fibers Market
Synthetic Fibers
Latin America Textile Market
Synthetic Fibers
Monofilament Market
Synthetic Fibers
Polymer Nanofiber Market
Synthetic Fibers
Aramid Fiber Market
Synthetic Fibers
Pan-Based Carbon Fiber Cloth Market
Synthetic Fibers
South Korea Textile Market
Synthetic Fibers
Europe Aramid Fiber Market
Synthetic Fibers
Synthetic Fabric Market
Synthetic Fibers
Polyolefin Fiber Market
Synthetic Fibers
Glass Fiber Yarn Market
Synthetic Fibers
Regenerated Fibers Market
Synthetic Fibers
Asia-Pacific Aramid Fiber Market
Synthetic Fibers
Parachute Fabric Market
Synthetic Fibers
Europe Nanofiber Market
Synthetic Fibers
Long Fiber Thermoplastics Market