
 Webbing Cutting Machine Market | 2026-2036
Webbing Cutting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Webbing Cutting Machine Market Analytics
Automotive manufacturers are redrawing procurement priorities for webbing cutting equipment as safety-critical textile demand intensifies. Honggang Cutting Machine Co. Ltd. leverages its manufacturing scale to serve domestic automotive tier-one suppliers. Brother Industries Ltd. sustains technology leadership through precision mechanical cutting platforms. Kingsing Auto Co. Ltd. anchors its position in automated feeding systems integrated with cutting workflows.
A webbing cutting machine severs woven strap material—typically nylon, polyester, or aramid fiber—using mechanical blades, laser beams, or water jets at tolerances measured in fractions of a millimeter, serving industries requiring precise length control for load-bearing applications. Automated product types command the dominant installed base as labor costs and throughput requirements escalate across textile and automotive facilities. Laser technology captures expanding share where heat-sealed edges prevent fraying in aerospace and safety harness applications. CNC systems concentrate margin pools through software-defined repeatability and reduced material waste.
ISO machinery safety standards and the EU Machinery Directive constrain market access for non-compliant equipment while elevating demand for certified automated platforms. China's SAMR enforces GB standards on industrial cutting equipment, compelling design modifications for domestic and export-bound manufacturers. Stakeholders must monitor evolving certification requirements across target geographies to align product development with compliance timelines.
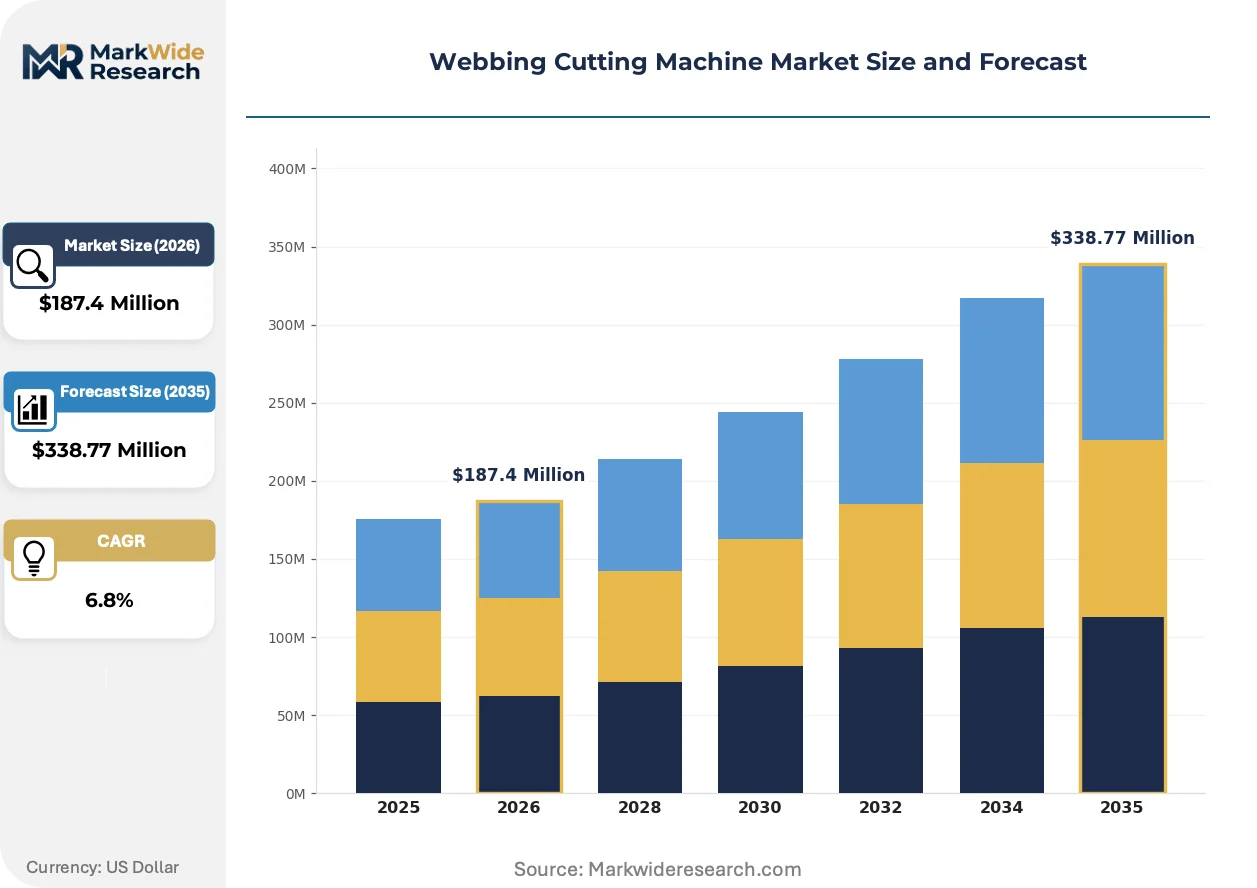
Market Dynamics
Automotive safety mandates and ISO machinery certification requirements are compressing equipment replacement cycles while elevating entry barriers for non-compliant suppliers. Tier-one seatbelt manufacturers now specify laser-sealing tolerances as standard procurement criteria.
Growth Catalysts
- EU Machinery Directive compliance deadlines:OEMs in Germany and France are retiring mechanical-only platforms ahead of mandatory CE marking updates for automated cutting systems.
- Aramid fiber penetration in aerospace harnesses:Heat-sealed edge requirements for Kevlar and Nomex webbing are pulling laser technology into previously mechanical-dominated installations.
- China's automotive cluster concentration:Tier-one seatbelt suppliers in Zhejiang and Guangdong provinces are scaling automated feeding-integrated lines to match EV production ramps.
Market Restraints
- High-purity optical component costs:CO2 laser tube and fiber source prices fluctuate with rare earth supply constraints from concentrated mining operations.
- Technical limitation in thick-stack cutting:Water jet systems face throughput ceilings above 12mm aramid bundles that mechanical shears still handle more reliably.
- REACH substance restrictions:Coolant and lubricant formulations for mechanical cutting require reformulation, extending equipment qualification timelines for EU-bound exports.
Strategic Opportunities
- India's PLI scheme for textile machinery:Domestic automotive belt manufacturers qualify for capital subsidy offsets on precision cutting equipment imports.
- Convergence of machine vision and CNC control:Real-time edge-detection feedback loops enable single-setup cutting of patterned webbing for luxury automotive trim applications.
- Direct-to-factory service channels:Equipment vendors bypass distributor networks to capture aftermarket blade and software upgrade revenue from high-volume Chinese OEMs.
Industry Challenges
- Mechatronics technician scarcity:Servo calibration and laser alignment expertise concentrates in automotive automation hubs, leaving textile machinery regions understaffed.
- ISO 13849-1 safety validation timelines:Control system certification for Category 3 PLd architectures adds 8-14 months to new platform introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Webbing Cutting Machine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Manual, CNC, Hydraulic Technology: Laser, Mechanical, Water Jet, Plasma End User: Textile Industry, Automotive Manufacturers, Furniture Makers, Aerospace Application: Industrial Production, Prototyping, Custom Orders, Mass Manufacturing |
| Companies Covered | John Howard Company, Kingsing Auto Co. Ltd., Lohia Group, Hightex Special Sewing Machine Inc., Honggang Cutting Machine Co. Ltd., DEMA Sewing Solutions, PIX Transmissions Ltd., Brother Industries Ltd., Seattle Fabrics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Webbing Cutting Machine Market Evolving Landscape
Laser heat-sealing technology is redrawing equipment specifications across safety-critical textile applications. Three developments are compressing technology adoption cycles and reshaping supplier competitive requirements.
Ultrafast fiber laser systems are supplanting mechanical cold-cutting in aerospace and motorsport harness production. Boeing and Airbus tier-two suppliers in Toulouse and Hamburg now specify sealed-edge tolerances below 0.1mm for aramid load straps. The shift eliminates post-cut fraying treatments and compresses downstream assembly labor by 30-40 percent in high-reliability applications.
China's SAMR enforcement of updated GB standards on industrial cutting equipment is forcing design modifications for both domestic and export-bound manufacturers. The 2024 revisions mandate interlocked guarding and emergency stop response times that legacy mechanical platforms cannot satisfy without control system overhauls. Japanese and German equipment vendors are accelerating localized production to bypass import certification bottlenecks for Chinese automotive OEMs.
Specification authority is migrating from procurement departments to plant-floor automation engineers at major seatbelt manufacturers. Zhejiang-based tier-one suppliers now issue technical requirement documents that prescribe servo motor brands, PLC architectures, and data logging protocols before price negotiation. The shift favors equipment vendors with open-architecture control platforms over proprietary black-box systems, particularly in facilities running mixed-vendor production lines.
Webbing Cutting Machine Market Segmentation
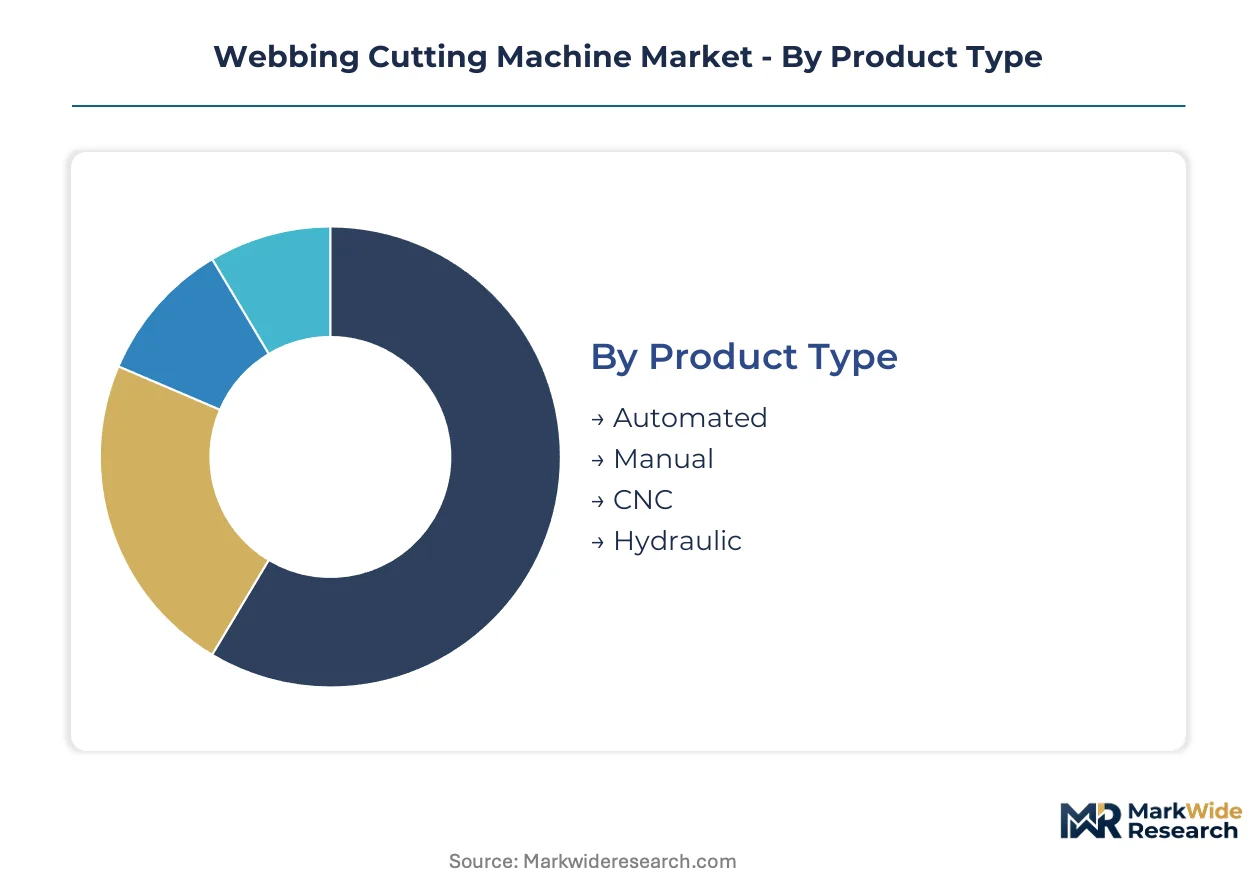
Equipment differentiation in webbing cutting machinery follows distinct technical and commercial fault lines. Procurement patterns diverge sharply across automation levels, cutting technologies, and end-use certification requirements.
Product Type:
CE marking and ISO 13849-1 safety validation requirements create tiered compliance burdens that reshape equipment replacement timelines and vendor selection criteria.
- Automated:Servo-driven feeding systems with programmable length control dominate high-volume automotive seatbelt production. Tier-one suppliers in Zhejiang and Guangdong provinces specify these platforms to match EV production ramps while satisfying SAMR enforcement of updated GB standards on interlocked guarding.
- CNC:Software-defined repeatability enables single-setup cutting of patterned webbing for luxury automotive trim applications. Real-time edge-detection feedback loops from converged machine vision systems are pulling this segment into aerospace prototyping workflows where tolerance verification is mandatory.
- Manual:Basic lever-actuated shears persist in custom furniture workshops and small-batch textile operations with limited capital budgets.
- Hydraulic:High-force cutting of thick aramid bundles above 12mm remains the domain of fluid-power systems in industrial safety harness production.
Automated platforms handle the majority of throughput; CNC systems are expanding most quickly on share as specification authority migrates to plant-floor automation engineers.
Technology:
Heat-sealing requirements for synthetic fibers and REACH substance restrictions on mechanical coolants are redrawing the technology mix across aerospace and automotive applications.
- Laser:CO2 and fiber laser systems seal cut edges to prevent fraying in Kevlar and Nomex load straps. Boeing and Airbus tier-two suppliers in Toulouse and Hamburg now specify sealed-edge tolerances below 0.1mm, eliminating post-cut treatments and compressing downstream assembly labor.
- Mechanical:Cold-cutting blades with programmable feed mechanisms retain cost advantages in thick-stack applications where water jet throughput ceilings create reliability gaps. REACH reformulation requirements for lubricants are extending equipment qualification timelines for EU-bound exports.
- Water Jet:Abrasive jet cutting serves prototyping environments requiring material flexibility without thermal distortion.
- Plasma:High-temperature ionized gas cutting finds limited application in metallic webbing and specialized industrial belting.
Laser technology commands the steepest expansion trajectory as heat-sealed edge requirements displace mechanical cold-cutting in safety-critical textile segments.
End User:
Customer concentration patterns follow automotive cluster geography and aerospace certification hubs, with procurement authority shifting from purchasing departments to technical engineering functions.
- Automotive Manufacturers:Seatbelt and harness production lines in Germany, France, and China drive precision equipment demand. OEMs are retiring mechanical-only platforms ahead of mandatory CE marking updates for automated cutting systems.
- Aerospace:Aramid fiber penetration in harness applications pulls laser technology into previously mechanical-dominated installations at Boeing and Airbus supplier networks.
- Textile Industry:Volume producers of nylon and polyester strapping serve packaging and industrial binding markets with varying tolerance requirements.
- Furniture Makers:Upholstery and webbing producers prioritize cost-efficient cutting for decorative and structural applications.
Automotive manufacturers absorb the dominant equipment volume; aerospace represents the fastest share gainer as sealed-edge specifications proliferate.
Application:
Production scale and repeatability requirements separate capital-intensive automated installations from flexible job-shop configurations.
- Mass Manufacturing:Continuous-feed automated lines with integrated quality verification serve tier-one automotive belt suppliers. Direct-to-factory service channels from equipment vendors bypass distributor networks to capture aftermarket blade and software upgrade revenue.
- Industrial Production:Batch-oriented cutting operations with quick-change tooling accommodate multiple webbing specifications on shared platforms.
- Prototyping:Low-volume validation environments require rapid setup changeover without dedicated line configurations.
- Custom Orders:Short-run specialty cutting for branded straps and limited-edition automotive trim demands flexible programming capabilities.
Mass manufacturing dominates installed capacity; custom orders are climbing fastest as luxury automotive trim specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Ningbo port complex underwrites China's dominance in precision textile machinery trade, handling over 40% of global containerized equipment exports. Automotive seatbelt supply chains cluster within 200 kilometers of this maritime gateway.
China
Zhejiang and Guangdong provinces host tier-one seatbelt suppliers scaling automated feeding-integrated lines to match EV production ramps. SAMR enforcement of updated GB standards on industrial cutting equipment mandates interlocked guarding and emergency stop response times that legacy mechanical platforms cannot satisfy. Japanese and German equipment vendors are accelerating localized production in Suzhou and Tianjin to bypass import certification bottlenecks.
Germany
OEMs in Stuttgart and Munich are retiring mechanical-only platforms ahead of mandatory CE marking updates for automated cutting systems under the EU Machinery Directive. The KBA coordinates with DIN standards bodies to align automotive safety belt specifications with ISO machinery certification requirements. Hamburg anchors aerospace supplier networks where Boeing and Airbus tier-two partners now specify laser-sealed edge tolerances below 0.1mm for aramid load straps.
United States
NHTSA safety mandates are compressing equipment replacement cycles at Detroit-area automotive belt manufacturers. OSHA machinery guarding standards intersect with state-level manufacturing incentives in Michigan and Ohio. The Port of Long Beach handles inbound precision cutting equipment serving Mexico-bound maquiladora operations under USMCA rules of origin.
India
Domestic automotive belt manufacturers in Pune and Chennai qualify for capital subsidy offsets under the PLI scheme for textile machinery imports. BIS certification requirements for industrial cutting equipment are tightening alongside CDSCO safety device regulations. The Delhi-Mumbai Industrial Corridor is attracting precision equipment vendors establishing service depots for aftermarket blade and software upgrade revenue.
France
Toulouse aerospace clusters pull laser technology into previously mechanical-dominated harness installations as Airbus supplier specifications proliferate. ANSM coordinates with EU Machinery Directive implementation timelines for CE marking updates. The Lyon-Grenoble manufacturing belt concentrates mechatronics technician expertise for servo calibration and laser alignment services.
Webbing Cutting Machine Market Competitive Landscape
Listed leaders compete with private specialists across technology platforms and geographic reach. The vendor base organizes into three tiers: multinational precision equipment conglomerates with diversified automation portfolios, regional machinery fabricators serving domestic automotive clusters, and specialized laser system developers focused on heat-sealing applications. Dominant competitive moves include capacity expansion in Chinese automotive corridors and strategic partnerships bridging mechanical cutting heritage with machine vision integration.
Among Asia-Pacific-based fabricators, Honggang Cutting Machine Co. Ltd. and Kingsing Auto Co. Ltd. exemplify the regional machinery tier serving domestic automotive OEMs. Brother Industries Ltd. occupies a position representing multinational precision equipment conglomerates with diversified automation portfolios. These three anchors illustrate how competitive positioning stratifies across manufacturing scale, control system architecture, and service network density.
| Leading Market Players |
|---|
| John Howard Company |
| Kingsing Auto Co. Ltd. |
| Lohia Group |
| Hightex Special Sewing Machine Inc. |
| Honggang Cutting Machine Co. Ltd. |
| DEMA Sewing Solutions |
| PIX Transmissions Ltd. |
| Brother Industries Ltd. |
| Seattle Fabrics Inc. |
| Others |
Value Network & Pricing Analysis
Sixteen-week lead times for CO2 laser tubes from concentrated rare earth processing facilities in China tether pricing power to upstream mineral access, while automotive OEM procurement calendars compress negotiation windows for equipment vendors serving Zhejiang seatbelt clusters.
Pricing Analysis
Volume-discount tiering structures separate automated CNC platforms with ISO 13849-1 certification from basic mechanical shears lacking CE marking eligibility. Price differentiation rests on servo motor brand specification and interlocked guarding compliance grade, with German and Japanese vendors commanding premiums for open-architecture control systems. Cost compression in mid-tier automated equipment is intensifying because Chinese domestic fabricators are scaling localized production. Tier-one automotive suppliers exhibit lowest price sensitivity due to safety-critical procurement mandates, while furniture workshops and small-batch textile operators drive economy-tier demand.
Supply Chain Analysis
Rare earth concentrate refining in China, ytterbium fiber sourcing from South Korea, and precision optical component finishing in Germany create a tripartite chokepoint for laser system assembly. Raw material dependencies span neodymium-doped glass, high-purity aluminum substrates, and ceramic bearing assemblies. Single-source vulnerability concentrates in ytterbium supply chains where South Korean refiners dominate semiconductor-grade purification. Distribution runs through direct-to-factory service channels that bypass distributor networks for blade and software upgrade revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as automotive safety mandates compress equipment replacement timelines and elevate compliance-driven procurement urgency.
For Market Incumbents: Fortify certification moats by accelerating ISO 13849-1 Category 3 PLd validation for new platform introductions, countering emerging Chinese domestic fabricators with localized production in Suzhou and Tianjin. Deepen backward integration into servo motor supply chains to insulate margin structures from component cost volatility.
For New Entrants and Emerging Players: Lead with machine vision-CNC convergence for luxury automotive trim applications, where real-time edge-detection feedback loops enable single-setup cutting of patterned webbing with limited incumbent penetration. Target India's PLI scheme beneficiary automotive belt manufacturers in Pune and Chennai with capital subsidy-aligned financing structures.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because EU Machinery Directive and SAMR GB standard enforcement cycles are structurally elevating barriers for non-compliant mechanical platforms. Acquisition targets should profile as specialized laser system developers with heat-sealing IP and aerospace supplier network access. Monitor CE marking update implementation velocity in Germany and France as inflection indicator for replacement demand timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13849-1 Certification Acceleration | Category 3 PLd validation compresses competitive access for non-compliant mechanical platforms. |
| Localized Production in Chinese Automotive Corridors | Suzhou and Tianjin facilities bypass SAMR import certification bottlenecks for Japanese and German vendors. |
| Machine Vision-CNC Convergence | Real-time edge-detection feedback loops pull aerospace prototyping workflows into CNC segment expansion. |
| Direct-to-Factory Service Channel Development | Aftermarket blade and software upgrade revenue capture from high-volume Chinese OEMs displaces distributor economics. |
| Aramid Fiber Heat-Sealing IP Development | Sealed-edge tolerance below 0.1mm specifications from Boeing and Airbus tier-two suppliers displace mechanical cold-cutting. |
Research Methodology
Desk research of customs trade databases, industrial machinery registration filings, and SAMR equipment certification records preceded structured interviews with plant engineers at tier-one seatbelt manufacturers, automation procurement leads at automotive OEMs, aftermarket service heads at precision equipment vendors, and mechatronics technicians in Zhejiang production clusters. Primary fieldwork combined with secondary validation across DIN standards documentation, EU Machinery Directive implementation timelines, and aerospace supplier qualification requirements. Bottom-up equipment shipment analysis triangulated against top-down automotive production capacity modeling.
Variance decomposition across technology platform adoption curves, regional regulatory enforcement intensity, and end-use certification requirements shaped the analytical framework over the projection horizon. Segmentation dimensions spanned automation level, cutting technology, end-use industry, and regional production cluster concentration. CAGRs derived from equipment replacement cycle compression analysis and laser technology penetration rate trajectories. Industry-specific forecast inputs incorporated EV production ramp schedules and aramid fiber specification proliferation in aerospace harness applications.
Underlying assumptions cover EU Machinery Directive compliance deadline adherence, SAMR GB standard enforcement continuity, and rare earth supply chain stability, with deviation risk concentrated in REACH substance restriction expansion and mechatronics technician availability in textile machinery regions. Practitioners should keep alternative scenarios live as automotive OEM platform standardization timelines and aerospace supplier consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
United States Fabric Shavers Market
Textile Machinery and Equipment
Gel Dryer Market
Textile Machinery and Equipment
Dyeing Machine Market
Textile Machinery and Equipment
Global Circular Knitting Machine Market
Textile Machinery and Equipment
Tarpaulin Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Automatic Fabric Folding Machines Market
Textile Machinery and Equipment
Asia Pacific Fabric Shavers Market
Textile Machinery and Equipment
Industrial Sewing Machines Market
Textile Machinery and Equipment
Hoarding Tarpaulin Market
Textile Machinery and Equipment
Textile Printer Market
Textile Machinery and Equipment
Global Weaving Machinery Market
Textile Machinery and Equipment
Linen Supply and Management Services Market
Textile Machinery and Equipment
Saddle Stitching Machine Market
Textile Machinery and Equipment
Multifunctional Clothes Folding Machine Market