
 Global Agricultural Textiles Market | 2026-2036
Global Agricultural Textiles Market Size, Share, and Industry Trends Forecast 2026-2036
Global Agricultural Textiles Market Analysis
The agricultural textiles sector is pivoting between premium technical fabrics engineered for multi-season durability and commodity-grade alternatives priced for single-cycle deployment. TenCate Industrial Fabrics leverages its polymer science heritage to dominate high-performance geotextile and crop cover segments. Garware Technical Fibres Ltd. anchors South Asian supply chains through backward integration into masterbatch and tape extrusion. Freudenberg Performance Materials differentiates via nonwoven expertise applied to breathable mulch films and erosion control matrices.
Agricultural textiles encompass woven, nonwoven, and knitted structures manufactured from polypropylene, polyester, natural fibers, or biodegradable polymers, engineered to regulate microclimate, suppress weeds, stabilize soil, or protect crops from pests and ultraviolet degradation. Shade nets and crop covers lead volume due to greenhouse expansion across semi-arid zones, while biodegradable mulch films represent the fastest-growing material segment as regulatory bans on conventional plastic tillage films spread. Geotextiles command premium pricing in soil erosion applications where polymer tensile strength and UV stabilization specifications determine project approval.
The EU Green Deal and REACH chemical compliance frameworks restrict persistent microplastic emissions from conventional polypropylene mulches, redirecting R&D budgets toward certified biodegradable alternatives. China's MIIT enforces GB standards for agricultural film thickness and recyclability, tightening market access for non-compliant imports. India's BIS certification mandates for shade net GSM ratings protect domestic weavers while creating compliance barriers for unqualified suppliers. Stakeholders must monitor how divergent biodegradability certification protocols between Europe, China, and North America fragment product standardization and complicate global SKU rationalization.
Market Dynamics
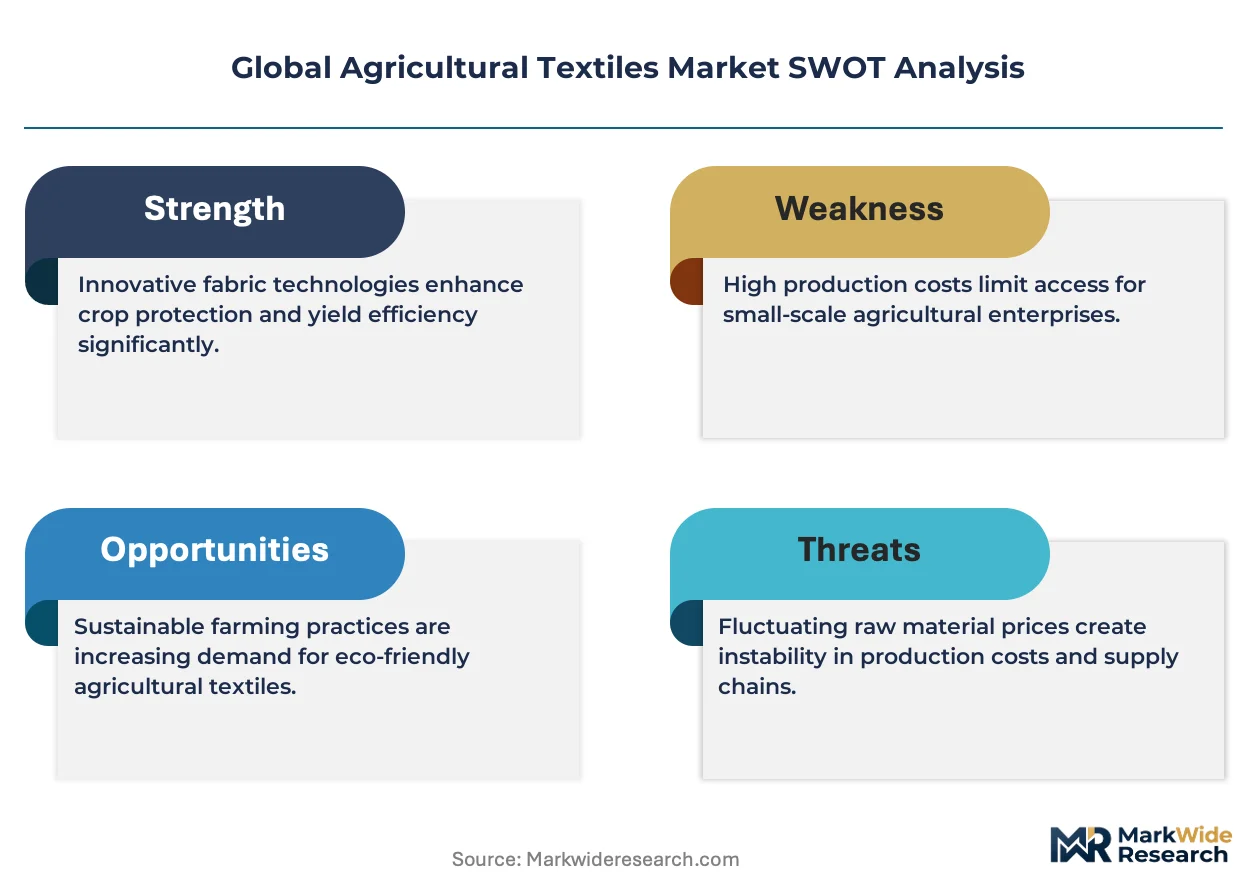
Polymer-to-fabric vertical clusters in Shandong Province, China, concentrate global supply capacity while EU Green Deal mandates force simultaneous feedstock substitution, creating a structural squeeze between scale efficiency and compliance cost.
Growth Catalysts
- EU Green Deal biodegradability mandates:REACH-compliant mulch film formulations are displacing conventional polypropylene in European greenhouse operations, redirecting procurement toward certified compostable alternatives.
- Shandong Province cluster economies:Integrated masterbatch-to-woven-fabric production in China's polymer belt compresses unit costs for shade net exports serving Middle Eastern and African horticulture.
- UV stabilization chemistry advances:HALS additive packages extending woven polypropylene lifespans beyond five growing seasons are reshaping replacement cycles in Australian and Chilean vineyard protection.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Gulf Coast petrochemical complexes transmit directly to agricultural textile input costs, compressing margin visibility for converters.
- Biodegradability certification fragmentation:Divergent compostability protocols between TÜV Austria's OK Compost, BPI North America, and China's GB/T standards create SKU proliferation and inventory risk.
- Mechanical recycling contamination:Soil-adhered mulch films and UV-degraded shade nets degrade reprocessing yields, limiting circular economy claims and exposing producers to extended producer responsibility liabilities.
Strategic Opportunities
- India BIS-certified shade net penetration:Unorganized domestic weavers in Maharashtra and Gujarat lack GSM standardization, creating white space for compliant suppliers to capture institutional horticulture procurement.
- Nonwoven geotextile soil stabilization:Freudenberg-style needlepunch technology is displacing woven alternatives in Brazilian soybean field erosion control, opening premium pricing for tensile-specified products.
- Japan METI carbon-neutral agriculture incentives:Biomass-derived PLA mulch films qualify for subsidy offsets in protected vegetable cultivation, accelerating pilot deployments in Chiba and Ibaraki prefectures.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists capable of balancing UV stability with biodegradation kinetics command premium compensation, constraining R&D throughput at mid-scale converters.
- Legacy extrusion asset retooling:Converting cast film lines to process starch-based blends requires screw and die modifications exceeding eighteen-month payback horizons.
- Multi-jurisdiction compliance sequencing:Simultaneous GB standard, REACH, and BIS certification timelines stretch product launch windows and strain regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Agricultural Textiles Market |
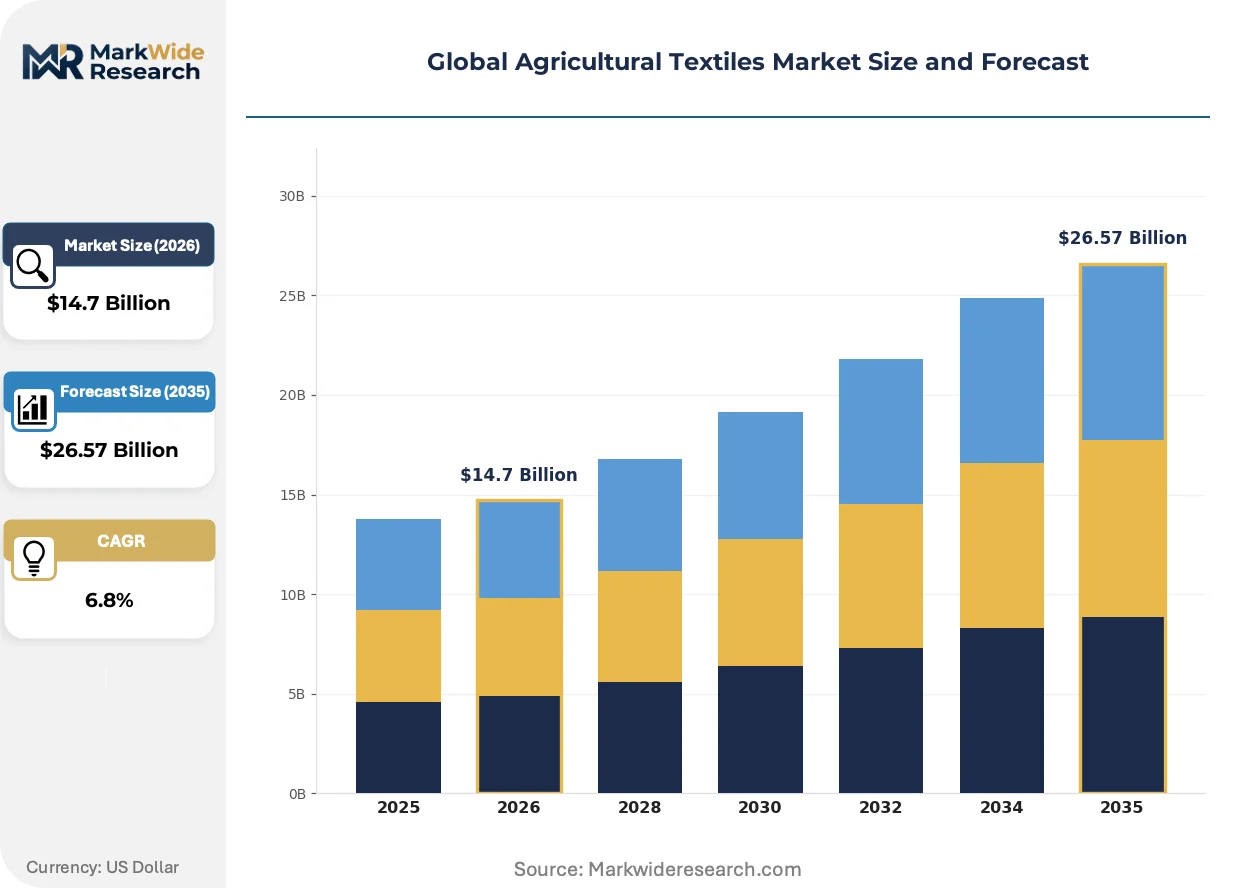
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Covers, Shade Nets, Mulch Films, Geotextiles Application: Greenhouses, Nurseries, Crop Protection, Soil Erosion Material: Polypropylene, Polyester, Natural Fibers, Biodegradable End User: Agronomy, Horticulture, Landscaping, Agriculture Cooperatives |
| Companies Covered | TenCate Industrial Fabrics, Garware Technical Fibres Ltd., Beaulieu Technical Textiles, Belton Industries, Freudenberg Performance Materials, Diatex SAS, Mogul Co. Ltd., Hy-Tex (UK) Ltd., Karatzis Group of Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Agricultural Textiles Market Emerging Trajectories
Active material science, regulatory chemistry constraints, and buyer procurement rationalization are simultaneously reshaping how agricultural textiles are formulated, certified, and deployed across climatic zones.
Photoselective shade netting is converging with spectral management for crop physiology. Red-light filtering polyethylene filaments manipulate photosynthetic photon flux distribution in Spanish Almería greenhouse complexes. Berry and soft-fruit growers in Huelva and Murcia are specifying 30-50% shade factors with discrete wavelength blocking. This convergence is compressing commodity shade net margins while opening specialty spectral-engineering premiums.
REACH microplastic restriction amendments are forcing polymer substitution strategies. ECHA's 2023 restriction proposal on intentionally added microplastics in agricultural applications mandates biodegradability thresholds within 120 days soil contact. Mulch film converters serving Dutch and Belgian vegetable cooperatives are accelerating PLA and PBAT blend validation. The regulatory pressure is fragmenting product portfolios between legacy polypropylene inventory and next-generation certified alternatives.
Greenhouse operator procurement consolidation is compressing supplier bases. Large Spanish and Mexican horticulture groups are consolidating annual shade net and crop cover purchasing through framework agreements with technical specification lock-ins. Smaller regional distributors in Morocco and Turkey are losing shelf space to direct mill relationships. This consolidation is most visible in Almería's 35,000-hectare concentrated greenhouse belt where three buying cooperatives control 60% of protective textile volume.
Global Agricultural Textiles Market Segmentation
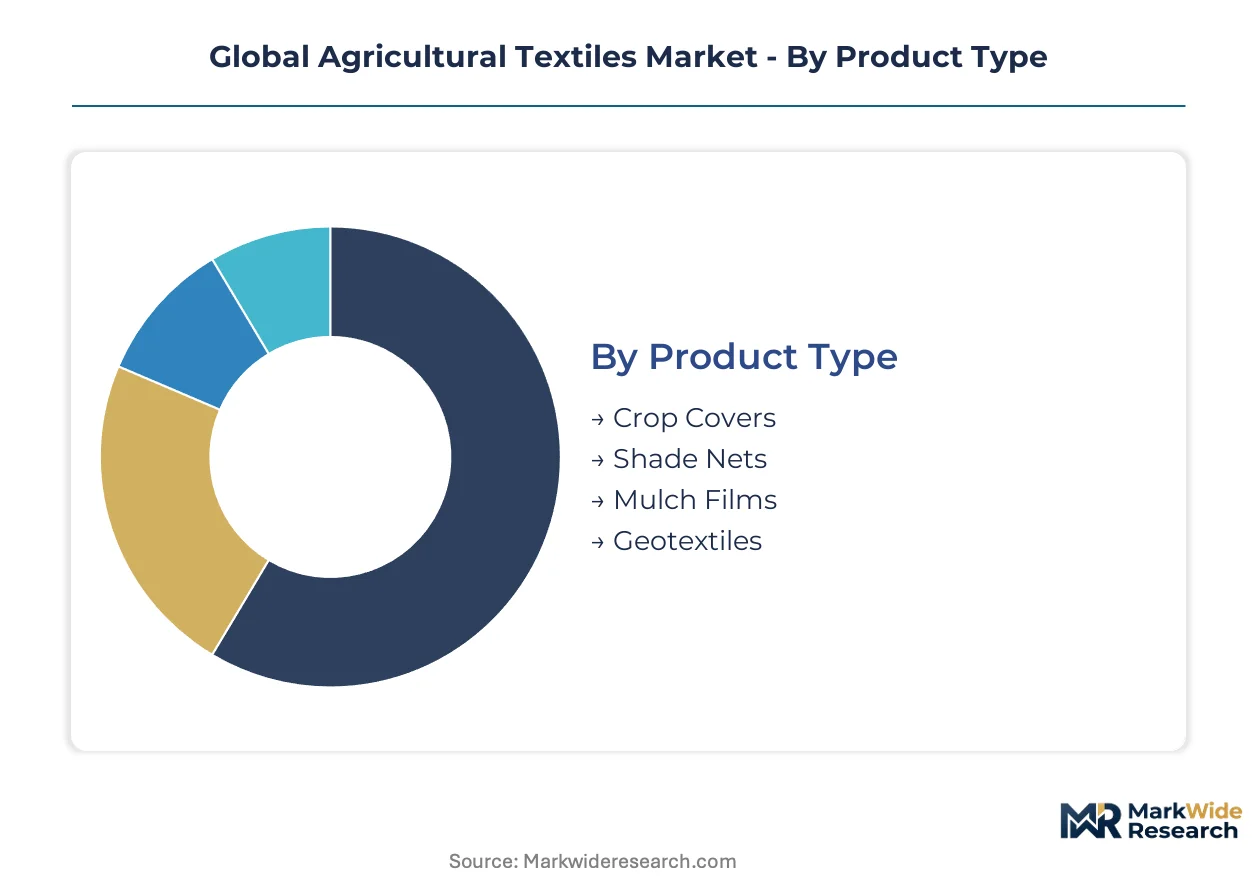
Agricultural textile procurement diverges sharply across product categories, with capital requirements for extrusion and weaving infrastructure dictating supplier concentration in woven structures versus fragmented competition in commodity films. Segment boundaries blur as greenhouse operators demand multi-functional fabrics combining shade, thermal regulation, and biodegradability certifications.
Product Type:
Capital intensity peaks in geotextile manufacturing where polymer science R&D and HALS stabilization chemistry command premium facility investment, while commodity mulch film extrusion tolerates lower entry thresholds.
- Shade Nets:Knitted or woven polyethylene structures with calibrated porosity regulate photosynthetic photon flux in Almería greenhouse complexes. Spanish berry cooperatives specify spectral-engineered variants with discrete red-light filtering, compressing commodity margins while opening specialty premiums.
- Mulch Films:Cast or blown polymer sheets suppress weeds and conserve soil moisture in vegetable cultivation. REACH microplastic restrictions in Dutch and Belgian markets are accelerating certified compostable PLA-PBAT blend substitution, fragmenting product portfolios between legacy polypropylene and next-generation alternatives.
- Crop Covers:Lightweight nonwoven or spunbond fabrics protect seedlings from frost and pest pressure. Nursery operators in China's Shandong Province favor reusable woven polypropylene for multi-season deployment.
- Geotextiles:High-tenacity woven or needlepunch structures stabilize soil in erosion control and drainage applications. Brazilian soybean field projects specify tensile-rated alternatives, displacing commodity woven products with premium-specified needlepunch technology.
Shade nets absorb the bulk of installed capacity; mulch films are expanding most quickly as regulatory bans on conventional plastics spread.
Application:
Customer concentration varies dramatically, with institutional greenhouse cooperatives consolidating procurement through framework agreements while fragmented nursery operators purchase through regional distributors.
- Greenhouses:Controlled-environment agriculture structures in semi-arid zones deploy shade nets, thermal screens, and ventilation fabrics simultaneously. Mexican and Moroccan horticulture groups are consolidating annual textile purchasing through direct mill relationships, squeezing regional distributor margins.
- Crop Protection:Insect netting, hail protection, and bird deterrent fabrics shield high-value fruit and vegetable crops. Chilean vineyard operators specify UV-stabilized woven polypropylene with five-season durability guarantees.
- Nurseries:Propagation facilities utilize frost protection fleeces and root control fabrics. Container nursery operations in Japan's Chiba Prefecture pilot biomass-derived PLA mulch films under METI carbon-neutral agriculture incentives.
- Soil Erosion:Slope stabilization and drainage applications specify high-strength geotextiles with certified tensile performance. Australian infrastructure projects mandate UV stabilization specifications that determine project approval.
Greenhouse applications dominate procurement volume; soil erosion commands the steepest expansion trajectory as climate volatility intensifies infrastructure investment.
Material:
Feedstock selection now hinges on biodegradability certification compatibility across divergent regulatory jurisdictions, with compliance costs reshaping competitive positioning.
- Polypropylene:Dominant polymer for woven shade nets and crop covers due to UV stability and mechanical durability. HALS additive packages extending lifespans beyond five growing seasons are reshaping replacement cycles in Australian and Chilean vineyard protection.
- Biodegradable:PLA, PBAT, and starch-based blends certified to TÜV Austria OK Compost or BPI North America standards. ECHA's restriction proposal on intentionally added microplastics mandates biodegradability thresholds within 120 days soil contact for European market access.
- Polyester:Higher-strength alternative for geotextile and permanent erosion control applications. Superior tensile characteristics command premium positioning in Brazilian soybean field stabilization projects.
- Natural Fibers:Jute, coir, and hemp-based textiles for short-cycle erosion control where complete biodegradation is desired. Limited UV resistance constrains deployment to single-season applications in humid tropical zones.
Polypropylene retains the largest installed production base; biodegradable alternatives are climbing the fastest as EU Green Deal mandates redirect R&D budgets.
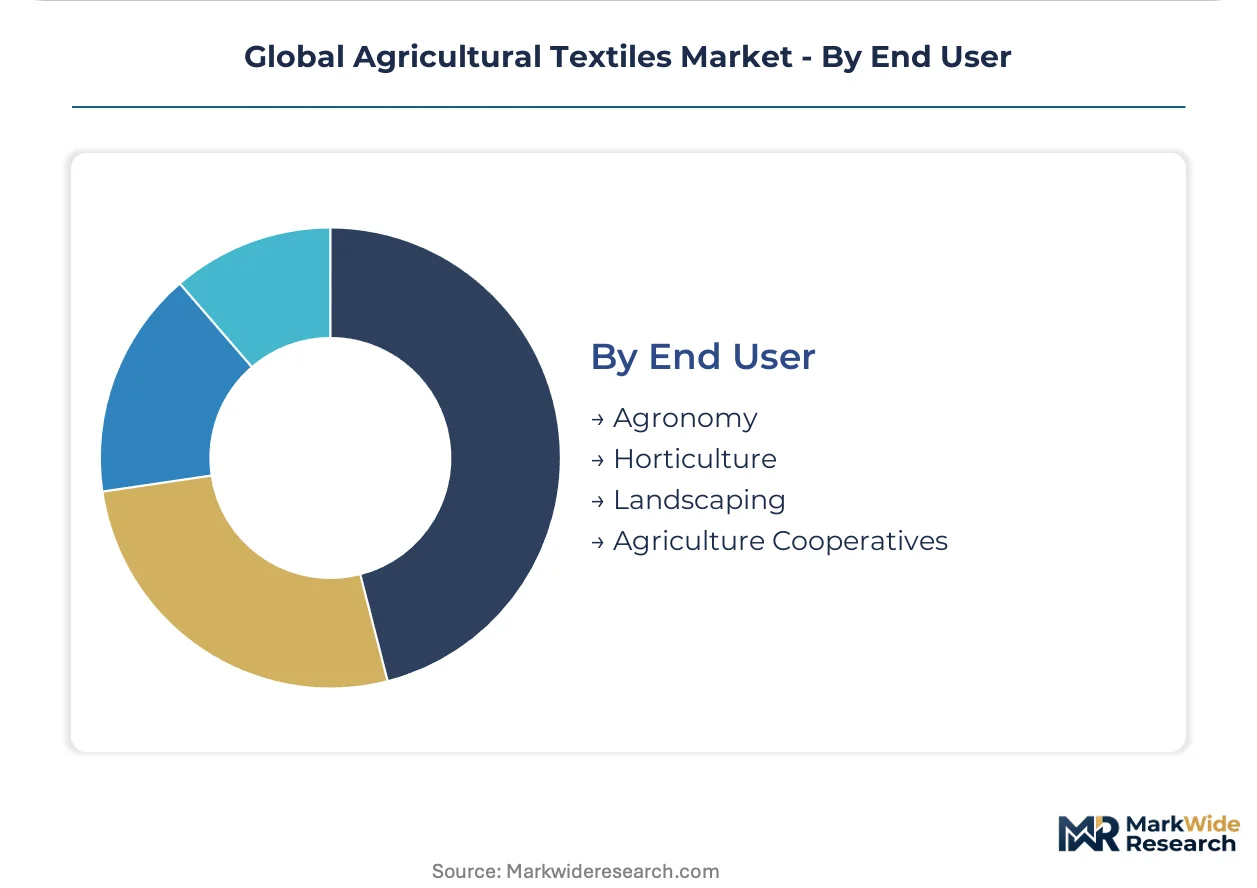
End User:
Procurement sophistication stratifies sharply, with agronomy research stations demanding specification lock-ins while agriculture cooperatives prioritize volume pricing.
- Horticulture:Protected vegetable and soft-fruit growers in Spain's Almería belt and Mexico's Sinaloa state drive shade net and crop cover specification. Three buying cooperatives control 60% of protective textile volume in the 35,000-hectare concentrated Spanish greenhouse zone.
- Agronomy:Research institutions and extension services pilot novel spectral-management and biodegradable formulations. Field trial validation precedes commercial deployment in institutional procurement protocols.
- Agriculture Cooperatives:Consolidated purchasing entities negotiate framework agreements with technical specification lock-ins. Smaller regional distributors in Turkey and Morocco are losing shelf space to direct manufacturer relationships.
- Landscaping:Golf course, municipal park, and residential erosion control applications. Lower specification tolerance permits commodity-grade geotextile penetration.
Horticulture concentrates the highest procurement value; agriculture cooperatives are gaining share fastest as buyer consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province's polymer-to-fabric vertical clusters concentrate global agricultural textile supply capacity while regulatory divergence across major markets fragments standardization efforts.
China
Shandong Province's integrated masterbatch-to-woven-fabric production belt serves domestic horticulture and export markets simultaneously. MIIT enforces GB standards for agricultural film thickness and recyclability, tightening market access for non-compliant imports. Qingdao and Weihai host the densest concentrations of shade net extrusion capacity serving Middle Eastern and African buyers.
Spain
Almería's 35,000-hectare concentrated greenhouse belt drives spectral-engineered shade net specification for berry and soft-fruit growers. ECHA's REACH microplastic restriction amendments mandate biodegradability thresholds within 120 days soil contact. Three buying cooperatives control 60% of protective textile volume, consolidating procurement through direct mill relationships.
Netherlands
Dutch and Belgian vegetable cooperatives accelerate certified compostable PLA-PBAT blend substitution for conventional polypropylene mulches. EU Green Deal mandates redirect R&D budgets toward TÜV Austria OK Compost certified alternatives. Wageningen research corridors anchor agronomy pilot programs validating novel biodegradable formulations.
India
Maharashtra and Gujarat nursery operators drive BIS-certified shade net demand as institutional horticulture procurement tightens GSM standardization requirements. Unorganized domestic weavers lack compliance infrastructure, creating white space for certified suppliers. Surat and Ahmedabad textile clusters expand technical fabric weaving capacity for agricultural applications.
Brazil
Soybean field erosion control projects specify tensile-rated needlepunch geotextiles, displacing commodity woven alternatives with premium performance requirements. ANVISA and environmental licensing frameworks tighten soil stabilization material specifications. São Paulo state infrastructure corridors anchor geotextile deployment for slope stabilization and drainage applications.
Global Agricultural Textiles Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification tier and polymer science capability, with HALS stabilization expertise and biodegradability validation separating price bands. The vendor base stratifies between integrated polymer-to-fabric operators and downstream converters dependent on merchant feedstock supply. Three archetypes dominate: heritage technical textile houses with captive R&D, regional extrusion specialists serving single markets, and diversified industrial conglomerates leveraging materials science crossovers. Capacity expansion and backward integration into masterbatch production represent the dominant competitive vectors as converters seek margin defense against propylene volatility.
Among heritage technical textile houses, TenCate Industrial Fabrics and Freudenberg Performance Materials exemplify premium-tier positioning through polymer science heritage and nonwoven expertise respectively. Garware Technical Fibres Ltd. occupies a position within the integrated specialist tier, representing the backward-integrated archetype with captive control over tape extrusion and masterbatch formulation. These three entities illustrate how competitive advantage concentrates in companies combining materials science capability with vertical control over critical process steps.
| Leading Market Players |
|---|
| TenCate Industrial Fabrics |
| Garware Technical Fibres Ltd. |
| Beaulieu Technical Textiles |
| Belton Industries |
| Freudenberg Performance Materials |
| Diatex SAS |
| Mogul Co. Ltd. |
| Hy-Tex (UK) Ltd. |
| Karatzis Group of Companies |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap weavers in India's Maharashtra and Gujarat clusters anchor commodity-grade shade net supply, their limited balance sheet capacity constraining certification investment while pricing discipline erodes against REACH-compliant European imports.
Pricing Analysis
Yield-per-hectare guarantees anchor value-based pricing for spectral-engineered shade nets in Spain's Almería greenhouse belt. Three-tier pricing structure across premium, standard, and economy levels separates TÜV Austria OK Compost certified mulch films from BIS-standardized shade nets and unorganized domestic weaver output. Cost compression in commodity polypropylene woven fabrics is intensifying because Shandong Province cluster economies compress export unit costs. Institutional horticulture cooperatives in Mexico and Morocco exhibit lowest price sensitivity; fragmented nursery operators in Turkey face acute margin pressure.
Supply Chain Analysis
TÜV Austria OK Compost, BPI North America, and China's GB/T standards create divergent qualification gating that fragments SKU rationalization across export markets. Manufacturing gravity centers on China's Shandong Province, India's Surat-Ahmedabad belt, and Germany's Freudenberg nonwoven complexes. Feedstock supply draws from Gulf Coast naphtha crackers, Shandong masterbatch formulators, and European PLA-PBAT compounders. Single-source vulnerability concentrates in HALS additive packages sourced from specialized polymer chemistry houses. Distribution runs through direct mill relationships with consolidated greenhouse cooperatives and regional distributor networks serving fragmented nursery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal biodegradability mandates and ECHA REACH microplastic restrictions erect a cost-of-compliance barrier that advantages certified incumbents while screening out unorganized weavers lacking regulatory affairs capacity.
For Market Incumbents: Acquire HALS stabilization chemistry R&D capabilities and captive masterbatch production assets. TenCate-style heritage technical textile houses should expand backward integration into polymer science talent pools to defend against propylene feedstock volatility. Freudenberg-style nonwoven specialists must lock in TÜV Austria certification capacity before ECHA restriction amendments tighten. For New Entrants and Emerging Players: Begin with BIS-certified shade net penetration in India's institutional horticulture procurement, where unorganized domestic weavers lack GSM standardization infrastructure. Maharashtra and Gujarat nursery operators present the most penetrable white space. A direct mill relationship model bypassing regional distributors captures procurement consolidation tailwinds. For Investors and Strategic Acquirers: Distressed-cycle entries favor backward-integrated mid-cap specialists with captive tape extrusion in Shandong Province or Surat-Ahmedabad clusters. Long-term viability hinges on biodegradability certification compatibility across EU, China, and North American protocols. The signal to watch is ECHA enforcement acceleration against conventional polypropylene mulch film inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Production | Captive feedstock supply defends margin compression from Gulf Coast propylene volatility. |
| Biodegradability Certification Investment | TÜV Austria OK Compost validation unlocks EU Green Deal-mandated procurement channels. |
| Spectral-Engineering R&D Expansion | Red-light filtering polyethylene filaments command premium positioning in Almería berry cooperatives. |
| Direct Mill Relationship Development | Bypassing regional distributors captures procurement consolidation among Mexican horticulture groups. |
| HALS Additive Package Acquisition | UV stabilization chemistry expertise extends replacement cycles in Australian vineyard protection. |
Methodological Framework
Independent corroboration across polymer plant managers, procurement leads at Dutch vegetable cooperatives, Shandong-based export distributors, and technical R&D directors at nonwoven specialists underwrites the qualitative findings. Secondary validation sources include customs and trade data for agricultural textile flows, MIIT GB standard filings, ECHA restriction proposal documentation, and SEC 10-K disclosures from listed technical textile producers. Bottom-up segment sizing triangulates against top-down macroeconomic agricultural investment indicators.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. Segmentation dimensions modeled include product type, application end-use, material feedstock certification tier, and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for policy inflection points. Key inputs include ECHA enforcement timelines, Shandong Province capacity expansion announcements, and BIS certification penetration rates in Indian institutional procurement.
Underlying measurement precision varies by segment; REACH-compliant biodegradable mulch films carry tighter precision than unorganized domestic weaver output in India. Forecasts reflect assumptions regarding regulatory enforcement acceleration and feedstock cost transmission. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Technical Textiles
Aramid Conveyor Belt Market
Technical Textiles
Wet-Molded Fibre Market
Technical Textiles
Smart Textiles for Military Market
Technical Textiles
Blackout Fabric Market
Technical Textiles
UV Protected Tarpaulin Sheets Market
Technical Textiles
Global Hybrid Fabrics Market
Technical Textiles
Silicone Fabrics Market
Technical Textiles
Geotextile Tubes Market
Technical Textiles
China Geotextiles Market
Technical Textiles
North America Technical Textiles Market
Technical Textiles
Active Smart Textiles Market
Technical Textiles
E-Textile Market
Technical Textiles
Blackout Fabric Laminates Market
Technical Textiles
Airbag Textiles Market
Technical Textiles
Webbing Market
Technical Textiles
Ceramic Textiles Market