
 Clinical Diagnostics Market | 2026-2036
Clinical Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Diagnostics Market Intelligence
The shift toward high-sensitivity, rapid-turnaround assays is bifurcating the market between centralized high-throughput labs and decentralized point-of-care settings. Roche Diagnostics leverages its extensive portfolio in immunoassay and molecular diagnostics to command a significant position. Abbott Laboratories competes through its strength in point-of-care solutions and infectious disease detection. Siemens Healthineers specializes in integrated automation systems for large clinical chemistry and hematology workflows.
Clinical diagnostics encompass in vitro tests performed on samples like blood or tissue to provide information for disease diagnosis, prevention, and treatment monitoring. These tests often rely on biochemical reactions measured by techniques such as photometry or fluorescence to quantify specific analytes. Immunoassay analyzers continue to form the bedrock of the market by volume, serving routine testing needs. The molecular diagnostics segment, particularly for oncology screening applications, represents the fastest-growing area due to its superior specificity.
Regulatory frameworks, including the US FDA's premarket approval process and the European Union's Medical Device Regulation (MDR), set stringent requirements for clinical validation and performance data. In parallel, market access in key growth areas like China is governed by approvals from the NMPA, influencing product design and documentation strategies. Navigating these varied and evolving regulatory pathways is a primary strategic consideration for all market participants.
Market Dynamics
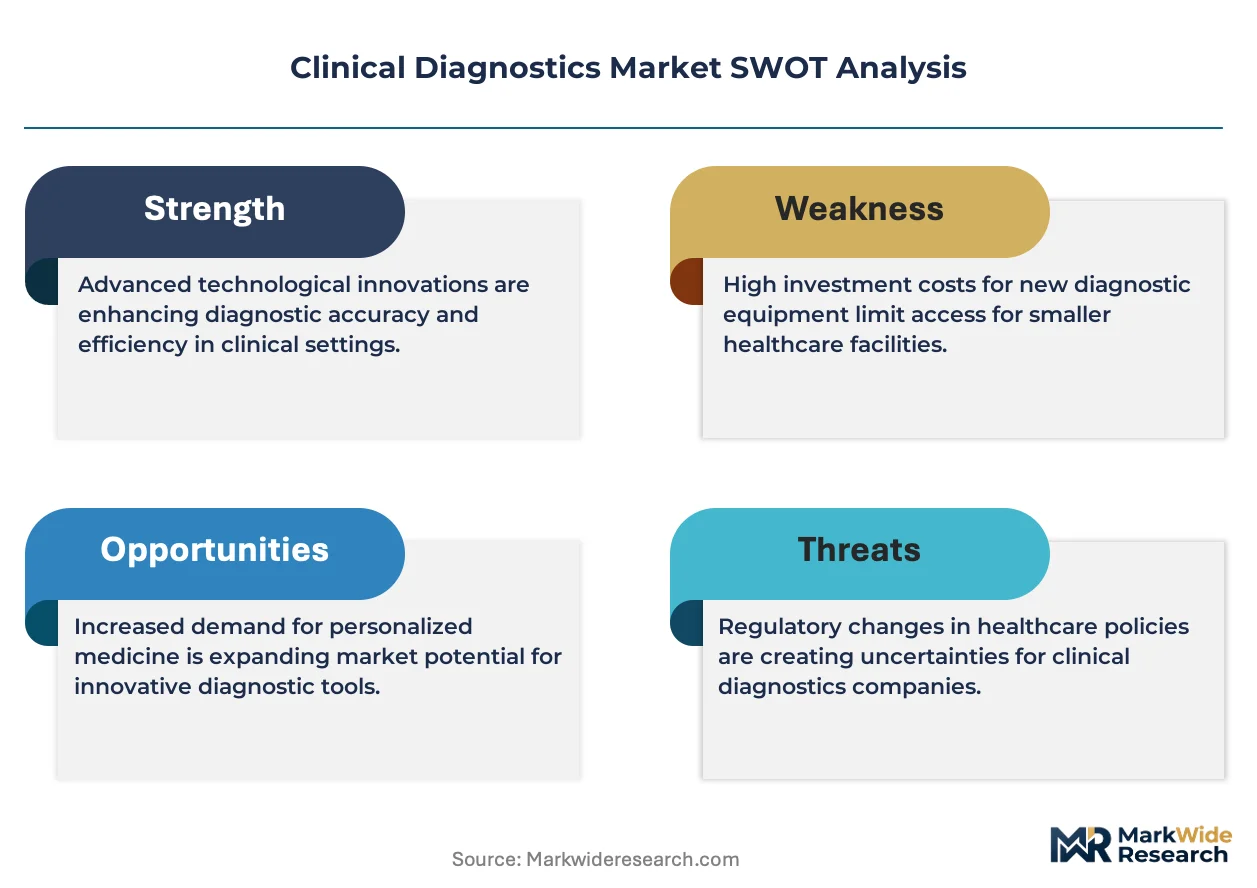
The bifurcation of testing between high-throughput centralized labs and decentralized point-of-care settings is the central force shaping the market. This structural split influences everything from instrument design and assay development to regulatory and reimbursement strategies across geographies.
Growth Catalysts
- Next-Generation Sequencing:Proliferation of NGS technologies provides superior specificity in oncology, enabling earlier disease detection and personalized medicine strategies.
- Healthcare Modernization in China:Government investment in hospital infrastructure, combined with NMPA regulatory support, accelerates adoption of advanced diagnostic platforms.
- Oncology Screening Demand:A clinical shift toward population-level cancer screening programs drives high test volumes for immunoassays and molecular diagnostics.
Market Restraints
- Complex Regulatory Pathways:Navigating disparate requirements like the US FDA's premarket approval and the EU's IVDR creates significant validation burdens and market-entry delays.
- High Capital Expenditure:Acquiring high-throughput automation systems for clinical chemistry represents a substantial financial barrier for many smaller laboratories.
- Data Interpretation Bottlenecks:Complex datasets from technologies like NGS require specialized bioinformatics expertise, a scarce resource limiting widespread adoption.
Strategic Opportunities
- Decentralized Testing Expansion:Deploying robust, low-cost point-of-care diagnostics for infectious diseases in underpenetrated rural regions of India and Brazil.
- AI in Predictive Diagnostics:Integrating machine learning with genomic data to identify novel biomarkers and develop predictive risk-scoring models for complex diseases.
- New Liquid Biopsy Applications:Expanding non-invasive liquid biopsy tests beyond oncology into areas like neurodegenerative diseases and advanced prenatal screening.
Industry Challenges
- Specialized Talent Shortages:A scarcity of trained bioinformaticians and molecular pathologists limits the ability of laboratories to effectively implement and scale next-generation sequencing workflows.
- LIS Integration Complexity:Integrating new, data-intensive diagnostic platforms with aging hospital Laboratory Information Systems (LIS) creates significant operational friction and data silos.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Diagnostics Market |
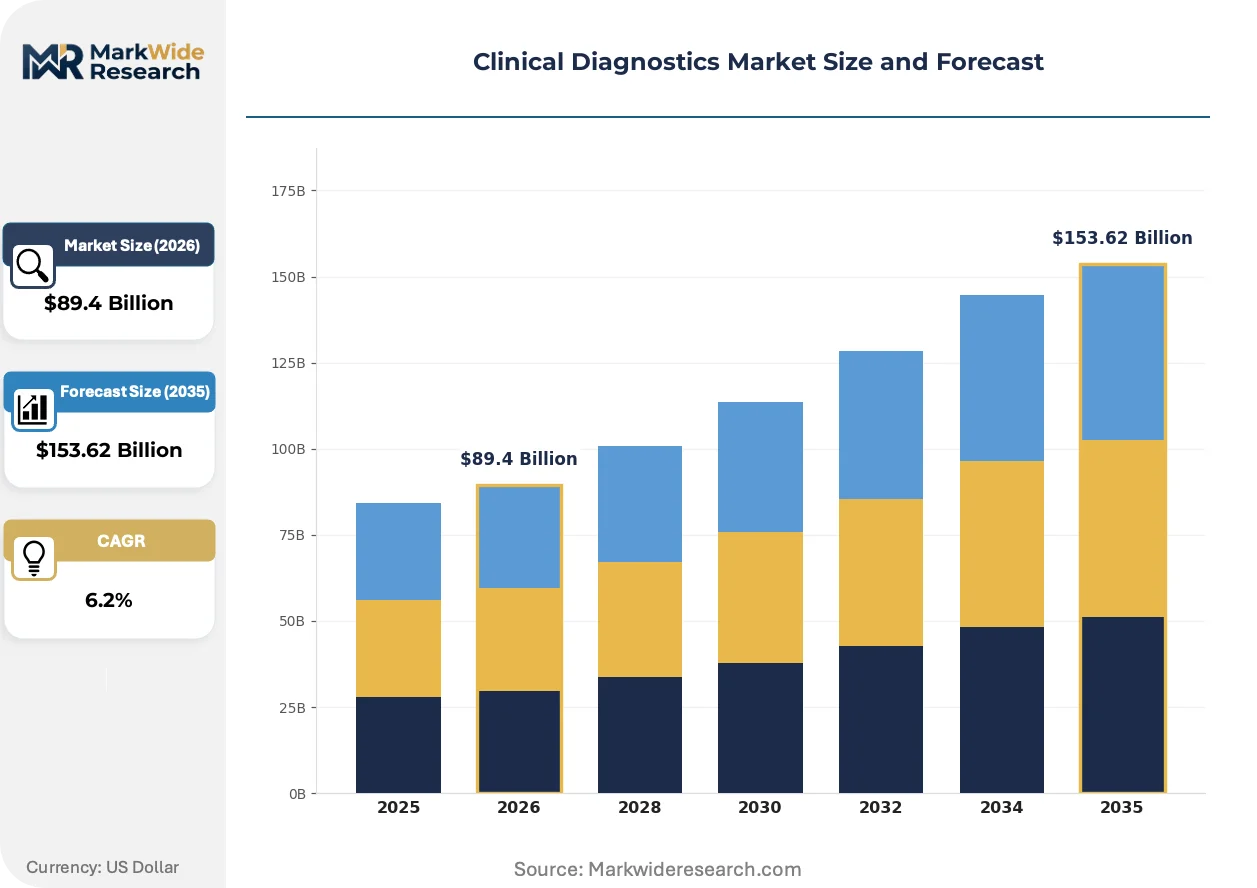
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $153.62 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunoassay Analyzers, Molecular Diagnostics, Hematology Analyzers, Clinical Chemistry Analyzers, Microbiology Systems Application: Cardiovascular Testing, Infectious Disease Detection, Oncology Screening, Metabolic Disorder Analysis, Genetic Testing End User: Diagnostic Laboratories, Research Institutes, Point-of-Care Centers, Blood Banks, Pharmaceutical Companies Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Flow Cytometry, Mass Spectrometry, Microarray Analysis |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher Corporation, Thermo Fisher Scientific, BD, bioMérieux SA, Bio-Rad Laboratories, Qiagen NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Diagnostics Market Strategic Shifts & Innovations
The pursuit of faster, more precise, and accessible diagnostic information is fundamentally altering instrument design and laboratory workflows. This evolution is defined by a technological push toward miniaturization and a parallel demand for integrated data analysis capabilities.
Microfluidic technology integrates complex laboratory functions onto a single chip using precisely controlled fluid flows. Point-of-care settings and outpatient clinics are rapidly adopting these systems for quick-turnaround results. This technology is miniaturizing sophisticated immunoassay and molecular tests, enabling their deployment outside the traditional centralized lab.
Europe's In Vitro Diagnostic Regulation (IVDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance. This forces manufacturers to conduct more rigorous performance studies and update technical documentation for all products sold in the EU. The regulation most heavily affects high-risk diagnostics, such as those for infectious diseases and cancer screening, compelling a complete overhaul of quality management systems.
A clear shift is occurring from purchasing standalone analyzers to acquiring total laboratory automation (TLA) solutions. High-volume reference labs are replacing piecemeal instrument procurement with integrated systems that connect pre-analytical, analytical, and post-analytical stages. This consolidation trend is most visible in the United States and Germany, where it addresses labor shortages and improves operational efficiency.
Clinical Diagnostics Market Segmentation
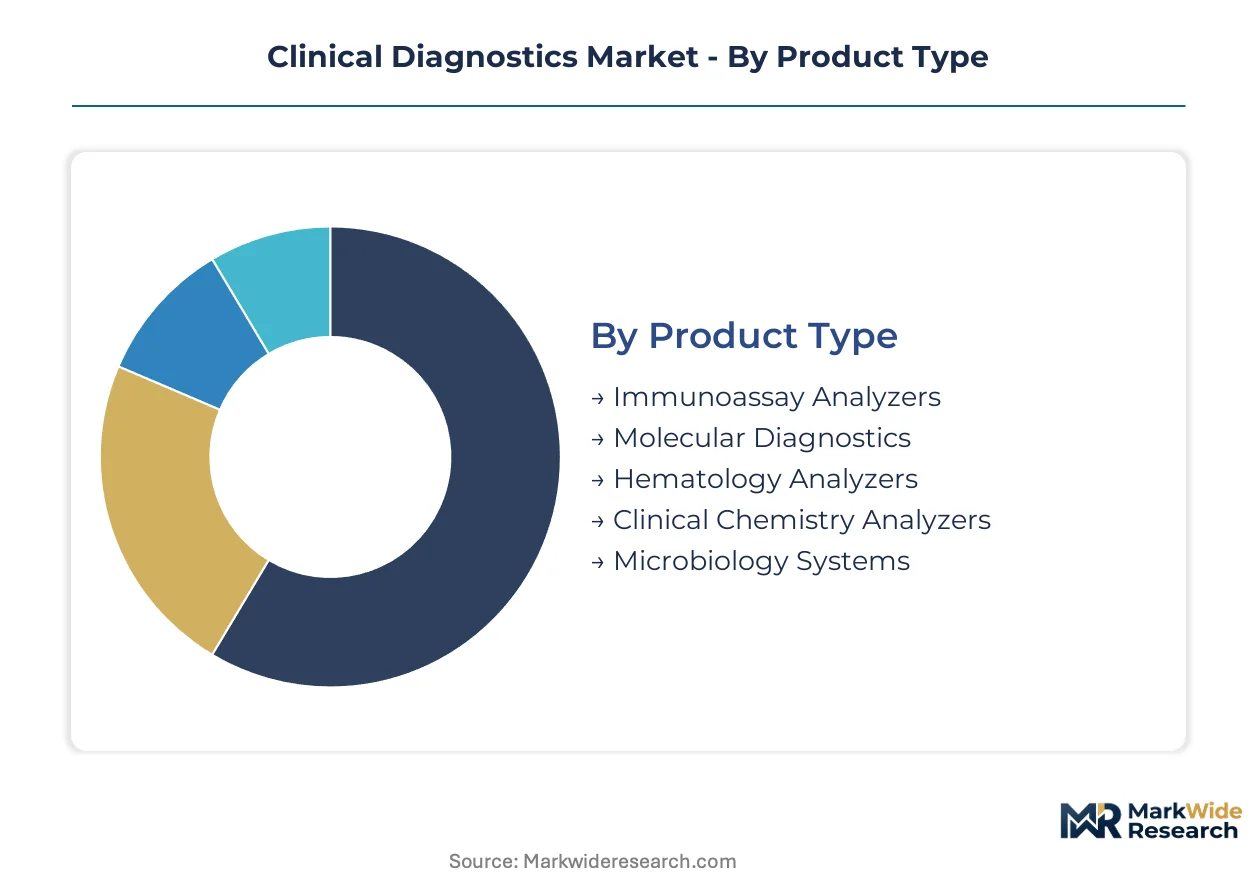
The Clinical Diagnostics Market exhibits diverse segmentation, reflecting varied technological approaches, application areas, and end-user requirements. Understanding these segments is critical for manufacturers to align product development with specific market needs and for healthcare providers to optimize diagnostic workflows.
Product Type:
Margin pools within this category heavily concentrate in molecular diagnostics due to their high specificity and advanced technology, while immunoassay analyzers capture significant volume-driven revenue.
- Molecular Diagnostics:This segment includes technologies like PCR and NGS, enabling precise detection of genetic material for disease diagnosis and pathogen identification. Demand is concentrating in oncology screening and personalized medicine strategies, driven by the superior specificity these methods offer for early and targeted interventions.
- Immunoassay Analyzers:These systems rely on antibody-antigen reactions, measured by techniques such as photometry or fluorescence, to quantify specific analytes in biological samples. Demand is substantial in routine testing and high-volume centralized laboratories, underpinned by established technology and broad applicability across numerous diagnostic areas.
- Hematology Analyzers:Automated instruments perform complete blood counts and differential analyses, crucial for diagnosing blood disorders and monitoring treatment.
- Clinical Chemistry Analyzers:These devices quantify various biochemical analytes in blood and urine, supporting the diagnosis of metabolic disorders and organ function assessment.
- Microbiology Systems:Instruments identify microbial pathogens and determine antibiotic susceptibility, essential for managing infectious diseases and public health.
The dominant share belongs to Immunoassay Analyzers, while Molecular Diagnostics is closing the gap fastest.
Application:
The highest test volumes in clinical diagnostics are driven by oncology screening and infectious disease detection, reflecting widespread public health priorities.
- Oncology Screening:This application focuses on early cancer detection, utilizing biomarker analysis and genetic profiling to identify malignancies at treatable stages. Demand is accelerating due to population-level screening programs and the shift towards personalized treatment protocols, improving patient outcomes through timely intervention.
- Infectious Disease Detection:This segment involves rapid and accurate identification of pathogens, crucial for outbreak management and effective treatment. Demand is high in point-of-care settings and public health initiatives, driven by urgent diagnostic needs and the global imperative to control infectious disease spread.
- Cardiovascular Testing:This category encompasses diagnostic tests for heart disease, including biomarker assessment for risk stratification and acute cardiac events.
- Metabolic Disorder Analysis:Tests in this area diagnose and monitor conditions like diabetes and thyroid dysfunction through the quantification of specific metabolic indicators.
- Genetic Testing:This application identifies inherited disease risks, pharmacogenomic responses, and chromosomal abnormalities, supporting personalized medical decisions.
Oncology Screening applications command significant revenue, with Genetic Testing demonstrating rapid expansion.
End User:
The operational models of diagnostic laboratories and point-of-care centers significantly influence instrument design and market penetration strategies.
- Diagnostic Laboratories:These facilities conduct centralized, high-throughput testing, often handling complex assays and specialized diagnostics for a wide patient base. Demand for these laboratories remains robust due to their economies of scale and extensive test menus, serving as reference points for intricate analyses.
- Point-of-Care Centers:These settings deploy rapid, decentralized testing solutions, providing immediate results closer to the patient. Demand is growing in remote and primary care environments, driven by the need for quick treatment initiation and enhanced accessibility to diagnostic services.
- Research Institutes:These entities utilize diagnostic tools for fundamental research, biomarker discovery, and the development of novel assays.
- Blood Banks:These facilities rely on clinical diagnostics for donor screening, blood typing, compatibility testing, and detection of infectious agents.
- Pharmaceutical Companies:These firms use diagnostic platforms for clinical trial support, patient stratification, and the development of companion diagnostics for new therapies.
Diagnostic Laboratories represent the largest user base, while Point-of-Care Centers are gaining share through accessibility.
Technology:
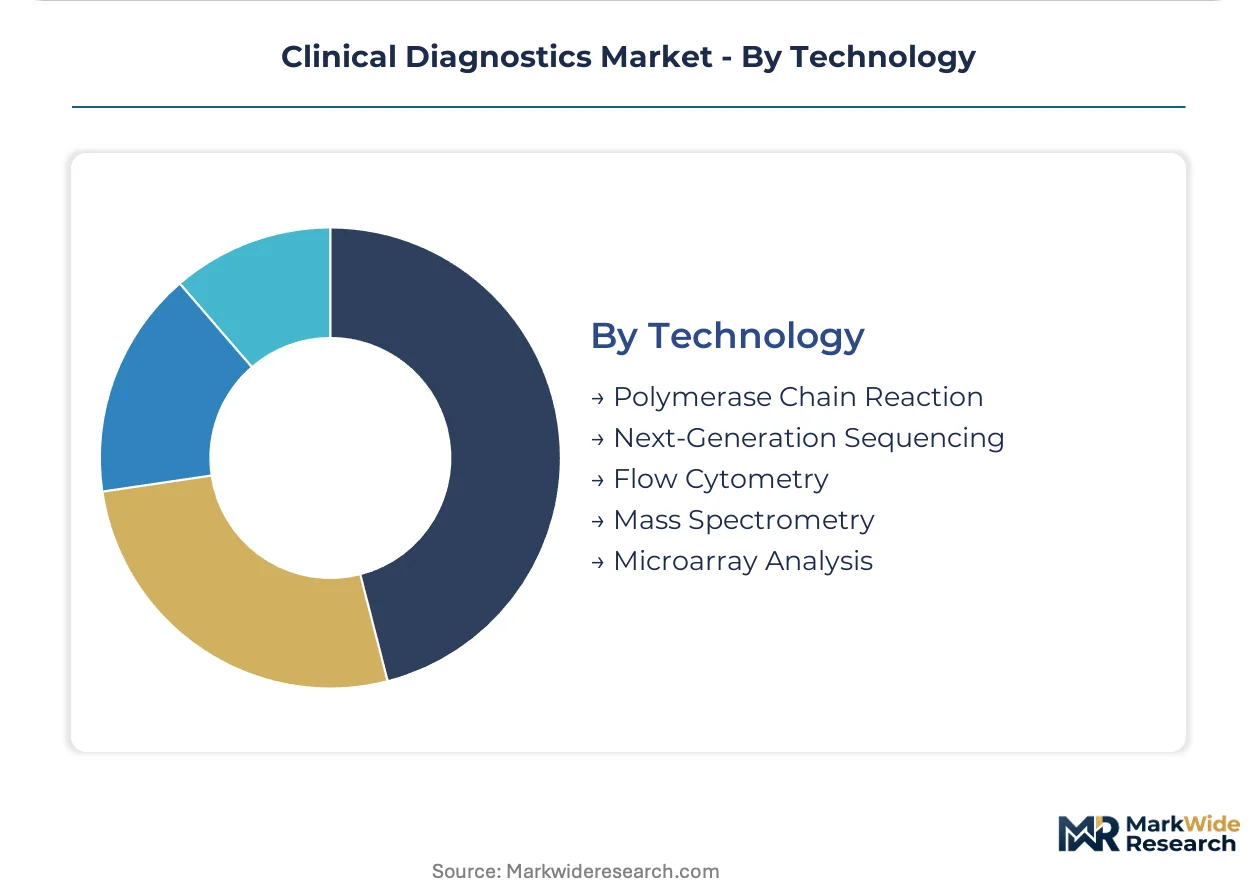
Next-Generation Sequencing offers unparalleled precision and depth of data, driving advanced diagnostic capabilities across various medical fields.
- Next-Generation Sequencing:This technology enables high-throughput DNA and RNA sequencing, providing comprehensive genomic profiling for disease characterization. Demand is concentrated in oncology and rare disease diagnosis, driven by the ability to generate extensive genetic information for personalized medicine approaches.
- Polymerase Chain Reaction:PCR technology amplifies specific DNA or RNA sequences, facilitating highly sensitive detection of pathogens and genetic mutations. Demand remains strong in infectious disease diagnosis and genetic testing, supported by its established methodology and high analytical sensitivity.
- Flow Cytometry:This technique analyzes and sorts cells based on light scattering and fluorescence properties, crucial for immunophenotyping and hematological malignancy diagnosis.
- Mass Spectrometry:This technology identifies and quantifies molecules based on their mass-to-charge ratio, applied in proteomics, metabolomics, and drug monitoring.
- Microarray Analysis:Microarrays are used for high-throughput gene expression profiling and detection of chromosomal abnormalities, supporting genetic research and diagnostics.
Polymerase Chain Reaction remains foundational, with Next-Generation Sequencing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Concentration in advanced diagnostic platform development and manufacturing influences global product availability and technological innovation for clinical diagnostics. This market dynamic shapes both demand patterns and the regulatory frameworks governing market access across various regions. Key countries drive significant investment and adoption in this sector.
United States
Demand for personalized medicine and oncology screening significantly drives innovation in diagnostic technologies. The US FDA's stringent premarket approval process sets a global benchmark for diagnostic device validation. Major biotechnology clusters in Boston and San Francisco accelerate the development of next-generation sequencing technologies and advanced assays.
Germany
Advanced healthcare infrastructure fuels consistent demand for high-throughput clinical chemistry and immunoassay systems. The European Union's Medical Device Regulation (MDR) requires stringent clinical evidence for all diagnostic products marketed within the bloc. Southern Germany's "MedTech Valley" around Erlangen and Tuttlingen hosts numerous established diagnostic manufacturers and innovative startups.
China
Healthcare modernization initiatives significantly expand the installed base of advanced diagnostic platforms across the country. The NMPA's approval process influences product design and localization strategies for foreign companies seeking market entry. Shanghai and Beijing serve as major hubs for diagnostic research, manufacturing, and attracting substantial foreign investment.
Japan
An aging population increases the need for early disease detection, chronic disease management, and preventative health screening. PMDA regulations ensure product safety and efficacy for in vitro diagnostics, fostering trust in advanced technologies. The Kansai region, including Osaka and Kyoto, is a prominent center for medical device and pharmaceutical innovation.
India
Expanding public and private healthcare access generates demand for affordable and decentralized diagnostic solutions, especially in rural areas. The CDSCO regulates in vitro diagnostic devices, emphasizing local manufacturing capabilities and broader accessibility. Bengaluru and Hyderabad are emerging as key centers for health tech innovation and diagnostic service providers.
Clinical Diagnostics Market Key Industry Players
Concentration sits with large, diversified healthcare technology conglomerates that leverage extensive R&D capabilities and global distribution networks. The market features a tiered structure, including established multi-national players, specialized molecular diagnostics firms, and emerging point-of-care solution providers. Portfolio diversification and strategic partnerships are dominant competitive moves among these entities.
Among the established global players, Swiss-based Roche Diagnostics represents a significant presence through its comprehensive immunoassay and molecular diagnostics portfolio. US-based Abbott Laboratories exemplifies strength in point-of-care solutions and infectious disease detection, serving both centralized and decentralized settings. Siemens Healthineers AG, a German medical technology company, occupies a strong position with its integrated automation systems for large clinical chemistry and hematology workflows. These companies anchor the market through their broad offerings and global reach.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher Corporation |
| Thermo Fisher Scientific |
| BD |
| bioMérieux SA |
| Bio-Rad Laboratories |
| Qiagen NV |
| Others |
Cost & Logistics Intelligence
Next-Generation Sequencing technology, as it substitutes for traditional assay methods, reshapes both the supply geography of diagnostic components and the pricing economics for advanced tests. This shift emphasizes specialized expertise over bulk reagent manufacturing.
Pricing Analysis
Europe's Medical Device Regulation (MDR) dictates the pricing tier structure for advanced diagnostic platforms, influencing market entry costs. Pricing stratifies across premium, standard, and economy tiers, often combining per-test transactional fees with instrument lease agreements. Price differentiation stems from regulatory approval levels, after-sales service, and test volume commitments. Pricing softness affects routine immunoassay testing, while specialized molecular diagnostics command premium pricing, with point-of-care centers exhibiting higher price sensitivity than large diagnostic laboratories.
Supply Chain Analysis
Port congestion along key Asia-Europe trade lanes increases inbound logistics costs for diagnostic components. Supply concentration centers on China for basic reagents, Germany for precision instrumentation, and the United States for advanced molecular diagnostics. The market relies on specialized enzymes and microfluidic chips as critical raw materials. Single-source vulnerability for highly specialized reagents represents a structural risk, while distribution runs through direct sales channels to large diagnostic laboratories and extensive distributor networks for point-of-care centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Clinical Diagnostics Market is undergoing a buyer-power shift as large diagnostic laboratory networks consolidate, increasing procurement leverage. This trend influences pricing and service expectations across the entire value chain.
For Market Incumbents: Fortify core market positions by investing heavily in next-generation sequencing R&D and integrated automation systems. Expand global distribution networks to counter the rise of emerging point-of-care solution providers. Achieve comprehensive IVDR compliance to maintain market access in Europe, turning regulatory shifts into a competitive advantage. Deepen vertical integration into specialized reagent manufacturing to mitigate supply chain risks.
For New Entrants and Emerging Players: Lead with robust, low-cost point-of-care diagnostics targeting underpenetrated rural regions of India and Brazil. Focus on infectious disease detection, a segment demanding rapid-turnaround solutions for urgent public health needs. Leverage microfluidic technology to miniaturize sophisticated tests, enabling deployment outside traditional centralized laboratories. Offer integrated data analysis capabilities to differentiate from established players.
For Investors and Strategic Acquirers: The market sits at a growth phase that favors specialized molecular diagnostics firms with strong intellectual property. Long-term viability remains strong, driven by aging populations and personalized medicine initiatives. Target AI-driven predictive analytics startups capable of integrating genomic data for novel biomarker discovery. Widespread reimbursement for new liquid biopsy applications beyond oncology serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Investment in NGS Platforms | Expands diagnostic capabilities for oncology screening, improving early disease detection. |
| IVDR Compliance Acceleration | Secures market access in the European Union, meeting stringent regulatory requirements. |
| Point-of-Care Product Development | Addresses demand for decentralized testing, particularly for infectious disease detection. |
| AI Integration for Predictive Diagnostics | Enhances biomarker identification, supporting personalized medicine strategies and risk models. |
| Strategic Partnerships with LIS Vendors | Improves data integration with hospital systems, reducing operational friction for laboratories. |
Research Approach
The analysis maps molecular diagnostics, immunoassay analyzers, and clinical chemistry, each validated through extensive interviews with clinicians and laboratory directors. Primary interviews with R&D directors, hospital procurement managers, and regulatory compliance officers provided critical insights. Secondary validation drew from US FDA filings, EU MDR guidance, and NMPA announcements. This approach utilized both bottom-up and top-down triangulation across diverse data points.
Forecast outputs were cross-referenced against historical market performance and macroeconomic indicators, ensuring internal consistency across the analysis window. The model segmented the market by product type, application, end user, technology, and regional regulatory frameworks. Compound annual growth rates were derived from a comprehensive model integrating historical trends and future projections. Key inputs included healthcare infrastructure investment and population-level screening program adoption rates.
Forecasts assume regulatory continuity in US FDA, EU MDR, and China NMPA regimes; material policy shifts would require re-modeling. Unforeseen global health crises or significant reimbursement changes represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market