
 Global Acute Kidney Injury Treatment Market | 2026-2036
Global Acute Kidney Injury Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Acute Kidney Injury Treatment Market Foresight
A shift from single-source dialysis procurement to multi-vendor agreements is pivoting purchasing power toward integrated health networks. Fresenius Medical Care anchors its position through captive manufacturing of dialyzers and concentrate solutions. Baxter International competes by leveraging its peritoneal dialysis portfolio across ambulatory settings. Pfizer Inc. differentiates through nephrology-focused pharmacological development pipelines.
Acute kidney injury treatment encompasses renal replacement modalities, pharmacological interventions, and hemodynamic support systems designed to restore electrolyte balance and fluid homeostasis in patients experiencing sudden renal function decline. Continuous renal replacement therapy operates at ultrafiltration rates of 20-35 ml/kg/hour in ICU environments to manage septic or cardiorenal syndrome patients. Dialysis equipment occupies the largest revenue pool due to capital intensity and recurring consumable demand, while pharmacological agents represent the fastest-expanding segment driven by novel tubular protective compounds. Kidney support devices command premium pricing in specialized diagnostic centers where biomarker-guided therapy personalization is standard.
The FDA enforces strict premarket review pathways for Class III renal devices under 510(k) and PMA frameworks, while the EMA's MDR transition demands enhanced clinical evidence for dialysis membrane biocompatibility claims. Japan's PMDA maintains accelerated approval channels for AKI diagnostics that demonstrate superior sensitivity for early tubular injury biomarkers. Stakeholders must monitor evolving reimbursement thresholds for home-based therapy delivery modes as payers recalibrate cost-effectiveness benchmarks against inpatient alternatives.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while elevating technical service requirements, forcing equipment manufacturers to embed predictive maintenance capabilities and outcome guarantees into standard contracts.
Growth Catalysts
- ICU capacity expansion:Health systems in Germany and Japan are adding dedicated nephrology units to manage cardiorenal syndrome admissions, creating installed base demand for continuous renal replacement systems.
- FDA pharmacovigilance mandates:Tighter premarket review pathways for nephrotoxic drug labels are accelerating companion diagnostic adoption alongside therapeutic interventions.
- Biomarker sensitivity thresholds:PMDA accelerated approval channels for tubular injury detection assays are shortening time-to-treatment windows in Japanese tertiary centers.
Market Restraints
- Membrane polymer supply concentration:Polysulfone and polyethersulfone resin production clusters in Germany and Japan create single-source vulnerability for dialyzer manufacturers.
- EMA MDR clinical evidence burdens:Enhanced biocompatibility documentation requirements for dialysis membranes are extending certification timelines by 18-24 months.
- Peritoneal dialysis substitution:Home-based ambulatory modalities are capturing stable chronic cases that previously generated recurring hemodialysis consumable revenue.
Strategic Opportunities
- India's nephrology infrastructure gap:Underpenetrated dialysis access in tier-2 cities creates white space for modular, lower-capital intensive treatment systems.
- AI-enabled dose personalization:Machine learning algorithms integrated with real-time clearance monitoring are enabling precision ultrafiltration protocols in academic medical centers.
- Home-based therapy reimbursement recalibration:CMS and private payers in the United States are expanding coverage for remote patient monitoring during nocturnal dialysis sessions.
Industry Challenges
- Specialized nephrology nursing shortages:CRRT operation requires certified ICU personnel that health systems in the United States and Germany struggle to recruit and retain.
- Legacy EMR integration complexity:New dialysis devices must interface with entrenched Epic and Cerner systems, adding 12-18 months to hospital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Acute Kidney Injury Treatment Market |
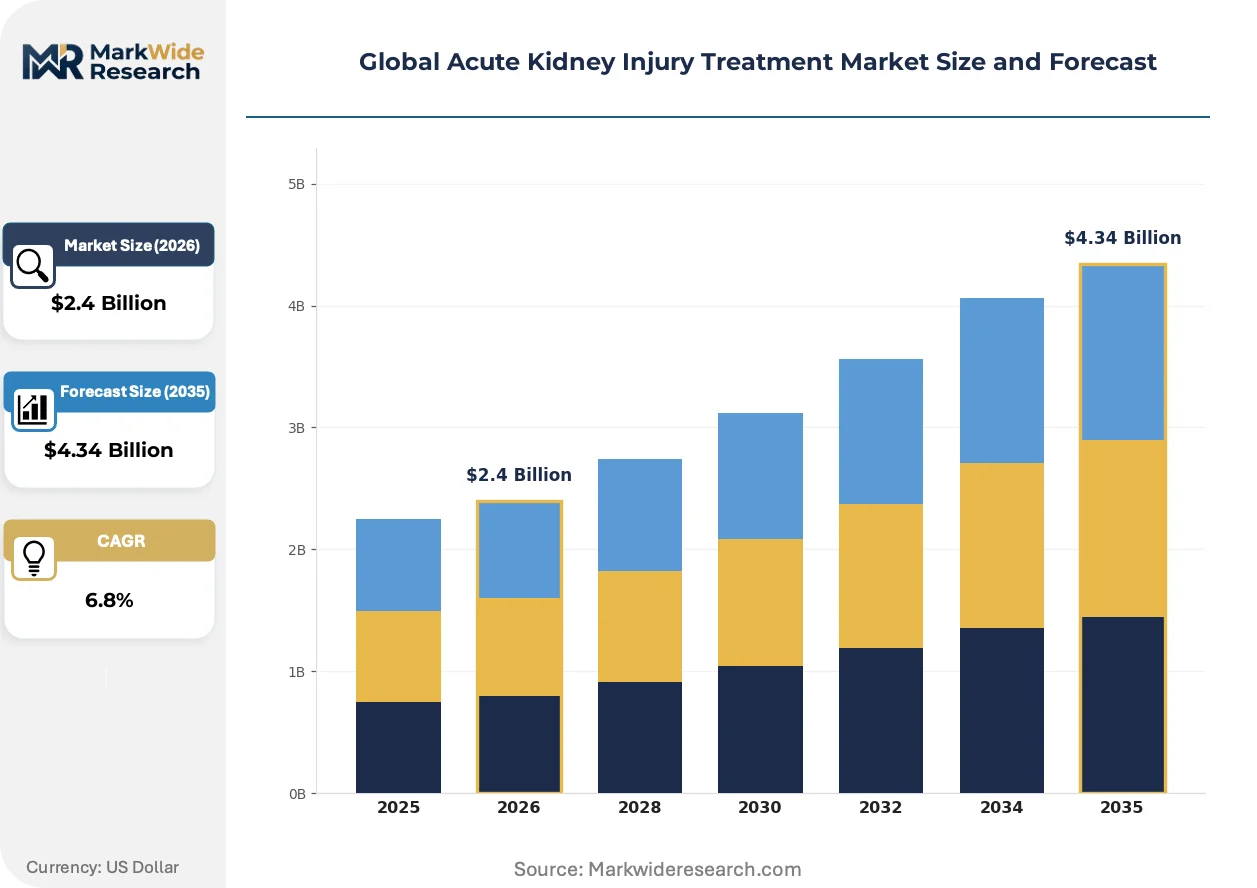
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialysis Equipment, Kidney Support Devices, Pharmacological Agents, Diagnostic Kits Therapy Area: Fluid Overload Management, Electrolyte Imbalance Correction, Renal Replacement Therapy, Hemodynamic Stabilization End User: Intensive Care Units, Nephrology Clinics, Emergency Departments, Specialized Diagnostic Centers Delivery Mode: Inpatient Treatment, Outpatient Care, Home-based Therapy, Ambulatory Care |
| Companies Covered | Pfizer Inc., Novartis AG, Fresenius Medical Care, Medtronic, Sanofi, Baxter International, AstraZeneca, Astellas Pharma Inc., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Acute Kidney Injury Treatment Market Shifts & Advancements
Real-time biomarker sensing and automated feedback loops are displacing protocol-driven dialysis, shifting clinical workflow from scheduled interventions to continuous physiological monitoring.
Sorbent-based regeneration systems are integrating portable water purification with dialysate recycling, enabling device miniaturization for transportable acute care. Military field hospitals and disaster response units in the United States and Israel are piloting these systems for expeditionary nephrology support. The technology is integrating hemofiltration and dialysis modalities into single-platform devices that reduce logistics burden and water consumption by 90%.
EMA's MDR transition is mandating post-market surveillance registries for all Class III renal devices, compelling manufacturers to fund multi-year outcome studies. This surveillance obligation is restructuring competitive economics toward players with balance sheet capacity to absorb longitudinal data collection costs. German and French notified bodies are prioritizing submissions with pre-registered clinical follow-up protocols.
Health network procurement committees are consolidating vendor rosters from 6-8 suppliers to 2-3 strategic partners, bundling device, consumable, and technical service spend. Integrated delivery networks in the United States are demanding total cost-per-treatment guarantees that transfer utilization risk to manufacturers. This concentration is visible most acutely in Texas and California health systems where three-network oligopsony controls 40% of acute dialysis purchasing volume.
Global Acute Kidney Injury Treatment Market Segmentation
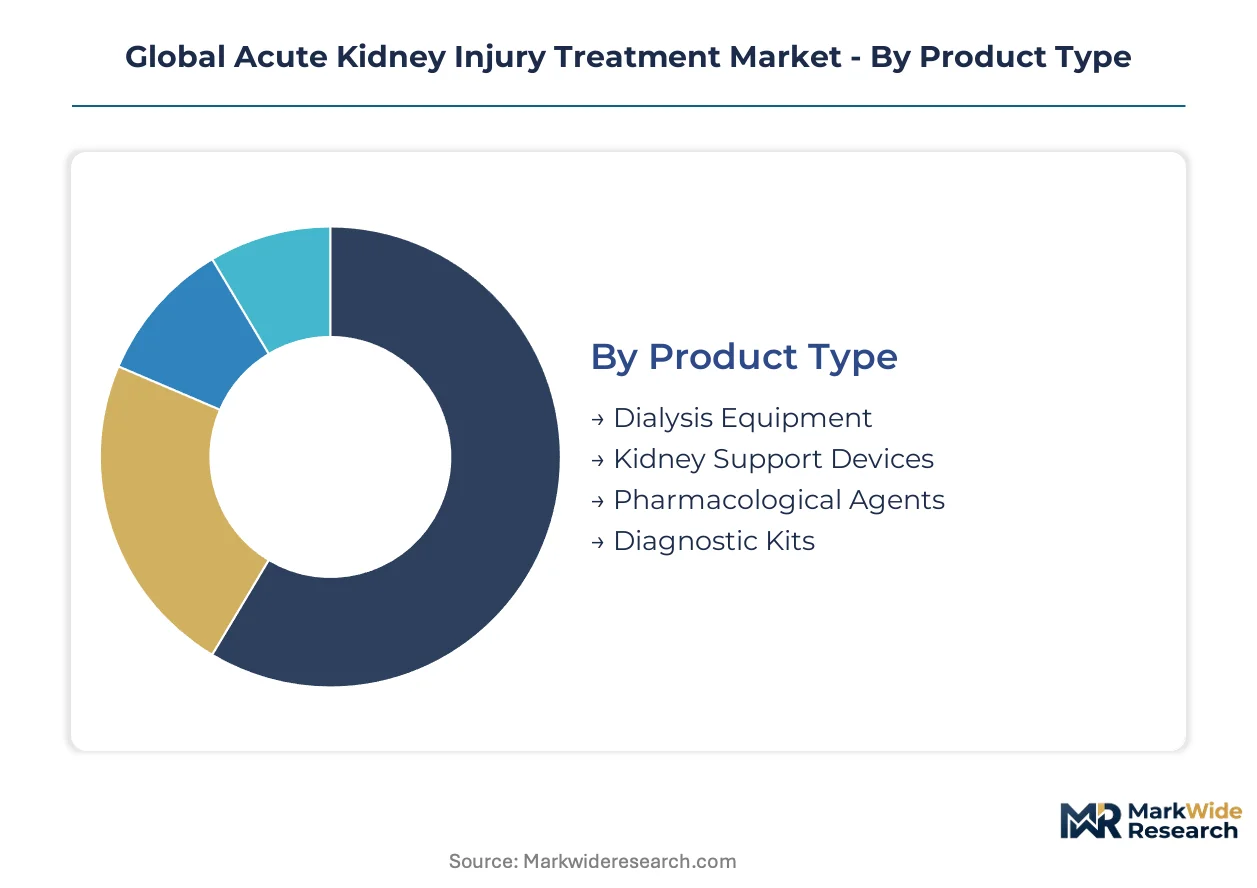
Treatment modality selection in acute kidney injury depends on clinical severity, hemodynamic stability, and infrastructure availability. Segmentation reveals where capital-intensive equipment dominates versus where pharmaceutical and diagnostic innovations are gaining traction. The analysis tracks how procurement patterns shift across care settings from ICU to home environments.
Product Type:
Dialysis equipment functions as standalone capital installations requiring dedicated plumbing and technical staffing, while kidney support devices and diagnostic kits embed into broader critical care workflows with lower standalone infrastructure demands.
- Dialysis Equipment:Hemodialysis and continuous renal replacement therapy systems operate at ultrafiltration rates of 20-35 ml/kg/hour in ICU environments. Demand concentrates in tertiary hospitals across Germany and Japan where cardiorenal syndrome admissions are climbing fastest; Fresenius Medical Care and Baxter International anchor supply through captive dialyzer manufacturing.
- Kidney Support Devices:Portable hemofiltration units integrate sorbent-based regeneration for water purification and dialysate recycling. Military field hospitals in the United States and Israel are piloting these systems for expeditionary nephrology support, reducing logistics burden and water consumption by 90%.
- Pharmacological Agents:Tubular protective compounds and nephrotoxic drug antidotes represent the fastest-expanding segment, driven by novel biomarker-guided dosing protocols.
- Diagnostic Kits:Early tubular injury biomarker assays enable PMDA accelerated approval channels in Japan, shortening time-to-treatment windows.
Volume placements concentrate in Dialysis Equipment; the faster expansion belongs to Pharmacological Agents.
Therapy Area:
Cost tier differentiation separates capital-intensive continuous modalities from lower-unit-cost intermittent interventions, with reimbursement thresholds varying sharply across inpatient versus ambulatory settings.
- Fluid Overload Management:Ultrafiltration protocols address volume expansion in congestive heart failure and septic patients. German nephrology units prioritize this indication amid expanding ICU capacity dedicated to cardiorenal syndrome admissions.
- Electrolyte Imbalance Correction:Intravenous bicarbonate and calcium infusions stabilize hyperkalemia and metabolic acidosis in emergency departments.
- Renal Replacement Therapy:Continuous and intermittent dialysis modalities restore solute clearance and fluid homeostasis in acute tubular necrosis. Academic medical centers in the United States are embedding AI-enabled dose personalization algorithms with real-time clearance monitoring.
- Hemodynamic Stabilization:Vasopressor protocols and inotropic support maintain perfusion pressure during AKI with multi-organ dysfunction.
Revenue concentration sits with Renal Replacement Therapy; Electrolyte Imbalance Correction is climbing the fastest as point-of-care testing expands.
End User:
Customer type determines technical service requirements and outcome guarantee structures, with integrated health networks demanding bundled contracts across device, consumable, and staffing support.
- Intensive Care Units:CRRT operation requires certified nephrology nursing personnel that health systems in the United States and Germany struggle to recruit and retain.
- Nephrology Clinics:Outpatient dialysis centers manage stable chronic cases transitioning from acute episodes.
- Emergency Departments:Rapid biomarker testing and temporary vascular access placement for urgent dialysis initiation.
- Specialized Diagnostic Centers:Premium-priced kidney support devices command placement where biomarker-guided therapy personalization is standard practice.
Installed base volumes cluster in Intensive Care Units; Specialized Diagnostic Centers are gaining share fastest through precision medicine adoption.
Delivery Mode:
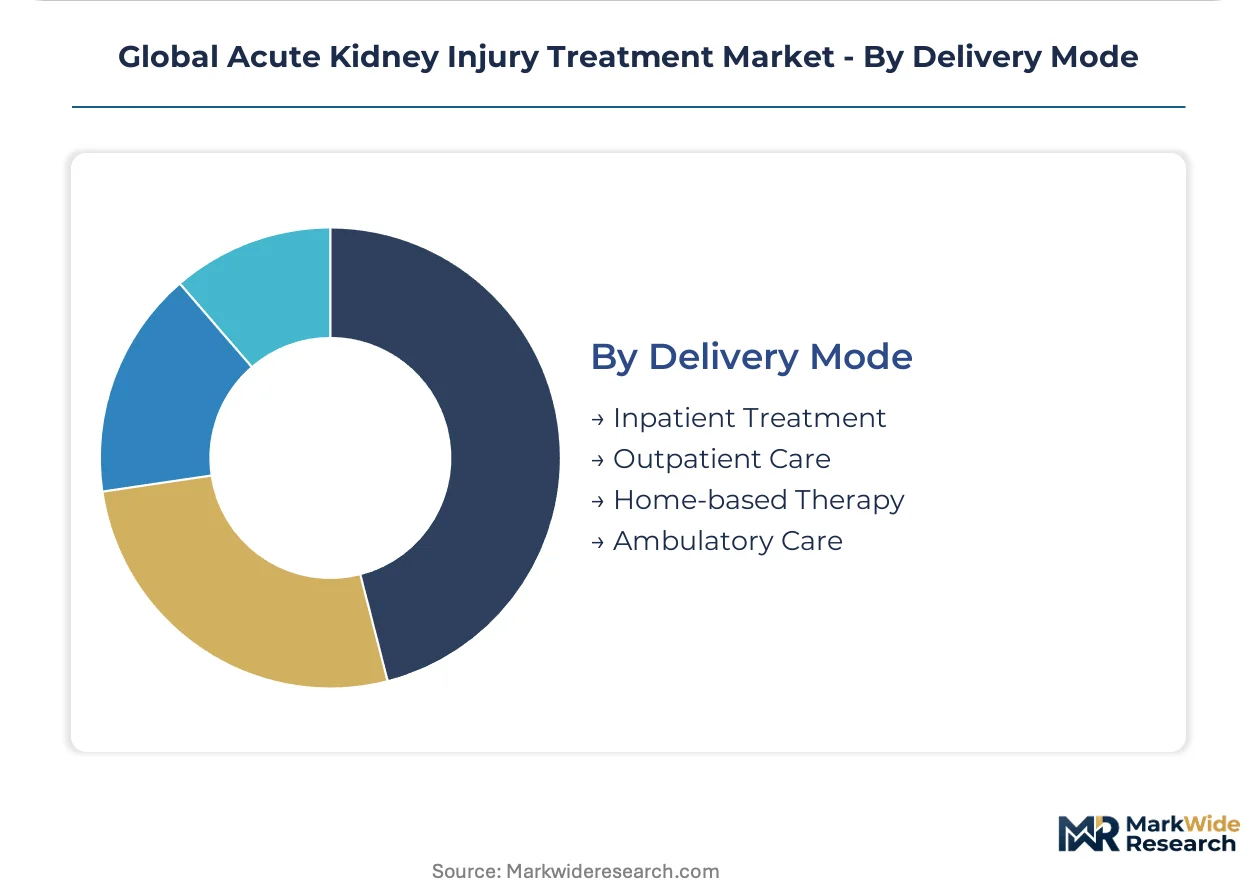
Maturity stage separates established inpatient reimbursement pathways from emerging home-based coverage frameworks undergoing recalibration by CMS and private payers.
- Inpatient Treatment:Tertiary hospital admissions generate the largest revenue pool through bundled DRG payments for acute dialysis.
- Outpatient Care:Ambulatory infusion centers manage subacute recovery and transitional dialysis.
- Home-based Therapy:Nocturnal dialysis with remote patient monitoring is expanding coverage under United States payer recalibration of cost-effectiveness benchmarks.
- Ambulatory Care:Peritoneal dialysis substitution is capturing stable chronic cases that previously generated recurring hemodialysis consumable revenue.
Revenue gravity centers on Inpatient Treatment; Home-based Therapy shows the steepest expansion trajectory as reimbursement frameworks evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems in the United States, Germany, and Japan concentrate installed base demand for continuous renal replacement therapy systems, while regulatory divergence across FDA, EMA, and PMDA frameworks shapes market entry velocity for device and pharmaceutical innovations.
United States
ICU capacity expansion in Texas and California health networks drives demand for CRRT systems, with three-network oligopsony controlling 40 percent of acute dialysis purchasing volume. FDA pharmacovigilance mandates for nephrotoxic drug labels accelerate companion diagnostic adoption. Academic medical centers in Boston and the Midwest embed AI-enabled dose personalization algorithms with real-time clearance monitoring.
Germany
Cardiorenal syndrome admissions climb fastest in tertiary hospitals across Bavaria and North Rhine-Westphalia, creating installed base demand for continuous renal replacement systems. EMA MDR transition demands enhanced clinical evidence for dialysis membrane biocompatibility claims, extending certification timelines. Polysulfone and polyethersulfone resin production clusters in Baden-Württemberg create supply concentration for dialyzer manufacturers.
Japan
Aging demographics drive ICU admissions in Tokyo and Osaka metropolitan areas, concentrating demand for acute kidney injury interventions. PMDA maintains accelerated approval channels for AKI diagnostics demonstrating superior sensitivity for early tubular injury biomarkers. Tertiary centers in Nagoya and Kyushu shorten time-to-treatment windows through biomarker-guided protocols.
India
Underpenetrated dialysis access in tier-2 cities creates white space for modular, lower-capital intensive treatment systems. The country's national pharmaceutical regulator evaluates nephrotoxic drug safety through pharmacovigilance programs aligned with WHO standards. Maharashtra and Gujarat host emerging manufacturing clusters for dialysis consumables serving domestic and export markets.
Israel
Military field hospitals pilot sorbent-based regeneration systems for expeditionary nephrology support, reducing logistics burden and water consumption. The national health system maintains centralized procurement for critical care devices. Tel Aviv medical technology clusters develop portable hemofiltration units integrating hemofiltration and dialysis modalities into single-platform devices.
Global Acute Kidney Injury Treatment Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers embed predictive maintenance capabilities and outcome guarantees into standard contracts. The vendor base compresses from six-to-eight suppliers toward two-to-three strategic partners per integrated health network, bundling device, consumable, and technical service spend. Three archetypes anchor positioning: captive dialyzer manufacturers with backward integration into membrane polymers, diversified critical care conglomerates with cross-modal dialysis portfolios, and pharmaceutical developers with nephrology-focused pipelines. M&A activity and geographic expansion represent the dominant competitive vectors as players absorb longitudinal data collection costs mandated by EMA post-market surveillance registries.
Among diversified critical care specialists, Fresenius Medical Care and Baxter International exemplify contrasting strategic positions. Fresenius anchors its position through captive manufacturing of dialyzers and concentrate solutions, occupying the integrated equipment-consumable archetype. Baxter competes by leveraging its peritoneal dialysis portfolio across ambulatory settings, representing the cross-modal diversification archetype. Pfizer Inc. sits within the pharmaceutical development tier, differentiating through nephrology-focused pipelines.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| Fresenius Medical Care |
| Medtronic |
| Sanofi |
| Baxter International |
| AstraZeneca |
| Astellas Pharma Inc. |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
Sorbent-based regeneration technology for portable dialysate recycling is compressing per-treatment cost economics while concentrating membrane polymer supply among German and Japanese resin producers. This production-method transition simultaneously enables device miniaturization for field deployment and tightens backward integration incentives for dialyzer manufacturers seeking supply security.
Pricing Analysis
Outcome guarantees and predictive maintenance bundles now separate premium-tier contracts from unbundled equipment-only sales in United States health network procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and geographic service density. Price erosion runs through standard-tier hemodialysis systems as procurement consolidation in Texas and California transfers utilization risk to manufacturers. Ambulatory peritoneal dialysis segments show highest price sensitivity due to home-based reimbursement recalibration.
Supply Chain Analysis
Direct-to-hospital channels handle CRRT system installations for integrated delivery networks, while distributor networks serve independent nephrology clinics. Polysulfone and polyethersulfone resin production clusters in Germany and Japan create single-source vulnerability for dialyzer membrane supply. Raw material dependencies center on medical-grade polymers, sorbent cartridges, and sterilization packaging. Tariff exposure on Chinese-sourced electronic components for device control systems elevates landed cost volatility. Distribution runs through specialized critical care equipment distributors with ISO 13485 certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA MDR post-market surveillance registries function as a cost-of-compliance moat, absorbing longitudinal data collection costs that only balance-sheet-capable manufacturers can sustain across the forecast window.
For Market Incumbents: Anchor market position through captive dialyzer manufacturing and sorbent cartridge backward integration to defend against peritoneal dialysis substitution. Prioritize predictive maintenance capability deployment and total cost-per-treatment guarantee structures to satisfy oligopsony procurement committees in United States health networks. Absorb EMA-mandated multi-year outcome study costs to exclude mid-cap competitors from Class III device certification pathways.
For New Entrants and Emerging Players: Capture white space in India's tier-2 city nephrology infrastructure gap with modular, lower-capital intensive CRRT systems designed for intermittent power and water scarcity. Target AI-enabled dose personalization algorithms as the most penetrable segment, embedding machine learning clearance monitoring for academic medical center pilot programs. Pursue software-as-medical-device pathways with 510(k) pre-submissions to bypass capital-intensive hardware manufacturing barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform roll-ups of AI-enabled renal monitoring startups by diversified critical care conglomerates seeking cross-modal dialysis portfolios. Long-term viability favors players with demonstrated MDR compliance infrastructure and installed base density in German tertiary hospitals. Watch FDA pharmacovigilance mandate expansion to nephrotoxic drug classes as the inflection signal for companion diagnostic valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR compliance enables Class III renal device market access across German and French health systems. |
| Hospital System Partnership | Integrated delivery network bundling secures 40% acute dialysis purchasing volume in Texas and California. |
| Backward Integration | Captive polysulfone resin production insulates Fresenius from German supply cluster concentration risk. |
| Software Companion Development | AI-enabled dose personalization algorithms command premium placement in Boston academic medical centers. |
| Reimbursement Strategy | CMS remote patient monitoring coverage expansion unlocks United States home-based nocturnal dialysis adoption. |
Research Methodology
Document review covered FDA 510(k) and PMA filings, EMA MDR submission databases, and Japanese PMDA accelerated approval records, complemented by interviews with ICU nephrology directors, hospital GPO contracts managers, biomedical engineers, and dialysis device procurement leads. Secondary validation drew from CMS Medicare reimbursement data, hospital procurement databases, and WHO pharmacovigilance program reports. Bottom-up installed base modeling and top-down health system expenditure analysis were triangulated against manufacturer revenue disclosures.
Segment-level value outputs were generated across treatment modality, therapy area, end-user setting, and delivery mode dimensions throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to historical CRRT adoption patterns and pharmacological pipeline advancement timelines. Model inputs incorporated ICU capacity expansion announcements from German and Japanese health ministries, PMDA biomarker sensitivity threshold guidance documents, and United States payer cost-effectiveness benchmark recalibration trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA notified body backlog resolution, polysulfone resin supply disruption events, and peritoneal dialysis reimbursement parity shifts. Projections reflect documented base assumptions regarding MDR transition timeline adherence and CMS remote monitoring coverage expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Renal Denervation Market
Nephrology
Renal Artery Embolization Market
Nephrology
Proteinuria Treatment Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
US Dialysis Services Market
Nephrology
Kidney Transplant Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market