
 Global Cervical Cancer Diagnostics and Therapeutics Market | 2026-2036
Global Cervical Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cervical Cancer Diagnostics and Therapeutics Market Foresight
HPV DNA testing is decoupling cervical cancer screening from traditional Pap smear economics by delivering higher sensitivity at lower long-run cost per case detected. Abbott Laboratories leverages integrated instrument-reagent platforms to sustain laboratory throughput advantages across high-volume screening networks. F. Hoffmann-La Roche Ltd anchors molecular diagnostics leadership through automated cobas HPV systems that dominate reference laboratory procurement in Europe and North America. Qiagen competes in sample preparation and assay content, occupying a critical position in the upstream workflow where nucleic acid extraction quality determines downstream diagnostic accuracy.
Cervical cancer diagnostics and therapeutics encompass screening modalities, confirmatory procedures, and treatment interventions targeting squamous cell and adenocarcinoma lesions of the uterine cervix, with HPV DNA detection relying on polymerase chain reaction amplification of high-risk viral genotypes in liquid-based cytology specimens. The primary purpose spans population-level precancerous lesion screening through therapeutic intervention monitoring for recurrence and treatment response. HPV DNA testing leads the product type dimension as national screening programs in Germany, Australia, and the Netherlands transition from cytology-primary to HPV-primary protocols. Next generation sequencing represents the fastest-growing technology segment as oncology centers adopt comprehensive genomic profiling to identify actionable targets in advanced or recurrent disease. Diagnostic laboratories capture the dominant margin pool in the end user dimension through centralized high-throughput processing that amortizes capital equipment across large patient cohorts.
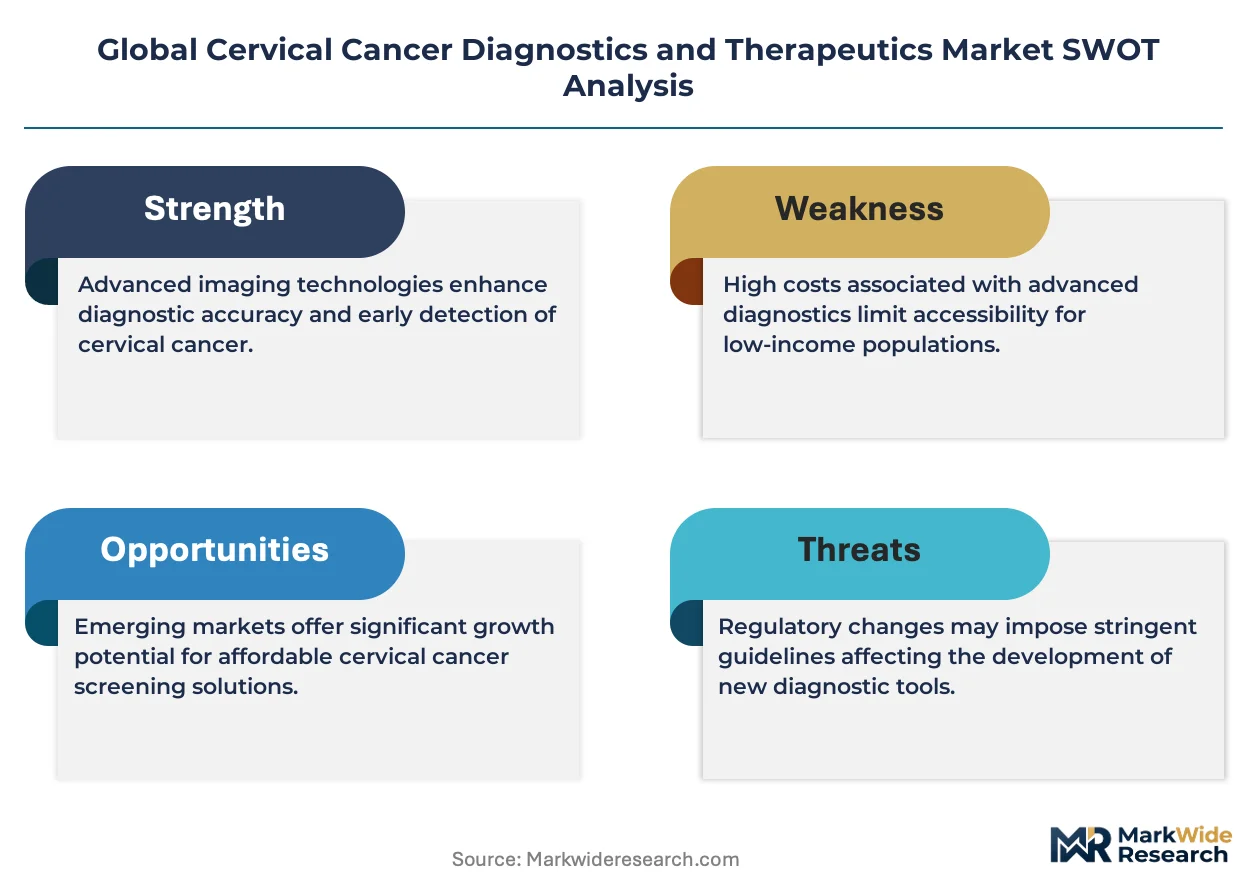
FDA premarket approval and EMA CE-IVD frameworks shape market access timelines for novel HPV genotyping assays, while WHO elimination strategy targets for cervical cancer incidence are driving national screening program expansion in lower-resource settings. The EU AI Act and FDA software-as-medical-device guidance are converging on algorithm-based cytology image analysis, creating new regulatory pathways for artificial intelligence-augmented screening tools. Stakeholders must monitor reimbursement decisions by Germany's Federal Joint Committee and Japan's Ministry of Health, Labour and Welfare as these determinations will signal which molecular platforms achieve sustainable volume adoption in the largest insured patient populations.
Market Dynamics
The transition from cytology-primary to HPV-primary screening protocols is restructuring laboratory procurement patterns and capital deployment priorities across oncology networks.
Growth Catalysts
- WHO elimination strategy targets:National screening program expansion in lower-resource settings is creating new addressable demand for molecular diagnostic platforms.
- FDA accelerated approval pathways:Companion diagnostics development timelines compress as regulatory frameworks prioritize oncology biomarker validation.
- Automated sample-to-answer systems:Reference laboratories in Germany, Japan, and the United States are consolidating instrument procurement around integrated workflow platforms.
Market Restraints
- Capital equipment intensity:High-throughput HPV DNA analyzers require substantial upfront laboratory infrastructure investment that limits adoption in budget-constrained settings.
- Reimbursement heterogeneity:Germany's Federal Joint Committee and Japan's Ministry of Health, Labour and Welfare maintain divergent coverage criteria that fragment market access.
- Sample preparation standardization:Nucleic acid extraction quality variability across collection sites introduces diagnostic accuracy risk that constrains test reliability.
Strategic Opportunities
- AI-augmented cytology image analysis:The EU AI Act and FDA software-as-medical-device guidance are converging on new regulatory pathways for algorithm-based screening tools.
- Next generation sequencing adoption:Oncology centers are deploying comprehensive genomic profiling for actionable target identification in advanced disease management.
- Point-of-care HPV testing:Decentralized molecular diagnostics penetration in rural India and sub-Saharan Africa addresses screening access gaps outside centralized laboratory networks.
Industry Challenges
- Cytopathologist workforce scarcity:Training pipeline limitations for specialized histopathology interpretation create diagnostic bottleneck constraints in screening program scale-up.
- CE-IVD technical documentation:EMA in vitro diagnostic regulation compliance timelines extend product launch schedules for novel genotyping assays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cervical Cancer Diagnostics and Therapeutics Market |
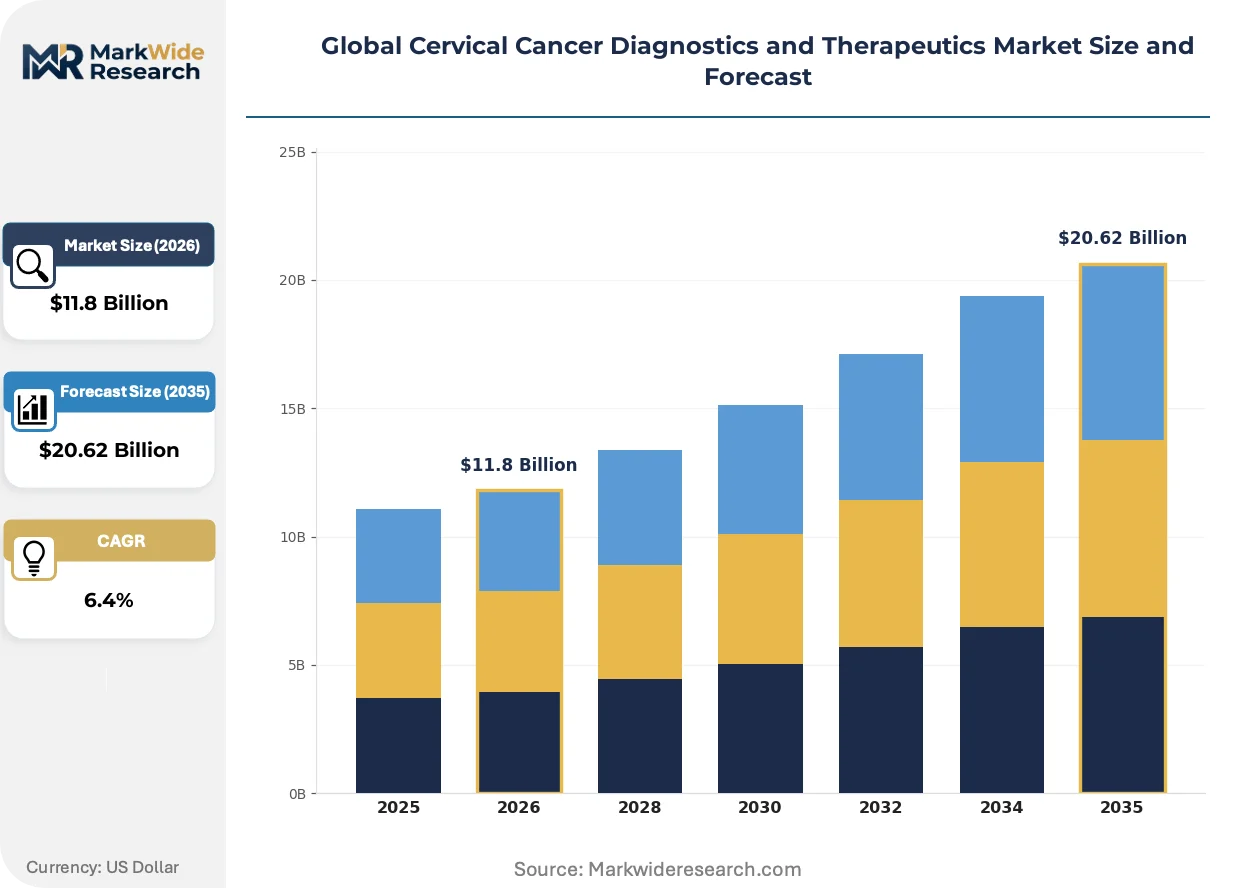
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pap Smear, HPV DNA Test, Colposcopy, Biopsy, Therapeutic Vaccine, Chemotherapy Application: Early Detection, Precancerous Lesion Screening, Treatment Monitoring, Post-Treatment Surveillance, Recurrence Analysis End User: Diagnostic Laboratories, Oncology Centers, Research Institutes, Specialized Clinics, Community Health Providers Technology: Polymerase Chain Reaction, Immunohistochemistry, Liquid-Based Cytology, Next Generation Sequencing, Radiotherapy, Targeted Therapy |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Qiagen, Merck & Co., Inc., Novartis AG, GlaxoSmithKline plc, Thermo Fisher Scientific, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cervical Cancer Diagnostics and Therapeutics Market Shifts & Advancements
Artificial intelligence integration and decentralized testing architectures are simultaneously compressing diagnostic turnaround times and expanding screening reach beyond traditional laboratory infrastructure.
Self-sampling HPV collection devices are decentralizing cervical cancer screening access by enabling specimen collection outside clinical settings. Community health programs in Australia and the Netherlands have validated mail-based sampling logistics. This architecture reduces patient visit burden while maintaining nucleic acid specimen integrity for centralized PCR processing.
The EU AI Act risk classification framework for medical device software is mandating algorithm validation standards that exceed prior CE-IVD technical documentation requirements. European pathology laboratories must now demonstrate clinical performance equivalence for AI-augmented cytology systems. Germany's reference laboratory networks are prioritizing vendors with pre-validated algorithm training datasets.
Consolidated procurement by hospital system integrated delivery networks is displacing independent laboratory purchasing autonomy in the United States. Large health systems in California and Texas are negotiating enterprise-wide HPV testing contracts that span multiple facility sites. This concentration shifts vendor relationship management from site-level clinical pathologists to centralized supply chain functions.
Global Cervical Cancer Diagnostics and Therapeutics Market Segmentation
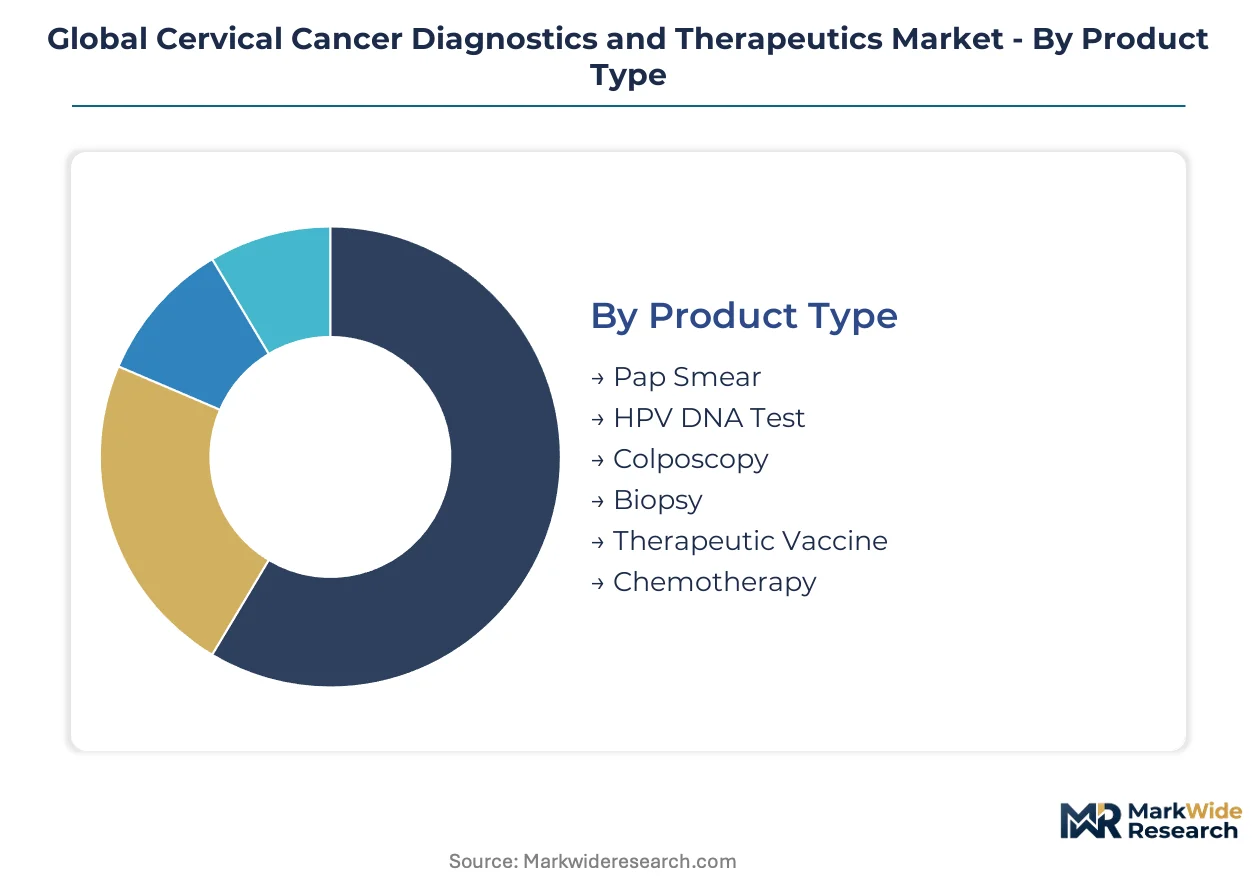
Cervical cancer diagnostics and therapeutics fragment across four distinct dimensions that shape procurement priorities and margin capture. Product type and technology segments determine capital intensity and workflow integration requirements, while application and end user categories dictate reimbursement pathways and patient access models.
Product Type:
Clinical utility and cost per case detected separate buyers across screening and therapeutic modalities.
- HPV DNA Test:Polymerase chain reaction amplification of high-risk viral genotypes in liquid-based cytology specimens delivers superior sensitivity over cytology alone. Germany, Australia, and the Netherlands have transitioned national screening programs to HPV-primary protocols, compressing demand for conventional Pap smears while expanding molecular platform procurement.
- Pap Smear:Conventional cytology examination of cervical cell morphology retains residual volume in resource-limited settings where infrastructure for molecular testing remains underdeveloped. United States community health providers in rural Texas and Mississippi continue Pap-primary workflows due to reimbursement lag in Medicaid programs.
- Colposcopy:Magnified visual examination of cervical epithelium guides biopsy site selection following abnormal screening results.
- Biopsy:Histopathological tissue sampling provides definitive diagnosis of cervical intraepithelial neoplasia grade and invasion status.
- Therapeutic Vaccine:Prophylactic and therapeutic immunization approaches target HPV oncogenic proteins for lesion regression.
- Chemotherapy:Systemic cytotoxic agents including cisplatin and paclitaxel regimens address locally advanced and metastatic disease.
Volume sits with HPV DNA testing and Pap smear screening; growth tilts toward therapeutic vaccines as immunotherapy pipelines mature.
Application:
Point in disease progression determines test sensitivity requirements and reimbursement coding complexity.
- Early Detection:Population-level asymptomatic screening targets precancerous transformation before invasive disease develops. Australia's national cervical screening program and Japan's regional pilot programs demonstrate highest per-capita testing intensity where coverage exceeds eighty percent of eligible women.
- Precancerous Lesion Screening:Cervical intraepithelial neoplasia identification through combined cytology and HPV triage protocols dominates laboratory throughput in European reference networks. Germany's statutory health insurance funds have expanded coverage for extended genotyping panels that distinguish HPV 16/18 from other high-risk types.
- Treatment Monitoring:Response assessment during chemoradiation protocols utilizes imaging and tumor marker surveillance.
- Post-Treatment Surveillance:Follow-up testing protocols after hysterectomy or conservative therapy completion track for residual disease.
- Recurrence Analysis:Comprehensive genomic profiling of metastatic lesions identifies actionable therapeutic targets.
Early detection commands the largest patient volume; precancerous lesion screening exhibits the steepest expansion trajectory as HPV-primary protocols diffuse.
End User:
Capital equipment scale and reimbursement contracting authority concentrate demand differently across provider types.
- Diagnostic Laboratories:Centralized high-throughput processing facilities amortize automated HPV analyzers across large patient cohorts. Quest Diagnostics and Laboratory Corporation of America processing networks in California and New York handle substantial volume under capitated contracts with integrated delivery networks.
- Oncology Centers:Academic medical centers in Boston and Houston deploy next generation sequencing platforms for comprehensive genomic profiling of advanced disease. Memorial Sloan Kettering and MD Anderson therapeutic decision-making drives companion diagnostic test adoption.
- Research Institutes:Translational oncology programs investigate novel biomarker validation and therapeutic target discovery.
- Specialized Clinics:Gynecologic oncology practices provide colposcopy and biopsy services with rapid histopathology turnaround.
- Community Health Providers:Federally qualified health centers and rural health clinics address screening access gaps in underserved populations.
Diagnostic laboratories capture dominant margin pools; oncology centers are gaining share fastest through precision medicine integration.
Technology:
Workflow automation and data output complexity differentiate platform investment requirements.
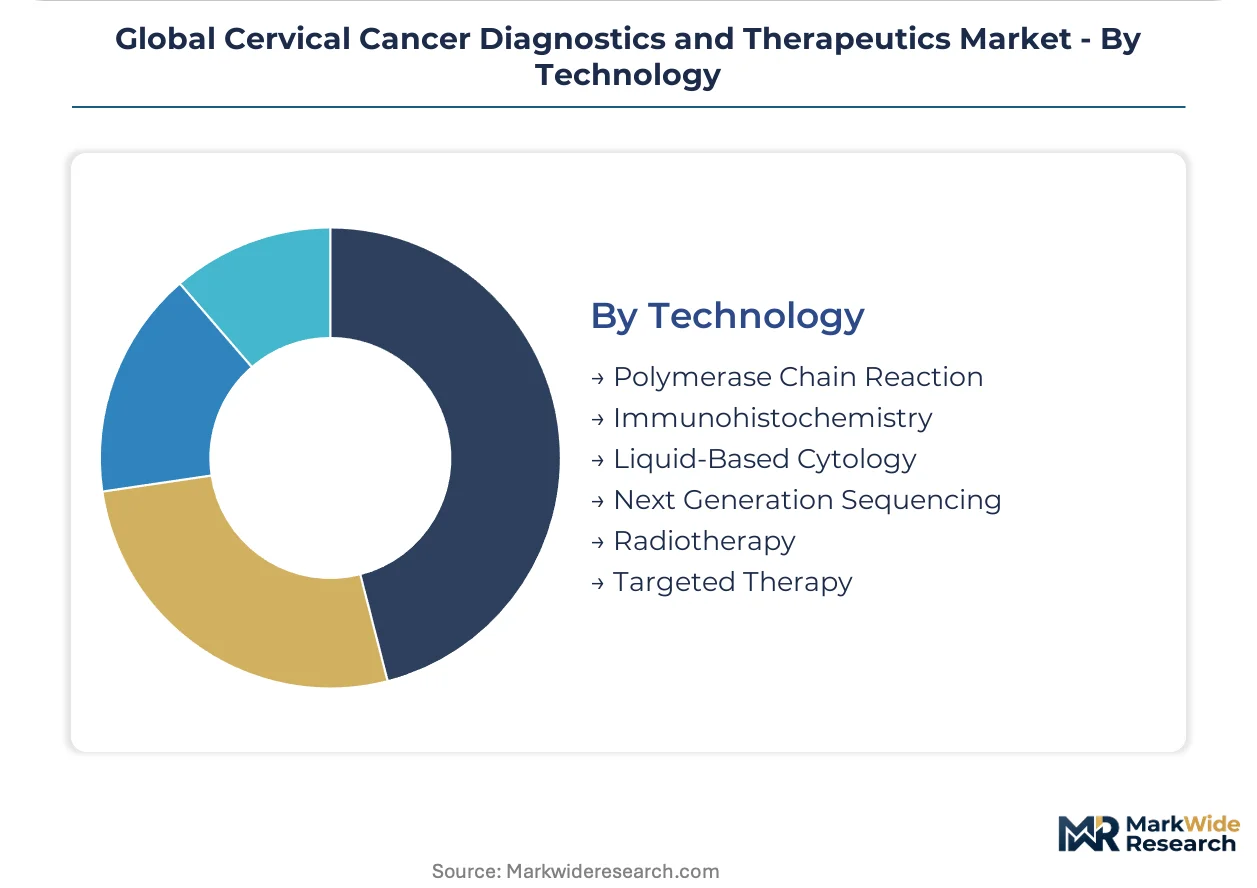
- Polymerase Chain Reaction:Nucleic acid amplification of HPV DNA sequences underpins current screening program infrastructure. Roche cobas and Abbott Alinity platforms dominate European and North American reference laboratory procurement through integrated sample-to-answer automation.
- Next Generation Sequencing:Massively parallel sequencing enables comprehensive genomic profiling of tumor mutational burden and microsatellite instability. Foundation Medicine and Tempus oncology panels are expanding reimbursement coverage for therapy selection in recurrent cervical cancer.
- Liquid-Based Cytology:Preservative fluid collection systems enable automated slide preparation and computer-assisted screening.
- Immunohistochemistry:Antibody-based protein detection characterizes tumor histology and PD-L1 expression status.
- Radiotherapy:External beam and brachytherapy delivery systems target localized disease with precision dose distribution.
- Targeted Therapy:Bevacizumab and pembrolizumab mechanisms exploit angiogenesis and immune checkpoint inhibition pathways.
Polymerase chain reaction anchors current volume; next generation sequencing climbs the fastest as comprehensive profiling penetrates advanced disease management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan where screening program coverage and reimbursement for molecular diagnostics remain most extensive. WHO elimination strategy targets are simultaneously expanding national screening programs in lower-resource settings. Regulatory frameworks across multiple geographies are reshaping product development timelines and market access pathways.
United States
FDA accelerated approval pathways for companion diagnostics compress oncology biomarker validation timelines. Integrated delivery networks in California and Texas negotiate enterprise-wide HPV testing contracts spanning multiple facility sites. Memorial Sloan Kettering and MD Anderson drive precision medicine adoption through comprehensive genomic profiling platforms.
Germany
The Federal Joint Committee expanded statutory health insurance coverage for extended HPV genotyping panels distinguishing HPV 16/18 from other high-risk types. Reference laboratory networks prioritize vendors with pre-validated algorithm training datasets under EU AI Act risk classification frameworks. Bavaria-based screening infrastructure handles substantial molecular diagnostic throughput across centralized high-volume processing facilities.
Japan
The Ministry of Health, Labour and Welfare determines sustainable volume adoption for molecular platforms across the largest insured patient populations. Regional pilot programs demonstrate highest per-capita testing intensity where coverage exceeds eighty percent of eligible women. Tokyo and Osaka academic medical centers deploy next generation sequencing for therapy selection in recurrent cervical cancer.
Australia
The national cervical screening program transitioned to HPV-primary protocols, compressing conventional Pap smear demand while expanding molecular platform procurement. Community health programs validated mail-based self-sampling logistics enabling specimen collection outside clinical settings. Sydney and Melbourne reference networks process decentralized samples while maintaining nucleic acid integrity for centralized PCR analysis.
India
Point-of-care HPV testing addresses screening access gaps outside centralized laboratory networks in rural regions. The country's national pharmaceutical regulator evaluates molecular diagnostic platform registrations for expanded screening program deployment. Maharashtra and Karnataka host emerging diagnostic infrastructure serving high-volume patient cohorts with automated sample-to-answer systems.
Global Cervical Cancer Diagnostics and Therapeutics Market Competitive Landscape
Integrated instrument-reagent platform consolidation dominates the current landscape as laboratories prioritize workflow automation over point solutions. The vendor base spans three tiers: multinational conglomerates with full diagnostic portfolios, specialized molecular diagnostics firms, and emerging point-of-care developers. Strategic archetypes include platform-integrated systems providers, sample preparation specialists, and therapeutics-focused biopharmaceutical developers. M&A activity and technology licensing agreements represent the dominant competitive moves as participants seek complementary capabilities.
Within the platform-integrated tier, Abbott Laboratories and F. Hoffmann-La Roche Ltd occupy positions exemplifying laboratory throughput advantages across high-volume screening networks. Qiagen represents the sample preparation specialist archetype, anchoring upstream workflow positions where nucleic acid extraction quality determines diagnostic accuracy. These three companies collectively illustrate the competitive tension between end-to-end automation and modular best-of-breed procurement strategies.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Qiagen |
| Merck & Co., Inc. |
| Novartis AG |
| GlaxoSmithKline plc |
| Thermo Fisher Scientific |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Cytopathologist workforce scarcity in Germany and Japan generates labor-cost differentials that widen pricing-tier spreads between premium reference laboratory services and economy-tier community health providers. FDA and EMA regulatory compliance burdens concentrate in high-throughput processing centers, compressing margins at the standard tier while insulating premium pricing for validated automated platforms.
Pricing Analysis
Volume concentrates in capitated screening contracts while margins concentrate in companion diagnostic and genomic profiling services. Three-tier pricing structure across premium, standard, and economy levels separates integrated instrument-reagent platforms from modular assay components and basic cytology consumables. Pricing pressure stems from Medicaid reimbursement lag in rural United States markets. Community health providers exhibit highest price sensitivity; academic oncology centers demonstrate lowest sensitivity due to precision medicine budget allocations.
Supply Chain Analysis
Polymerase chain reaction reagent supply rests on German and United States specialty chemical producers with secondary concentration in Japanese precision manufacturing. Critical inputs include thermostable DNA polymerases, fluorescent probe chemistries, and liquid-based cytology preservative fluids. Single-source vulnerability in high-fidelity enzyme supply creates concentration risk for assay manufacturers. Distribution runs through diagnostic laboratory GPO contracts and direct hospital system procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained through cytopathologist training pipeline bottlenecks that prop pricing for automated image analysis platforms. Capacity scarcity in specialized histopathology interpretation sustains premium tiers even as molecular testing commoditizes.
For Market Incumbents: Anchor market position through backward integration into nucleic acid extraction chemistry manufacturing, capturing upstream margin pools currently held by sample preparation specialists. Defend against point-of-care molecular disruptors by embedding companion diagnostic content within therapeutic development partnerships. Prioritize EU AI Act pre-validation investments to secure reference laboratory procurement in Germany. For New Entrants and Emerging Players: Telemedicine-integrated self-sampling logistics offer the lowest customer acquisition cost pathway into underserved rural India and sub-Saharan Africa screening programs. White-space concentration sits with decentralized HPV testing outside centralized laboratory networks. Mail-based specimen collection partnerships with community health programs provide viable go-to-market architecture. For Investors and Strategic Acquirers: Re-rating potential sits with sample preparation automation specialists given WHO elimination strategy procurement acceleration in lower-resource settings. Long-term viability favors platform-integrated systems providers over point-solution vendors. Monitor Germany's Federal Joint Committee reimbursement decisions as the signal indicating sustainable volume adoption for extended genotyping panels.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Technical Documentation Pathway | EMA compliance timelines determine competitive launch sequencing for novel HPV genotyping assays. |
| Hospital System Partnership | Integrated delivery networks in California consolidate procurement authority across multi-site screening contracts. |
| Software Companion Development | FDA software-as-medical-device guidance creates regulatory pathway for AI-augmented cytology image analysis. |
| Reimbursement Strategy | Japan's Ministry of Health, Labour and Welfare coverage determinations signal molecular platform adoption sustainability. |
| Manufacturing Scale-Up | Automated sample-to-answer system production capacity constraints limit addressable market expansion in India. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with clinical laboratory directors, pathology department heads, diagnostic assay R&D leads, and hospital GPO contract managers combined with FDA 510(k) submissions, EMA CE-IVD technical documentation, and WHO cervical cancer elimination strategy progress reports. Bottom-up instrument placement modeling and top-down screening program expenditure estimates were triangulated to validate market sizing.
Data-stream reconciliation across manufacturer shipment reports, laboratory capital expenditure disclosures, and national health accounts expenditure data informed the analytical framework. Segmentation dimensions spanned product type, technology platform, application stage, and end-user category across the projection horizon. CAGRs were derived from instrument placement velocity, assay volume per installed base, and reimbursement trajectory modeling. HPV-primary protocol transition timelines and companion diagnostic approval pathways served as industry-specific forecast inputs.
The model holds under stable regulatory reimbursement environments; deviation in FDA software-as-medical-device enforcement posture or major European Union IVD regulation implementation delays would shift adoption curves. Forecasts reflect documented assumptions regarding screening program expansion rates and molecular platform replacement cycles. Reimbursement policy reversals in Germany or Japan, alongside cytopathologist workforce supply shocks, constitute the small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market