
 Global Blood Gas Analyzers Market | 2026-2036
Global Blood Gas Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Gas Analyzers Market Analysis
CE marking under the EU Medical Device Regulation is collapsing the competitive field for non-European manufacturers seeking European market access. Danaher Corporation leverages its vertical integration across sensor manufacturing and diagnostic platforms to sustain pricing power in bench-top systems. Werfen S.A. anchors its position through specialized critical care applications, while Abbott Laboratories competes aggressively in the portable analyzer segment with point-of-care deployment capabilities.
Blood gas analyzers are clinical diagnostic instruments that measure pH, partial pressures of oxygen and carbon dioxide, and electrolyte concentrations in arterial or venous blood samples using electrochemical or optical sensor arrays, primarily to guide ventilation management and acid-base disorder treatment in acute care settings. Portable analyzers are capturing the fastest expansion as hospitals decentralize testing to emergency departments and surgical suites, while bench-top systems still dominate laboratory revenue streams due to higher throughput and multi-parameter menu breadth. Electrochemical sensor technology leads installed base volumes, though optical sensors are gaining ground in handheld formats where calibration stability and reduced maintenance cycles command premium positioning.
The FDA regulates these devices as Class II medical products requiring 510(k) premarket notification, while the EU MDR imposes stricter clinical evidence requirements for legacy device recertification, effectively filtering smaller manufacturers from both markets. China's NMPA has accelerated review timelines for innovative diagnostic equipment under its priority review pathway, redirecting R&D investment toward dual-registered products. Stakeholders must monitor evolving CLIA complexity classifications in the United States and MDR transition deadlines in Europe, as these regulatory gatekeepers will determine which product portfolios retain commercial viability across the largest addressable markets.
Market Dynamics
The decentralization of critical care diagnostics is restructuring competitive advantage around portable analyzer deployment speed and CLIA waiver compliance rather than laboratory throughput alone.
Growth Catalysts
- Emergency department point-of-care expansion:Hospitals in the United States are relocating blood gas testing from central labs to trauma bays and surgical suites, accelerating demand for handheld electrochemical devices.
- EU MDR recertification deadlines:The collapsing timeline for legacy device compliance is filtering smaller competitors from European markets, concentrating volume among established manufacturers with clinical evidence reserves.
- Optical sensor miniaturization:Solid-state optical arrays are achieving calibration stability in handheld formats previously dominated by electrochemical methods, opening new deployment scenarios.
Market Restraints
- Palladium electrode supply concentration:Electrochemical sensor manufacturing depends on Russian and South African palladium refining, exposing production costs to geopolitical supply shocks.
- EU MDR clinical evidence requirements:Legacy device recertification demands prospective studies that smaller manufacturers cannot fund, structurally excluding them from the second-largest addressable market.
- Capillary blood sampling limitations:Point-of-care analyzers using capillary specimens face accuracy constraints in high-acuity hypoperfusion states, restricting substitution for arterial methods in ICU settings.
Strategic Opportunities
- China NMPA priority review pathway:Accelerated timelines for innovative diagnostic equipment are redirecting R&D investment toward dual-registered products targeting both Chinese and Western markets.
- Veterinary critical care expansion:Emergency and specialty animal hospitals in Germany and the United States are adopting human-grade portable analyzers for intraoperative monitoring.
- Integrated respiratory-renal parameter menus:Converging blood gas and creatinine testing on single cartridge platforms addresses bundled reimbursement incentives in US value-based care contracts.
Industry Challenges
- Biomedical engineering talent scarcity:Electrochemical sensor calibration and quality system management require specialized expertise that outpaces university program output in the United States and Germany.
- Multi-jurisdiction certification parallelism:Simultaneous FDA 510(k), EU MDR, and NMPA submissions demand redundant clinical studies and documentation systems, compressing R&D efficiency.
- Legacy LIS/HIS integration complexity:Point-of-care analyzers must interface with disparate hospital information architectures, requiring customized middleware development for each major health system.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Gas Analyzers Market |
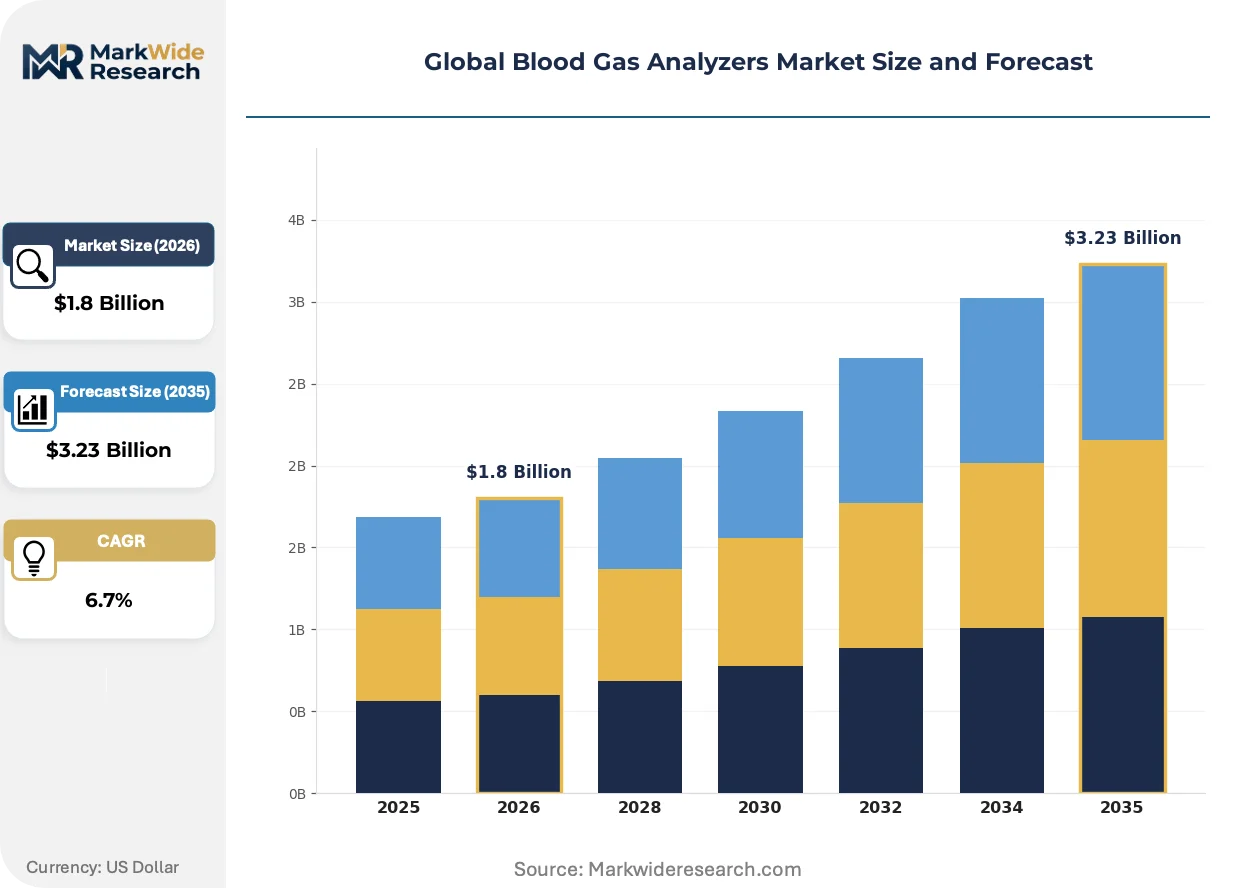
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Analyzers, Bench-top Analyzers, Hand-held Analyzers, Laboratory Analyzers End User: Hospitals, Clinics, Diagnostic Laboratories, Research Facilities Technology: Optical Sensors, Electrochemical Sensors, Mass Spectrometry, Microfluidics Application: Critical Care, Emergency Medicine, Surgical Procedures, Home Healthcare |
| Companies Covered | Danaher Corporation, Werfen S.A., F. Hoffmann-La Roche Ltd., Abbott Laboratories, Siemens Healthineers AG, Radiometer Medical ApS, Medica Corporation, Nova Biomedical, Instrumentation Laboratory, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Gas Analyzers Market Emerging Trajectories
Sensor architecture convergence and regulatory pathway fragmentation are forcing simultaneous investment in optical miniaturization and multi-jurisdiction compliance infrastructure.
Microfabricated solid-state optical sensors are supplanting traditional electrode-based measurement in handheld blood gas analyzers. Emergency medicine departments in the United States are adopting these devices for rapid turnaround in triage protocols. The shift is compressing maintenance cycles and enabling deployment in ambulatory settings previously inaccessible to electrochemical platforms.
EU MDR recertification requirements are collapsing the competitive field for non-European manufacturers seeking European market access. Legacy devices face mandatory clinical evidence generation that exceeds original 510(k) substantiation standards. Bench-top system manufacturers with established European notified body relationships are absorbing displaced volume from excluded competitors.
Hospital procurement departments are consolidating analyzer contracts under multi-parameter platform agreements that bundle blood gas, electrolyte, and metabolite testing. Independent service organizations are losing maintenance revenue as manufacturers capture aftermarket value through captive reagent and calibration contracts. The United States exhibits the most pronounced concentration, with integrated delivery networks standardizing across regional footprints.
Global Blood Gas Analyzers Market Segmentation
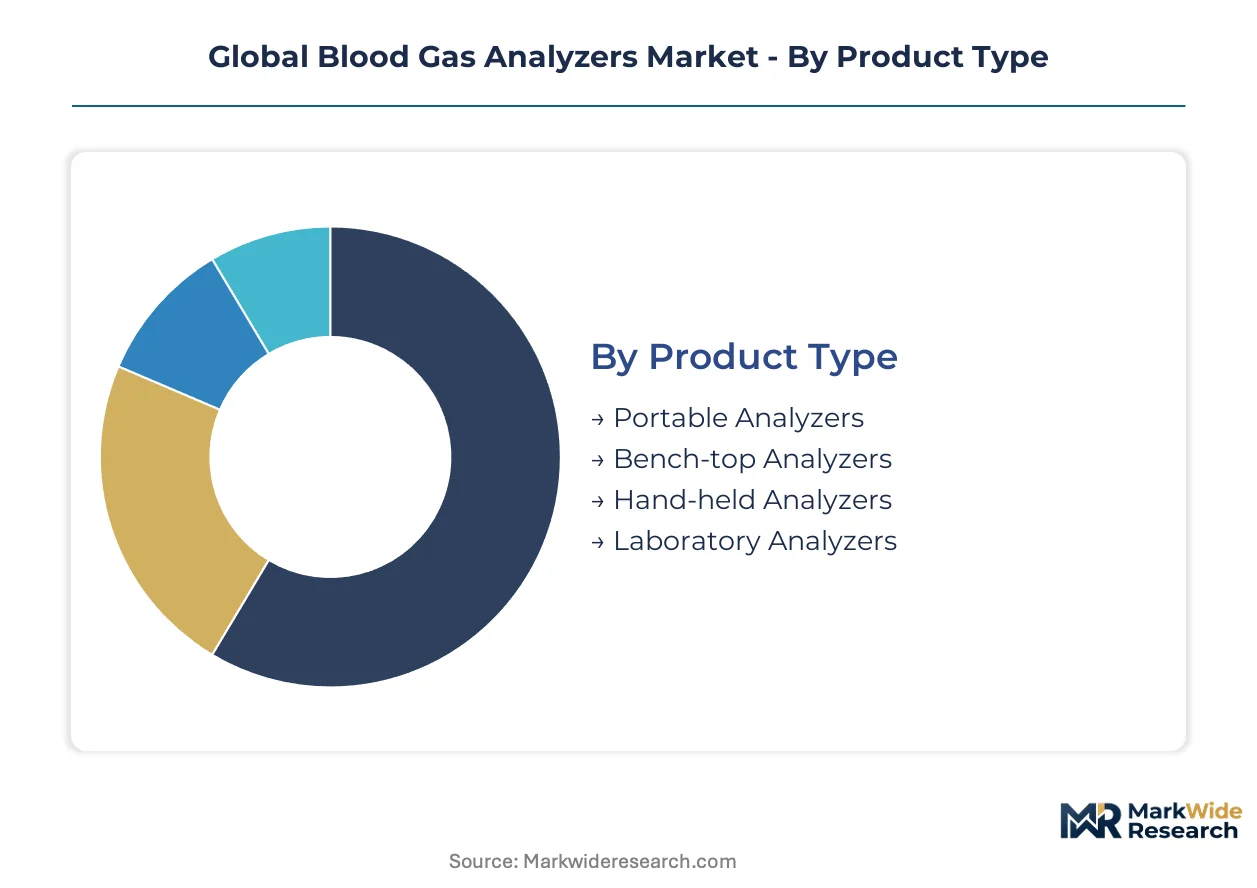
Blood gas analyzer segmentation reflects divergent regulatory pathways and deployment economics. Product form factors, sensor technologies, and care settings each carry distinct certification burdens and reimbursement profiles that reshape competitive strategy.
Product Type:
FDA CLIA complexity classifications and EU MDR clinical evidence requirements create divergent compliance economics across form factors.
- Portable Analyzers:Compact electrochemical or optical platforms designed for bedside deployment in emergency departments and surgical suites. Demand concentrates in United States trauma centers where CLIA-waived status accelerates procurement; optical miniaturization is compressing maintenance cycles and enabling ambulatory deployment.
- Bench-top Analyzers:High-throughput laboratory systems with multi-parameter menus spanning blood gas, electrolytes, and metabolites. German university hospitals anchor installed base volumes due to centralized laboratory infrastructure and bundled procurement contracts with integrated delivery networks.
- Hand-held Analyzers:Single-patient-use devices for point-of-care arterial sampling. China NMPA priority review pathway is redirecting R&D toward dual-registered handheld formats.
- Laboratory Analyzers:Reference-grade systems for clinical laboratories and blood gas quality control programs. United States reference laboratories sustain replacement demand through captive reagent contracts.
Bench-top systems handle the majority of throughput; portable analyzers are gaining share fastest as hospitals decentralize testing to emergency departments.
End User:
Procurement authority and reimbursement structure vary sharply across institutional settings, reshaping vendor sales motion and service contract design.
- Hospitals:Acute care facilities with centralized laboratories and distributed point-of-care networks. United States integrated delivery networks standardize across regional footprints, concentrating contract value.
- Clinics:Outpatient facilities and urgent care centers with limited laboratory infrastructure. Germany's ambulatory care sector adopts portable analyzers for same-day respiratory assessment.
- Diagnostic Laboratories:Independent and hospital-affiliated reference laboratories processing high specimen volumes. China clinical laboratory chains are expanding automated blood gas capacity under diagnostic service privatization.
- Research Facilities:Academic medical centers and pharmaceutical development sites requiring research-use-only configurations. United States NIH-funded institutions sustain specialized parameter menu demand.
Hospitals command the largest installed base; diagnostic laboratories are expanding most quickly as China's clinical laboratory sector consolidates.
Technology:
Sensor architecture selection determines calibration stability, maintenance burden, and regulatory submission complexity across jurisdictions.
- Optical Sensors:Solid-state microfabricated arrays measuring pH and gas partial pressures through fluorescence or absorbance. Handheld formats in United States emergency departments are displacing electrochemical methods where reduced drift enables extended deployment cycles.
- Electrochemical Sensors:Traditional electrode-based measurement using palladium and silver-silver chloride reference systems. Bench-top configurations in German critical care laboratories retain dominance due to established quality control protocols and lower per-test consumable costs.
- Mass Spectrometry:Research-grade systems for precise isotope and metabolite quantification. Academic medical centers in the United States deploy for specialized metabolic studies.
- Microfluidics:Lab-on-chip architectures integrating sample handling and detection in disposable cartridges. Development-stage platforms target China point-of-care markets under NMPA innovative device pathway.
Electrochemical sensors retain the majority of installed base; optical sensors are climbing the fastest as solid-state miniaturization reaches handheld formats.
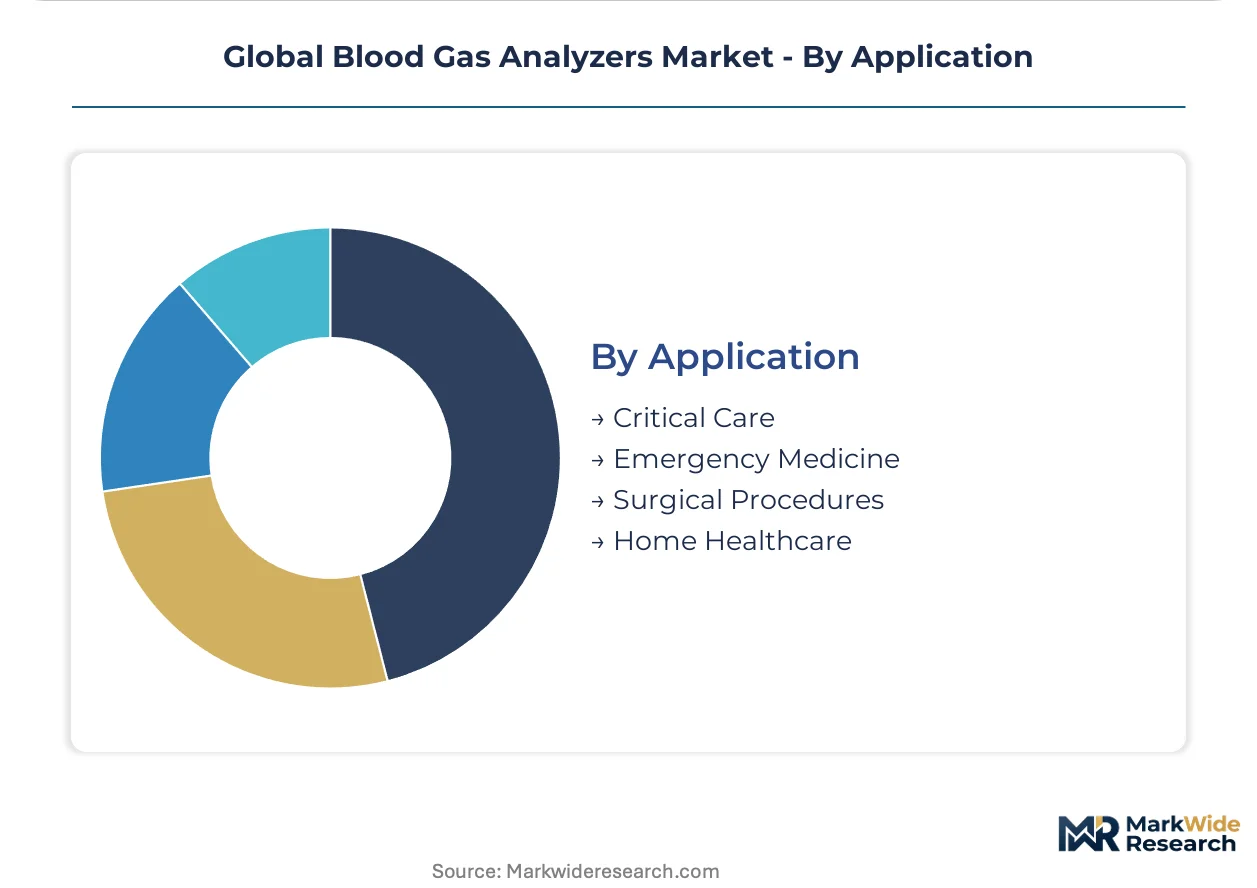
Application:
Clinical acuity and reimbursement intensity determine analyzer specification requirements and service contract pricing power.
- Critical Care:Intensive care unit ventilation management and acid-base disorder monitoring requiring arterial specimen accuracy. United States academic medical centers sustain demand for multi-parameter platforms with creatinine integration under value-based care contracts.
- Emergency Medicine:Rapid triage and trauma resuscitation protocols demanding sub-minute turnaround. German emergency departments are standardizing portable optical analyzers for capillary sampling in hypoperfusion assessment.
- Surgical Procedures:Intraoperative monitoring of perfusion and respiratory status during anesthesia. United States ambulatory surgical centers adopt handheld devices for orthopedic and cardiovascular cases.
- Home Healthcare:Remote respiratory monitoring for chronic obstructive pulmonary disease and sleep-disordered breathing. China home healthcare pilot programs are testing cloud-connected portable analyzers under digital health initiatives.
Critical care generates the majority of procedure-linked revenue; emergency medicine is expanding most quickly as point-of-care protocols displace central laboratory workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA CLIA waivers and EU MDR recertification deadlines are redirecting capital toward compliant manufacturing bases. Hospital modernization programs in critical care infrastructure anchor demand concentration across three continents.
United States
Integrated delivery networks in Texas and Florida are consolidating point-of-care contracts under multi-hospital agreements. FDA 510(k) pathways for moderate-complexity devices accelerate portable analyzer deployment in emergency departments. The Boston-Cambridge corridor sustains electrochemical sensor R&D through NIH-funded academic medical centers.
Germany
University hospital systems in Bavaria and North Rhine-Westphalia maintain centralized laboratory infrastructure for high-throughput bench-top systems. EU MDR recertification requirements filter smaller manufacturers from European market access. The Stuttgart medical technology cluster advances optical sensor miniaturization for handheld formats.
China
Clinical laboratory chains in Shanghai and Guangdong expand automated blood gas capacity under diagnostic service privatization. NMPA priority review pathways for innovative equipment redirect R&D investment toward dual-registered products. The Yangtze River Delta anchors manufacturing scale for export-oriented portable analyzer production.
Japan
Aging demographics and critical care bed expansion drive analyzer replacement cycles in Tokyo and Osaka metropolitan hospitals. PMDA streamlined review processes for priority medical devices accelerate product registration timelines. The Kansai region maintains precision electrochemical component supply chains for domestic manufacturers.
United Kingdom
NHS trust consolidation in London and the Midlands standardizes procurement around multi-parameter platform agreements. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UK-specific submissions. The Cambridge-Oxford-London golden triangle sustains research-use-only analyzer demand for pharmaceutical development.
Global Blood Gas Analyzers Market Vendor Landscape
Player mix skews toward diversified diagnostic conglomerates with captive sensor manufacturing and specialized critical care technology firms. Market structure concentrates volume among five to seven established manufacturers with clinical evidence reserves for EU MDR compliance. Strategic archetypes include vertically integrated platform providers, point-of-care specialists, and laboratory-focused high-throughput suppliers. Competitive moves center on optical sensor miniaturization R&D and multi-jurisdiction regulatory submission parallelism to capture CLIA-waived and NMPA-priority segments.
Among US-based diversified health technology conglomerates, Danaher Corporation and Abbott Laboratories occupy positions spanning bench-top and portable analyzer categories. Werfen S.A., a Spanish diagnostic specialist, exemplifies the critical care-focused archetype with concentrated European market presence. These three entities represent distinct strategic postures: conglomerate platform breadth, emergency medicine point-of-care deployment, and specialized intensive care application depth.
| Leading Market Players |
|---|
| Danaher Corporation |
| Werfen S.A. |
| F. Hoffmann-La Roche Ltd. |
| Abbott Laboratories |
| Siemens Healthineers AG |
| Radiometer Medical ApS |
| Medica Corporation |
| Nova Biomedical |
| Instrumentation Laboratory |
| Others |
Supply Flow & Price Mechanics
Long-term reagent supply contracts lock in both palladium electrode access and per-test pricing visibility for bench-top system manufacturers serving German university hospitals. These arrangements insulate holders from spot market volatility while compressing margins for competitors forced into short-term procurement.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels dominates: FDA-cleared CLIA-waived handheld devices command premium positioning, moderate-complexity bench-top systems anchor mid-market contracts, and refurbished laboratory analyzers serve price-sensitive diagnostic laboratories. Pricing pressure stems from integrated delivery network bundling in the United States, where multi-hospital procurement agreements force concessions on per-test reagent pricing. Diagnostic laboratories exhibit highest price sensitivity due to thin margins on high-volume processing, while academic medical centers prioritize parameter breadth over unit economics.
Supply Chain Analysis
Inventory buffers for palladium electrodes extend to six-month coverage as Russian and South African refining concentration creates lead-time vulnerability. Electrochemical sensor manufacturing draws from palladium, silver-silver chloride, and specialized glass membrane suppliers concentrated in Japan, Germany, and the United States. Single-source dependency on Russian palladium refining exposes production costs to geopolitical disruption. Distribution runs through captive reagent contracts directly from manufacturers to hospital integrated delivery networks, bypassing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where cartridge interoperability and cloud-connected analyzer fleets are redefining competitive moats around installed base lock-in rather than device hardware alone.
For Market Incumbents: Fortify CLIA-waived portfolio depth against optical sensor miniaturization threats from emerging point-of-care specialists. Deepen backward integration into solid-state optical array fabrication to capture calibration stability premiums in handheld formats. Prioritize EU MDR notified body relationship maintenance to absorb volume from recertification-excluded competitors. For New Entrants and Emerging Players: After-sales service fragmentation in China's clinical laboratory chains presents immediate white-space opportunity. Target NMPA priority review pathway for dual-registered handheld formats combining blood gas and creatinine parameters. Pursue veterinary critical care applications in Germany and the United States as regulatory-light entry channel with human-grade technology transfer potential. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with captive sensor manufacturing and established European notified body relationships. Long-term viability favors platforms with reagent annuity economics and multi-jurisdiction certification parallelism already operational. Watch FDA CLIA complexity reclassification announcements as inflection signal for point-of-care addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence reserves filter smaller competitors from European market access. |
| Hospital System Partnership | Integrated delivery network bundling in Texas and Florida concentrates contract value. |
| Software Companion Development | Cloud-connected analyzer fleets enable remote calibration monitoring in China home healthcare pilots. |
| Reimbursement Strategy | Value-based care contracts in United States academic medical centers reward creatinine-integrated parameter menus. |
| Backward Integration | In-house optical sensor production captures premium positioning in handheld emergency department deployment. |
Methodological Framework
Initial hypotheses were tested against primary input from biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at diagnostic manufacturers and refined through secondary validation. FDA 510(k) filings, EU MDR notified body documentation, NMPA priority review pathway records, and hospital procurement database extracts provided foundational data. Bottom-up installed base modeling and top-down revenue triangulation converged on segment-level estimates.
Variance decomposition across product type, sensor technology, end-user setting, care setting application, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate synthesis rather than single-point extrapolation. Modeled inputs included point-of-care protocol adoption curves in United States emergency departments, EU MDR recertification timeline compliance rates, and China clinical laboratory privatization expansion trajectories.
Underlying assumptions cover regulatory pathway stability, palladium supply continuity, and hospital capital expenditure commitment levels, with deviation risk concentrated in FDA CLIA reclassification timing and EU MDR notified body capacity constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Lab Accessories Market
Laboratory Equipment
Electrophoresis Equipment and Supplies Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Asia Pacific Cell Counting Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Blood Processing and Storage Equipment Market
Laboratory Equipment
Human Platelet Lysate Market
Laboratory Equipment
Multi Channel Hotplate Magnetic Stirrers Market
Laboratory Equipment
Middle East and Africa Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Pipette Tips Market
Laboratory Equipment
US Cath Labs Market