
 Molecular Diagnostics Market | 2026-2036
Molecular Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Diagnostics Market Analysis
Multi-sourced reagent procurement is expanding across the molecular diagnostics supply base as manufacturers reduce dependence on sole suppliers of critical enzymes and oligonucleotides. Abbott Laboratories leverages backward integration into nucleic acid extraction chemistry to secure raw material continuity. Thermo Fisher Scientific anchors global distribution through its captive channel network spanning reference laboratories and academic institutions. QIAGEN N.V. competes on modular automation platforms that integrate sample prep with real-time PCR detection.
Molecular diagnostics encompasses laboratory techniques that detect and quantify nucleic acid sequences—DNA or RNA—through amplification, hybridization, or sequencing-based methods, typically requiring thermal cyclers operating at 50–95°C with fluorescence detection thresholds of 1–10 copies per reaction. These technologies enable pathogen identification, oncogenic mutation profiling, and inherited disease screening with turnaround times ranging from 30 minutes to several days. Reagents and assays capture the dominant share of product-type revenue due to recurring consumable demand tied to installed instrument bases. PCR technology leads in infectious disease testing volume, while NGS applications in oncology represent the fastest-expanding margin pool as panel complexity rises. Reference laboratories constitute the most concentrated end-user channel, though hospital-based labs are building in-house NGS capacity to retain oncology specimen flow.
FDA oversight of companion diagnostics through the Center for Devices and Radiological Health shapes product development roadmaps, requiring co-approval with targeted therapeutics. CLIA laboratory certification standards govern test complexity classification and personnel qualifications, directly affecting market access for laboratory-developed tests. ISO 15189 accreditation requirements influence quality management system investments across European and Asian commercial laboratories. Stakeholders must monitor evolving payer coverage determinations for multi-gene panels versus single-analyte tests, as reimbursement policy will determine which technology platforms achieve scalable clinical adoption.
Market Dynamics
Companion diagnostic co-approval requirements under FDA Center for Devices and Radiological Health oversight are compressing development timelines while fragmenting addressable patient populations into biomarker-defined subsegments. This regulatory architecture forces assay developers to synchronize validation cycles with pharmaceutical pipeline milestones, creating interdependent commercialization pathways.
Growth Catalysts
- Medicare reimbursement expansion:Coverage determinations for next-generation sequencing-based cancer panels in the United States remove payment uncertainty for oncology testing, accelerating hospital laboratory adoption of complex molecular profiling.
- ISO 15189 accreditation mandates:European and Asian commercial laboratories face escalating quality management system investments, driving replacement demand for automated platforms that reduce manual handling errors and documentation burden.
- PCR platform installed base expansion:Thermal cycler placement in clinical laboratories generates recurring consumable demand for pathogen identification assays, particularly in infectious disease surveillance applications.
Market Restraints
- Enzyme supply concentration:Critical reagents including DNA polymerases and reverse transcriptases rely on limited qualified suppliers, creating vulnerability to batch variability or geographic disruption in raw material sourcing.
- CLIA complexity classification friction:Laboratory-developed tests face personnel qualification requirements and proficiency testing mandates that extend validation timelines and limit test menu flexibility for moderate-complexity facilities.
- Point-of-care molecular substitution pressure:Antigen-based rapid diagnostics compete for infectious disease testing volume where turnaround time prioritization outweighs analytical sensitivity requirements.
Strategic Opportunities
- Hospital in-house NGS capacity buildout:Health systems seek to retain oncology specimen flow and margin by installing sequencing infrastructure previously outsourced to reference laboratories.
- Modular automation convergence:Integration of nucleic acid extraction chemistry with real-time PCR detection on unified platforms reduces laboratory footprint and technician training requirements.
- Multi-sourced reagent procurement models:Manufacturers reduce sole-supplier dependence for oligonucleotides and critical enzymes, creating procurement advisory and qualification service opportunities.
Industry Challenges
- Bioinformatics pipeline validation:Next-generation sequencing assay deployment requires computational biology expertise scarce in clinical laboratory settings, forcing outsourcing or extended hiring cycles.
- Legacy LIS integration complexity:New molecular platforms must interface with established laboratory information systems through HL7 or proprietary protocols, extending implementation timelines and requiring vendor-specific customization.
- Reimbursement coding alignment:Multi-gene panel claims face audit scrutiny when billing codes do not map cleanly to reported biomarker results, creating revenue recognition risk for high-complexity testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Diagnostics Market |
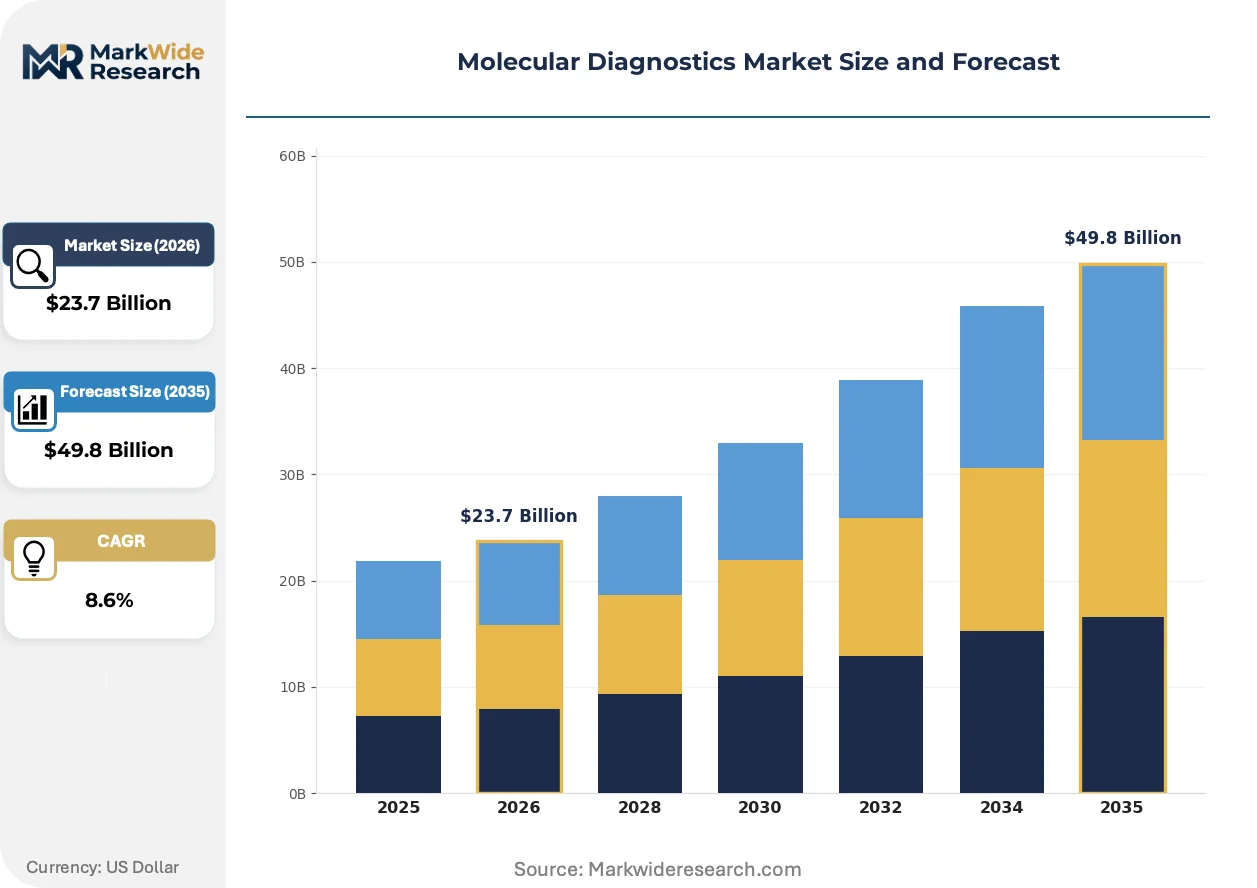
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Assays Technology: PCR, NGS, Microarray, Sanger Sequencing Application: Infectious Diseases, Oncology, Genetic Testing, Blood Screening End User: Hospitals, Clinics, Reference Laboratories, Academic Institutions |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Danaher Corporation, Thermo Fisher Scientific Inc., QIAGEN N.V., Illumina, Inc., bioMérieux SA, Hologic, Inc., Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Diagnostics Market Emerging Trajectories
Workflow unification is compressing the traditional separation between sample preparation and analytical detection, with platform architectures converging on pre-integrated consumable cartridges. This structural shift reduces hands-on time while constraining laboratory flexibility to mix reagent suppliers.
Sample-to-answer cartridge systems are modularizing molecular testing workflows by embedding nucleic acid extraction, amplification, and detection within single-use consumables. Hospital-based clinical laboratories adopt these platforms to reduce contamination risk and technician training burden. This architecture is modularizing competitive differentiation away from discrete instrument specifications toward integrated chemistry reliability and supply security.
FDA breakthrough device designation pathways for companion diagnostics are accelerating premarket review timelines for assays linked to targeted oncology therapeutics. Pharmaceutical sponsors now coordinate regulatory submissions across drug and diagnostic divisions, compressing launch synchronization. Oncology reference laboratories in the United States respond by building dedicated companion diagnostic service lines to capture co-development partnership opportunities.
Consolidated procurement contracts are reshaping reagent purchasing patterns as health system laboratories negotiate multi-year supply agreements covering instruments, consumables, and service. Group purchasing organizations aggregate demand across independent hospital networks, displacing spot purchasing from distributors. This concentration is most visible in United States integrated delivery networks seeking to standardize platforms across affiliated clinical sites.
Molecular Diagnostics Market Segmentation
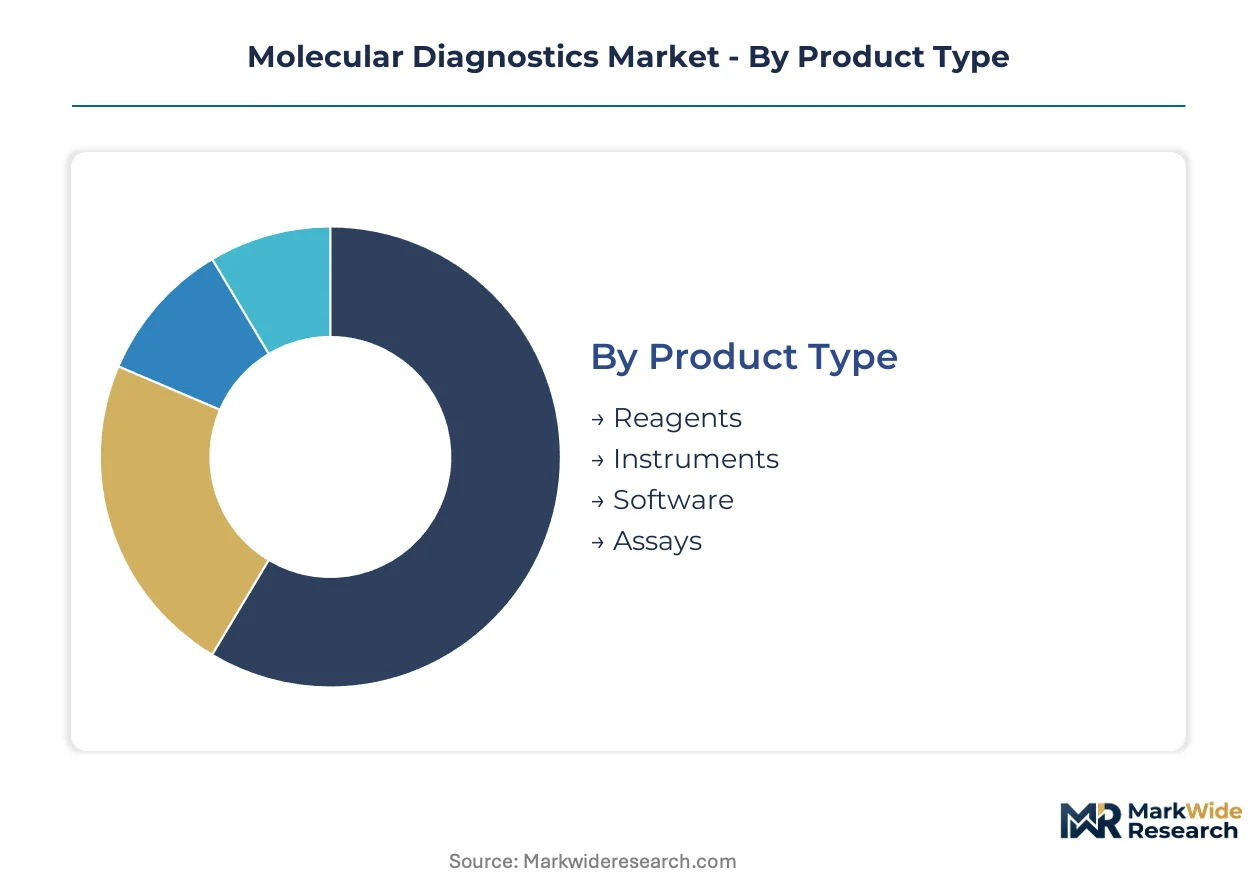
Molecular diagnostics segmentation reflects how laboratories balance analytical sophistication against operational constraints. Procurement patterns diverge sharply between high-throughput reference laboratories and point-of-care settings with limited technical infrastructure.
Product Type:
Reagents dominate procurement volumes through recurring consumable demand, while instruments anchor capital investment cycles and vendor lock-in.
- Reagents:Enzymes, primers, and master mixes constitute the highest-frequency purchase category. Hospital laboratories in the United States concentrate orders through multi-year supply agreements to secure polymerase continuity amid raw material volatility.
- Instruments:Thermal cyclers and sequencing platforms require substantial capital deployment and validation timelines. Academic institutions in Germany drive replacement demand as ISO 15189 accreditation mandates escalate quality management investments.
- Software:Bioinformatics pipelines for variant calling and clinical interpretation.
- Assays:FDA-cleared test kits for specific pathogen or biomarker detection.
Reagents lead volumes today; assays are gaining share fastest through companion diagnostic co-development partnerships.
Technology:
Platform selection hinges on sensitivity requirements, turnaround time, and laboratory technical capacity across different testing environments.
- PCR:Real-time amplification systems operate at thermal cycling thresholds of 50–95°C with fluorescence detection down to 1–10 copies per reaction. Infectious disease surveillance programs in Japan rely on PCR for pathogen identification where analytical sensitivity outweighs multiplexing needs.
- NGS:Next-generation sequencing enables parallel analysis of thousands of loci with panel complexity expanding rapidly. Oncology reference laboratories in the United States build dedicated service lines to capture Medicare reimbursement for cancer profiling.
- Microarray:Hybridization-based detection for copy number variation and SNP genotyping.
- Sanger Sequencing:Gold-standard confirmation method for variant validation in inherited disease screening.
PCR leads volumes today; NGS is expanding most quickly as panel complexity rises in oncology applications.
Application:
Clinical utility and reimbursement coverage determine which disease areas absorb molecular testing investment.
- Infectious Diseases:Respiratory pathogen panels and sexually transmitted infection assays generate highest test frequency. Hospital laboratories prioritize PCR-based respiratory testing during seasonal surveillance periods.
- Oncology:Solid tumor and liquid biopsy profiling command premium pricing through companion diagnostic linkages. The FDA's breakthrough device designation pathway accelerates commercial timelines for assay developers in this segment.
- Genetic Testing:Carrier screening and hereditary cancer panels for reproductive and preventive medicine.
- Blood Screening:Nucleic acid testing for transfusion-transmitted pathogens in donor populations.
Infectious diseases lead volumes today; oncology is climbing the fastest through Medicare coverage expansion for sequencing-based panels.
End User:
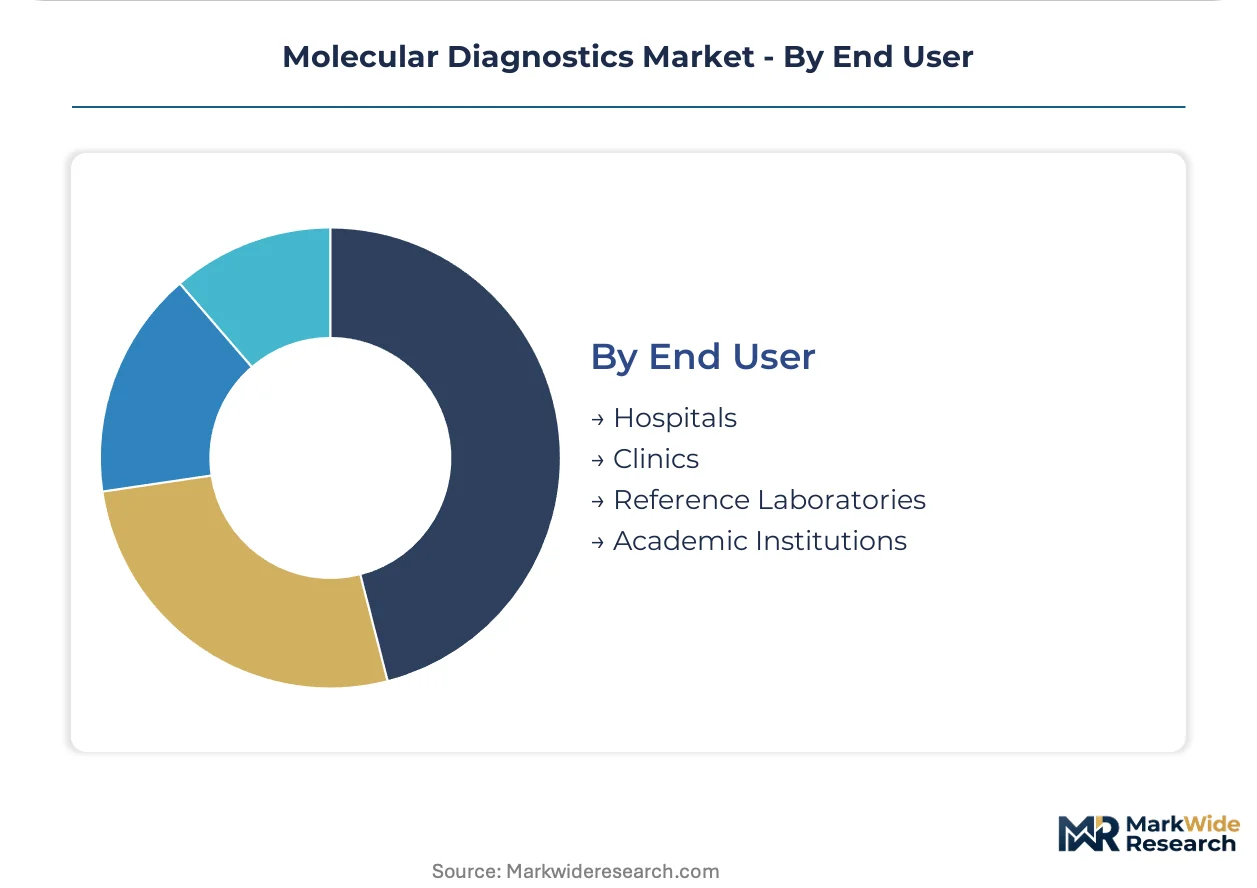
Site-of-care location shapes platform architecture preferences between centralized high-complexity laboratories and distributed testing nodes.
- Hospitals:Clinical laboratories within integrated delivery networks seek to retain oncology specimen flow previously outsourced to reference laboratories. Health systems in the United States negotiate consolidated procurement contracts standardizing platforms across affiliated sites.
- Reference Laboratories:Centralized high-throughput facilities process specimens from multiple collection points. Academic medical centers in Switzerland anchor specialized companion diagnostic service lines for pharmaceutical co-development.
- Clinics:Point-of-care settings with limited technical infrastructure and rapid turnaround requirements.
- Academic Institutions:Research-focused laboratories driving early technology adoption and assay development.
Reference laboratories lead volumes today; hospitals are gaining share fastest through in-house NGS capacity buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors molecular diagnostics development through concentrated pharmaceutical and academic research institutions. The United States, Germany, Japan, China, and Switzerland concentrate platform manufacturing and clinical adoption. Each market shapes demand through distinct regulatory architectures and reimbursement policies.
United States
Medicare coverage determinations for next-generation sequencing cancer panels drive hospital laboratory investment in complex molecular profiling. FDA breakthrough device designations for companion diagnostics compress commercial timelines for assay developers. The Boston-Cambridge biotechnology corridor concentrates pharmaceutical co-development partnerships with diagnostic manufacturers.
Germany
ISO 15189 accreditation mandates escalate quality management investments across commercial laboratories, accelerating automated platform replacement cycles. The national medical device regulator enforces stringent clinical evidence requirements for companion diagnostic approvals. The Rhine-Ruhr industrial region anchors nucleic acid extraction chemistry manufacturing for European distribution networks.
Japan
Infectious disease surveillance programs rely on PCR-based pathogen identification where analytical sensitivity outweighs rapid turnaround requirements. PMDA oversight of companion diagnostics requires synchronized validation with pharmaceutical pipeline milestones. The Kanto region surrounding Tokyo concentrates reference laboratory capacity and academic medical center adoption of sequencing platforms.
China
Domestic manufacturers expand thermal cycler placement in provincial hospital systems to reduce import dependence for infectious disease testing. NMPA regulatory reforms streamline innovation pathway approvals for molecular diagnostic instruments. The Yangtze River Delta clusters nucleic acid reagent production facilities serving Asia-Pacific distribution channels.
Switzerland
Academic medical centers in Basel and Zurich anchor specialized companion diagnostic service lines for pharmaceutical co-development partnerships. Swissmedic maintains alignment with EMA regulatory standards while offering accelerated review pathways for breakthrough technologies. The Basel pharmaceutical corridor concentrates assay validation infrastructure for European market access.
Molecular Diagnostics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue modular automation and point-of-care miniaturization. The vendor base concentrates around three strategic archetypes: diversified life science conglomerates with captive distribution networks, specialized molecular biology platform developers, and clinical diagnostics incumbents with installed instrument bases. Competitive positioning depends on backward integration into nucleic acid chemistry and multi-year supply contract penetration within integrated delivery networks.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc., Danaher Corporation, and Abbott Laboratories exemplify scale-driven archetypes that anchor global reagent supply security through in-house manufacturing of critical enzymes and oligonucleotides. These entities represent the consolidation endpoint where instrument placement, consumable recurrence, and service contracts converge into unified procurement relationships with hospital systems and reference laboratories.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| Thermo Fisher Scientific Inc. |
| QIAGEN N.V. |
| Illumina, Inc. |
| bioMérieux SA |
| Hologic, Inc. |
| Siemens Healthineers AG |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up reference laboratory networks concentrate procurement leverage across United States integrated delivery networks, compressing reagent pricing through multi-year consolidated supply agreements while simultaneously demanding supply security commitments from enzyme manufacturers.
Pricing Analysis
Input-cost pass-through from polymerase and oligonucleotide suppliers operates on quarterly adjustment clauses tied to fermentation substrate indices. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared companion diagnostic assays from laboratory-developed tests and research-use-only reagents. Pricing pressure stems from group purchasing organization aggregation of hospital laboratory demand. Moderate-complexity facilities exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize supply continuity over unit cost.
Supply Chain Analysis
Workforce availability constraints in nucleic acid chemistry manufacturing concentrate production in the Yangtze River Delta, Rhine-Ruhr industrial region, and Boston-Cambridge biotechnology corridor. Critical inputs draw from qualified suppliers of DNA polymerases, reverse transcriptases, and synthetic oligonucleotides. Single-source vulnerability persists for thermostable enzyme variants protected by process trade secrets. Distribution runs through captive channel networks anchored by diversified life science conglomerates serving reference laboratories and hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory co-approval requirements, with FDA breakthrough device designations for companion diagnostics creating synchronized revenue cycles between assay developers and pharmaceutical sponsors.
For Market Incumbents: Hedge against point-of-care molecular substitution by embedding nucleic acid extraction chemistry into unified automation platforms that reduce laboratory footprint. Consolidate multi-year supply contracts with integrated delivery networks before hospital in-house NGS capacity buildout accelerates. Prioritize backward integration into critical enzyme manufacturing to secure raw material continuity amid supplier concentration risks.
For New Entrants and Emerging Players: Launch via modular sample-to-answer cartridge systems targeting moderate-complexity hospital laboratories seeking to reduce technician training burden. White-space opportunities concentrate in infectious disease surveillance applications where analytical sensitivity requirements exceed point-of-care antigen test capabilities. Pursue ISO 15189 accreditation advisory services as entry wedge into European commercial laboratory replacement cycles.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized molecular biology platform developers lacking captive distribution networks but holding companion diagnostic co-development partnerships. Long-term viability over the next decade hinges on reimbursement coding alignment capabilities for multi-gene panel claims. Monitor Medicare coverage determination timelines for next-generation sequencing-based cancer panels as inflection signal for hospital laboratory capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | FDA breakthrough device designation compresses commercial timelines for oncology assay developers. |
| Modular Automation Platform Launch | QIAGEN N.V. competes on unified sample prep and real-time PCR detection integration. |
| Multi-Sourced Reagent Procurement Program | Abbott Laboratories reduces sole-supplier dependence for critical enzymes and oligonucleotides. |
| Hospital In-House NGS Capacity Buildout | Health systems retain oncology specimen flow previously outsourced to reference laboratories. |
| ISO 15189 Accreditation Investment | European commercial laboratories face escalating quality management system mandates. |
Methodological Framework
Direct dialogue with assay development directors, hospital laboratory managers, regulatory affairs specialists at FDA, and GPO contracts managers grounds qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS Medicare coverage determinations, ClinicalTrials.gov companion diagnostic listings, and hospital procurement database extracts. Bottom-up instrument placement and consumable recurrence models triangulate against top-down addressable patient population estimates.
Bottom-up modeling of thermal cycler installed bases and reagent consumption rates across reference laboratories, hospital systems, and academic institutions generates volume projections. Segmentation dimensions include product type, technology platform, application area, and end-user site-of-care. CAGRs derive from instrument replacement cycles, panel complexity expansion in oncology, and reimbursement policy trajectory across the analysis window. Forecast inputs incorporate CLIA complexity classification trends and pharmaceutical pipeline biomarker stratification.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden Medicare coverage reversals for multi-gene panels or prolonged enzyme supply disruptions. Forecasts reflect assumptions regarding FDA breakthrough device designation throughput and ISO 15189 accreditation adoption curves. Material deviation in companion diagnostic co-approval timelines or group purchasing organization contract concentration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
LDL Test Market
Diagnostics
Glaucoma Diagnostics Market
Diagnostics
BRIC in-Vitro Diagnostics (IVD) Market
Diagnostics
Latex Agglutination Test Market
Diagnostics
Global Neurodiagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Extraction Kits Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
US in Vitro Diagnostics Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Malaria Diagnostics Market
Diagnostics
Global RSV Diagnostics Market
Diagnostics
Global HIV Diagnosis Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Vibrio Diagnostics Market