
 Cardiolipin Antibodies Test Market | 2026-2036
Cardiolipin Antibodies Test Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiolipin Antibodies Test Market Outlook
The pricing and performance gap between premium chemiluminescence platforms and commodity ELISA kits is hardening across autoimmune diagnostics. EUROIMMUN AG leverages its Heidelberg-based manufacturing footprint to dominate specialized antiphospholipid assay supply in Europe. Bio-Rad Laboratories sustains R&D intensity across multiplexed immunoassay architectures for research-grade cardiolipin antibody detection. Trinity Biotech anchors its position through vertically controlled reagent production and reference laboratory partnerships in North America.
Cardiolipin antibodies are immunoglobulins directed against phospholipid-binding proteins, detected via solid-phase immunoassay using purified cardiolipin antigen coated on polystyrene microwells or magnetic particles, with primary clinical utility in diagnosing antiphospholipid syndrome and thrombotic risk stratification. IgG test type occupies the largest share of routine clinical demand due to established correlation with thrombotic events, while total antibodies panels are gaining fastest in comprehensive autoimmune screening protocols. Diagnostic laboratories channel generates the highest volume throughput, though specialty clinics command superior per-test margins through bundled prenatal and rheumatology service lines.
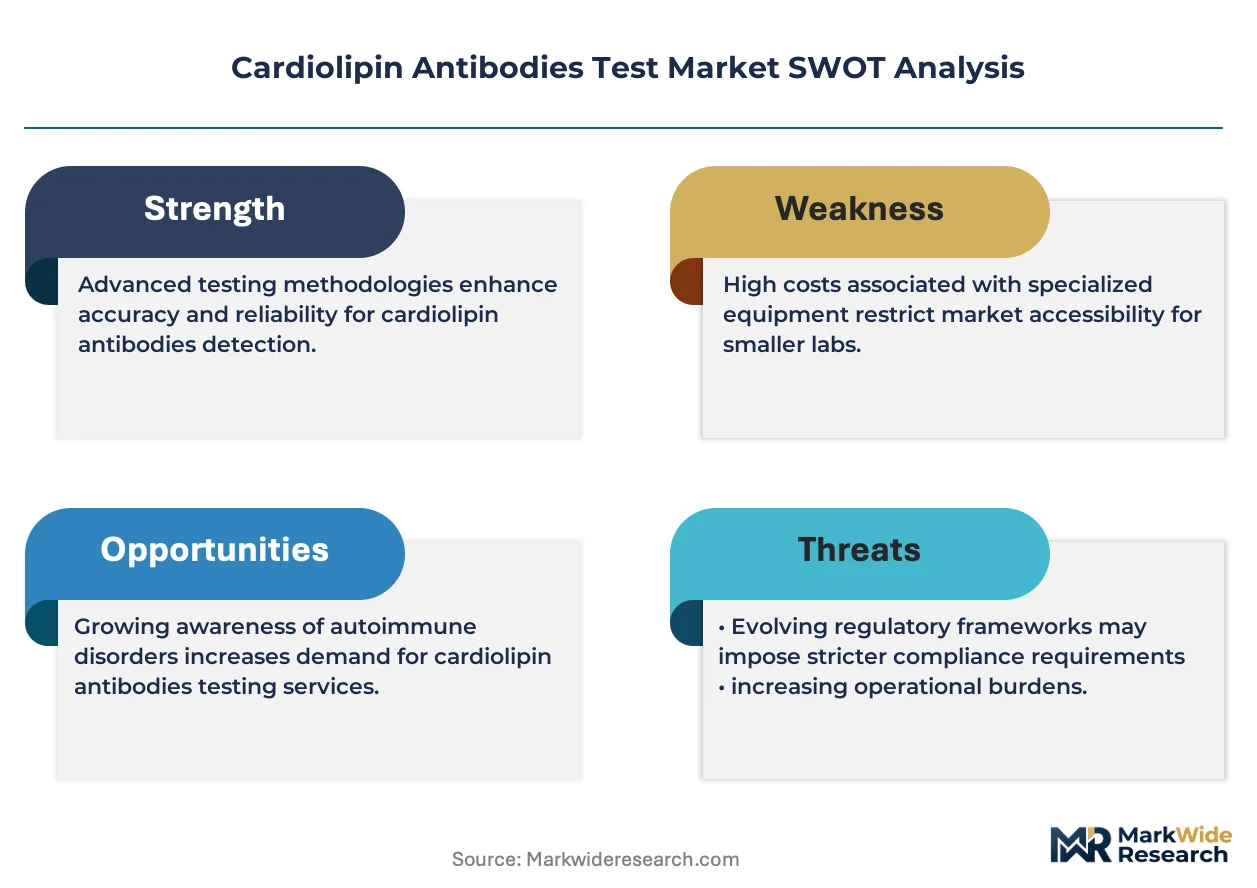
FDA 510(k) pathways and CLIA laboratory certification govern commercial assay deployment in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence requirements for cardiolipin antibody kits entering European markets. Japan's PMDA maintains distinct analytical sensitivity thresholds that shape product configuration for Asia-Pacific submissions. Stakeholders must monitor evolving regulatory divergence between FDA's streamlined predicate device routes and EMA's escalating post-market surveillance obligations.
Market Dynamics
Automated chemiluminescence platforms are compressing turnaround times in antiphospholipid syndrome screening, forcing diagnostic laboratories to retire legacy ELISA workflows or absorb margin erosion from manual processing overhead.
Growth Catalysts
- EU MDR Implementation:Stricter clinical evidence requirements for cardiolipin antibody kits are consolidating certified suppliers, concentrating procurement toward validated manufacturers in Germany and accelerating replacement of unregistered legacy assays.
- Rheumatology Service Bundling:Specialty clinics are integrating prenatal thrombotic risk panels with routine antiphospholipid screening, expanding test volume through bundled reimbursement pathways in tertiary care networks.
- Magnetic Particle Separation:Enhanced solid-phase immunoassay architectures using paramagnetic bead coatings are reducing inter-batch variability, improving analytical precision for IgG isotype quantification in high-throughput laboratory settings.
Market Restraints
- Purified Antigen Input Volatility:Bovine heart-derived cardiolipin extraction faces supply instability from slaughterhouse sourcing concentration in Argentina and Brazil, creating lot-to-lot consistency risks for assay manufacturers.
- Predicate Device Pathway Saturation:FDA 510(k) clearance routes for cardiolipin antibody assays are encountering predicate exhaustion, extending regulatory timelines for novel isotype-specific kits seeking commercial entry.
- Point-of-Care Lateral Flow Substitution:Rapid qualitative screening devices for antiphospholipid antibodies are capturing preliminary diagnostic demand in resource-limited settings, threatening reference laboratory volume for routine screening.
Strategic Opportunities
- India Diagnostic Expansion:CDSCO streamlined medical device registration pathways and rising autoimmune disease awareness in Mumbai and Delhi hospital networks create underpenetrated demand for automated cardiolipin antibody testing infrastructure.
- Multiplexed Autoimmune Panels:Convergence of chemiluminescence instrumentation with bead-based multiplexing enables simultaneous cardiolipin, beta-2 glycoprotein I, and lupus anticoagulant detection, reducing per-patient diagnostic cost and serum volume requirements.
- Direct-to-Consumer Channel:Telemedicine-integrated laboratory networks are offering cardiolipin antibody screening through at-home phlebotomy collection, bypassing traditional hospital-based rheumatology referrals for preconception counseling segments.
Industry Challenges
- Immunoassay Specialist Talent Scarcity:Diagnostic manufacturers face recruitment friction for analytical biochemists experienced in phospholipid antigen stabilization and heterophile antibody interference mitigation.
- CLIA Laboratory Certification Timelines:High-complexity testing designation requirements for cardiolipin antibody assays impose 12-18 month facility qualification periods, constraining rapid geographic expansion for reference laboratory operators.
- Legacy LIS Integration Complexity:Automated immunoassay platforms require middleware customization for bidirectional interfacing with entrenched laboratory information systems in established hospital networks, delaying instrument placement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiolipin Antibodies Test Market |
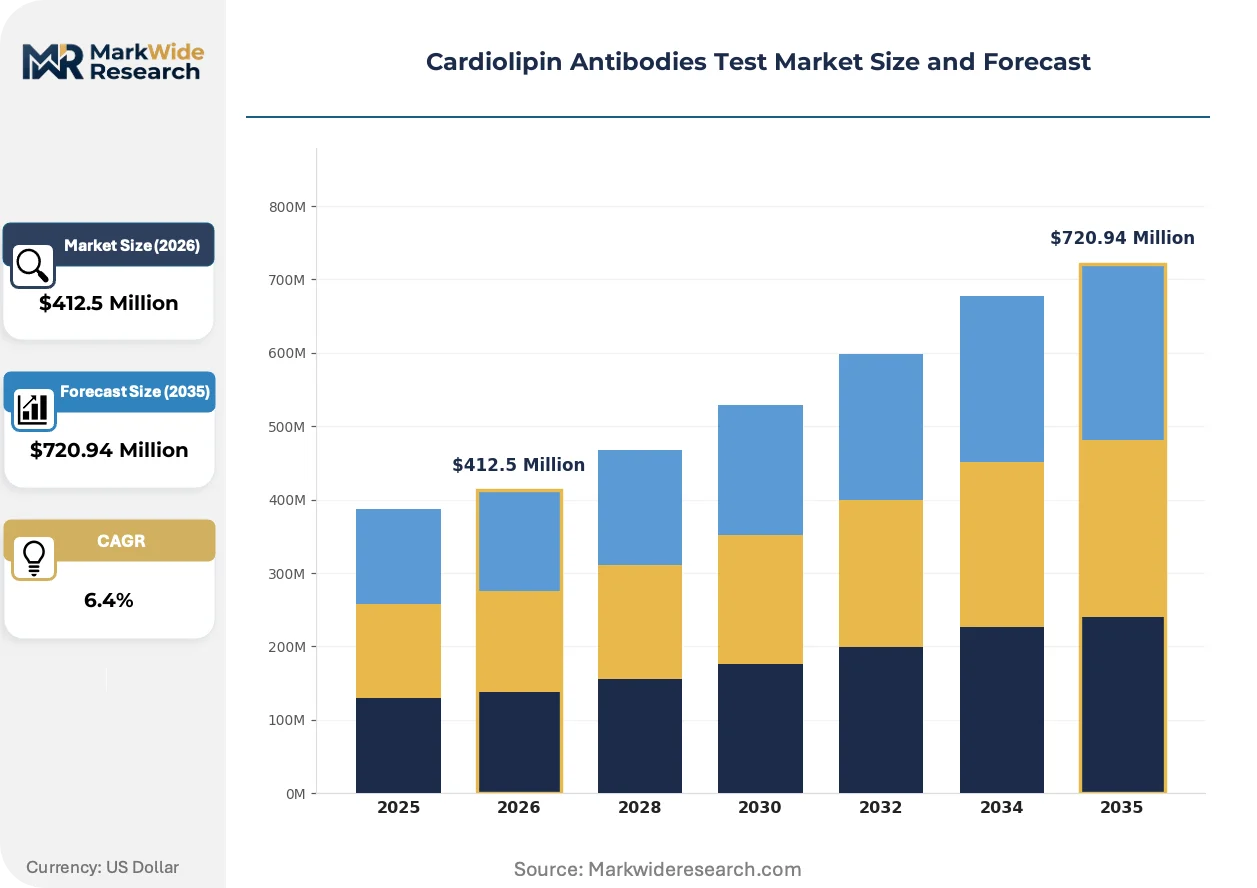
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: IgM, IgG, Total Antibodies, Anticardiolipin End User: Hospitals, Diagnostic Laboratories, Research Institutes, Specialty Clinics Distribution Channel: Direct Sales, Online Sales, Medical Distributors, Retail Pharmacies Application: Autoimmune Disorders, Thrombosis, Cardiovascular Diseases, Fertility Issues |
| Companies Covered | Trinity Biotech, Bio-Rad Laboratories, ARUP Laboratories, Diagnostic Automation, Portea Medical, Abnova, Eagle Biosciences, EUROIMMUN AG, AESKU.Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiolipin Antibodies Test Market Strategic Shifts
Chemiluminescence detection architectures are displacing colorimetric endpoints across autoimmune serology, compressing analytical sensitivity thresholds while restructuring competitive positioning between platform manufacturers and reagent suppliers.
Magnetic microparticle chemiluminescence immunoassay technology captures cardiolipin antibodies through antigen-coated paramagnetic beads, enabling automated washing and signal amplification. Large hospital laboratories in the United States and Germany are adopting these platforms at replacement cycle pace of 4-5 years. This transition is overtaking open-system ELISA reagent suppliers, forcing them toward OEM partnerships or niche research-grade positioning.
EU In Vitro Diagnostic Regulation post-market surveillance obligations now mandate annual safety reporting and performance trend analysis for cardiolipin antibody kits, elevating quality management system costs. Manufacturers serving European diagnostic laboratories must maintain vigilance databases tracking false-positive rates across clinical sites. IgG isotype-specific assays face heightened scrutiny in France and Germany, where notified bodies demand extended clinical evidence packages for initial conformity assessments.
Hospital procurement departments are consolidating autoimmune serology contracts under single-source instrument-reagent agreements, displacing best-of-breed reagent sourcing. Integrated delivery networks in Texas and California are negotiating exclusive multi-year supply arrangements with platform manufacturers. This concentration is most visible in academic medical centers, where capital equipment leasing bundles now include per-test reagent minimums and remote technical support subscriptions.
Cardiolipin Antibodies Test Market Segmentation
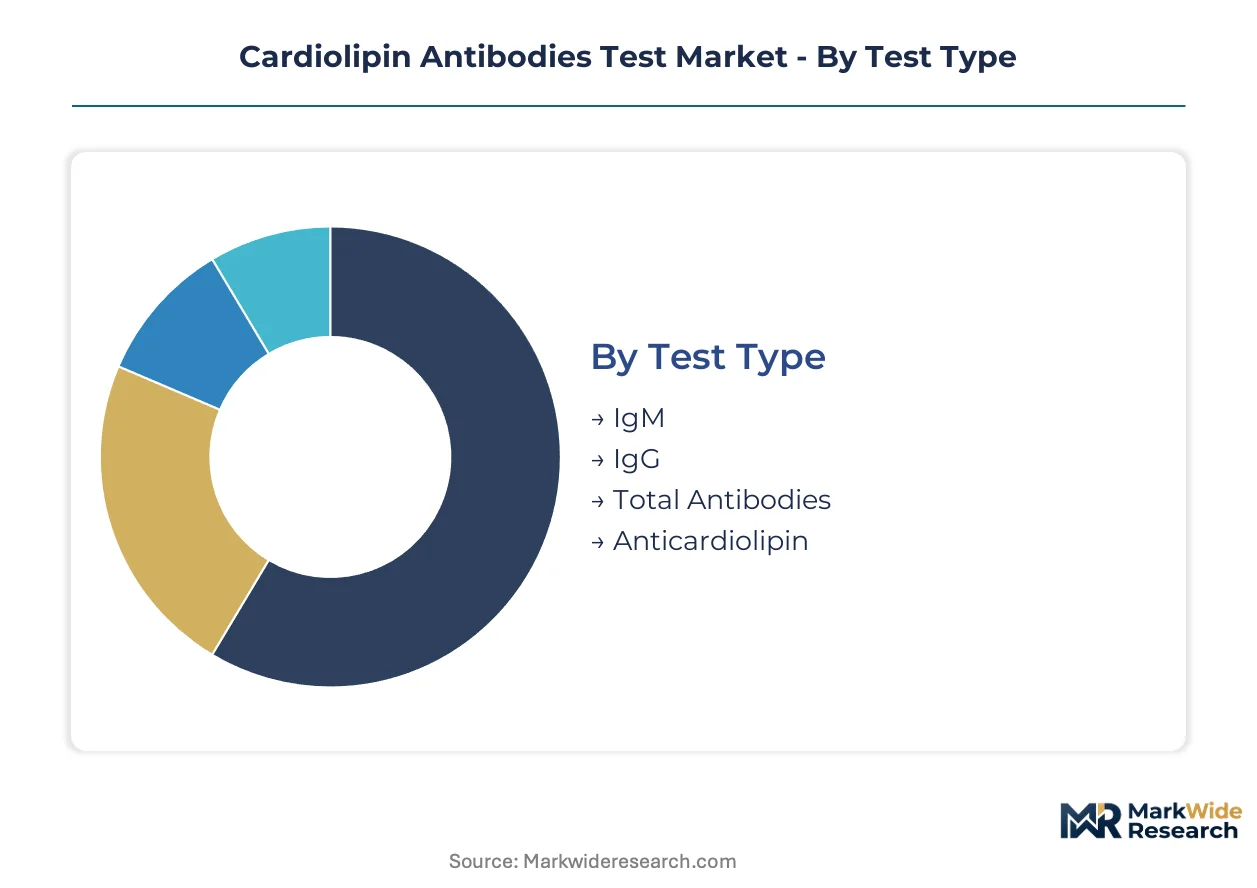
Test selection in cardiolipin antibody diagnostics hinges on clinical indication specificity and laboratory workflow integration. Segmentation reveals how IgG dominance in thrombotic risk stratification contrasts with emerging demand for comprehensive antibody profiling in fertility clinics.
Test Type:
Laboratory procurement decisions prioritize analytical correlation strength with clinical endpoints over panel breadth.
- IgG:Immunoglobulin G isotype detection demonstrates the strongest established correlation with arterial and venous thrombotic events in antiphospholipid syndrome. Hospital laboratories in Germany and the United States concentrate routine screening volume here, driven by rheumatology guideline adherence and established reimbursement codes.
- Total Antibodies:Combined IgG/IgM/IgA detection panels reduce serum volume requirements and streamline comprehensive autoimmune screening protocols. Specialty clinics in prenatal and fertility service lines are expanding fastest here, capturing bundled diagnostic revenue through single-draw efficiency.
- IgM:Acute-phase isotype marker with transient elevation patterns requires careful temporal interpretation in clinical context.
- Anticardiolipin:Traditional assay nomenclature persists in legacy laboratory information system configurations and historical literature references.
Volume sits with IgG; growth tilts toward Total Antibodies.
End User:
Capital equipment intensity and reimbursement structure create divergent margin profiles across care settings.
- Diagnostic Laboratories:High-throughput automated chemiluminescence platforms generate maximum test volume through centralized processing economies. Large independent laboratory networks in Texas and California anchor North American capacity, constrained by CLIA high-complexity certification timelines that extend facility qualification periods.
- Specialty Clinics:Rheumatology and reproductive endocrinology practices command superior per-test margins through bundled prenatal thrombotic risk panels and direct patient relationships. EUROIMMUN AG and AESKU.Diagnostics supply specialized assay formats tailored to these settings in European markets.
- Hospitals:Academic medical centers integrate testing within broader autoimmune serology menus under instrument-reagent bundled agreements.
- Research Institutes:Multiplexed immunoassay architectures and novel isotype-specific kits drive demand in translational immunology applications.
Throughput concentrates in Diagnostic Laboratories; margin expansion favors Specialty Clinics.
Distribution Channel:
Procurement consolidation and regulatory compliance requirements reshape route-to-market economics.
- Direct Sales:Platform manufacturers negotiate exclusive multi-year instrument-reagent agreements with integrated delivery networks, displacing open-system reagent sourcing. Hospital procurement departments in academic medical centers favor capital equipment leasing bundles with per-test minimums and remote technical support subscriptions.
- Medical Distributors:Specialized diagnostic distributors maintain inventory depth for ELISA kit formats and legacy assay configurations serving smaller laboratory segments.
- Online Sales:E-procurement portals streamline reordering for standardized reagent consumables in high-volume reference laboratories.
- Retail Pharmacies:Minimal penetration due to prescription and processing complexity requirements for autoimmune serology.
Contract value concentrates in Direct Sales; flexibility resides with Medical Distributors.
Application:
Clinical utility expansion beyond thrombosis screening is reshaping test menu design and marketing positioning.
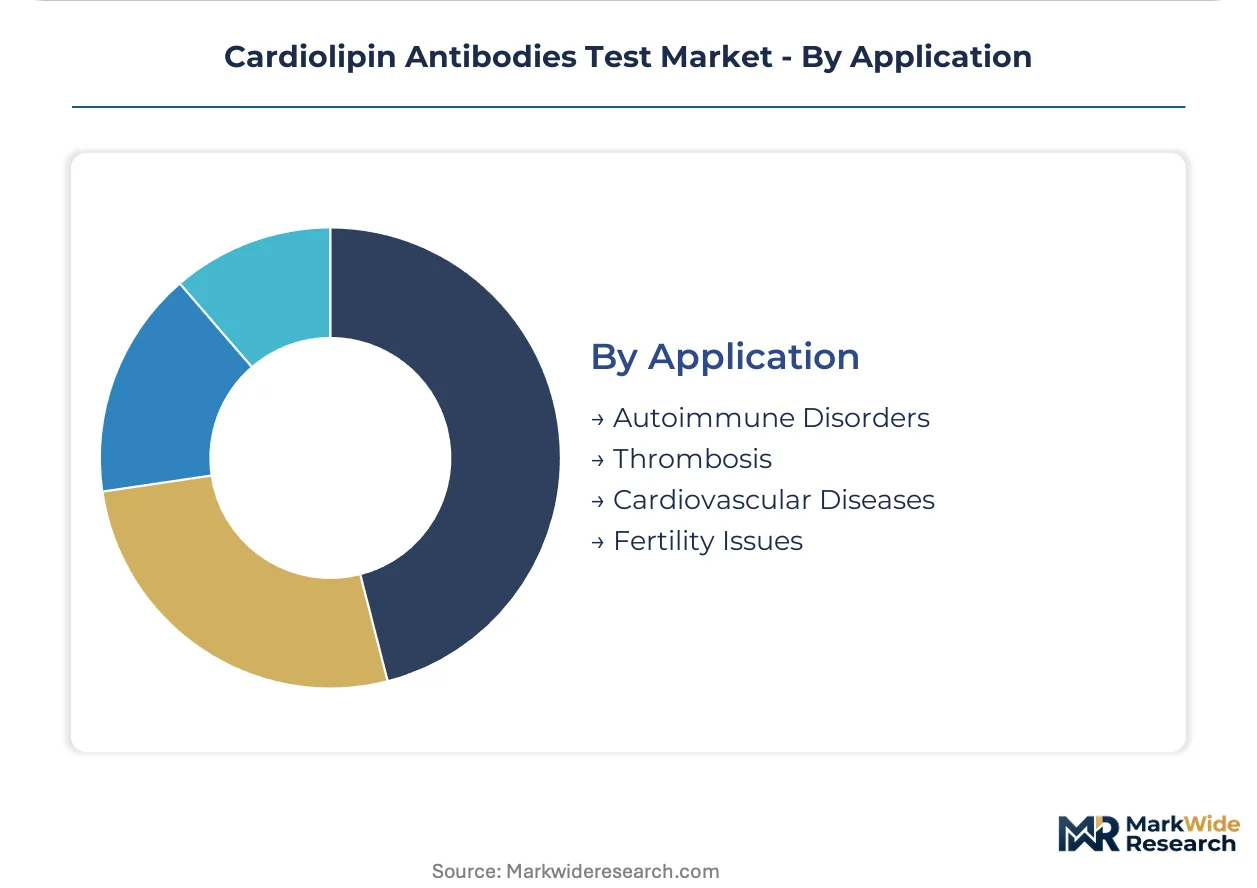
- Autoimmune Disorders:Antiphospholipid syndrome diagnosis remains the primary clinical indication, with IgG quantification supporting thrombotic risk stratification in systemic lupus erythematosus overlap populations. Rheumatology service bundling in tertiary care networks sustains core demand volume.
- Fertility Issues:Recurrent pregnancy loss evaluation and preconception counseling are expanding fastest, driven by reproductive endocrinology practice growth and telemedicine-integrated laboratory network development for at-home phlebotomy collection.
- Thrombosis:Cerebrovascular and deep venous thrombosis workup maintains steady utilization in cardiovascular service lines.
- Cardiovascular Diseases:Myocardial infarction risk assessment applications remain investigational in mainstream clinical practice.
Established utilization centers on Autoimmune Disorders; application expansion is steepest in Fertility Issues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg anchors European autoimmune diagnostics manufacturing, with EUROIMMUN AG and AESKU.Diagnostics operating specialized assay production facilities serving clinical laboratories across Germany and export markets.
United States
Texas and California hospital networks drive automated chemiluminescence platform adoption for antiphospholipid syndrome screening. FDA 510(k) pathways and CLIA high-complexity certification requirements shape commercial entry timelines for assay manufacturers. Academic medical centers in the Northeast Corridor negotiate bundled instrument-reagent agreements consolidating procurement under single-source contracts.
Germany
Rheumatology service bundling in tertiary care networks expands prenatal thrombotic risk panel utilization. EU In Vitro Diagnostic Regulation post-market surveillance obligations mandate annual safety reporting for cardiolipin antibody kits, elevating quality management costs for manufacturers. The Heidelberg-Mannheim corridor concentrates specialized autoimmune diagnostics production serving European diagnostic laboratories.
India
Mumbai and Delhi hospital networks generate underpenetrated demand for automated cardiolipin antibody testing infrastructure as autoimmune disease awareness rises. CDSCO streamlined medical device registration pathways accelerate commercial entry for international assay manufacturers. Diagnostic laboratory chains in Maharashtra and Karnataka expand centralized processing capacity for autoimmune serology menus.
Japan
PMDA analytical sensitivity thresholds shape product configuration requirements for cardiolipin antibody assay submissions in Asia-Pacific markets. Tokyo and Osaka metropolitan hospital networks maintain distinct performance benchmarks for phospholipid antigen detection. The Kanto region concentrates regulatory consulting expertise guiding manufacturers through national pharmaceutical regulator approval processes.
United Kingdom
London and Southeast England rheumatology practices integrate comprehensive antibody profiling into preconception counseling service lines. MHRA conformity assessment procedures align with EU MDR evidence requirements for IVD kit registration. The Oxford-Cambridge corridor hosts research institutes driving demand for multiplexed immunoassay architectures in translational immunology applications.
Cardiolipin Antibodies Test Market Competitive Environment
Premium-margin players sit above commodity-margin players across platform-reagent bundling intensity, with integrated instrument manufacturers capturing hospital procurement contracts while open-system reagent suppliers defend position in reference laboratory segments. The vendor base organizes into three strategic archetypes: vertically controlled manufacturers with captive reagent production, platform-agnostic reagent specialists, and research-grade multiplex assay developers. Dominant competitive moves include exclusive multi-year supply agreements with integrated delivery networks and OEM partnerships bridging chemiluminescence platform gaps.
Among European-based autoimmune diagnostics manufacturers, EUROIMMUN AG and AESKU.Diagnostics occupy positions within the specialized assay tier, anchoring regional supply for antiphospholipid syndrome screening. Trinity Biotech represents North American vertically controlled production archetypes, while Bio-Rad Laboratories exemplifies research-grade multiplexing capability in translational applications. These named entities illustrate how geographic clustering and business model differentiation segment competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Trinity Biotech |
| Bio-Rad Laboratories |
| ARUP Laboratories |
| Diagnostic Automation |
| Portea Medical |
| Abnova |
| Eagle Biosciences |
| EUROIMMUN AG |
| AESKU.Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Bovine heart-derived cardiolipin antigen extraction costs flow from Argentine and Brazilian slaughterhouse sourcing through assay manufacturing tiers, with purified phospholipid input volatility compressing margins for ELISA kit suppliers while automated chemiluminescence platform manufacturers capture value through bundled instrument-reagent contracts.
Pricing Analysis
Throughput-based pricing anchors hospital laboratory procurement decisions, with per-test reagent minimums and remote technical support subscriptions bundled under multi-year capital equipment leasing arrangements. Price differentiation separates FDA-cleared chemiluminescence platforms from research-grade multiplex assays, while certification tier and geographic delivery cost further stratify procurement economics. Pricing pressure stems from predicate device pathway saturation extending regulatory timelines for novel isotype-specific kits. Academic medical centers demonstrate lowest price sensitivity through bundled autoimmune serology contracts, whereas independent reference laboratories face acute margin compression from manual processing overhead.
Supply Chain Analysis
Analytical biochemist recruitment friction in Heidelberg-Mannheim and Texas-California manufacturing corridors constrains phospholipid antigen stabilization capacity expansion for assay manufacturers. Supply concentrates in Germany and the United States for specialized autoimmune diagnostics production, with India emerging as secondary assembly geography following CDSCO registration streamlining. Raw material dependencies encompass bovine cardiolipin extracts, paramagnetic bead coatings, and chemiluminescence substrate reagents. Single-source vulnerability in South American slaughterhouse sourcing creates lot-to-lot consistency risks. Distribution runs through direct sales teams negotiating exclusive integrated delivery network agreements and specialized diagnostic distributors maintaining ELISA kit inventory depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR implementation is consolidating certified suppliers and forcing weaker assay manufacturers toward exit or acquisition, transforming competitive dynamics into a consolidation play for validated manufacturers with quality management system infrastructure.
For Market Incumbents: Anticipate predicate device pathway exhaustion by accelerating novel isotype-specific kit submissions ahead of regulatory backlog accumulation. Deepen backward integration into bovine cardiolipin extraction to secure purified antigen supply against Argentine-Brazilian sourcing concentration. Defensive consolidation through reference laboratory partnership expansion in Texas and California hospital networks counters point-of-care lateral flow substitution threats.
For New Entrants and Emerging Players: CDSCO streamlined medical device registration pathways in India open a window for automated cardiolipin antibody testing infrastructure deployment in Mumbai and Delhi hospital networks. Target fertility clinic segments with prenatal thrombotic risk panel bundling as the most penetrable application expansion vector. Pursue OEM partnerships with established chemiluminescence platform manufacturers to bypass 12-18 month CLIA high-complexity certification timelines.
For Investors and Strategic Acquirers: Annual safety reporting mandates under EU MDR post-market surveillance obligations are the leading indicator that quality management system sophistication will determine long-term viability across the analysis window. Acquisition target archetype: vertically controlled manufacturers with captive reagent production and Heidelberg-based specialized assay footprints. Watch magnetic particle separation technology adoption rates in large hospital laboratories as the inflection signal for platform displacement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate device pathway saturation demands earlier filing timelines for novel isotype-specific kits seeking commercial entry. |
| EU MDR Conformity Assessment Investment | Notified body clinical evidence packages for IgG assays in France and Germany elevate quality management barriers. |
| Hospital System Partnership Expansion | Integrated delivery networks in Texas and California consolidate autoimmune serology contracts under single-source agreements. |
| Magnetic Particle Platform Migration | Paramagnetic bead coating adoption in large laboratories displaces open-system ELISA reagent suppliers. |
| Telemedicine-Integrated Laboratory Network Development | At-home phlebotomy collection bypasses traditional rheumatology referrals for preconception counseling segments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with rheumatology laboratory directors, diagnostic platform procurement managers, biomedical engineers specializing in immunoassay architectures, and GPO contracts managers at integrated delivery networks. FDA 510(k) clearance databases, EMA medical device registration filings, CDSCO import records, and hospital procurement contract disclosures provided secondary validation. Bottom-up test volume modeling across diagnostic laboratories, specialty clinics, and hospital settings triangulated against top-down autoimmune diagnostics market sizing.
Segmentation dimensions were modeled at test type specificity, end user capital equipment intensity, distribution channel contract structure, and application clinical indication granularity across the projection horizon. CAGRs were derived from test volume trajectory analysis and per-test pricing evolution assumptions. Forecast inputs incorporated CLIA high-complexity certification timeline constraints, EU MDR post-market surveillance cost escalation, and magnetic particle separation technology replacement cycle pacing.
Caveats apply where regulatory divergence between FDA streamlined predicate routes and EMA escalating surveillance obligations, or where bovine cardiolipin supply disruption from South American sourcing concentration, could materially shift the outlook. A small set of named triggers—EU MDR notified body capacity constraints, chemiluminescence platform replacement cycle acceleration, and point-of-care lateral flow sensitivity improvements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Herpes Marker Testing Market