
 Global Cardiac Biomarkers Testing Market | 2026-2036
Global Cardiac Biomarkers Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Biomarkers Testing Market Foresight
CE marking under the EU In Vitro Diagnostic Regulation is redrawing competitive access across Europe, forcing manufacturers to rebuild technical documentation and clinical evidence portfolios. F. Hoffmann-La Roche leverages its established IVD infrastructure to sustain compliance leadership across multiple biomarker platforms. Abbott Laboratories anchors its position through integrated point-of-care systems that span emergency departments and ambulatory settings. Siemens Healthineers competes on manufacturing scale, operating high-throughput immunoassay lines that serve centralized laboratory networks.
Cardiac biomarkers testing encompasses quantitative or qualitative laboratory analysis of circulating proteins, enzymes, and peptides released during myocardial injury or stress, typically performed through immunoassay-based methods with detection thresholds reaching picogram-per-milliliter sensitivity for high-sensitivity troponin assays. The primary purpose is rapid diagnosis, risk stratification, and therapeutic monitoring in acute cardiovascular events. Troponin testing dominates value generation due to its entrenched role in myocardial infarction protocols and successive generation upgrades to high-sensitivity formats. Microfluidics technology represents the fastest-expanding segment as miniaturized platforms enable near-patient testing with reduced sample volumes and shortened turnaround times. Diagnostic laboratories remain the largest end-user channel, though cardiac care units are capturing disproportionate growth through decentralized testing expansion.
FDA 510(k) clearances and EU IVDR conformity assessments govern product entry in the two largest addressable territories, while Japan's PMDA maintains distinct clinical performance benchmarks that filter market participants. The FDA's evolving guidance on high-sensitivity troponin clinical cutoffs directly shapes assay development priorities and competitive positioning. Stakeholders must monitor regulatory divergence between major jurisdictions, as harmonization gaps in analytical performance standards create compliance complexity for multi-region product strategies.
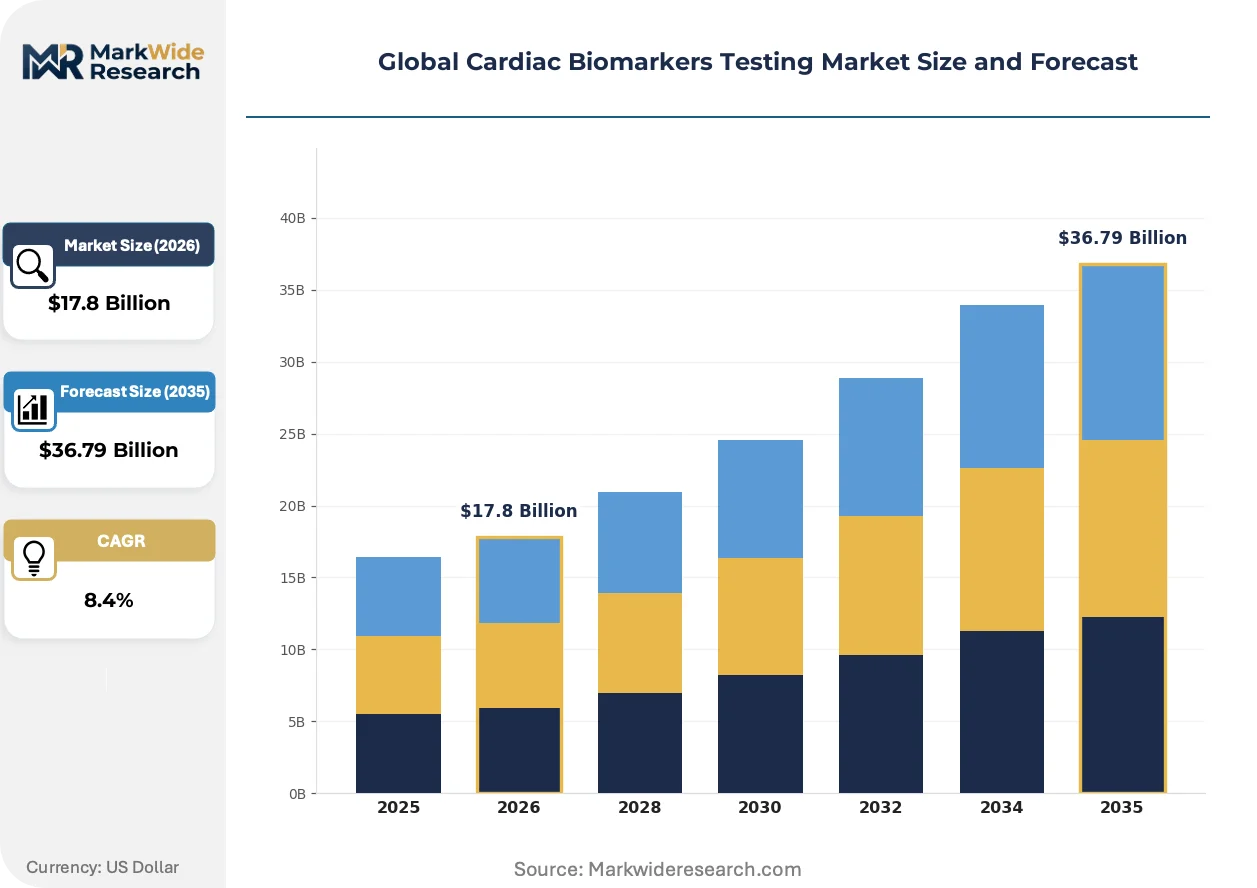
Market Dynamics
The transition from centralized laboratory testing to point-of-care cardiac diagnostics is restructuring competitive economics, compressing turnaround times from hours to minutes while demanding entirely new manufacturing and distribution capabilities from incumbent suppliers.
Growth Catalysts
- EU IVDR Compliance Deadlines:The 2022 In Vitro Diagnostic Regulation mandates recertification of all cardiac biomarker assays, creating replacement demand for next-generation platforms that meet elevated clinical evidence standards.
- Microfluidics Miniaturization:Lab-on-chip architectures reduce sample volumes to microliters, enabling finger-stick troponin testing in ambulance settings and expanding addressable testing locations.
- Japan's Super-Aged Demographics:Over 29% of Japan's population exceeds 65 years, sustaining chronic cardiovascular monitoring volumes that outpace population growth rates.
Market Restraints
- Antibody Supply Concentration:High-affinity troponin monoclonal antibodies derive from a narrow supplier base concentrated in the United States and Western Europe, exposing assay manufacturers to batch-to-batch variability risks.
- Reimbursement Compression:CMS laboratory fee schedule adjustments in the United States constrain pricing power for routine cardiac panels, pressuring gross margins on high-volume assays.
- Platform Lock-In Effects:Hospital systems with installed immunoanalyzer bases face substantial switching costs, slowing adoption of novel biomarker formats that require capital equipment replacement.
Strategic Opportunities
- India's Diagnostic Network Expansion:Tier-2 and Tier-3 cities lack cardiac testing infrastructure, creating first-mover advantage for portable troponin platforms that bypass centralized lab dependencies.
- Multiplex Biomarker Panels:Simultaneous quantification of troponin, BNP, and D-dimer on single cartridges improves diagnostic yield in emergency departments while reducing per-test operational costs.
- FDA Breakthrough Device Designation:Expedited review pathways for novel cardiac biomarkers with superior analytical performance compress time-to-market by 12-18 months versus standard 510(k) submissions.
Industry Challenges
- Clinical Laboratorian Shortages:Specialized expertise in high-sensitivity troponin assay validation and quality control is scarce, extending implementation timelines for new platform deployments.
- Interoperability Friction:Point-of-care devices must integrate with hospital information systems and electronic health records, requiring costly custom interface development for each institutional deployment.
- Harmonization Deficits:Analytical performance standards for high-sensitivity troponin differ between FDA, PMDA, and IVDR jurisdictions, forcing redundant clinical studies for multi-region product registrations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Biomarkers Testing Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $36.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Troponin, Creatine Kinase-MB, Myoglobin, B-Type Natriuretic Peptide, Copeptin Application Area: Acute Coronary Syndrome, Heart Failure, Arrhythmia Diagnosis, Myocardial Infarction, Risk Assessment End User: Cardiac Care Units, Diagnostic Laboratories, Outpatient Clinics, Research Institutes, Ambulatory Care Centers Technology: Immunoassay, Electrochemiluminescence, Enzyme-Linked Immunosorbent Assay, Fluorescence Immunoassay, Microfluidics |
| Companies Covered | F. Hoffmann-La Roche, Abbott Laboratories, Siemens Healthineers, Thermo Fisher Scientific, Becton Dickinson and Company, Bio-Rad Laboratories, bioMérieux, Randox Laboratories, Beckman Coulter, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Biomarkers Testing Market Shifts & Advancements
Digital connectivity and assay sensitivity thresholds are advancing in parallel, creating new performance tiers that separate emergency diagnostic workflows from chronic disease monitoring applications.
Electrochemiluminescence detection architectures are supplanting traditional chemiluminescent immunoassays in high-throughput laboratory settings. Reference laboratories in Germany and the United States are adopting these platforms for troponin quantification at femtomolar sensitivity. The technology is supplanting older enzyme-linked formats by enabling 24-hour operational windows with reduced calibration frequency.
Japan's PMDA revised its clinical performance benchmarks for high-sensitivity troponin assays in 2023, requiring manufacturers to demonstrate 99th percentile reference limit precision across sex-stratified populations. This policy shift elevates analytical validation burdens for market entry. Domestic Japanese manufacturers with established clinical study infrastructure are capturing disproportionate share of new assay approvals.
Emergency departments are unbundling cardiac biomarker testing from comprehensive metabolic panels, purchasing troponin-specific cartridges on consumption-based contracts rather than bundled service agreements. This purchasing fragmentation favors point-of-care vendors with flexible supply arrangements. The United States exhibits the most pronounced unbundling behavior, driven by emergency physician practice autonomy and separate reimbursement coding.
Global Cardiac Biomarkers Testing Market Segmentation
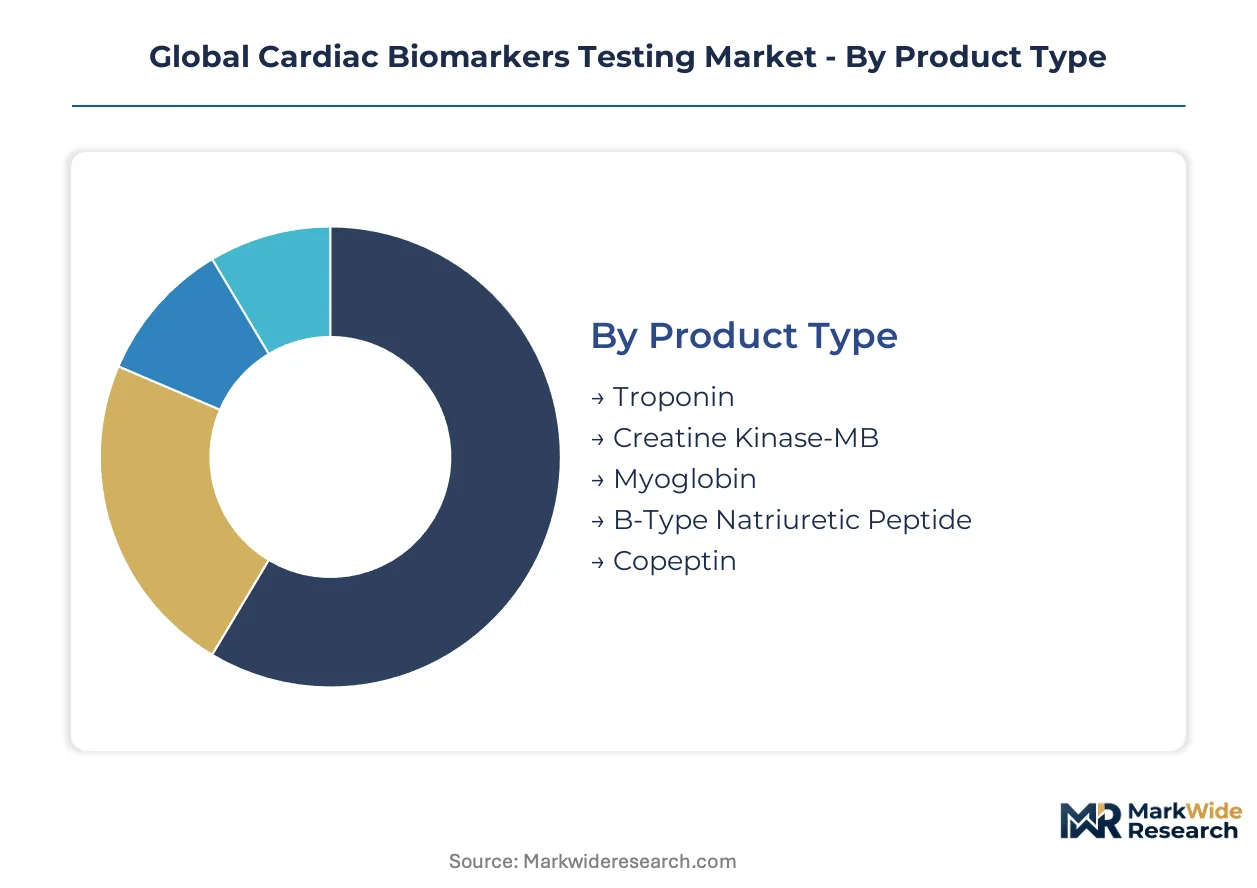
Cardiac biomarker testing segments diverge sharply by clinical workflow integration and regulatory pathway complexity. Product and technology categories concentrate manufacturing investment in the United States, Germany, and Japan, while application and end-user segments distribute demand across emergency, chronic, and preventive care settings.
Product Type:
Troponin assays dominate domestic production in the United States and Japan, while creatine kinase-MB and myoglobin formats see heavier export orientation toward emerging diagnostic networks.
- Troponin:High-sensitivity immunoassays detect cardiac troponin I and T at picogram-per-milliliter thresholds, enabling myocardial infarction diagnosis within hours of symptom onset. Demand concentrates in hospital emergency departments across the United States, Germany, and Japan where chest pain protocols mandate rapid rule-out testing.
- B-Type Natriuretic Peptide:Quantitative assays measure NT-proBNP and BNP peptides released during ventricular wall stress, supporting heart failure severity grading and therapeutic monitoring. German reference laboratories and Japanese cardiac centers drive sustained volume for chronic cardiovascular management programs.
- Creatine Kinase-MB:Enzyme activity assays detect myocardial-specific CK isoenzymes, serving as secondary confirmation markers in regions with limited high-sensitivity troponin access.
- Myoglobin:Early-release heme protein assays provide rapid negative predictive value for myocardial injury, deployed primarily in ambulance and pre-hospital settings.
- Copeptin:C-terminal provasopressin fragments enable dual-marker strategies with troponin for accelerated myocardial infarction exclusion, gaining traction in European emergency protocols.
Troponin commands the established base. The steepest expansion runs through B-Type Natriuretic Peptide.
Application Area:
Acute applications cluster in high-throughput hospital systems with substantial capital equipment investment, while chronic and risk stratification applications distribute across outpatient networks with lighter infrastructure requirements.
- Acute Coronary Syndrome:Rapid diagnostic protocols require serial biomarker testing at presentation and intervals to detect rising or falling patterns indicative of unstable angina or non-ST elevation myocardial infarction. United States emergency departments and German chest pain units anchor procedural standardization.
- Myocardial Infarction:Definitive diagnosis hinges on troponin elevation above the 99th percentile reference limit with clinical evidence of ischemia, forming the regulatory benchmark for high-sensitivity assay approvals. Japanese PMDA and FDA guidance shapes manufacturer development priorities.
- Heart Failure:BNP and NT-proBNP monitoring guides diuretic therapy titration and hospitalization risk stratification in chronic care settings.
- Arrhythmia Diagnosis:Biomarker elevation patterns assist in differentiating ischemic from non-ischemic rhythm disturbances.
- Risk Assessment:Pre-operative and preventive screening applications expand testing into ambulatory and occupational health settings.
Myocardial Infarction anchors the revenue base. Acute Coronary Syndrome is climbing the fastest as emergency protocols compress diagnostic timelines.
End User:
Capital-intensive end users concentrate in metropolitan medical centers across the United States, Germany, and Japan, while decentralized channels target secondary cities and transportable care models.
- Diagnostic Laboratories:Centralized reference facilities process high-volume cardiac panels on automated immunoanalyzer platforms, achieving economies of scale through 24-hour operational scheduling. Siemens Healthineers and Roche installations dominate laboratory networks in Germany and the United States.
- Cardiac Care Units:Intensive care and coronary care settings require stat turnaround times under 60 minutes, driving point-of-care platform adoption with direct connectivity to electronic health records.
- Ambulatory Care Centers:Same-day surgical and procedural facilities deploy rapid troponin testing for pre-operative risk stratification.
- Outpatient Clinics:Community-based cardiology practices integrate BNP testing for chronic heart failure monitoring.
- Research Institutes:Academic medical centers validate novel biomarker signatures and assay performance characteristics for regulatory submission.
Diagnostic Laboratories command the established base. Cardiac Care Units are gaining share fastest through point-of-care decentralization.
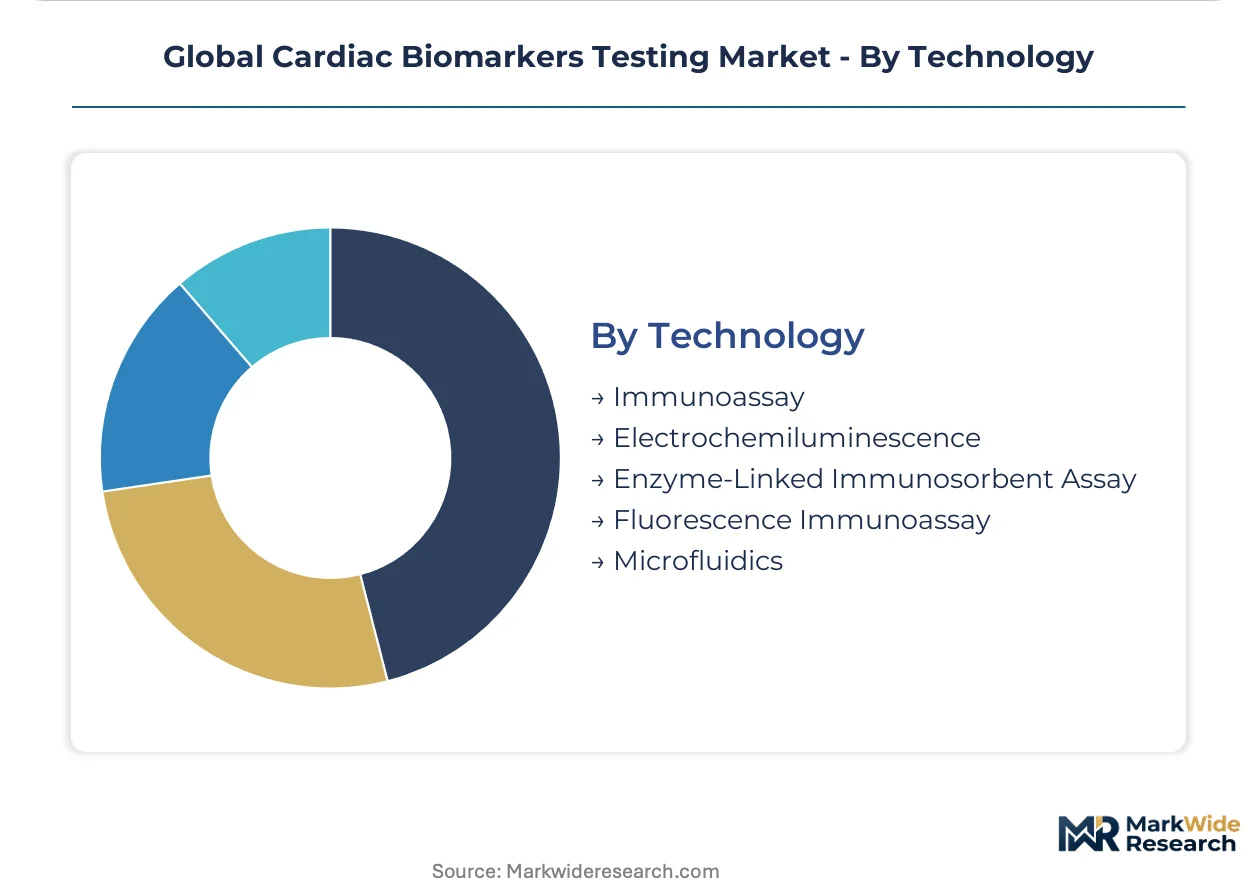
Technology:
Electrochemiluminescence and microfluidics platforms concentrate advanced manufacturing in Germany and the United States, while conventional immunoassay formats maintain broader geographic production distribution.
- Electrochemiluminescence:Ru(bpy)3-based detection achieves femtomolar sensitivity with wide dynamic range, supporting 24-hour laboratory operation with extended calibration stability. German reference laboratories and United States health systems anchor platform standardization for high-sensitivity troponin quantification.
- Microfluidics:Lab-on-chip architectures integrate sample preparation, reaction chambers, and optical detection in disposable cartridges, enabling finger-stick testing with microliter sample volumes. Japanese manufacturers and United States point-of-care vendors lead cartridge miniaturization for ambulance and emergency department deployment.
- Immunoassay:Chemiluminescent and fluorescent detection formats dominate installed base across mid-throughput laboratory segments.
- Enzyme-Linked Immunosorbent Assay:Conventional ELISA formats persist in research and resource-limited settings with lower capital requirements.
- Fluorescence Immunoassay:Time-resolved fluorescence detection supports multiplexed biomarker quantification on compact benchtop instruments.
Immunoassay anchors the installed base. Microfluidics is expanding most quickly as near-patient testing restructures emergency workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's streamlined 510(k) pathway for high-sensitivity troponin assays accelerates commercial entry in the United States, while Japan's PMDA maintains distinct clinical performance benchmarks that filter market participants. Germany's reference laboratories anchor European standardization under evolving IVDR requirements.
United States
Emergency departments in the United States drive sustained cardiovascular screening volumes through chest pain protocols mandating rapid troponin rule-out testing. CMS laboratory fee schedule adjustments constrain pricing power for routine cardiac panels. The Greater Boston and San Francisco Bay Area clusters concentrate point-of-care platform development for ambulance deployment.
Germany
German chest pain units anchor procedural standardization for acute coronary syndrome diagnostics across European hospital networks. CE marking under the EU In Vitro Diagnostic Regulation mandates recertification of all cardiac biomarker assays, creating replacement demand. The Rhine-Ruhr metropolitan region hosts high-throughput immunoanalyzer installations serving centralized laboratory networks.
Japan
Over 29% of Japan's population exceeds 65 years, sustaining chronic cardiovascular monitoring volumes that outpace population growth rates. PMDA revised clinical performance benchmarks for high-sensitivity troponin assays in 2023, requiring 99th percentile reference limit precision across sex-stratified populations. Domestic manufacturers with established clinical study infrastructure capture disproportionate share of new assay approvals in Tokyo and Osaka medical centers.
India
Tier-2 and Tier-3 cities lack cardiac testing infrastructure, creating first-mover advantage for portable troponin platforms that bypass centralized lab dependencies. The country's national pharmaceutical regulator evaluates diagnostic import registrations with escalating local clinical trial requirements. Maharashtra and Karnataka states concentrate private diagnostic network expansion targeting cardiac care unit decentralization.
United Kingdom
National Health Service procurement frameworks favor integrated point-of-care systems spanning emergency departments and ambulatory settings. MHRA post-Brexit regulatory autonomy maintains alignment with IVDR standards while streamlining UK-specific conformity routes. The Oxford-Cambridge-London arc anchors academic medical center validation of novel biomarker signatures for regulatory submission.
Global Cardiac Biomarkers Testing Market Competitive Landscape
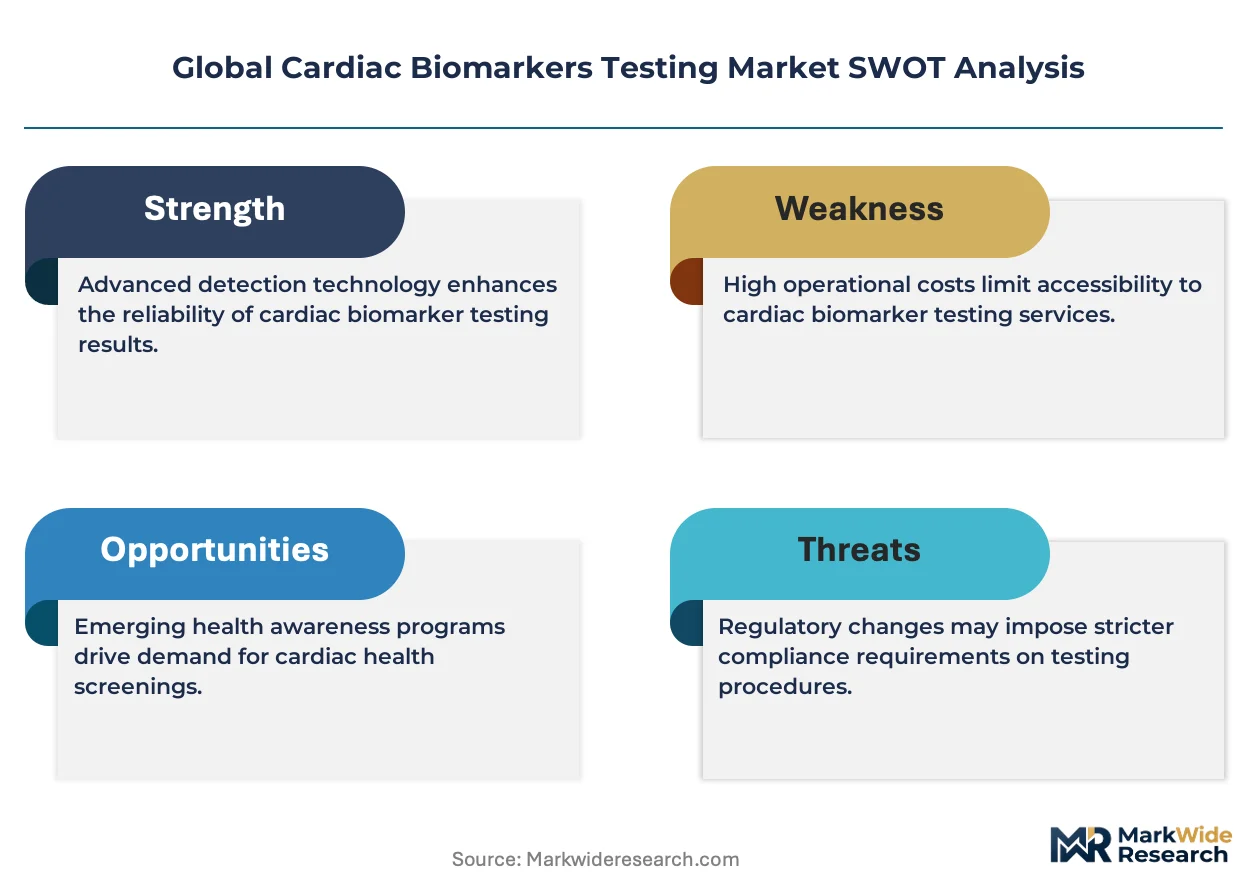
Player mix skews toward diversified diagnostic conglomerates with established IVD infrastructure. Market structure concentrates manufacturing scale among three to four vertically integrated suppliers controlling high-affinity antibody supply chains and automated immunoanalyzer platforms. Strategic archetypes include centralized laboratory specialists, point-of-care integrators, and reference laboratory service providers. Competitive moves center on microfluidics miniaturization partnerships and multiplex biomarker panel development.
Within the diversified diagnostic conglomerate tier, F. Hoffmann-La Roche and Abbott Laboratories exemplify contrasting platform strategies. Roche occupies a position emphasizing compliance leadership across multiple biomarker platforms under European regulatory frameworks. Abbott represents the point-of-care integration archetype, anchoring emergency department and ambulatory setting deployment. Siemens Healthineers sits within the manufacturing scale tier, serving centralized laboratory networks with high-throughput immunoassay lines. These three entities collectively illustrate the competitive spectrum from laboratory automation to decentralized testing architectures.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Abbott Laboratories |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| Bio-Rad Laboratories |
| bioMérieux |
| Randox Laboratories |
| Beckman Coulter |
| Others |
Supply & Pricing Matrix
Electrochemiluminescence detection architectures replacing chemiluminescent immunoassays simultaneously redraw supply geography toward German and United States manufacturing clusters while compressing per-test economics through extended calibration intervals and reduced reagent consumption.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA 510(k) cleared high-sensitivity troponin assays commanding substantial premiums over CE-marked equivalents in United States emergency departments. Three-tier pricing structure across premium, standard, and economy levels reflects analytical sensitivity thresholds, with femtomolar-capable platforms at the apex. Price erosion runs through economy-tier immunoassay formats as Indian and Chinese manufacturers expand cartridge production. Hospital procurement committees demonstrate highest price sensitivity, while cardiac care units prioritize turnaround time over per-test cost.
Supply Chain Analysis
United States and Germany anchor high-affinity monoclonal antibody production for troponin assays, with Japanese manufacturers supplying specialized microfluidic cartridges for point-of-care deployment. Critical inputs include recombinant antibody cell lines, Ru(bpy)3 electrochemiluminescence substrates, and precision-molded polymer microchannels. Single-source vulnerability concentrates in high-affinity troponin antibody suppliers, exposing assay manufacturers to batch-to-batch variability and qualification delays. Distribution runs through diagnostic conglomerate direct sales forces serving hospital networks, supplemented by specialized IVD distributors for mid-tier laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care microfluidics adoption in ambulance and pre-hospital settings signals early-cycle expansion, with decentralized testing penetration still below saturation thresholds across Tier-2 and Tier-3 diagnostic networks.
For Market Incumbents: Consolidate antibody supply security through captive bioreactor capacity or exclusive supplier partnerships, as high-affinity troponin monoclonal concentration in United States and Western European vendors creates vulnerability. Deepen installed base lock-in via electronic health record integration investments that raise switching costs for hospital systems evaluating platform migration. Prioritize EU IVDR technical documentation completion to capture replacement demand from assays requiring recertification. For New Entrants and Emerging Players: Lead with portable troponin platforms targeting India's Tier-2 and Tier-3 cities, where centralized laboratory infrastructure gaps create first-mover advantage for finger-stick testing bypassing lab dependencies. Penetrate European emergency departments through copeptin-troponin dual-marker strategies that accelerate myocardial infarction exclusion protocols. Deploy consumption-based cartridge contracts that align with unbundled purchasing behavior in United States emergency physician practices. For Investors and Strategic Acquirers: EU IVDR recertification deadlines reshape the acquisition landscape, elevating targets with completed technical documentation and clinical evidence portfolios above those facing compliance gaps. Five-to-ten year viability favors manufacturers with backward integration into antibody production and microfluidic cartridge fabrication. Monitor FDA breakthrough device designation awards as inflection indicators for novel biomarker platforms with compressed time-to-market trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidics Platform Miniaturization | Lab-on-chip architectures enable finger-stick troponin testing in ambulance settings with microliter sample volumes. |
| Multiplex Biomarker Panel Development | Simultaneous troponin-BNP-D-dimer quantification improves emergency department diagnostic yield and operational efficiency. |
| EU IVDR Technical Documentation Completion | Recertification compliance secures continued market access across European reference laboratory networks. |
| Antibody Supply Chain Captive Integration | In-house bioreactor capacity mitigates batch-to-batch variability risks from concentrated external suppliers. |
| Hospital Information System Integration Investment | Direct electronic health record connectivity raises institutional switching costs and extends platform retention. |
Research Methodology
A standing panel of emergency medicine physicians, clinical laboratory directors, IVD regulatory affairs specialists, and hospital procurement managers provided ongoing calibration against market developments throughout the study period. Primary fieldwork combined structured interviews with biomarker assay manufacturers and secondary validation through FDA 510(k) filings, PMDA approval summaries, EU IVDR notified body certificates, and hospital GPO contract databases. Bottom-up demand modeling across emergency department, cardiac care unit, and diagnostic laboratory channels triangulated against top-down manufacturer revenue segmentation.
Consistency checks validated volume and value outputs against installed base estimates for automated immunoanalyzer platforms and point-of-care device placements across the analysis window. Segmentation dimensions spanned product type, application area, end user, and technology platform, with regional regulatory clusters modeled as distinct adoption corridors. CAGRs derived from logistic penetration curves applied to high-sensitivity troponin assay conversion rates and microfluidics platform deployment trajectories. Forecast inputs incorporated EU IVDR recertification timelines, CMS laboratory fee schedule adjustment patterns, and Japan's super-aged demographic cardiovascular monitoring intensity.
Forecasts assume regulatory continuity in FDA 510(k) pathways, EU IVDR conformity assessment procedures, and PMDA clinical performance benchmarks; material policy shifts in analytical sensitivity standards or reimbursement coding would require re-modeling. Specific risks include antibody supply disruption, interoperability implementation delays, and harmonization deficits between jurisdictional performance requirements. Recalibration cycles align with material shifts in regulatory guidance, breakthrough device designation awards, and decentralized testing penetration metrics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market