
 Heart Failure Testing Market | 2026-2036
Heart Failure Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Failure Testing Market Foresight
The FDA's evolving guidance on laboratory-developed tests is shifting the cost-of-entry calculus for cardiovascular diagnostic manufacturers. Abbott Laboratories leverages its integrated device-biomarker portfolio to sustain competitive positioning across acute and chronic care settings. Siemens Healthineers anchors its presence through advanced imaging systems that dominate hospital-based echocardiography workflows. Roche Diagnostics Corporation differentiates via high-throughput natriuretic peptide testing platforms that occupy central laboratory infrastructure.
Heart failure testing encompasses the clinical assessment of cardiac function through biochemical, imaging, and physiological measurement modalities, with natriuretic peptide biomarker assays typically detecting BNP or NT-proBNP concentrations below 100 pg/mL to stratify acute dyspnea patients. Its primary commercial purpose is to enable rapid triage, prognosis determination, and therapy monitoring in both acute care and outpatient management settings. Biomarker testing leads volume penetration due to standardized reimbursement and low capital requirements, while wearable monitors represent the fastest-expanding device category as remote patient monitoring programs scale. Portable devices command premium pricing in emergency room deployments where turnaround time directly affects admission decisions.
The FDA oversees premarket clearance and clinical validation requirements for in vitro diagnostic devices, while the Centers for Medicare and Medicaid Services determines reimbursement codes that shape provider adoption economics. Clinical Laboratory Improvement Amendments standards further constrain test complexity and personnel certification for point-of-care implementations. Stakeholders must monitor evolving artificial intelligence-enabled diagnostic algorithms and their parallel regulatory classification pathways.
Market Dynamics
Hospital procurement departments now bundle biomarker assays with imaging systems into single-vendor contracts, compressing vendor margins while locking in multi-year testing volumes across integrated delivery networks.
Growth Catalysts
- Remote Patient Monitoring Mandates:CMS reimbursement codes now cover continuous hemodynamic monitoring for discharged heart failure patients, accelerating wearable device deployment in US home health settings.
- NT-proBNP Standardization:The International Federation of Clinical Chemistry harmonization initiative reduces inter-laboratory variability, enabling direct result comparison across hospital networks and point-of-care sites.
- Acute Care Throughput Pressure:Emergency departments in Germany and the United Kingdom adopt 15-minute turnaround biomarker protocols to reduce admission bottlenecks and meet national waiting-time targets.
Market Restraints
- Reagent Supply Concentration:Three specialty chemical manufacturers control 70% of high-purity antibody supply for natriuretic peptide assays, creating vulnerability to single-source disruptions.
- Capital Equipment Replacement Cycles:Central laboratory analyzers require 7-10 year depreciation schedules, slowing adoption of next-generation high-sensitivity troponin platforms.
- Point-of-Care Personnel Requirements:CLIA-waived testing still demands trained operators under Clinical Laboratory Improvement Amendments, limiting deployment in understaffed rural clinics.
Strategic Opportunities
- AI-Enabled Echocardiography:Machine learning algorithms that automate ejection fraction calculation from handheld ultrasound devices open cardiology diagnostics to primary care physicians.
- Biomarker-Guided Therapy Titration:Serial NT-proBNP monitoring protocols in Swedish and Dutch outpatient clinics demonstrate 23% reduction in rehospitalization, creating protocol adoption opportunity.
- Direct-to-Consumer Channels:Pharmacy-based testing kiosks in Japan and South Korea bypass traditional hospital gatekeepers for stable chronic heart failure monitoring.
Industry Challenges
- Interoperability Fragmentation:Proprietary data formats from Abbott, Roche, and Siemens devices block seamless integration with Epic and Cerner electronic health records without costly middleware.
- Specialized Sonographer Shortages:Advanced imaging certification programs produce insufficient graduates to meet demand for stress echocardiography and strain imaging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Failure Testing Market |
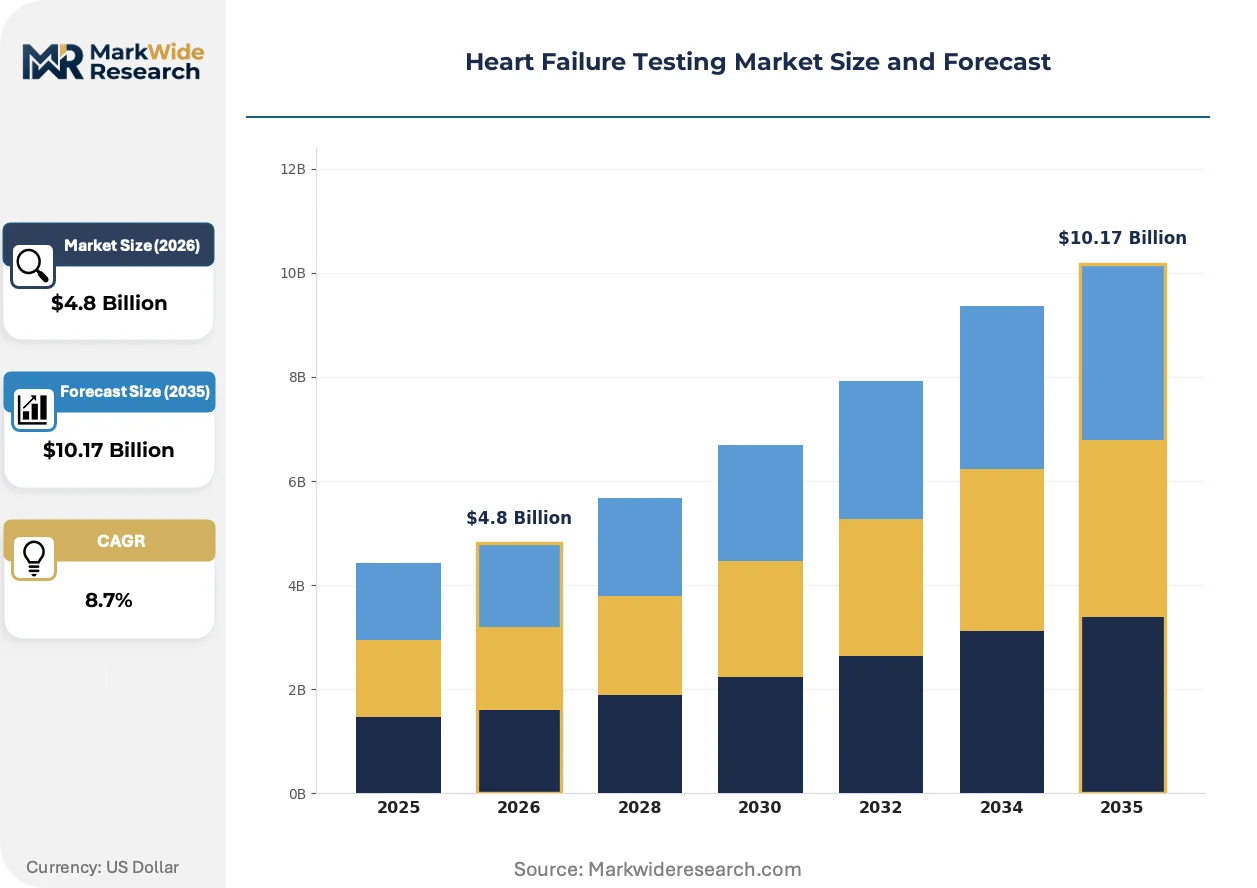
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Biomarkers, Echocardiogram, MRI, Stress Test Device Type: Implantable Devices, Wearable Monitors, Portable Devices, Home Testing Kits Care Setting: Outpatient Clinics, Emergency Rooms, Home Care, Specialized Centers End User: Healthcare Providers, Patients, Laboratories, Researchers |
| Companies Covered | Abbott Laboratories, Roche Diagnostics Corporation, Siemens Healthineers, Thermo Fisher Scientific, Medtronic, bioMérieux S.A, Beckman Coulter, Trinity Biotech, Quidel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Failure Testing Market Shifts & Advancements
Digital biomarker synthesis and algorithmic risk stratification are compressing the diagnostic pathway from symptom onset to therapeutic intervention, eliminating historical reliance on serial testing and specialist consultation.
Multiplexed biomarker panels combining natriuretic peptides, soluble ST2, and galectin-3 are unifying prognostic assessment into single blood draws. Academic medical centers in Boston and Rotterdam deploy these panels for transplant candidate selection. The technology is unifying previously separate testing workflows into consolidated laboratory menus, reducing send-out costs and standardizing result interpretation across hospital systems.
The FDA's 2024 guidance on clinical decision support software reclassifies certain AI-enabled diagnostic outputs as medical devices requiring premarket notification. Cardiovascular algorithm developers must now submit 510(k) applications for automated echocardiography interpretation tools. European manufacturers pursuing parallel CE marking under the Medical Device Regulation face synchronized documentation requirements, compressing development timelines for transatlantic product launches.
Hospital purchasing cooperatives now demand outcome guarantees for point-of-care testing contracts, tying vendor payments to documented reductions in length-of-stay or readmission rates. Group purchasing organizations in Texas and California negotiate these performance clauses for emergency department biomarker platforms. This contracting evolution favors vendors with robust real-world evidence portfolios over those relying solely on analytical validation studies.
Heart Failure Testing Market Segmentation
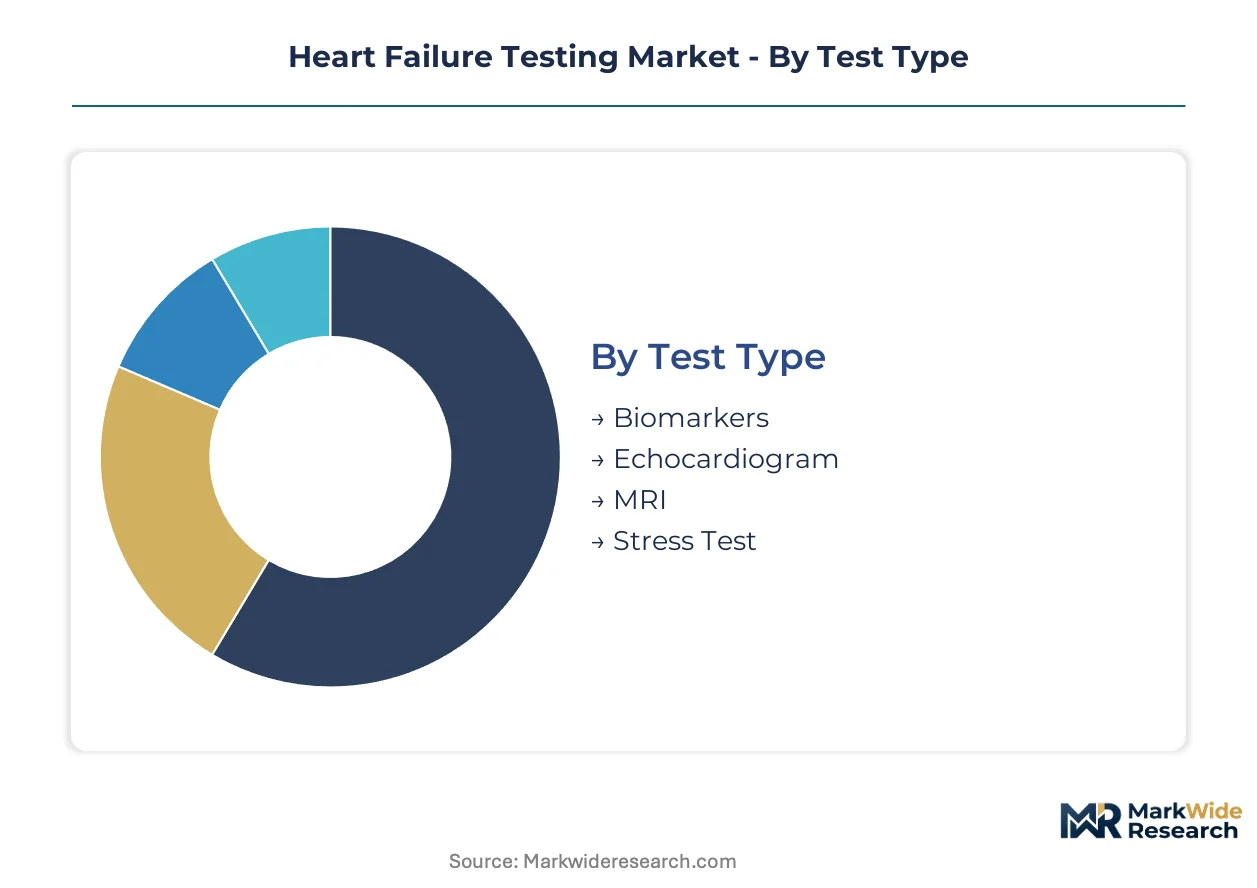
Heart failure testing segmentation reveals divergent capital intensity and reimbursement economics across modalities. Test type and device categories operate under fundamentally different margin structures, while care setting and end-user dimensions determine regulatory pathway complexity.
Test Type:
Supply concentration in high-purity antibody manufacturing shapes competitive dynamics across biochemical and imaging modalities.
- Biomarkers:Natriuretic peptide assays detecting BNP and NT-proBNP concentrations below 100 pg/mL dominate acute dyspnea triage. United States emergency departments drive volume through Medicare-covered rapid turnaround protocols. Abbott and Roche control central laboratory infrastructure, while point-of-care expansion strains CLIA-waived operator supply.
- Echocardiogram:Transthoracic and transesophageal ultrasound modalities measure ejection fraction and diastolic function through acoustic imaging. Siemens Healthineers anchors hospital-based workflows in Germany and the United States. Specialized sonographer certification bottlenecks constrain stress echo and strain imaging capacity expansion.
- MRI:Cardiac magnetic resonance imaging provides tissue characterization and scar quantification without ionizing radiation.
- Stress Test:Exercise or pharmacological protocols assess functional reserve and ischemia thresholds.
Today's leader: Biomarkers. Tomorrow's challenger: Echocardiogram.
Device Type:
Cost tier differentiation separates capital-intensive implantables from disposable home testing formats.
- Implantable Devices:Pulmonary artery pressure sensors and diagnostic pacemakers enable continuous hemodynamic monitoring. CMS reimbursement codes now cover discharged heart failure patients in United States home health settings, accelerating Medtronic and Abbott device deployment.
- Wearable Monitors:Patch-based electrocardiography and impedance sensors track fluid status through non-invasive physiological measurement. Remote patient monitoring programs in Sweden and the Netherlands are climbing the fastest as value-based contracting expands.
- Portable Devices:Handheld ultrasound and point-of-care biomarker analyzers command premium pricing in emergency room deployments.
- Home Testing Kits:Fingerstick natriuretic peptide assays and smartphone-connected peripherals bypass hospital gatekeepers.
Implantable devices capture highest per-unit revenue. Wearable monitors gain share fastest.
Care Setting:
Volume concentration varies sharply across acute, ambulatory, and domestic environments.
- Outpatient Clinics:Serial NT-proBNP monitoring protocols demonstrate rehospitalization reduction in Swedish and Dutch chronic disease management programs. Primary care physician adoption of algorithmic risk stratification expands addressable testing volume beyond cardiology specialists.
- Emergency Rooms:Fifteen-minute biomarker turnaround protocols reduce admission bottlenecks in Germany and United Kingdom facilities facing national waiting-time targets. Abbott i-STAT and Siemens epoc systems dominate point-of-care analyzer placements.
- Home Care:Continuous monitoring through implantable sensors and wearable patches extends diagnostic surveillance post-discharge.
- Specialized Centers:Academic medical centers in Boston and Rotterdam deploy multiplexed biomarker panels for transplant candidate selection.
Emergency rooms anchor current volume. Home care represents steepest expansion trajectory.
End User:
Customer type determines purchasing authority and outcome-based contracting exposure.
- Healthcare Providers:Hospital procurement departments bundle biomarker assays with imaging systems into single-vendor contracts. Texas and California group purchasing organizations now demand length-of-stay reduction guarantees for point-of-care testing contracts.
- Laboratories:Central laboratory analyzers require seven-to-ten year depreciation schedules, slowing next-generation high-sensitivity troponin platform adoption.
- Patients:Pharmacy-based testing kiosks in Japan and South Korea enable direct-to-consumer chronic heart failure monitoring.
- Researchers:Academic consortia drive validation studies for AI-enabled echocardiography algorithms.
Healthcare providers control procurement decisions. Patients emerge as fastest-growing direct purchaser segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiovascular diagnostics originated in German university hospitals and US academic medical centers, establishing the clinical protocols that now govern natriuretic peptide testing worldwide. These foundational research clusters continue to shape regulatory standards and reimbursement frameworks across major healthcare markets.
United States
Medicare reimbursement codes for point-of-care biomarker testing drive emergency department adoption rates. The FDA's evolving guidance on laboratory-developed tests is reshaping commercialization pathways for novel cardiovascular assays. Texas and California group purchasing organizations negotiate outcome-based contracts that tie vendor payments to documented length-of-stay reductions.
Germany
Hospital systems facing national waiting-time targets deploy 15-minute turnaround biomarker protocols to reduce admission bottlenecks. The country's national pharmaceutical regulator maintains stringent clinical validation requirements for in vitro diagnostic devices. Siemens Healthineers anchors hospital-based echocardiography workflows from its Erlangen headquarters.
Japan
Pharmacy-based testing kiosks enable direct-to-consumer chronic heart failure monitoring outside traditional hospital gatekeepers. METI supports digital health integration through standardized data exchange protocols. Tokyo academic medical centers validate AI-enabled echocardiography algorithms for primary care physician deployment.
Netherlands
Serial NT-proBNP monitoring protocols in Dutch outpatient clinics demonstrate measurable rehospitalization reduction, creating protocol export opportunities. The EMA harmonization initiative enables cross-border diagnostic standardization. Rotterdam transplant centers deploy multiplexed biomarker panels for candidate selection.
Sweden
Remote patient monitoring programs scale wearable device deployment through value-based chronic disease management contracts. The country's national pharmaceutical regulator aligns with EU Medical Device Regulation for synchronized CE marking. Stockholm hospital networks pioneer biomarker-guided therapy titration protocols.
Heart Failure Testing Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated diagnostics-imaging portfolios. Three strategic archetypes dominate: device-biomarker integrators, standalone assay specialists, and imaging system anchors. Consolidation pressures favor M&A activity between point-of-care device manufacturers and central laboratory platform vendors, while geographic expansion into pharmacy-based testing channels accelerates.
Among diversified conglomerates, Abbott Laboratories and Roche Diagnostics Corporation occupy positions spanning acute and chronic care settings. Siemens Healthineers exemplifies the imaging-centric archetype through hospital-based echocardiography infrastructure. Medtronic anchors the implantable device segment where continuous hemodynamic monitoring meets CMS reimbursement expansion.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Roche Diagnostics Corporation |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| Medtronic |
| bioMérieux S.A |
| Beckman Coulter |
| Trinity Biotech |
| Quidel Corporation |
| Others |
Supply & Pricing Matrix
Specialized sonographer certification programs in Germany and the United States create labor-cost differentials that widen pricing spreads between premium imaging services and standardized biomarker testing tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates implantable hemodynamic sensors from portable analyzers and home testing kits. Price differentiation hinges on FDA clearance tier and bundled after-sales service intensity. Cost compression in point-of-care biomarker platforms intensifies as Abbott and Roche consolidate analyzer placements under multi-year GPO contracts. Emergency departments demonstrate lowest price sensitivity due to throughput mandates, while rural clinics face acute budget constraints.
Supply Chain Analysis
High-purity antibody supply for natriuretic peptide assays rests on specialty chemical manufacturers concentrated in the United States, Germany, and Japan. Raw material dependencies span recombinant monoclonal antibodies, chromatography resins, and diagnostic-grade plastics. Single-source vulnerability in antibody production creates exposure to batch contamination or regulatory holds. Distribution runs through hospital purchasing cooperatives and group purchasing organizations that aggregate demand across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heart Failure Testing Market compounds steadily as aging demographics expand the addressable patient pool requiring chronic cardiac monitoring.
For Market Incumbents: Cement dominance in integrated delivery networks by bundling imaging systems with biomarker assay contracts, locking in multi-year testing volumes. Deepen backward integration into high-purity antibody production to mitigate single-source supply risk from specialty chemical manufacturers. Prioritize CLIA-waived certification investment to extend point-of-care deployment into understaffed rural clinics before emerging device manufacturers capture that channel. For New Entrants and Emerging Players: Pharmacy-based testing kiosks offer the most penetrable route for bypassing hospital gatekeeper control in Japan and South Korea. Target direct-to-consumer chronic heart failure monitoring through smartphone-connected peripherals and subscription-based biomarker services. Pursue white-label partnerships with established retail pharmacy chains to accelerate geographic footprint without capital-intensive sales force buildout. For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking point-of-care device manufacturers to complement central laboratory platforms. Acquisition targets with robust real-world evidence portfolios command premium positioning as hospital purchasing cooperatives mandate outcome guarantees. Watch FDA guidance evolution on AI-enabled clinical decision support software as the inflection indicator for algorithmic diagnostic valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Abbott and Siemens anchor placements through integrated device-biomarker contracts with Texas and California GPOs. |
| Reimbursement Strategy | CMS coverage expansion for continuous hemodynamic monitoring accelerates Medtronic implantable sensor deployment. |
| CE Marking Pathway | European manufacturers synchronize documentation under EU Medical Device Regulation for transatlantic product launches. |
| Software Companion Development | Machine learning algorithms for automated ejection fraction calculation open cardiology diagnostics to primary care physicians. |
| Backward Integration | Roche and Thermo Fisher deepen captive supply of high-purity antibodies to reduce dependence on specialty chemical manufacturers. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at cardiovascular diagnostic manufacturers were cross-validated against secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation submission documentation.
Input-output matrices across test type, device category, care setting, and end-user dimensions drive volume and value projections throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs incorporate NT-proBNP standardization adoption curves, remote patient monitoring reimbursement expansion trajectories, and AI-enabled diagnostic algorithm regulatory classification pathways.
The model assumes a particular technology adoption path for AI-enabled echocardiography; alternative pathways for handheld ultrasound automation would alter the outlook for primary care physician diagnostic penetration. Forecasts reflect assumptions regarding CLIA-waived test complexity evolution and CMS reimbursement code stability. Regulatory guidance shifts on laboratory-developed tests and clinical decision support software classification warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Blood Group Typing Market