
 Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market | 2026-2036
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
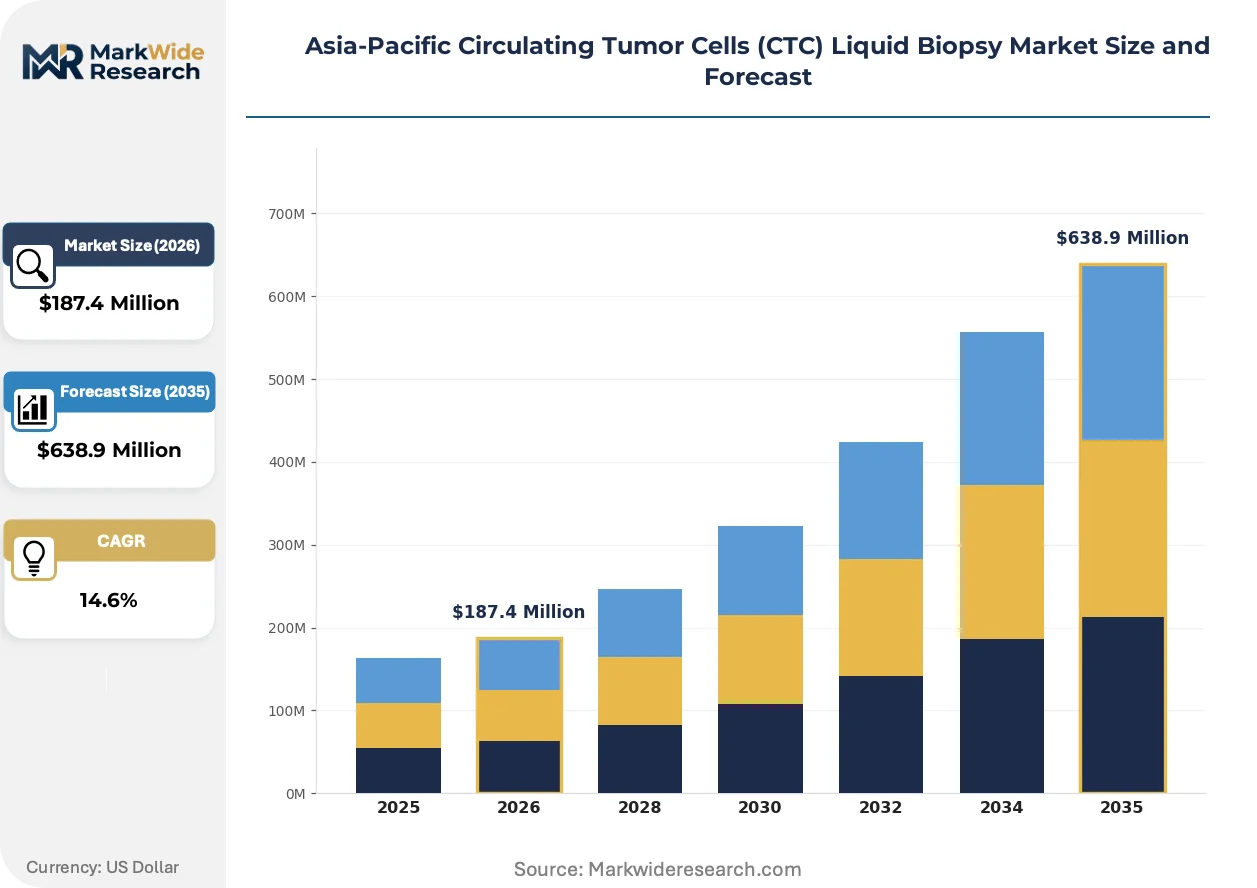
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market Outlook
Chinese clinical laboratory networks is shifting toward automated CTC isolation platforms to manage rising oncology sample volumes. Guardant Health leverages its circulating tumor DNA expertise to extend into CTC-based assay development across East Asian markets. Sysmex Corporation anchors its position through deep integration with Japan's hospital laboratory infrastructure and proprietary cell analysis systems. QIAGEN competes by sustaining broad PCR and NGS sample preparation portfolios that feed into multi-omic liquid biopsy workflows.
Asia-Pacific circulating tumor cells liquid biopsy encompasses the isolation, enumeration, and molecular characterization of tumor-derived cells shed into peripheral blood, typically captured through immunomagnetic separation or microfluidic enrichment at sensitivities reaching single-cell resolution. These platforms enable real-time cancer progression tracking without invasive tissue sampling, primarily serving treatment monitoring and therapeutic selection in solid tumor management. Microfluidics-based CTC isolation commands the technology segment due to superior cell viability preservation for downstream genomic analysis. Next-generation sequencing integration is expanding fastest as oncology centers demand comprehensive mutational profiling from limited CTC inputs. Cancer diagnosis applications retain the largest patient volume footprint, though biomarker discovery segments attract premium pricing from pharmaceutical partners.
Japan's PMDA governs in vitro diagnostic registration timelines, while China's NMPA oversees innovative device designation and clinical trial waivers for breakthrough oncology tests. Australia's TGA alignment with EU MDR standards creates dual-market certification efficiencies for Asia-Pacific manufacturers. India's CDSCO import licensing requirements and state-level clinical establishment rules shape product access corridors. Stakeholders must monitor evolving reimbursement decisions by Japan's Chuikyo and China's NHSA, as these determinations will dictate whether CTC liquid biopsy shifts from private-pay oncology to standard-of-care coverage across the region's largest addressable patient pools.
Market Dynamics
Automated microfluidic isolation platforms are compressing turnaround times for CTC enumeration while China's NMPA breakthrough device designation accelerates commercialization timelines for novel assays. This dual pressure from technology maturation and regulatory streamlining is restructuring competitive positioning across the region's oncology laboratory networks.
Growth Catalysts
- Japan's PMDA accelerated approval pathways:Companion diagnostic designations slash registration timelines for CTC-based assays, enabling faster clinical adoption in precision oncology networks.
- Microfluidic enrichment technologies:Single-cell resolution capture preserves cell viability for downstream genomic analysis, expanding utility in biomarker discovery workflows.
- China's tier-one hospital clusters:Concentrated oncology patient volumes create scalable deployment environments for high-throughput CTC isolation systems.
Market Restraints
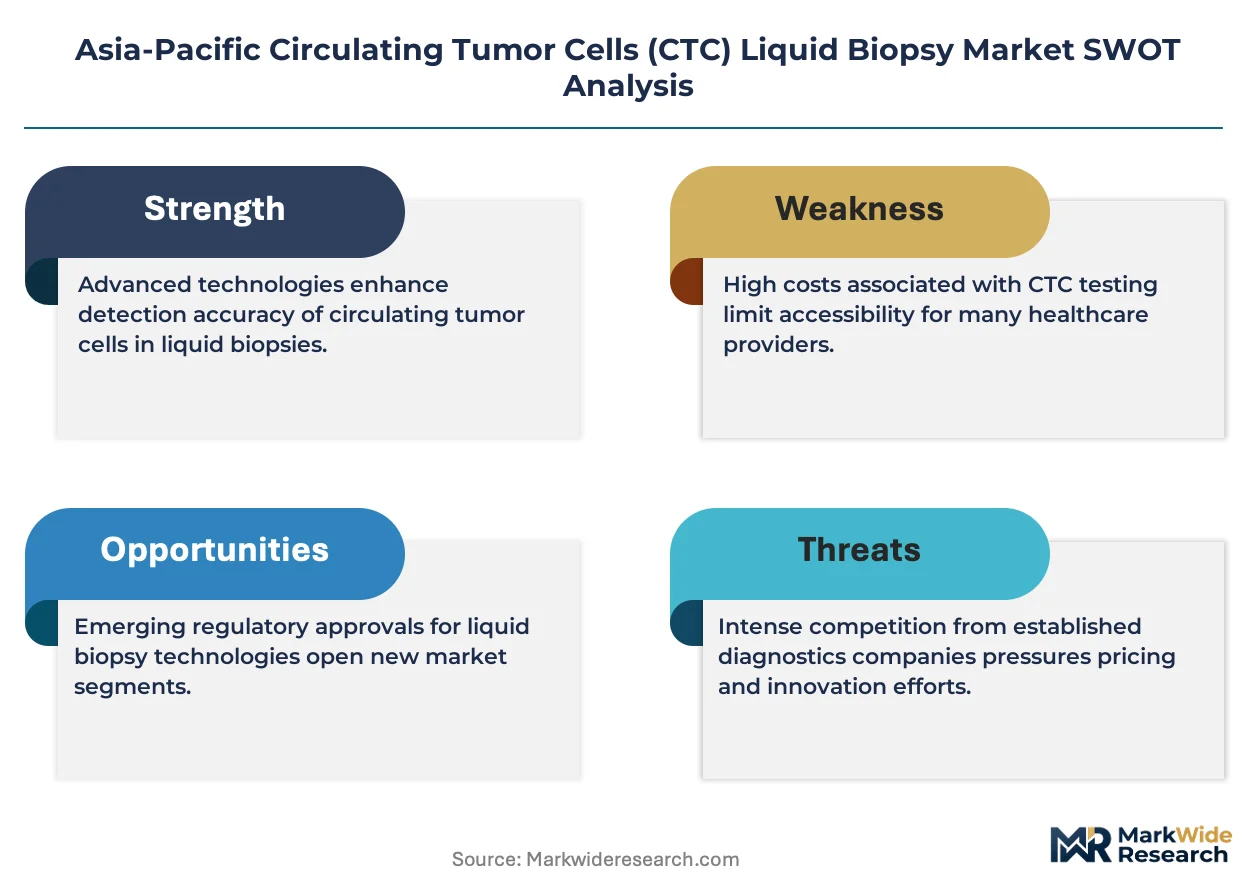
- Reimbursement uncertainty:Japan's Chuikyo and China's NHSA have not established standard-of-care coverage codes, forcing private-pay models that limit addressable patient pools.
- Input cost volatility:Rare-earth magnetic nanoparticles for immunomagnetic separation face supply concentration from Chinese processors, creating price instability for isolation consumables.
- Technical sensitivity limitations:Epithelial-mesenchymal transition causes antigen downregulation, producing false-negative CTC counts in late-stage metastatic monitoring applications.
Strategic Opportunities
- India's CDSCO regulatory modernization:Streamlined import licensing for innovative medical devices opens access corridors for automated CTC platforms in emerging oncology centers.
- Next-generation sequencing convergence:Integration of CTC isolation with comprehensive mutational profiling creates premium service tiers for pharmaceutical biomarker discovery partnerships.
- Australia's TGA-EU MDR alignment:Dual-market certification efficiencies enable Asia-Pacific manufacturers to leverage single regulatory filings for expanded geographic reach.
Industry Challenges
- Pre-analytical standardization gaps:Variable blood draw protocols and shipping conditions across hospital networks degrade CTC sample integrity, complicating multi-site clinical validation studies.
- Computational pathology talent scarcity:Shortage of bioinformaticians capable of integrating CTC genomic data with electronic health record systems slows workflow integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CellSearch, DEPArray, LiquidBiopsy, OncoCEE End User: Hospitals, Research Institutes, Clinical Laboratories, Oncology Centers Technology: Microfluidics, PCR, Next-Generation Sequencing, Imaging Application: Cancer Diagnosis, Treatment Monitoring, Prognosis Evaluation, Biomarker Discovery |
| Companies Covered | Guardant Health, Thermo Fisher Scientific, QIAGEN, Sysmex Corporation, F. Hoffmann-La Roche, Exact Sciences Corporation, Illumina, Natera, Biocept, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market Strategic Shifts
Digital pathology integration and artificial intelligence-assisted CTC classification are compressing diagnostic interpretation timelines while expanding the clinical utility of liquid biopsy workflows beyond enumeration to functional characterization.
Microfluidic chip-based isolation systems are consolidating market share from immunomagnetic separation methods as oncology laboratories prioritize cell viability preservation for downstream single-cell sequencing. Major hospital networks in Japan and China are adopting these platforms at accelerated procurement cycles. The technology shift is consolidating vendor relationships around integrated system suppliers capable of delivering both isolation hardware and analytical software.
China's NMPA innovative medical device designation pathway is compressing clinical trial requirements for breakthrough oncology diagnostics, enabling faster market entry for novel CTC enumeration assays. Japanese regulators are observing these streamlined procedures for potential PMDA pathway harmonization. Early-stage companies are responding by prioritizing China-first regulatory strategies for initial commercial validation.
Hospital procurement committees are unbundling after-sales service contracts from capital equipment purchases, forcing CTC platform vendors to compete on discrete service pricing rather than bundled maintenance agreements. This shift is most pronounced in China's provincial hospital systems where centralized purchasing authorities demand transparent cost separation. Vendors are responding with modular service tiers calibrated to laboratory throughput volumes.
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market Segmentation
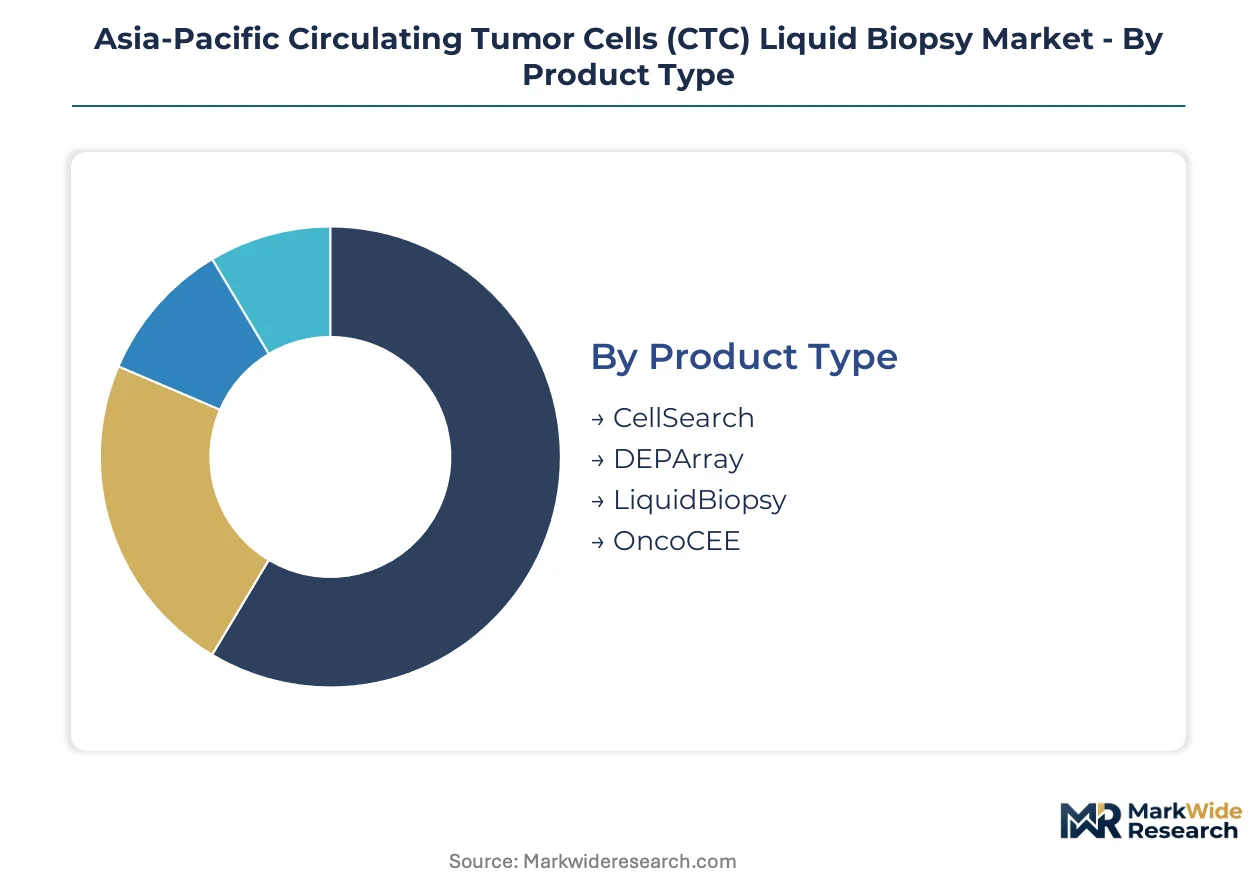
CTC liquid biopsy purchasing decisions in Asia-Pacific hinge on workflow integration depth, regulatory clearance status, and downstream analytical compatibility. Laboratory procurement committees evaluate platforms across four intersecting dimensions that determine clinical utility and reimbursement eligibility.
Product Type:
Capital allocation patterns favor systems with proven regulatory pathways and established service infrastructures.
- CellSearch:The first FDA-cleared CTC enumeration platform employs immunomagnetic separation targeting EpCAM-positive cells. China's tier-one oncology centers deploy CellSearch for standardized treatment monitoring where NMPA clearance streamlines procurement.
- DEPArray:Dielectrophoretic cell isolation enables single-cell recovery with 100% purity for downstream genomic analysis. Japan's precision oncology networks prioritize DEPArray for biomarker discovery workflows where cell viability preservation commands premium pricing.
- LiquidBiopsy:Proprietary microfluidic platforms from regional manufacturers compete on consumable cost structures.
- OncoCEE:China-developed systems leverage domestic supply chains for magnetic nanoparticle reagents.
CellSearch leads on scale; DEPArray leads on momentum.
End User:
Site-specific sample volumes and reimbursement access shape equipment specifications.
- Hospitals:Integrated oncology departments in China and Japan require high-throughput platforms processing 100+ samples daily. China's provincial hospital procurement authorities negotiate centralized contracts that favor automated systems with remote technical support capabilities.
- Clinical Laboratories:Independent reference labs in India's tier-one cities are adopting CTC isolation as a differentiated service offering. CDSCO import licensing reforms enable faster platform deployment for laboratories serving medical tourism corridors.
- Research Institutes:Academic medical centers prioritize single-cell resolution for translational oncology programs.
- Oncology Centers:Specialized cancer hospitals concentrate demand for treatment monitoring applications.
Hospitals dominate installed base; clinical laboratories are expanding most quickly.
Technology:
Platform selection trades sensitivity against analytical breadth and turnaround time.
- Microfluidics:Chip-based isolation preserves cell viability through gentle hydrodynamic capture without antibody dependence. Japan's PMDA breakthrough device designation accelerates approvals for microfluidic platforms that enable single-cell sequencing workflows.
- Next-Generation Sequencing:CTC-NGS integration delivers comprehensive mutational profiling from limited cell inputs. China's NMPA innovative device pathway prioritizes NGS-compatible platforms for companion diagnostic development.
- PCR:Targeted amplification supports rapid hotspot mutation detection in resource-constrained settings.
- Imaging:Fluorescence microscopy provides morphological validation for CTC enumeration.
Microfluidics commands current procurement; NGS integration shows steepest expansion trajectory.
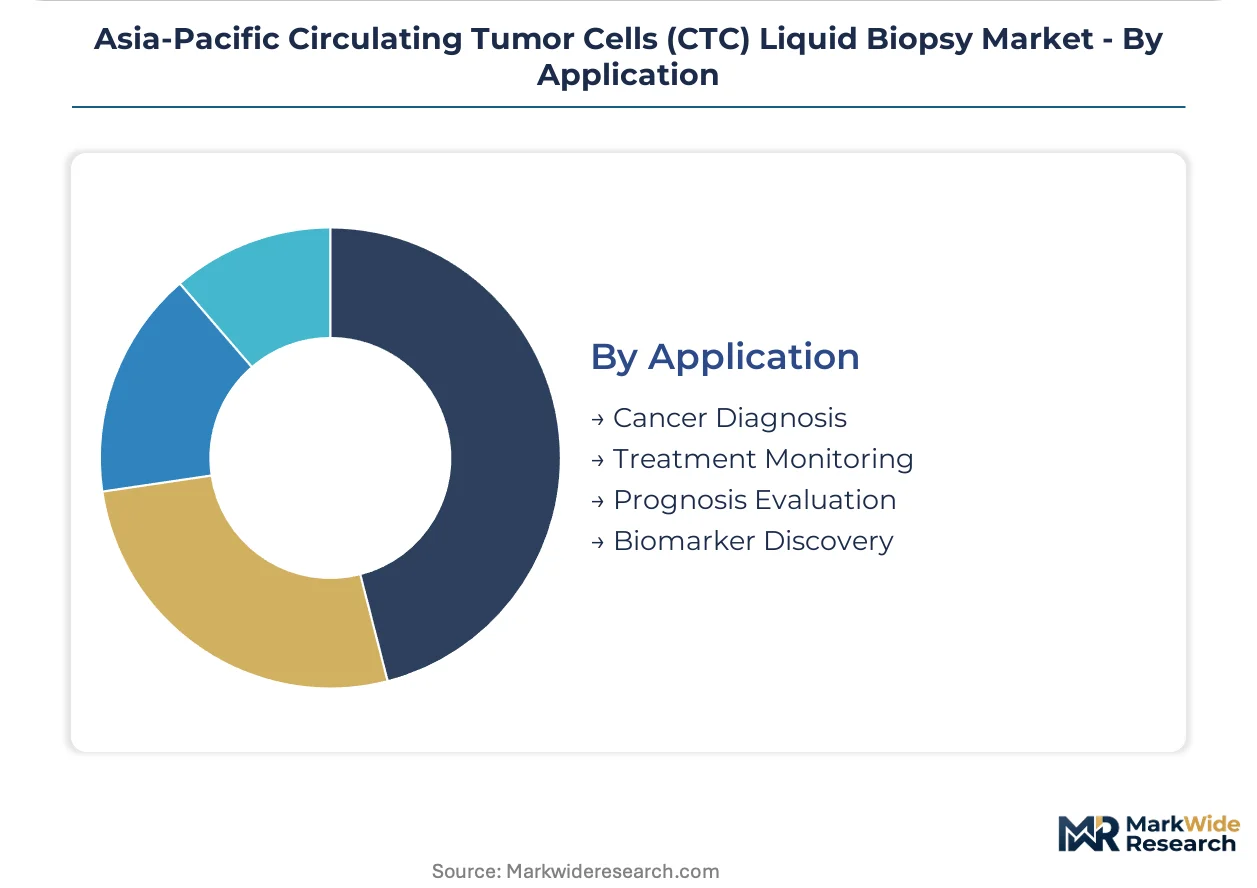
Application:
Reimbursement status and pharmaceutical partnership potential determine segment prioritization.
- Cancer Diagnosis:Initial CTC detection for suspected malignancy remains limited by sensitivity constraints in early-stage disease. Private-pay models dominate where Japan's Chuikyo and China's NHSA have not established coverage codes.
- Biomarker Discovery:Pharmaceutical partnerships for clinical trial patient stratification generate premium service revenues. Australia's TGA-aligned regulatory framework enables dual-market certification for biomarker discovery platforms serving Asia-Pacific and European trials.
- Treatment Monitoring:Serial CTC enumeration tracks therapeutic response in metastatic solid tumors.
- Prognosis Evaluation:Baseline CTC counts correlate with progression-free survival in breast, prostate, and colorectal cancers.
Treatment monitoring leads on scale; biomarker discovery leads on margin.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are accelerating platform deployment across Asia-Pacific as manufacturers exploit cost-of-compliance gaps between Japan's stringent PMDA pathways and China's streamlined NMPA breakthrough designations. Laboratory procurement committees in tier-one hospital clusters now weight regulatory velocity alongside analytical performance in capital allocation decisions.
China
Tier-one hospital clusters in Beijing, Shanghai, and Guangzhou are scaling automated CTC isolation platforms to manage surging oncology sample volumes. NMPA's innovative medical device designation compresses clinical trial requirements for breakthrough diagnostics. The Yangtze River Delta concentration of precision medicine institutes is driving biomarker discovery partnerships with domestic platform developers.
Japan
Precision oncology networks in Tokyo and Osaka prioritize single-cell resolution platforms for companion diagnostic development. PMDA accelerated approval pathways slash registration timelines for CTC-based assays aligned with targeted therapies. The Kanto region's integrated hospital-laboratory infrastructure anchors Sysmex Corporation's domestic service deployment.
India
Tier-one city reference laboratories are adopting CTC isolation as differentiated service offerings for medical tourism corridors. CDSCO import licensing reforms enable faster platform deployment for private oncology centers. Maharashtra's Mumbai-Pune corridor concentrates emerging diagnostic service capacity serving domestic and Gulf-state patient flows.
Australia
TGA alignment with EU MDR standards creates dual-market certification efficiencies for Asia-Pacific manufacturers targeting European trial networks. Sydney and Melbourne academic medical centers prioritize NGS-integrated CTC platforms for translational oncology programs. The country's pharmaceutical clinical trial concentration attracts biomarker discovery service investments.
South Korea
MFDS streamlined pathways for companion diagnostics are accelerating CTC assay commercialization for lung and gastric cancer monitoring. Seoul Capital Area hospital networks deploy high-throughput systems for national cancer screening program integration. The country's biotechnology manufacturing base supports consumable supply chain localization for regional platform vendors.
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue microfluidic automation and single-cell sequencing integration. The vendor base stratifies across three tiers: multinational diagnostics conglomerates with integrated hospital-laboratory relationships; regional platform specialists leveraging domestic regulatory pathways; and emerging microfluidic chip developers competing on consumable cost structures. Market structure favors players with combined hardware-software-service portfolios capable of meeting centralized procurement requirements. Consolidation pressure concentrates around automated isolation technologies and NGS compatibility capabilities.
Among United States-based molecular diagnostics developers, Guardant Health exemplifies the ctDNA-to-CTC platform extension archetype. QIAGEN and Thermo Fisher Scientific represent the sample preparation-to-sequencing workflow integration tier. Sysmex Corporation anchors the Asia-Pacific regional specialist position through deep hospital-laboratory infrastructure integration. These three entities occupy distinct competitive vectors: liquid biopsy platform expansion, multi-omic workflow convergence, and regional service density respectively.
| Leading Market Players |
|---|
| Guardant Health |
| Thermo Fisher Scientific |
| QIAGEN |
| Sysmex Corporation |
| F. Hoffmann-La Roche |
| Exact Sciences Corporation |
| Illumina |
| Natera |
| Biocept |
| Others |
Value Chain & Pricing Dynamics
Private-equity-backed diagnostic platform roll-ups in China and Japan are consolidating regional service networks while enforcing standardized consumable pricing across hospital procurement contracts. This ownership concentration tightens margin discipline for CTC isolation reagents and compresses distributor layers in tier-one oncology clusters.
Pricing Analysis
Distributor margin compression runs through China's provincial hospital procurement systems where centralized purchasing authorities demand transparent cost separation between capital equipment and after-sales service. Three-tier pricing structure across premium, standard, and economy levels stratifies by NMPA breakthrough device designation and single-cell sequencing compatibility. Pricing pressure stems from domestic Chinese manufacturers leveraging local magnetic nanoparticle supply chains to undercut imported consumables. Clinical laboratories in India's tier-one cities exhibit highest price sensitivity due to private-pay patient bases, while Japan's precision oncology networks tolerate premium tiers for PMDA-cleared companion diagnostic workflows.
Supply Chain Analysis
Refurbishment flows for microfluidic isolation chips remain underdeveloped across Asia-Pacific, creating stranded asset risk for capital-intensive CTC platforms nearing technical end-of-life. Rare-earth magnetic nanoparticle processing concentrates in China, with secondary sourcing from South Korea and Japan for high-purity reagent grades. Supply chain risk centers on single-source vulnerability for EpCAM antibody conjugates used in immunomagnetic separation workflows. Distribution runs through hospital procurement committees in China and integrated laboratory networks in Japan, with emerging direct-to-laboratory channels gaining traction in India's reference lab segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific CTC liquid biopsy market compounds steadily as regulatory streamlining across NMPA and PMDA pathways accelerates commercial validation timelines for novel assays.
For Market Incumbents: Anticipate margin erosion from domestic Chinese microfluidic chip manufacturers by deepening backward integration into magnetic nanoparticle production and securing exclusive service contracts with Japan's precision oncology networks. Threat substitution from ctDNA-based liquid biopsy platforms demands accelerated NGS integration roadmaps. Certification investment in Australia's TGA-EU MDR dual pathway creates defensive moat against regional competitors lacking harmonized regulatory capabilities. For New Entrants and Emerging Players: The price-point gap between premium single-cell sequencing platforms and economy-tier enumeration systems offers white-space entry for mid-market microfluidic automation. India's CDSCO-imported platform segment remains most penetrable due to medical tourism corridor expansion and limited domestic manufacturing. Go-to-market through clinical laboratory service partnerships bypasses capital-intensive hospital procurement cycles while building utilization proof points for eventual tier-one hospital adoption. For Investors and Strategic Acquirers: Multinational diagnostics conglomerates with ctDNA platform assets are the most active acquirer in this space, seeking CTC capabilities to complete multi-omic liquid biopsy portfolios. Long-term viability rests on reimbursement code establishment by Japan's Chuikyo and China's NHSA shifting private-pay oncology toward standard-of-care coverage. Acquisition target archetype: regional microfluidic chip developers with NMPA innovative device designation and established hospital-laboratory service relationships. Monitor PMDA pathway harmonization initiatives with NMPA breakthrough procedures as inflection signal for accelerated Japan market entry.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Breakthrough Device Designation | Compresses clinical trial requirements for novel CTC enumeration assays entering China's tier-one hospital clusters. |
| NGS Integration Partnership | Enables comprehensive mutational profiling from limited CTC inputs for pharmaceutical biomarker discovery contracts. |
| Microfluidic Chip Manufacturing Scale-Up | Reduces consumable cost structures against immunomagnetic separation methods through domestic Chinese supply chains. |
| Hospital System Service Contract | Locks in recurring revenue streams through unbundled after-sales agreements with China's provincial procurement authorities. |
| PMDA Companion Diagnostic Pathway | Accelerates registration timelines for CTC-based assays aligned with targeted therapies in Japan's precision oncology networks. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital laboratory directors, clinical pathology leads, regulatory affairs specialists at NMPA and PMDA, and procurement managers at China's provincial hospital authorities with secondary validation. Secondary sources encompassed NMPA innovative device filings, PMDA companion diagnostic registration databases, hospital procurement contract disclosures, and GPO pricing benchmarks. Bottom-up installed base modeling and top-down addressable patient pool estimates triangulated market sizing across the analysis window.
Historical reference periods anchored the projection horizon to pre-pandemic baseline utilization and post-regulatory-reform adoption curves. Segmentation dimensions modeled included technology platform type, end-user site category, application purpose, and regulatory clearance tier. CAGRs derived from year-over-year platform shipment trajectories and consumable pull-through rates, with NGS integration penetration and reimbursement code establishment timelines serving as key forecast sensitivity inputs.
Caveats apply where NMPA policy reversals on breakthrough device waivers or Chuikyo reimbursement denials for CTC-based monitoring could materially shift the outlook. Practitioners should monitor PMDA-NMPA regulatory harmonization progress and rare-earth export restriction developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market