
 Global Monocyte Activation Tests Market | 2026-2036
Global Monocyte Activation Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Global Monocyte Activation Tests Market Foresight
The EU In Vitro Diagnostic Regulation (IVDR) is shifting procurement standards across European transplant networks, forcing laboratories to revalidate legacy monocyte activation protocols. Lonza Group leverages its endotoxin detection heritage to anchor workflow integration for cell-therapy manufacturers. Charles River Laboratories competes through preclinical immunotoxicology services that bundle monocyte readouts into broader safety packages. Thermo Fisher Scientific dominates reagent supply chains with cryopreserved monocyte lots that reduce inter-assay variability.
Monocyte activation tests measure cytokine release and surface-marker upregulation in isolated CD14-positive monocytes exposed to stimulants such as lipopolysaccharide or alloantigens, typically quantified via flow cytometry or ELISA to assess innate immune competence. The primary commercial purpose is predicting adverse immunological events in transplant recipients and monitoring cytokine-release syndrome in CAR-T patients. Flow cytometry-based test types command premium pricing due to multiparametric readout capabilities, while multiplex assays represent the fastest-expanding category as laboratories consolidate cytokine panels onto single platforms. Diagnostic laboratories anchor volume demand, though pharmaceutical companies are deepening adoption for biologics safety testing.
The FDA's IVD guidance, the EU IVDR conformity assessment pathways, and WHO biological reference standards collectively determine which monocyte activation assays achieve clinical diagnostic claims versus research-use-only status. These frameworks shape reimbursement eligibility and cross-border kit commerce, particularly for luminescence and chemiluminescence technology platforms seeking CE marking or 510(k) clearance. Stakeholders must monitor evolving companion diagnostic linkages between monocyte activation biomarkers and specific immunotherapy drugs, as these pairings will determine which testing platforms capture long-term platform lock-in.
Market Dynamics
The EU IVDR conformity assessment timelines are compressing vendor certification windows while transplant centers simultaneously demand higher analytical specificity from monocyte activation protocols.
Growth Catalysts
- Alloantigen-specific protocols:Transplant immunology programs in Germany's Rhine-Main cluster are validating donor-specific monocyte response profiling to predict graft rejection earlier than conventional histocompatibility testing.
- FDA IVD guidance:The 2023 framework for cell-based therapy diagnostics is elevating analytical performance benchmarks, forcing assay standardization that improves cross-laboratory reproducibility and expands reimbursable indications.
- CAR-T safety monitoring:Cytokine-release syndrome surveillance in adoptive cell therapy manufacturing is embedding monocyte activation readouts into mandatory release criteria for commercial batches.
Market Restraints
- Cryopreserved monocyte lot variability:Primary cell sourcing from leukapheresis collections exhibits donor-dependent activation baselines that complicate longitudinal patient monitoring and increase control material costs.
- IVDR technical documentation burden:European notified body backlogs for class C in vitro diagnostics are extending time-to-market for new luminescence platforms by 18-24 months versus pre-2022 CE marking pathways.
- Flow cytometry infrastructure concentration:Multiparametric readout capabilities remain concentrated in academic medical centers and large reference laboratories, limiting community hospital access to premium test categories.
Strategic Opportunities
- India transplant network expansion:The country's national organ allocation system is formalizing immunological monitoring protocols, creating first-mover advantage for assay providers establishing local analytical validation partnerships.
- Multiplex cytokine consolidation:Single-platform ELISA alternatives are capturing volume from discrete ELISA workflows as laboratories seek to reduce technician hands-on time and plate consumption.
- Biologics immunotoxicology bundling:Preclinical safety packages for monoclonal antibody programs are incorporating monocyte activation endpoints alongside standard T-cell dependent antibody response studies.
Industry Challenges
- CD14-positive cell isolation standardization:Magnetic bead protocols versus plastic adherence methods yield divergent activation phenotypes that complicate multi-site clinical trial data pooling.
- Companion diagnostic co-development timelines:Synchronizing assay validation with immunotherapy drug approval pathways requires early engagement with FDA's Center for Devices and Radiological Health that many diagnostic developers lack experience navigating.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Monocyte Activation Tests Market |
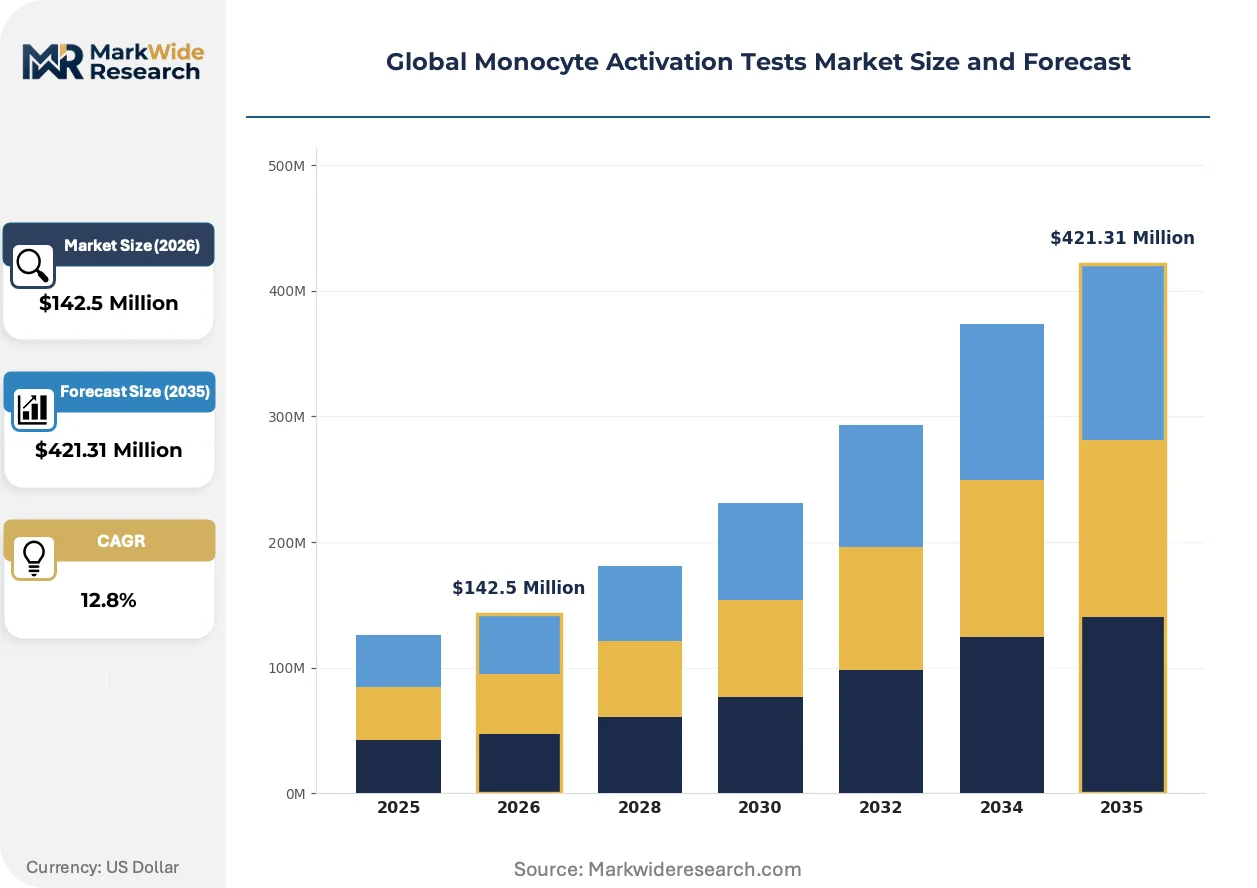
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $421.31 Million |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Flow Cytometry, ELISA, PCR Assays, Immunohistochemistry, Western Blot, Multiplex Assays Application Area: Infectious Disease Diagnosis, Immunotherapy Monitoring, Autoimmune Disease Research, Vaccine Development, Transplantation, Toxicology Screening End User: Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Blood Banks, Contract Research Organizations, Academic Centers Technology Platform: Microfluidics, Magnetic Bead-Based, Luminescence, Chemiluminescence, Electrochemical Immunoassays, Label-Free Detection |
| Companies Covered | Lonza Group, Charles River Laboratories, Merck KGaA, Thermo Fisher Scientific, Bio-Rad Laboratories, Eurofins Scientific, MAT BioTech, Sanquin, Hyglos GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Monocyte Activation Tests Market Shifts & Advancements
Workflow automation and regulatory harmonization are compressing the gap between research-grade monocyte assays and clinically validated diagnostic platforms.
Multiplex bead-based cytokine quantification is consolidating previously discrete ELISA workflows into single-run analytical panels. Large transplant centers in the United States are adopting these platforms to reduce sample volume requirements and technician processing time. The technology is consolidating competitive positioning around integrated instrument-reagent contracts that lock in consumable revenue streams.
The EU IVDR's 2022 implementation is mandating clinical performance studies for class C in vitro diagnostics that previously relied on analytical equivalence alone. Manufacturers must now generate prospective diagnostic accuracy data in intended-use populations, elevating development costs but improving payer confidence. Luminescence platforms seeking CE marking are most affected, with several vendors withdrawing legacy research-use-only kits rather than completing conformity assessments.
Contract research organizations are displacing in-house analytical development for pharmaceutical immunotoxicology programs. Biologics developers in Germany and Switzerland are outsourcing monocyte activation studies to specialized providers with established GLP certification and established relationships with regulatory agencies. This concentration is most visible in the Rhine-Main biotech corridor, where CRO capacity expansion is outpacing pharmaceutical internal hiring for immunology expertise.
Global Monocyte Activation Tests Market Segmentation
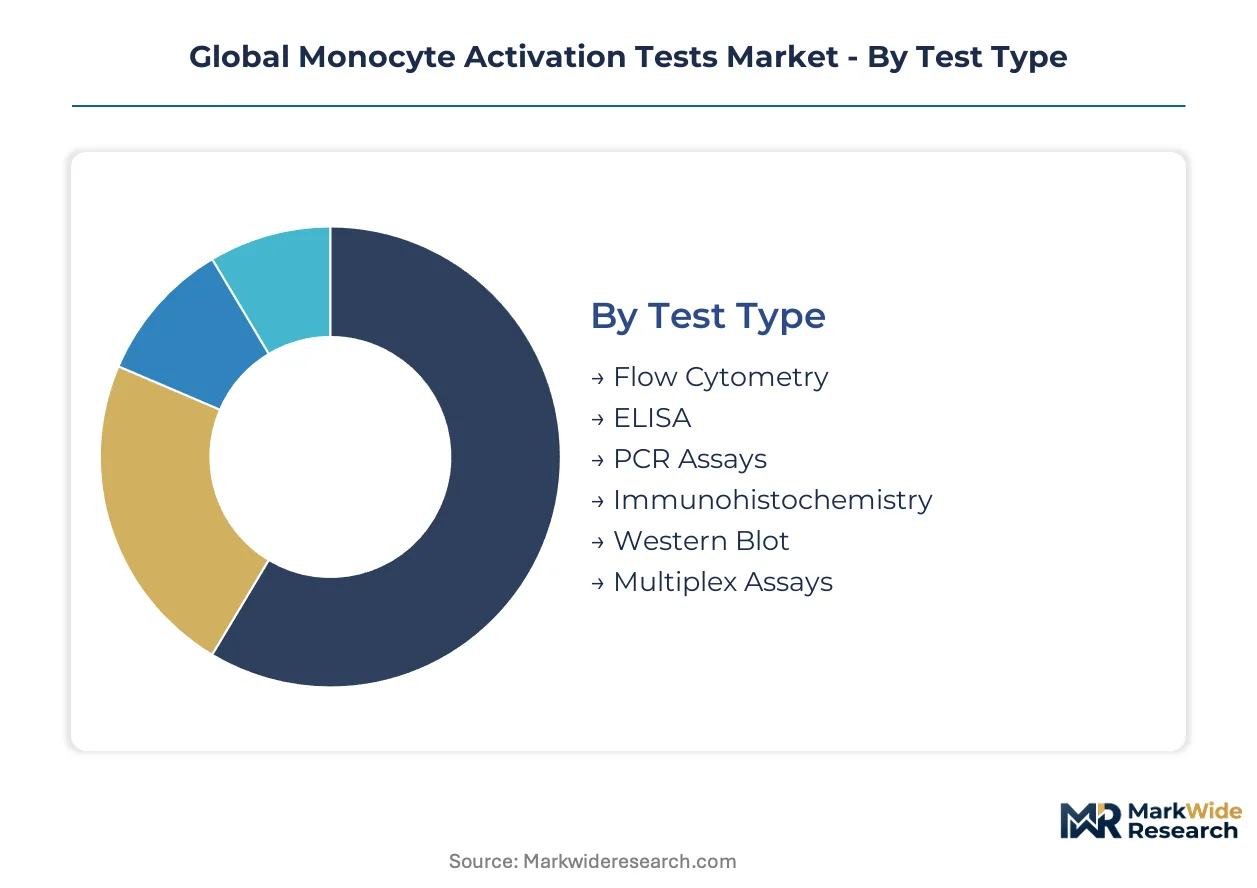
Test format selection in the monocyte activation market reflects divergent analytical requirements across transplant immunology and cell therapy manufacturing. Procurement patterns vary sharply by whether laboratories prioritize multiparametric resolution, throughput scalability, or regulatory submission compatibility.
Test Type:
Buyers in this category separate by their need for single-parameter precision versus multiplex panel consolidation and their available capital equipment infrastructure.
- Flow Cytometry:Multiparametric surface-marker quantification enables simultaneous CD14, CD80, CD86, and HLA-DR readouts from single-cell suspensions. Transplant centers in Germany's Rhine-Main cluster deploy these platforms for donor-specific monocyte response profiling to predict graft rejection earlier than conventional histocompatibility testing.
- Multiplex Assays:Bead-based cytokine panels consolidate IL-1β, IL-6, TNF-α, and IL-10 quantification into single-run workflows, reducing sample volume requirements and technician processing time. Large reference laboratories in the United States are adopting these platforms to capture volume migrating from discrete ELISA workflows.
- ELISA:Conventional enzyme-linked immunosorbent assays remain prevalent in resource-constrained settings for single-analyte cytokine detection with established protocol familiarity.
- PCR Assays:Nucleic acid amplification methods detect monocyte activation signatures through cytokine gene expression profiling.
- Immunohistochemistry:Tissue-section staining localizes activated monocyte populations within histological contexts.
- Western Blot:Protein electrophoresis confirms activation pathway signaling at research-grade specificity.
ELISA leads volumes today; multiplex assays are gaining share fastest.
Application Area:
Commercial maturity across use cases ranges from reimbursable diagnostic claims to preclinical research services with divergent pricing power.
- Transplantation:Alloantigen-specific monocyte response testing predicts acute cellular rejection and guides immunosuppression titration in solid organ and hematopoietic stem cell recipients. Germany's transplant networks are accelerating validation of donor-specific protocols under tightening EU IVDR procurement standards.
- Immunotherapy Monitoring:CAR-T manufacturing facilities embed monocyte activation readouts into mandatory batch release criteria for cytokine-release syndrome surveillance. The FDA's 2023 IVD guidance for cell-based therapy diagnostics is elevating analytical performance benchmarks for these assays.
- Infectious Disease Diagnosis:Pathogen-specific monocyte activation patterns distinguish bacterial from viral etiologies in sepsis workups.
- Autoimmune Disease Research:Dysregulated innate immune activation profiling supports mechanistic studies in rheumatoid arthritis and systemic lupus erythematosus.
- Vaccine Development:Adjuvant-induced monocyte responses predict immunogenicity in early-phase clinical trials.
- Toxicology Screening:Drug-induced immune activation monitoring integrates into preclinical safety packages for biologics development.
Transplantation commands the steepest pricing; immunotherapy monitoring shows the steepest expansion trajectory.
End User:
Customer concentration and purchasing sophistication vary by institutional scale and regulatory exposure.
- Diagnostic Laboratories:High-throughput service providers anchor commercial volume demand with established reimbursement pathways and quality management systems. These facilities prioritize workflow automation and regulatory pre-cleared assay formats.
- Contract Research Organizations:Specialized providers with GLP certification and established regulatory agency relationships are displacing in-house analytical development for pharmaceutical immunotoxicology programs in Germany and Switzerland.
- Pharmaceutical Companies:Biologics developers incorporate monocyte activation endpoints into preclinical safety packages and companion diagnostic co-development strategies.
- Research Institutes:Academic and government laboratories drive protocol innovation with flexible research-use-only procurement.
- Blood Banks:Leukapheresis collection facilities supply cryopreserved monocyte lots for assay manufacturing and quality control.
- Academic Centers:University-affiliated medical centers bridge clinical service and translational research with hybrid purchasing patterns.
Diagnostic laboratories dominate current revenue; contract research organizations are climbing the fastest.
Technology Platform:
Platform selection determines regulatory pathway complexity and capital equipment lock-in duration.
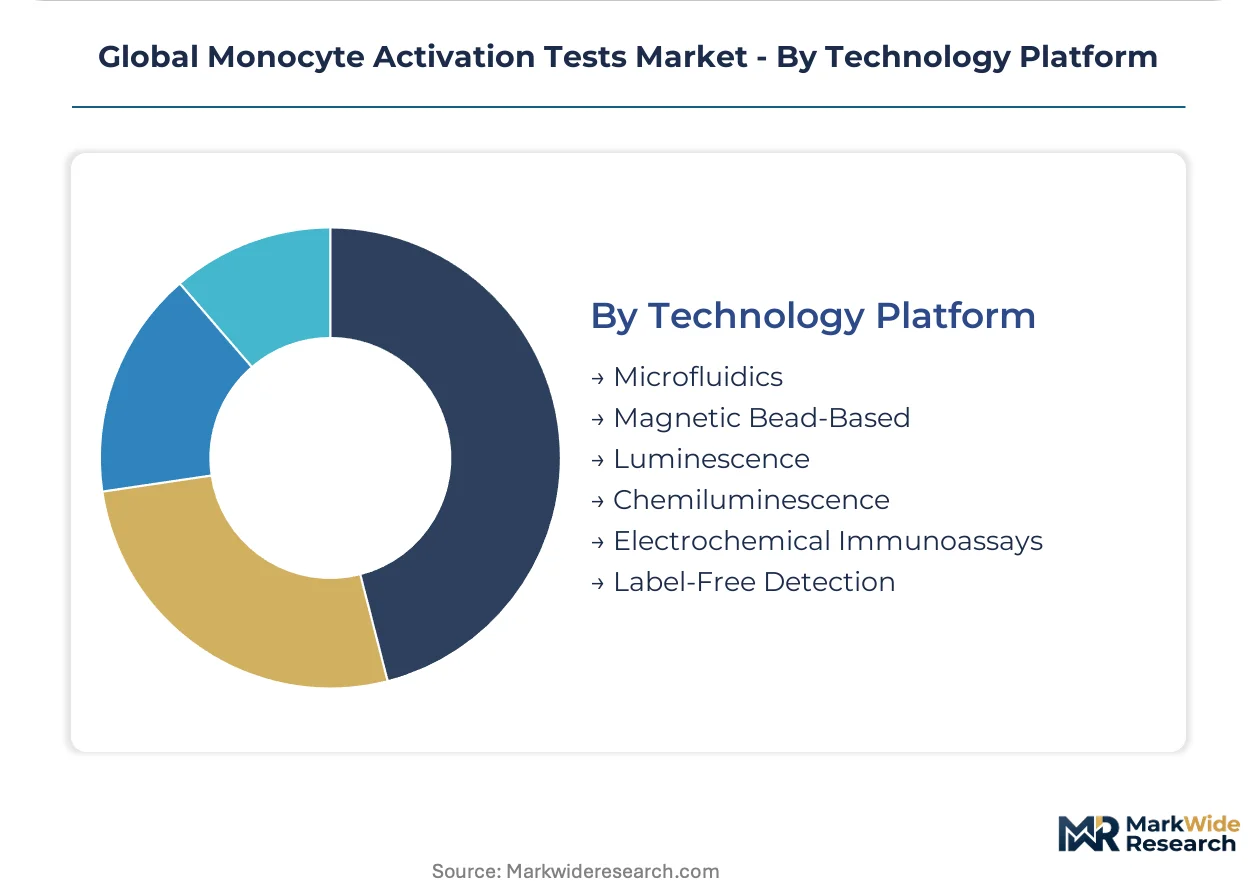
- Magnetic Bead-Based:CD14-positive cell isolation and cytokine capture workflows enable standardized, automatable protocols with reduced technician variability. Lonza Group leverages its endotoxin detection heritage to anchor workflow integration for cell-therapy manufacturers using these platforms.
- Luminescence:High-sensitivity signal amplification supports low-abundance cytokine detection with broad dynamic range. EU IVDR class C conformity assessments are extending time-to-market for these platforms by 18-24 months versus pre-2022 CE marking pathways.
- Chemiluminescence:Enzyme-catalyzed light emission provides quantitative readouts with established instrument footprints in clinical laboratories.
- Microfluidics:Miniaturized fluid handling reduces reagent consumption and sample volume requirements for point-of-care applications.
- Electrochemical Immunoassays:Direct electronic signal transduction eliminates optical detection components for simplified instrumentation.
- Label-Free Detection:Surface plasmon resonance and interferometric methods capture real-time binding kinetics without reporter conjugates.
Magnetic bead-based systems capture the largest installed base; microfluidics platforms are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The monocyte activation testing industry traces its commercial origins to European transplant immunology programs in the 1990s, where academic medical centers first standardized cytokine release protocols for graft monitoring. German and Swiss laboratories subsequently scaled these assays into industrial workflows for pharmaceutical safety testing.
United States
FDA's 2023 IVD guidance for cell-based therapy diagnostics is elevating analytical performance benchmarks for monocyte activation assays. Transplant centers in Boston and San Francisco are validating donor-specific response profiling to predict graft rejection earlier than conventional histocompatibility testing. The Greater Boston biotech corridor anchors commercial assay development for CAR-T safety monitoring applications.
Germany
The EU IVDR's 2022 implementation is mandating clinical performance studies for class C in vitro diagnostics that previously relied on analytical equivalence alone. The Rhine-Main biotech cluster coordinates multicenter transplant immunology trials with contract research organizations expanding capacity faster than pharmaceutical internal hiring. Frankfurt-area laboratories are accelerating validation of donor-specific monocyte response protocols under tightening procurement standards.
Switzerland
Swissmedic's alignment with EU IVDR conformity assessment pathways is compressing vendor certification windows for luminescence platforms. Basel-based pharmaceutical developers are outsourcing monocyte activation studies to specialized providers with established GLP certification. The country's contract research infrastructure concentrates immunotoxicology expertise that biologics developers increasingly access rather than building in-house.
India
The national organ allocation system is formalizing immunological monitoring protocols, creating first-mover advantage for assay providers establishing local analytical validation partnerships. CDSCO's evolving framework for in vitro diagnostic registration is shaping procurement standards across transplant networks. Mumbai and Delhi medical centers are piloting cryopreserved monocyte workflows to reduce inter-assay variability in longitudinal patient monitoring.
Japan
PMDA's biological product licensing requirements are embedding monocyte activation readouts into mandatory release criteria for cell therapy manufacturing. Tokyo and Osaka transplant centers are adopting multiplex cytokine panels to consolidate previously discrete ELISA workflows. The Kanto region's reference laboratories anchor volume demand for regulatory pre-cleared assay formats with established reimbursement pathways.
Global Monocyte Activation Tests Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and workflow integration capabilities. The vendor base separates into three tiers: multinational life science conglomerates with end-to-end reagent-instrument systems; specialized contract research organizations with GLP-certified immunotoxicology services; and regional diagnostic developers focused on single-parameter ELISA formats. Consolidation pressure is intensifying as EU IVDR documentation burdens favor scaled players with dedicated regulatory affairs infrastructure. Strategic moves center on backward integration into cryopreserved monocyte sourcing and technology licensing partnerships for multiplex platform standardization.
Among the multinational tier, Lonza Group and Thermo Fisher Scientific occupy positions anchored by endotoxin detection heritage and cryopreserved cell supply chains respectively. Charles River Laboratories exemplifies the CRO archetype with preclinical immunotoxicology bundling capabilities. MAT BioTech represents specialized diagnostic developers concentrating on transplant-specific assay formats. These three archetypes—conglomerate systems providers, outsourced analytical services, and focused assay specialists—collectively shape competitive dynamics as regulatory harmonization elevates barriers for smaller entrants.
| Leading Market Players |
|---|
| Lonza Group |
| Charles River Laboratories |
| Merck KGaA |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Eurofins Scientific |
| MAT BioTech |
| Sanquin |
| Hyglos GmbH |
| Others |
Supply & Pricing Matrix
Cryopreserved monocyte lot costs cascade through assay manufacturing tiers, with leukapheresis collection variability in the United States and Germany compressing margins at the standard reagent level while premium multiparametric platforms in transplant centers capture pricing power through regulatory certification depth.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates flow cytometry platforms with IVDR clinical claims from research-use-only ELISA kits and unvalidated legacy protocols. Price differentiation rests on analytical specificity certification and workflow automation bundling. Cost compression in standard reagent tiers is intensifying because donor-dependent activation baselines force redundant control material expenditure. Academic medical centers exhibit the sharpest price sensitivity, while CAR-T manufacturers prioritize performance reliability over unit economics.
Supply Chain Analysis
Domestic-content mandates under India's CDSCO registration framework are reshaping sourcing patterns for transplant network assay validation partnerships. Leukapheresis collection concentrates in the United States, Germany, and India, with cryopreservation logistics feeding from specialized blood banking infrastructure. Raw material dependencies center on Ficoll gradient media, magnetic bead separation kits, and recombinant cytokine standards. Single-source vulnerability permeates CD14-positive cell isolation reagent supply. Distribution runs through diagnostic reagent distributors and direct instrument-reagent contracts with large reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU IVDR conformity assessment pathways are filtering procurement toward analytically validated platforms with clinical performance documentation.
For Market Incumbents: To counter notified body backlogs extending CE marking timelines, Lonza Group and Thermo Fisher Scientific should deepen backward integration into cryopreserved monocyte sourcing and accelerate multiplex platform standardization partnerships. Certification investment in class C IVD clinical performance studies anchors pricing power against research-use-only competitors. For New Entrants and Emerging Players: Contract research organizations in the Rhine-Main biotech corridor offer the most penetrable channel partner type for assay providers lacking established regulatory agency relationships. India's national organ allocation system formalization presents white-space opportunity for local analytical validation partnerships. A go-to-market angle bundling monocyte activation endpoints with broader immunotoxicology service packages bypasses direct instrument-reagent contract competition. For Investors and Strategic Acquirers: Roll-up economics work for specialized CROs with GLP certification because pharmaceutical outsourcing of immunotoxicology programs is displacing in-house analytical development faster than capacity expansion. Long-term viability favors platforms with companion diagnostic co-development experience. The signal to watch is FDA Center for Devices and Radiological Health engagement depth among diagnostic developers.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Clinical Performance Study Completion | CE marking for class C diagnostics under EU IVDR mandates prospective accuracy data in intended-use populations. |
| Cryopreserved Monocyte Sourcing Integration | Captive supply of leukapheresis-derived CD14-positive cells reduces inter-assay variability and control material costs. |
| Multiplex Cytokine Platform Standardization | Single-run consolidation of IL-1β, IL-6, TNF-α, and IL-10 quantification captures volume migrating from discrete ELISA workflows. |
| Companion Diagnostic Co-Development | Early FDA CDRH engagement synchronizes assay validation with immunotherapy drug approval pathways. |
| India Transplant Network Partnership | CDSCO registration framework and national organ allocation formalization create first-mover advantage for local validation. |
Research Methodology
Bottom-up diagnostic laboratory and pharmaceutical company modeling reconciled against top-down reagent supply chain tracking forms the analytical core of this study. Primary interviews with transplant immunologists, cell therapy manufacturing quality leads, diagnostic laboratory directors, and contract research organization executives combined with secondary validation from FDA 510(k) filings, EUDAMED device registrations, ClinicalTrials.gov intervention records, and EU IVDR notified body guidance documents. Top-down trade data on cryopreserved cell imports and instrument-reagent contract disclosures triangulate against bottom-up facility-level adoption estimates.
Input-output matrices map test format adoption, application area penetration, and technology platform deployment across the projection horizon. Segmentation dimensions modeled include test type, application area, end user, and technology platform, with regional regulatory cluster and reimbursement pathway status as cross-cutting variables. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns and regulatory milestone timing. Industry-specific forecast inputs incorporate EU IVDR conformity assessment completion rates and CAR-T manufacturing facility expansion pipelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on cell-based therapy diagnostics and CDSCO IVD registration framework maturation. Forecasts reflect documented assumptions regarding notified body capacity expansion and transplant center consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Herpes Marker Testing Market