
 Clarified Butter Market | 2026-2036
Clarified Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Clarified Butter Market Intelligence
The shift toward grass-fed and organic sourcing is unwinding traditional dairy supply chain dependencies, creating new value tiers. This movement allows niche producers to challenge large-scale dairy operations. Amul (GCMMF) leverages its vast cooperative network to sustain market leadership in India. In contrast, Organic Valley differentiates with a portfolio strictly focused on certified organic clarified butter for the North American and European consumer base.
Clarified butter is pure milk fat, produced by heating butter to remove water and milk solids. This process yields a product with a high smoke point, typically above 250°C (482°F), making it ideal for high-heat cooking. The Ghee product type, a variant with a distinct nutty flavor from browned milk solids, commands significant market share. Demand from the food service end-user segment is accelerating, favoring bulk packaging formats like tubs and large plastic containers.
Product quality and labeling are governed by food safety authorities such as the FDA in the United States and the FSSAI in India. European food standards, overseen by the EFSA, also influence import requirements regarding purity and allowable residues. Future success depends on aligning product attributes with regional culinary traditions while ensuring supply chain traceability.
Market Dynamics
The central dynamic in the clarified butter market is the tension between traditional, volume-driven production and the rising demand for products with verifiable sourcing credentials. Consumer and food service preferences for grass-fed and organic variants are creating new value tiers, compelling a re-evaluation of dairy supply chain dependencies.
Growth Catalysts
- Food Service Expansion:The professional food service sector's adoption of clarified butter is increasing due to its high smoke point, making it a preferred fat for high-heat cooking techniques in restaurants and commercial kitchens.
- South Asian Culinary Tradition:Deep-rooted consumption patterns in South Asia, particularly India, anchor baseline demand, where ghee is integral to daily cuisine, religious practices, and Ayurvedic health systems.
- Clean Label Movement:Consumer demand for natural foods with simple, recognizable ingredients favors clarified butter's purity, a trend reinforced by food labeling regulations from authorities like the FDA in the United States.
Market Restraints
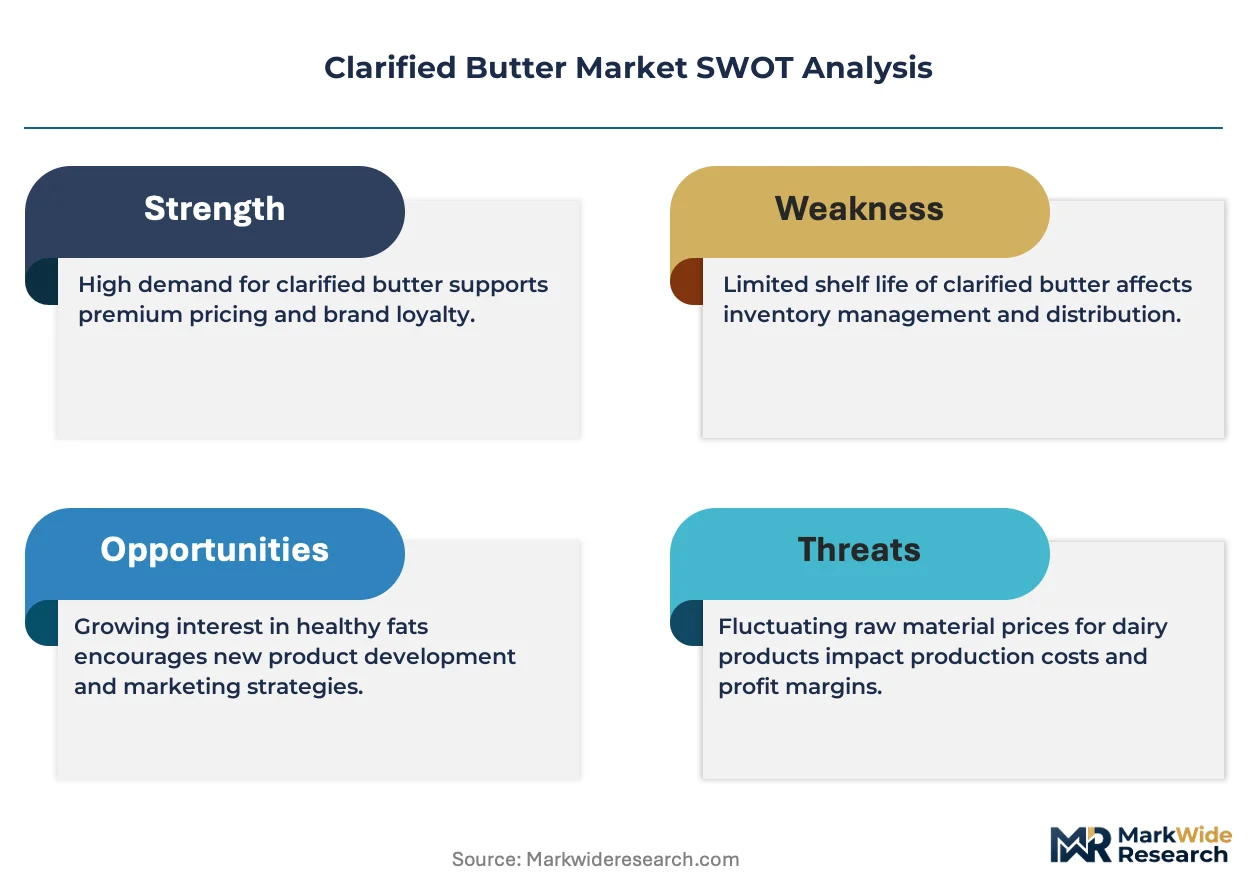
- Raw Material Volatility:Price and availability fluctuations in raw milk, the primary input, create significant cost instability for producers, directly impacting final product margins and consumer-facing prices.
- Competition from Cooking Oils:A diverse market of high-smoke-point cooking oils, including avocado, coconut, and sunflower oil, presents a persistent substitution threat, particularly in Western markets with less traditional attachment to ghee.
- Limited Organic Dairy Supply:The constrained supply and higher cost of certified organic milk acts as a bottleneck for the premium organic segment, limiting scalability for producers targeting this high-growth niche.
Strategic Opportunities
- European Market Penetration:Expanding distribution into European health-food and gourmet retail channels by aligning with EFSA organic and purity standards presents a significant opportunity beyond traditional consumer bases.
- Nutraceutical Formulations:Incorporating clarified butter into nutraceuticals and dietary supplements opens a new B2B sales channel, leveraging its profile as a healthy fat and a carrier for fat-soluble vitamins.
- Flavored and Infused Variants:The development of value-added products, such as clarified butter infused with herbs, spices, or garlic, caters to home cooks and chefs seeking convenient, differentiated flavor profiles.
Industry Challenges
- Adulteration and Counterfeiting:Combating the fraudulent practice of adulterating clarified butter with cheaper vegetable oils or animal fats remains a critical operational challenge, requiring rigorous testing to meet FSSAI and FDA purity standards.
- Cold Chain Logistics:Managing a reliable and cost-effective cold chain for transporting raw butter to processing facilities adds complexity and expense, especially for producers sourcing from geographically dispersed dairy farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clarified Butter Market |
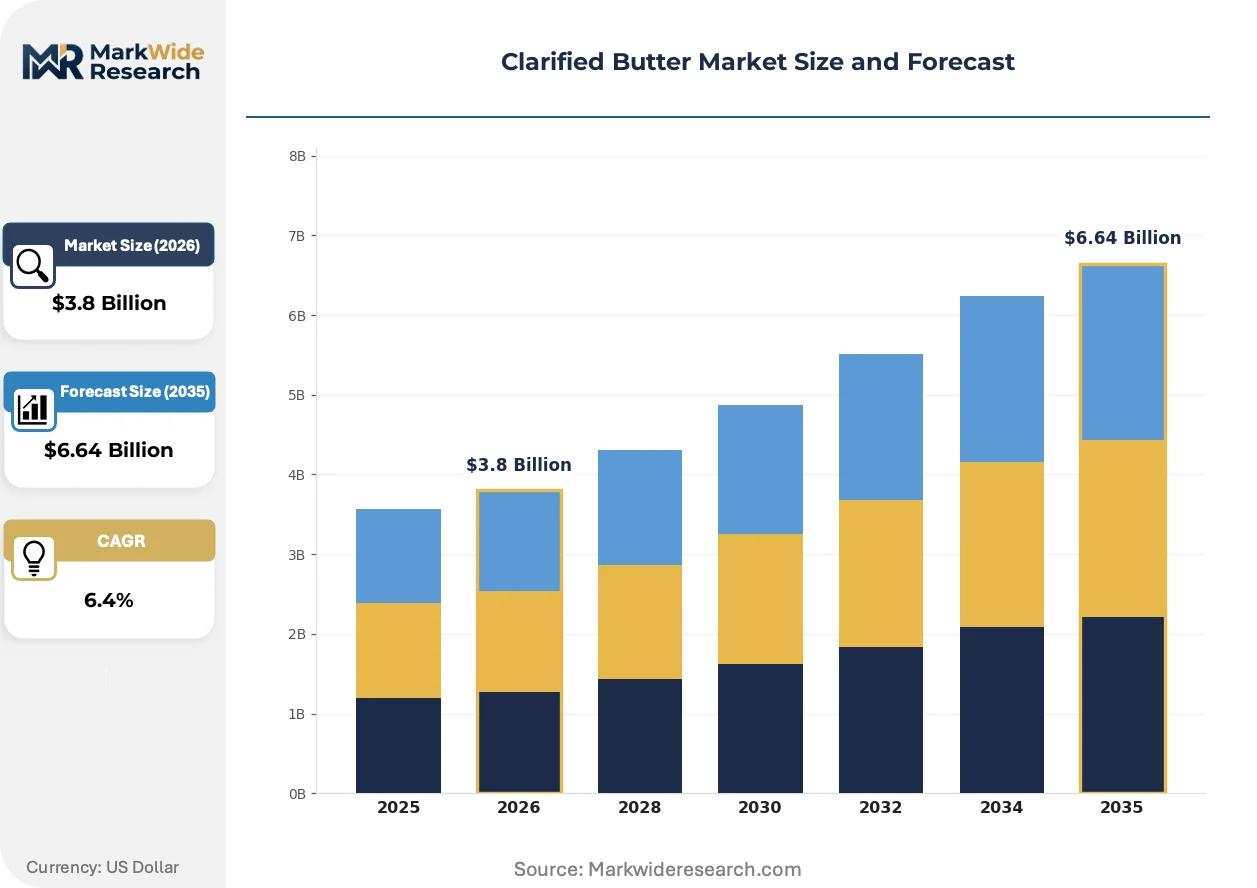
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsalted, Salted, Organic, Ghee End User: Food Service, Retail, Home Cooking, Bakery Packaging Type: Glass Jars, Plastic Containers, Tubs, Pouches Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Wholesale |
| Companies Covered | Nestlé, Patanjali Ayurved Limited, Amul (GCMMF), Arla Foods, Organic Valley, Mother Dairy, Britannia Industries, Almarai, Fonterra Co-operative Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clarified Butter Market Strategic Shifts & Innovations
Product evolution is increasingly defined by the ability to prove authenticity and purity through verifiable sourcing. This focus on traceability intersects with processing innovations and shifting consumer health priorities, fundamentally altering how value is created and communicated in the market.
Advanced filtration techniques, including membrane filtration, enable more precise separation of milk fat from water and milk solids at lower temperatures than traditional heating methods. Niche and premium-focused producers are adopting these processes to craft products with distinct textures and milder flavor profiles. This technological precision is fragmenting the market by allowing for a wider variety of specialized, high-value clarified butter products beyond conventional ghee.
India's FSSAI has intensified enforcement of its quality standards and AGMARK certification for ghee to combat product adulteration. This regulatory pressure is forcing producers to invest in sophisticated laboratory testing, quality control systems, and transparent supply chain documentation. The formal, organized sector benefits from these stricter rules by gaining consumer trust, while smaller, unorganized players face significant compliance hurdles.
A pronounced consumer shift toward wellness-oriented diets is elevating demand for products with specific sourcing claims, such as "grass-fed" or "from A2 milk." This behavior disrupts traditional purchasing decisions based on brand loyalty or price, steering buyers toward products whose labels communicate superior nutritional or ethical attributes. This trend is most visible in North American and European retail channels, driving growth in the premium and organic segments.
Clarified Butter Market Segmentation
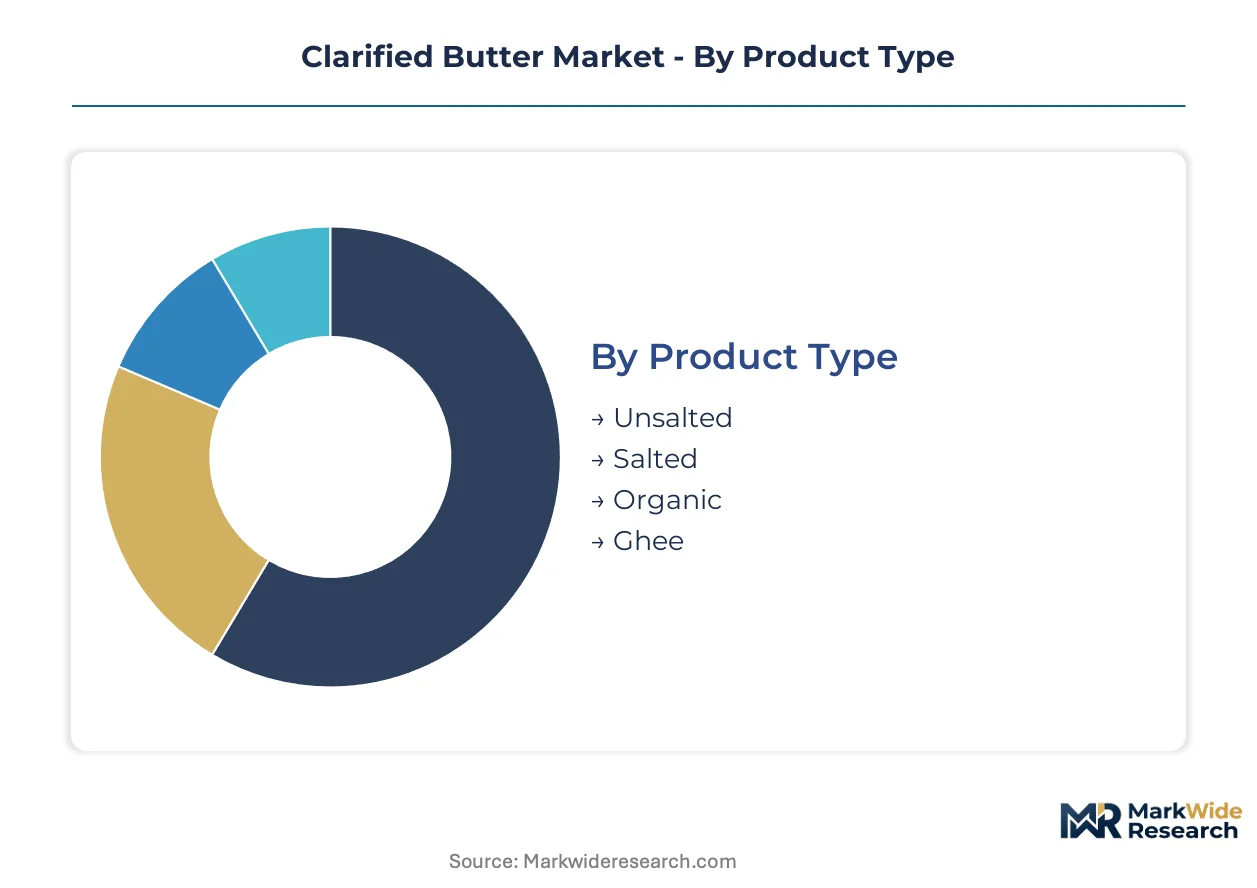
Understanding the clarified butter market through segmentation clarifies how diverse product forms and end-user needs shape its commercial landscape. This analysis illuminates specific demand drivers and supply chain configurations across various categories. Distinct segments reveal varying growth trajectories and competitive dynamics for producers.
Product Type:
The channel-mix for clarified butter is heavily influenced by specific product types, determining how each variant reaches its intended consumer or commercial buyer.
- Ghee:This traditional Indian product is pure milk fat, often prepared to have a distinct nutty flavor from browned milk solids. Demand concentrates significantly within South Asian markets, particularly India, driven by its integral role in daily cuisine and religious practices.
- Organic:Organic clarified butter is produced from the milk of cows raised on certified organic feed and pasture, free from synthetic pesticides or hormones. This premium segment sees demand concentrating in North American and European retail channels, driven by wellness-oriented consumer preferences for traceable sourcing.
- Unsalted:This variant of clarified butter offers a neutral flavor profile, making it versatile for various culinary applications.
- Salted:Salted clarified butter provides an enhanced flavor for cooking and baking, appealing to specific regional taste preferences.
Ghee dominates the installed base, reflecting its deep cultural roots and widespread use. Organic is where expansion concentrates, driven by evolving consumer health priorities in Western markets.
End User:
End-user segments dictate the application volume and specific product attributes required, from bulk formats to specialized culinary needs.
- Food Service:This segment comprises restaurants, hotels, and commercial kitchens utilizing clarified butter for high-heat cooking due to its high smoke point. Demand accelerates for bulk packaging formats like tubs and large plastic containers, supporting efficient kitchen operations.
- Home Cooking:Individual consumers use clarified butter for daily culinary needs, baking, and traditional recipes, especially in South Asian households. This segment values convenient packaging and consistent quality for everyday use.
- Retail:Retail channels serve individual consumers through supermarkets, hypermarkets, and convenience stores, offering various product sizes.
- Bakery:Bakeries employ clarified butter for its rich flavor and stable properties in pastries, breads, and other baked goods.
The food service sector shows the steepest expansion trajectory, while home cooking maintains a consistent, substantial baseline demand.
Packaging Type:
Packaging types often reflect the intended customer type and cost tier, influencing both shelf appeal and logistical efficiency.
- Tubs:These larger plastic containers are favored by the food service industry and bulk consumers for their practicality and cost-effectiveness. Their design supports easy scooping and storage in commercial kitchens.
- Glass Jars:Glass jars typically target premium retail segments and health-conscious consumers, offering perceived quality and preserving product integrity. They are common in European and North American specialty stores.
- Plastic Containers:These versatile containers cater to a broad consumer base, balancing durability and affordability for everyday use.
- Pouches:Pouches offer a lightweight and flexible packaging solution, often used for smaller portions or convenient dispensing.
Tubs hold a substantial share in commercial applications, whereas glass jars represent a segment where premiumization and branding are driving innovation.
Distribution Channel:
Supply concentration patterns reveal how clarified butter products are distributed, ranging from broad consumer access to specialized market niches.
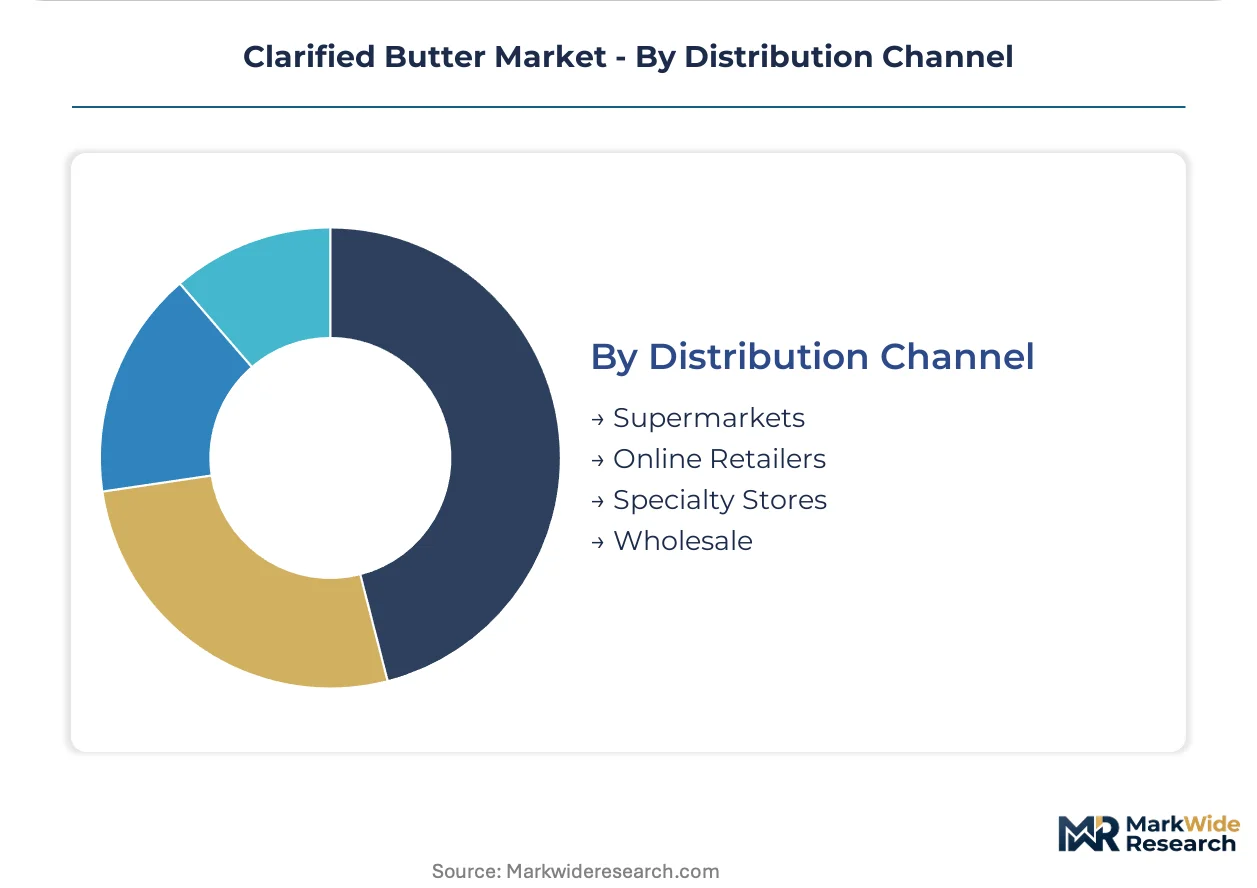
- Supermarkets:These large retail chains provide broad consumer access, offering a wide range of clarified butter brands and product types. They serve as a primary channel for household consumption across diverse geographies.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales, offering convenience and access to niche organic or specialty clarified butter products. This channel is gaining share fastest in North American and European markets.
- Specialty Stores:These outlets cater to specific dietary needs or gourmet preferences, stocking premium and organic clarified butter variants.
- Wholesale:Wholesale channels supply bulk clarified butter to food service establishments, bakeries, and industrial food manufacturers.
Supermarkets offer unparalleled market reach, while wholesale channels ensure efficient supply to industrial and food service end-users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's traditional ghee exports meet growing demand in North America and Europe, shaping international trade flows for clarified butter. This trade-flow corridor underscores the product's cultural significance in South Asia and its rising appeal in Western markets. Regional supply chain configurations are adapting to these evolving international demands.
India
Deep-rooted consumption patterns anchor baseline demand for clarified butter, integral to daily cuisine and religious practices. India's FSSAI has intensified enforcement of quality standards and AGMARK certification to combat adulteration. Gujarat, a major dairy state, sees significant investment in organized sector ghee production facilities to meet national consumption.
United States
Wellness-oriented diets, the clean label movement, and premium organic segments drive demand for clarified butter. The FDA's food labeling regulations reinforce consumer preferences for natural products with simple ingredients. California's health-food retail channels increasingly stock specialized, grass-fed clarified butter variants for health-conscious buyers.
Germany
European health-food and gourmet retail channels show rising interest in organic clarified butter products. EFSA organic and purity standards influence import requirements for all dairy items entering the European Union. Bavaria, a prominent dairy region, develops niche clarified butter products for both regional consumption and export markets.
United Arab Emirates
Traditional culinary uses and a growing expatriate population support consistent clarified butter consumption. The SFDA sets food safety standards for imported and locally produced dairy items to ensure product quality. Dubai's extensive food service sector utilizes bulk clarified butter for its diverse hospitality industry and restaurant operations.
Clarified Butter Market Key Industry Players
Listed leaders compete with private specialists across product innovation and supply chain reach within the clarified butter market. The market structure exhibits a tiered consolidation, with large dairy cooperatives operating alongside niche organic producers. Strategic archetypes include volume-driven commodity suppliers and premium-focused craft brands. Companies engage in portfolio diversification and geographic expansion to secure market share in specific consumer segments.
Within the volume-driven tier, Amul (GCMMF) represents a cooperative model anchoring market leadership in India through its vast network. Organic Valley exemplifies the premium segment, focusing strictly on certified organic clarified butter for North American and European consumers. Nestlé, a global food conglomerate, occupies a position leveraging broad distribution channels and brand recognition across diverse product categories. These entities demonstrate varied approaches to market penetration and value capture.
| Leading Market Players |
|---|
| Nestlé |
| Patanjali Ayurved Limited |
| Amul (GCMMF) |
| Arla Foods |
| Organic Valley |
| Mother Dairy |
| Britannia Industries |
| Almarai |
| Fonterra Co-operative Group |
Cost & Logistics Intelligence
Large-scale dairy processing capacity in India drives significant volume, influencing global price floors for commodity clarified butter and solidifying supply concentration. This scale economy allows major players to maintain competitive pricing for traditional ghee variants.
Pricing Analysis
The traditional heating method for clarified butter establishes a baseline price point, while advanced filtration techniques command a premium due to distinct textures and milder flavors. Commodity spot pricing dominates for bulk ghee, alongside contract-based long-term offtake for organic and premium segments. Price differentiation stems from quality grade, sourcing claims like grass-fed or A2 milk, and processing method innovation. Pricing pressure stems from raw material volatility in milk prices and competition from alternative high-smoke-point cooking oils. Food service and home cooking in South Asia exhibit high price sensitivity, while North American and European health-food consumers are less sensitive for certified organic variants.
Supply Chain Analysis
Managing raw butter inventory and lead times from dispersed dairy farms adds complexity to the clarified butter supply chain, particularly for premium segments. Geographic supply concentration centers in India, New Zealand, and Ireland. Raw milk constitutes the primary input dependency, alongside specialized packaging materials such as glass jars for premium products. Cold chain logistics for raw butter transport represents a structural supply chain risk. Distribution runs primarily through supermarkets for retail and wholesale channels for food service and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clarified butter market is experiencing a buyer-power shift as health-conscious consumers in North America and Europe increasingly fragment demand towards niche organic and grass-fed variants.
For Market Incumbents: Shield market share from niche organic producers by investing in AGMARK certification and advanced filtration techniques. Amul can leverage its vast cooperative network to offer certified organic lines, mitigating competition from smaller, premium brands. Control over dairy farm sourcing ensures consistent raw milk quality, addressing adulteration concerns. This strategy counters the threat of premium segment erosion.
For New Entrants and Emerging Players: EFSA organic certification fast-tracks entry into European health-food retail channels for specialized clarified butter. Target underpenetrated nutraceutical formulations by positioning clarified butter as a healthy fat carrier for fat-soluble vitamins. Focus on direct-to-consumer online platforms with transparent sourcing narratives to build trust among wellness-oriented buyers. This approach captures high-value niches.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among premium organic clarified butter brands with strong direct-to-consumer channels. Long-term viability rests with brands demonstrating verifiable sourcing credentials and robust quality control, appealing to evolving consumer health priorities. Target acquisition profiles include mid-sized producers specializing in grass-fed or A2 milk variants with established North American or European distribution. The signal to watch is the sustained growth of the European health-food retail segment.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Filtration Technology | Improves product purity and allows for distinct textures, catering to premium segment demand. |
| Expand AGMARK/EFSA Certification | Builds consumer trust and enables market access to regulated international markets like India and Europe. |
| Develop Nutraceutical Partnerships | Opens new B2B sales channels by integrating clarified butter into health supplements. |
| Diversify Packaging Formats | Caters to varied end-user needs, from bulk food service tubs to premium glass jars for retail. |
| Strengthen Cold Chain Logistics | Reduces raw material spoilage and ensures quality control from farm to processing facility. |
Research Approach
A spread of perspectives from dairy farm owners, food service procurement managers, retail category buyers, and FSSAI/FDA regulatory officials converged on the working assumptions for clarified butter market dynamics. Primary interviews with industry stakeholders were complemented by secondary validation from customs data, dairy cooperative reports, and food safety authority publications. This approach ensured robust bottom-up and top-down triangulation of market intelligence.
Product type, end-user segment, packaging format, distribution channel, and regional culinary traditions constituted the segmentation dimensions modeled across the analysis window. Compound annual growth rates were derived from historical trends and projected shifts in consumer preferences and regulatory landscapes. Key forecast inputs included raw milk price projections and anticipated expansion of the professional food service sector.
Decision-makers should treat outputs as directional under base assumptions regarding raw milk supply stability and regulatory enforcement; material deviation would warrant model refresh. Forecasts reflect assumptions about sustained demand from South Asian markets and continued growth in Western premium segments. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Vegan Cheese Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
North America Dairy Alternative Market