
 North America Dairy Alternative Market | 2026-2036
North America Dairy Alternative Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dairy Alternative Market Analytics
Plant-based food technologist talent is collapsing across the Great Lakes and Pacific Coast, constraining formulation innovation just as brands race to improve taste parity with conventional dairy. Danone SA leverages its established refrigerated distribution network to sustain shelf presence in conventional grocery. Califia Farms LLC anchors its growth in barista-specific oat and almond formulations that dominate cafe channel placements. SunOpta Inc. competes through integrated ingredient sourcing and contract manufacturing services for private-label entrants.
North America dairy alternatives comprise formulated beverages derived from oilseeds, grains, or nuts processed through enzymatic treatment, homogenization, and ultra-high temperature pasteurization to achieve protein dispersion, emulsion stability, and shelf-safe fluidity suitable for direct consumption or culinary application. Oat Milk commands the fastest expansion due to its neutral flavor profile and lower environmental water footprint compared to almond cultivation. Almond Milk retains the largest volume position but faces margin compression from California irrigation constraints and pollinator supply volatility. Foodservice channel demand through cafes and restaurants is outpacing household retail velocity as operators standardize plant-based milk as a default offering.
The U.S. FDA governs allergen labeling and nutrient content claims for plant-based beverages, while Health Canada mandates bilingual packaging and dairy alternative nomenclature under its food regulations. The USDA Organic certification and Non-GMO Project verification create tiered market access thresholds that filter smaller entrants from mainstream retail placement. Stakeholders must monitor evolving protein fortification standards and state-level environmental disclosure mandates that will reshape formulation investments and supplier qualification criteria.
Market Dynamics
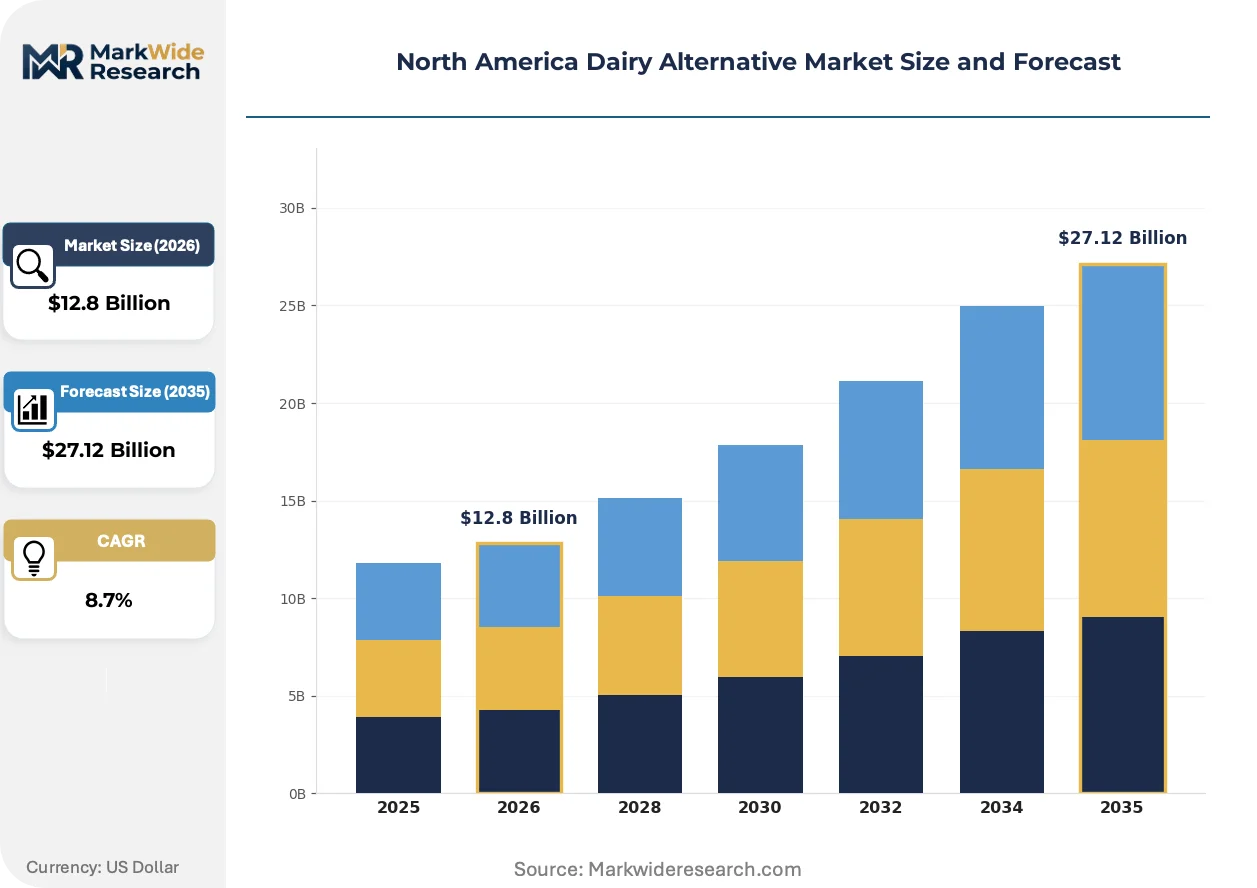
Enzymatic protein extraction and precision fermentation are compressing formulation timelines while California's water scarcity intensifies almond supply volatility, forcing brands to relocate sourcing and reformulate around oat and fava bean bases.
Growth Catalysts
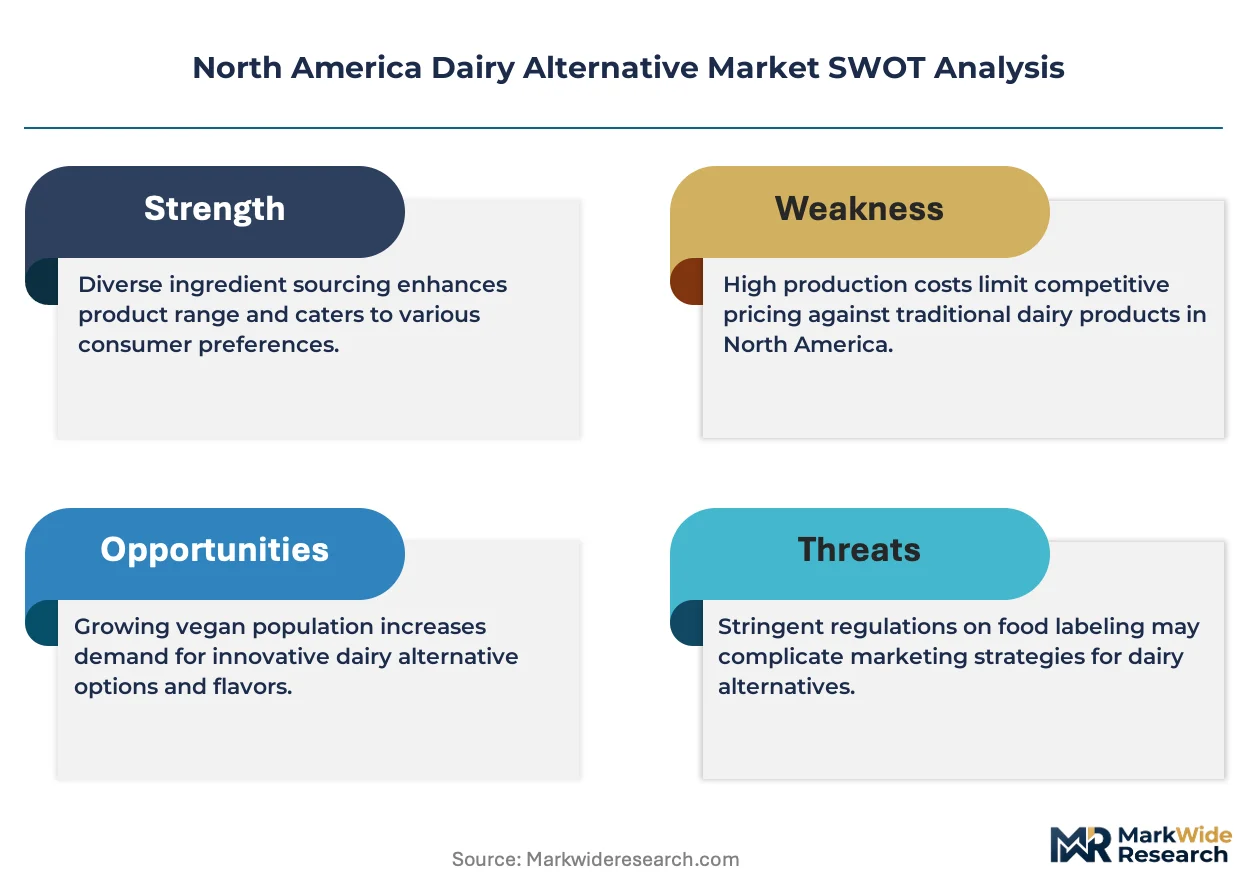
- Health Canada's updated food guide:The 2019 revision elevated plant proteins as core dietary recommendations, accelerating institutional procurement across Canadian school districts and healthcare foodservice.
- Precision fermentation:This biotechnology enables animal-identical dairy proteins without lactose or cholesterol, opening formulation pathways for next-generation cheese and yogurt alternatives previously unattainable with conventional plant bases.
- Metropolitan foodservice clusters:Toronto's cafe density and New York's specialty coffee culture have normalized oat milk as default offering, creating pull-through demand that cascades into retail velocity.
Market Restraints
- California irrigation constraints:Almond cultivation consumes approximately 10% of the state's agricultural water, exposing supply chains to drought-driven price spikes and pollinator colony collapse disorder.
- Technical limitation in protein dispersion:Plant proteins aggregate and precipitate in acidic coffee environments, requiring expensive hydrocolloid stabilizers that erode margin structures for barista-formulated products.
- Substitution threat from A2 dairy:This conventional dairy variant with modified beta-casein protein addresses digestive sensitivity without requiring consumer behavior change, capturing health-motivated switchers.
Strategic Opportunities
- Mexico's underpenetrated retail:Modern trade expansion in Guadalajara and Monterrey creates first-mover positioning for shelf-stable formulations before domestic competitors consolidate distribution.
- USDA Organic certification tailwind:Federal procurement preferences and retailer slotting fee reductions for organic-certified products incentivize reformulation investments that command price premiums.
- Direct-to-foodservice distribution:Bypassing conventional grocery wholesale through refrigerated logistics partnerships with Sysco and US Foods captures higher margins and locks in operator exclusivity.
Industry Challenges
- Food technologist scarcity:Formulation expertise in enzymatic hydrolysis and emulsion science concentrates in California and Wisconsin, constraining R&D velocity for brands outside these corridors.
- Clean label certification timelines:Non-GMO Project verification requires 3-6 month supply chain audits that delay product launches and freeze promotional calendars during peak seasonal windows.
- Legacy dairy cooperative retaliation:State-level labeling restrictions and checkoff-funded competitive campaigns in Wisconsin and Idaho create political friction for plant-based market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dairy Alternative Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Packaging Type: Cartons, Bottles, Tetra Packs, Pouches Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Convenience Stores End User: Households, Foodservice, Cafes, Restaurants |
| Companies Covered | Blue Diamond Growers, Vitasoy International Holdings Limited, Danone SA, Ripple Foods, SunOpta Inc., Oatly Group AB, The Hain Celestial Group Inc., Agrifoods International Cooperative Ltd, Califia Farms LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dairy Alternative Market Evolving Landscape
Biotechnology and regulatory clarity are converging to separate premium-positioned formulations from commodity alternatives, while foodservice procurement standardization locks in channel-specific winners.
Precision fermentation for whey and casein proteins is decomposing the traditional plant-versus-animal binary by enabling lactose-free, cholesterol-free products with identical functional performance to conventional dairy. Specialty cheese manufacturers and premium ice cream brands are adopting these ingredients fastest, compressing the timeline for taste parity and forcing commodity oat and almond brands into price-driven positioning.
The FDA's draft guidance on labeling plant-based milk alternatives mandates voluntary nutrient disclosure statements comparing calcium, protein, and vitamin D levels to dairy milk. This regulatory clarity pressures brands to fortify formulations or accept disadvantageous shelf positioning, with mainstream grocery retailers already revising planogram criteria to favor nutritionally competitive products in core dairy aisles.
Foodservice operators are consolidating procurement around single-source barista formulations that perform across espresso, cold brew, and steam wand applications without splitting. This specification tightening favors suppliers with dedicated cafe channel infrastructure, compressing the vendor base in metropolitan markets like Los Angeles, Chicago, and Vancouver where operator consolidation is most advanced.
North America Dairy Alternative Market Segmentation
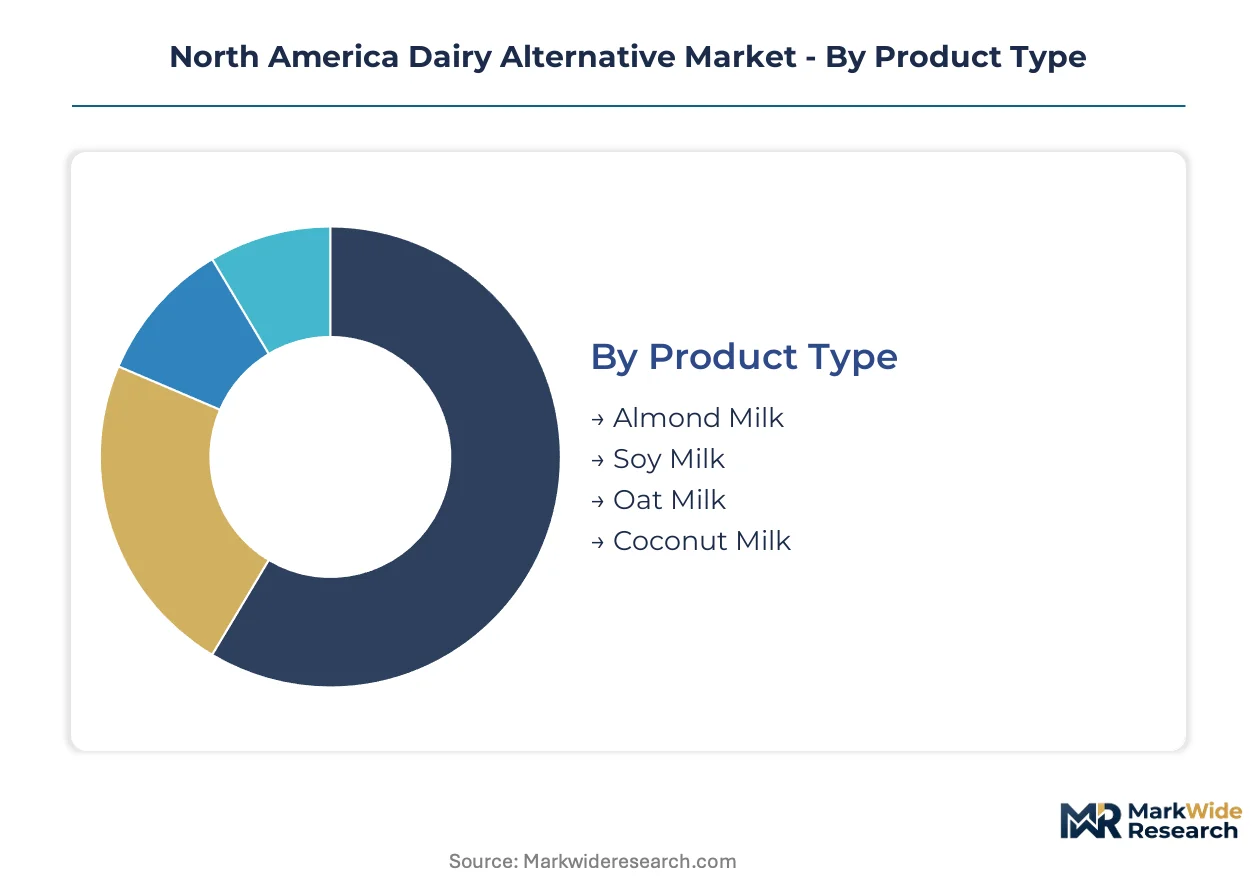
Segmentation reveals how substitution pressure varies across product formulations, packaging formats, and channel access. Understanding these divisions exposes where conventional dairy retains defensive strength and where plant-based alternatives achieve breakthrough velocity.
Product Type:
Almond milk faces the most acute substitution threat from A2 dairy and precision fermentation alternatives, while oat milk's neutral flavor profile insulates it from direct functional replacement.
- Almond Milk:Formulated from California-sourced nuts through blanching, grinding, and enzymatic treatment to achieve emulsion stability. Household retail in California and Arizona concentrates demand, though irrigation constraints and pollinator volatility compress margins and force reformulation toward blended bases.
- Oat Milk:Produced via enzymatic hydrolysis of oat starches into maltose, yielding a naturally sweet, neutral-flavored beverage with superior foam stability for espresso applications. Cafe channel procurement in Toronto, New York, and Los Angeles normalizes this as default offering, creating pull-through retail demand.
- Soy Milk:The original commercial plant milk, processed through aqueous extraction of defatted soy flakes; retains entrenched position in health food retail but faces allergen labeling friction and consumer preference shifts toward cleaner-tasting alternatives.
- Coconut Milk:Extracted from mature coconut flesh through mechanical pressing, delivering high-fat content suited for culinary applications; constrained by tropical sourcing dependence and pronounced flavor limitations in neutral beverage use.
Almond milk retains volume leadership; oat milk holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates shelf-stable mass-market penetration from premium refrigerated positioning, with packaging technology determining distribution reach and margin capture.
- Cartons:Gable-top paperboard with polyethylene barriers dominates refrigerated dairy-alternative aisles in conventional grocery; higher per-unit cost limits discount channel penetration but commands placement adjacent to conventional milk.
- Tetra Packs:Aseptic brick packaging enables ambient distribution without cold chain dependency, unlocking convenience store and foodservice pantry stocking across extended geographies.
- Bottles:PET and HDPE formats support transparent visual branding and resealability; concentrates in premium refrigerated segments and direct-to-consumer subscription channels.
- Pouches:Flexible film packaging reduces material cost and shipping weight; limited to single-serve formats and institutional foodservice portion control applications.
Tetra packs dominate ambient channel penetration; cartons capture the premium refrigerated tier.
Distribution Channel:
Application concentration varies sharply between household pantry stocking and immediate consumption occasions, with channel selection determining price realization and brand positioning.
- Supermarkets:Conventional grocery placement in dairy-alternative or natural foods aisles; planogram competition intensifies as FDA labeling guidance pressures nutritional parity claims.
- Foodservice:Direct procurement by restaurant and cafe operators; Sysco and US Foods distribution partnerships lock in volume commitments and operator exclusivity arrangements.
- Health Food Stores:Specialty retail with curated organic and Non-GMO Project verified assortments; higher shelf fees and certification requirements filter smaller entrants.
- Online Retailers:Direct-to-consumer and third-party marketplace fulfillment; subscription models concentrate in metropolitan markets with reliable cold chain last-mile infrastructure.
Supermarkets retain household volume leadership; foodservice channels climb fastest on cafe procurement standardization.
End User:
Customer type segmentation separates habitual daily consumption from occasional culinary substitution, with usage occasion determining formulation requirements and price sensitivity.
- Cafes:Espresso bar and specialty coffee operators demand barista-specific formulations with steam wand stability and neutral flavor; procurement consolidates around single-source suppliers with dedicated channel infrastructure.
- Households:Pantry stocking for cereal, baking, and direct consumption; price sensitivity intensifies as commodity oat and almond brands proliferate in conventional retail.
- Restaurants:Back-of-house culinary applications including sauces, desserts, and smoothies; volume purchasing through broadline distributors with formulation flexibility for menu-specific customization.
- Foodservice:Institutional feeding including healthcare, education, and corporate catering; Health Canada's food guide revision accelerates plant protein procurement across Canadian school districts and hospital systems.
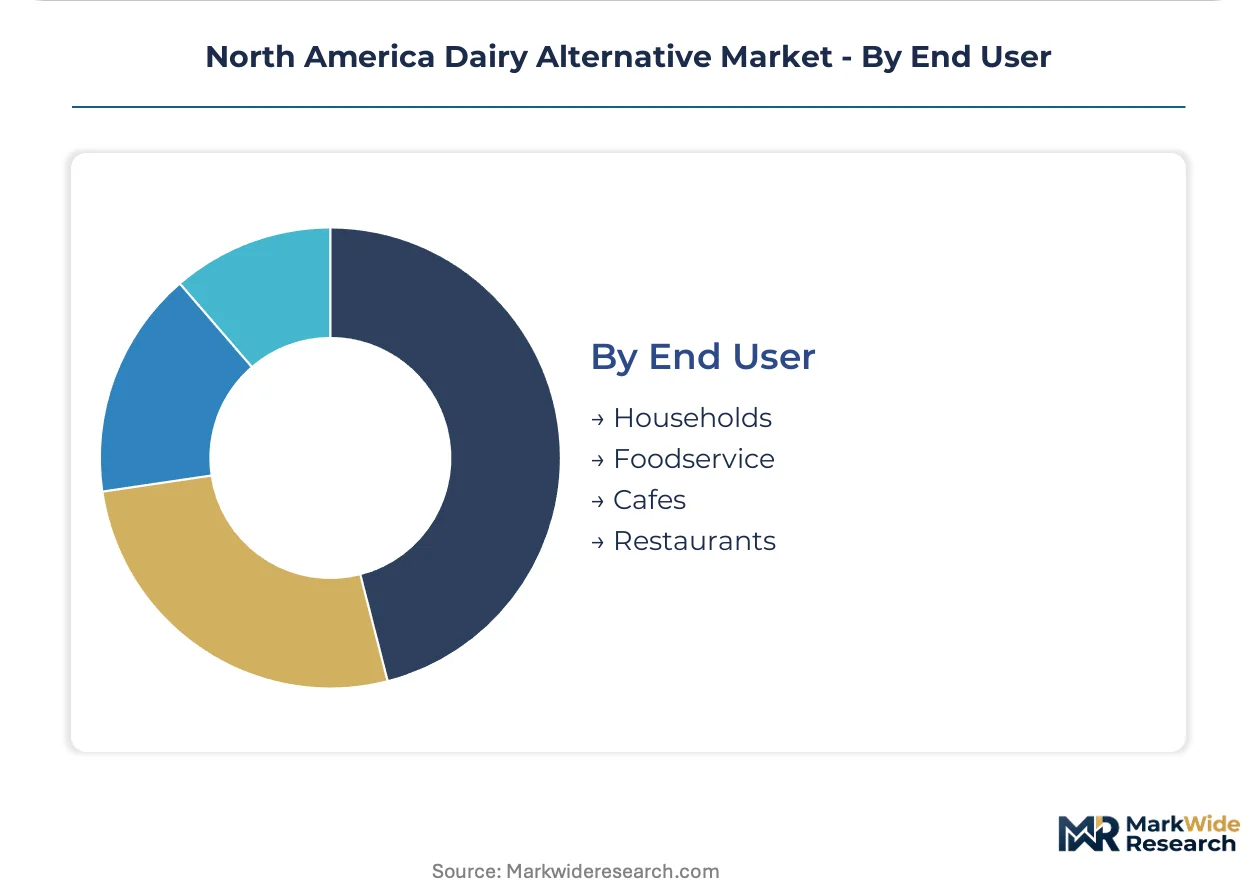
Households retain absolute volume leadership; cafes hold the steepest expansion curve on metropolitan procurement standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA anchors regulatory oversight for plant-based beverages in the United States, while Health Canada governs bilingual labeling and nomenclature standards north of the border. Mexico's expanding modern trade channels present untapped penetration opportunities for shelf-stable formulations.
United States
California's almond cultivation supplies the dominant ingredient base, though drought-driven water scarcity forces reformulation toward oat and fava bean alternatives. The FDA's updated labeling guidance mandates voluntary nutrient disclosure statements comparing plant-based products to dairy milk. Los Angeles and New York metropolitan clusters concentrate cafe channel procurement standardization around barista-specific oat formulations.
Canada
Health Canada's 2019 food guide revision elevated plant proteins as core dietary recommendations, accelerating institutional procurement across school districts and healthcare foodservice. Bilingual packaging requirements under the Food and Drugs Act create compliance thresholds that filter smaller entrants from mainstream retail placement. Toronto's cafe density normalizes oat milk as default offering, creating pull-through demand that cascades into retail velocity.
Mexico
Modern trade expansion in Guadalajara and Monterrey creates first-mover positioning for shelf-stable formulations before domestic competitors consolidate distribution. The country's national food safety regulator oversees labeling standards for imported plant-based beverages entering through Nuevo León and Jalisco distribution corridors. Mexico City Metro's specialty coffee culture is adopting oat milk procurement patterns that mirror North American metropolitan trends.
California
The state's agricultural water constraints expose almond supply chains to drought-driven price spikes and pollinator colony collapse disorder. California Department of Food and Agriculture programs monitor irrigation efficiency standards that directly impact nut cultivation economics. The innovation corridor spanning San Francisco to Los Angeles concentrates food technologist talent in enzymatic hydrolysis and emulsion science.
New York Metro
Specialty coffee culture in Brooklyn and Manhattan has normalized oat milk as default offering, forcing operator procurement consolidation around single-source barista formulations. State-level environmental disclosure mandates reshape supplier qualification criteria for brands seeking shelf placement. The metropolitan foodservice cluster drives specification tightening that favors suppliers with dedicated cafe channel infrastructure.
North America Dairy Alternative Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North America dairy alternative market. The vendor base stratifies into three tiers: multinational conglomerates with refrigerated distribution networks, mid-scale specialists with foodservice channel infrastructure, and private-label contract manufacturers with integrated ingredient sourcing. Strategic moves concentrate on direct-to-foodservice distribution partnerships and precision fermentation technology licensing.
Within the multinational tier, Danone SA and Oatly Group AB represent established refrigerated supply chain operators, while Califia Farms LLC and Ripple Foods exemplify barista-specific formulation specialists. SunOpta Inc. occupies a position as an integrated contract manufacturer serving private-label entrants. Blue Diamond Growers anchors almond-based ingredient supply for blended formulations. These five entities collectively illustrate the competitive archetypes: conglomerate scale, channel specialization, and upstream integration.
| Leading Market Players |
|---|
| Blue Diamond Growers |
| Vitasoy International Holdings Limited |
| Danone SA |
| Ripple Foods |
| SunOpta Inc. |
| Oatly Group AB |
| The Hain Celestial Group Inc. |
| Agrifoods International Cooperative Ltd |
| Califia Farms LLC |
| Others |
Value Network & Pricing Analysis
Scale economies in enzymatic hydrolysis equipment anchor supply concentration among California and Wisconsin processing clusters, compressing unit costs for oat base formulations while forcing smaller brands toward contract manufacturing partnerships that surrender margin control. This concentration dynamics creates pricing floors set by integrated operators with captive ingredient sourcing, while commodity almond processors face margin erosion from irrigation cost pass-throughs.
Pricing Analysis
Geographic price spreads between California-sourced almond milk and Great Lakes-processed oat formulations reflect water scarcity premiums and logistics differentials across the continent. Three-tier pricing structure across premium refrigerated barista formulations, standard shelf-stable retail, and economy private-label tiers separates brands by certification grade and channel infrastructure investment. Pricing pressure stems from precision fermentation entrants achieving taste parity at lower input costs. Household retail segments exhibit highest price sensitivity; foodservice operators tolerate premium positioning for steam wand stability guarantees.
Supply Chain Analysis
Inbound logistics costs from Canadian Prairie oat growing regions and California Central Valley almond orchards concentrate exposure to Port of Oakland congestion and intermodal rail bottlenecks at Chicago. Raw material sourcing draws from Canadian oat cultivation, California almond groves, and Midwestern soy processing infrastructure. Single-source vulnerability concentrates in California water-dependent nut supply. Distribution runs through Sysco and US Foods refrigerated networks for foodservice, with conventional grocery relying on direct-store-delivery and warehouse club pallet programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA labeling compliance and Health Canada bilingual packaging creates defensive moats that filter sub-scale entrants from mainstream retail placement. Network effects in foodservice procurement standardization lock operator relationships behind multi-year distribution agreements.
For Market Incumbents: Fortify refrigerated distribution infrastructure against precision fermentation substitution by locking exclusive barista formulation partnerships with metropolitan cafe chains. Expand backward integration into Canadian oat milling capacity to hedge California water risk. Prioritize Non-GMO Project certification investments that sustain premium shelf positioning as FDA disclosure requirements intensify nutritional parity competition. For New Entrants and Emerging Players: Lead with shelf-stable Tetra Pack formulations targeting Mexico's underpenetrated modern trade channels in Guadalajara and Monterrey before domestic competitors consolidate distribution. Exploit food technologist scarcity gaps by locating R&D in secondary Midwestern corridors outside California-Wisconsin concentration. Pursue direct-to-foodservice distribution bypassing conventional grocery slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation licensing platforms over commodity plant-base processors facing agricultural input volatility. Long-term viability rests on intellectual property portfolios enabling animal-identical protein production. Acquisition targets should demonstrate integrated ingredient sourcing or exclusive foodservice channel infrastructure. Monitor FDA protein fortification standard evolution as inflection signal for formulation investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Licensing | Enables animal-identical dairy proteins without agricultural input exposure to California water scarcity. |
| Direct-to-Foodservice Distribution Partnership | Captures higher margins through Sysco and US Foods refrigerated logistics bypassing grocery wholesale. |
| Canadian Oat Supply Integration | Secures drought-resistant base material as California almond irrigation constraints intensify. |
| Barista Formulation Specialization | Locks operator exclusivity through steam wand stability specifications in Toronto and New York clusters. |
| USDA Organic Certification Investment | Qualifies for federal procurement preferences and retailer slotting fee reductions in conventional grocery. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with plant-based food technologists, category buyers at conventional grocery retailers, foodservice procurement directors, and contract manufacturing executives; and secondary validation through FDA guidance documents, Health Canada food regulations, USDA organic certification databases, and Nielsen retail audit data. Bottom-up triangulation cross-referenced ingredient sourcing patterns against top-down market sizing from production capacity and channel velocity estimates.
Across the analysis window, forecasts modeled product type segmentation by base ingredient and formulation complexity, packaging format by shelf-stable versus refrigerated requirements, and distribution channel by foodservice versus retail penetration patterns. CAGRs derived from historical velocity trends adjusted for regulatory catalysts including Health Canada's food guide revision and FDA labeling guidance implementation. Industry-specific inputs incorporated California water allocation forecasts and pollinator supply volatility indices.
Forecasts assume regulatory continuity in FDA plant-based beverage oversight and Health Canada bilingual packaging mandates; material policy shifts including state-level labeling restrictions or federal procurement standard changes would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Vegan Butter Market
Dairy Alternatives
Global Vegan Sour Cream Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Vegan Ice Cream Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Legumes Plant-Based Milk Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Low Calorie Cream Cheese Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Global Milk Replacers Market