
 North America Pizza Oven Market | 2026-2036
North America Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
North America Pizza Oven Market Insights
Foodservice distribution channels are concentrating around specialized equipment dealers and direct-to-operator digital platforms, a shift that is reshaping how pizza oven manufacturers reach end users. EarthStone Wood-Fire Ovens leverages its artisan positioning to dominate the premium wood-fired segment across independent restaurants. Blodgett Oven Company sustains manufacturing scale advantages in conveyor and gas-fired systems for high-volume chains. Middleby Corporation anchors its presence through broad foodservice equipment portfolios that cross-sell into existing restaurant accounts.
A pizza oven is a thermally insulated chamber engineered to sustain temperatures between 450°F and 900°F, utilizing refractory materials, steel, or brick composites to distribute radiant and convective heat for rapid dough cooking and crust formation. Its primary commercial purpose centers on throughput consistency, flavor development through thermal mass, and operational durability under continuous service cycles. Wood-fired and gas configurations command the largest installed base in full-service restaurants, while conveyor systems lead in quick-service throughput economics. Electric variants are gaining traction in food trucks and urban bakeries where venting constraints and energy efficiency features reduce compliance burdens.
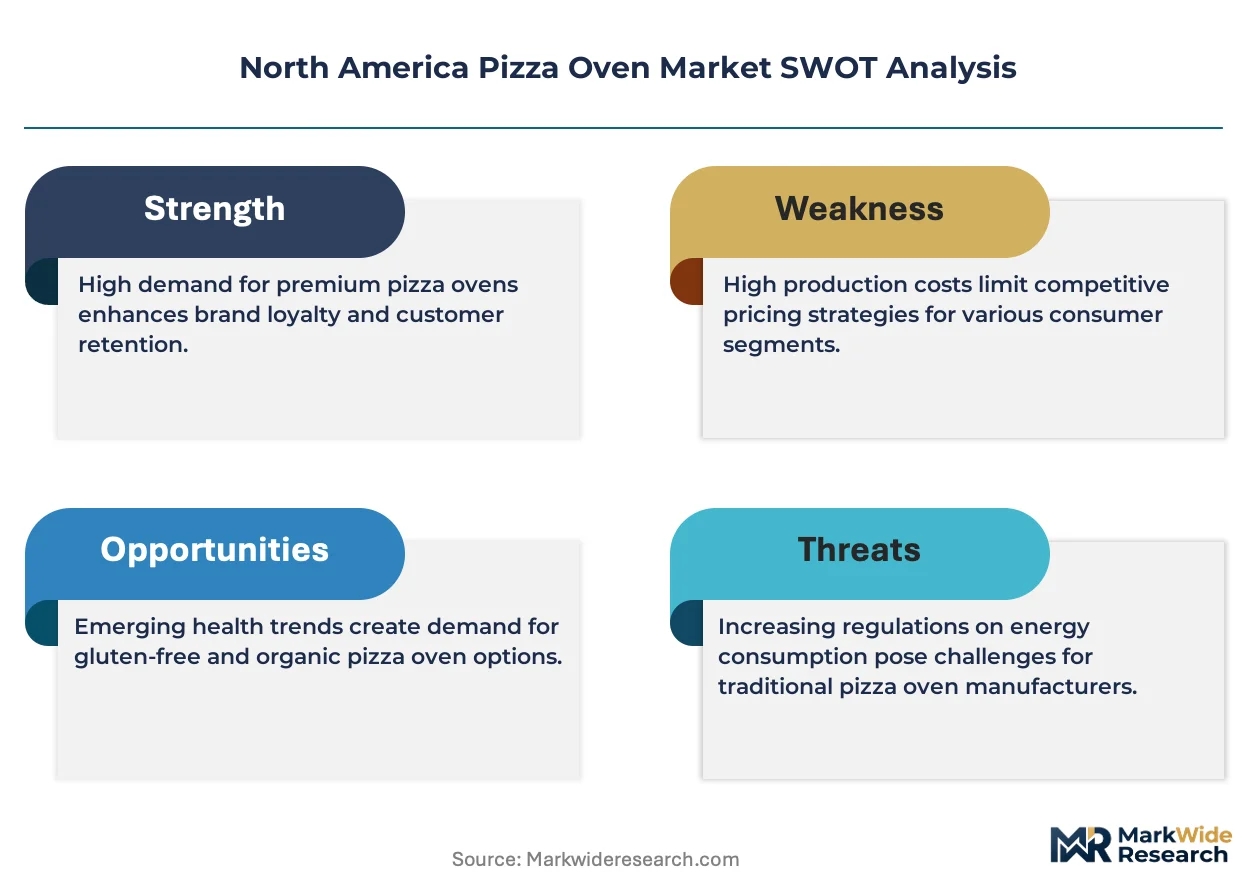
The U.S. Department of Energy sets minimum efficiency standards for commercial cooking equipment, while NSF International certifies sanitation and material safety for food zone contact surfaces, and UL standards govern electrical and gas-fired safety in fixed and mobile installations. These frameworks elevate capital costs for non-compliant imports but create protected terrain for certified domestic manufacturers. Stakeholders must monitor evolving municipal electrification mandates and food truck permitting rules that will determine whether gas or electric platforms capture the next replacement cycle.
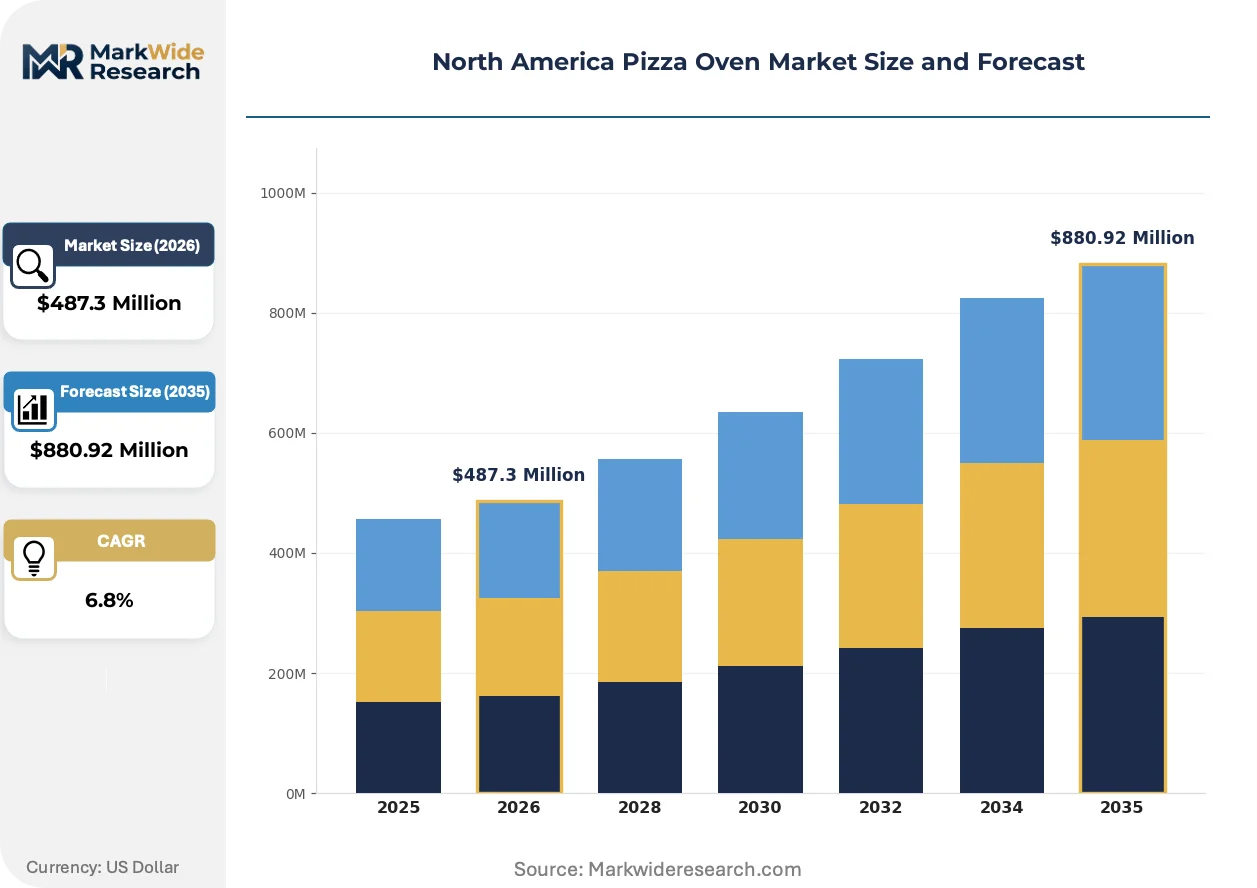
Market Dynamics
The U.S. Department of Energy's commercial kitchen equipment standards are compressing replacement cycles across independent pizzerias and fast-casual chains, forcing manufacturers to redesign thermal architectures around efficiency mandates rather than legacy performance benchmarks.
Growth Catalysts
- Texas food truck permitting surge:Municipal streamlining of mobile food vendor licenses in Dallas, Houston, and Austin is accelerating compact electric oven deployments. Food truck operators prioritize ventless systems that bypass hood installation requirements.
- Fast-casual throughput demands:Conveyor oven configurations are capturing share from traditional deck ovens as Chipotle-style pizza concepts optimize for 90-second cook times. Thermal consistency across high-volume lunch rushes drives specification decisions.
- Refractory material advances:New ceramic fiber composites reduce preheat energy consumption by improving heat retention. California operators facing electricity rate escalation are specifying these linings for operational cost control.
Market Restraints
- Steel and nickel alloy input volatility:Conveyor belt fabrication depends on stainless steel grades whose price fluctuations compress manufacturer margins. Foundry capacity concentration in the Great Lakes region amplifies supply risk.
- NSF certification timeline friction:Sanitation validation for novel combustion chamber designs extends product launch windows by 8-14 months. Smaller manufacturers lack capital reserves to sustain extended approval cycles.
- Induction cooking substitution:Flat-top induction ranges with pizza steel accessories are capturing budget-conscious bakery and café segments. These systems eliminate hood infrastructure entirely.
Strategic Opportunities
- Northeast corridor electrification mandates:New York City and Boston building codes are phasing out gas hookups in new commercial construction. Electric deck ovens with rapid-recovery elements will capture this replacement wave.
- Direct-to-operator digital platforms:Specialized equipment dealers are launching configuration tools that bypass traditional foodservice distribution. California and Texas operators are completing entire specification workflows online.
- Wood-fired aesthetic hybridization:Gas-assisted wood-burning systems combine visual theater with operational consistency. Premium independent restaurants in Chicago and Montreal are specifying these for open-kitchen designs.
Industry Challenges
- Refractory mason skill scarcity:Traditional brick oven construction requires craftsmen whose apprenticeship pipelines collapsed during the 2008-2016 restaurant contraction. Manufacturers must internalize this fabrication or abandon the segment.
- UL field certification complexity:Mobile food truck installations require electrical and gas safety validation at each operational jurisdiction. Operators face redundant inspection fees across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Pizza Oven Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood-Fired, Gas, Electric, Conveyor End User: Restaurants, Bakeries, Food Trucks, Home Users Installation Type: Mobile, Stationary, Built-In, Portable Feature: Temperature Control, Timer, Multi-Function, Energy Efficient |
| Companies Covered | EarthStone Wood-Fire Ovens, Marra Forni, Wood Stone Corporation, Blodgett Oven Company, Californo, Chicago Brick Oven, Middleby Corporation, Mugnaini Imports, Forno Bravo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Pizza Oven Market Trends and Innovations
Thermal management systems are converging with IoT architectures, creating operational visibility that reshapes how kitchen managers optimize energy consumption and maintenance scheduling across distributed restaurant footprints.
Smart oven controllers integrating temperature sensors, door-position monitors, and energy metering are digitizing fleet management for multi-unit operators. California-based fast-casual chains are deploying these systems across 50-plus locations to standardize crust quality and compress energy audits. The data infrastructure is digitizing procurement decisions, with performance analytics now driving specification renewals.
The U.S. Department of Energy's pending amendments to commercial cooking equipment standards will tighten allowable standby energy consumption. Gas-fired deck oven manufacturers are redesigning burner modulation systems and pilot-light interlocks to maintain compliance eligibility. High-volume operators in Texas and Arizona are pre-positioning orders ahead of implementation to lock in grandfathered equipment classifications.
Leasing and equipment-as-a-service arrangements are displacing capital purchase models among emerging restaurant groups. Specialized finance platforms now bundle installation, maintenance, and upgrade rights into monthly obligations. Food truck operators across the Pacific Northwest are adopting these structures to preserve working capital for route expansion and permit diversification.
North America Pizza Oven Market Segmentation
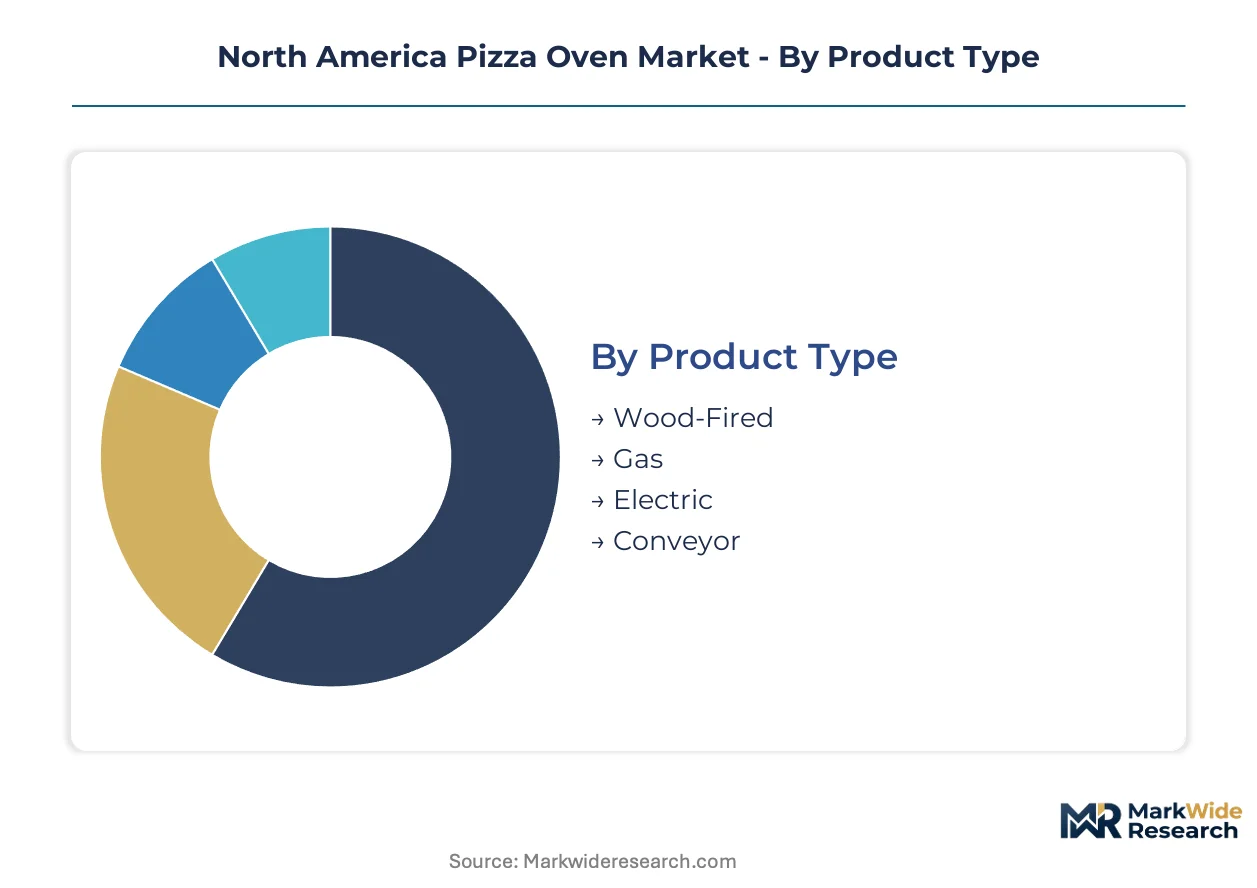
Pizza oven procurement decisions hinge on thermal architecture, operational mobility, and energy compliance. Segment boundaries blur as hybrid systems and IoT-enabled controls reshape traditional equipment categories across Texas, California, and Northeast corridor operators.
Product Type:
Wood-fired systems dominate artisan positioning while gas and electric platforms split on infrastructure availability and municipal electrification mandates.
- Wood-Fired:Refractory brick or stone chambers with direct flame contact generate 700°F-900°F temperatures for rapid crust charring. Demand clusters in Chicago and Montreal premium independents where open-kitchen theater drives customer acquisition. Masonry construction costs and skilled labor scarcity constrain manufacturer scaling.
- Gas:Atmospheric or infrared burner configurations deliver consistent 500°F-650°F output with faster recovery than wood systems. Fast-casual chains across Texas and Arizona specify these for throughput reliability during lunch rushes. DOE efficiency standards are forcing burner modulation redesigns.
- Electric:Resistive or induction elements eliminate venting requirements and suit food trucks and urban bakeries facing gas hookup restrictions.
- Conveyor:Continuous belt mechanisms with forced-air convection achieve 90-second cook times for high-volume quick-service economics.
Established volume favors Gas; emerging adoption favors Electric.
End User:
Customer procurement authority varies from centralized chain specifications to independent operator discretion.
- Restaurants:Full-service and fast-casual operators specify thermal systems based on menu positioning and kitchen throughput requirements. California fast-casual chains are deploying IoT-enabled fleet management across 50-plus locations to standardize crust quality.
- Food Trucks:Mobile operators prioritize ventless electric systems that bypass hood installation and reduce permitting friction. Dallas, Houston, and Austin municipal streamlining is accelerating compact oven deployments.
- Bakeries:Artisan bread and pastry producers seek dual-use thermal mass for pizza production during off-peak hours.
- Home Users:Residential outdoor installations favor portable gas and wood-fired units with aesthetic design priority over commercial durability.
Restaurants command the dominant procurement volume; Food Trucks are climbing the fastest.
Installation Type:
Physical mobility requirements determine engineering tradeoffs between thermal mass and transportability.
- Stationary:Permanent foundation-mounted systems maximize refractory thermal mass for heat retention and flavor development. Northeast corridor full-service restaurants favor these for open-kitchen permanence.
- Mobile:Trailer-mounted or vehicle-integrated configurations require UL field certification at each operational jurisdiction. Pacific Northwest operators face redundant inspection fees across state lines.
- Built-In:Custom architectural integration with surrounding kitchen infrastructure suits premium independent pizzerias.
- Portable:Countertop or wheeled units serve catering operations and temporary event deployments.
Stationary installations anchor replacement revenue; Mobile configurations are expanding most quickly.
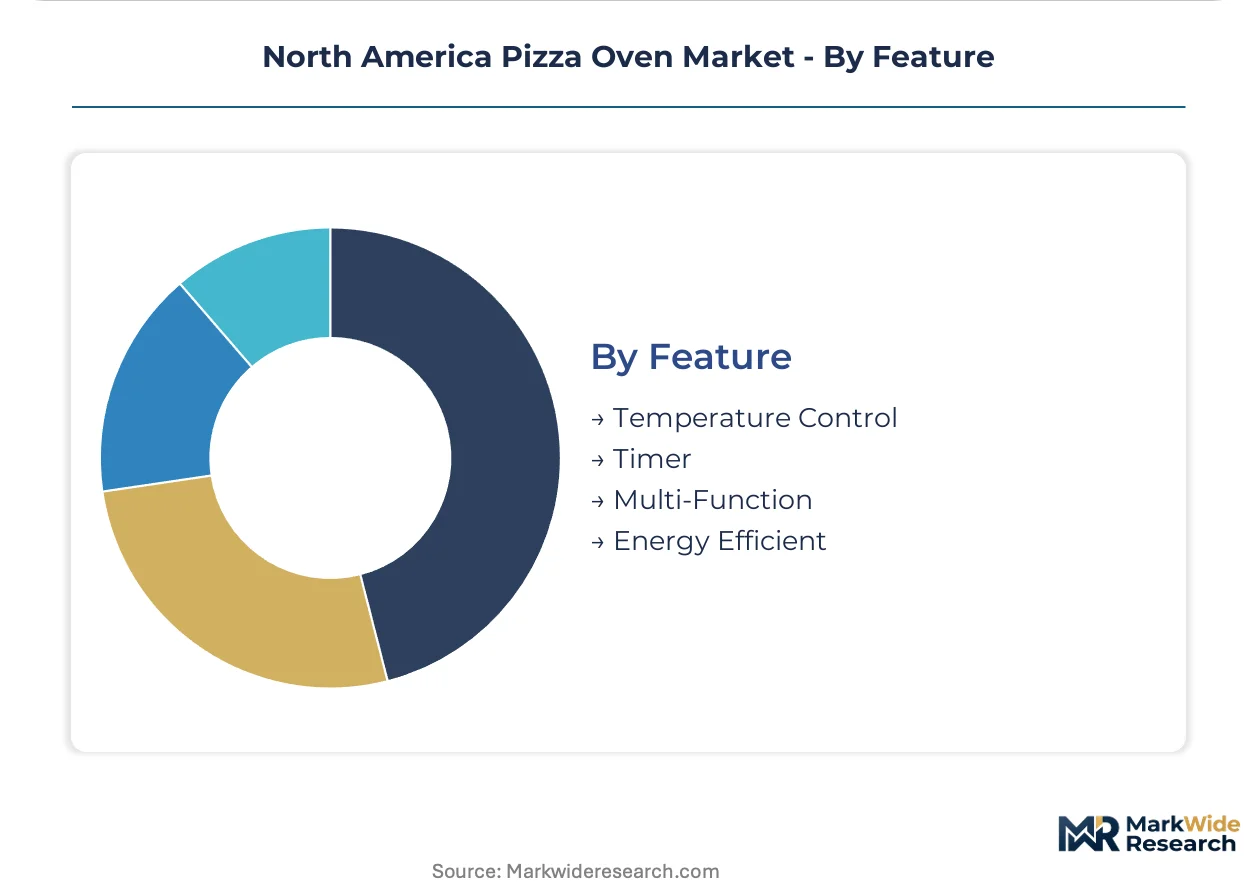
Feature:
Control sophistication separates premium specifications from baseline equipment tiers.
- Energy Efficient:Ceramic fiber composite linings and standby power interlocks reduce consumption. California operators facing electricity rate escalation specify these for operational cost control.
- Temperature Control:PID-based digital thermostats with multi-zone sensing enable precise thermal management. Fast-casual chains deploy these for crust consistency across distributed locations.
- Timer:Programmable cycle automation reduces labor attention requirements during high-volume service periods.
- Multi-Function:Configurable chambers supporting roasting, baking, and pizza production maximize equipment utilization in space-constrained kitchens.
Energy Efficient features dominate new specifications; Temperature Control systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas operators command pricing premiums on mobile electric configurations while California buyers absorb cost escalations from electrification mandates. This asymmetry concentrates manufacturer attention on compliance-flexible product architectures.
United States
Food truck permitting surges in Dallas, Houston, and Austin accelerate compact ventless oven deployments. The U.S. Department of Energy's commercial kitchen equipment standards compress replacement cycles across independent pizzerias. California fast-casual chains deploy IoT-enabled fleet management across 50-plus locations to standardize crust quality.
Canada
Ontario and Quebec restaurant operators prioritize energy-efficient ceramic fiber linings amid electricity rate pressures. Health Canada sanitation certifications govern food zone contact surface requirements. Toronto and Montreal premium independents specify gas-assisted wood-burning systems for open-kitchen theater.
Mexico
Expanding fast-casual pizza concepts in Mexico City Metro and Nuevo León drive conveyor oven demand for throughput economics. The country's national standards body certifies commercial cooking equipment safety. Bajío Region foodservice distributors are consolidating procurement around specialized equipment dealers with direct digital platforms.
North America Pizza Oven Market Competitive Landscape
Artisan-specialist fabricators and scale-driven equipment conglomerates split the market along premium-versus-volume fault lines. The vendor base concentrates around three strategic archetypes: heritage wood-fired masons, conveyor-system industrialists, and diversified foodservice portfolios. Dominant competitive moves include geographic expansion into Texas food truck corridors and technology licensing for IoT-enabled thermal management.
Among heritage-positioned specialists, EarthStone Wood-Fire Ovens and Marra Forni occupy positions anchored to artisan refractory construction. Scale-driven conglomerate Middleby Corporation exemplifies the diversified portfolio archetype through cross-selling leverage. Blodgett Oven Company represents the industrial fabrication tier with manufacturing scale advantages in conveyor configurations.
| Leading Market Players |
|---|
| EarthStone Wood-Fire Ovens |
| Marra Forni |
| Wood Stone Corporation |
| Blodgett Oven Company |
| Californo |
| Chicago Brick Oven |
| Middleby Corporation |
| Mugnaini Imports |
| Forno Bravo |
| Others |
Pricing and Supply Chain Analysis
Great Lakes foundry concentration for stainless steel conveyor belt fabrication anchors margin capture at the conveyor-system tier, while refractory mason scarcity in premium wood-fired construction shifts value toward specialized fabricators with captive masonry teams.
Pricing Analysis
Configured-to-order pricing for custom refractory brick ovens commands a 40-60% premium over standard gas deck configurations. Three-tier pricing structure across premium, standard, and economy levels stratifies by UL certification grade and thermal recovery speed. Cost compression in standard gas tiers is intensifying because California electrification mandates are forcing burner redesigns. Food truck operators show highest price sensitivity, prioritizing ventless electric systems under $8,000, while Chicago premium independents absorb masonry costs exceeding $25,000 for open-kitchen theater.
Supply Chain Analysis
Stainless steel feedstock draws from Great Lakes foundries, Italian refractory ceramic imports, and Chinese control component assemblies. Nickel alloy and ceramic fiber composite dependencies rest on single-source vulnerabilities in specialty refractory grades. Tariff exposure on Italian ceramic linings amplifies cost volatility for wood-fired manufacturers. Distribution runs through specialized foodservice equipment dealers and direct-to-operator digital platforms, with California and Texas operators completing full specification workflows online.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America pizza oven demand sits in early-cycle expansion as food truck permitting surges across Texas metropolitan corridors accelerate compact electric oven penetration beyond traditional restaurant replacement rates.
For Market Incumbents: Harden certification moats by pre-positioning UL field validation networks across Pacific Northwest state lines before mobile operators face redundant inspection fee accumulation. Deepen backward integration into ceramic fiber composite production to offset Italian refractory import tariff exposure. Prioritize burner modulation R&D to maintain DOE compliance eligibility as efficiency standards tighten. For New Entrants and Emerging Players: Build out digital-native specification platforms targeting California fast-casual chains with IoT-enabled fleet management needs. White-space concentration sits in gas-assisted wood-burning hybrid systems for Montreal and Chicago open-kitchen theater. Go-to-market leverage rests on leasing-as-a-service bundling for Pacific Northwest food truck route expansion. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-integrated thermal management sub-segments as sensor and controller costs embed into base configurations. Long-term viability favors diversified foodservice equipment portfolios with cross-selling leverage into existing restaurant accounts. Target acquisition archetype: heritage-positioned wood-fired specialists with captive masonry fabrication. Signal to watch: municipal electrification mandate acceleration beyond New York City and Boston into secondary Northeast corridor markets.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Thermal Management Integration | California fast-casual chains deploy sensor networks across 50-plus locations to standardize crust quality. |
| Ceramic Fiber Composite Sourcing | Manufacturers internalize refractory production to bypass Italian import tariff exposure on specialty linings. |
| Direct-to-Operator Digital Platform | Texas and California operators complete entire specification workflows online, bypassing traditional distribution. |
| Gas-Assisted Wood-Fire Hybridization | Premium Chicago and Montreal independents specify these systems for operational consistency with visual theater. |
| Equipment-as-a-Service Leasing | Pacific Northwest food truck operators adopt monthly bundles to preserve working capital for route expansion. |
Research Methodology
Desk research of NSF certification databases, DOE efficiency standard filings, and municipal food truck permitting records preceded structured interviews with fast-casual chain procurement directors, food truck operator-owners, refractory mason contractors, and specialized equipment dealer principals. Primary intelligence combined with secondary validation from UL safety filings and trade customs data. Bottom-up unit shipment estimates triangulated against top-down foodservice equipment spending benchmarks.
Assumptions held fixed include DOE implementation timelines and current municipal electrification code trajectories, while variables included food truck permit issuance velocity and ceramic fiber composite adoption rates. Segmentation modeling spanned thermal architecture, installation mobility, end-user category, and control sophistication dimensions across the projection horizon. CAGRs derived from logistic penetration curves fitted to replacement cycle data and new installation buildouts. Industry-specific inputs incorporated electricity rate escalation curves for California operators and steel price volatility indices from Great Lakes foundry regions.
Practitioners should monitor municipal electrification mandate expansion and food truck permitting streamlining velocity for early signals of gas-to-electric platform mix shifts. Cross-checking against National Restaurant Association equipment spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bakery Products
Bakery Mixes Market
Bakery Products
Canada Frozen Bakery Market
Bakery Products
Asia-Pacific Bakery Products Market
Bakery Products
Low Fat Baked Goods Market
Bakery Products
Bakery Premixes Market
Bakery Products
Global Bakery Product Market
Bakery Products
Bakery Fats Market
Bakery Products
Low Fat Muffin Market
Bakery Products
Layer Cake Mixes Market
Bakery Products
Low Calorie Rice Cake Market
Bakery Products
Dough Whitener Market
Bakery Products
North America Sweet Biscuits Market
Bakery Products
Muffins Market
Bakery Products
Organic Frozen Bakery Market
Bakery Products
Gluten-Free Bakery Products Market
Bakery Products
Asia-Pacific Baked Food and Cereals Market