
 Vegan Cheese Market | 2026-2036
Vegan Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Cheese Market Intelligence
Subscription-based recipe and replenishment services for home cooks is rebalancing how vegan cheese brands build recurring revenue beyond one-time retail purchases. Miyoko's Creamery leverages direct-to-consumer memberships to sustain higher margins and deeper customer relationships. Violife competes through broad retail distribution across multiple continents, while Daiya anchors its position in North American foodservice channels with specialized melting formulations for pizza and sandwich applications.
Vegan cheese comprises plant-derived fat and protein matrices—typically cashew, coconut oil, or pea protein bases—fermented or processed to mimic the texture, melt, and flavor profile of conventional dairy cheese, serving commercial food manufacturing and retail consumer markets. Nut-based varieties occupy the premium tier due to longer production cycles and artisan positioning, while pea protein-based formats represent the fastest-growing structural segment as manufacturers solve earlier texture and taste limitations. Block and shredded forms dominate institutional procurement, whereas spreadable and slice formats command higher household penetration rates among flexitarian and lactose-intolerant customer segments.
FDA labeling standards in the United States and EFSA novel food assessments in Europe shape ingredient approval timelines and product positioning claims, directly influencing which formulations achieve commercial scale. India's FSSAI is developing plant-based dairy analog regulations that will determine market access for imported and domestic vegan cheese products alike. Stakeholders must monitor evolving allergen disclosure mandates and fermentation-derived ingredient classifications as these regulatory boundaries will determine which production technologies achieve scalable approval.
Market Dynamics
Pea protein fermentation technology is compressing production timelines and eroding the cost premium that nut-based formulations historically commanded, forcing incumbent suppliers to reposition their ingredient sourcing strategies.
Growth Catalysts
- REACH labeling frameworks:European disclosure mandates are accelerating clean-label reformulations as manufacturers preempt stricter ingredient transparency requirements.
- Quick-service restaurant channel expansion:North American foodservice operators are embedding plant-based options into permanent menu architecture rather than limited-time offerings.
- Cashew supply concentration in Vietnam and India:Established processing infrastructure is stabilizing input costs for premium-tier producers despite climate volatility elsewhere.
Market Restraints
- Coconut oil price volatility:Weather disruptions in Southeast Asian growing regions create margin compression for fat-dependent formulations.
- FSSAI regulatory uncertainty:India's pending plant-based dairy analog standards are freezing import licensing decisions and domestic investment timelines.
- Casein mimicry limitations:Current protein cross-linking technologies fail to replicate the stretch and mouthfeel of aged dairy cheeses in high-heat applications.
Strategic Opportunities
- German retail shelf expansion:Discounters and premium grocers are dedicating linear footage growth to fermented plant-based alternatives ahead of category maturation.
- Precision fermentation convergence:Microbial dairy protein production is integrating with plant-fat matrices to create hybrid products with superior functional performance.
- Direct-to-consumer subscription channels:Replenishment models bypass retail slotting fees and capture customer data for flavor development pipelines.
Industry Challenges
- Fermentation scale-up capex requirements:Commercial bioreactor capacity for dairy-identical proteins demands capital commitments that strain mid-tier balance sheets.
- Novel food approval timelines:EFSA assessment queues for precision fermentation ingredients extend market entry schedules by 18-36 months.
- Allergen cross-contamination protocols:Shared equipment between nut-based and allergen-free production lines complicates facility certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Cheese Market |
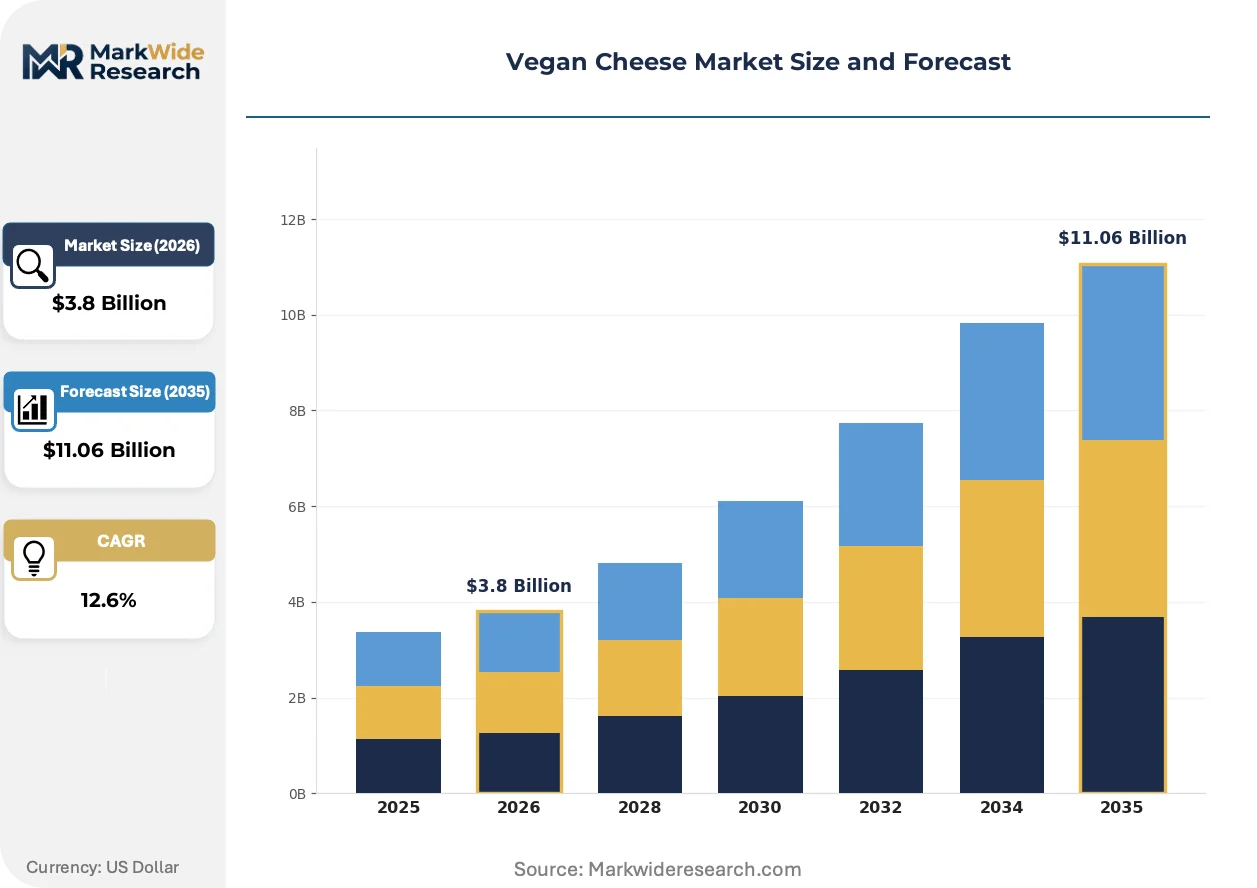
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nut-Based, Soy-Based, Coconut-Based, Rice-Based, Pea Protein-Based, Others Form: Block, Slices, Shredded, Spreadable, Powder, Cubes Application: Foodservice, Household Consumption, Bakery, Snacking, Catering, Institutional Use Customer Type: Vegans, Lactose Intolerant, Flexitarians, Health Conscious, Allergic Consumers, Ethical Shoppers |
| Companies Covered | Kite Hill, Treeline, Miyoko's Creamery, Go Veggie, Tofutti, Violife, Follow Your Heart, Dreamfarm, Daiya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Cheese Market Strategic Shifts & Innovations
Fermentation-derived ingredients and AI-assisted flavor mapping are converging to close the sensory gap with conventional cheese, while regulatory frameworks in multiple jurisdictions are crystallizing the rules of commercial engagement.
Pea protein isolate combined with enzymatic modification is integrating into mainstream formulations to achieve melt characteristics previously restricted to coconut oil bases. Pizza chains and sandwich manufacturers are adopting these reformulations at accelerating pace as price parity with dairy approaches. The technology is integrating fat and protein matrices at molecular scale, compressing the performance gap between plant-derived and animal-derived ingredients.
EFSA novel food assessments are extending approval timelines for fermentation-derived casein alternatives, forcing developers to front-load toxicology and allergenicity studies. European manufacturers are responding by establishing dedicated regulatory affairs functions and pre-submission consultation protocols. Smaller entrants lacking compliance infrastructure are shelving precision fermentation programs and retreating to established ingredient decks.
Flexitarian households are rotating toward spreadable and slice formats for daily consumption while reserving block purchases for entertaining occasions. Retail data from German supermarkets indicates this behavioral bifurcation is concentrating volume in convenience-oriented packaging sizes. Foodservice procurement in North American college and corporate dining contracts is capturing the institutional counterpart to this household pattern.
Vegan Cheese Market Segmentation
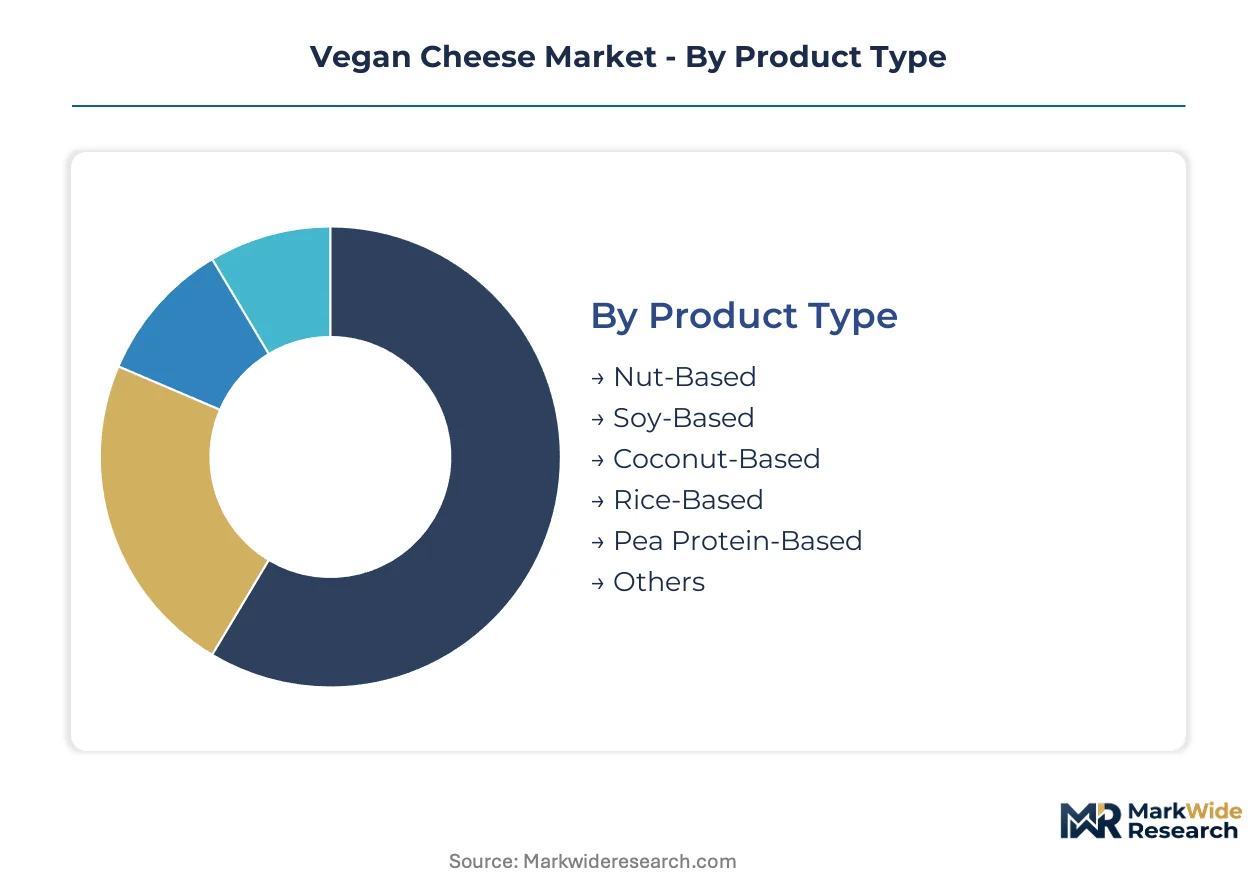
Product differentiation across protein bases and form factors determines manufacturing capital requirements and margin profiles in vegan cheese. Each segmentation axis reveals distinct competitive dynamics between artisan positioning and mass-market scalability.
Product Type:
Nut-based and precision fermentation platforms demand the heaviest upfront bioreactor and aging facility investments, while commodity protein isolates run on repurposed dairy processing equipment.
- Nut-Based:Cashew and almond matrices require extended fermentation cycles and temperature-controlled aging rooms to develop complex flavor profiles. German premium grocers and North American specialty retailers concentrate procurement here, though Vietnam-India supply concentration creates input cost vulnerability.
- Pea Protein-Based:Enzymatically modified isolates achieve melt characteristics through extrusion and shear-cell processing rather than fermentation. Quick-service pizza chains in the United States are accelerating adoption as price parity with dairy approaches within foodservice channels.
- Soy-Based:Mature processing infrastructure supports economy-tier positioning across Asian retail markets.
- Coconut-Based:Fat-dependent formulations dominate shredded and slice applications despite Southeast Asian weather-driven margin volatility.
- Rice-Based:Hypoallergenic positioning captures niche demand from multi-allergen households.
- Others:Emerging protein sources including oat and fava bean remain in pilot-scale production.
Nut-based formats absorb the bulk of installed artisan capacity; pea protein-based production is expanding most quickly.
Form:
Form factor selection directly shapes packaging automation requirements and cold-chain logistics intensity, with spreadable formats demanding the most sophisticated emulsion stability engineering.
- Block:Aged and cultured varieties require months-long fermentation protocols and humidity-controlled storage infrastructure. European retail channels dedicate expanding linear footage to these formats as flexitarian households reserve block purchases for entertaining occasions.
- Spreadable:High-shear processing and hydrocolloid stabilization systems enable creamy textures without aging investment. Daily consumption rotation among lactose-intolerant and health-conscious segments drives household penetration in German discounters.
- Slices:Precision thickness control and individual packaging automation support sandwich manufacturing integration.
- Shredded:Anti-caking coatings and moisture barriers address foodservice operational requirements.
- Powder:Spray-dried formats serve bakery and sauce manufacturing with extended shelf stability.
- Cubes:Snacking-oriented portioning targets institutional catering and convenience retail.
Block formats command the highest unit margins; spreadable applications are climbing the fastest.
Application:
Foodservice procurement operates on specification-driven tender processes with stringent melt and stretch performance requirements, while household channels reward flavor innovation and packaging convenience.
- Foodservice:Permanent menu architecture at quick-service restaurants demands consistent melt behavior across holding equipment. North American pizza chains specify specialized formulations that withstand conveyor oven temperatures without oil separation.
- Household Consumption:Subscription replenishment models and direct-to-consumer channels capture recurring revenue through flavor variety rotation. Miyoko's Creamery leverages membership data to pipeline new product development.
- Bakery:Lamination-stable fats and browning-compatible proteins address croissant and pastry applications.
- Snacking:Portion-controlled formats with extended ambient stability target convenience retail.
- Catering:Bulk formats with neutral flavor profiles support customizable buffet presentations.
- Institutional Use:College and corporate dining contracts prioritize cost-controlled nutrition compliance.
Foodservice channels lock in the largest volume commitments; household direct-to-consumer is gaining share fastest.
Customer Type:
Allergen sensitivity and ethical motivation create divergent price elasticity profiles, with medical necessity segments accepting substantial premiums over lifestyle-driven purchasers.
- Lactose Intolerant:Medical necessity drives consistent repurchase regardless of price premium. European REACH labeling frameworks accelerate clean-label reformulations as manufacturers target this segment's ingredient transparency demands.
- Flexitarians:Occasional dairy reduction without complete elimination creates rotation opportunities across multiple protein bases. German supermarket data indicates this segment concentrates volume in convenience-oriented packaging sizes.
- Vegans:Ethical consistency requirements support premium positioning and artisan brand loyalty.
- Health Conscious:Nutritional density and clean-label claims drive purchase decisions.
- Allergic Consumers:Multi-allergen avoidance necessitates dedicated facility certification.
- Ethical Shoppers:Sustainability certifications and carbon footprint disclosures influence selection.
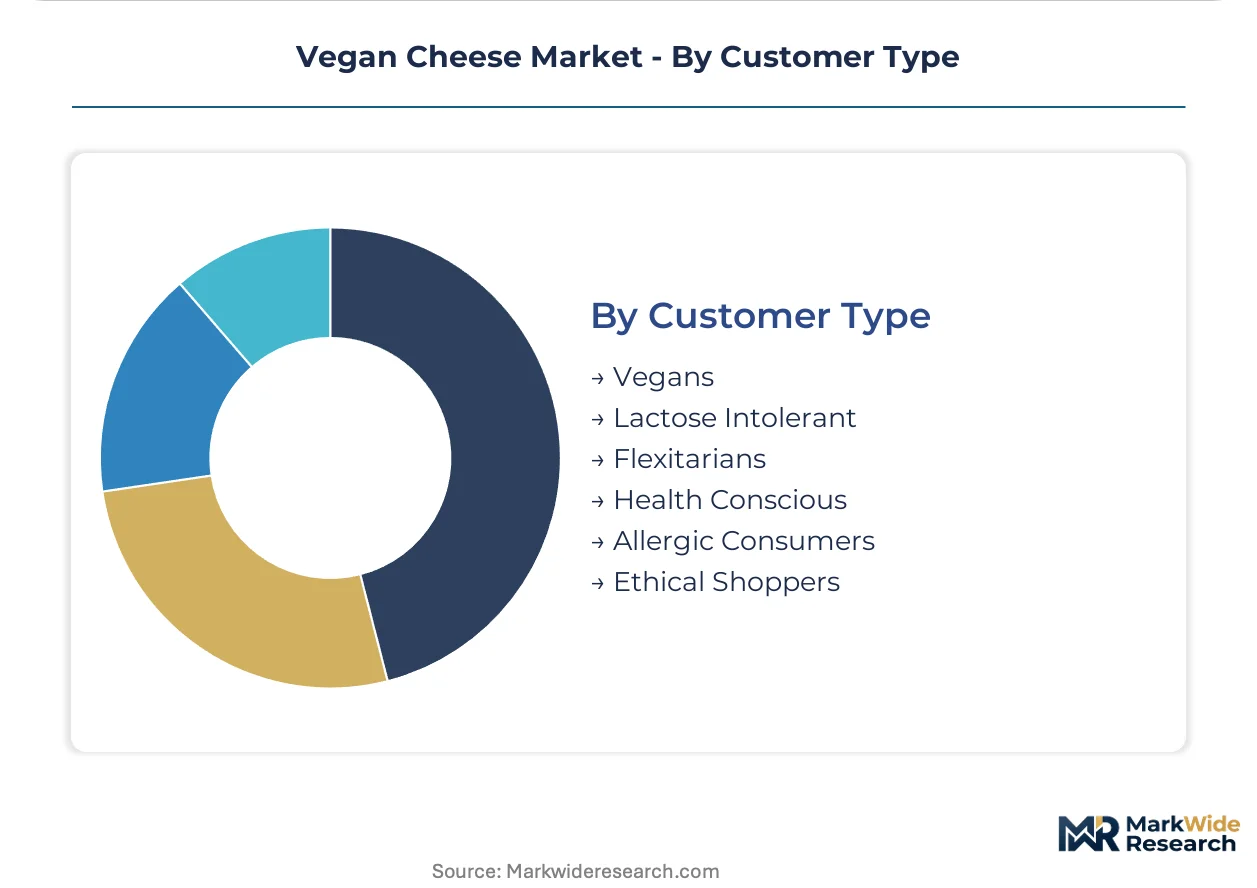
Lactose-intolerant households generate the most predictable demand; flexitarian adoption is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in cashew-processing hubs while consumption surges in retail markets with maturing plant-based food cultures. Manufacturing gravitates toward Vietnam and India for nut-based inputs, yet demand acceleration centers on Germany, the United States, and select European markets where discounters dedicate expanding shelf space.
United States
Quick-service restaurant chains embed plant-based cheese into permanent menu architecture, driving foodservice procurement volume. FDA labeling standards govern ingredient disclosure and positioning claims, constraining novel fermentation-derived formulations. California's Bay Area hosts clustered precision fermentation startups advancing dairy-identical protein production.
Germany
Discounters and premium grocers allocate expanding linear footage to fermented plant-based alternatives, concentrating household demand. EFSA novel food assessments shape approval timelines for innovative ingredients entering European markets. Berlin-Brandenburg anchors multiple vegan cheese production facilities serving domestic retail and export channels.
India
Domestic cashew processing infrastructure stabilizes input costs for premium-tier global suppliers despite climate volatility elsewhere. FSSAI plant-based dairy analog regulations remain under development, freezing import licensing and domestic investment timelines. Maharashtra and Karnataka host established nut-processing clusters supplying international vegan cheese manufacturers.
United Kingdom
Flexitarian households rotate toward spreadable formats for daily consumption, concentrating volume in convenience-oriented packaging. REACH labeling frameworks accelerate clean-label reformulations targeting ingredient transparency demands. London's foodservice sector integrates plant-based cheese options across quick-service and casual dining channels.
Canada
Foodservice operators in college and corporate dining contracts prioritize cost-controlled nutrition compliance with plant-based alternatives. Health Canada maintains novel food assessment protocols for fermentation-derived ingredients. Ontario's Greater Toronto Area clusters retail distribution hubs serving North American markets.
Vegan Cheese Market Key Industry Players
Capital-heavy producers compete with asset-light designers across divergent manufacturing models in the vegan cheese sector. Nut-based artisan manufacturers operate aging facilities and temperature-controlled infrastructure, while pea protein formulators leverage repurposed dairy processing equipment for scale. Three archetypes dominate: fermentation-forward precision specialists, commodity protein mass-market suppliers, and hybrid direct-to-consumer brands. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure bioreactor access and retail distribution.
Within the direct-to-consumer archetype, Miyoko's Creamery exemplifies membership-driven recurring revenue models, while Violife represents broad retail distribution across multiple continents. Daiya anchors foodservice channel positioning with specialized formulations. These three occupy distinct competitive vectors: Miyoko's exemplifies premium artisan positioning, Violife represents mass-market scalability, and Daiya captures institutional procurement relationships.
| Leading Market Players |
|---|
| Kite Hill |
| Treeline |
| Miyoko's Creamery |
| Go Veggie |
| Tofutti |
| Violife |
| Follow Your Heart |
| Dreamfarm |
| Daiya |
| Others |
Cost & Logistics Intelligence
Fermentation microbiologist clusters in California's Bay Area and Berlin-Brandenburg anchor production cost structures, with labor-rate differentials between these hubs widening spreads between artisan premium tiers and commodity-standard offerings.
Pricing Analysis
Margin tightening in nut-based tiers reflects Vietnam-India cashew supply concentration and extended aging facility depreciation. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein base complexity and fermentation protocol length. Price differentiation hinges on certification grade (EFSA novel food approval status) and brand heritage. Foodservice buyers exhibit lowest price sensitivity due to specification-driven procurement, while German discounter shoppers drive cost-down pressure through volume concentration.
Supply Chain Analysis
Cashew supply rests on Vietnamese and Indian processing infrastructure, with coconut oil feedstock drawing from Indonesian and Philippine production clusters. Pea protein isolate sources from North American and European extraction facilities. Single-source vulnerability concentrates in Southeast Asian fat inputs exposed to weather-driven commodity volatility. Distribution runs through temperature-controlled cold-chain networks serving retail grocery and foodservice channels, with direct-to-consumer subscription models bypassing traditional slotting-fee structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial bioreactor capacity for precision fermentation proteins constrains supply expansion, propping pricing power for incumbent producers with secured manufacturing slots.
For Market Incumbents: Acquire fermentation facility capacity in Germany and California to preempt pea protein displacement of nut-based positioning. Secure backward integration into cashew processing clusters in Maharashtra and Karnataka before climate volatility disrupts input costs. Defend against precision fermentation entrants by accelerating EFSA pre-submission consultations for novel ingredient decks. For New Entrants and Emerging Players: The mid-tier price-point gap between Violife's mass-market positioning and Miyoko's premium subscription model opens white-space in German retail discounters and North American college dining contracts. Target spreadable formats for lactose-intolerant households seeking daily rotation convenience. Pursue co-manufacturing partnerships with repurposed dairy processors to bypass capital-heavy bioreactor requirements. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid direct-to-consumer brands possessing subscription data pipelines and regulatory pre-approval assets given accelerating EFSA assessment queues. Long-term viability favors precision fermentation convergence plays integrating microbial dairy proteins with plant-fat matrices. Watch FSSAI plant-based dairy analog finalization as inflection trigger for Indian market access and import licensing normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Commercial bioreactor capacity for dairy-identical proteins addresses casein mimicry limitations in high-heat applications. |
| Direct-to-Consumer Subscription Launch | Membership models bypass retail slotting fees and capture flavor development data from Miyoko's Creamery archetype. |
| EFSA Pre-Submission Consultation | Early regulatory engagement compresses novel food approval timelines for fermentation-derived ingredients. |
| Cashew Processing Backward Integration | Upstream control over Vietnam-India supply clusters stabilizes input costs against climate volatility. |
| Foodservice Channel Expansion | Permanent menu architecture at quick-service restaurants locks in volume commitments through specialized melting formulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with vegan cheese brand managers, fermentation facility operators, retail category buyers, foodservice procurement directors, and regulatory affairs specialists combined with FDA labeling guidance documents, EFSA novel food assessment registers, FSSAI draft notifications, and REACH framework updates. Bottom-up production capacity modeling triangulated against top-down retail velocity estimates from Nielsen and Circana audit data.
Data-stream reconciliation across protein base production volumes, form factor packaging automation rates, and channel-specific pricing surveys generated consistent outputs across the analysis window. Segmentation dimensions modeled include protein source technology, form factor packaging requirements, application channel, and customer motivation archetype. CAGRs derived from elasticity-adjusted demand curves incorporating flexitarian adoption rates and foodservice menu permanency shifts.
Inputs from EFSA pre-submission protocols and FSSAI draft standards were available through the study window; gaps in precision fermentation commercial scale-up timelines introduce uncertainty bands around hybrid product launch schedules. Forecasts reflect documented assumptions on regulatory approval velocity and consumer sensory acceptance thresholds. A small set of named triggers—FSSAI finalization, EFSA queue clearance rates, and Southeast Asian weather patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
Lactose-Free Milk Market
Dairy Alternatives
North America Non-Dairy Ice Cream Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Hemp Milk Market
Dairy Alternatives
Coconut Milk and Cream Market
Dairy Alternatives
Soy Milk Powder Market
Dairy Alternatives
United Kingdom Dairy Alternatives Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Vegan Ice Cream Market