
 Cheese Analogue Market | 2026-2036
Cheese Analogue Market Size, Share, and Industry Trends Forecast 2026-2036
Cheese Analogue Market Intelligence
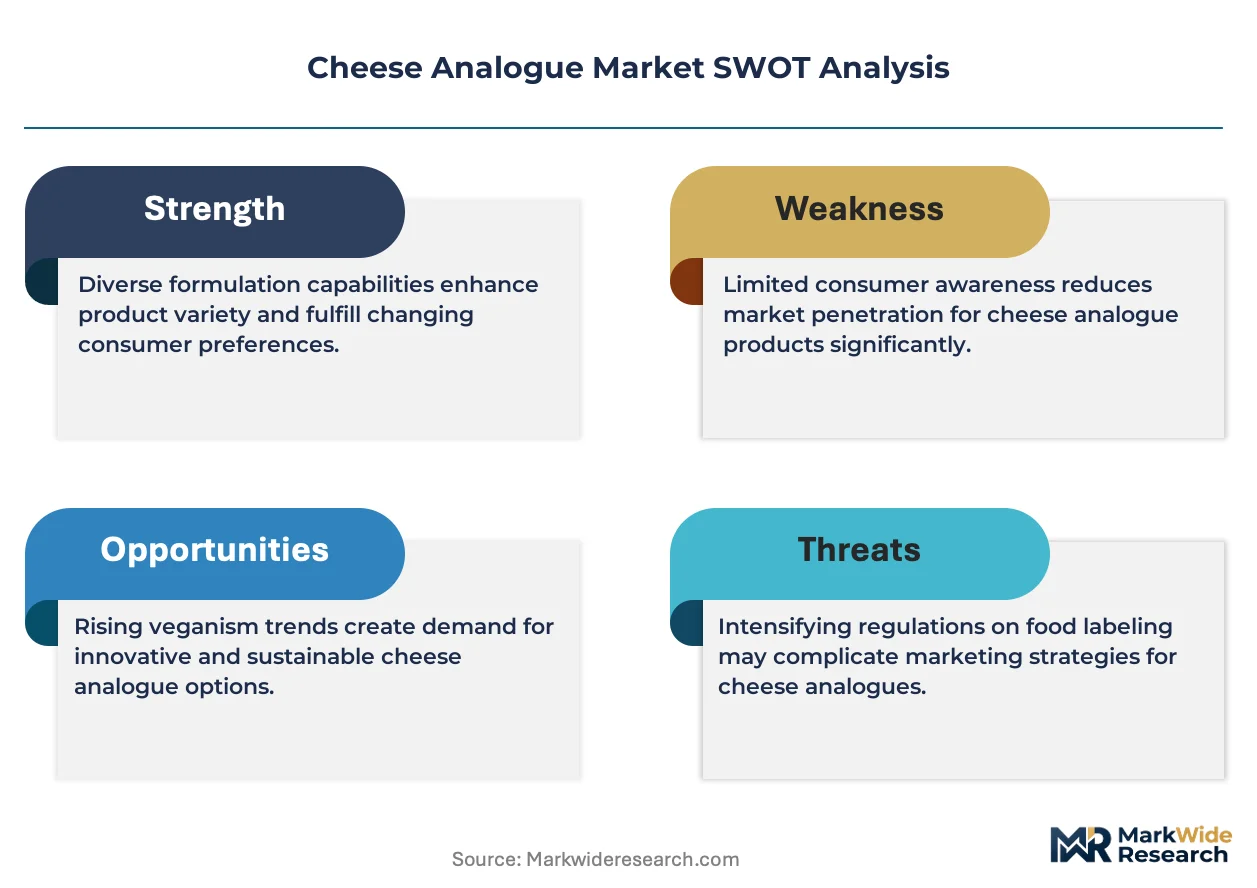
Asia-Pacific is tilting toward expanded casein analogue production as food manufacturers seek cost-stable cheese alternatives for processed foods. Ingredion leverages its ingredient formulation depth to supply modified starches that replicate melt functionality in pizza applications. GOOD PLANeT Foods anchors its position through coconut oil-based mozzarella designed specifically for foodservice grating and shredding. Daiya Foods differentiates via allergen-free formulations that exclude both soy and nuts, capturing specialty retail and gourmet restaurant channels.
Cheese analogues are engineered food products designed to replicate the sensory, functional, and nutritional properties of natural cheese through controlled combinations of proteins, fats, starches, and emulsifiers, typically achieving 30-50% cost reduction against dairy equivalents while maintaining standardized melt profiles critical to industrial food production. Their primary commercial purpose centers on delivering price-stable, shelf-consistent ingredients for high-volume food manufacturing and foodservice operations where dairy price volatility disrupts margin planning. Mozzarella analogue dominates volume flows into pizza and ready meals, where stretch and browning specifications are tightly calibrated. Plant-based proteins represent the fastest-growing ingredient source as coconut oil and pea protein formulations displace earlier-generation soy-dominant recipes in retail chains. Casein-based analogues retain margin concentration in bakery and packaged foods where European manufacturers prioritize melt stability over clean-label positioning.
FDA standards of identity for cheese products in the United States restrict "cheese" labeling on analogue products, pushing manufacturers toward "cheese alternative" or "plant-based" nomenclature that reshapes retail shelf positioning and consumer search behavior. EFSA and EMA frameworks govern novel protein safety assessments and additive approvals for European analogue launches, creating a dual-track compliance burden for exporters seeking cross-Atlantic distribution. BIS certification requirements in India add another layer for ingredient sourcing and label claims. Stakeholders must monitor how evolving protein fractionation technologies and shifting enforcement of dairy-term protections in key jurisdictions will reshape competitive access and product positioning decisions.
Market Dynamics
The cheese analogue market pivots on dairy price volatility that forces food manufacturers toward cost-stable ingredient sourcing. This structural pressure intensifies as quick-service restaurants and pizza chains expand procurement of mozzarella analogues to protect margin predictability.
Growth Catalysts
- EU Farm to Fork Strategy:Tightened labeling requirements for dairy alternatives accelerate clean-label formulation investments by European food manufacturers seeking compliant positioning.
- Foodservice procurement concentration:Pizza chains and quick-service restaurants now standardize analogue specifications for stretch and browning consistency across multi-location operations.
- Pea protein fractionation:Advances in protein extraction technology enable functional cheese alternatives that replicate dairy melt profiles without soy or allergen liabilities.
Market Restraints
- Casein supply concentration:European casein analogue production depends on concentrated dairy protein processing capacity in Germany and France, creating input vulnerability.
- FDA standards of identity:United States restrictions on "cheese" labeling force costly nomenclature repositioning and retail shelf reclassification.
- Coconut oil price cycles:Plant-based analogue margins compress when tropical oil markets spike, undermining the cost-stability value proposition.
Strategic Opportunities
- Asia-Pacific casein expansion:Food manufacturers in Southeast Asia seek localized analogue production to reduce import dependency and currency exposure.
- Modified starch functionality:Ingredient suppliers can capture pizza-application share by delivering tailored melt-replication systems that reduce formulation complexity.
- Allergen-free channel positioning:Retail and gourmet restaurant segments reward soy-free, nut-free formulations with premium placement and dedicated shelf space.
Industry Challenges
- Protein technologist scarcity:Formulation science expertise in dairy-protein mimicry concentrates among a limited pool of specialists, constraining R&D velocity.
- Dual-track compliance burden:Exporters must simultaneously satisfy FDA nomenclature rules and EFSA novel-protein assessments, extending launch timelines.
- Legacy equipment retrofit costs:Dairy processing lines require modification to handle analogue viscosity and temperature profiles, demanding capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheese Analogue Market |
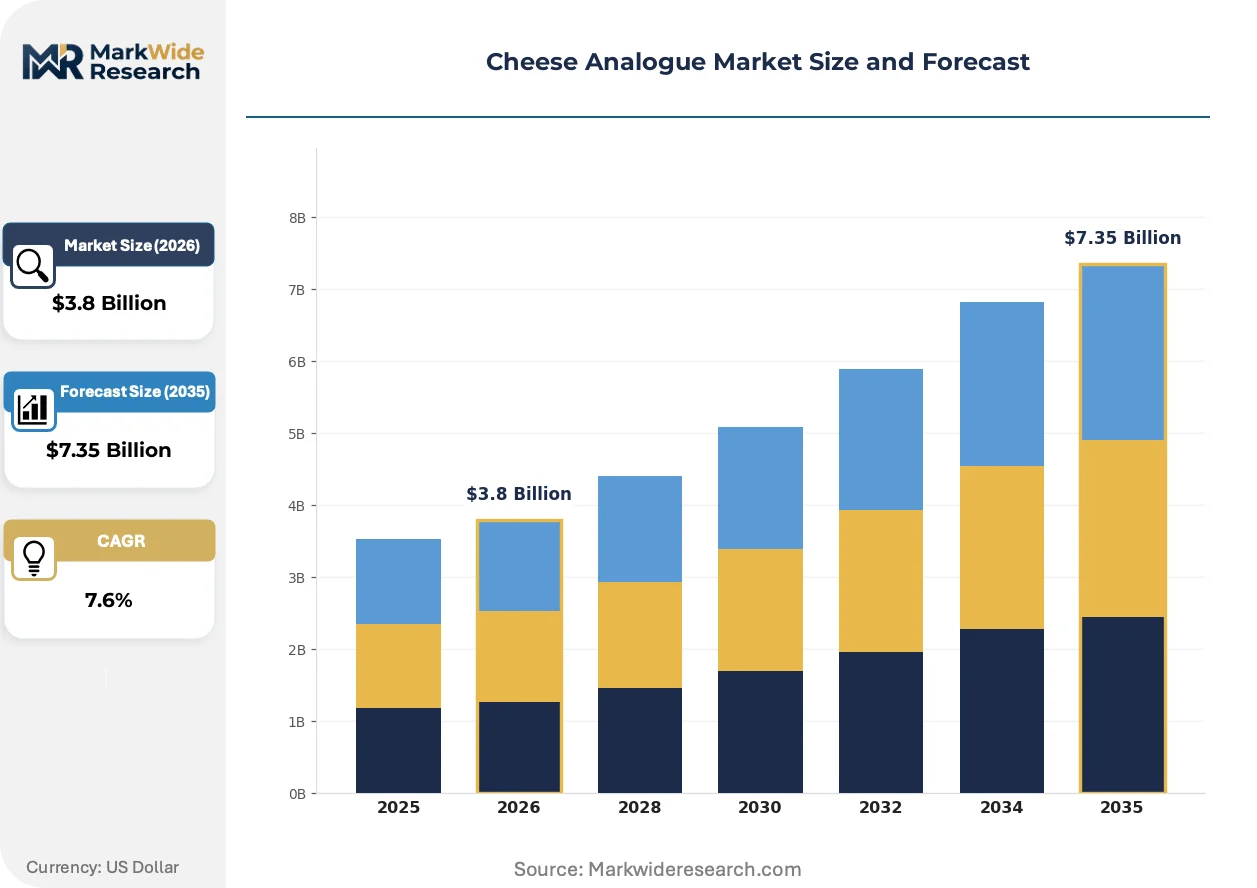
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheddar, Mozzarella, Processed, Cream Cheese, Provolone Ingredient Source: Plant-Based Proteins, Casein, Soy, Coconut Oil, Starch Application: Foodservice, Packaged Foods, Snacks, Bakery, Ready Meals End User: Retail Chains, Food Manufacturers, Catering Services, Gourmet Restaurants |
| Companies Covered | Follow Your Heart, GOOD PLANeT Foods, Flora Food Group, Tofutti Brands, Danone, Daiya Foods, Kite Hill, Ingredion, Miyoko's Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheese Analogue Market Strategic Shifts & Innovations
Ingredient science and regulatory labeling pressure are converging to reshape how cheese alternatives achieve functional parity with dairy. These forces drive divergence between cost-optimized industrial formulations and clean-label retail positioning.
Pea-coconut oil hybrid formulations are hybridizing the plant-based analogue segment by combining protein functionality with fat-crystal structuring. Pizza manufacturers in Germany and the United States adopt these systems fastest for foodservice applications. The technology is hybridizing previously separate soy-dominant and starch-heavy recipe architectures into unified platforms that satisfy both melt-performance and allergen-avoidance requirements.
EFSA novel-protein safety frameworks are tightening pre-market assessment requirements for European analogue launches. Manufacturers must now document protein digestibility and allergenicity profiles before commercialization. Bakery and packaged-food segments face the steepest compliance burden, with some reformulating toward casein-based systems to bypass novel-protein classification.
Foodservice procurement teams now specify performance-based ingredient contracts that penalize melt-profile deviation rather than accepting commodity-grade analogue. This behavior compresses supplier qualification cycles and concentrates volume among technically capable formulators. The shift is most visible in Germany, where plant-based penetration in foodservice exceeds other European markets and buyers demand batch-to-batch functional consistency.
Cheese Analogue Market Segmentation
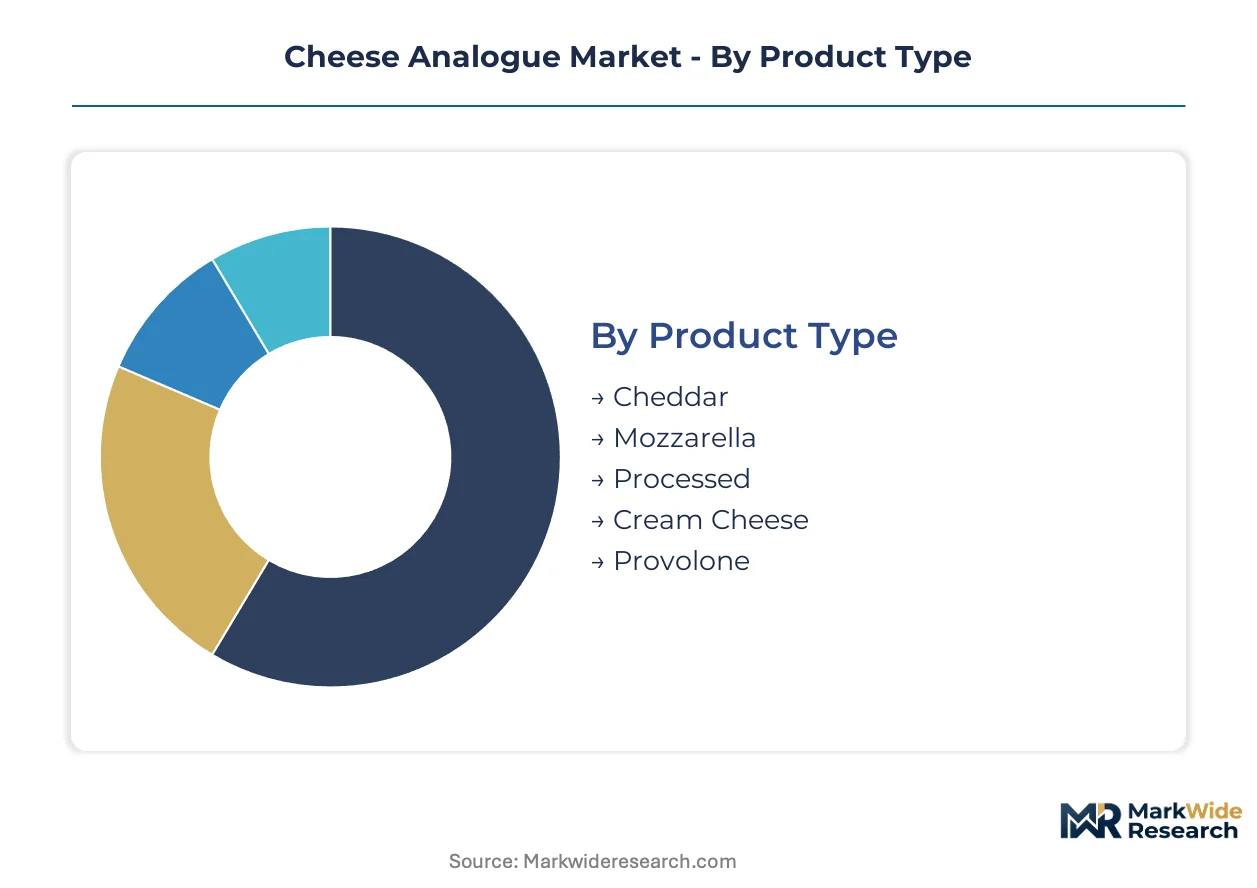
Cheese analogue manufacturers engineer distinct formulations around melt profiles, protein stability, and cost targets that vary sharply across pizza chains, industrial bakeries, and retail channels. Segmentation reveals where formulation investments concentrate and which ingredient architectures command procurement priority.
Product Type:
Product type segmentation tracks the use-case spectrum from stretch-critical pizza applications to spreadable retail formats, with each variant demanding specific fat-crystal structures and protein networks.
- Mozzarella:Engineered for stretch coefficient and browning consistency under conveyor ovens. Pizza chains in Germany and the United States standardize procurement specifications around this variant to protect margin predictability against dairy price swings.
- Cheddar:Dominates processed-food applications where sharp flavor replication and sliceability matter. Packaged-food manufacturers in Southeast Asia source this type most heavily for ready-meal cheese sauces.
- Processed:Shelf-stable blocks for industrial slicing operations. Catering services favor this format for portion-control reliability.
- Cream Cheese:Spreadable emulsions targeting bakery fillings and bagel applications. Retail chains in North America stock this variant for private-label lines.
- Provolone:Smoked and unsmoked variants for sandwich manufacturing. Italian-style deli processors specify this type for sub-chain supply contracts.
The dominant share belongs to Mozzarella, while Cream Cheese is closing the gap fastest.
Ingredient Source:
Ingredient source segmentation rotates through cost tier, separating commodity starch systems from premium protein formulations that command foodservice validation.
- Casein:Dairy-derived protein fractions delivering authentic melt and stretch. European bakery and packaged-food manufacturers prioritize this source for EFSA-compliant positioning that avoids novel-protein classification.
- Plant-Based Proteins:Pea and fava protein isolates formulated with coconut oil for clean-label positioning. German foodservice buyers drive fastest adoption here, with pizza chains specifying allergen-free performance contracts.
- Soy:Legacy protein base with established supply chains but declining retail preference due to allergen labeling. Still anchors volume in Asian industrial applications.
- Coconut Oil:Fat-crystal structuring agent for plant-based melt replication. Price volatility in tropical oil markets compresses margins cyclically.
- Starch:Modified tapioca and potato starches for cost-optimized processed cheese. Ingredion and similar suppliers tailor viscosity profiles for specific extrusion equipment.
Casein retains the largest volume position, though Plant-Based Proteins are expanding most quickly as clean-label pressure intensifies.
Application:
Application segmentation maps customer type, distinguishing high-volume industrial buyers from specification-driven foodservice operators.
- Foodservice:Performance-contract procurement where melt-profile deviation triggers penalties. Quick-service restaurants and pizza chains dominate demand, with Germany showing highest plant-based penetration.
- Packaged Foods:Industrial cheese sauces, slices, and spreads for retail distribution. Manufacturers prioritize casein-based systems for EFSA compliance and shelf stability.
- Ready Meals:Single-serve cheese components for frozen and chilled dinner platforms. European processors specify standardized browning to match consumer expectations.
- Bakery:Fillings and toppings for industrial croissant and pastry production. Melt stability under oven spring conditions drives formulation requirements.
- Snacks:Powdered and sauced formats for extruded and puffed products. Cost minimization dominates procurement criteria here.
Foodservice commands the dominant procurement volume, while Ready Meals are gaining share fastest as chilled dinner platforms expand.
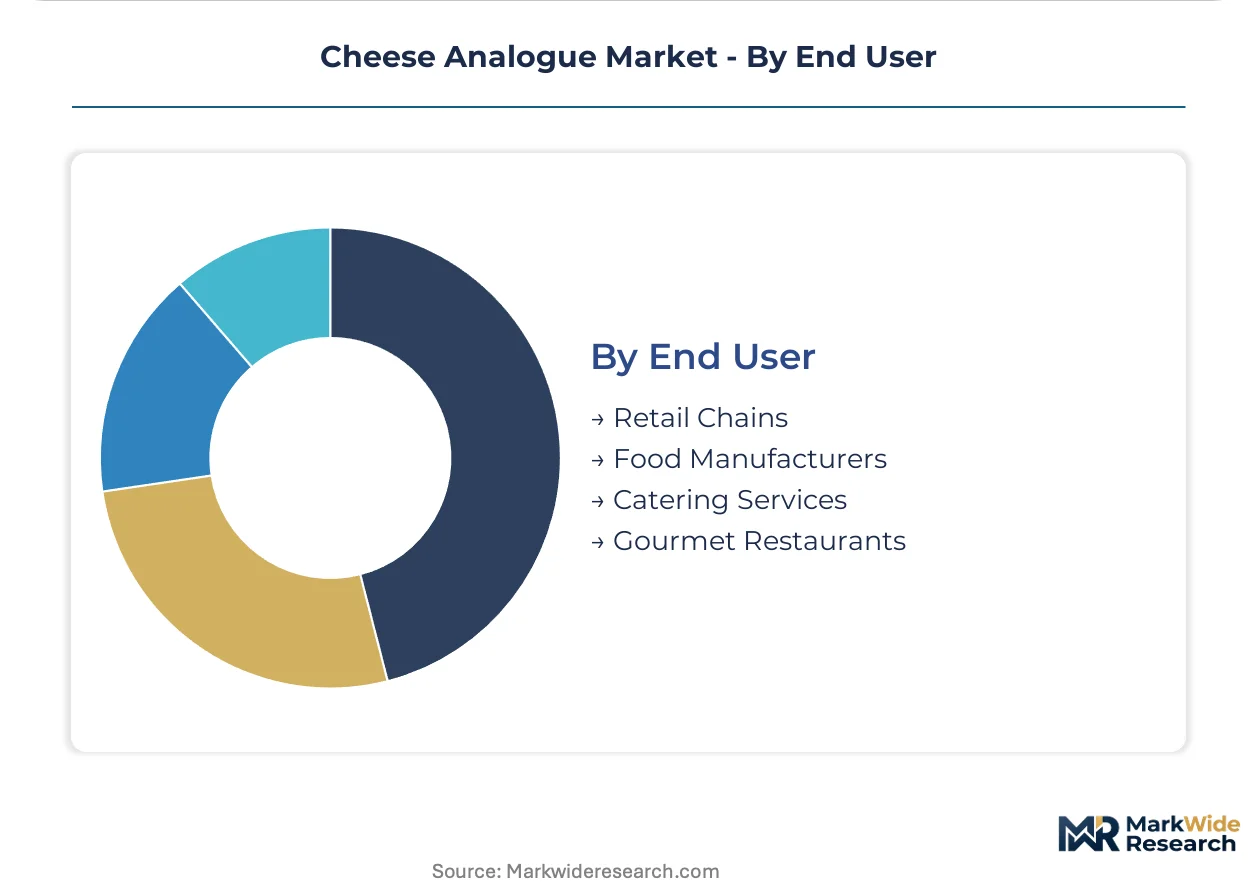
End User:
End user segmentation follows supply concentration, tracking how procurement power aggregates among scaled buyers versus fragmented channels.
- Food Manufacturers:Industrial-scale buyers with dedicated formulation teams and multi-year supply agreements. These stakeholders drive standardization of melt and stretch specifications across production facilities.
- Retail Chains:Private-label developers seeking clean-label positioning for plant-based dairy aisles. Allergen-free claims command premium shelf placement.
- Gourmet Restaurants:Small-volume buyers prioritizing flavor authenticity and artisanal positioning. Pea-coconut oil hybrids penetrate here as chefs test plant-based menu items.
- Catering Services:Volume operators requiring portion consistency and holding stability under buffet conditions. Processed blocks dominate this channel.
Food Manufacturers hold the dominant procurement position, while Gourmet Restaurants are climbing the fastest as plant-based menu expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes cheese analogue through foodservice channels at rates exceeding other European markets, while the United States channels demand through pizza chains seeking margin protection against dairy volatility. China and India industrialize analogue production for processed-food manufacturing. Brazil's quick-service sector drives South American adoption patterns.
United States
Quick-service restaurants and pizza chains standardize mozzarella analogue procurement to shield margins from dairy price swings. FDA standards of identity restrict "cheese" labeling, forcing manufacturers toward "plant-based" nomenclature that reshapes retail positioning. Chicago and Dallas-Fort Worth anchor foodservice distribution networks where procurement teams specify melt-profile consistency across multi-location operations.
Germany
Plant-based penetration in foodservice exceeds other European markets, with buyers demanding batch-to-batch functional consistency. The EU Farm to Fork Strategy tightens labeling requirements for dairy alternatives, accelerating clean-label formulation investments. Bavaria concentrates casein processing capacity where manufacturers prioritize EFSA-compliant positioning over novel-protein classification.
China
Food manufacturers in the Yangtze River Delta expand localized analogue production to reduce import dependency and currency exposure. GB standards and SAMR frameworks govern food additive approvals and protein safety assessments for domestic launches. Shanghai-based industrial clusters integrate modified starch systems into processed-cheese formulations for bakery and snack applications.
India
BIS certification requirements add compliance layers for ingredient sourcing and label claims in analogue manufacturing. Packaged-food processors in Maharashtra and Gujarat source cheddar-type analogues most heavily for ready-meal cheese sauces. Mumbai-Pune industrial corridors develop casein-based production to serve domestic bakery segments prioritizing melt stability.
Brazil
Quick-service restaurant chains drive analogue adoption as dairy price volatility disrupts margin planning in the foodservice sector. ANVISA governs novel protein safety assessments and additive approvals for commercial launches. São Paulo anchors South American procurement concentration where pizza chains specify stretch and browning performance in multi-year supply agreements.
Cheese Analogue Market Key Industry Players
Capability concentration sits with specialized formulators mastering protein-fractionation technology; scale advantage sits with diversified ingredient suppliers leveraging existing distribution infrastructure. The market structures around three tiers: multinational ingredient houses with formulation depth, dedicated analogue specialists with foodservice validation, and private-label manufacturers serving retail chains. Competitive moves center on strategic partnerships between protein suppliers and finished-product manufacturers, plus capacity expansion into Asia-Pacific production nodes.
Within the plant-based specialist tier, GOOD PLANeT Foods and Daiya Foods exemplify divergent positioning strategies. GOOD PLANeT Foods anchors its market presence through coconut oil-based mozzarella systems designed for foodservice grating and shredding applications. Daiya Foods occupies a position defined by allergen-free formulations excluding both soy and nuts, capturing specialty retail placement and gourmet restaurant channel access. Ingredion represents the ingredient-supplier archetype, leveraging modified starch formulation depth to supply melt-replication systems for pizza manufacturing applications.
| Leading Market Players |
|---|
| Follow Your Heart |
| GOOD PLANeT Foods |
| Flora Food Group |
| Tofutti Brands |
| Danone |
| Daiya Foods |
| Kite Hill |
| Ingredion |
| Miyoko's Creamery |
| Others |
Cost & Logistics Intelligence
Coconut oil price volatility determines both pricing tier spreads and supply chain shape in cheese analogue manufacturing, compressing plant-based formulation margins when tropical commodity markets spike while simultaneously pushing procurement teams toward multi-source fat sourcing strategies and long-term contracting instruments.
Pricing Analysis
German foodservice buyers encounter the widest price spreads, with casein-based mozzarella analogues commanding premiums over starch-heavy formulations due to EFSA compliance positioning and melt-profile consistency guarantees. Three-tier pricing structure across premium, standard, and economy levels separates allergen-free pea-coconut systems from conventional soy-based recipes and commodity modified-starch blocks. Pricing pressure stems from coconut oil cyclicality, which undermines the cost-stability value proposition that drives analogue adoption. Quick-service restaurant chains exhibit highest price sensitivity, while gourmet restaurants tolerate premium positioning for clean-label credentials.
Supply Chain Analysis
Contract manufacturing concentration rests with European dairy protein processors in Bavaria and Normandy, where casein fractionation capacity anchors regional supply. Raw material flows draw from Indonesian and Philippine coconut oil plantations, Ukrainian and Argentine pea protein facilities, and modified starch operations in the US Midwest. Single-source vulnerability concentrates in tropical oil supply, where climate disruption and currency fluctuation propagate through formulation costs. Distribution runs through foodservice redistribution centers in Chicago, Frankfurt, and São Paulo, with direct industrial supply agreements bypassing wholesale channels for large-scale food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among multi-location pizza chains and quick-service restaurant groups, which now dictate performance-based procurement contracts that penalize functional deviation and compress supplier margins.
For Market Incumbents: Insulate formulation portfolios against coconut oil volatility by securing backward integration into pea protein processing or captive supply agreements with tropical oil cooperatives. Invest in EFSA pre-market dossier preparation to defend European positioning against novel-protein classification risks. Prioritize equipment retrofitting for batch-to-batch consistency validation, as foodservice procurement teams increasingly specify melt-profile penalties in multi-year agreements. For New Entrants and Emerging Players: Establish a beachhead in allergen-free retail channels where soy-free and nut-free claims command dedicated shelf space and premium placement. Target Southeast Asian industrial bakery segments, where localized production reduces import dependency and currency exposure for processors seeking EFSA-compliant casein alternatives. Lead with modified starch functionality partnerships that reduce pizza-manufacturer formulation complexity without requiring protein-fractionation expertise. For Investors and Strategic Acquirers: EU Farm to Fork Strategy implementation reshapes the acquisition landscape by elevating clean-label formulation capabilities above commodity-scale production assets. Long-term viability centers on protein-fractionation technology mastery and foodservice validation relationships rather than brand equity alone. Target acquisition archetypes include specialized formulators with documented EFSA novel-protein safety dossiers and established quick-service restaurant supply contracts. The signal to watch is enforcement tightening around dairy-term protections in key jurisdictions, which will accelerate compliant-positioning premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Pea Protein Fractionation Capacity Expansion | Reduces dependency on soy and coconut oil while capturing EFSA-compliant positioning in European bakery segments. |
| Modified Starch Functionality Partnerships | Ingredion and similar suppliers capture pizza-application share by delivering tailored melt-replication systems. |
| Allergen-Free Channel Positioning | Soy-free and nut-free formulations secure premium retail placement and gourmet restaurant access for specialized players. |
| Asia-Pacific Production Localization | Southeast Asian manufacturing reduces import dependency and currency exposure for industrial bakery customers. |
| Foodservice Performance Contracting | Multi-year agreements with melt-profile penalties concentrate volume among technically capable formulators. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with foodservice procurement directors, plant-based formulation scientists, quick-service restaurant supply chain managers, and dairy protein processing engineers. Secondary validation drew from FDA standards of identity filings, EFSA novel-protein safety assessments, BIS certification documentation, and food additive approval records. Trade customs data, SEC filings of diversified ingredient suppliers, and food manufacturing capex disclosures provided additional triangulation. Bottom-up volume modeling across ingredient source and application segments was cross-checked against top-down market sizing.
Calibration against historical analogue adoption curves in quick-service restaurant chains and pizza manufacturing sectors anchored the projection framework. Segmentation dimensions modeled include product type, ingredient source, application channel, and end-user concentration across the analysis window. CAGRs were derived from elasticity-adjusted demand curves incorporating dairy price volatility scenarios and clean-label penetration rates. Forecast inputs included coconut oil futures trajectory assumptions and EFSA enforcement intensity indices for dairy-term protections.
Stress conditions across tropical commodity price spikes, regulatory classification delays, and foodservice procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding protein-fractionation technology maturation and enforcement patterns for dairy alternative labeling. Quarterly review of coconut oil futures curves, EFSA novel-protein assessment queue lengths, and quick-service restaurant procurement contract terms is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Non-Dairy Creamer Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Camel Milk Products Market
Dairy Alternatives
North America Non-Dairy Milk Market
Dairy Alternatives
Coconut Yogurt Market
Dairy Alternatives
Asia-Pacific Non-Dairy Milk Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Non-Dairy Frozen Dessert Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Non-Dairy Cheese Market
Dairy Alternatives
Europe Almond Milk Market
Dairy Alternatives
Dry Yogurt Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market