
 United States Textured Vegetable Protein Market | 2026-2036
United States Textured Vegetable Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United States Textured Vegetable Protein Market Analytics
Plant-based meat alternatives within quick-service restaurant chains is expanding as a primary demand channel for textured vegetable protein in the United States. Archer Daniels Midland Company leverages its Midwest soy-processing infrastructure to supply bulk TVP to food manufacturers. Cargill Inc. competes through backward integration into North American soybean origination and crushing. Ingredion Inc. differentiates via clean-label ingredient systems that improve TVP's mouthfeel in finished applications.
Textured vegetable protein refers to defatted soy flour or concentrate extruded under heat and pressure to create fibrous, sponge-like structures that rehydrate to simulate meat texture. Typical protein content ranges from 50% to 70% on a dry basis, with extrusion temperature and shear rate determining final texture granularity. Granules and chunks lead volume within product-type segments due to their ubiquity in ground-meat analogs and restructured whole-muscle products. Meat alternatives anchor application-level demand, while protein supplements represent the fastest-growing application as sports-nutrition brands reformulate with plant isolates.
The FDA oversees TVP labeling under the Federal Food, Drug, and Cosmetic Act, while USDA-FSIS regulates its use in meat-product simulations, creating dual compliance exposure for manufacturers. California's Proposition 65 enforcement on heavy metals and acrylamide in processed plant proteins adds state-level testing burdens absent in other jurisdictions. Stakeholders must monitor whether FDA completes its plant-based dairy and meat labeling rulemaking, as finalized standards would reshape permissible marketing claims and reformulation priorities across the supply chain.
Market Dynamics
The United States textured vegetable protein market pivots on tightening dual-jurisdiction labeling standards, where FDA and USDA-FSIS overlapping authority forces manufacturers into parallel compliance pathways that reshape formulation priorities and marketing claims.
Growth Catalysts
- Quick-service restaurant procurement:Major chains are expanding plant-based menu lines, creating institutional demand pull for bulk TVP supply contracts that stabilize volume throughput for Midwest processors.
- California Proposition 65 enforcement:Heavy metal and acrylamide testing mandates, while burdensome, are accelerating clean-process investments that differentiate compliant suppliers in premium channels.
- High-moisture extrusion advancement:Next-generation extrusion technology is enabling whole-muscle texture simulation that closes the sensory gap with animal protein in restructured meat applications.
Market Restraints
- Soybean price volatility:Defatted soy flour input costs fluctuate with commodity futures, compressing processor margins during drought cycles in Illinois and Iowa growing regions.
- Midwest supply concentration:Crushing and extrusion capacity clusters along the Mississippi River corridor, creating single-point vulnerability to barge transport disruptions and regional weather events.
- FDA-USDA jurisdictional friction:Dual regulatory exposure for meat-analog manufacturers generates legal uncertainty that slows new product pipeline velocity and raises compliance overhead.
Strategic Opportunities
- Sports nutrition application expansion:Protein supplement brands are reformulating with textured soy isolates, opening higher-margin channels beyond traditional food manufacturing.
- Texas and Florida food-tech corridors:Underdeveloped extrusion infrastructure in Sun Belt states offers greenfield capacity for suppliers seeking geographic diversification from Midwest concentration.
- Clean-label ingredient system convergence:Binding technology paired with natural flavor masking is enabling shorter ingredient decks that qualify for retail premium positioning.
Industry Challenges
- Extrusion engineering talent scarcity:Specialized process engineers who optimize shear-rate and temperature profiles for texture granularity are concentrated at legacy Midwest processors, limiting new entrant scale-up velocity.
- Dual certification timeline compression:Manufacturers must secure both FDA facility registration and USDA-FSIS label approval for meat-analog products, extending time-to-market by six to twelve months versus single-jurisdiction categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Textured Vegetable Protein Market |
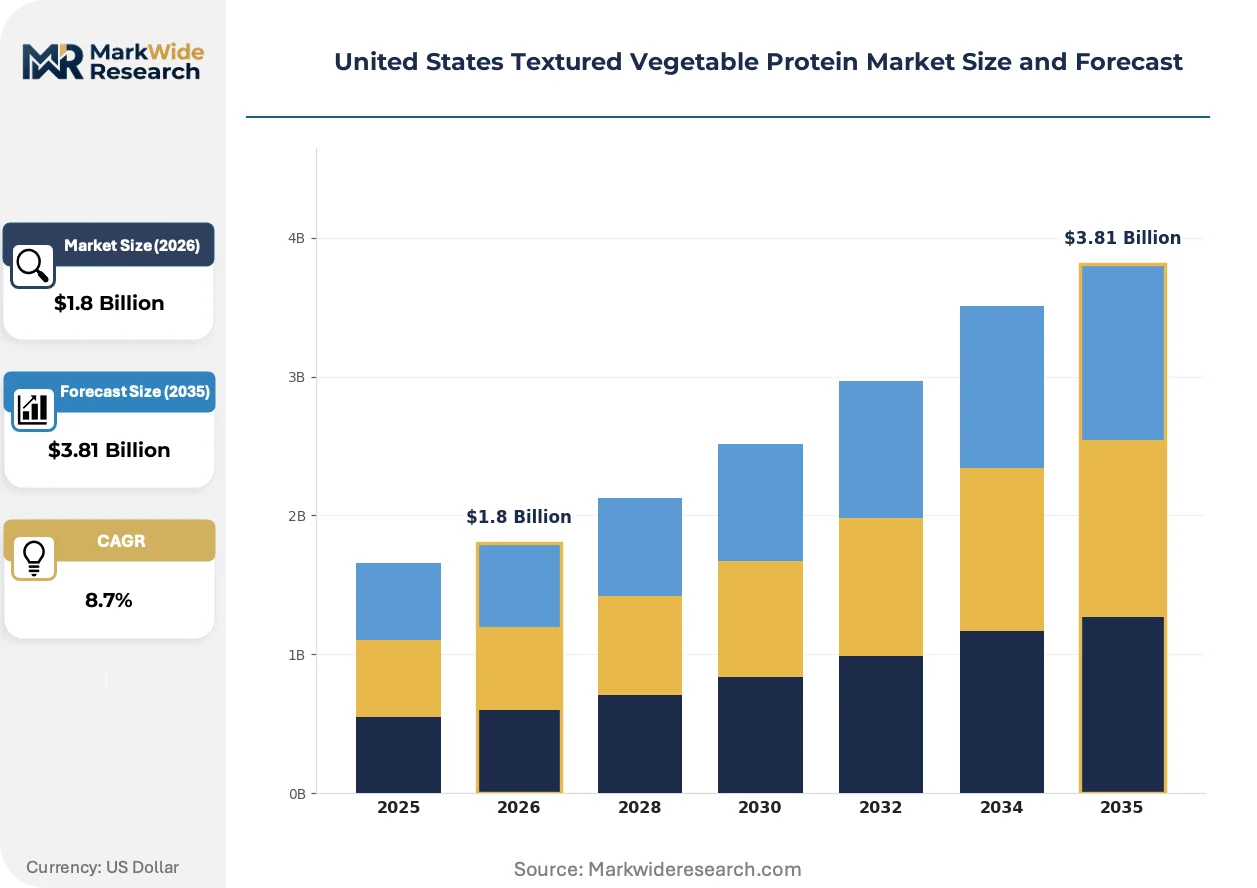
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Chunks, Flakes, Slices End User: Food Industry, Animal Feed, Nutraceuticals, Ready-to-Eat Meals Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale Application: Meat Alternatives, Snack Foods, Protein Supplements, Sauces |
| Companies Covered | Archer Daniels Midland Company, Cargill Inc., Ingredion Inc., The Scoular Company, International Flavors & Fragrances Inc., MGP Ingredients Inc., Axiom Foods Inc., AGT Food and Ingredients, Crown Soya Protein Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Textured Vegetable Protein Market Evolving Landscape
Extrusion technology convergence with precision fermentation is redefining protein texturization capabilities, while regulatory clarity efforts and shifting procurement models reshape competitive positioning across the value chain.
High-moisture extrusion is unifying thermal and mechanical processing into continuous systems that generate fibrous structures without intermediate drying steps. Food manufacturers serving the refrigerated meat-alternative segment are adopting these systems at pilot scale, with early installations in California's Bay Area food-tech cluster. The technology is unifying what were previously separate dry and wet texturization stages, collapsing capital requirements and enabling smaller-batch flexibility for premium product lines.
The FDA's pending plant-based meat labeling rulemaking is forcing reformulation investments as manufacturers anticipate stricter nutrient-disclosure and standardized-term requirements. Processors are front-loading R&D spending to secure compliant positioning before rule finalization, particularly for products containing TVP as the primary protein source. The rulemaking most affects Midwest bulk suppliers who must coordinate label databases across multiple downstream brand customers.
Direct-procurement relationships between quick-service chains and extrusion facilities are compressing traditional ingredient distributor roles. Large restaurant groups are negotiating toll-manufacturing agreements that specify texture parameters and lot-traceability standards, bypassing conventional food-ingredient distribution. This pattern is most visible in California and Texas, where regional chain headquarters proximity enables just-in-time supply coordination.
United States Textured Vegetable Protein Market Segmentation
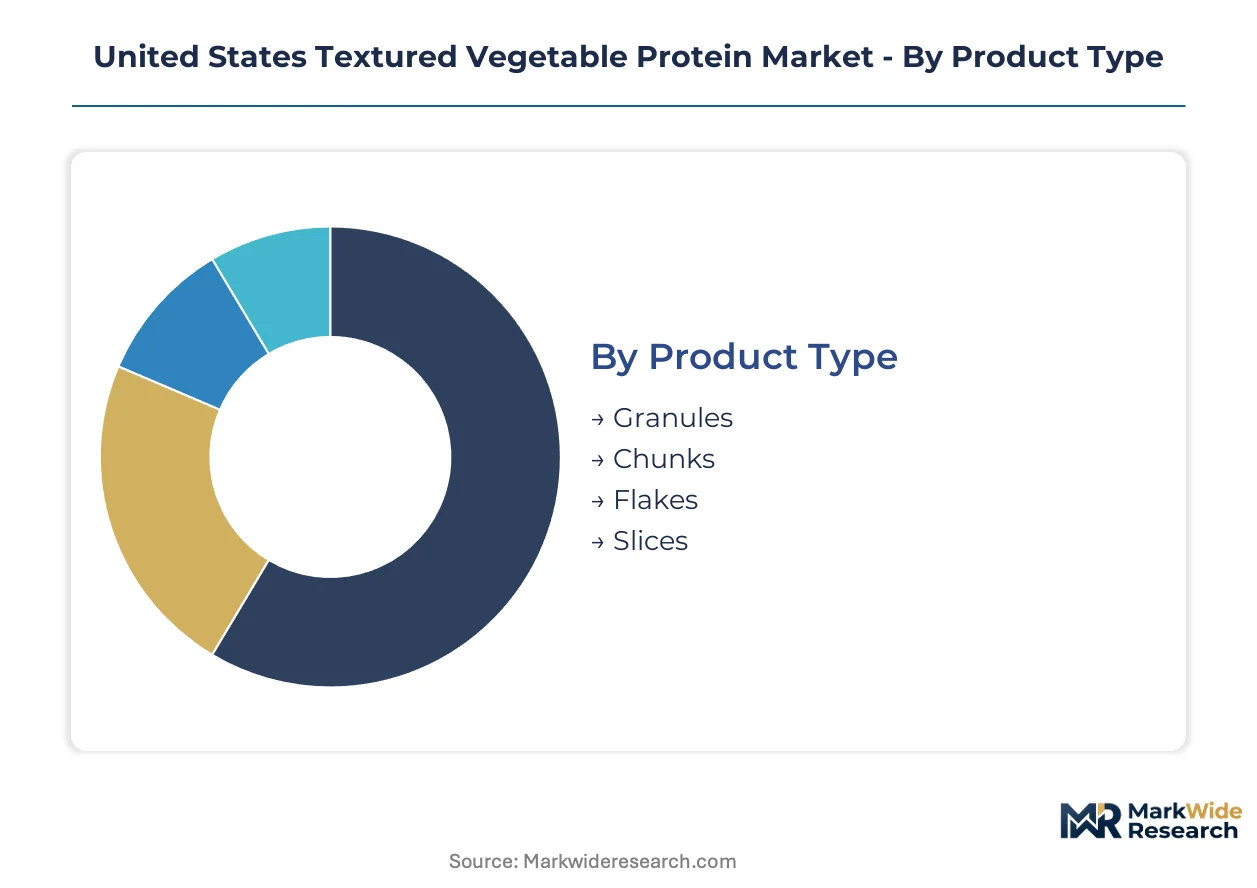
TVP's extrusion versatility creates distinct performance profiles across physical forms and end-use specifications. Manufacturers optimize shear-rate parameters differently for quick-service restaurant supply versus sports-nutrition applications. Segmentation clarity enables procurement teams to match texture granularity with specific rehydration requirements.
Product Type:
Upgrade cycles in extrusion equipment are pushing processors toward finer texture control, with older single-screw systems yielding to twin-screw configurations that expand the addressable granularity spectrum.
- Granules:Small, porous particles ranging 1-3mm that rehydrate rapidly in hot water or broth. Quick-service chains in California's Bay Area specify granules for ground-beef analogs where bite-size uniformity determines menu consistency. FDA labeling scrutiny on meat-simulation claims intensifies reformulation precision for this high-volume segment.
- Chunks:Larger fibrous structures 5-15mm that simulate whole-muscle texture after rehydration. Midwest soy processors supply chunks to frozen entrée manufacturers seeking striated mouthfeel in restructured chicken and pork alternatives. High-moisture extrusion advancement is compressing the sensory gap with animal protein here.
- Flakes:Thin, sheet-like structures with high surface-area-to-volume ratios for rapid sauce absorption. Food manufacturers in Texas incorporate flakes into shelf-stable meal kits where rehydration speed drives consumer satisfaction scores.
- Slices:Precut geometric forms engineered for direct substitution in deli-style applications. Premium positioning in health food stores commands price premiums when paired with clean-label ingredient decks.
Volume placements concentrate in Granules; the faster expansion belongs to Chunks.
End User:
Cost-tier stratification separates commodity bulk purchasers from premium channel stakeholders, with certification requirements and lot-traceability standards widening the procurement gap between segments.
- Food Industry:Manufacturers of meat alternatives, baked goods, and extended meat products constitute the foundational demand base. Illinois and Iowa crushing facilities prioritize food-grade extrusion runs that meet USDA-FSIS dual-jurisdiction standards for meat-simulation products.
- Animal Feed:Pet food and livestock nutrition formulators utilize lower-protein TVP grades as cost-effective amino acid sources. Pricing volatility in soybean futures directly compresses margin structures in this price-sensitive segment.
- Nutraceuticals:Protein isolate suppliers serving sports-nutrition brands demand 70%+ protein content with heavy-metal testing documentation. California Proposition 65 enforcement elevates compliance costs that filter into premium positioning.
- Ready-to-Eat Meals:Shelf-stable and frozen entrée producers specify moisture-optimized TVP for microwave-rehydration performance. Direct-procurement relationships with extrusion facilities are displacing traditional distributor roles here.
Food Industry anchors current throughput; Nutraceuticals is climbing the fastest.
Distribution Channel:
Customer-type bifurcation between institutional procurement teams and individual consumers reshapes packaging specifications, minimum order quantities, and technical service intensity across channel structures.
- Online Retail:Direct-to-consumer platforms serving home cooks and small-batch food entrepreneurs. Bulk bag sizes and rehydration instruction clarity determine return rates.
- Supermarkets:Mass-market retail placement requires branded packaging with prominent protein-content callouts. Slotting fees and promotional calendars strain working capital for emerging suppliers.
- Health Food Stores:Specialty retailers emphasizing organic certification and non-GMO verification. Clean-label positioning commands 15-30% price premiums over conventional channels.
- Wholesale:Food-service distributors and ingredient brokers supplying manufacturers. Lot-traceability documentation and certificate-of-analysis availability gate entry to qualified supplier lists.
Wholesale dominates institutional volume; Online Retail is gaining share fastest.
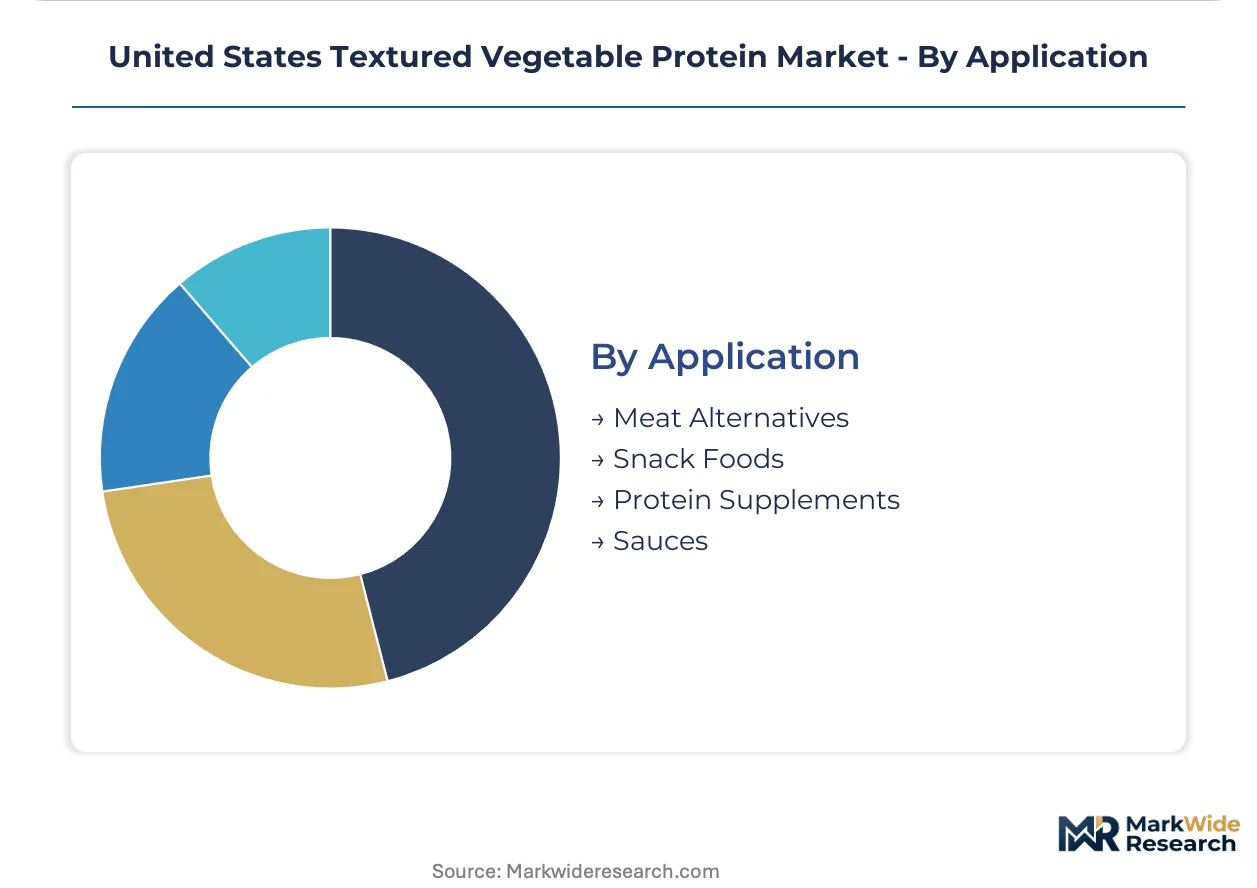
Application:
Supply concentration in Midwest extrusion corridors creates geographic dependency for meat-alternative applications, while protein supplement formulators seek geographic diversification to reduce single-point vulnerability.
- Meat Alternatives:The core application encompassing ground-meat simulations, restructured whole-muscle products, and extended meat formulations. Quick-service restaurant procurement contracts stabilize volume throughput for Iowa and Illinois processors.
- Snack Foods:Extruded puffs, crisps, and textured inclusions where TVP provides protein fortification and structural integrity. Flavor-masking technology investments determine palatability thresholds.
- Protein Supplements:Powder and bar applications requiring ultra-fine grind sizes and neutral flavor profiles. Sports-nutrition brands in Texas and Florida are driving geographic demand dispersion.
- Sauces:Hydrated TVP as thickening agents and protein enrichers in ready-to-serve gravies and pasta sauces. Rehydration stability under retort conditions specifies granule selection.
Meat Alternatives retains volume leadership; Protein Supplements shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in California's food-tech corridor and Iowa's bio-processing districts concentrate TVP investment through state-level tax abatements. Federal soybean subsidies stabilize input costs across the Midwest while coastal clean-label mandates reshape formulation priorities.
California
Bay Area food-tech clusters drive demand for high-moisture extrusion capabilities in whole-muscle analog development. Proposition 65 enforcement on heavy metals and acrylamide imposes testing burdens absent in other states. Los Angeles and San Francisco anchor direct-procurement relationships between quick-service chains and toll manufacturers.
Midwest Soy Belt
Illinois and Iowa crushing facilities supply defatted soy flour to extrusion plants along the Mississippi River corridor. USDA-FSIS dual-jurisdiction standards for meat-analog products create compliance complexity for Iowa-based processors. Chicago's logistics infrastructure enables just-in-time distribution to frozen entrée manufacturers.
Texas
Dallas-Fort Worth and Houston food-tech corridors attract greenfield extrusion investment seeking geographic diversification from Midwest concentration. State economic development incentives target alternative protein manufacturing through property tax abatements. San Antonio's distribution networks serve expanding quick-service restaurant procurement in the Sun Belt.
Pacific Northwest
Seattle and Portland metro areas concentrate sports-nutrition brand headquarters driving protein supplement demand. Washington State's clean-energy grid attracts processors seeking carbon-neutral production positioning. Regional organic certification infrastructure supports premium channel supply for health food store distribution.
Southeast
Atlanta and Miami distribution hubs facilitate shelf-stable meal kit assembly incorporating TVP flakes and granules. Florida's absence of state-level heavy metal testing reduces compliance overhead versus California suppliers. Southeast poultry industry adjacency creates technical talent pools for extrusion engineering recruitment.
United States Textured Vegetable Protein Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with bulk ingredient suppliers commanding volume contracts while formulated-system vendors capture premium positioning. The market structures around three tiers: integrated agribusiness conglomerates with captive crushing capacity, mid-scale extrusion specialists serving regional food manufacturers, and ingredient-system innovators bundling TVP with flavor masking and binding technologies. Consolidation pressure operates through backward integration into soybean origination and forward integration into toll-manufacturing partnerships with quick-service chains.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill Inc. occupy positions defined by Midwest soy-processing infrastructure and origination networks. Ingredion Inc. exemplifies the formulated-system archetype, differentiating through clean-label ingredient architectures that improve finished-application performance. These three entities represent distinct competitive vectors: scale-driven supply security, geographic concentration risk management, and premium-channel technical positioning.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Inc. |
| Ingredion Inc. |
| The Scoular Company |
| International Flavors & Fragrances Inc. |
| MGP Ingredients Inc. |
| Axiom Foods Inc. |
| AGT Food and Ingredients |
| Crown Soya Protein Group |
| Others |
Value Network & Pricing Analysis
Family-owned Midwest soy-processing cooperatives anchor defatted flour supply, translating crushing-margin discipline into contract pricing stability for extrusion facilities serving quick-service restaurant chains. Their captive origination networks buffer spot-market volatility, though California clean-label mandates extract compliance premiums that stratify regional pricing spreads.
Pricing Analysis
Short lead-time premiums apply to high-moisture extrusion toll runs for Bay Area food-tech developers, while spot inventory discounts move through legacy single-screw granule stockpiles. Contract-based long-term offtake dominates institutional procurement, with price differentiation resting on USDA-FSIS dual-certification status and organic verification grade. Cost compression in commodity-grade TVP intensifies as Illinois and Iowa crush capacity expands, squeezing margin structures for non-certified suppliers. Quick-service restaurant procurement teams exhibit lowest price sensitivity due to menu-price pass-through power; pet food formulators remain most exposed to soybean futures swings.
Supply Chain Analysis
Dual-sourcing qualification mandates from major quick-service chains force extrusion facilities to maintain redundant supplier relationships across Iowa and Illinois crushing networks. Geographic supply concentration centers on the United States, with limited Canadian canola-protein alternatives entering premium clean-label channels. Raw material dependencies include defatted soy flour, hexane solvent for oil extraction, and natural gas for extrusion thermal energy. Single-source vulnerability concentrates along Mississippi River barge corridors, where flood disruptions have idled Midwest processing clusters. Distribution runs through Chicago cold-chain hubs and Dallas-Fort Worth food-service distribution centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States textured vegetable protein market sits in a technology-transition phase, with high-moisture extrusion systems displacing legacy dry-texturization infrastructure across California and Texas food-tech corridors.
For Market Incumbents: To counter precision-fermentation protein startups capturing premium positioning, Midwest processors should deepen backward integration into identity-preserved soybean origination and expand high-moisture extrusion capacity in Dallas-Fort Worth to reduce geographic concentration exposure. Securing dual FDA-USDA certification databases across multiple downstream brand customers preserves contract renewals amid tightening labeling rulemaking. For New Entrants and Emerging Players: Capture shelf-stable ready-to-eat meal kit supply in Florida and Georgia distribution hubs, where absence of Proposition 65 testing burdens enables faster SKU velocity versus California competitors. Sports nutrition protein isolate supply in Texas represents the most penetrable white-space, with toll-manufacturing partnerships offering lower capital barriers than greenfield extrusion buildouts. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale extrusion specialists with existing USDA-FSIS label approvals in Iowa and Illinois, where family-owned operators face generational transition pressures. Long-term viability across the analysis window hinges on clean-process technology positioning. The signal to watch is FDA plant-based meat labeling rule finalization, which would trigger reformulation capex demands and consolidate compliant supplier lists.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Enables whole-muscle texture simulation for refrigerated meat-alternative lines in California. |
| Backward Integration into Identity-Preserved Soybean Origination | Secures non-GMO and organic feedstock streams for health food store premium channels. |
| Dual FDA-USDA Certification Investment | Accelerates label approval timelines for meat-analog products facing jurisdictional friction. |
| Toll-Manufacturing Partnership with Quick-Service Chains | Compresses distributor margins while locking in volume throughput for Midwest processors. |
| Clean-Label Ingredient System Development | Binds TVP with natural flavor masking to qualify for retail premium positioning. |
Research Methodology
Independent corroboration across extrusion engineering directors, quick-service restaurant procurement leads, and sports-nutrition brand formulators underwrites the qualitative findings in this study. Primary interviews with Iowa and Illinois plant managers, California food-tech R&D heads, and Texas distribution channel partners combined with secondary validation from USDA-FSIS label databases, FDA guidance documents, and customs trade records. Bottom-up capacity assessments across Mississippi River corridor facilities triangulated against top-down demand modeling from institutional procurement disclosures.
Rate-of-change decomposition across the projection horizon separates volume growth into replacement demand for legacy extrusion equipment, expansion demand from new quick-service menu lines, and premium conversion from clean-label reformulation. Segmentation dimensions modeled include product type granularity, end-user certification tier, distribution channel structure, and application-specific rehydration performance. CAGRs derived from facility-level throughput projections and brand-customer contract visibility. Forecast inputs incorporated Proposition 65 enforcement intensity and high-moisture extrusion adoption curves.
The model holds under stable FDA-USDA jurisdictional boundaries; deviation in labeling rule finalization timing or soybean futures volatility spikes would shift capacity expansion schedules materially. Deviation in California heavy metal testing enforcement thresholds would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plant Based Food
Vegan Alternatives Market
Plant Based Food
India Plant Based Milk Market
Plant Based Food
Vegan Pastry Market
Plant Based Food
Vegan Pasta Market
Plant Based Food
Low Fat Plant-Based Diet Market
Plant Based Food
USA Plant-Based Creamers Market
Plant Based Food
Vegan Food Market
Plant Based Food
South America Soy Beverages Market
Plant Based Food
Plant-Based Fish Market
Plant Based Food
Plant-Based Burger Market
Plant Based Food
Plant Based Breads Market
Plant Based Food
Fermented Plant Extracts Market
Plant Based Food
Fermented Plant Protein Market
Plant Based Food
Plant-Based Food and Beverages Market
Plant Based Food
Dandelion Root Extract Market
Plant Based Food
Global Plant Based Food Market