
 Asia-Pacific Coconut Milk Market | 2026-2036
Asia-Pacific Coconut Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Coconut Milk Market Outlook
Thailand's Board of Investment incentive framework is hardening the cost-of-entry calculus for new coconut milk processors seeking export licenses. Celebes Coconut Corporation leverages its integrated plantation-to-can operations across Mindanao to sustain cost advantages in bulk food manufacturing supply. Thai Agri Foods Public Co., Ltd anchors its position through dedicated R&D facilities in Samut Sakhon that specialize in aseptic tetra pack formulations for food manufacturers.
Asia-Pacific coconut milk denotes the aqueous extract mechanically pressed from mature coconut endosperm, typically standardized to fat content between 17-24% for full-fat grades and below 10% for light variants, serving as a dairy alternative and functional ingredient in Southeast Asian cuisines and global plant-based formulations. Organic product type commands premium shelf positioning in Australian and Japanese supermarkets where certification requirements filter out conventional competitors. Food manufacturers represent the fastest-growing end user segment as plant-based dairy reformulation accelerates across ASEAN processed food sectors, while traditional household consumption remains mature but volume-stable across rural Indonesia and the Philippines.
Thailand's Ministry of Public Health enforces food additive and labeling standards that determine which coconut milk products qualify for domestic retail and export eligibility, while Indonesia's National Agency of Drug and Food Control regulates shelf-life claims and preservative thresholds that directly shape formulation decisions by local processors. Food manufacturers and distributors must monitor how evolving ASEAN harmonized food standards will alter cross-border certification burdens and reformulation costs.
Market Dynamics
ASEAN processed food manufacturers are consolidating procurement around aseptic carton formats, compressing demand toward processors with integrated cold-chain capabilities and tetra pack certification.
Growth Catalysts
- Thailand's Board of Investment incentives:Tax holidays and export facilitation for processed coconut products are accelerating capacity expansion in Samut Sakhon and Surat Thani provinces.
- Plant-based dairy reformulation:Food manufacturers across Indonesia's Java corridor are substituting coconut milk for dairy solids in ice cream, yogurt, and confectionery applications.
- ASEAN harmonized food standards:Mutual recognition protocols for shelf-life testing are reducing cross-border certification burdens between Thailand, Indonesia, and Vietnam.
Market Restraints
- Fresh coconut supply concentration:Mindanao and southern Thailand account for over sixty percent of regional kernel supply, exposing processors to climatic volatility and logistics bottlenecks.
- Preservative threshold restrictions:Indonesia's National Agency of Drug and Food Control caps benzoate levels below those permitted in Thai domestic retail, forcing dual formulation runs.
- Oat and almond milk substitution:Barista-grade oat formulations from European suppliers are displacing coconut milk in Australian cafe chains and specialty beverage outlets.
Strategic Opportunities
- Vietnam's underdeveloped processing base:Domestic coconut harvests in Ben Tre and Tra Vinh provinces currently export raw kernel to Thailand, creating white space for integrated crushing and canning facilities.
- Organic certification arbitrage:Australian and Japanese supermarkets command premium positioning for EU-equivalent organic grades, rewarding processors who secure BioGro or JAS certification.
- E-commerce direct-to-household channels:Platforms like Shopee and Lazada are enabling Indonesian processors to bypass traditional wet-market distribution and capture margin from urban Java households.
Industry Challenges
- Aseptic packaging technician scarcity:Tetra Pak line operators and sterilization engineers command wage premiums in Thailand, constraining expansion timelines for new entrants.
- Dual certification timeline compression:Processors seeking simultaneous Thai FDA and Indonesian BPOM approvals face conflicting documentation requirements and divergent shelf-life validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Coconut Milk Market |
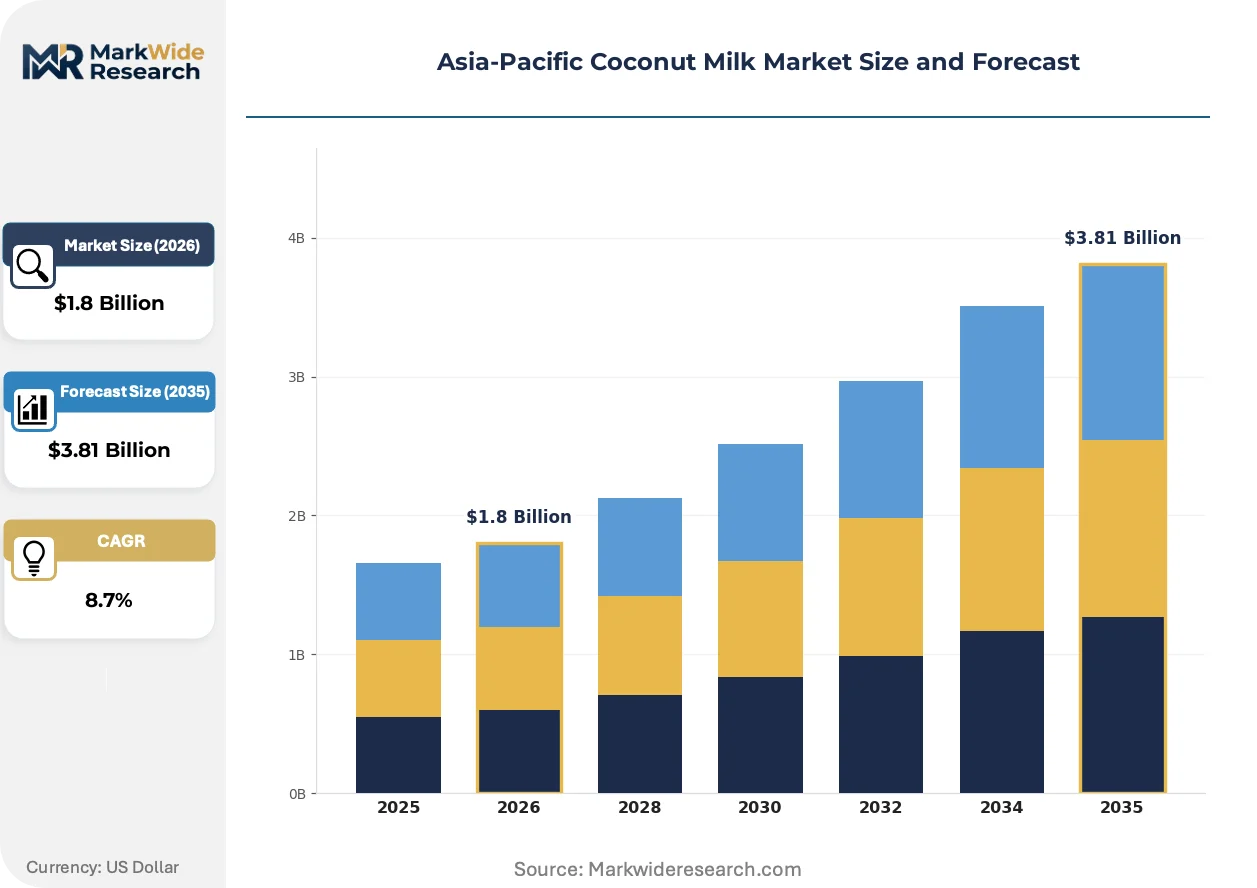
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Organic, Light, Flavored End User: Households, Restaurants, Cafes, Food Manufacturers Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Packaging Type: Plastic Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Goya Foods, Inc., Celebes Coconut Corporation, Theppadungporn Coconut Co., Ltd, Vita Coco, Edward & Sons Trading Co, Thai Agri Foods Public Co., Ltd, ThaiCoconut Public Company Limited, Ducoco, McCormick & Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Coconut Milk Market Strategic Shifts
Processing technology and packaging formats are converging to extend ambient shelf stability while preserving fat emulsion integrity, reshaping competitive advantage around capital-intensive aseptic capabilities rather than commodity crushing scale.
UHT sterilization paired with multilayer carton barriers is unifying previously separate chilled and ambient supply chains. Indonesian and Thai food manufacturers are adopting these systems at replacement cycle points, enabling direct-to-manufacturer bulk delivery without refrigerated intermediaries. This unifying technology is compressing margins for processors dependent on canned formats and cold-chain distribution.
Thailand's Ministry of Public Health revised food additive labeling requirements now mandate allergen cross-contamination warnings for coconut-dairy copacking facilities. The regulation forces reformulation decisions for processors running dual dairy and plant-based lines, particularly affecting exporters to Australian retail. Affected manufacturers are segregating production schedules or investing in dedicated coconut-only facilities.
Cafe procurement managers are consolidating supplier relationships around single-source barista-grade coconut milk with guaranteed foam stability across espresso applications. This specification-driven consolidation is displacing generic canned formats in Australian and Japanese foodservice channels. The shift is most visible in Melbourne and Sydney specialty coffee chains where consistency protocols override cost minimization.
Asia-Pacific Coconut Milk Market Segmentation
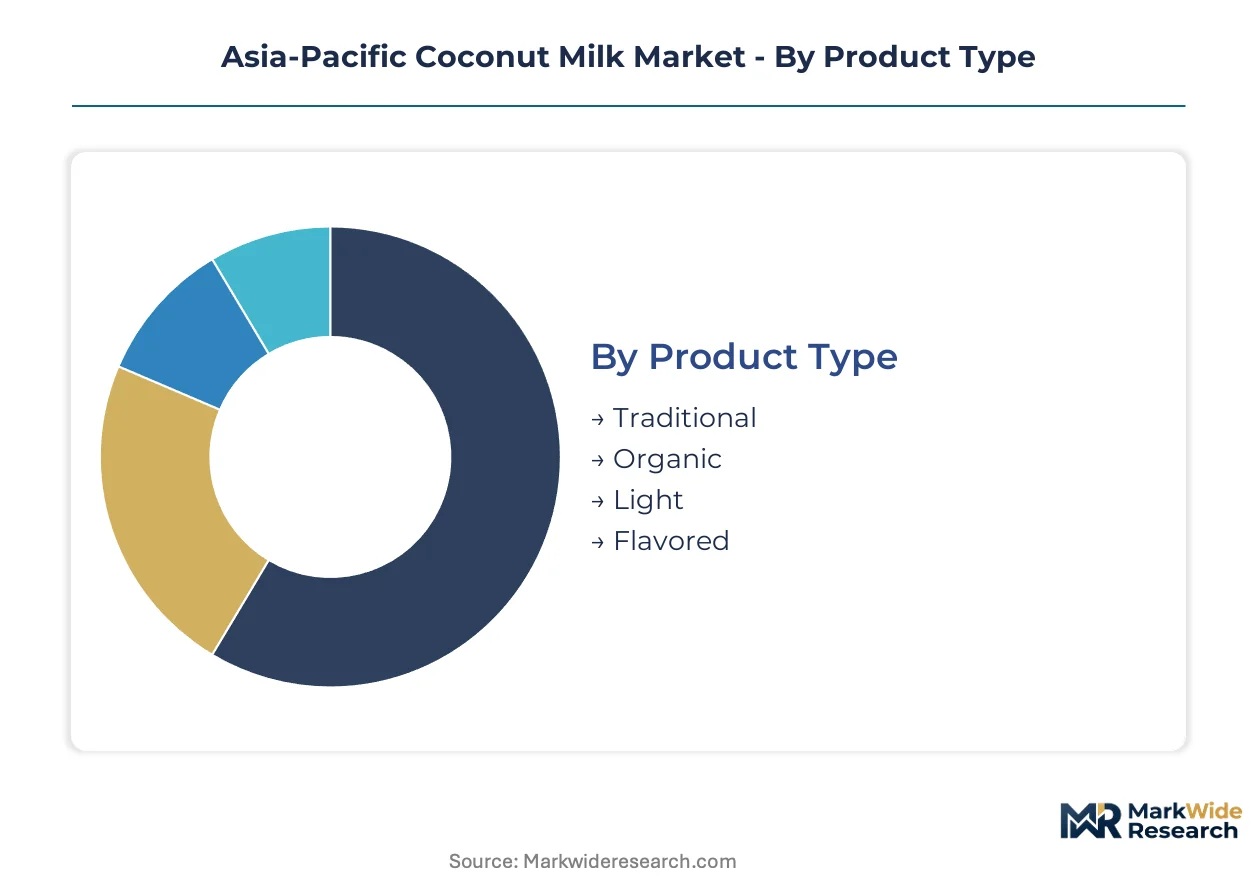
Segmentation in Asia-Pacific coconut milk reveals how procurement specifications diverge between commodity food manufacturing and premium retail positioning. Technical requirements around fat standardization, aseptic stability, and certification status create distinct capability thresholds that reshape processor investment priorities across Thailand, Indonesia, and Vietnam.
Product Type:
Standardization intensity varies sharply across this category, from commodity crushing with minimal processing controls to certified organic supply chains requiring full traceability documentation.
- Traditional:Full-fat aqueous extract standardized to 17-24% fat content serves as the baseline input for Indonesia's Java-based food manufacturers and Philippine household cooking. Demand concentrates in wet-market channels and institutional foodservice where cost minimization overrides certification requirements.
- Organic:EU-equivalent certified grades command shelf price premiums in Australian and Japanese supermarkets. BioGro and JAS certification requirements filter out conventional competitors, concentrating supply among Thai processors with integrated plantation control in Samut Sakhon and Surat Thani.
- Light:Below 10% fat formulations target health-positioned retail segments in urban Australian and Japanese markets.
- Flavored:Vanilla and pandan variants occupy niche positioning in Southeast Asian cafe applications and specialty beverage channels.
Most installed capacity flows through Traditional grades. Expansion is steepest in Organic certification tiers.
End User:
Volume scale inversely correlates with margin capture across this category, with bulk food manufacturing offering throughput stability while cafe channels yield premium pricing for barista-grade specifications.
- Food Manufacturers:ASEAN processed food sectors in Indonesia's Java corridor are substituting coconut milk for dairy solids in ice cream, yogurt, and confectionery applications. Plant-based dairy reformulation is accelerating procurement consolidation around aseptic carton formats with guaranteed emulsion stability.
- Cafes:Australian specialty coffee chains in Melbourne and Sydney are consolidating supplier relationships around single-source barista-grade coconut milk with guaranteed foam stability across espresso applications. Consistency protocols override cost minimization in this channel.
- Restaurants:Southeast Asian foodservice channels maintain steady demand for canned formats in traditional curry and soup applications.
- Households:Rural Indonesia and the Philippines sustain mature but volume-stable consumption through wet-market and traditional trade channels.
Food Manufacturers absorb the largest volume share. Cafes are gaining share fastest on value terms.
Distribution Channel:
Channel selection determines certification burden and cold-chain requirements, with direct-to-manufacturer bulk delivery bypassing retail packaging overhead entirely.
- Supermarkets:Australian and Japanese retail chains enforce organic certification and allergen labeling standards that reshape processor formulation decisions. Shelf-positioning competition concentrates among Thai exporters with dedicated R&D facilities for aseptic tetra pack formats.
- Online Retail:Shopee and Lazada platforms enable Indonesian processors to bypass traditional wet-market distribution and capture margin from urban Java households. E-commerce direct-to-household channels are compressing intermediary layers in Indonesia's domestic market.
- Specialty Stores:Health-focused retailers in Australian metropolitan markets curate premium organic and barista-grade assortments.
- Convenience Stores:Single-serve pouch and small-format can distribution serves immediate-consumption demand in Philippine and Indonesian urban transit corridors.
Supermarkets move the highest absolute volume. Online Retail is climbing the fastest in Indonesia and Vietnam.
Packaging Type:
Capital intensity and technician scarcity create divergent expansion economics, with aseptic systems requiring sterilization engineering capabilities that command wage premiums in Thailand.
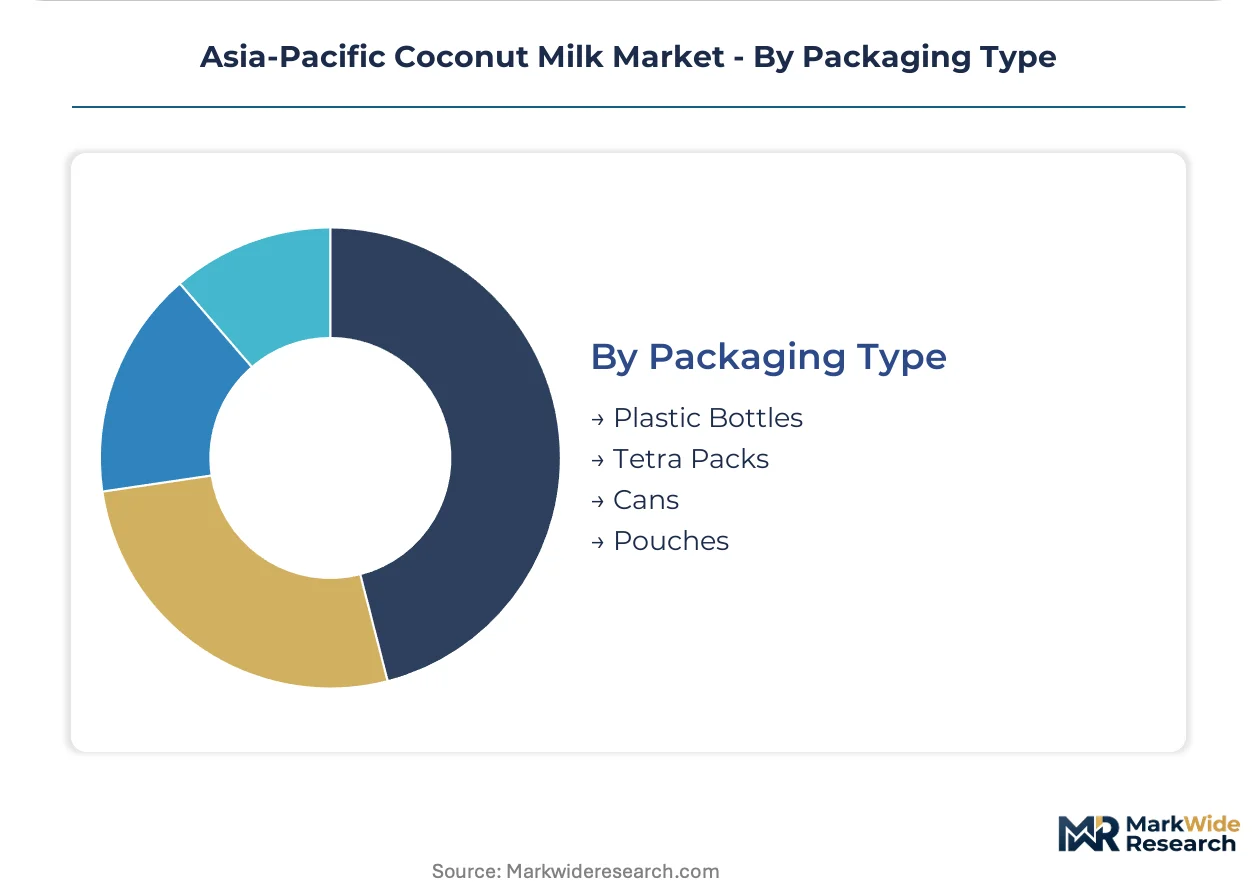
- Tetra Packs:Multilayer carton barriers paired with UHT sterilization unify previously separate chilled and ambient supply chains. Indonesian and Thai food manufacturers are adopting these systems at replacement cycle points, enabling direct-to-manufacturer bulk delivery without refrigerated intermediaries.
- Cans:Metal formats retain cost advantages in Philippine and Indonesian wet-market channels where ambient distribution infrastructure remains limited. Canned formats face margin compression as aseptic carton adoption accelerates among ASEAN food manufacturers.
- Plastic Bottles:Chilled distribution formats serve premium retail positioning in Australian supermarkets with established cold-chain infrastructure.
- Pouches:Flexible single-serve packaging targets convenience store and foodservice portion-control applications in Southeast Asian urban markets.
Most installed capacity flows through Cans. Expansion is steepest in Tetra Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Coconut milk processing originated in Thailand's coastal provinces during the 1970s export boom, then spread through ASEAN as Japanese and European buyers established quality protocols. Processing clusters now concentrate where fresh kernel supply intersects with cold-chain infrastructure and aseptic packaging expertise.
Thailand
Samut Sakhon and Surat Thani provinces host the region's densest processor concentration, driven by Board of Investment tax holidays for processed coconut exports. Thailand's Ministry of Public Health enforces additive and labeling standards that determine domestic retail and export eligibility. R&D facilities in Samut Sakhon specialize in aseptic tetra pack formulations for food manufacturers.
Indonesia
Java's food manufacturing corridor absorbs the largest regional volume, with processors supplying both local households and ASEAN reformulation demand. The National Agency of Drug and Food Control caps benzoate levels below Thai thresholds, forcing dual formulation runs. Urban Java households increasingly bypass wet markets through Shopee and Lazada direct channels.
Philippines
Mindanao accounts for the majority of domestic kernel supply, with Celebes Coconut Corporation leveraging integrated plantation-to-can operations for cost advantages. Wet-market and traditional trade channels sustain mature household consumption across rural provinces. Canned formats retain dominance where ambient distribution infrastructure remains limited.
Vietnam
Ben Tre and Tra Vinh provinces harvest substantial coconut volumes but currently export raw kernel to Thai processors. Underdeveloped domestic crushing and canning infrastructure creates white space for integrated facility investment. E-commerce penetration in Ho Chi Minh City is accelerating faster than northern metros.
Australia
Melbourne and Sydney specialty coffee chains drive barista-grade coconut milk specification, with consistency protocols overriding cost minimization. TGA-aligned allergen labeling requirements reshape exporter formulation decisions. Supermarket chains enforce organic certification standards that filter out conventional competitors.
Asia-Pacific Coconut Milk Market Competitive Environment
The competitive structure tilts toward integrated plantation-processor hybrids with captive kernel supply. Thai and Philippine operators dominate volume positions through backward integration into Mindanao and Surat Thani growing regions. Two strategic archetypes prevail: aseptic tetra pack specialists serving food manufacturers, and commodity canners supplying wet-market channels. Competitive moves concentrate on capacity expansion in Vietnam and dual certification for Thai-Indonesian cross-border sales.
Among integrated operators, Celebes Coconut Corporation exemplifies the plantation-controlled archetype through its Mindanao-based operations. Thai Agri Foods Public Co., Ltd and Theppadungporn Coconut Co., Ltd represent the R&D-intensive tier with dedicated aseptic formulation capabilities. These Thai processors occupy positions shaped by Board of Investment incentives and Ministry of Public Health regulatory compliance.
| Leading Market Players |
|---|
| Goya Foods, Inc. |
| Celebes Coconut Corporation |
| Theppadungporn Coconut Co., Ltd |
| Vita Coco |
| Edward & Sons Trading Co |
| Thai Agri Foods Public Co., Ltd |
| ThaiCoconut Public Company Limited |
| Ducoco |
| McCormick & Company |
| Others |
Value Chain & Pricing Dynamics
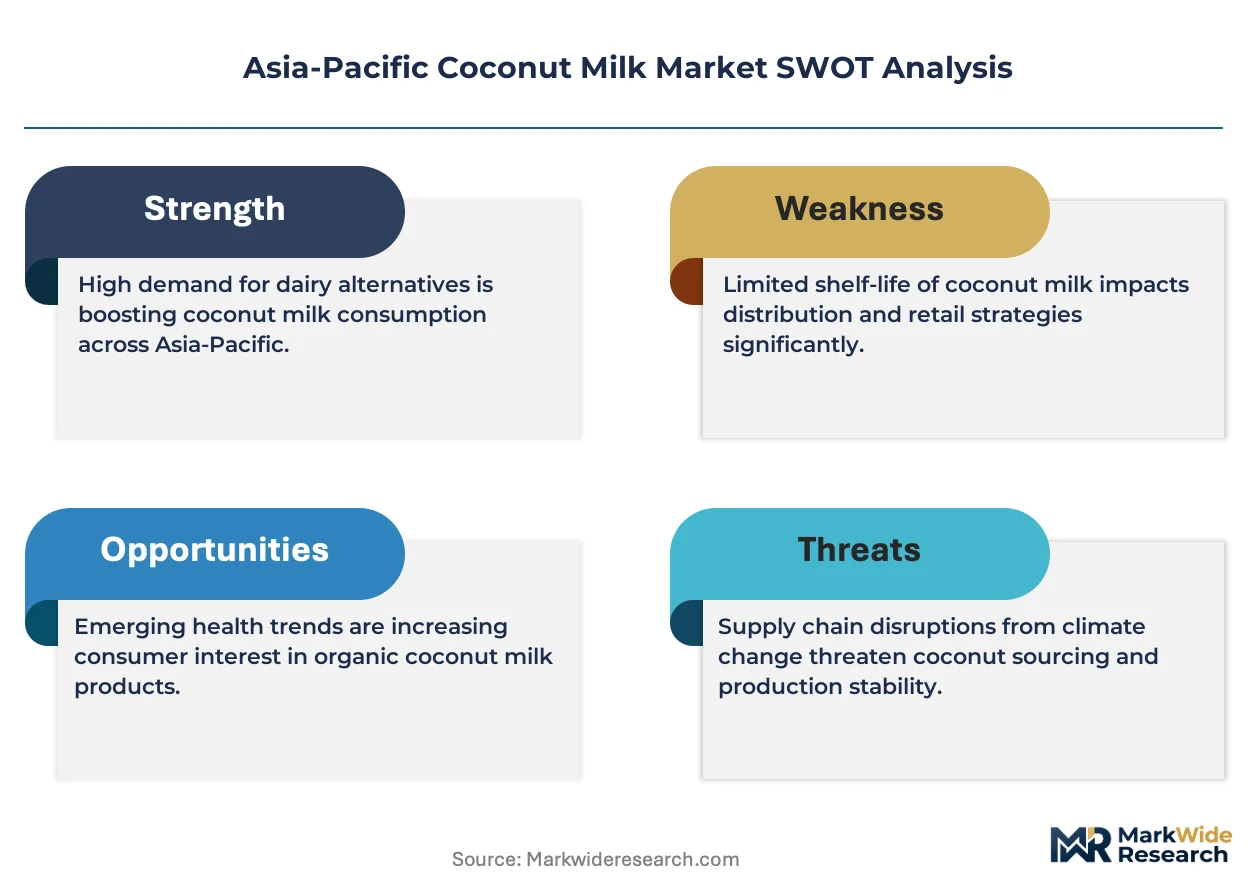
EU-equivalent organic certification requirements gate qualified supply and premium-tier pricing access, filtering out conventional competitors from Australian and Japanese supermarket shelves while rewarding Thai processors with integrated plantation control in Samut Sakhon and Surat Thani.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and volume commitment. Premium organic tiers with BioGro or JAS certification command shelf price multiples over conventional wet-market grades. Cost compression in economy canned formats is intensifying because aseptic carton adoption among ASEAN food manufacturers displaces metal packaging demand. Food manufacturers exhibit lowest price sensitivity due to reformulation-driven procurement consolidation, while rural Philippine households remain most price-responsive.
Supply Chain Analysis
Single-source vulnerability sits with Mindanao and southern Thailand, which account for over sixty percent of regional kernel supply. Fresh coconut harvests draw from plantation clusters in the Philippines, Thailand, and Indonesia's outer islands. Logistics chokepoints through southern Thai ports and Mindanao ferry routes expose processors to climatic disruption and port congestion. Distribution runs through direct-to-manufacturer bulk delivery for ASEAN food manufacturers, bypassing retail packaging overhead entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's Board of Investment tax holidays against Indonesia's stricter benzoate thresholds create a regulatory arbitrage window for cross-border processing investment.
For Market Incumbents: Acquire aseptic packaging engineering capabilities to defend against tetra pack displacement of canned formats. Celebes Coconut Corporation's integrated plantation-to-can model in Mindanao demonstrates how upstream control over kernel supply insulates margin from raw material volatility. Dual certification investment for simultaneous Thai FDA and Indonesian BPOM approvals captures cross-border procurement consolidation. For New Entrants and Emerging Players: Underserved Vietnamese food manufacturers represent the most penetrable buyer archetype, as Ben Tre and Tra Vinh provinces currently export raw kernel to Thai processors without domestic crushing infrastructure. White space exists for integrated canning facilities serving both local reformulation demand and re-export to ASEAN markets. E-commerce direct-to-household channels through Shopee and Lazada offer go-to-market access to urban Java households bypassing traditional wet-market layers. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale organic-certified processors because certification scarcity concentrates supply among Thai operators with plantation control. Long-term viability hinges on aseptic capability acquisition and dual-market regulatory positioning. The signal to watch is Vietnam's domestic processing infrastructure buildout as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Operations | Celebes Coconut Corporation's Mindanao control demonstrates kernel supply security against climatic volatility. |
| Aseptic Tetra Pack Capacity Expansion | Thai Agri Foods' Samut Sakhon R&D facilities anchor food manufacturer procurement consolidation. |
| Dual Certification Investment | Simultaneous Thai FDA and Indonesian BPOM approvals unlock cross-border sales without reformulation runs. |
| E-commerce Channel Development | Shopee and Lazada platforms enable Indonesian processors to capture margin from urban Java households. |
| Organic Certification Arbitrage | BioGro and JAS credentials filter competitors from Australian and Japanese premium retail positioning. |
Study Parameters
Bottom-up food manufacturer and cafe procurement modeling reconciled against top-down coconut kernel supply tracking forms the analytical core of this study. Primary interviews with coconut processing plant managers, ASEAN food manufacturer procurement leads, aseptic packaging line engineers, and Australian supermarket category buyers combined with secondary validation from Thai FDA additive regulations, Indonesian BPOM shelf-life standards, customs export data, and ASEAN harmonized food standard protocols.
Input-output matrices across product type, end user, distribution channel, and packaging format dimensions drive volume and value projections throughout the forecast period. CAGRs derive from segment-level demand elasticity modeling against supply-side capacity expansion timelines. Industry-specific forecast inputs include Board of Investment incentive uptake rates and aseptic packaging technician wage premium trajectories in Thailand.
Underlying measurement precision varies by segment; food manufacturer procurement volumes carry tighter precision than household wet-market consumption estimates. Forecasts reflect assumptions around ASEAN regulatory harmonization progress and climatic stability in Mindanao growing regions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Vegan Condensed Milk Market
Dairy Alternatives
Breast Milk Substitutes Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Vegan Cheese Alternatives Market
Dairy Alternatives
Europe Non-Dairy Milk Market
Dairy Alternatives
Protein Ice Cream Market
Dairy Alternatives
Japan Dairy Alternatives Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
On-The-Go Yoghurt Market
Dairy Alternatives
Dairy Whiteners Market
Dairy Alternatives
Global Soy Desserts Market
Dairy Alternatives
Vegan Yogurts Market
Dairy Alternatives
United States Coffee Creamer Market
Dairy Alternatives
Dairy Free Yogurt Market
Dairy Alternatives
Dairy Free Shortening Market