
 Saudi Arabia Organic Food Market | 2026-2036
Saudi Arabia Organic Food Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Organic Food Market Insights
Direct-to-consumer subscription revenue is reshaping margin distribution in Saudi Arabia's organic food sector. Almarai Company leverages its integrated dairy supply chain to dominate organic milk distribution across the Kingdom. Abazeer specializes in premium organic produce sourced from local farms near Taif. Organic Foods & Café controls the high-end retail experience through its Jeddah and Riyadh flagship locations.
Organic food comprises agricultural products cultivated without synthetic pesticides, genetically modified organisms, or artificial fertilizers, certified under national or international standards such as SFDA organic regulations or EU-equivalent protocols. Primary commercial purpose centers on delivering verified chemical-free nutrition to health-conscious consumers while commanding price premiums over conventional alternatives. Fruits and vegetables lead product type volume due to established local greenhouse capacity in Al-Qassim and Tabuk regions. Supermarkets anchor distribution channel throughput as Panda Retail Company and Savola Group expand dedicated organic shelf space. Biodegradable packaging gains structural momentum from SFDA plastic-reduction guidelines and retailer sustainability commitments.
SFDA organic certification requirements, SASO quality standards, and the Saudi Green Initiative framework collectively shape product labeling, import documentation, and farm-to-retail traceability obligations. Compliance costs favor scaled operators with dedicated quality assurance teams over fragmented local suppliers. Stakeholders must monitor enforcement consistency between SFDA field inspections and third-party certifier audits to anticipate supply bottlenecks or market access shifts.
Market Dynamics
SFDA organic certification enforcement is compressing supply chain participation, favoring scaled operators with dedicated compliance infrastructure over fragmented local growers.
Growth Catalysts
- Saudi Green Initiative targets:Government sustainability commitments accelerate farm conversion subsidies and water-efficient greenhouse expansion in Al-Qassim and Tabuk provinces.
- Health-conscious household formation:Riyadh and Jeddah families with disposable income prioritize chemical-free nutrition for children, concentrating premium demand in Central and Western provinces.
- Controlled-environment agriculture:Hydroponic and vertical farming technologies extend growing seasons beyond traditional desert constraints, expanding local organic vegetable output.
Market Restraints
- Input cost volatility:Organic feedstock and non-synthetic fertilizer prices fluctuate with global commodity markets, squeezing margin predictability for domestic producers.
- Supply concentration risk:Certified organic farmland remains concentrated around Taif and Al-Baha highlands, creating geographic vulnerability to regional climate shocks.
- SFDA audit backlog:Certification processing delays extend farm-to-shelf timelines, freezing working capital for small-scale operators awaiting compliance clearance.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail channels carry limited organic SKUs relative to Riyadh, presenting shelf-space expansion potential for early movers.
- Direct-to-consumer subscription models:Weekly produce box delivery bypasses supermarket margin extraction, capturing full retail value for integrated farm operations.
- Biodegradable packaging mandates:SFDA plastic-reduction guidelines create first-mover advantage for suppliers with compostable certification and cold-chain compatible materials.
Industry Challenges
- Agronomist talent scarcity:Organic cultivation expertise specific to arid-climate greenhouse management remains concentrated among a narrow specialist cohort, constraining farm expansion velocity.
- Cold-chain capex intensity:Temperature-controlled logistics from farm to retail requires refrigerated vehicle fleets and warehouse infrastructure beyond typical distributor balance sheets.
- Traceability system integration:SFDA farm-to-retail documentation requirements demand ERP upgrades that legacy accounting systems cannot accommodate without substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Organic Food Market |
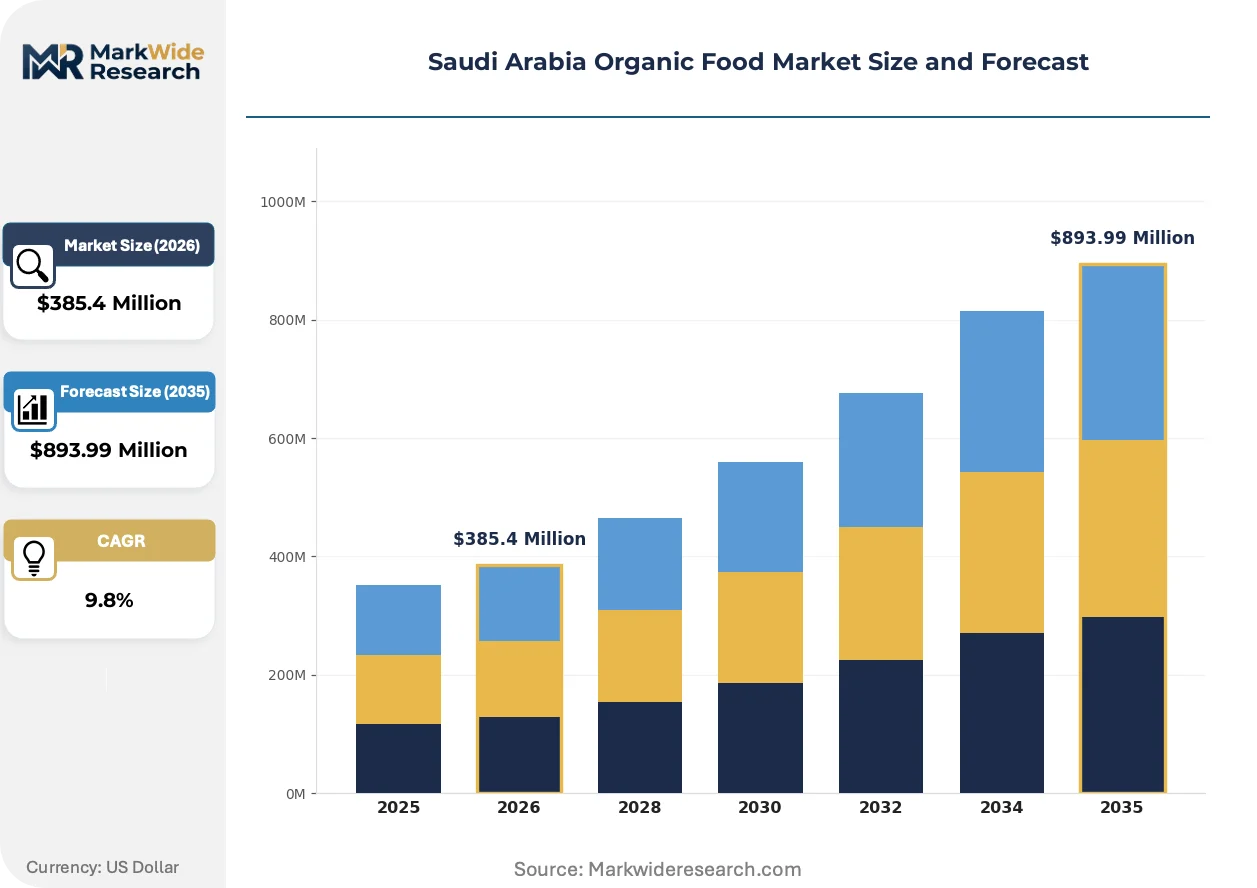
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $893.99 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Grains, Dairy Distribution Channel: Supermarkets, Online Stores, Farmers' Markets, Health Food Stores Packaging Type: Biodegradable, Glass, Plastic, Carton Customer Type: Health Enthusiasts, Families, Restaurants, Retailers |
| Companies Covered | Abazeer, Almarai Company, Organic Foods & Café, Savola Group, NADEC, Organic Life Est., Natureland, Panda Retail Company, Almizan Natural Trading Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Organic Food Market Trends and Innovations
Digital traceability platforms and climate-adaptive cultivation methods are restructuring how organic produce moves from Saudi farms to household tables.
Blockchain-enabled supply chain verification is rendering obsolete paper-based organic certification documentation. Premium supermarket banners in Riyadh and Jeddah now mandate QR-code traceability for private-label organic lines. This compression of verification overhead is accelerating supplier consolidation as small farms lack IT infrastructure to participate.
SFDA's phased implementation of stricter maximum residue limits for imported organic produce is redirecting procurement toward domestic certified growers. The regulation tightens documentation requirements for EU-equivalent and USDA-organic labeled imports entering Kingdom ports. Local greenhouse operators in Tabuk are expanding tomato and cucumber capacity to capture displaced import volume.
Restaurant procurement committees now specify organic dairy and vegetable quotas in centralized supply contracts. Hotel chains and catering groups in Riyadh are displacing spot-market purchasing with annual framework agreements tied to volume commitments. This buyer concentration is most visible in the Central Province, where institutional foodservice demand anchors planning for Almarai and specialized produce distributors.
Saudi Arabia Organic Food Market Segmentation
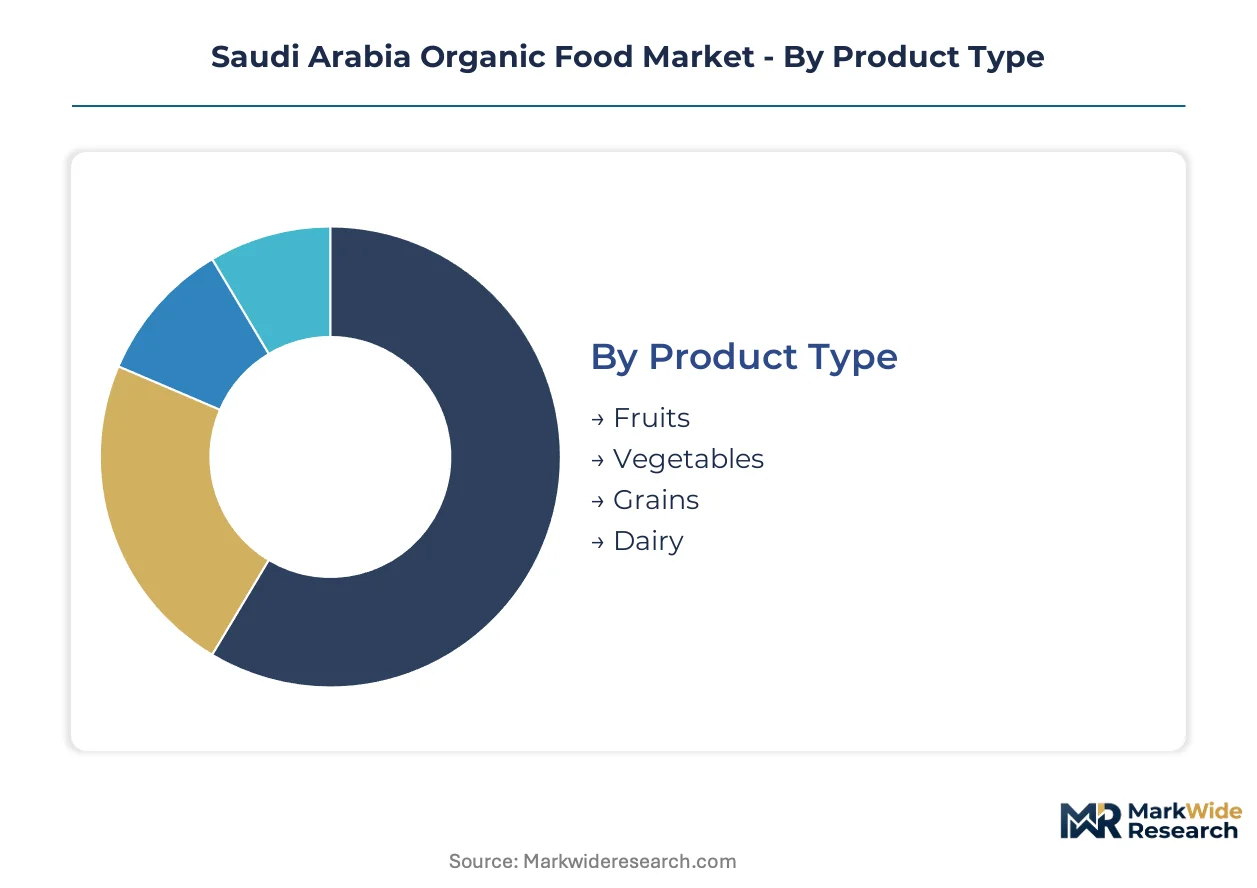
Segmentation reveals how SFDA certification requirements and cold-chain infrastructure shape commercial viability across product lines and channels. Understanding these divides exposes where compliance costs concentrate and where margin extraction shifts from farm to retail.
Product Type:
After-sales intensity varies sharply: dairy demands cold-chain maintenance and shelf-life monitoring, while grains require minimal post-purchase service.
- Fruits:Certified organic cultivation in Al-Qassim and Tabuk greenhouses supplies year-round tomato, cucumber, and strawberry output. Riyadh households drive volume through premium supermarket procurement, though perishability forces rapid inventory turns that strain distributor working capital.
- Vegetables:Leafy greens and cruciferous crops dominate local organic greenhouse capacity, with hydroponic systems extending growing seasons beyond traditional desert constraints. Jeddah restaurant procurement committees specify organic vegetable quotas in centralized supply contracts, concentrating demand in Western Province foodservice channels.
- Grains:Organic wheat and rice varieties rely heavily on imported supply due to limited domestic cultivation suitable for arid climates.
- Dairy:Integrated operators control organic milk distribution through captive cold-chain infrastructure reaching retail and foodservice endpoints.
By volume, Vegetables leads. By growth pace, Dairy is expanding most quickly.
Distribution Channel:
Cost tier stratification separates premium retail experiences from mass-market throughput, with channel selection directly determining customer acquisition economics and margin retention.
- Supermarkets:Panda Retail Company and Savola Group dedicate expanding shelf space to certified organic lines, anchoring mass-market accessibility. Central Province locations around Riyadh generate disproportionate revenue per square meter due to health-conscious household density.
- Online Stores:Direct-to-consumer subscription models bypass supermarket margin extraction, capturing full retail value for integrated farm operations with last-mile delivery capability.
- Farmers' Markets:Taif and Al-Baha highland producers sell direct to consumers seeking provenance verification, though SFDA traceability requirements limit participation to certified operators.
- Health Food Stores:Organic Foods & Café flagship locations in Jeddah and Riyadh control high-end retail experience with curated private-label assortments.
Supermarkets dominate transaction volume. Online Stores show the steepest expansion trajectory as subscription penetration deepens in metropolitan households.
Packaging Type:
Margin pressure from sustainability mandates favors suppliers with compostable certification and cold-chain compatible materials, creating technology-based competitive moats.
- Biodegradable:SFDA plastic-reduction guidelines and retailer commitments accelerate adoption of compostable films and molded fiber containers. Cold-chain compatibility remains the critical technical barrier for widespread dairy and fresh produce deployment.
- Glass:Premium dairy and condiment lines utilize returnable bottle systems in high-end retail channels, though logistics complexity limits geographic reach.
- Plastic:Conventional polyethylene and polypropylene retain cost advantage for mass-market SKUs despite regulatory pressure.
- Carton:Liquid dairy and juice applications favor aseptic carton formats with established recycling infrastructure in Kingdom urban centers.
Plastic retains volume leadership. Biodegradable packaging gains share fastest as compliance deadlines approach.
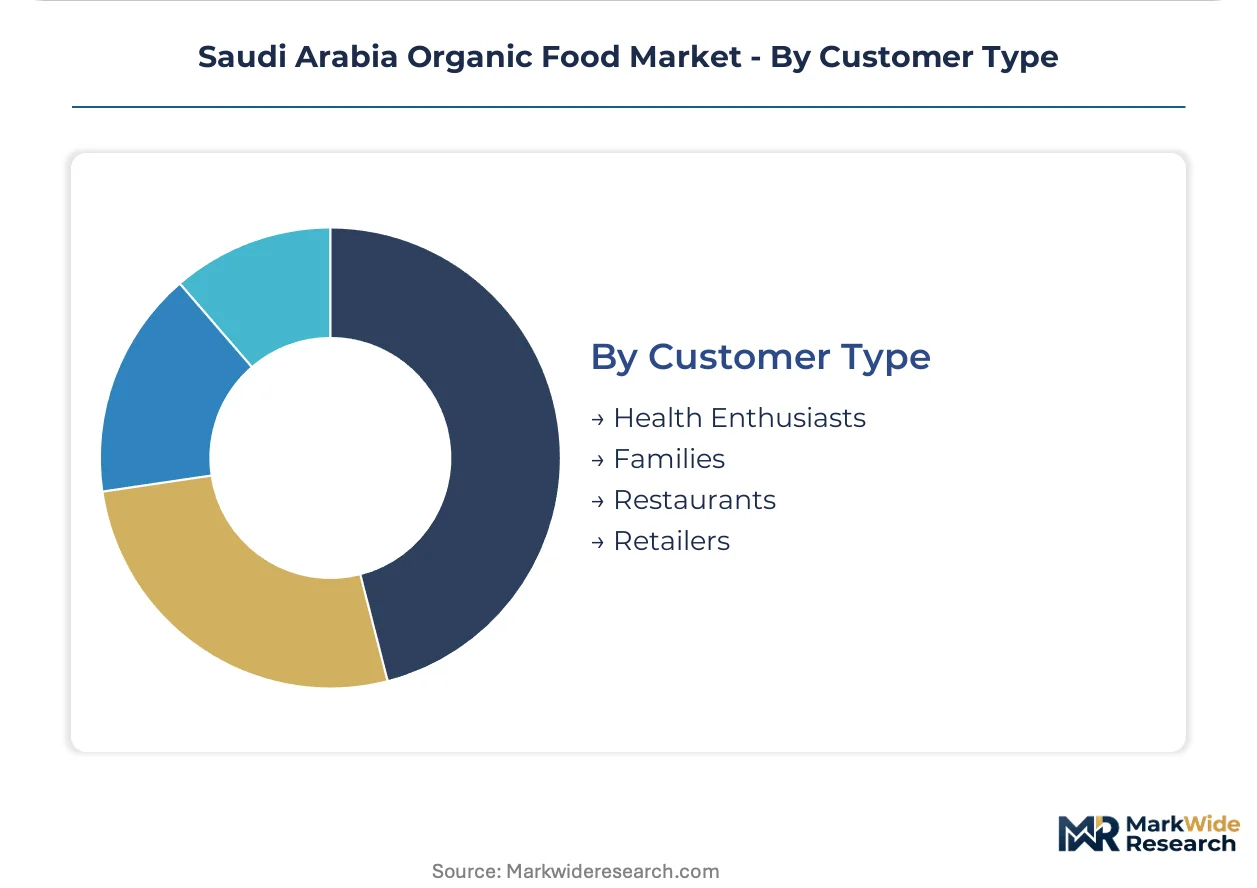
Customer Type:
Application concentration in foodservice procurement creates volume stability, while household demand fragmentation rewards flexible supply configurations.
- Health Enthusiasts:Individual consumers seeking verified chemical-free nutrition drive premium pricing tolerance and early adoption of novel organic SKUs.
- Families:Riyadh and Jeddah households with disposable income prioritize organic produce for children, generating recurring weekly purchase patterns.
- Restaurants:Hotel chains and catering groups displace spot-market purchasing with annual framework agreements tied to volume commitments, anchoring planning visibility for specialized distributors.
- Retailers:Supermarket and health food store buyers curate organic assortments based on SFDA certification status and QR-code traceability compliance.
Families generate the highest transaction frequency. Restaurants are climbing the fastest as institutional procurement formalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Saudi Arabia's organic food landscape. Riyadh households absorb premium pricing with minimal elasticity, while Eastern Province buyers demand promotional thresholds before trial. This demand-elasticity contrast shapes where distributors allocate cold-chain investment.
Riyadh
Health-conscious families with disposable income drive recurring weekly purchase patterns for certified organic produce. SFDA organic labeling enforcement tightens supply chain compliance for retailers operating in the capital. Central Province supermarket banners expand dedicated shelf space to capture this concentrated premium demand.
Jeddah
Restaurant procurement committees specify organic dairy and vegetable quotas in centralized supply contracts, anchoring foodservice volume. Western Province retail channels carry broader organic SKU assortments than Eastern markets. Hotel chains and catering groups displace spot-market purchasing with annual framework agreements tied to volume commitments.
Eastern Province
Dammam and Khobar retail channels carry limited organic SKUs relative to Riyadh, presenting shelf-space expansion potential for early movers. SFDA audit backlogs extend farm-to-shelf timelines, freezing working capital for small-scale operators awaiting compliance clearance. Local distributor networks lack the cold-chain density found in Central and Western regions.
Taif and Al-Baha Highlands
Certified organic farmland concentrates in these highland zones, creating geographic vulnerability to regional climate shocks. Taif-based producers sell direct to consumers at farmers' markets seeking provenance verification. Saudi Green Initiative farm conversion subsidies accelerate water-efficient greenhouse expansion in these elevated growing areas.
Tabuk
Hydroponic and vertical farming technologies extend growing seasons beyond traditional desert constraints in this northwestern province. Local greenhouse operators expand tomato and cucumber capacity to capture displaced import volume from stricter SFDA maximum residue limits. Controlled-environment agriculture clusters attract agronomist talent scarce across the broader Kingdom.
Saudi Arabia Organic Food Market Competitive Landscape
Integrated dairy operators and specialized produce distributors split the market along cold-chain capability lines. Consolidation favors scaled players with dedicated SFDA compliance infrastructure over fragmented local growers. Three archetypes dominate: vertically integrated agribusinesses with captive supply chains, premium retail experience curators, and mass-market supermarket banners with expanding organic assortments. Competitive moves concentrate on direct-to-consumer subscription launches and biodegradable packaging certification to meet SFDA plastic-reduction guidelines.
Within the integrated agribusiness tier, Almarai Company leverages its dairy supply chain dominance across the Kingdom. Specialized produce distribution is represented by Abazeer, which sources from local farms near Taif. On the premium retail vector, Organic Foods & Café anchors high-end positioning through flagship locations in Jeddah and Riyadh. These three exemplify how compliance scale, provenance control, and experience curation define competitive position in this enforcement-intensive market.
| Leading Market Players |
|---|
| Abazeer |
| Almarai Company |
| Organic Foods & Café |
| Savola Group |
| NADEC |
| Organic Life Est. |
| Natureland |
| Panda Retail Company |
| Almizan Natural Trading Company |
| Others |
Pricing and Supply Chain Analysis
The Dammam-Jeddah refrigerated freight corridor anchors cost dynamics for organic produce moving between Eastern Province farms and Western Province retail hubs, concentrating pricing power among operators with captive cold-chain fleets while forcing margin compression on distributors leasing third-party logistics capacity.
Pricing Analysis
After-sales service revenue from subscription box renewals and loyalty program extensions drives lifetime customer value beyond initial transaction margins. Three-tier pricing structure across premium certified organic, standard organic, and conventional produce tiers separates Riyadh households with minimal price elasticity from Eastern Province buyers demanding promotional thresholds. Pricing pressure stems from SFDA compliance cost absorption as certification audit fees and traceability system investments compound. Families with children in Central Province urban cores show least price sensitivity, while Eastern Province retail channels exhibit highest promotional dependency.
Supply Chain Analysis
Export-control restrictions on advanced greenhouse automation technologies from Dutch and Israeli suppliers limit controlled-environment agriculture expansion for domestic operators. Geographic supply concentration centers on Saudi Arabia's Taif and Al-Baha highlands for field-grown organic crops, with Tabuk and Al-Qassim provinces dominating greenhouse vegetable output. Raw material dependencies include organic feedstock imports from Argentina and Ukraine, non-synthetic fertilizers from Turkey, and biodegradable packaging films from European suppliers. Single-source vulnerability concentrates in certified organic seed supply channels. Distribution runs through supermarket banners with dedicated organic shelf space, supplemented by direct-to-consumer subscription channels capturing full retail value.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized agronomist expertise in arid-climate organic cultivation remains concentrated among a narrow cohort, constraining farm expansion velocity and creating acquisition premiums for operations with proven technical teams.
For Market Incumbents: Entrench market position through backward integration into captive organic seed propagation and greenhouse infrastructure in Tabuk, while accelerating SFDA certification for private-label lines to preempt regulatory enforcement shifts. Threat of direct-to-consumer subscription models displacing supermarket channel volume demands preemptive loyalty program investment and last-mile delivery capability development. For New Entrants and Emerging Players: Establish a beachhead in Eastern Province retail channels where organic SKU penetration lags Riyadh and Jeddah benchmarks, targeting Dammam and Khobar supermarket banners with underserved health-conscious households. White-space opportunity concentrates in biodegradable packaging certification for cold-chain compatible materials, where SFDA compliance deadlines create first-mover advantage. Go-to-market angle should emphasize QR-code traceability integration from launch to meet premium supermarket banner procurement requirements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates with underperforming organic divisions lacking dedicated compliance infrastructure, presenting operational turnaround opportunities through SFDA certification investment and cold-chain capex deployment. Long-term viability frames around water-efficient greenhouse technology adoption and climate-adaptive cultivation methods as arid-region production constraints intensify. Signal to watch is SFDA enforcement consistency between field inspections and third-party certifier audits as inflection indicator for supply bottleneck severity and market access shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Subscription Launch | Bypasses supermarket margin extraction for integrated farm operations with last-mile capability. |
| Biodegradable Packaging Certification | SFDA plastic-reduction guidelines create compliance moat for compostable cold-chain materials. |
| Controlled-Environment Agriculture Expansion | Tabuk hydroponic clusters capture displaced import volume from stricter residue limits. |
| SFDA Certification Investment | Preempts enforcement compression favoring scaled operators with dedicated compliance teams. |
| QR-Code Traceability Integration | Premium supermarket banners mandate blockchain-enabled verification for private-label organic lines. |
Research Methodology
A standing panel of greenhouse operations managers, SFDA compliance officers, supermarket category buyers, and cold-chain logistics coordinators provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against SFDA regulatory filings, Saudi Green Initiative subsidy disbursement records, customs import documentation for organic feedstock, and supermarket banner annual reports. Bottom-up farm production estimates triangulated against top-down retail consumption data.
Scenario-bracketing framed projections across the analysis window, modeling volume and value outputs through segmentation by product type, distribution channel, packaging format, and customer archetype. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and subsidy program expansion. Industry-specific forecast inputs incorporated water-efficient greenhouse technology adoption curves and SFDA audit processing timelines.
Macroeconomic conditions sit as an overlay; deviation in oil revenue disbursement patterns, expatriate household formation rates, or food import tariff regimes would shift the trajectory. Forecasts reflect assumptions around SFDA enforcement consistency and Saudi Green Initiative subsidy continuity. Material shifts in maximum residue limit regulations or cold-chain infrastructure investment levels would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Food and Beverages
Brazil Organic Food Market
Organic Food and Beverages
India Organic Food Market
Organic Food and Beverages
Global Natural and Organic Food Market
Organic Food and Beverages
Organic Dry Yeast Market
Organic Food and Beverages
United States Organic Food Market
Organic Food and Beverages
Global Organic Soup Market
Organic Food and Beverages
Global Organic Dried Fruit Market
Organic Food and Beverages
Scandinavia Organic Packaged Food and Beverages Market
Organic Food and Beverages
Organic Drinks Market
Organic Food and Beverages
Organic Yogurt Market
Organic Food and Beverages
Germany Organic Food Market
Organic Food and Beverages
UK Organic Food Market
Organic Food and Beverages
Italy Organic Food Market
Organic Food and Beverages
Asia-Pacific Organic Food Market
Organic Food and Beverages
Europe Organic Food Market
Organic Food and Beverages
Japan Organic Food Market