
 Coconut Milk and Cream Market | 2026-2036
Coconut Milk and Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Milk and Cream Market Outlook
Food service operators and plant-based manufacturers are reorganizing procurement priorities around coconut-derived ingredients. Danone S.A. leverages its dairy-alternative infrastructure to extend coconut beverage distribution across European retail channels. Thai Coconut Public Co. Ltd. anchors supply security through integrated plantation-to-processing operations in Thailand. The Vita Coco Company, Inc. competes on brand recognition in North American premium beverage segments.
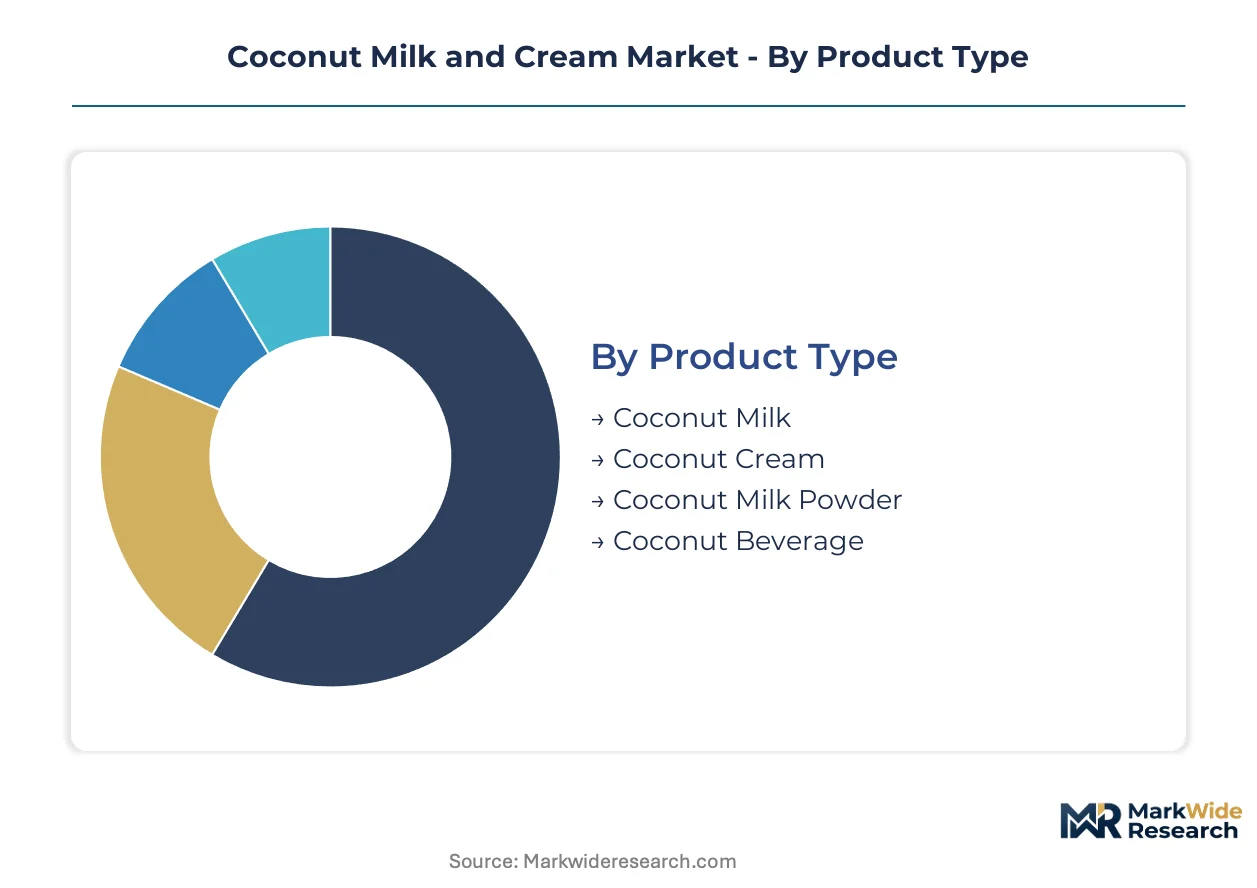
Coconut milk and cream comprise the aqueous and lipid fractions extracted from grated coconut kernel, typically containing 15-25% fat for milk and 20-30% fat for cream, with applications spanning dairy substitution, culinary enrichment, and beverage formulation. The product type landscape shows coconut milk powder capturing margin pools through extended shelf life and reduced logistics costs, while coconut beverages lead volume expansion in retail channels. Application segmentation reveals dairy alternatives as the fastest-growing category, though culinary use sustains the largest revenue base across food service and ethnic cuisine manufacturing.
USDA organic certification and FDA food labeling requirements shape product claims and import documentation for coconut derivatives entering the United States, while EFSA and EU Green Deal sustainability frameworks govern European market access and carbon footprint disclosure. Stakeholders must monitor evolving deforestation-free supply chain mandates and decide between certification investments or geographic sourcing diversification.
Market Dynamics
Plant-based dairy substitution is restructuring procurement priorities across food service and retail channels, pulling volume from conventional dairy infrastructure toward coconut-derived alternatives. Raw material access in Southeast Asian processing clusters anchors competitive positioning.
Growth Catalysts
- EU Green Deal sustainability mandates:The Farm to Fork Strategy tightens deforestation-free supply chain requirements for imported coconut derivatives, accelerating certification investments among European importers.
- Food service operator demand:Restaurant chains and institutional kitchens are standardizing coconut milk formulations for dairy-free menu expansion, creating pull-through for cream products in culinary applications.
- Spray-drying technology:Coconut milk powder production lines are capturing margin pools through extended shelf life and reduced cold-chain logistics costs, opening new distribution channels.
Market Restraints
- Raw material concentration:Coconut kernel supply concentrates in Thai and Philippine coastal plantations, exposing processors to monsoon disruption and climate volatility.
- Substitute competition:Oat and almond milk alternatives compete aggressively on price in North American retail beverage segments, compressing coconut beverage margin expansion.
- REACH chemical compliance:European importers face documentation burdens for processing aids and residual solvents in coconut cream extraction, extending customs clearance timelines.
Strategic Opportunities
- USDA organic certification pathway:Premium positioning through organic claims commands shelf space in US natural grocery channels, with FDA labeling requirements shaping compliant import documentation.
- Aseptic packaging convergence:Combination of UHT processing and multilayer carton technology enables ambient distribution of coconut cream into food service and manufacturing segments previously limited to canned formats.
- Indian ethnic cuisine manufacturing:Underpenetrated processing capacity for coconut milk in South Asian ready-meal production offers white space for ingredient suppliers.
Industry Challenges
- Deforestation-free traceability systems:EU Green Deal supply chain mandates require farm-level geolocation data, forcing processors to reconfigure supplier relationships and audit protocols.
- Extraction equipment capex cycles:Cold-press and enzyme-assisted processing technologies demand capital-intensive machinery upgrades, straining mid-scale processor balance sheets.
- Skilled technician scarcity:Coconut cream fractionation and standardization expertise concentrates among veteran operators in Thai processing hubs, limiting replication speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Milk and Cream Market |
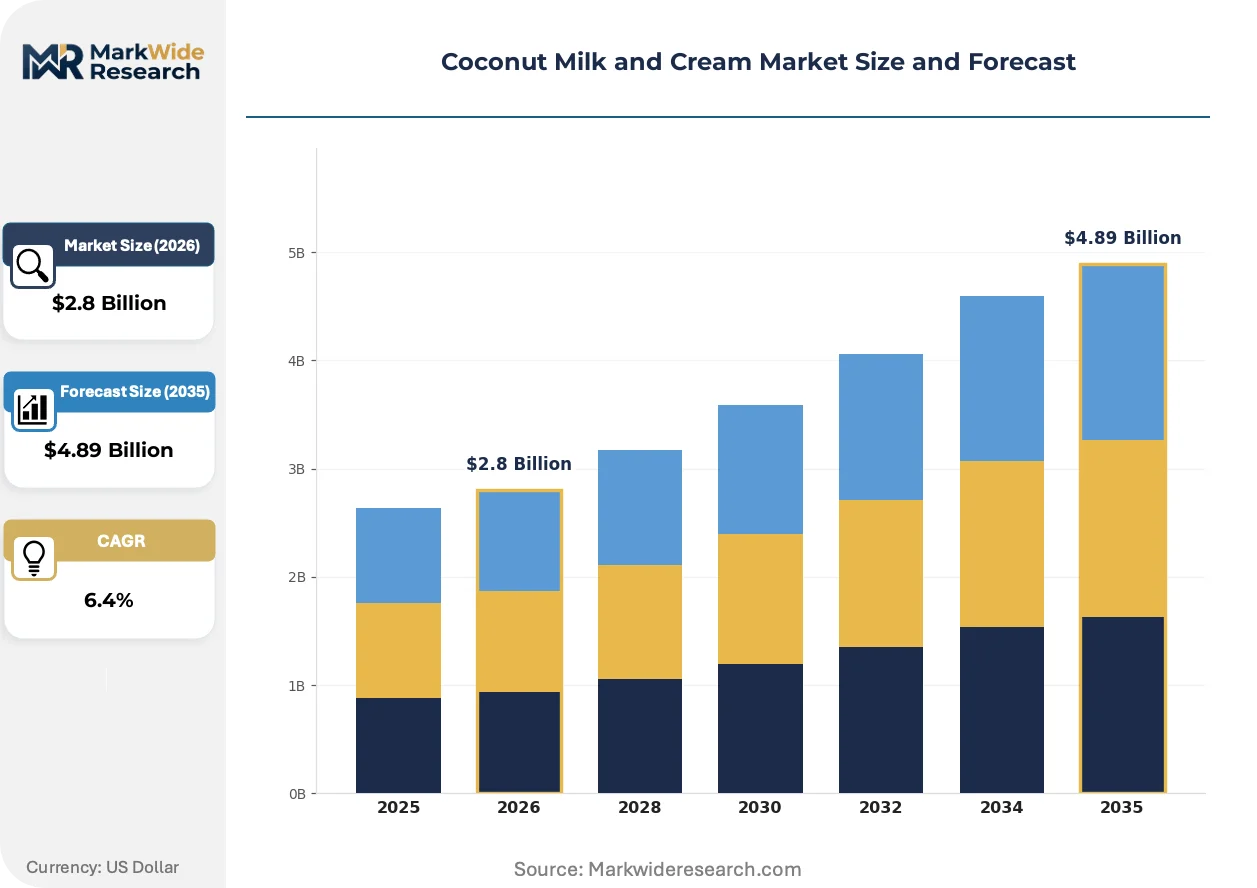
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coconut Milk, Coconut Cream, Coconut Milk Powder, Coconut Beverage Application: Dairy Alternatives, Culinary Use, Bakery Products, Beverages Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Specialty Stores End User: Households, Food Service, Restaurants, Manufacturers |
| Companies Covered | Danone S.A., The Vita Coco Company, Inc., Thai Coconut Public Co. Ltd., Sambu Group, Nestlé, Theppadungporn Coconut Co., Ltd., McCormick & Company Inc., Celebes Coconut Corporation, Goya Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Milk and Cream Market Strategic Shifts
Technology convergence and regulatory disclosure requirements are compressing traditional supply chain configurations while opening new channel access for processed coconut derivatives.
Enzymatic extraction protocols using cellulase and pectinase treatments are displacing conventional mechanical pressing in premium coconut cream production. Specialty food manufacturers in European dairy-alternative segments are adopting these methods to achieve cleaner flavor profiles and higher lipid recovery rates. This biotechnology shift is compressing yield gaps between artisanal and industrial processors.
The EU Green Deal's Corporate Sustainability Reporting Directive now mandates carbon footprint disclosure for imported agricultural derivatives, including coconut milk and cream entering European ports. Food manufacturers must document scope 3 emissions from plantation through processing, reshaping supplier qualification criteria. German and Dutch importers are responding by consolidating purchases through vertically integrated Thai suppliers with certified carbon accounting.
Direct procurement relationships between food service chains and Southeast Asian processors are shortening traditional distributor layers. Large US restaurant groups now contract directly with Thai Coconut Public Co. Ltd. and comparable integrated operators, bypassing regional ingredient distributors. This disintermediation is most visible in North American coastal metro markets where specialty beverage and culinary coconut products command premium positioning.
Coconut Milk and Cream Market Segmentation
Coconut milk and cream derivatives flow through distinct channel configurations depending on fat content, shelf stability, and end-use processing requirements. Each segment category exhibits different margin profiles and regulatory exposure based on how products reach food manufacturers, food service operators, and retail consumers.
Product Type:
Traditional liquid formats dominate food service procurement through institutional distributors, while powder and ready-to-drink beverages access retail through divergent cold-chain and ambient logistics networks.
- Coconut Milk:Aqueous lipid emulsion containing 15-25% fat extracted from grated kernel, serving as the foundational input for dairy substitution formulations. Thai and Philippine processors supply bulk aseptic totes to North American and European food manufacturers seeking clean-label emulsification properties. Demand concentrates in ethnic cuisine manufacturing and plant-based yogurt production, where fat standardization determines finished product texture.
- Coconut Cream:Concentrated lipid fraction at 20-30% fat, prized for whippability and mouthfeel in premium dessert applications. Southeast Asian integrated processors capture margin through controlled fractionation and UHT stabilization. European dairy-alternative brands specify enzymatic-extraction cream for cleaner flavor profiles in frozen dessert formulations.
- Coconut Milk Powder:Spray-dried lipid-protein matrix with 24-month ambient stability, reducing logistics costs for inland distribution. Asian instant noodle and curry paste manufacturers specify reconstitution ratios for manufacturing consistency.
- Coconut Beverage:Diluted, homogenized, and often sweetened ready-to-drink format competing in retail dairy-alternative shelves. North American natural grocery channels and European convenience stores drive volume through single-serve carton formats.
Coconut milk dominates installed base across food service and manufacturing. Coconut beverage is where expansion concentrates.
Application:
Cost tier stratification separates commodity culinary procurement from premium-positioned dairy alternatives, with bakery and beverage applications occupying intermediate margin positions.
- Dairy Alternatives:Fastest-climbing application as plant-based yogurt, ice cream, and cheese manufacturers reformulate with coconut fat for clean-label appeal. US and German natural product brands specify organic-certified cream with documented carbon footprints to satisfy ESG procurement mandates. FDA and EFSA labeling requirements shape protein and fat claim substantiation.
- Culinary Use:Traditional cooking applications in Southeast Asian, Caribbean, and Latin American cuisines sustain volume through ethnic restaurant chains and ready-meal manufacturing. Thai coconut milk anchors curry paste and soup base production with standardized brix and pH specifications.
- Bakery Products:Fat replacement in gluten-free and vegan formulations, where coconut cream provides structure without hydrogenated oils. European artisan bakeries and industrial biscuit manufacturers specify cold-pressed grades for flavor integrity.
- Beverages:Smoothie base, coffee whitener, and cocktail ingredient applications through food service and retail channels. Specialty coffee chains in US coastal metros standardize coconut cream for dairy-free latte programs.
Culinary use dominates installed base. Dairy alternatives represent the steepest expansion trajectory.
Distribution Channel:
Volume scale separates mass retail from premium-channel positioning, with digital commerce capturing trial-driven segments and specialty stores anchoring ethnic authenticity claims.
- Supermarkets:Mainstream retail placement for coconut beverages and canned milk through dairy-alternative and international food aisles. US and UK grocery multiples drive case volume through promotional programming and private-label expansion.
- Health Food Stores:Premium positioning for organic, raw, and cold-pressed coconut derivatives with transparent supply chain claims. Natural grocery chains in Germany and California enforce supplier qualification through third-party certification audits.
- Online Retail:Direct-to-consumer and marketplace platforms enabling subscription models for coconut milk powder and specialty cream grades. Asian e-commerce aggregators connect Southeast Asian processors with European ingredient buyers.
- Specialty Stores:Ethnic grocery and gourmet food retailers curating authentic Thai, Filipino, and Sri Lankan origin products for diaspora communities and culinary enthusiasts.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
End User:
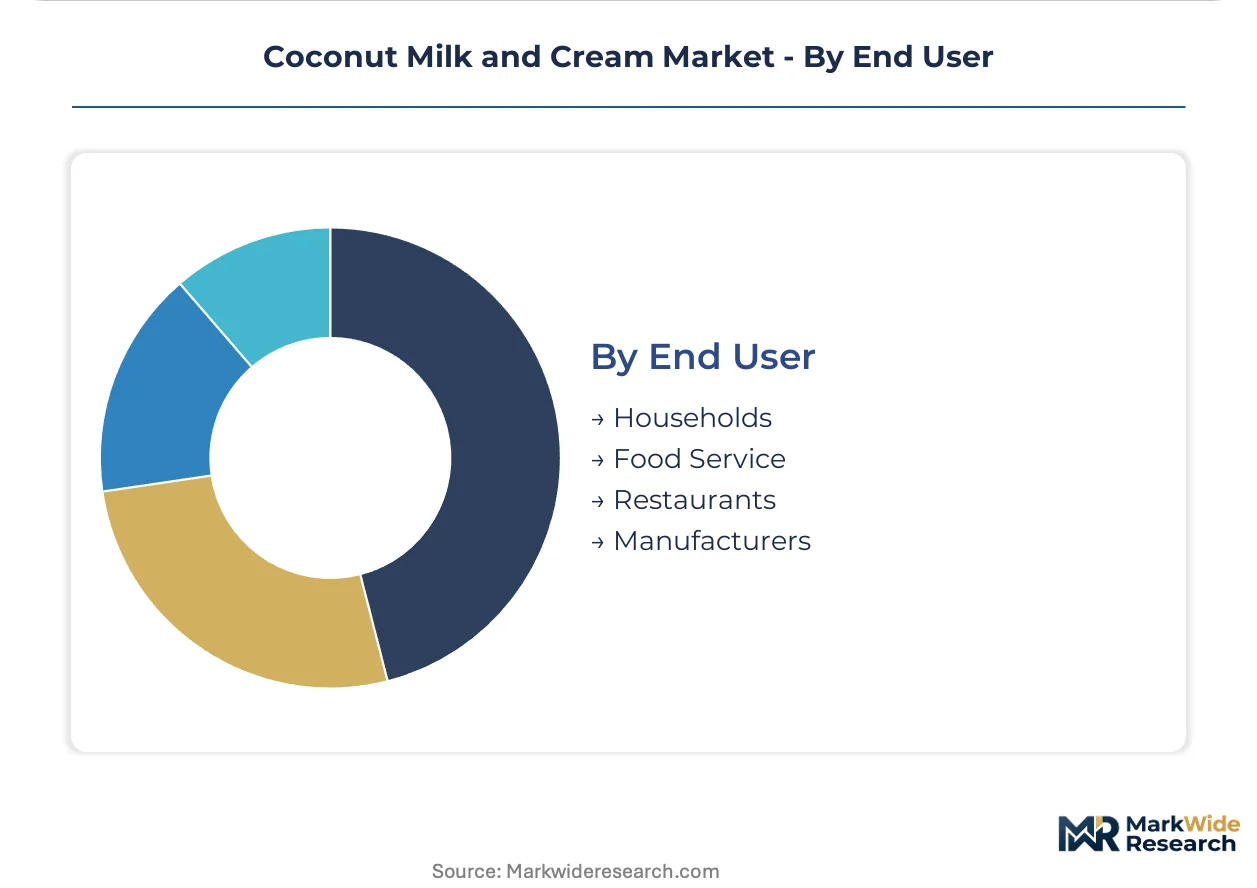
Customer type determines specification intensity, with manufacturers demanding certificate-of-analysis documentation while households respond to brand recognition and packaging convenience.
- Households:Retail consumers purchasing canned, carton, or powdered formats for home cooking and beverage preparation. German and US households show willingness-to-pay premiums for organic and fair-trade certifications.
- Food Service:Restaurant chains, catering operations, and institutional kitchens requiring consistent fat content and shelf stability for menu standardization. Direct procurement relationships with Thai integrated processors are shortening distributor layers.
- Restaurants:Independent and chain ethnic cuisine operators specifying origin-specific coconut milk for authenticity positioning in Thai, Indian, and Caribbean menu segments.
- Manufacturers:Ingredient procurement by dairy-alternative, bakery, and ready-meal producers with stringent microbiological and traceability requirements. EU Green Deal deforestation-free mandates are reshaping supplier qualification protocols for European manufacturing customers.
Households dominate installed base. Manufacturers represent the fastest-gaining share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai and Philippine processors ship bulk aseptic coconut milk to food manufacturers in Germany and the United States, anchoring the dominant trade corridor for coconut derivatives. European demand concentrates around sustainability-certified supply chains, while North American buyers prioritize organic claims and direct procurement relationships.
United States
Specialty coffee chains and plant-based yogurt manufacturers drive coconut cream procurement from Thai integrated suppliers. FDA food labeling requirements govern protein and fat claim substantiation on dairy-alternative packaging. Direct contracting between Los Angeles-based restaurant groups and Southeast Asian processors is shortening traditional distributor layers in coastal metro markets.
Germany
Natural grocery multiples and artisan bakeries specify organic-certified coconut derivatives with documented carbon footprints. EU Green Deal Corporate Sustainability Reporting Directive mandates scope 3 emissions disclosure for imported agricultural derivatives. Hamburg and Rotterdam port clusters consolidate purchases through vertically integrated Thai suppliers with certified carbon accounting systems.
Thailand
Integrated plantation-to-processing operations in Samut Sakhon and Ratchaburi provinces anchor global supply security for coconut milk and cream fractions. Thai Coconut Public Co. Ltd. and Theppadungporn Coconut Co., Ltd. control upstream kernel supply through captive coastal plantation networks. Bangkok-based exporters are investing in enzymatic extraction capacity to serve European dairy-alternative manufacturers demanding cleaner flavor profiles.
Philippines
Celebes Coconut Corporation and regional processors in Davao and Quezon provinces supply spray-dried milk powder to Asian instant noodle and curry paste manufacturers. The country's coconut authority enforces quality grading standards for kernel moisture and oil content. Mindanao processing clusters face monsoon disruption risks that expose buyers to raw material volatility during typhoon seasons.
India
Ready-meal manufacturers in Maharashtra and Tamil Nadu underutilize domestic coconut milk processing capacity for ethnic cuisine production. FSSAI food safety standards govern microbiological specifications for coconut derivatives in packaged food applications. Kerala's coastal plantation belt supplies fresh kernel to local cream extraction units serving South Asian diaspora markets in Europe and North America.
Coconut Milk and Cream Market Competitive Environment
Player mix skews toward integrated Southeast Asian plantation-processors and multinational dairy-alternative brands with established retail distribution. Market structure concentrates around three archetypes: Thai and Filipino integrated operators controlling upstream supply, European and North American brand owners with dairy-alternative infrastructure, and specialty ingredient suppliers serving ethnic cuisine manufacturing. Dominant competitive moves include direct procurement contracting between food service chains and integrated processors, plus certification investments to satisfy EU Green Deal deforestation-free mandates.
Among integrated Southeast Asian operators, Thai Coconut Public Co. Ltd. and Theppadungporn Coconut Co., Ltd. exemplify the plantation-to-processing archetype with captive kernel supply. Danone S.A. represents the multinational dairy-alternative infrastructure play, leveraging existing plant-based beverage distribution networks. The Vita Coco Company, Inc. occupies a position in North American premium beverage segments built on brand recognition rather than upstream integration.
| Leading Market Players |
|---|
| Danone S.A. |
| The Vita Coco Company, Inc. |
| Thai Coconut Public Co. Ltd. |
| Sambu Group |
| Nestlé |
| Theppadungporn Coconut Co., Ltd. |
| McCormick & Company Inc. |
| Celebes Coconut Corporation |
| Goya Foods Inc. |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal deforestation-free mandates gate both supplier qualification and price differentiation simultaneously, forcing European importers to pay certification premiums while excluding uncertified origins from premium tier access. Thai and Philippine integrated processors capture margin through controlled upstream supply, while spot-market buyers absorb volatility from monsoon-disrupted harvests.
Pricing Analysis
Mechanical-pressing extraction lines trade at commodity benchmarks while enzymatic-extraction cream commands 15-25% premiums for cleaner flavor profiles. Three-tier pricing structure across organic-certified, conventional food-grade, and industrial-grade separates shelf-stable aseptic totes from canned formats and spray-dried powder. Cost compression in North American retail beverages stems from oat and almond substitution, squeezing coconut beverage margins. Food service operators show lowest price sensitivity due to menu standardization requirements, while private-label retail buyers drive hardest bargain.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for aseptic totes and 4-6 months for spray-dried powder, forcing working capital intensity on importers. Raw material supply concentrates in Thailand, the Philippines, and Indonesia, with kernel quality grading determining downstream fractionation yields. Processing capacity draws from cold-press equipment, enzyme treatment systems, and UHT stabilization lines. Single-source vulnerability runs through Thai coastal plantations exposed to typhoon disruption. Distribution runs through integrated processor direct contracts, regional ingredient distributors, and retail grocery multiples.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. EU Green Deal traceability requirements create switching costs that lock qualified suppliers into long-term manufacturing relationships.
For Market Incumbents: Fortify upstream kernel security through backward integration into Philippine and Indonesian coastal plantations. Invest in enzymatic extraction capacity to meet European dairy-alternative manufacturer specifications for cleaner flavor profiles. Oat milk substitution in North American retail threatens volume share; respond with aseptic packaging convergence enabling ambient distribution into food service channels previously limited to canned formats.
For New Entrants and Emerging Players: USDA organic certification fast-track opens shelf space in US natural grocery channels where incumbent brands lack penetration. Target Indian ready-meal manufacturers in Maharashtra and Tamil Nadu with bulk aseptic supply contracts, exploiting underutilized domestic processing capacity. Enter through direct procurement relationships with Los Angeles-based restaurant groups, bypassing established distributor layers in coastal metro markets.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across enzymatic extraction and carbon-accounting certification systems, favoring scaled operators with balance sheet capacity. Five-to-ten year viability hinges on EU Green Deal compliance infrastructure rather than commodity trading margins. Acquire integrated Thai plantation-processors with captive kernel supply and certified deforestation-free traceability. Monitor German importer consolidation through Hamburg and Rotterdam port clusters as inflection signal for pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Supply | Thai processors secure kernel access against monsoon volatility and price spikes. |
| Enzymatic Extraction Capacity Buildout | Bangkok exporters serve European dairy-alternative brands demanding cleaner flavor profiles. |
| USDA Organic Certification Investment | US natural grocery channels enforce supplier qualification through third-party audits. |
| Aseptic Packaging Technology Adoption | UHT processing enables ambient distribution into food service segments beyond canned formats. |
| Direct Procurement Relationship Development | Los Angeles restaurant groups contract with Thai Coconut Public Co. Ltd., shortening distributor layers. |
Study Parameters
Initial hypotheses were tested against primary input from coconut processing plant managers, European importer procurement leads, food service chain menu development directors, and FSSAI regulatory affairs specialists and refined through secondary validation. Trade data from Thai Customs and Philippine Coconut Authority production statistics, EU Green Deal implementation guidance, FDA food labeling guidance documents, and SEC filings from listed dairy-alternative manufacturers anchored quantitative baselines. Bottom-up volume builds from processor capacity utilization and top-down demand segmentation from end-use applications were cross-referenced for convergence.
Variance decomposition across product type, application segment, distribution channel, and end-user category shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers. Modeled dimensions included fat content tier, extraction technology generation, shelf-stability format, and regional regulatory cluster. Forecast inputs incorporated EU Corporate Sustainability Reporting Directive compliance timelines and enzymatic extraction adoption curves in European dairy-alternative manufacturing.
Decision-makers should treat outputs as directional under sustained EU Green Deal enforcement and stable Southeast Asian plantation yields; material deviation in either would warrant model refresh. Forecasts reflect assumptions about certification adoption rates and climate volatility patterns. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Savory Yogurt Market
Dairy Alternatives
Saudi Arabia Dairy Alternatives Market
Dairy Alternatives
US Lactose-Free Dairy Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
Dairy-Free Creams Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Germany Dairy Alternatives Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Sugar-Free Soy Milk Powder Market
Dairy Alternatives
Savory Yogurt Foods Market
Dairy Alternatives
Dairy Free Shortening Market
Dairy Alternatives
Dairy-Free Chocolate Market
Dairy Alternatives
Plant-Based Cheese Wedges Market
Dairy Alternatives
Rice Milk Market
Dairy Alternatives
South America Dairy Alternatives Market
Dairy Alternatives
Dairy Free Yogurt Market