
 North America Prebiotic Ingredients Market | 2026-2036
North America Prebiotic Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Prebiotic Ingredients Market Analytics
Plant-based inulin is consolidating market share as food formulators replace synthetic resistant starch in clean-label applications. Cargill, Incorporated leverages its North American chicory root supply chain to anchor domestic inulin production. DuPont de Nemours, Inc. competes through advanced enzymatic manufacturing platforms for oligosaccharide synthesis. Kerry Group plc differentiates via integrated flavor-masked prebiotic systems for beverage applications.
North America prebiotic ingredients comprise non-digestible food components—typically oligosaccharide chains of 3–10 sugar units or polysaccharide fibers like inulin—that resist upper gastrointestinal hydrolysis and selectively ferment in the colon to stimulate beneficial gut microbiota proliferation. Manufacturers extract these compounds from chicory root, Jerusalem artichoke, or dairy whey, then standardize to minimum purity thresholds for commercial food, pharmaceutical, and feed integration. Inulin dominates product type volumes due to established extraction infrastructure and broad GRAS recognition, while oligosaccharides represent the fastest-expanding category driven by infant formula and clinical nutrition demand. Plant-based sourcing leads volume given consumer preference for recognizable ingredient origins, though dairy-based prebiotics sustain premium positioning within probiotic combination supplements.
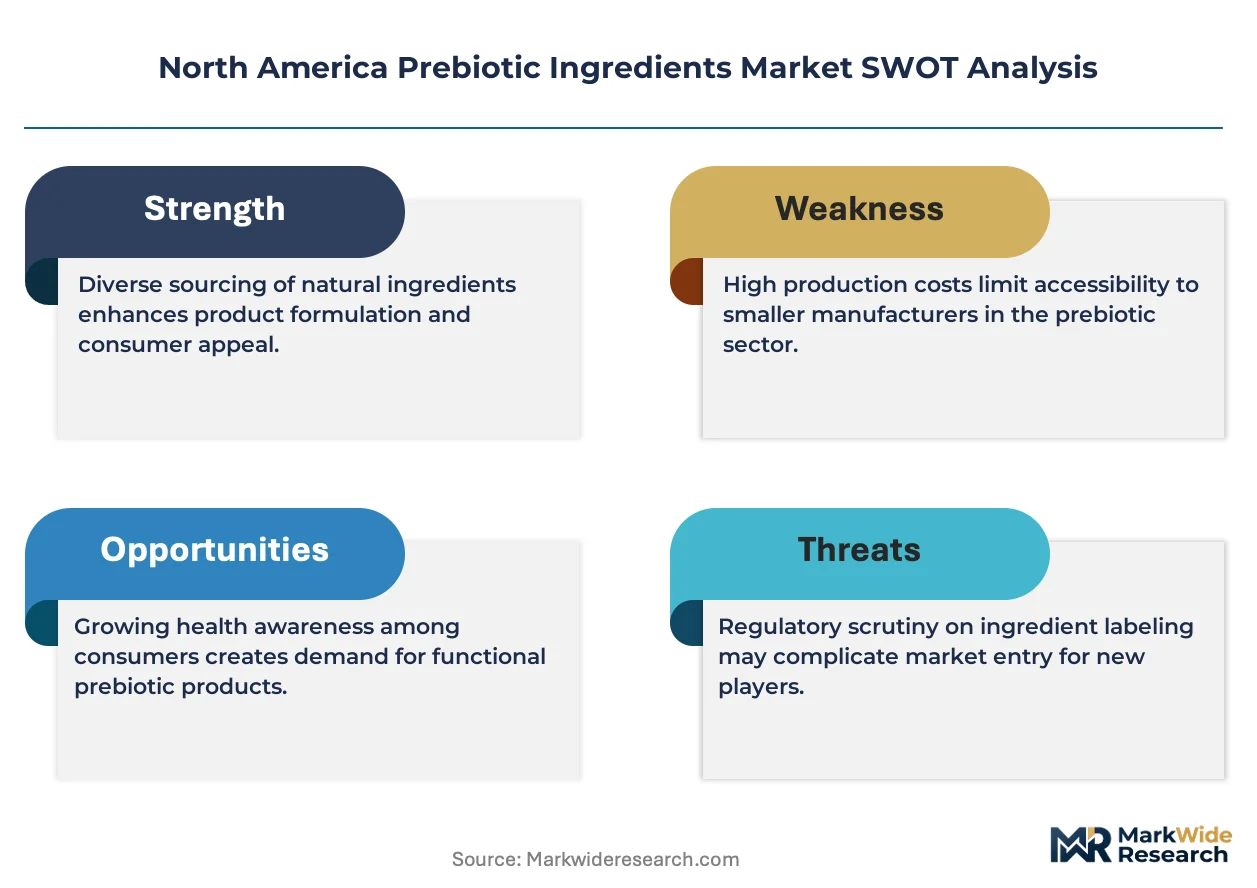
The U.S. FDA oversees GRAS self-affirmation and notification pathways that determine which novel prebiotic fibers achieve food additive clearance, while Health Canada administers the Food and Drug Regulations and Natural Health Products Directorate standards governing prebiotic health claims and supplement labeling across Canadian provinces. These frameworks shape formulation decisions, as unapproved fiber types face restricted use in conventional foods and limited marketing language. Stakeholders must monitor evolving fiber definition harmonization between FDA and Health Canada, as divergent classifications between jurisdictions fragment cross-border product development strategies and complicate unified North American portfolio planning.
Market Dynamics
The U.S. FDA's evolving GRAS notification framework for novel fibers is compressing approval timelines and accelerating ingredient innovation pipelines across the North American prebiotic ingredients market.
Growth Catalysts
- FDA GRAS Modernization:The FDA's streamlined self-affirmation pathway for novel prebiotic fibers is reducing regulatory friction for chicory root and Jerusalem artichoke derivatives entering conventional foods.
- Infant Formula Fortification:Oligosaccharide demand from clinical nutrition manufacturers in California and New York formulation clusters is pulling volume through specialized distribution channels.
- Clean-Label Substitution:Food formulators are replacing synthetic resistant starch with plant-based inulin to meet retailer ingredient transparency mandates.
Market Restraints
- Chicory Root Supply Concentration:Belgian and Dutch agricultural processors control upstream chicory root extraction capacity, creating input cost volatility for North American inulin manufacturers.
- Health Canada Divergence:The Natural Health Products Directorate maintains distinct fiber classification standards from FDA definitions, fragmenting cross-border product development.
- Enzymatic Production Costs:Advanced oligosaccharide synthesis requires specialized biocatalytic infrastructure that limits manufacturing scale-up for mid-tier producers.
Strategic Opportunities
- Canadian Prairie Expansion:Saskatchewan and Manitoba Jerusalem artichoke cultivation offers domestic polysaccharide sourcing to reduce trans-Atlantic supply dependency.
- Pet Nutrition Crossover:Functional animal feed applications for gut microbiome modulation represent an underpenetrated vertical with minimal regulatory overlap.
- Beverage System Integration:Flavor-masked prebiotic delivery formats enable entry into ready-to-drink categories previously blocked by sensory limitations.
Industry Challenges
- Microbiome Scientist Shortage:Formulation teams lack sufficient gut health specialists to execute clinical substantiation for structure-function claims.
- Dual-Jurisdiction Compliance:Product managers must maintain parallel documentation systems for FDA GRAS self-affirmation and Health Canada Natural Product Number applications.
- Legacy ERP Integration:Batch tracking requirements for prebiotic purity standardization clash with existing food manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Prebiotic Ingredients Market |
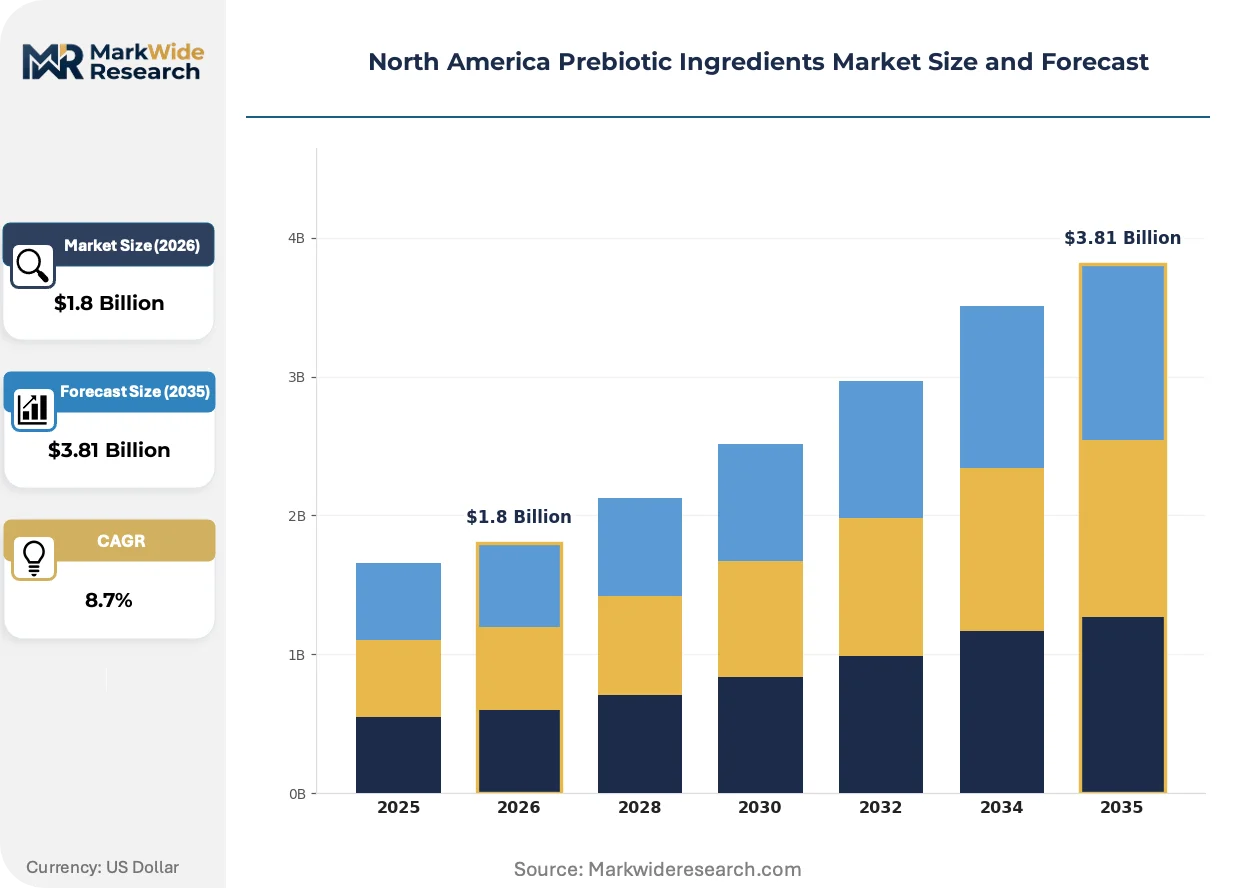
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inulin, Oligosaccharides, Lactulose, Resistant Starch End User: Food & Beverage, Pharmaceuticals, Dietary Supplements, Animal Feed Source: Plant-based, Dairy-based, Synthetic, Others Application: Functional Foods, Probiotic Supplements, Nutraceuticals, Food Fortification |
| Companies Covered | Ingredion Incorporated, Cargill, Incorporated, DuPont de Nemours, Inc., Kerry Group plc, Sensus NV, Beneo GmbH, FrieslandCampina, Archer Daniels Midland Company, Roquette America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Prebiotic Ingredients Market Evolving Landscape
Enzymatic manufacturing platforms and evolving fiber regulatory frameworks are compressing development cycles while procurement teams reshape supplier qualification criteria across the North American prebiotic ingredients market.
Enzymatic oligosaccharide synthesis is consolidating technical differentiation among advanced biocatalytic producers. Infant formula and clinical nutrition manufacturers are adopting these precision-manufactured ingredients at accelerating rates. This technology is consolidating market position for suppliers with in-house enzymatic capabilities while marginalizing conventional acid-hydrolysis operations.
The FDA's evolving GRAS notification framework is compressing approval timelines for novel prebiotic fibers. Food additive clearance pathways now accommodate shorter safety substantiation packages for well-characterized oligosaccharide structures. Dietary supplement manufacturers in California and New York formulation clusters are responding by accelerating pipeline diversification into GRAS-affirmed ingredients.
Direct-procurement relationships between prebiotic ingredient suppliers and functional food brand owners are displacing traditional distributor intermediaries. Large beverage and snack manufacturers are consolidating supplier bases to capture volume pricing and technical collaboration access. This channel compression is most visible among California-based clean-label brands seeking captive supply agreements for inulin and fructooligosaccharide streams.
North America Prebiotic Ingredients Market Segmentation
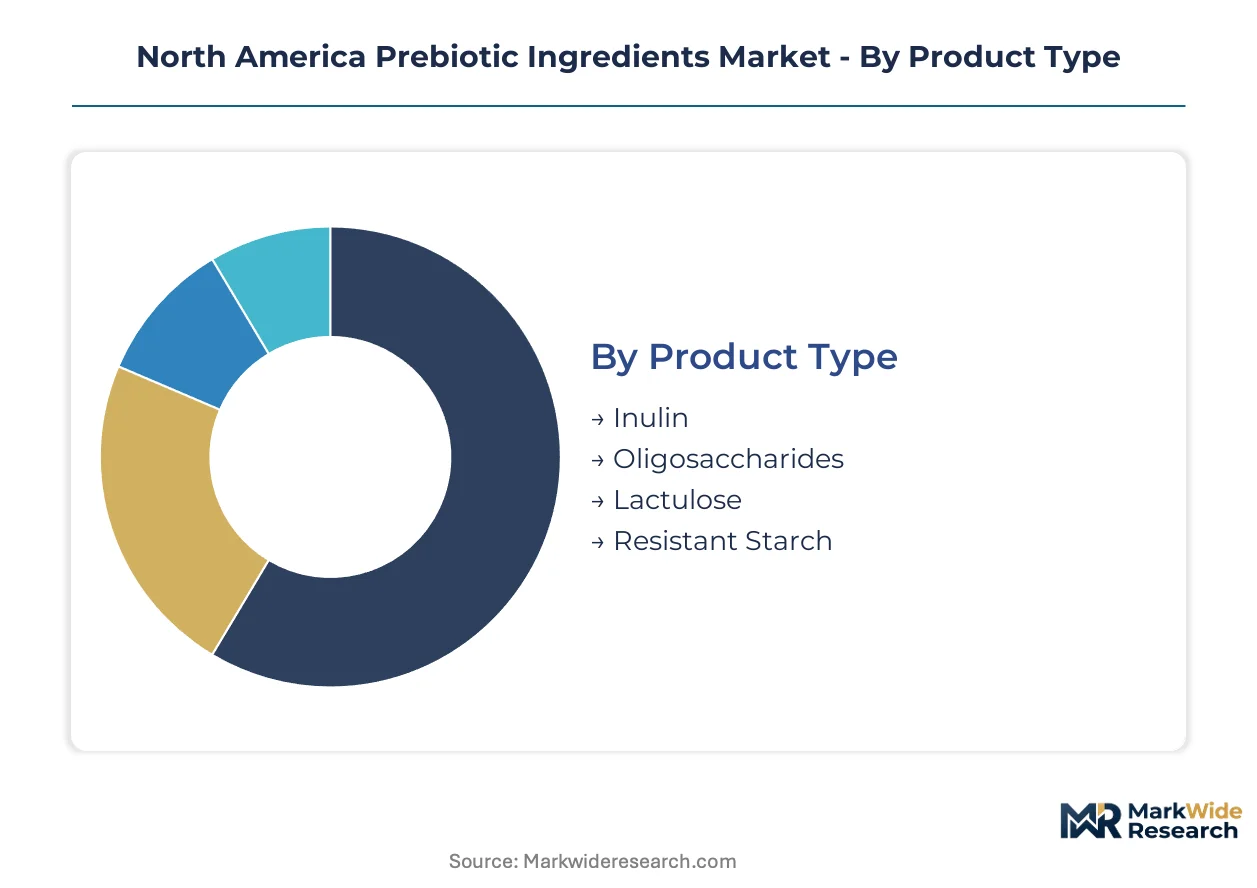
Prebiotic ingredient purchasing patterns diverge sharply across formulation requirements, with food manufacturers prioritizing sensory compatibility while pharmaceutical buyers demand clinical-grade purity documentation. Understanding these segment-specific technical thresholds enables suppliers to align extraction and standardization investments with actual demand concentration.
Product Type:
Formulators are upgrading from first-generation resistant starch to precision-fermentable oligosaccharides as clean-label mandates intensify and GRAS pathways mature for novel fiber structures.
- Inulin:Long-chain polysaccharide (degree of polymerization 10-60) extracted primarily from chicory root through hot-water diffusion. Food and beverage manufacturers in the Midwest and California formulation clusters consume bulk volumes for bakery and dairy texture modification, though Belgian-Dutch upstream concentration creates price volatility for North American compounders.
- Oligosaccharides:Short-chain structures (fructooligosaccharides, galactooligosaccharides) manufactured via enzymatic biocatalysis or acid hydrolysis. Infant formula producers in New York and clinical nutrition specialists are pulling volume through specialized distribution channels as FDA GRAS notifications accelerate for well-characterized structures.
- Lactulose:Synthetic disaccharide produced through alkaline isomerization of lactose, positioned primarily for pharmaceutical laxative applications rather than microbiome modulation.
- Resistant Starch:Retrograded or chemically modified starch fractions, now losing share to plant-based alternatives as retailers enforce ingredient transparency mandates.
Volume placements concentrate in inulin; the faster expansion belongs to oligosaccharides.
End User:
Cost tier differentiation separates commodity-scale food fortification from premium-priced clinical nutrition, with regulatory documentation requirements widening the procurement gap between segments.
- Food & Beverage:Clean-label brands and legacy manufacturers across the United States and Canada are replacing synthetic fibers with chicory-derived inulin to meet retailer transparency mandates. California-based beverage innovators and Midwest dairy processors anchor regional demand concentration.
- Dietary Supplements:Probiotic combination products and standalone prebiotic capsules drive premium pricing, with New York and California formulation clusters specializing in GRAS-affirmed ingredient sourcing.
- Pharmaceuticals:Clinical nutrition and medical food applications require batch-level purity certification and structure-function claim substantiation, limiting supplier qualification to manufacturers with dedicated pharmaceutical-grade production lines.
- Animal Feed:Functional pet nutrition and livestock gut health modulation represent an underpenetrated vertical with minimal regulatory overlap and growing veterinary microbiome research investment.
Revenue margins peak in pharmaceuticals; volume scale dominates food and beverage procurement.
Source:
Supply concentration patterns favor domestic cultivation investments as formulators seek to reduce trans-Atlantic chicory root dependency and secure captive raw material streams.
- Plant-based:Chicory root and Jerusalem artichoke extraction leads volume given consumer preference for recognizable ingredient origins. Saskatchewan and Manitoba agricultural expansion programs are targeting domestic polysaccharide sourcing to offset European processor concentration.
- Dairy-based:Whey-derived galactooligosaccharides sustain premium positioning within infant formula and probiotic combination supplements, though lactose supply constraints limit manufacturing scale-up.
- Synthetic:Chemically produced resistant starch and modified polysaccharides are losing formulation share as clean-label substitution accelerates across conventional food categories.
- Others:Emerging fermentation-derived and algae-sourced prebiotics remain pre-commercial, awaiting FDA GRAS affirmation for food additive clearance.
Plant-based sourcing commands volume leadership; dairy-based maintains premium price positioning.
Application:
Customer maturity separates established functional food categories from emerging nutraceutical formats where sensory masking and delivery system innovation determine commercial viability.
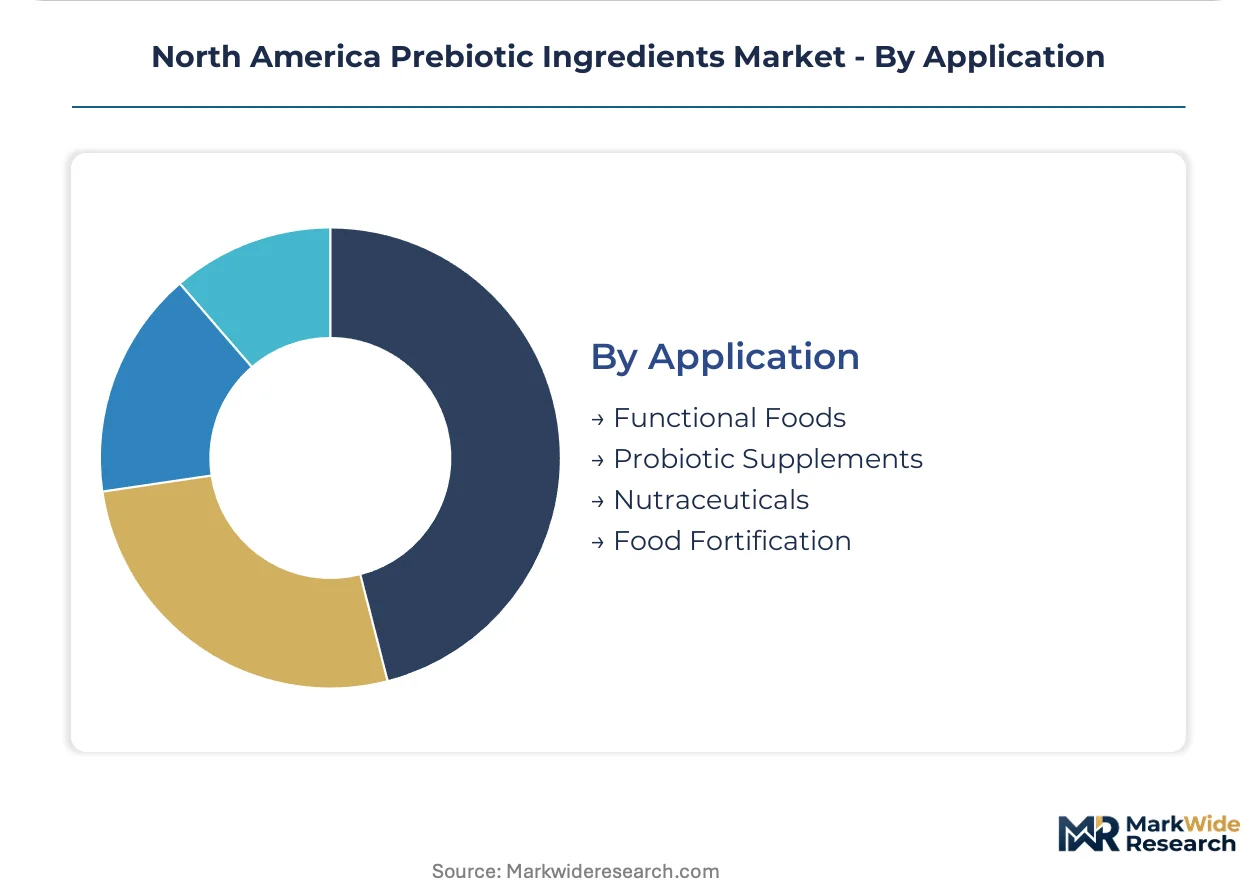
- Functional Foods:Prebiotic-fortified yogurts, cereals, and baked goods represent the most penetrated application, with Midwest dairy processors and California clean-label brands driving formulation standardization.
- Probiotic Supplements:Synbiotic combinations pairing prebiotic fibers with live cultures require stability testing and shelf-life validation, concentrating demand among specialized contract manufacturers.
- Nutraceuticals:Medical foods and condition-specific nutrition products demand clinical substantiation for structure-function claims, creating documentation barriers for commodity-grade suppliers.
- Food Fortification:Mass-market staple fortification (flour, beverages, dairy) represents volume opportunity constrained by price sensitivity and sensory compatibility requirements.
Functional foods anchor current volume; nutraceuticals are climbing the fastest as clinical validation investments mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in California and New York accelerate prebiotic ingredient demand concentration. Canadian prairie provinces attract agricultural investment through targeted cultivation incentives. Mexican maquiladora corridors near the US border process raw botanical extracts for cross-border supply chains.
United States
FDA GRAS modernization compresses approval timelines for novel fibers entering conventional foods. California formulation clusters in San Francisco and Los Angeles drive beverage innovation with flavor-masked prebiotic systems. Midwest dairy processors anchor inulin demand for yogurt and baked goods fortification.
Canada
Health Canada's Natural Health Products Directorate maintains distinct fiber classification standards from FDA definitions. Saskatchewan and Manitoba Jerusalem artichoke expansion programs target domestic polysaccharide sourcing. Ontario-based supplement manufacturers concentrate probiotic combination product development.
Mexico
Nearshoring incentives in Nuevo León and Baja California attract botanical extraction facilities serving US brands. COFEPRIS regulatory alignment efforts with FDA frameworks facilitate cross-border ingredient trade. Guadalajara formulation clusters specialize in cost-optimized prebiotic blending for Latin American markets.
North America Prebiotic Ingredients Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated ingredient suppliers commanding premium positioning in pharmaceutical-grade applications while toll manufacturers capture commodity food fortification volumes. The vendor base organizes around three archetypes: agricultural processors with captive chicory root supply chains, enzymatic biocatalysis specialists, and flavor-system integrators masking sensory off-notes. Dominant competitive moves include backward integration into raw cultivation and strategic partnerships with infant formula manufacturers.
Among North American agricultural processors, Cargill, Incorporated and Roquette America exemplify scale-driven chicory root sourcing archetypes. DuPont de Nemours, Inc. occupies a position within the enzymatic manufacturing tier for precision oligosaccharide synthesis. Kerry Group plc anchors the integrated flavor-system vector with prebiotic delivery expertise.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill, Incorporated |
| DuPont de Nemours, Inc. |
| Kerry Group plc |
| Sensus NV |
| Beneo GmbH |
| FrieslandCampina |
| Archer Daniels Midland Company |
| Roquette America |
| Others |
Value Network & Pricing Analysis
Infant formula manufacturers in New York and California formulation clusters command pricing leverage through long-term offtake agreements, while food fortification buyers face spot-market volatility driven by Belgian-Dutch chicory root concentration. Pharmaceutical-grade prebiotic procurement operates on certification-tiered contracts, with clinical nutrition specialists absorbing premium pricing for batch-level purity documentation.
Pricing Analysis
Short lead-time premiums dominate pharmaceutical-grade prebiotic transactions, with clinical nutrition manufacturers paying elevated rates for expedited GRAS-affirmed oligosaccharide delivery. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade certification from food-grade inulin from feed-grade resistant starch. Cost compression in commodity food fortification is intensifying because Midwest dairy processors and California beverage brands are consolidating supplier bases for volume discounts. Dietary supplement contract manufacturers exhibit highest price sensitivity due to margin pressure from probiotic combination product competition, while infant formula specialists show lowest sensitivity given regulatory compliance requirements.
Supply Chain Analysis
Chicory root extraction capacity rests on Belgian and Dutch agricultural processors, with North American manufacturers dependent on trans-Atlantic raw material flows for inulin production. Jerusalem artichoke cultivation in Saskatchewan and Manitoba and enzymatic biocatalysis infrastructure in the United States represent emerging domestic alternatives. Single-source vulnerability in European upstream processing exposes North American compounders to input cost volatility from energy price fluctuations and currency movements. Distribution runs through direct-procurement relationships between ingredient suppliers and functional food brand owners, displacing traditional distributor intermediaries among California clean-label brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around enzymatic manufacturing capabilities and captive raw material sourcing, with FDA GRAS modernization and Health Canada divergence pressures forcing acid-hydrolysis operators and distributor-dependent suppliers toward exit or acquisition.
For Market Incumbents: Deepen backward integration into Saskatchewan and Manitoba Jerusalem artichoke cultivation to offset European chicory root dependency, while expanding in-house enzymatic biocatalysis capacity to defend against precision-oligosaccharide specialists. Secure captive supply agreements with infant formula manufacturers in New York formulation clusters before GRAS notification pathways mature for additional competitors. Prioritize Health Canada Natural Product Number pre-clearance to maintain cross-border portfolio coherence against FDA-Health Canada regulatory divergence. For New Entrants and Emerging Players: Launch via toll manufacturing partnerships with Midwest dairy processors seeking clean-label inulin fortification, avoiding capital-intensive extraction infrastructure. Target pet nutrition and functional animal feed applications as the most penetrable vertical, given minimal regulatory overlap and underdeveloped supplier qualification requirements. Differentiate through flavor-masked prebiotic delivery systems for ready-to-drink beverage categories where sensory limitations currently block incumbent entry. For Investors and Strategic Acquirers: The window for entry favors enzymatic biocatalysis specialists with pharmaceutical-grade certification infrastructure and established FDA GRAS notification track records. Mid-cap acid-hydrolysis operators facing margin compression from enzymatic competition represent distressed acquisition targets with retoolable assets. Watch Health Canada-FDA fiber definition harmonization negotiations as the critical inflection signal for cross-border product development economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Cultivation | Saskatchewan and Manitoba Jerusalem artichoke programs reduce trans-Atlantic chicory root dependency for North American inulin manufacturers. |
| Enzymatic Manufacturing Scale-Up | Advanced biocatalytic infrastructure enables precision oligosaccharide synthesis for infant formula and clinical nutrition demand concentration. |
| GRAS Notification Pipeline Expansion | FDA self-affirmation pathway acceleration supports novel fiber clearance for conventional food additive applications. |
| Flavor-System Integration Investment | Masked prebiotic delivery formats unlock ready-to-drink beverage categories previously blocked by sensory off-notes. |
| Pet Nutrition Vertical Entry | Functional animal feed applications offer underpenetrated growth with minimal regulatory overlap and rising veterinary microbiome research. |
Research Methodology
Multi-period observation of FDA GRAS notification volumes, Health Canada Natural Product Number issuances, and chicory root import flows anchored the trend analysis, supplemented by interviews with prebiotic ingredient procurement directors at infant formula manufacturers, enzymatic biocatalysis R&D leads, FDA regulatory affairs consultants, Health Canada compliance officers, and functional food brand managers. Secondary validation drew from FDA GRAS notification databases, Health Canada Licensed Natural Health Products Database, U.S. Census Bureau import statistics, and SEC 10-K filings of publicly traded ingredient suppliers. Bottom-up segment sizing triangulated against top-down market value estimates derived from production capacity and average selling price assumptions.
Segment-weighting across product type, end user, source, and application dimensions informed volume and value distribution modeling throughout the forecast period. CAGRs were derived from regression analysis of historical growth patterns adjusted for regulatory pathway maturation and supply chain reconfiguration dynamics. Industry-specific inputs included FDA GRAS affirmation timelines for novel fiber structures, enzymatic manufacturing capacity expansion announcements, and Jerusalem artichoke cultivation acreage projections from Canadian prairie agricultural programs.
Regulatory pathway delays, European chicory root harvest variability, and enzymatic production cost trajectories are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Birch Sap Market
Ingredients
Cold Pressed Oil Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Microencapsulated Oil Market
Ingredients
Roll-Dried Starch Market
Ingredients
Ingredients Market
Ingredients
Revivable Yeast Market
Ingredients
Europe Dairy Protein Market
Ingredients
North America Cheese Powder Market
Ingredients
Wheat Germ Oil Market
Ingredients
Global Inactive Dried Yeast Market
Ingredients
Cocoa Fiber Market
Ingredients
South America Fermented Ingredients Market
Ingredients
India Protein Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Licorice Root Market