
 India Dairy Alternatives Market | 2026-2036
India Dairy Alternatives Market Size, Share, and Industry Trends Forecast 2026-2036
India Dairy Alternatives Market Insights
Oat protein concentrate is recalibrating cost structures across India Dairy Alternatives formulations, narrowing the price gap with traditional dairy. Epigamia leverages its cold-chain infrastructure to dominate premium refrigerated segments in metropolitan outlets. Goodmylk Co. anchors its position through in-house production of oat and almond bases, securing supply consistency. Country Delight competes on direct-to-home delivery density, reaching consumers outside conventional retail catchments.
India dairy alternatives encompass plant-derived beverages and food ingredients formulated to replicate the functional properties of bovine milk, typically containing two to twelve percent plant solids with emulsifiers and fortificants to achieve comparable mouthfeel and nutritional profiles. These products serve consumers seeking lactose-free, cholesterol-free, or ethically sourced nutrition across beverage, culinary, and snacking applications. Almond milk occupies the premium shelf position in urban supermarkets, commanding higher margins despite import dependency on raw kernels. Soy milk sustains volume leadership through established processing infrastructure and lower input costs, though growth decelerates relative to emerging options. Oat milk captures the fastest expansion trajectory, driven by café partnerships and perceived environmental credentials among health-conscious consumers.
FSSAI standards govern product nomenclature and nutritional claims for plant-based beverages in India, while BIS certification requirements influence packaging and shelf-stability parameters for national distribution. The PLI scheme for food processing incentivizes domestic manufacturing scale-up, reducing reliance on imported oat and almond raw materials. Stakeholders must monitor regulatory clarity on dairy terminology restrictions and the pace of organized retail expansion into tier-two cities as determinants of addressable market geometry.
Market Dynamics
Oat milk's rapid café adoption in Mumbai and Bangalore is compressing soy milk's long-held volume dominance, while FSSAI's evolving plant-based labeling standards force reformulation investments across domestic manufacturers.
Growth Catalysts
- PLI Scheme for Food Processing:Production-linked incentives subsidize domestic oat and almond processing equipment, reducing import dependency on raw kernels from Australia and California.
- Urban Café Partnerships:Specialty coffee chains in Maharashtra and Karnataka now standardize oat milk as the default dairy alternative, normalizing consumption among affluent millennials.
- Organized Retail Expansion:Modern trade formats in Pune and Hyderabad dedicate refrigerated shelf space to premium plant-based beverages, accelerating trial among first-time buyers.
Market Restraints
- Raw Material Import Concentration:Almond kernel supply chains remain captive to California drought cycles and shipping cost volatility, squeezing margin predictability for local processors.
- Cold-Chain Infrastructure Gaps:Tier-two cities lack consistent refrigerated logistics, limiting shelf-stable product penetration outside metropolitan zones.
- FSSAI Nomenclature Restrictions:Pending restrictions on "milk" terminology in plant-based labeling create compliance uncertainty and potential relabeling costs.
Strategic Opportunities
- Tier-Two City Penetration:Direct-to-home delivery models in Ahmedabad and Jaipur bypass retail infrastructure gaps, capturing households outside organized trade catchments.
- Fortification Mandates Alignment:FSSAI's micronutrient fortification guidelines for plant-based beverages create first-mover advantage for calcium and vitamin D enriched formulations.
- Oat Protein Concentrate Integration:Domestic enzyme hydrolysis technology converges with local oat sourcing to enable cost-competitive protein fortification without dairy inputs.
Industry Challenges
- Emulsifier Sourcing Complexity:Food-grade lecithin supply from sunflower and rapeseed origins faces price instability, forcing continuous formulation adjustments to maintain mouthfeel consistency.
- Shelf-Stability Certification Timelines:BIS approval processes for aseptic packaging configurations delay new product launches by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Dairy Alternatives Market |
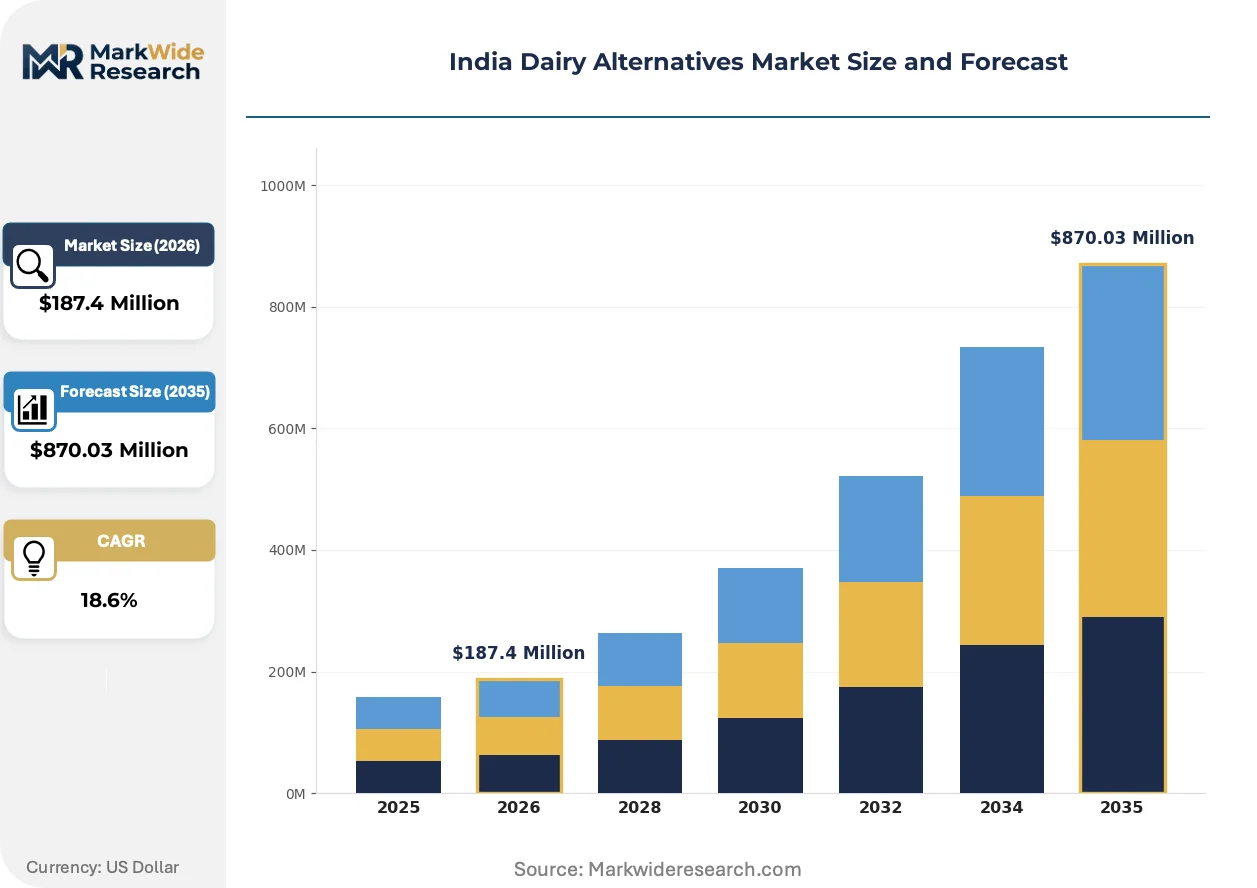
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Almond Milk, Soy Milk, Oat Milk, Coconut Milk Application: Beverages, Cooking Ingredients, Dairy Substitutes, Snacks Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Health Food Stores Customer Type: Health Conscious Consumers, Vegans, Lactose Intolerant Individuals, Fitness Enthusiasts |
| Companies Covered | Epigamia, The Alternative Company, Goodmylk Co., The Hershey Company, Jus Amazin, Country Delight, Only Earth, Grabenord, Raw Pressery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Dairy Alternatives Market Trends and Innovations
Clean-label enzymatic processing is eliminating chemical additive dependence, while regional sourcing mandates and subscription commerce models reshape how plant-based nutrition reaches Indian households.
Enzymatic oat processing is overtaking conventional chemical hydrolysis methods in premium formulation facilities. Specialty manufacturers in Bangalore and Pune deploy cellulase and amylase blends to achieve creamy textures without synthetic emulsifiers. This biotechnology shift enables shorter ingredient lists that satisfy FSSAI's evolving clean-label expectations while reducing import dependency on European processing aids.
FSSAI's draft guidelines on plant-based dairy terminology are forcing preemptive packaging redesigns across domestic manufacturers. The regulatory uncertainty compresses marketing investment cycles as brands await final nomenclature rulings. Premium positioned products in Maharashtra face the highest exposure, with several labels already pivoting to "oat beverage" and "almond drink" descriptors ahead of formal mandates.
Subscription-based replenishment models are displacing intermittent supermarket purchases among urban households. Direct-to-home platforms in Delhi-NCR and Bangalore lock consumers into monthly oat and almond milk deliveries at price points below premium retail. This channel shift concentrates demand forecasting power with platform operators, squeezing traditional distributor margins and forcing manufacturers to negotiate volume commitments against payment term compression.
India Dairy Alternatives Market Segmentation
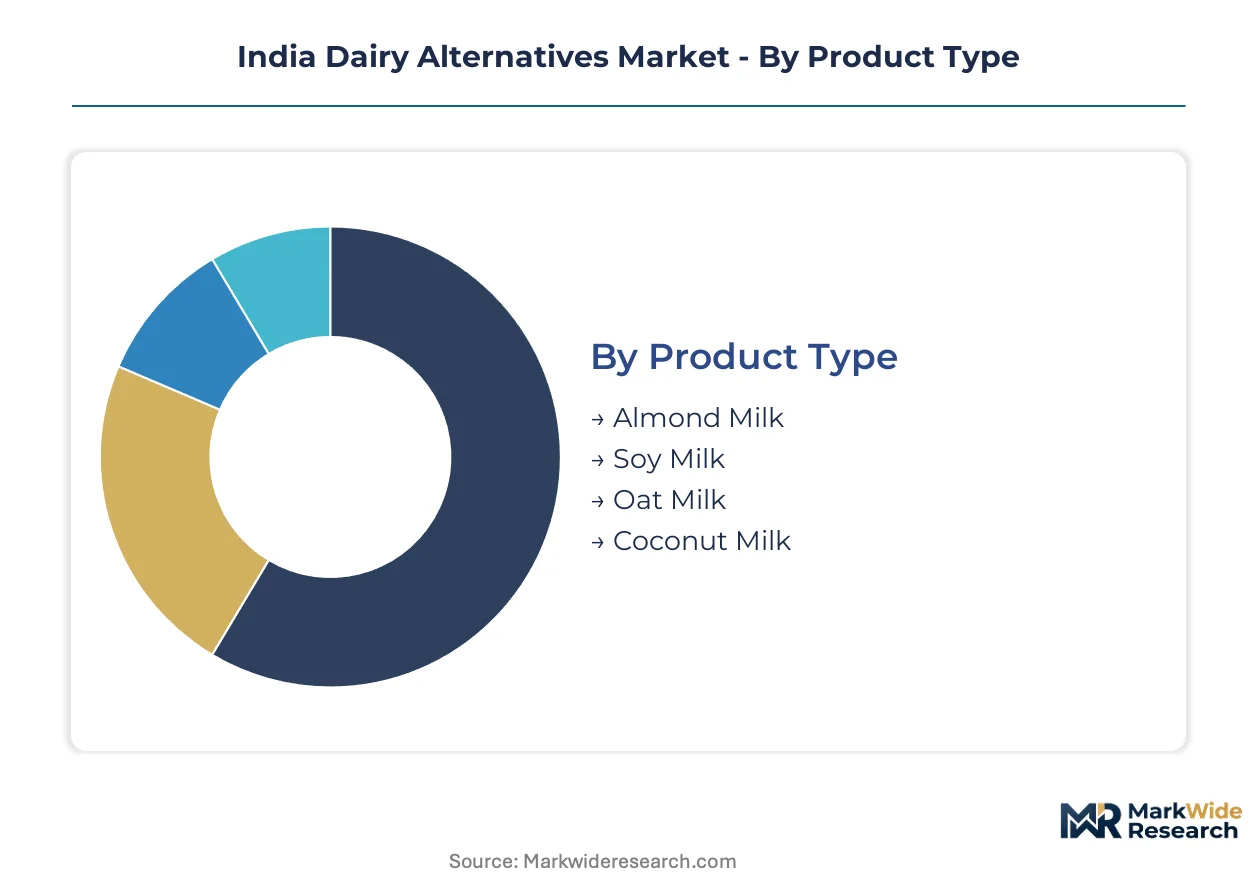
India's dairy alternatives landscape fragments across ingredient sourcing constraints, application versatility, and channel accessibility. Understanding these segment boundaries clarifies where formulation investments concentrate and how regulatory pressures reshape competitive positioning.
Product Type:
Supply concentration for raw inputs—California almonds, Australian oats, domestic soy—determines margin structures and geographic availability across each product category.
- Soy Milk:Established processing infrastructure leverages domestic soybean crushing capacity, yielding the lowest unit economics among plant-based options. Volume concentrates in Maharashtra and Gujarat, where organized dairy cooperatives have pivoted equipment toward plant-based lines.
- Oat Milk:Enzymatic hydrolysis technology enables creamy mouthfeel without chemical additives, attracting café partnerships in Mumbai and Bangalore. Import dependency on Australian grain creates working capital intensity for local processors.
- Almond Milk:California kernel imports drive premium positioning in urban supermarkets, with FSSAI fortification mandates pushing calcium and vitamin D enrichment as standard.
- Coconut Milk:Kerala and Tamil Nadu coastal sourcing provides regional cost advantages for culinary applications, though limited shelf-stable processing constrains national distribution.
Today's leader: Soy Milk. Tomorrow's challenger: Oat Milk.
Application:
End-use differentiation separates commodity-grade formulations from value-added propositions, with café and culinary channels commanding technical specifications that retail beverages ignore.
- Beverages:Ready-to-drink formats dominate refrigerated shelf space in modern trade, with barista-specific oat variants capturing premium placement in Maharashtra and Karnataka coffee chains.
- Dairy Substitutes:Functional replication of dairy proteins in baking and confectionery requires specific emulsifier blends, narrowing supplier qualification to Bangalore and Pune specialty manufacturers.
- Cooking Ingredients:Coconut and soy bases anchor South Indian and North Indian regional cuisines respectively, with tetra-pack stability enabling pantry stocking outside cold-chain catchments.
- Snacks:Emerging category leveraging oat and almond bases for yogurt-style preparations, constrained by BIS certification timelines for aseptic packaging configurations.
Beverages generate current volume concentration. Dairy substitutes offer the steepest expansion trajectory as bakery chains standardize plant-based inputs.
Distribution Channel:
Channel selection directly determines temperature requirements, margin structures, and consumer education burdens for manufacturers entering India's fragmented retail landscape.
- Supermarkets:Modern trade formats in Delhi-NCR and Bangalore dedicate refrigerated linear meters to premium plant-based beverages, with placement fees compressing net margins for emerging brands.
- Online Retailers:Subscription models lock urban households into monthly replenishment cycles, concentrating demand forecasting power with platform operators and squeezing traditional distributor margins.
- Specialty Stores:Health-focused retail in Pune and Hyderabad offers curated discovery environments for clean-label enzymatic products, bypassing commodity price competition.
- Health Food Stores:Ayurveda-aligned outlets in tier-two cities drive trial among first-time buyers, though limited cold-chain infrastructure restricts refrigerated SKU penetration.
Supermarkets anchor present revenue. Online retailers are displacing intermittent purchase patterns fastest among metropolitan millennials.
Customer Type:
Consumer motivation segmentation reveals where premium pricing tolerance intersects with nutritional literacy, shaping formulation and communication strategies.
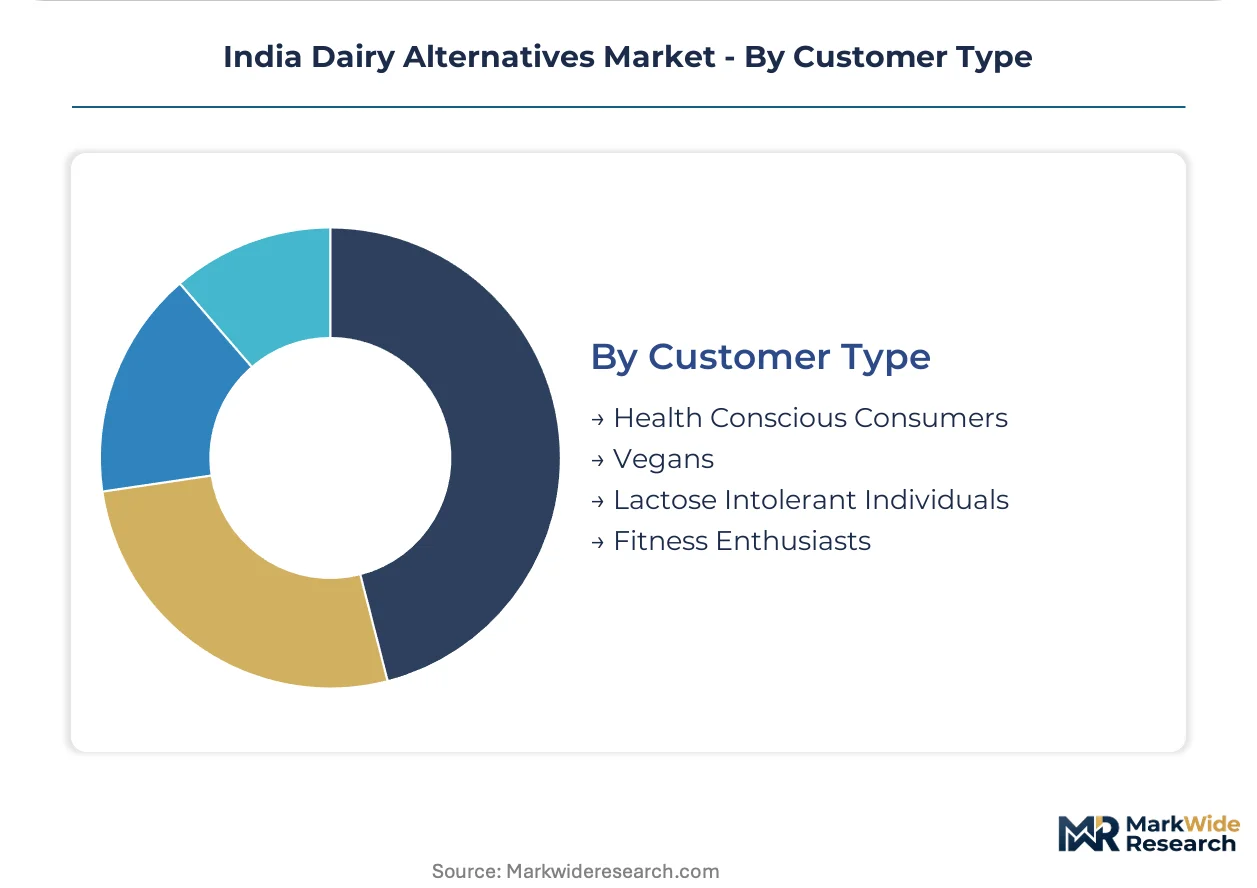
- Health Conscious Consumers:Micronutrient fortification awareness drives calcium and vitamin D demand, with FSSAI labeling standards creating compliance thresholds that filter subscale competitors.
- Lactose Intolerant Individuals:Medical necessity segment with lowest price elasticity, concentrated in North Indian urban populations with documented dairy digestion prevalence.
- Vegans:Ethical sourcing requirements prioritize domestic oat and coconut origins over imported almond inputs, with environmental credential claims subject to FSSAI substantiation rules.
- Fitness Enthusiasts:Protein-fortified variants attract gym-affiliated consumers in Mumbai and Bangalore, though oat protein concentrate integration remains cost-prohibitive for mass positioning.
Health conscious consumers dominate current spend. Fitness enthusiasts represent the fastest-climbing segment as protein fortification technology matures domestically.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra anchors India's dairy alternatives production, with Mumbai's café density and Pune's processing infrastructure creating a concentrated demand-supply corridor that shapes national pricing benchmarks.
Maharashtra
Café partnerships in Mumbai drive oat milk normalization among affluent millennials, while FSSAI's evolving plant-based labeling standards force reformulation investments across Pune-based manufacturers. The Mumbai-Pune industrial belt concentrates enzymatic processing capacity for premium beverage formulations.
Karnataka
Specialty coffee chains in Bangalore standardize oat milk as default dairy alternatives, compressing soy milk's historical volume dominance in South Indian markets. The state's PLI scheme beneficiaries expand domestic oat processing equipment, reducing Australian grain import dependency. Bangalore's food-tech cluster incubates clean-label enzymatic startups.
Gujarat
Established soybean crushing infrastructure enables lowest-unit-economics soy milk production, serving price-sensitive North Indian markets through cooperative dairy equipment pivots. FSSAI fortification mandates push calcium and vitamin D enrichment as standard across Surat and Ahmedabad processing facilities. The Anand dairy cooperative belt repurposes chilling networks for plant-based distribution.
Delhi-NCR
Direct-to-home subscription platforms lock urban households into monthly replenishment cycles, bypassing retail infrastructure gaps in satellite cities. BIS certification requirements for aseptic packaging delay new product launches by six to nine months across Noida and Gurugram manufacturing zones. The region's cold-chain density enables refrigerated SKU penetration unmatched in tier-two catchments.
Tamil Nadu
Coastal coconut sourcing provides regional cost advantages for culinary applications, though limited shelf-stable processing constrains national distribution beyond traditional South Indian consumption patterns. FSSAI nomenclature restrictions on "milk" terminology create compliance uncertainty for Chennai-based exporters targeting North Indian markets. The state's tetra-pack infrastructure expansion targets pantry-stocking formats outside cold-chain dependencies.
India Dairy Alternatives Market Competitive Landscape
Capacity expansion dominates the current landscape as domestic processors scale enzymatic hydrolysis technology to capture café channel growth. The market structures around three tiers: multinational food conglomerates with legacy beverage infrastructure, domestic dairy cooperatives pivoting equipment toward plant-based lines, and venture-backed food-tech startups specializing in clean-label formulations. Strategic archetypes include cold-chain-dependent premium refrigerated players, shelf-stable mass-market commoditizers, and direct-to-home subscription platforms. Vertical integration into in-house oat and almond base production represents the dominant competitive move, alongside geographic expansion into tier-two cities through delivery density investments.
Within the domestic food-tech tier, Epigamia leverages its cold-chain infrastructure to anchor premium refrigerated positioning in metropolitan outlets, while Goodmylk Co. exemplifies backward integration strategy through captive oat and almond base production. Country Delight occupies the direct-to-home delivery density archetype, reaching consumers outside conventional retail catchments through subscription lock-in mechanics.
| Leading Market Players |
|---|
| Epigamia |
| The Alternative Company |
| Goodmylk Co. |
| The Hershey Company |
| Jus Amazin |
| Country Delight |
| Only Earth |
| Grabenord |
| Raw Pressery |
| Others |
Pricing and Supply Chain Analysis
Enzymatic processing certification bifurcates the India dairy alternatives landscape into premium clean-label formulations and commodity chemical-hydrolysis alternatives, with this tier divergence manifesting in both input cost structures and supply chain sourcing patterns. FSSAI's evolving fortification mandates and nomenclature restrictions amplify this split, forcing manufacturers to choose between investing in domestic enzyme technology or accepting thinner margins on import-dependent conventional processing.
Pricing Analysis
Input-cost pass-through from California almond kernel imports and Australian oat grain sourcing governs margin structures across premium tiers, while domestic soy crushing capacity anchors economy pricing in Gujarat and Maharashtra. Price differentiation rests on enzymatic certification status and cold-chain delivery capability, with metropolitan café channels showing lowest price sensitivity and tier-two health food stores exhibiting highest elasticity. Cost compression in almond-based SKUs is intensifying because of drought-cycle volatility and shipping rate instability, squeezing processors without captive sourcing arrangements.
Supply Chain Analysis
Single-source vulnerability sits with California for almond kernels and Australia for premium oat grain, exposing margin predictability to climate and logistics disruptions. Domestic soy sourcing draws from Madhya Pradesh and Maharashtra crushing facilities, while enzymatic processing enzymes currently feed from European specialty suppliers. Tariff exposure on imported inputs represents the dominant structural risk. Distribution runs through direct-to-home subscription platforms in Delhi-NCR and Bangalore, bypassing traditional retail infrastructure gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India dairy alternatives market compounds steadily as urban café partnerships normalize oat milk consumption among affluent millennials, creating predictable replenishment demand. FSSAI regulatory clarity on plant-based terminology will catalyze the next investment cycle as compliance thresholds filter subscale competitors.
For Market Incumbents: Extend cold-chain infrastructure density into Pune and Hyderabad satellite markets before subscription platforms lock household replenishment patterns. Deepen backward integration into domestic oat processing equipment through PLI scheme utilization to reduce Australian grain import dependency. The threat of venture-backed food-tech startups with clean-label enzymatic capabilities demands preemptive capacity positioning. For New Entrants and Emerging Players: Capture tier-two city households in Ahmedabad and Jaipur through direct-to-home delivery models that bypass supermarket placement fee structures. The most penetrable white space sits in protein-fortified variants for fitness enthusiasts, where oat protein concentrate integration remains technically immature. A go-to-market angle anchored in FSSAI pre-compliance with draft nomenclature standards builds regulatory credibility ahead of formal mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where enzymatic processing capability scarcity intersects with café channel lock-in mechanics. The market reads as a viable compounder over a multi-year horizon, with acquisition targets clustering around domestic enzyme technology holders and refrigerated logistics operators. The signal to watch is FSSAI's final ruling on "milk" terminology restrictions, which will trigger relabeling cost shocks and accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Domestic Oat Processing | PLI scheme subsidies reduce Australian grain import dependency and working capital intensity. |
| Enzymatic Processing Certification Investment | FSSAI clean-label expectations favor cellulase and amylase blends over chemical hydrolysis methods. |
| Direct-to-Home Subscription Platform Launch | Delhi-NCR and Bangalore household lock-in mechanics bypass supermarket placement fee compression. |
| Café Channel Partnership Standardization | Maharashtra and Karnataka coffee chain default positioning normalizes oat milk among millennials. |
| FSSAI Pre-Compliance Packaging Redesign | Early "oat beverage" and "almond drink" descriptor pivots mitigate relabeling cost exposure. |
Research Methodology
Multiple input streams — primary interviews with food-tech founders and plant managers, secondary validation through FSSAI regulatory filings and PLI scheme beneficiary disclosures, and customs data on almond kernel imports — were reconciled through bottom-up and top-down triangulation. Conversations with category buyers at modern trade retailers, supply chain heads at direct-to-home platforms, and enzymatic processing technology providers informed demand and capacity assumptions. Secondary sources included BIS certification records, organized retail audit data from Maharashtra and Karnataka, and cold-chain infrastructure mapping across tier-one and tier-two cities.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to build the analytical framework across the analysis window. Segmentation dimensions modeled included product type, application, distribution channel, and customer motivation archetype. CAGRs were derived through category growth rate reconciliation and input-cost elasticity modeling. Forecast inputs incorporated café partnership expansion rates, enzymatic processing capacity buildout timelines, and FSSAI regulatory implementation assumptions.
Regulatory implementation delays, raw material import cost spikes, and cold-chain infrastructure rollout shortfalls are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about PLI scheme continuation and urban café partnership sustainability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Buttermilk Market
Dairy Alternatives
Sesame Milk Market
Dairy Alternatives
Cheese Alternative Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
Dairy Alternatives Market
Dairy Alternatives
A2 Milk Powder Market
Dairy Alternatives
Almond Milk Market
Dairy Alternatives
Yogurt Alternative Market
Dairy Alternatives
Hazelnut Milk Market
Dairy Alternatives
Vegan Coffee Creamer Market
Dairy Alternatives
North America Non-Dairy Yogurt Market
Dairy Alternatives
Oat Drinks Market
Dairy Alternatives
North America Non-Dairy Cheese Market
Dairy Alternatives
Peanut Milk Market
Dairy Alternatives
Macadamia Milk Market