
 Global Staple Gun Market | 2026-2036
Global Staple Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Global Staple Gun Market Outlook
Modular kit configurations is recalibrating buyer choice in the staple gun space, as manufacturers bundle compatible fastener assortments with tool platforms to lock in consumables revenue. Stanley Black & Decker leverages its DeWalt battery ecosystem to anchor professional loyalty across cordless fastening lines. Bosch competes through integrated sensor-enabled depth control in its pneumatic range. Arrow Fastener specializes in light-duty manual models for the crafting segment, sustaining brand recognition among hobbyist buyers.
A staple gun is a handheld mechanical or powered fastening device that drives metal staples into wood, plastic, or composite substrates using spring-loaded, solenoid, or compressed-air actuation mechanisms with typical staple crown widths ranging from 4 to 14 millimeters. Its primary industrial purpose is to secure upholstery, sheathing, insulation, and trim materials in construction, furniture, and packaging workflows. Pneumatic staple guns dominate commercial job-site volume due to cycle speed and durability under continuous load. Electric battery-operated models represent the fastest-expanding power source category as lithium-ion energy density improves tool portability. Manual staple guns retain margin strength in the crafting and DIY end user segment where price sensitivity and intermittent use patterns limit power-tool investment.
The US Consumer Product Safety Commission enforces blade-guard and trigger-lock standards that shape electric staple gun design requirements for North American distribution. The EU Machinery Directive and CE marking obligations govern pneumatic tool safety ratings for European market access, while China's GB standards for power tool electromagnetic compatibility constrain import specifications. Stakeholders must monitor evolving cordless battery platform consolidation, as tool ecosystem exclusivity increasingly determines contractor procurement loyalty and aftermarket fastener attachment rates.
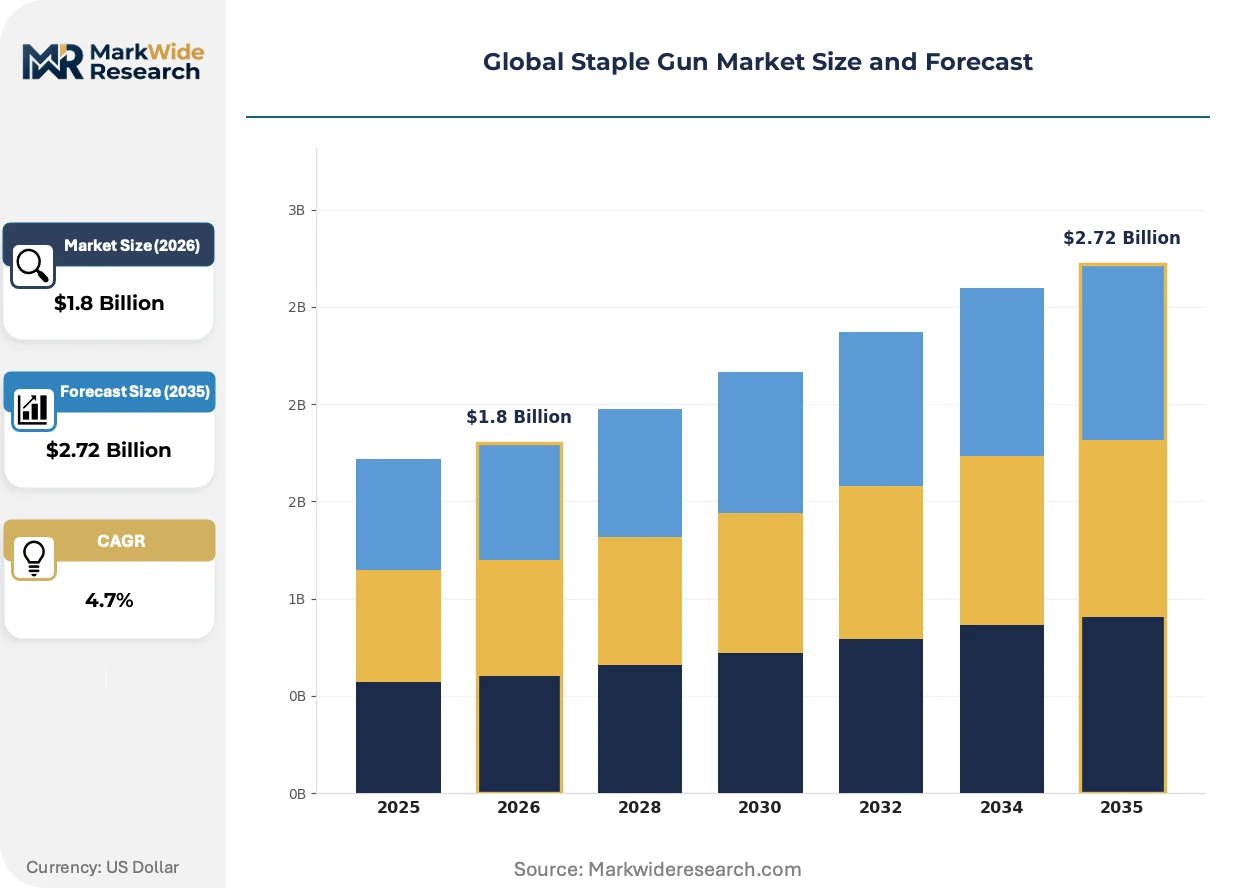
Market Dynamics
Battery platform consolidation is restructuring competitive loyalty in the staple gun market, as tool manufacturers leverage proprietary lithium-ion ecosystems to capture recurring fastener revenue and lock professional contractors into branded consumable streams.
Growth Catalysts
- Residential renovation intensity:Home improvement spending in the United States sustains contractor-grade tool procurement volumes, with professional users replacing manual and pneumatic units for cordless convenience.
- EU Machinery Directive safety upgrades:Enhanced CE marking requirements for pneumatic fastening tools are accelerating replacement cycles among European commercial operators seeking compliant equipment.
- Lithium-ion energy density gains:Improved battery chemistry extends runtime per charge, enabling cordless staple guns to penetrate applications previously reserved for compressed-air systems.
Market Restraints
- Steel staple input volatility:Fluctuations in cold-rolled steel prices compress margin predictability for consumable manufacturers dependent on commodity metal feedstocks.
- Pneumatic infrastructure lock-in:Established job-site air compressor networks create switching costs that slow cordless adoption among legacy commercial users.
- Manual tool price anchoring:Low-cost hand-operated models cap premium pricing power in the DIY segment where intermittent use patterns resist power-tool investment.
Strategic Opportunities
- India construction formalization:Building code enforcement expansion in Indian urban centers creates first-time demand for code-compliant fastening equipment among emerging contractor classes.
- Packaging automation retrofit:E-commerce fulfillment centers are integrating handheld electric staplers into semi-automated carton sealing workflows, opening industrial volume beyond traditional construction.
- US Inflation Reduction Act efficiency incentives:Energy-efficient building envelope mandates are increasing specification rates for insulation fastening tools in residential retrofit programs.
Industry Challenges
- Battery platform interoperability:Proprietary voltage and connector standards fragment contractor fleets, forcing multi-brand job sites to maintain redundant charging infrastructure.
- Pneumatic technician certification:Compressed-air system safety training requirements lengthen onboarding timelines for rental fleet operators expanding cordless-equipment service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Staple Gun Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Staple Guns, Electric Staple Guns, Pneumatic Staple Guns, Heavy-Duty Staplers End User: Construction, Furniture Manufacturing, Crafting, Packaging Industry Power Source: Battery Operated, Corded Electric, Pneumatic, Manual Distribution Channel: Online Retailers, Home Improvement Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Bostitch, Hitachi, Stanley Black & Decker, Bosch, Senco, Makita, Arrow Fastener, Steinell, Dewalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Staple Gun Market Strategic Shifts
Tool intelligence and connectivity are penetrating the staple gun category, transforming standalone fastening devices into data-generating assets that integrate with construction management software and predictive maintenance systems.
Brushless motor technology is unifying power delivery consistency across cordless staple gun platforms, eliminating the torque fade that plagued earlier battery-operated generations. Commercial roofing contractors in North America are adopting these units for membrane fastening at rates that outpace pneumatic alternatives. The technology is unifying performance benchmarks previously segmented by power source, compressing the historical performance gap between electric and compressed-air systems.
China's GB standards for power tool electromagnetic compatibility are tightening import specifications for cordless fastening equipment entering domestic distribution. Manufacturers must redesign control circuitry and shielding to satisfy radiated emission thresholds, adding engineering validation cycles to product launch timelines. Battery-operated models with integrated electronics face the most significant redesign burden, with compliance costs disproportionately affecting mid-tier import brands.
Rental channel expansion is capturing contractor segments that previously purchased tools outright, particularly among specialty trades with intermittent fastening needs. Equipment rental networks in Germany and France are building dedicated fastening tool fleets, displacing direct sales volume for pneumatic and cordless categories. This shift concentrates procurement influence with fleet managers rather than individual contractors, altering manufacturer sales force deployment and service bundling requirements.
Global Staple Gun Market Segmentation
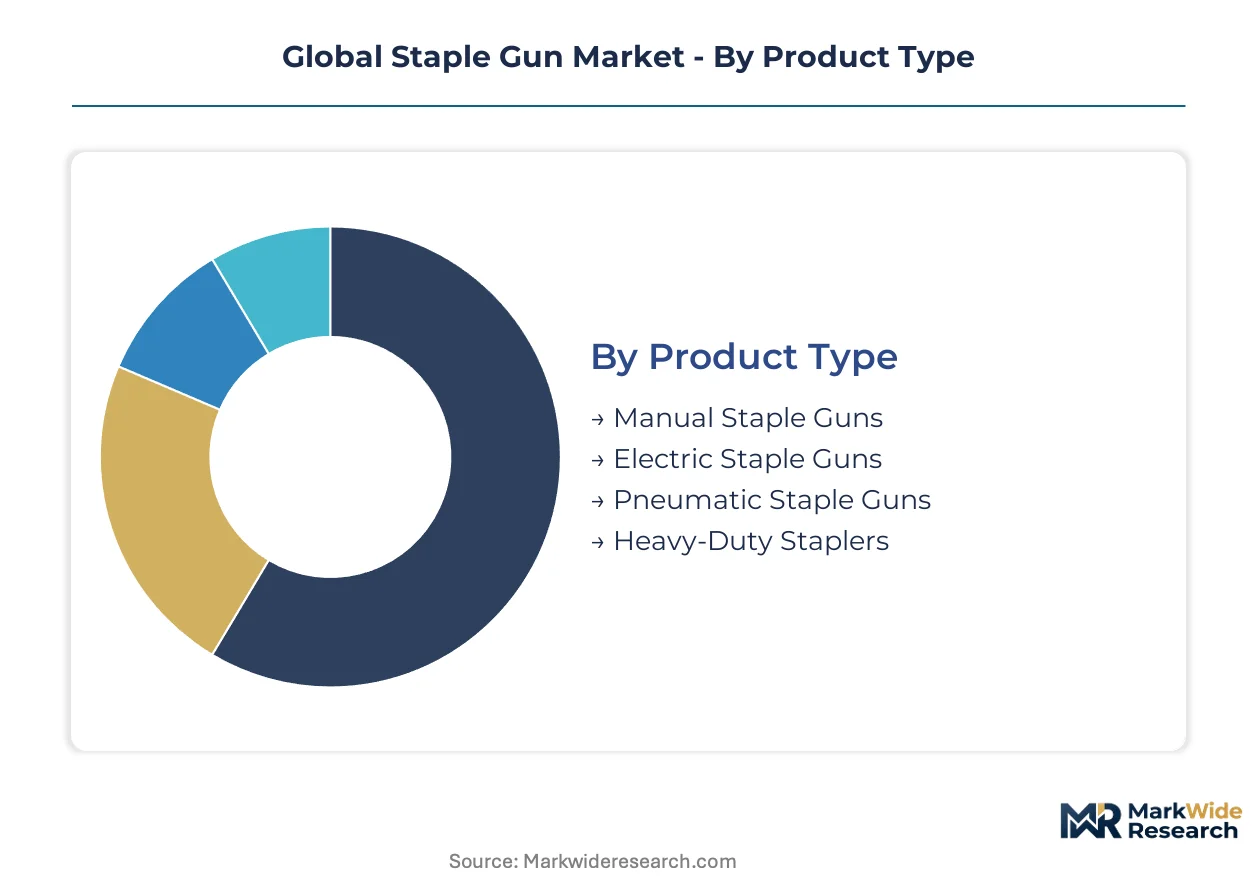
Segmentation in the staple gun market reveals distinct performance tiers across power sources and end-use applications. Professional contractors and industrial buyers prioritize cycle speed and durability, while hobbyist segments drive volume through price-sensitive manual tool purchases. Understanding these splits enables targeted product development and channel strategy.
Product Type:
Pneumatic units dominate commercial job-site volume through raw cycle speed, while cordless electric models command premium pricing in mobile applications.
- Manual Staple Guns:Spring-loaded mechanisms drive staples through mechanical force alone, with typical crown widths from 4 to 10 millimeters. Demand concentrates in North American crafting and light DIY segments where intermittent use patterns resist power-tool investment and price sensitivity anchors purchasing decisions.
- Electric Staple Guns:Solenoid or motor-driven actuation delivers consistent driving force for medium-duty applications including upholstery and trim work. Adoption is accelerating in European residential renovation markets where corded and battery-operated models displace manual tools among semi-professional users seeking productivity gains.
- Pneumatic Staple Guns:Compressed-air systems achieve the fastest cycle rates for continuous commercial use in sheathing and roofing applications.
- Heavy-Duty Staplers:Reinforced frames and high-capacity magazines penetrate dense substrates in industrial packaging and structural assembly.
Mature deployment sits with pneumatic systems in established construction workflows. Newer deployment is concentrated in battery-operated electric models gaining share in mobile job-site applications.
End User:
Application requirements span from precision fastening in delicate materials to high-speed repetitive driving in structural assembly.
- Construction:Commercial contractors specify tools for sheathing, roofing membrane, and insulation fastening where OSHA safety standards govern trigger-lock and blade-guard requirements. Demand clusters in United States residential retrofit programs and German commercial building envelope upgrades.
- Furniture Manufacturing:Upholstery and frame assembly operations require consistent staple depth control for fabric attachment and joint reinforcement. Adoption is expanding in Vietnamese and Polish export-oriented manufacturing hubs seeking faster assembly methods to meet contract delivery schedules.
- Crafting:Hobbyist and artisan users prioritize lightweight manual tools for paper, fabric, and light wood projects.
- Packaging Industry:Carton sealing and pallet stabilization workflows drive volume in e-commerce fulfillment operations.
Construction commands the highest per-unit pricing through professional-grade specifications. Crafting delivers the largest absolute unit volume through entry-level price points.
Power Source:
Energy delivery mechanisms determine portability, runtime, and infrastructure requirements across job-site conditions.
- Battery Operated:Lithium-ion platforms deliver cordless mobility with brushless motors eliminating torque fade during extended use. Penetration is climbing fastest in North American commercial roofing and European renovation contracting where compressor-free operation reduces setup time and transportation logistics.
- Corded Electric:Continuous AC power suits stationary workshop environments and high-volume production lines without battery swap interruptions.
- Pneumatic:Compressed-air systems maintain cost efficiency for fleet operators with existing compressor infrastructure.
- Manual:Zero energy dependency suits remote locations and budget-constrained intermittent users.
Established infrastructure locks in pneumatic systems among legacy commercial fleets. Battery chemistry improvements are displacing corded and compressed-air alternatives in mobile applications.
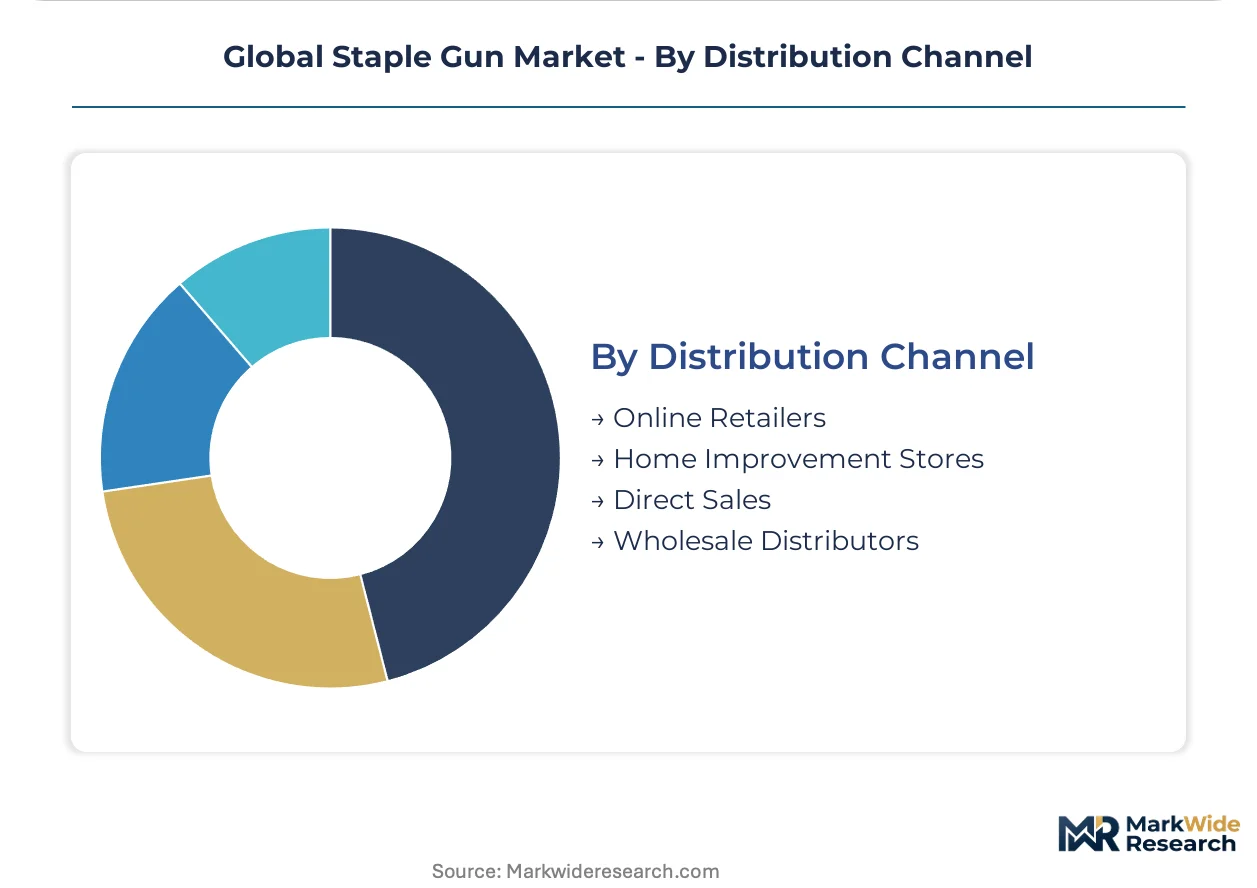
Distribution Channel:
Channel selection reflects buyer type, urgency, and service requirements across professional and consumer segments.
- Online Retailers:E-commerce platforms aggregate comparison shopping and deliver to job sites or home workshops with 24-48 hour fulfillment. Growth concentrates in United States and United Kingdom DIY segments where Amazon and specialized tool retailers capture share from traditional hardware channels.
- Home Improvement Stores:Physical retail enables hands-on evaluation and immediate pickup for project-driven purchases.
- Direct Sales:Manufacturer field representatives serve large contractor fleets and industrial accounts with customized service agreements.
- Wholesale Distributors:Industrial supply houses stock professional-grade pneumatic and cordless lines for trade-specific procurement.
Direct sales capture the highest-margin commercial accounts with bundled service contracts. Online retailers are gaining share fastest in replacement and upgrade purchases among informed buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in Vietnam and bonded logistics parks in Shanghai concentrate staple gun assembly capacity for re-export to North American and European markets. Mexico's IMMEX program draws pneumatic tool manufacturing to Baja California and Nuevo León to serve US contractor demand with tariff-advantaged supply chains.
United States
Residential renovation spending and professional contractor procurement sustain volume leadership across cordless and pneumatic categories. OSHA blade-guard and trigger-lock standards shape electric staple gun design requirements for domestic distribution. Dallas-Fort Worth and Atlanta metropolitan areas anchor regional distribution hubs serving Sun Belt construction growth.
Germany
Commercial building envelope upgrades and rental fleet expansion drive pneumatic and cordless tool replacement cycles. EU Machinery Directive CE marking obligations govern pneumatic tool safety ratings for European market access. Stuttgart and Munich industrial corridors concentrate professional-grade tool manufacturing and aftermarket service networks.
China
Export-oriented manufacturing hubs supply global demand for manual and electric staple gun platforms at scale. GB standards for power tool electromagnetic compatibility constrain import specifications for cordless equipment entering domestic distribution. Yangtze River Delta clusters around Shanghai and Suzhou integrate component sourcing with finished goods assembly for international brands.
India
Building code enforcement expansion in urban centers creates first-time demand for code-compliant fastening equipment among emerging contractor classes. BIS certification requirements and DGFT import regulations shape product specifications for domestic market entry. Maharashtra and Gujarat manufacturing zones develop assembly capacity for Southeast Asian re-export markets.
Vietnam
Furniture manufacturing export growth drives upholstery tool demand among assembly operations serving North American and European retail contracts. Special economic zone tax incentives concentrate light manufacturing in Binh Duong and Dong Nai provinces. Ho Chi Minh City logistics corridors facilitate bonded warehousing for regional distribution.
Global Staple Gun Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the staple gun market, creating a tiered structure where scale-driven portfolios face off against craftsmanship-positioned niche operators. The vendor base spans battery-platform ecosystems, pneumatic system specialists, and manual tool heritage brands. Three archetypes dominate: diversified power-tool conglomerates leveraging battery interoperability, pneumatic-focused industrial equipment manufacturers, and craft-specialist manual tool brands. Competitive moves center on battery platform consolidation to capture consumables revenue and geographic expansion into Southeast Asian manufacturing hubs.
Within the diversified conglomerate tier, Stanley Black & Decker and Bosch exemplify scale-driven positioning across cordless and pneumatic product lines. Arrow Fastener occupies a specialist position anchored in light-duty manual models for hobbyist segments. Senco and Bostitch represent pneumatic-focused industrial equipment manufacturers serving commercial job-site applications.
| Leading Market Players |
|---|
| Bostitch |
| Hitachi |
| Stanley Black & Decker |
| Bosch |
| Senco |
| Makita |
| Arrow Fastener |
| Steinell |
| Dewalt |
| Others |
Value Chain & Pricing Dynamics
Cold-rolled steel feedstock volatility cascades through staple gun manufacturing tiers, compressing margin buffers for consumable producers while forcing tool makers to recalibrate battery-platform bundling strategies to lock in recurring revenue streams.
Pricing Analysis
Margin tightening in the manual tool tier reflects commodity metal input swings and low-cost Asian import saturation. Three-tier pricing structure across professional cordless, commercial pneumatic, and entry-level manual levels stratifies by runtime specification and fastener compatibility depth. Brand premium and battery ecosystem lock-in represent the primary differentiation vectors. Cost-down pressure on pneumatic lines accelerates because rental fleet operators consolidate procurement around fewer vendor relationships. DIY hobbyists exhibit highest price sensitivity, while commercial contractors prioritize total cost of ownership over unit acquisition.
Supply Chain Analysis
CE marking and OSHA compliance certification gates concentrate finished goods assembly in China, Vietnam, and Mexico for tariff-advantaged access to North American and European demand centers. Lithium-ion cells, cold-rolled steel strip, and precision-machined aluminum castings constitute critical upstream dependencies. Single-source vulnerability sits with cylindrical cell supply from East Asian chemical conglomerates. Distribution runs through home improvement retail chains, industrial wholesale houses, and direct manufacturer field forces serving large contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery platform consolidation is forcing sub-scale pneumatic specialists and undifferentiated manual tool brands toward exit or acquisition, compressing viable competitive positions to ecosystem-anchored portfolios or craft-niche craftsmanship positioning.
For Market Incumbents: Deploy proprietary battery ecosystem expansion to capture fastener attachment revenue and neutralize emerging cordless challengers. Deepen backward integration into lithium-cell supply through offtake agreements with Korean and Chinese chemical producers. Reinforce channel control via exclusive distributor arrangements in German and US rental fleet networks to block second-tier brand shelf access. For New Entrants and Emerging Players: Specialty roofing contractors in secondary US metropolitan areas represent an underserved buyer archetype with intermittent fastening needs and low existing brand loyalty. Target Indian urban contractor classes facing first-time code compliance requirements as building enforcement expands. Pursue white-label manufacturing partnerships with Vietnamese furniture export assemblers seeking bundled tool-fastener procurement. For Investors and Strategic Acquirers: Distressed-cycle entries favor pneumatic-focused industrial equipment manufacturers with established compressor infrastructure relationships in European commercial building markets. Mid-cap specialists with regional manufacturing footprints and CE-marking capabilities offer viable 5-10 year consolidation platforms. Monitor lithium carbonate price normalization as inflection signal for cordless platform investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Proprietary voltage systems from Stanley Black & Decker and Bosch lock professional contractors into recurring fastener revenue streams. |
| Backward Integration into Cell Supply | Captive lithium sourcing from Korean chemical producers reduces input volatility exposure for cordless tool manufacturers. |
| Rental Channel Fleet Partnerships | Equipment rental networks in Germany and France concentrate procurement influence with fleet managers over individual contractors. |
| Southeast Asian Manufacturing Relocation | Vietnam's special economic zones and Mexico's IMMEX program offer tariff-advantaged assembly for North American market access. |
| Sensor-Enabled Depth Control Integration | Bosch's pneumatic range demonstrates how electronic feedback systems differentiate professional-grade specifications in saturated markets. |
Study Parameters
Document review covered customs trade databases, SEC 10-K filings from diversified tool manufacturers, and EU Machinery Directive technical documentation, complemented by interviews with procurement directors at US residential construction firms, fleet managers at German equipment rental networks, and aftermarket service heads at Southeast Asian manufacturing subcontractors. Secondary validation drew from OSHA enforcement records, CE marking registries, and BIS certification filings for Indian market entry. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to anchor volume projections.
Historical shipment data cross-referenced against panel input from distributor inventory managers and OEM procurement teams shaped the analytical framework across the analysis window. Segmentation dimensions modeled include power source architecture, end-use application intensity, professional versus consumer buyer type, and regional regulatory compliance tier. CAGRs emerged from iterative convergence of demand elasticity parameters and replacement cycle assumptions. Brushless motor penetration curves and battery energy density improvement trajectories supplied industry-specific forecast inputs.
Revisions become necessary when lithium raw material supply disruptions, regulatory standard updates, or construction spending contraction materialize outside modeled parameters. Forecasts reflect documented assumptions about technology substitution rates and channel structure stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Friction Washer Market
Tools
End Mill Holder Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Mechanical Springs Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Powder Compacting Pressers Market
Tools
Squeegee Market
Tools
Asia Pacific Power Tools Market
Tools
Digital Cutting Machine Market
Tools
Digital Levels Market
Tools
Portable Tools Market
Tools
Gouging Torch Market
Tools
Core Shooter Machine Market
Tools
Woodworking Tools Market
Tools
Tension Tester Market
Tools
Impact Wrenches Market