
 Pre-Owned Construction Equipment Market | 2026-2036
Pre-Owned Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Owned Construction Equipment Market Analysis
Multi-source procurement from auction houses and dealer networks is recalibrating how contractors acquire fleet assets. Caterpillar, Inc. leverages its certified used program and global dealer footprint to sustain pricing power across regional markets. Ritchie Bros. Auctioneers Incorporated anchors the secondary market through its unreserved auction model and digital bidding platform. Komatsu Used Equipment Corp. differentiates via factory-backed inspections and warranty coverage that competes with new-equipment financing terms.
Pre-owned construction equipment encompasses previously operated machinery that has undergone operational service, typically retaining structural integrity and functional specifications such as hydraulic system pressure ratings, engine hour accumulations, and undercarriage wear metrics for tracked units. Its primary commercial purpose is to transfer productive capital assets downstream at depreciated cost points, enabling fleet expansion without new-equipment capital outlay. Excavators lead product type demand due to versatility across earthmoving and utility applications, while online marketplaces represent the fastest-expanding sales channel as digital inspection tools reduce buyer uncertainty. Auctions remain a mature, high-volume liquidation pathway where price discovery concentrates for aged or surplus fleet.
The EPA enforces emissions compliance that limits resale viability of pre-Tier 4 diesel machines in the United States, while India's CEA and state pollution control boards are tightening equipment registration norms for imported used assets. ISO 9001 quality management standards and equipment-specific inspection protocols shape cross-border trade eligibility and buyer confidence in secondary transactions. Stakeholders must monitor regulatory divergence between source and destination markets to anticipate which equipment vintages will face restricted mobility or accelerated depreciation.
Market Dynamics
EPA Tier 4 Final emissions standards are compressing the resale window for pre-Tier 4 diesel machines, forcing rental fleets and contractors to accelerate equipment turnover cycles while redirecting older assets toward export markets with less stringent requirements.
Growth Catalysts
- India's PLI scheme incentives:Domestic manufacturing subsidies are drawing cross-border equipment flows into Indian infrastructure projects, creating absorption capacity for Tier 3 and older machines displaced from US fleets.
- Rental fleet expansion:Equipment rental companies are prioritizing certified used programs to contain capital outlay while maintaining utilization rates across earthmoving and utility applications.
- Telematics integration:Remote monitoring systems are reducing buyer uncertainty in secondary transactions by providing verified engine hour data and maintenance histories.
Market Restraints
- Steel price volatility:Input cost swings for undercarriage components and hydraulic cylinders compress margin buffers for refurbishment operations.
- Supply concentration in auction channels:Unreserved auction models concentrate price discovery power among a handful of North American liquidation platforms.
- Technical limitation of battery retrofits:Electrification conversion kits remain economically unviable for mid-life excavators and dozers due to power density constraints.
Strategic Opportunities
- Southeast Asian infrastructure buildout:Vietnam and Indonesia are absorbing aged crawler cranes and motor graders that face registration restrictions in India.
- Outcome-based maintenance contracts:Factory-backed service agreements tied to uptime metrics are displacing traditional warranty coverage in secondary sales.
- Digital inspection platforms:AI-powered wear-assessment tools are compressing due diligence timelines for cross-border equipment procurement.
Industry Challenges
- Certified equipment appraiser shortage:ISO 9001 inspection protocols require specialized technicians whose training pipelines lag market expansion.
- Cross-border customs complexity:Divergent CEA registration norms and state pollution control board requirements fragment import eligibility across Indian states.
- Legacy hydraulic system interoperability:Attachment coupling standards vary by OEM vintage, complicating fleet standardization for multi-brand operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Owned Construction Equipment Market |
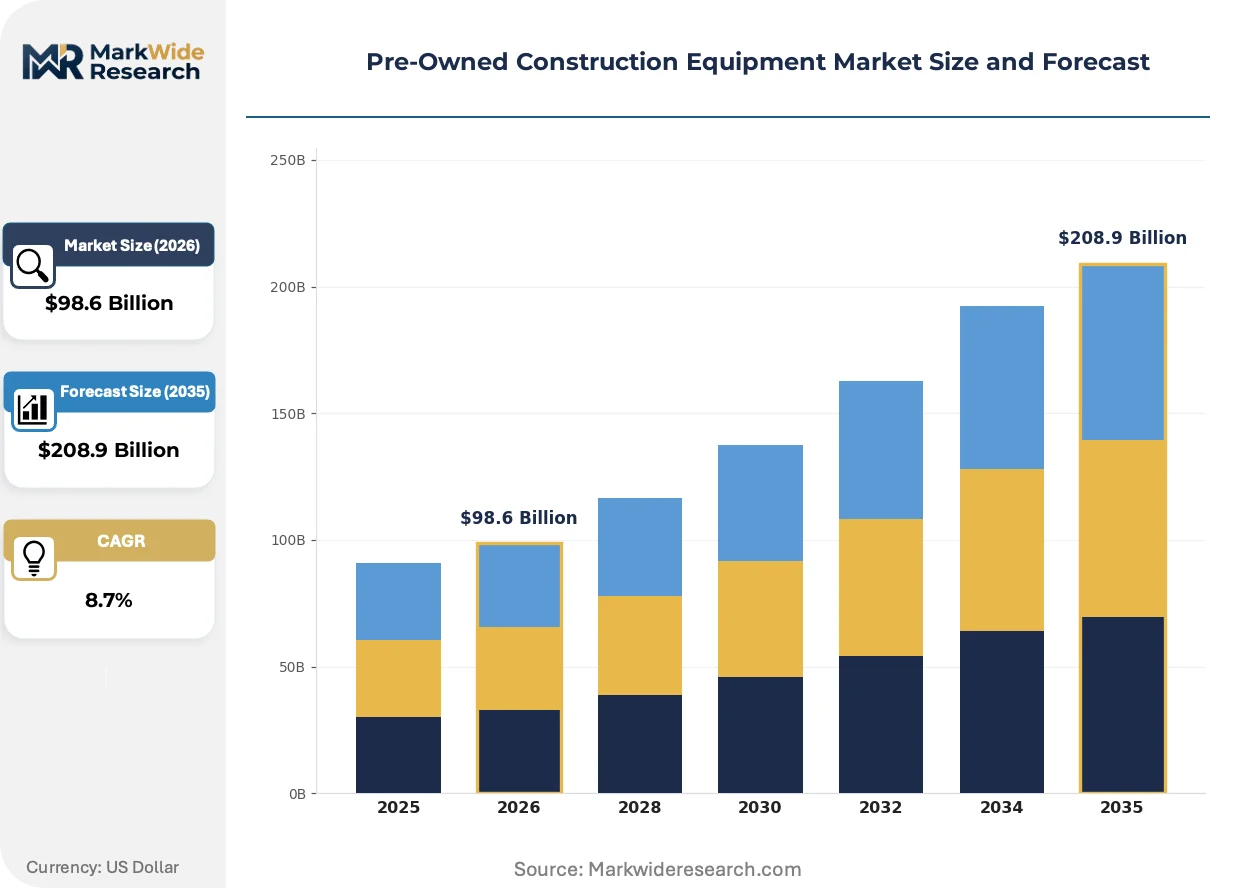
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Cranes, Loaders End User: Contractors, Rental Companies, Government Agencies, Farmers Sales Channel: Direct Sales, Online Marketplaces, Auctions, Dealers Capacity: Lightweight, Medium, Heavyweight, Ultra-Heavy |
| Companies Covered | Hitachi Construction Machinery, Kobelco Construction Machinery Co., Ltd., Caterpillar, Inc., Ritchie Bros. Auctioneers Incorporated, Equippo AG, Komatsu Used Equipment Corp., Terex Corporation, Sandhills Global, Volvo CE Used Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Owned Construction Equipment Market Emerging Trajectories
Digital verification tools and emissions-driven asset migration are restructuring how secondary equipment circulates between markets, compressing traditional dealer intermediation while elevating transparency as a competitive differentiator.
Telematics-enabled condition monitoring is rewriting trust formation in remote transactions. Fleet management platforms now aggregate engine diagnostics, hydraulic pressure logs, and undercarriage wear metrics into portable asset passports. Contractors in Texas and Alberta are adopting these verified data streams to bid on auction-listed machines without physical inspection, collapsing geographic arbitrage in pricing.
REACH substance restrictions and EU Green Deal carbon border adjustments are tightening import eligibility for older diesel construction equipment across European ports. Refurbishment workshops in Poland and Romania are responding by specializing in Tier 4 retrofit packages that extend machine residency within the single market, creating a two-tier secondary circulation system.
Consolidated procurement through online marketplaces is fragmenting traditional dealer relationships. Mid-sized earthmoving contractors in São Paulo and Johannesburg are bypassing regional distributors to source directly from US auction aggregators, compressing margin capture by local intermediaries while extending payment cycles through platform-integrated financing.
Pre-Owned Construction Equipment Market Segmentation
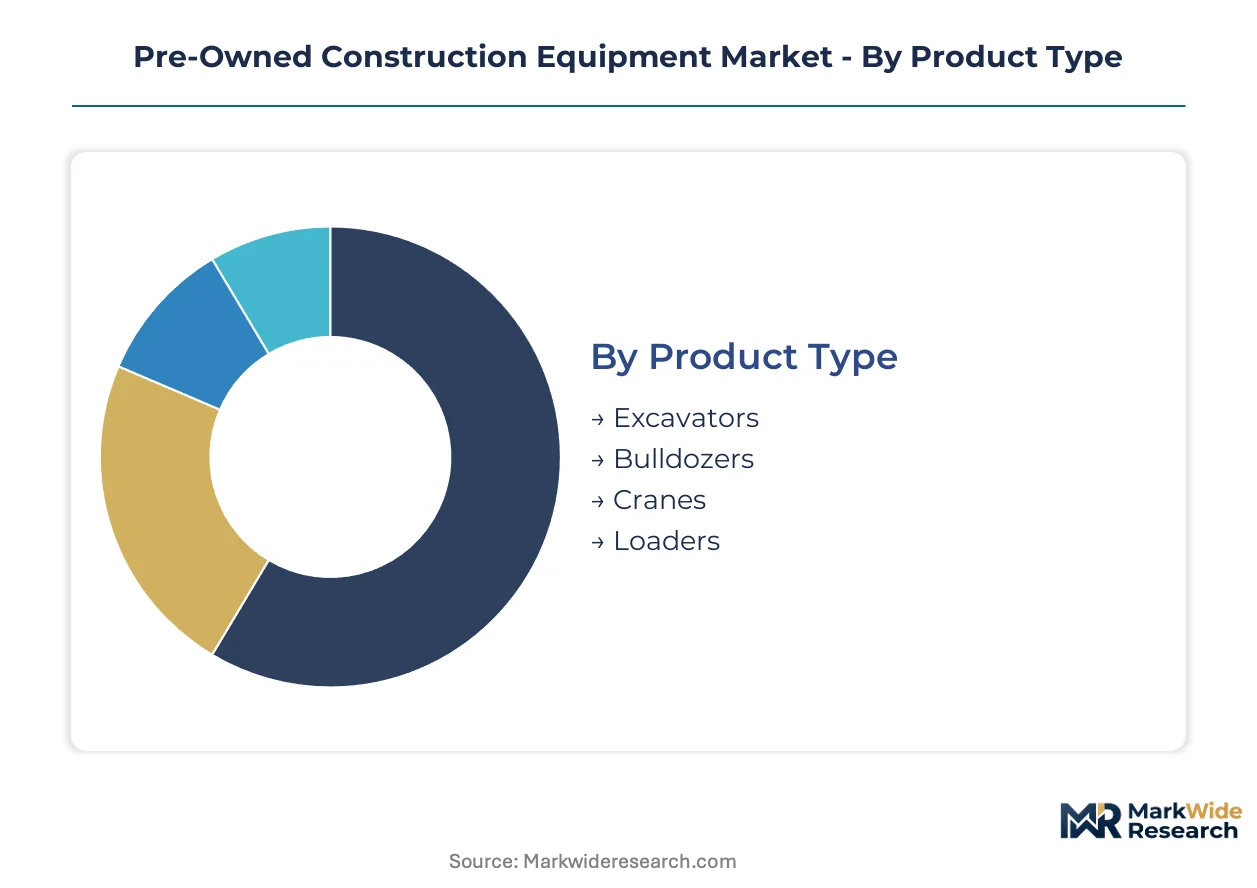
Segmentation in the pre-owned construction equipment market determines liquidity depth and pricing transparency. Equipment type and sales channel configurations shape how depreciation curves intersect with buyer risk tolerance across regional markets.
Product Type:
Supply concentrates in tracked earthmoving equipment where inspection standardization supports cross-border trade.
- Excavators:Hydraulic systems with boom-arm configurations ranging from mini to mining-class specifications dominate secondary transaction volumes. Demand concentrates with utility contractors in Texas and Alberta who source mid-life units from auction aggregators to expand fleet capacity without new-equipment capital outlay.
- Bulldozers:Tracked dozers with undercarriage wear metrics and blade control systems retain resale value through multiple ownership cycles. Crawler units face accelerated turnover in the United States as EPA Tier 4 Final compliance compresses the resale window for pre-Tier 4 diesel machines.
- Cranes:Mobile and crawler crane categories with boom length certifications and load chart verifications.
- Loaders:Wheel and track loader variants with bucket capacity ratings and hydraulic attachment compatibility.
Today's leader: Excavators. Tomorrow's challenger: Bulldozers.
End User:
Customer type determines financing structure and warranty expectations in secondary transactions.
- Contractors:Earthmoving and utility contractors with project-based equipment needs drive demand for certified used programs with verified maintenance histories.
- Rental Companies:Fleet operators prioritizing utilization rates over ownership duration source refurbished units through dealer networks and factory-backed inspection protocols.
- Government Agencies:Public procurement entities with bid-specification requirements and extended depreciation schedules.
- Farmers:Agricultural operators seeking depreciated capital assets for seasonal earthmoving and land preparation applications.
Rental companies command volume leverage. Contractors represent the steepest expansion trajectory.
Sales Channel:
Channel selection shapes price discovery mechanisms and buyer due diligence requirements.
- Direct Sales:Manufacturer-certified used programs with factory inspections and extended warranty coverage compete with new-equipment financing terms.
- Online Marketplaces:Digital platforms with telematics-verified asset passports and AI-powered wear assessment tools are climbing the fastest as remote bidding reduces geographic arbitrage in pricing.
- Auctions:Unreserved auction models with unreserved bidding concentrate liquidation volume for aged or surplus fleet assets.
- Dealers:Regional distributor networks with parts availability and service capacity support localized buyer relationships.
Dealers retain trust advantage. Online marketplaces scale fastest.
Capacity:
Weight class determines transport economics and application versatility in secondary markets.
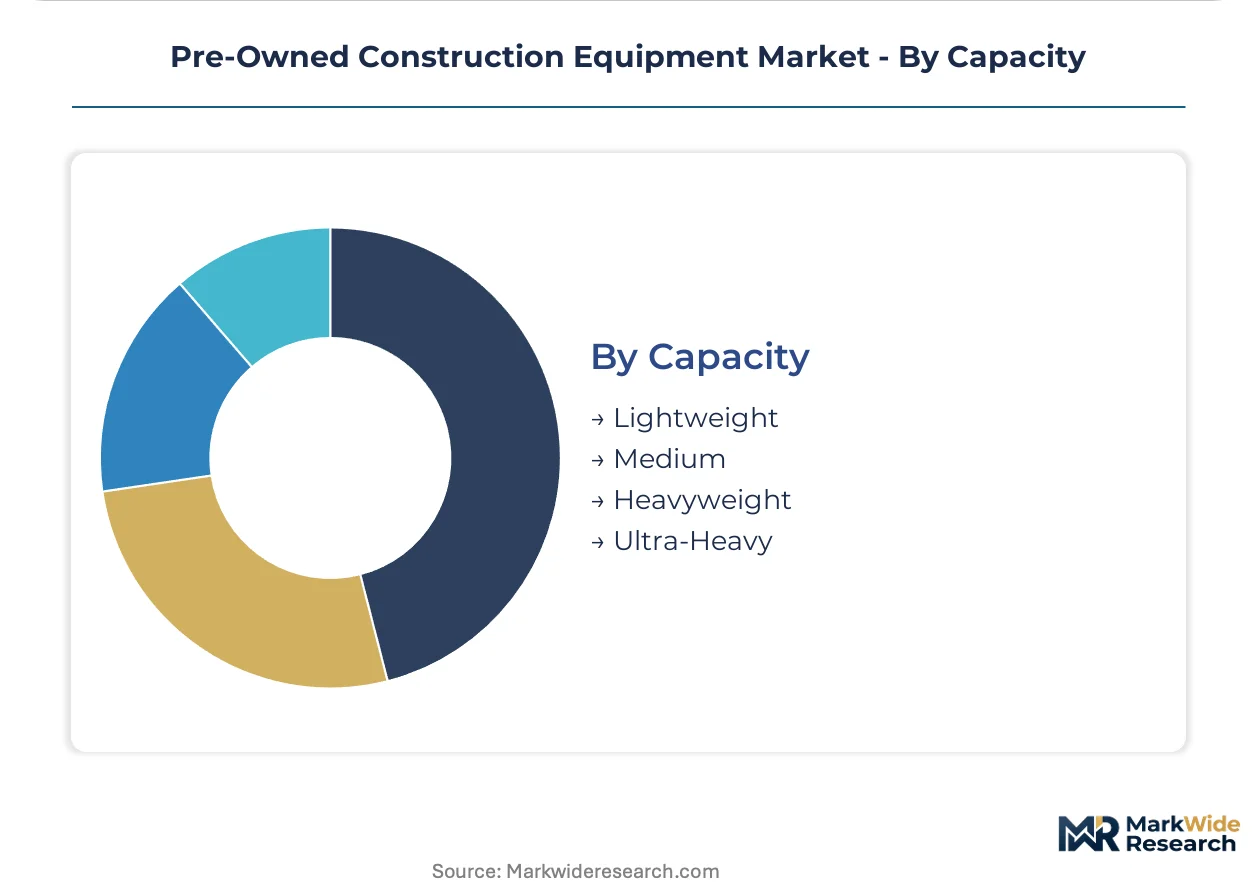
- Lightweight:Compact excavators and skid-steer loaders under 6 metric tons with trailer-transportable dimensions.
- Medium:Standard excavators and wheel loaders in the 6-20 metric ton range serving general construction applications.
- Heavyweight:Large excavators and dozers above 20 metric tons requiring specialized transport and site preparation.
- Ultra-Heavy:Mining-class equipment with componentized transport requirements and limited buyer pool concentration.
Medium capacity dominates transaction flow. Heavyweight units capture margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting pre-Tier 4 diesel equipment from EPA-compliant markets toward jurisdictions with less stringent emissions enforcement. This cost-of-compliance gap is compressing asset depreciation curves in origin markets while extending operational lifespans in destination economies.
United States
EPA Tier 4 Final standards are accelerating fleet turnover among rental operators and earthmoving contractors. Contractors in Texas and Alberta are liquidating mid-life excavators through unreserved auction channels. Dallas-Fort Worth anchors the secondary distribution network where telematics-verified assets flow toward export aggregators.
Germany
REACH substance restrictions and EU Green Deal carbon border adjustments are tightening import eligibility for older diesel machines. Refurbishment workshops in Poland and Romania are specializing in Tier 4 retrofit packages. Hamburg serves as the primary logistics hub for equipment redirection toward Southeast Asian markets.
India
CEA registration norms and state pollution control board requirements are fragmenting import eligibility across Indian states. PLI scheme incentives for domestic manufacturing are drawing cross-border equipment flows into infrastructure projects. Maharashtra and Gujarat concentrate absorption capacity for Tier 3 and older machines displaced from US fleets.
China
Dual carbon goals under MEE oversight are constraining operational permits for legacy diesel equipment in coastal provinces. Domestic contractors are sourcing certified used assets through factory-backed programs to avoid new-equipment capital outlay. Yangtze River Delta manufacturing clusters are repurposing refurbishment capacity for regional redistribution.
Indonesia
Infrastructure buildout across Java and Sumatra is absorbing aged crawler cranes and motor graders that face registration restrictions in India. State-owned contractors are prioritizing depreciated capital assets for project-based fleet expansion. Jakarta anchors the procurement network where digital marketplaces are compressing traditional dealer intermediation.
Pre-Owned Construction Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital marketplace aggregation and telematics-enabled verification services. The vendor base stratifies across three maturity tiers: OEM-certified used programs with factory inspection protocols, auction platforms with unreserved bidding models, and online marketplaces with AI-powered condition assessment. Strategic archetypes include capital-light aggregators, vertically integrated refurbishment operators, and technology-enabled inspection specialists. M&A activity concentrates on digital platform acquisitions and regional auction house consolidation.
Within the OEM-certified tier, Caterpillar, Inc. and Komatsu Used Equipment Corp. exemplify factory-backed warranty coverage that competes with new-equipment financing terms. Among auction-platform operators, Ritchie Bros. Auctioneers Incorporated anchors the secondary market through unreserved auction models and digital bidding infrastructure. These three companies represent distinct competitive vectors: manufacturer-controlled distribution, liquidation platform scale, and hybrid digital-physical service integration.
| Leading Market Players |
|---|
| Hitachi Construction Machinery |
| Kobelco Construction Machinery Co., Ltd. |
| Caterpillar, Inc. |
| Ritchie Bros. Auctioneers Incorporated |
| Equippo AG |
| Komatsu Used Equipment Corp. |
| Terex Corporation |
| Sandhills Global |
| Volvo CE Used Equipment |
| Others |
Supply Flow & Price Mechanics
Certified-versus-uncertified equipment bifurcation creates parallel pricing tracks that reshape procurement patterns across dealer networks and auction channels. Factory-backed inspection protocols command premium positioning through warranty coverage and telematics verification, while unreserved liquidation streams absorb aged assets at compressed valuations. This tier divergence concentrates margin capture among OEM-certified programs in the United States and Germany, while redirecting depreciated Tier 3 machines toward export aggregators serving Indian and Indonesian infrastructure markets.
Pricing Analysis
Distributor margin compression runs through regional dealer networks as online marketplaces disintermediate traditional intermediaries. Three-tier pricing structure across OEM-certified, dealer-refurbished, and auction-liquidated equipment reflects inspection depth and warranty duration. Cost compression in standard-tier refurbishment is intensifying because steel price volatility for undercarriage components erodes margin buffers. Rental companies exhibit lowest price sensitivity due to utilization-rate prioritization, while agricultural operators and small contractors drive volume in economy-tier auction acquisitions.
Supply Chain Analysis
Single-source vulnerability sits with North American auction platforms that concentrate price discovery power for aged fleet liquidation. Equipment sourcing draws from the United States, Germany, and Japan as primary origin markets for high-hour assets entering secondary circulation. Steel inputs, hydraulic cylinder components, and engine remanufacturing kits constitute critical refurbishment dependencies. Tariff exposure on cross-border equipment transfers fragments import eligibility, particularly where India's CEA registration norms diverge across state pollution control boards. Distribution runs through Dallas-Fort Worth and Hamburg logistics hubs before final-mile deployment to regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Tier 4 Final emissions standards accelerate equipment turnover cycles and redirect asset flows toward absorption markets with less stringent enforcement.
For Market Incumbents: Acquire telematics-enabled inspection platforms to defend against digital marketplace disintermediation. OEM-certified programs should deepen factory-backed warranty coverage to differentiate from auction-liquidated alternatives. Capacity addition in Polish and Romanian refurbishment workshops captures Tier 4 retrofit demand before EU Green Deal carbon border adjustments tighten further. For New Entrants and Emerging Players: Capture outcome-based maintenance contract white space where uptime-guarantee pricing displaces traditional warranty coverage. Southeast Asian infrastructure buildout in Vietnam and Indonesia represents the most penetrable geography for aged crawler crane and motor grader placement. Direct-to-contractor digital platforms with AI-powered wear assessment compress due diligence timelines and bypass established dealer relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated refurbishment operators combining auction sourcing with factory-authorized service capacity. Long-term viability hinges on regulatory arbitrage duration between EPA-compliant origin markets and destination economies with extended operational lifespan allowances. Watch CEA registration norm harmonization across Indian states as the critical inflection signal for cross-border equipment mobility.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Remote monitoring systems from Sandhills Global and Ritchie Bros. compress buyer uncertainty in secondary transactions. |
| Factory-Backed Certification Expansion | Caterpillar and Komatsu warranty programs compete directly with new-equipment financing terms for rental fleet procurement. |
| Tier 4 Retrofit Specialization | Polish and Romanian workshops extend machine residency within EU single markets ahead of carbon border adjustments. |
| Digital Marketplace Aggregation | Online platforms with AI-powered inspection reduce geographic arbitrage for contractors in São Paulo and Johannesburg. |
| Cross-Border Logistics Hub Development | Dallas-Fort Worth and Hamburg anchoring redistributes pre-Tier 4 assets toward Indian and Southeast Asian absorption markets. |
Methodological Framework
Multiple input streams — equipment auction transaction records, OEM-certified used program disclosures, and customs trade documentation — were reconciled against primary interviews with fleet managers at rental companies, procurement leads at earthmoving contractors, aftermarket service directors at dealer networks, and regulatory affairs specialists at import aggregators. Secondary validation incorporated EPA enforcement bulletins, CEA registration databases, EU Green Deal implementation guidance, and ISO 9001 inspection protocol standards. Bottom-up equipment flow modeling and top-down market sizing triangulated volume estimates across the analysis window.
Historical auction clearance rates and panel-based contractor sentiment inputs were cross-referenced to construct demand projections. Segmentation dimensions modeled include equipment type, sales channel configuration, capacity weight class, and end-user financing structure. CAGRs were derived from regression analysis against infrastructure spending indices and emissions regulatory phase-in schedules. Steel price volatility indices and telematics adoption curves served as industry-specific forecast modifiers throughout the projection horizon.
Steel price volatility, regulatory divergence between EPA and CEA jurisdictions, and battery retrofit technology breakthroughs are the dominant revision risks to modeled equipment flow assumptions. Forecasts reflect documented assumptions about emissions enforcement continuity and infrastructure spending commitment durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Bale Openers Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Backhoes Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Shield Machines Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Australia Mobile Cranes Rental Market