
 Handheld Engraving Machine Market | 2026-2036
Handheld Engraving Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Engraving Machine Market Insights
Modular accessory ecosystems around core engraving units is realigning how buyers configure their purchases. Gravotech leverages its European manufacturing base to sustain premium positioning in industrial marking systems. Shenzhen LaserPecker Technology Co., Ltd. competes aggressively on portability and smartphone integration for consumer artisans. Shenzhen Ortur Technology Co., Ltd. anchors its growth in open-source firmware communities that drive user-driven feature expansion.
A handheld engraving machine is a portable device that uses rotary cutters, diamond styluses, or focused laser beams to incise permanent marks onto metal, wood, glass, or polymer surfaces, typically operating at speeds between 5,000 and 35,000 RPM for rotary units or 1 to 10 watts for diode laser variants. Its primary purpose is to apply traceable identifiers, decorative patterns, or functional textures directly at the point of use without requiring fixed industrial infrastructure. Laser engraver units command the highest margin pools due to consumable-free operation and software upgrade paths, while battery-operated segments are gaining fastest among mobile maintenance teams. Rotary technology remains the volume leader in automotive component marking where deep metal penetration matters, though diamond tip systems face margin compression from tungsten carbide alternatives.
The EU Machinery Directive and CE marking framework shape product access by mandating emergency stop functionality and laser safety interlocks for European importation. The US FDA regulates laser-emitting engravers under 21 CFR 1040 for radiation safety, while China's SAMR enforces GB standards for electromagnetic compatibility in domestic sales. Stakeholders must monitor evolving laser classification thresholds and battery transport regulations that could force hardware redesigns or restrict cross-border fulfillment channels.
Market Dynamics
Jewelry designers and small-batch manufacturers are pulling portable laser and rotary units into workflows previously reserved for fixed industrial infrastructure, compressing the addressable market downward while fragmenting purchasing authority.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for emergency stop functionality and laser safety interlocks are forcing OEMs toward certified safety architectures, filtering out uncertified competitors and elevating average selling prices for compliant units.
- Shenzhen hardware cluster export capacity:Concentrated manufacturing in China's Pearl River Delta supplies cost-optimized engravers to North American and European export markets, accelerating unit economics for entry-level buyers.
- Diode laser technology maturation:Power efficiency gains in 1-10 watt laser variants eliminate consumable costs associated with rotary cutters and diamond styluses, shifting margin pools toward software-upgradeable platforms.
Market Restraints
- Tungsten carbide tip substitution:Diamond stylus systems face sustained margin compression as lower-cost carbide alternatives achieve acceptable wear rates for decorative marking applications.
- Battery transport regulatory friction:Lithium-ion cell restrictions under IATA and UN 38.3 testing requirements complicate cross-border fulfillment for cordless engraving units.
- Rotary speed ceiling limitations:Mechanical spindle designs topping at 35,000 RPM cannot match laser throughput for polymer and coated metal applications, constraining technology mix in high-volume settings.
Strategic Opportunities
- Mobile maintenance team penetration:Battery-operated segments are gaining fastest among field service technicians requiring on-site part identification without mains power access.
- Open-source firmware ecosystems:User-driven feature expansion through community-developed control software lowers R&D burden for emerging OEMs and accelerates functional differentiation.
- Smartphone integration convergence:Bluetooth-connected engraving apps are displacing dedicated control hardware for consumer artisan segments, collapsing price floors and expanding first-time buyer pools.
Industry Challenges
- Laser safety officer certification timelines:Class 3B and Class 4 laser deployment requires trained personnel under OSHA and EU workplace directives, slowing enterprise adoption cycles.
- Legacy ERP integration complexity:Shop-floor engraving units must interface with existing MES and traceability systems, extending implementation timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Engraving Machine Market |
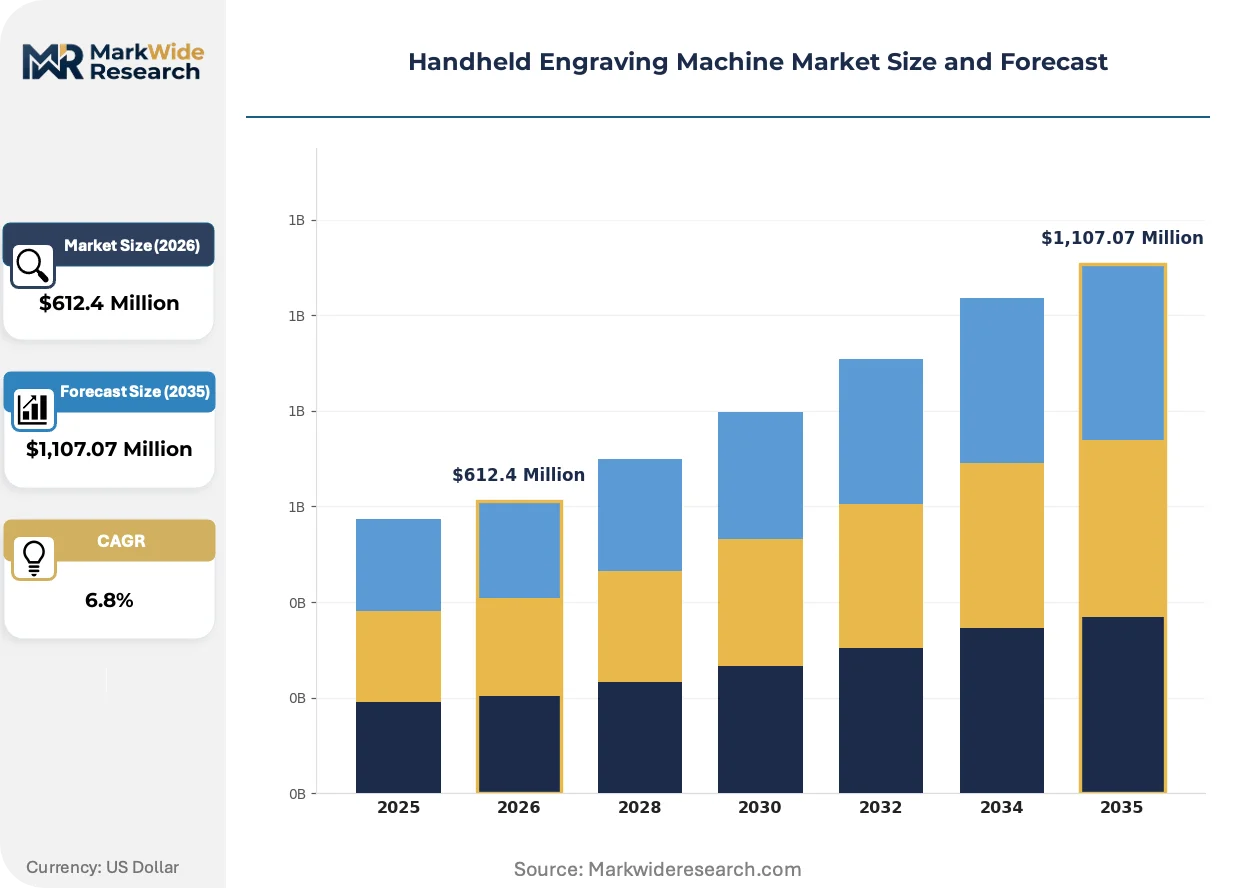
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Pneumatic, Battery Operated, Corded, Laser Engraver Technology: Rotary, Diamond Tip, Laser, Micro-Abrasion, Ultrasonic Application: Jewelry Design, Automotive Components, Aerospace Marking, Woodcraft, Electronic Devices End User: Artisans, Manufacturers, Maintenance Teams, Quality Control Inspectors |
| Companies Covered | Gravotech, Epilog Laser, Trotec Laser GmbH, HeatSign, Shenzhen LaserPecker Technology Co., Ltd., Shenzhen Ortur Technology Co., Ltd., Shenzhen Neje Technology Co., Ltd., Shenzhen Atomstack Technology Co., Ltd., Shenzhen Sculpfun Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Engraving Machine Market Trends and Innovations
Software-defined control architectures and wireless connectivity protocols are dissolving the boundary between consumer-grade portability and industrial-grade precision, enabling single platforms to serve adjacent buyer segments.
Diode laser modules with integrated beam-shaping optics are converging with machine vision alignment systems to enable freehand engraving on curved or irregular surfaces without mechanical fixturing. Automotive aftermarket parts suppliers are adopting these units for VIN restoration and component traceability. The technology is converging with cloud-based pattern libraries that push design updates directly to field-deployed hardware, compressing the traditional design-to-marking cycle from days to minutes.
REACH substance restrictions on cobalt-containing hard metals are forcing rotary tool manufacturers to reformulate cutting geometries around ceramic and cermet alternatives. The regulation is reshaping supplier qualification requirements for European importers. German and Italian OEMs are responding by accelerating in-house carbide sintering capabilities to maintain supply chain control.
Direct-to-maker distribution via hardware crowdfunding platforms is collapsing traditional two-step distribution margins for entry-level laser engravers. Shenzhen-based vendors are bypassing regional distributors entirely, capturing end-user data and service revenue streams previously held by local dealers. This channel shift is most visible in North American hobbyist and Etsy-seller segments where price transparency and community reviews dominate purchase decisions.
Handheld Engraving Machine Market Segmentation
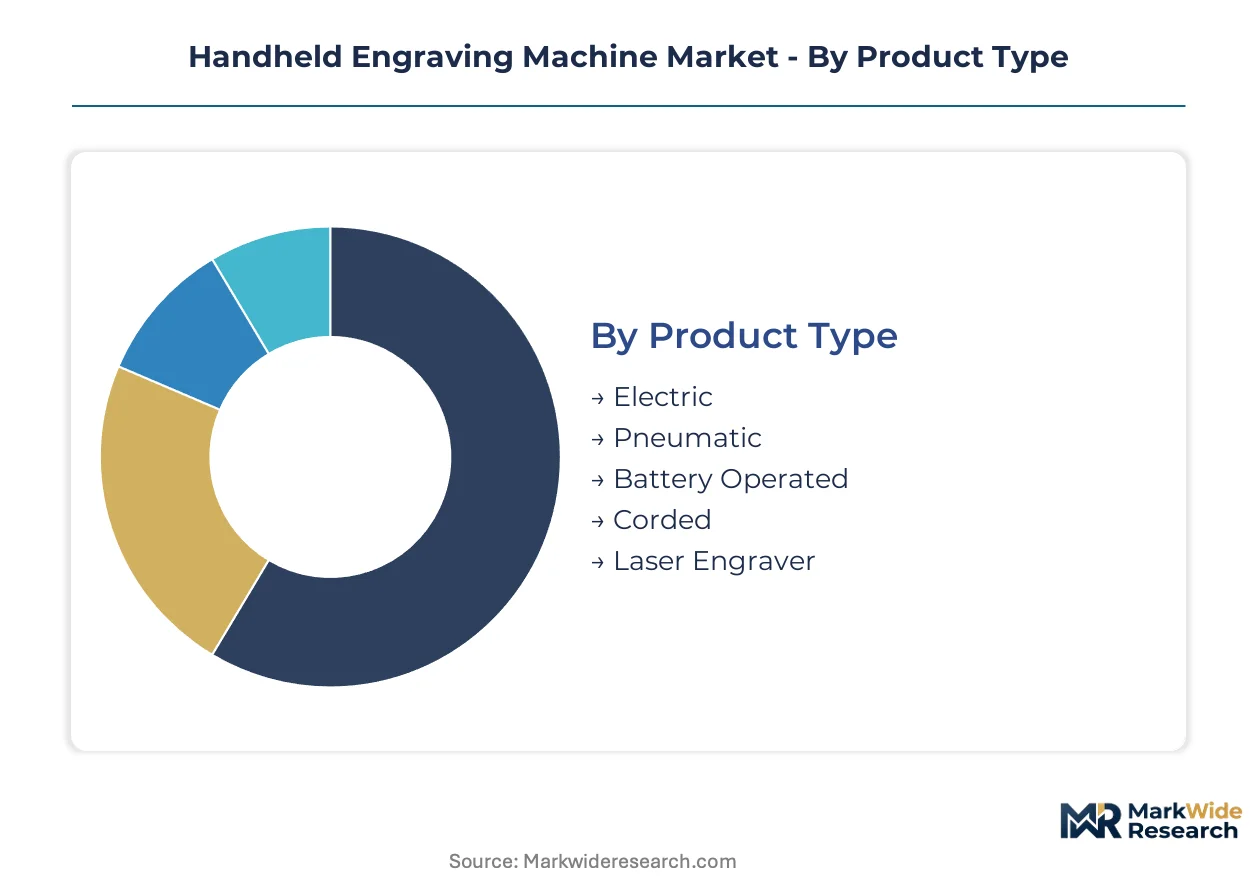
Segmentation in handheld engraving machines reveals how technology choices lock buyers into distinct operational ecosystems. Product type and power source decisions cascade into regulatory compliance obligations, maintenance burden, and total cost of ownership trajectories that reshape competitive positioning across artisan, industrial, and field service verticals.
Product Type:
Integration depth varies sharply: corded and pneumatic units anchor fixed workstations, while battery-operated and laser variants enable standalone deployment without facility infrastructure.
- Electric:Mains-powered rotary and reciprocating motor designs dominate volume production environments. Demand concentrates in German and Italian automotive supplier parks where continuous duty cycles and deep metal penetration specifications predominate.
- Pneumatic:Compressed-air-driven units deliver higher torque density for hardened steel marking in heavy manufacturing. Italian compressor OEMs bundle these with shop-air installations, embedding engraving capability within facility infrastructure rather than standalone purchase decisions.
- Battery Operated:Lithium-ion cordless platforms are expanding most quickly among North American field maintenance teams requiring on-site VIN restoration and asset tagging without generator support.
- Corded:Tethered electric designs persist in budget-conscious artisan workshops where mobility requirements remain secondary to acquisition cost minimization.
- Laser Engraver:Diode and fiber laser handhelds command premium positioning through software-upgradeable control architectures and consumable-free operation.
Corded electric units lead volumes today; battery-operated segments are gaining share fastest.
Technology:
Cost tier stratification separates capital-intensive laser platforms from consumable-dependent mechanical systems, with mid-range diamond and carbide alternatives occupying contested middle ground.
- Rotary:High-speed mechanical spindles operating between 5,000 and 35,000 RPM remain the default for deep metal engraving in aerospace component traceability. German tool manufacturers defend margin positions through proprietary collet systems and vibration-dampening housings.
- Diamond Tip:Monocrystalline and polycrystalline diamond styluses deliver micron-scale precision for jewelry hallmarking and watch case engraving. Swiss and Belgian luxury goods manufacturers specify these for precious metal applications where surface integrity commands priority.
- Laser:Solid-state and fiber laser sources eliminate mechanical wear while enabling grayscale imaging and barcode serialization. Chinese diode laser OEMs from Shenzhen hardware clusters are collapsing price floors through vertical integration of driver electronics and beam delivery optics.
- Micro-Abrasion:Pressurized abrasive stream systems texturize surfaces without thermal damage, serving medical device marking where heat-affected zones violate biocompatibility protocols.
- Ultrasonic:Piezoelectric vibration tools penetrate brittle ceramics and glass substrates that fracture under mechanical stress, finding niche adoption in Japanese electronics component marking.
Rotary technology anchors current volume; laser platforms are climbing the fastest.
Application:
Customer maturity diverges: jewelry and woodcraft segments tolerate learning curves and open-source control software, while aerospace and automotive buyers mandate certified process validation and supplier audit trails.
- Jewelry Design:Precious metal surface decoration and hallmark compliance drive demand for portable units that travel between trade shows and client consultations. Italian goldsmith districts around Arezzo and Valenza Pollo specify compact rotary and laser platforms for hallmarking flexibility.
- Automotive Components:Powertrain and chassis part traceability requirements under EU End-of-Life Vehicle directives and US NHTSA regulations enforce permanent marking depth standards. German OEM supplier parks concentrate demand for pneumatic and high-torque electric units.
- Aerospace Marking:FAA and EASA airworthiness directives mandate part serialization with specific depth and contrast requirements. French and UK aerostructure manufacturers specify laser systems with integrated vision verification to eliminate human-readable inspection errors.
- Woodcraft:Decorative personalization and maker-culture hobbyist demand concentrates in North American direct-to-consumer channels, where Shenzhen-based vendors bypass traditional distribution through crowdfunding platforms.
- Electronic Devices:PCB marking, connector serialization, and component traceability under RoHS and REACH substance tracking requirements favor non-contact laser methods that avoid conductive debris generation.
Automotive applications lead volumes today; jewelry design is expanding most quickly.
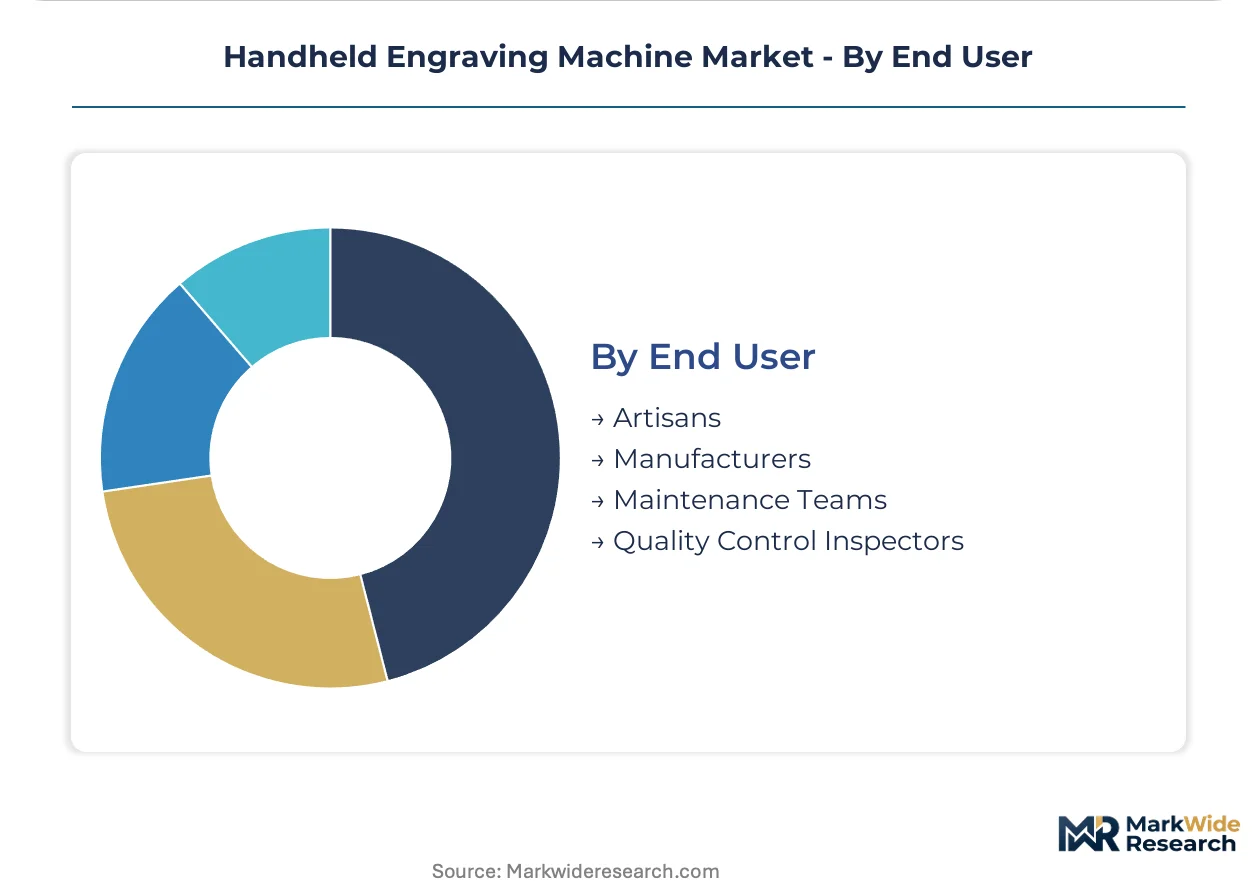
End User:
Procurement authority fragmentation separates capital-budget manufacturers from expense-account field technicians, with quality control inspectors occupying hybrid purchasing roles.
- Artisans:Independent craftspeople and Etsy-scale producers prioritize smartphone-integrated control apps and cloud pattern libraries over industrial-grade precision specifications. Shenzhen LaserPecker and Ortur target this segment through Bluetooth connectivity and community-developed firmware.
- Manufacturers:Production floor integration demands MES connectivity, batch serialization, and audit trail documentation that consumer-grade platforms cannot satisfy. Gravotech and German industrial marking specialists defend this tier through certified safety architectures and ERP integration toolkits.
- Maintenance Teams:Field service technicians require battery autonomy, ruggedized housings, and rapid pattern loading for on-site asset identification. North American utility and transportation fleet operators are pulling cordless laser units into preventive maintenance workflows.
- Quality Control Inspectors:Incoming goods verification and non-conformance marking responsibilities create demand for portable units that bridge laboratory precision with shop-floor durability. Japanese automotive transplant facilities in the US Southeast specify these for supplier audit flexibility.
Manufacturers dominate current procurement volumes; maintenance teams are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Handheld engraving technology traces its industrial roots to Swiss and German precision toolmaking traditions of the early twentieth century, where watchmakers and metalworkers developed portable marking instruments for artisan workshops. Contemporary demand geography reflects this heritage while incorporating new manufacturing centers in East Asia and North America.
Germany
Automotive supplier parks in Baden-Württemberg and Bavaria sustain concentrated demand for pneumatic and high-torque electric units serving powertrain traceability mandates. The KBA enforces EU Machinery Directive compliance through type-approval protocols that filter non-certified equipment from industrial procurement channels. Stuttgart-based tooling clusters maintain captive carbide sintering capabilities to satisfy REACH substance restrictions on cobalt-containing hard metals.
China
Shenzhen hardware clusters in the Pearl River Delta dominate export manufacturing of cost-optimized diode laser and rotary platforms for North American and European hobbyist segments. SAMR enforces GB standards for electromagnetic compatibility and laser radiation safety in domestic distribution. Guangdong-based firmware communities drive open-source control software development that accelerates feature expansion across consumer-grade product lines.
United States
Field maintenance teams in utility and transportation sectors are pulling battery-operated laser units into preventive maintenance workflows for on-site asset identification. The FDA regulates laser-emitting engravers under 21 CFR 1040 radiation safety standards, while OSHA mandates laser safety officer certification for Class 3B and Class 4 workplace deployments. Texas and California anchor demand concentration for cordless platforms serving oilfield and aerospace aftermarket applications.
Italy
Goldsmith districts around Arezzo and Valenza Pollo specify compact rotary and laser platforms for hallmarking flexibility and precious metal surface decoration. CE marking requirements under the EU Machinery Directive shape product access through mandatory emergency stop functionality and laser safety interlocks. Italian compressor OEMs bundle pneumatic engraving units with shop-air installations, embedding capability within facility infrastructure rather than standalone purchase decisions.
Japan
Piezoelectric vibration engraving tools penetrate brittle ceramics and glass substrates for electronics component marking in Kyushu and Kansai manufacturing regions. METI oversees JIS standard compliance for industrial equipment safety and electromagnetic compatibility. Nagoya-area automotive transplant facilities specify portable units for supplier audit flexibility and incoming goods verification workflows.
Handheld Engraving Machine Market Competitive Landscape
The competitive structure tilts toward geographically clustered specialists rather than diversified industrial conglomerates. European manufacturers defend premium positioning through certified safety architectures and ERP integration toolkits, while Chinese hardware clusters compete aggressively on cost engineering and firmware accessibility. Three archetypes dominate: heritage European industrial marking specialists, Shenzhen-based consumer electronics crossovers, and open-source firmware community anchors. Capacity expansion in Pearl River Delta manufacturing and strategic partnerships for distribution bypass dominate competitive moves.
Among European heritage manufacturers, Gravotech exemplifies the certified safety architecture archetype. Shenzhen LaserPecker Technology Co., Ltd. and Shenzhen Ortur Technology Co., Ltd. occupy positions within the consumer-portable tier, representing the Shenzhen hardware cluster's convergence of smartphone integration and community-driven firmware development. These Chinese entities sit within a broader ecosystem of vertically integrated diode laser OEMs that collapse price floors through captive supply of driver electronics and beam delivery optics.
| Leading Market Players |
|---|
| Gravotech |
| Epilog Laser |
| Trotec Laser GmbH |
| HeatSign |
| Shenzhen LaserPecker Technology Co., Ltd. |
| Shenzhen Ortur Technology Co., Ltd. |
| Shenzhen Neje Technology Co., Ltd. |
| Shenzhen Atomstack Technology Co., Ltd. |
| Shenzhen Sculpfun Technology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jewelry designers and small-batch manufacturers demanding CE-certified safety architectures for European market access are compelling OEMs to absorb certification costs into unit economics, compressing margins at the economy tier while elevating premium positioning for compliant architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction flows, with premium tiers anchored by Gravotech and German industrial specialists commanding spreads based on ERP integration toolkits and emergency stop functionality. Price differentiation separates laser engraver platforms with software-upgradeable control architectures from consumable-dependent rotary systems. Cost compression in the economy tier is intensifying because Shenzhen hardware clusters vertically integrate driver electronics and beam delivery optics. Artisan buyers through crowdfunding channels exhibit highest price sensitivity; aerospace procurement teams under FAA and EASA mandates show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German automotive supplier parks and Italian goldsmith districts are forcing component vendors to maintain parallel qualification tracks across Chinese diode laser foundries and European carbide sintering facilities. Manufacturing concentrates in China for electronics and optics, Germany for precision mechanical assemblies, and Italy for pneumatic compressor-integrated systems. Raw material dependencies span lithium-ion cells for cordless platforms, cobalt-free cermet formulations for REACH compliance, and monocrystalline diamond substrates for jewelry applications. Single-source vulnerability concentrates in Shenzhen firmware communities controlling open-source control architectures. Distribution runs through hardware crowdfunding platforms for entry-tier units and industrial distributor networks for certified systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Machinery Directive compliance mandates and FDA laser classification thresholds continuously reset competitive barriers, with REACH substance restrictions on cobalt-containing hard metals driving the latest wave of supplier requalification.
For Market Incumbents: Acquire captive carbide sintering capabilities to insulate against REACH-driven supplier disruption. German and Italian OEMs are already internalizing ceramic and cermet cutting geometries. Certification investment in Class 3B and Class 4 laser safety officer training programs defends position against Shenzhen-based entrants lacking OSHA and EU workplace directive compliance infrastructure. For New Entrants and Emerging Players: Begin with battery-operated laser platforms serving North American field maintenance teams in utility and transportation sectors, where cordless autonomy requirements outpace incumbent product cycles. Smartphone-integrated control apps for artisan segments offer the most penetrable white-space, collapsing dedicated hardware requirements through Bluetooth connectivity. For Investors and Strategic Acquirers: Asymmetric upside sits with open-source firmware community anchors that lower R&D burden while accelerating functional differentiation. Long-term viability over a multi-year window hinges on regulatory compliance scalability rather than unit cost alone. Watch for IATA lithium-ion transport restriction enforcement as the inflection signal that reshapes cordless product roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Sintering | REACH compliance on cobalt hard metals forces German OEMs to internalize ceramic cutting geometry production. |
| Open-Source Firmware Ecosystem Development | Shenzhen-based vendors accelerate feature expansion through community-driven control software at lower R&D burden. |
| Battery Supply Agreement with UN 38.3 Certified Cells | IATA transport restrictions elevate compliant lithium-ion sourcing to competitive differentiator for cordless units. |
| Smartphone Integration Platform Launch | Bluetooth-connected engraving apps collapse price floors and expand first-time buyer pools among Etsy-scale artisans. |
| Laser Safety Officer Certification Program | OSHA and EU workplace directive compliance becomes mandatory gating factor for enterprise Class 3B and Class 4 deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with jewelry designers, automotive supplier quality engineers, field maintenance technicians, and open-source firmware developers with secondary validation through FDA 21 CFR 1040 filings, EU Machinery Directive type-approval databases, and Shenzhen hardware cluster export customs records. Bottom-up unit shipment modeling and top-down value aggregation were cross-referenced for triangulation.
Comparable historical periods anchored volume and value trajectories across the projection horizon, with segmentation modeled by product type, technology, application, end user, and power source. CAGRs were derived from fitted growth curves calibrated to OEM shipment disclosures and distributor inventory turns. Industry-specific forecast inputs included laser classification threshold evolution and battery transport regulatory enforcement patterns.
Several conditions sit outside the modeled scope, including hypothetical tariff restructuring on Chinese electronics imports and breakthrough solid-state battery commercialization timelines. Forecasts reflect documented assumptions about regulatory stability and technology substitution rates. Deviation in EU Machinery Directive enforcement intensity or IATA lithium-ion restriction scope would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gear Honing Machines Market
Tools
Mold Racks Market
Tools
Machine Vise Market
Tools
Cordless Impact Wrench Market
Tools
Global Electric Portable Drill Market
Tools
Power Drill Market
Tools
Thickness Planers Market
Tools
Rotary Tools Market
Tools
Crimping Tool Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Foldable Ladder Market
Tools
Bearing Installation Tool Kit Market
Tools
Gouging Torch Market
Tools
Woodworking CNC Tools Market
Tools
Wood-Sanding Machine Market
Tools
Europe Woodworking Power Tools Market