
 Saw Blades Market | 2026-2036
Saw Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Saw Blades Market Intelligence
Buyer concentration among tool manufacturers is decoupling from traditional metal workshop demand as construction contractors and furniture makers diversify procurement channels. Robert Bosch GmbH leverages its power-tool ecosystem to sustain blade attachment rates across cordless platforms. LEUCO AG anchors European woodworking demand through specialized carbide-tipped circular saw blades for CNC machining centers. WIKUS competes in band saw blade niches where bi-metal durability commands premium positioning in metal fabrication.
Saw blades are precision cutting tools manufactured from high-speed steel, carbide-tipped alloys, or diamond-coated substrates, engineered with specific tooth geometries and rake angles to sever wood, metal, stone, or plastic with dimensional accuracy. Circular saw blades dominate volume in construction and woodworking where large-diameter carbide-tipped designs handle bulk rip and crosscut operations. Diamond blades command the fastest growth trajectory in stone masonry and concrete cutting as infrastructure investment intensifies demand for abrasive-resistant cutting edges. Band saw blades retain mature, stable demand in metal fabrication where continuous cutting of structural steel requires bi-metal weld endurance.
OSHA machine guarding standards in the United States and REACH substance restrictions in Europe constrain coating chemistries and mandate blade guard integration, elevating compliance costs for manufacturers serving both markets. China's GB standards and SAMR certification requirements create additional testing burdens for carbide sourcing and diamond segment bonding. Stakeholders must monitor evolving efficiency regulations across multiple geographies while aligning R&D spending toward material innovations that satisfy tightening environmental and safety protocols.
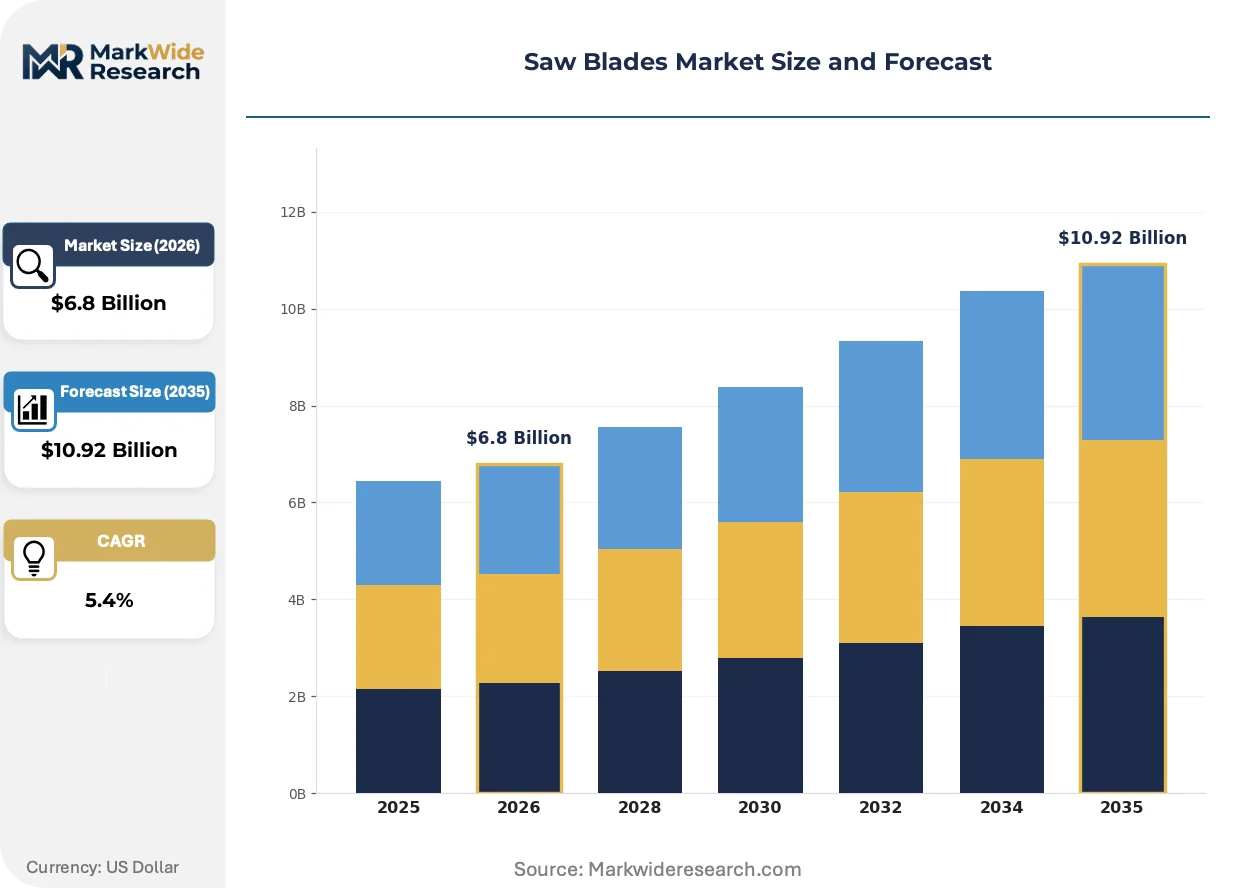
Market Dynamics
Carbide-tipped and diamond-coated blade technologies are compressing replacement cycles while China's MIIT efficiency standards and the EU's F-Gas Regulation force simultaneous equipment upgrades across metal fabrication and woodworking verticals.
Growth Catalysts
- CNC machining center penetration:Furniture makers in Germany's Baden-Württemberg cluster demand specialized carbide-tipped circular saw blades for precision cutting operations.
- REACH substance restrictions:Coating chemistry reforms across Europe are accelerating R&D investment in compliant bonding agents for diamond segment attachment.
- Infrastructure concrete cutting:Diamond blades for stone masonry command expanding volume as abrasive-resistant cutting edges replace conventional abrasive wheels in highway and building projects.
Market Restraints
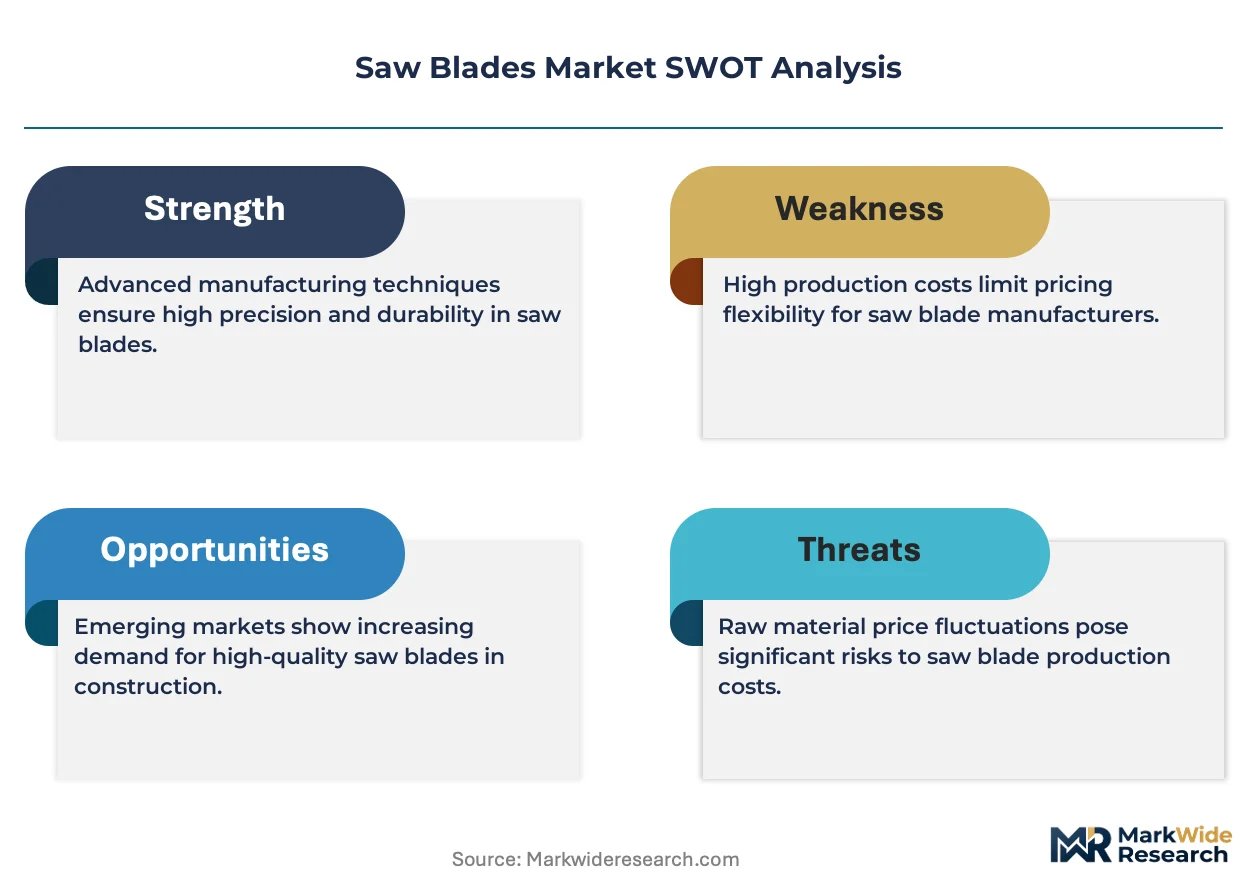
- Tungsten carbide price volatility:Raw material concentration in Chinese supply chains exposes blade manufacturers to input cost swings and export quota uncertainties.
- Bi-metal weld technical ceiling:Band saw blade durability in continuous structural steel cutting hits performance limits that diamond alternatives have not yet cost-effectively breached.
- OSHA machine guarding compliance:Blade guard integration mandates elevate manufacturing costs for products serving the United States market without commensurate price recovery mechanisms.
Strategic Opportunities
- India's PLI scheme for manufacturing:Tool producers can establish localized carbide-tipping facilities to serve domestic furniture and construction equipment demand.
- EU Green Deal circularity requirements:Blade remanufacturing and tip-replacement services gain regulatory preference over disposable cutting tool models.
- Digital cutting parameter optimization:Sensor-embedded blades converging with IoT feedback loops enable predictive wear monitoring in high-volume CNC environments.
Industry Challenges
- Carbide tip brazing certification timelines:China's SAMR bonding testing protocols extend product approval cycles by six to nine months for imported blade assemblies.
- Multi-standard compliance engineering:Simultaneous satisfaction of OSHA guarding, REACH coatings, and GB material specifications fragments R&D resources across incompatible technical requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saw Blades Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circular Saw Blades, Band Saw Blades, Reciprocating Saw Blades, Jig Saw Blades, Diamond Blades Material: High-Speed Steel, Carbide Tipped, Diamond Coated, Bi-Metal, Tungsten Carbide Application: Woodworking, Metal Fabrication, Construction, Plastic Cutting, Stone Masonry End User: Tool Manufacturers, Construction Contractors, Metal Workshops, DIY Enthusiasts, Furniture Makers |
| Companies Covered | Festool Group GmbH & Co. KG, WIKUS, Robert Bosch GmbH, LEUCO AG, Lenox Corporation, Stanley Black and Decker Inc., The Milwaukee Electric Tool Corporation, Dimar Cutting Tools Ltd., Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saw Blades Market Strategic Shifts & Innovations
Material science advances in substrate bonding and tooth geometry are compressing the performance gap between premium and standard blade tiers while regulatory pressure on industrial cooling and emissions reshapes equipment procurement criteria.
Polycrystalline diamond compact cutting edges are integrating into high-speed circular saw designs for composite material processing. Aerospace tier suppliers in Germany and Japan adopt these blades for carbon-fiber reinforced polymer machining where conventional carbide dulls within minutes. The technology is integrating precision cutting capability into automated production lines previously requiring waterjet or laser alternatives.
The EU's F-Gas Regulation on fluorinated greenhouse gases in industrial cooling systems is mandating refrigeration retrofits in metal fabrication facilities. Wet-cutting blade stations dependent on cooled flood coolant must upgrade to closed-loop systems or dry-cutting alternatives. German machine-tool operators face the steepest compliance costs given their concentration of legacy wet-cutting infrastructure.
Direct procurement from blade specialists is displacing distributor-mediated purchasing among mid-sized construction contractors. E-commerce platforms with technical specification filters and volume pricing algorithms capture share from traditional industrial supply houses. This channel rotation is most visible in the United States where contractor buying groups consolidate spend through negotiated direct agreements with carbide-tipping specialists.
Saw Blades Market Segmentation
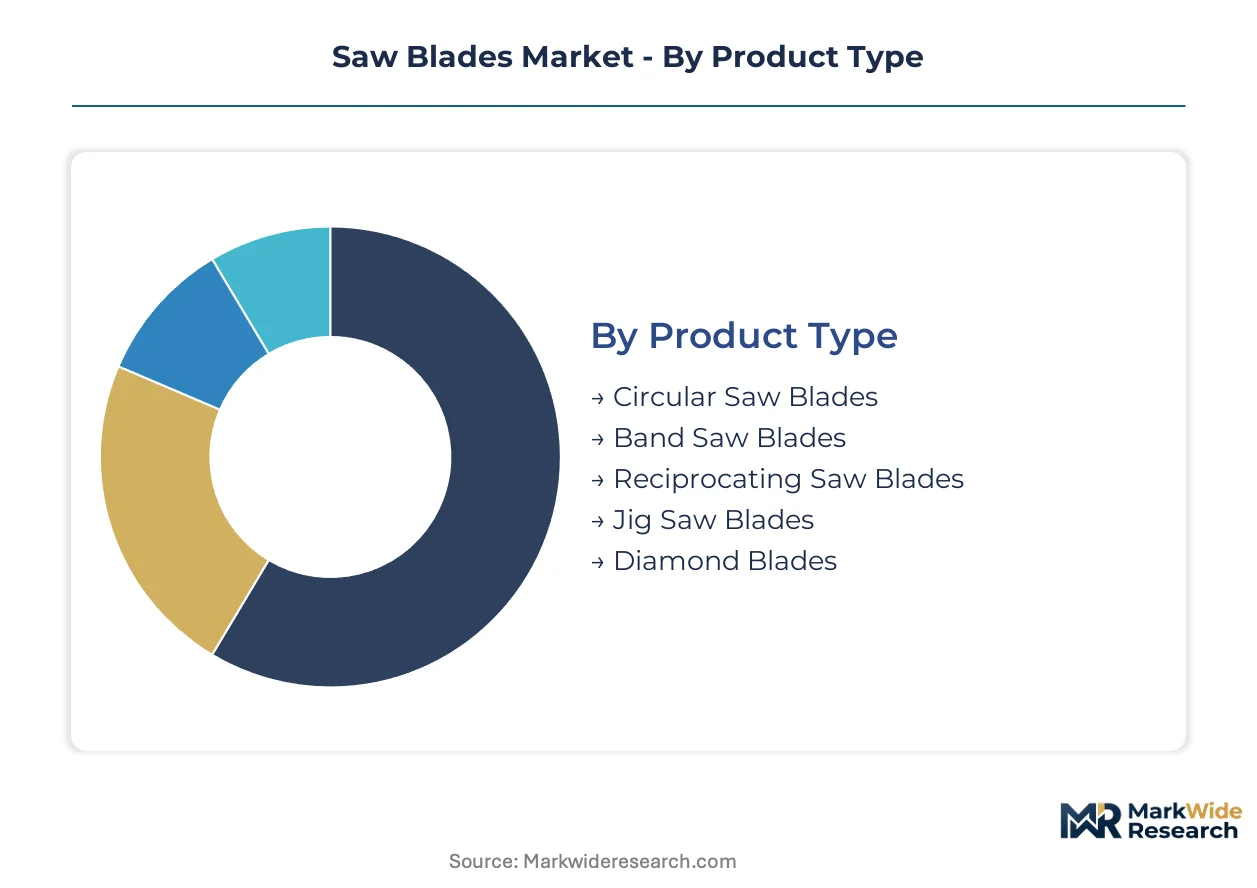
Segmentation in saw blades reveals distinct procurement patterns across material technologies and end-use applications. Product type and material composition drive fundamentally different margin structures, while application verticals determine regulatory exposure and replacement cycle velocity.
Product Type:
Circular saw blades command volume leadership in construction and woodworking, while diamond blades capture the steepest premium expansion trajectory.
- Circular Saw Blades:Large-diameter carbide-tipped designs dominate bulk rip and crosscut operations across construction sites and furniture manufacturing facilities. German CNC machining centers in Baden-Württemberg concentrate specialized demand for precision-ground tooth geometries.
- Band Saw Blades:Bi-metal weld construction delivers continuous cutting endurance for structural steel processing in metal fabrication. Mature demand stability reflects replacement-rate predictability rather than technology disruption.
- Reciprocating Saw Blades:Demolition and remodeling contractors in the United States drive consumption through cordless power-tool platform attachments.
- Jig Saw Blades:Curved-cutting precision for finish carpentry and custom furniture work supports moderate volume with higher SKU fragmentation.
- Diamond Blades:Abrasive-resistant cutting edges replace conventional wheels in highway infrastructure and building projects. China's MIIT efficiency standards accelerate wet-to-dry cutting transitions in municipal concrete work.
Mature deployment sits with band saw blades in continuous metal processing. Newer deployment is concentrated in diamond blades for abrasive material applications.
Material:
Cost tier stratification separates commodity steel substrates from precision-engineered carbide and diamond coatings.
- High-Speed Steel:Entry-level cutting tools for intermittent DIY and light workshop use. Price-sensitive procurement through distributor channels constrains margin recovery.
- Carbide Tipped:Tungsten carbide teeth brazed to steel bodies deliver multi-material cutting durability. REACH substance restrictions on coating chemistries force European manufacturers toward compliant bonding agent R&D.
- Diamond Coated:Polycrystalline diamond compact edges machine carbon-fiber reinforced polymers for aerospace tier suppliers in Germany and Japan. Waterjet and laser substitution creates technology competition at the precision frontier.
- Bi-Metal:High-speed steel teeth electron-beam welded to flexible alloy backings optimize fatigue resistance in continuous band saw operations.
- Tungsten Carbide:Solid substrate construction for extreme-wear mining and quarrying applications. Chinese export quota uncertainties expose manufacturers to input cost volatility.
Volume concentration rests with carbide-tipped configurations. Technology migration is accelerating toward diamond-coated substrates.
Application:
End-use differentiation determines blade specification complexity and regulatory compliance burden intensity.
- Woodworking:Furniture makers demand specialized tooth geometries for hardwood, softwood, and engineered panel materials. OSHA machine guarding mandates elevate manufacturing costs for US-serving product lines.
- Metal Fabrication:Structural steel cutting requires bi-metal weld endurance in continuous production environments. EU F-Gas Regulation retrofits force wet-cutting station upgrades to closed-loop cooling or dry alternatives.
- Construction:General contractors consolidate procurement through direct agreements with carbide-tipping specialists, displacing traditional industrial supply house intermediation.
- Plastic Cutting:Specialized tooth geometries prevent melting and chip welding in thermoplastic and composite material processing.
- Stone Masonry:Diamond blades gain share fastest against abrasive wheels in highway and infrastructure concrete cutting applications.
Established application density clusters in woodworking. Emerging application intensity is shifting toward stone masonry infrastructure work.
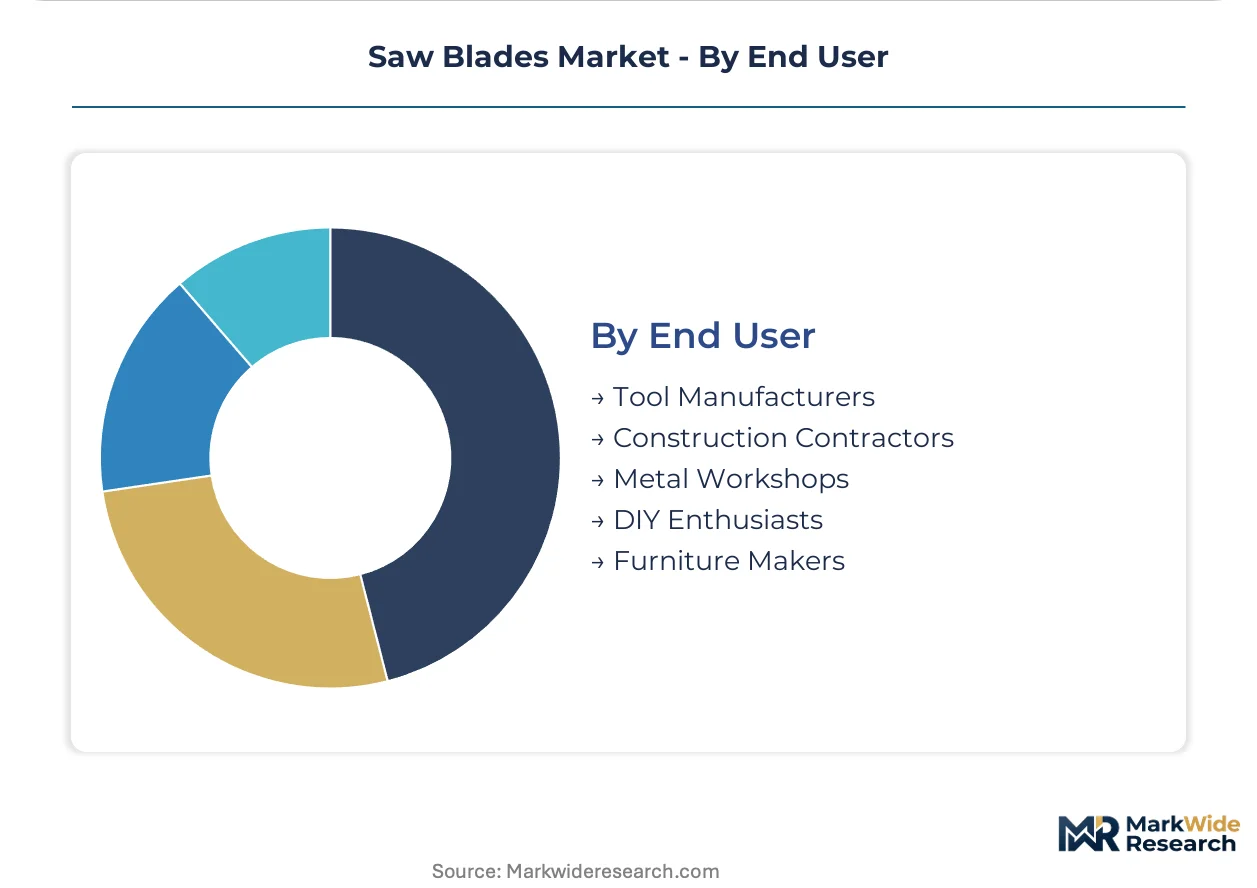
End User:
Customer type segmentation reveals procurement channel bifurcation between integrated tool platforms and specialized blade sourcing.
- Tool Manufacturers:Power-tool OEMs bundle blade attachments to sustain ecosystem lock-in across cordless platform generations. Attachment rate optimization drives volume commitment negotiations.
- Construction Contractors:Mid-sized US contractors leverage buying group consolidation for direct procurement from blade specialists. E-commerce technical specification filters capture share from distributor networks.
- Metal Workshops:Continuous cutting operations demand predictable replacement cycles and bi-metal weld technical support.
- DIY Enthusiasts:Price-sensitive occasional use supports entry-level high-speed steel and basic carbide-tipped consumption through retail channels.
- Furniture Makers:Precision CNC machining centers in specialized manufacturing clusters require customized tooth geometries and rapid tip-replacement services.
Longstanding end-user concentration persists with metal workshops. Procurement transformation is advancing most rapidly among construction contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany's Baden-Württemberg machine-tool cluster, where specialized blade consumption outpaces broader European industrial output. China's MIIT efficiency standards and the EU's F-Gas Regulation on industrial cooling are reshaping equipment upgrade cycles across metal fabrication and woodworking verticals.
Germany
Furniture makers in Baden-Württemberg drive specialized carbide-tipped circular saw blade demand for CNC machining centers. The EU's F-Gas Regulation mandates refrigeration retrofits in wet-cutting stations, forcing metal fabricators toward closed-loop cooling or dry-cutting alternatives. Stuttgart's machine-tool cluster anchors precision blade consumption for aerospace composite processing.
United States
OSHA machine guarding standards elevate manufacturing costs for blade guard integration across construction and woodworking product lines. Mid-sized contractors consolidate procurement through direct agreements with carbide-tipping specialists, displacing traditional distributor networks. The Southeast industrial corridor shows fastest channel rotation toward e-commerce technical specification platforms.
China
MIIT efficiency standards accelerate wet-to-dry cutting transitions in municipal concrete work and metal fabrication facilities. SAMR certification requirements extend product approval cycles by six to nine months for imported blade assemblies. Yangtze River Delta manufacturing bases concentrate carbide sourcing and diamond segment bonding operations under tightening GB material specifications.
India
The PLI scheme for manufacturing attracts tool producers to establish localized carbide-tipping facilities serving domestic furniture and construction equipment demand. BIS standards create testing alignment challenges for multi-standard compliance engineering. Gujarat and Maharashtra industrial corridors concentrate emerging procurement from infrastructure contractors adopting diamond blades for highway projects.
Japan
Aerospace tier suppliers adopt polycrystalline diamond compact cutting edges for carbon-fiber reinforced polymer machining. METI industrial efficiency guidelines pressure metal fabricators toward equipment modernization. The Chubu region around Nagoya anchors precision blade demand for automated production lines previously requiring waterjet alternatives.
Saw Blades Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue digital cutting parameter optimization and sensor-embedded blade technologies. The vendor base organizes around three archetypes: power-tool ecosystem bundlers, specialized carbide-tipping fabricators, and premium diamond-coating specialists. Consolidation pressure concentrates among mid-scale bi-metal weld producers facing technical ceiling constraints. Dominant competitive moves include strategic partnerships for IoT feedback loop integration and geographic expansion into India's PLI-subsidized manufacturing zones.
Within the power-tool ecosystem tier, Robert Bosch GmbH and Stanley Black and Decker Inc. represent archetypal platform bundlers sustaining attachment rates across cordless generations. Among specialized European fabricators, LEUCO AG occupies a position exemplifying precision carbide-tipping concentration for CNC machining centers. WIKUS anchors the bi-metal band saw blade segment where durability commands premium positioning in continuous structural steel cutting.
| Leading Market Players |
|---|
| Festool Group GmbH & Co. KG |
| WIKUS |
| Robert Bosch GmbH |
| LEUCO AG |
| Lenox Corporation |
| Stanley Black and Decker Inc. |
| The Milwaukee Electric Tool Corporation |
| Dimar Cutting Tools Ltd. |
| Makita Corporation |
| Others |
Cost & Logistics Intelligence
Construction contractor procurement consolidation in the United States is forcing blade manufacturers to absorb blade guard integration costs mandated by OSHA machine guarding standards, compressing margins on construction-grade carbide-tipped lines while premium CNC-specialized products retain pricing power through specification lock-in.
Pricing Analysis
Volume concentrates in standard carbide-tipped circular saw blades where price competition intensifies among distributor channels, while premium diamond-coated and polycrystalline diamond compact configurations command sustained margin premiums through aerospace and infrastructure specification requirements. Three-tier pricing structure across premium, standard, and economy levels separates OEM-bundled attachments from specialized fabricator direct sales and retail DIY channels. Cost compression in standard tiers is intensifying because REACH-compliant bonding agent R&D investments elevate European manufacturing baselines without full price pass-through. DIY enthusiasts exhibit highest price sensitivity through retail procurement, while German furniture makers in Baden-Württemberg demonstrate lowest sensitivity due to CNC downtime cost exposure.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns serving machine-tool clusters, construction corridors, and municipal infrastructure contractors respectively. Tungsten carbide sourcing concentrates in China, bi-metal weld substrate production centers on Germany and Japan, and diamond segment bonding operations cluster in the Yangtze River Delta. Raw material dependencies draw from Chinese tungsten concentrate exports, European cobalt alloy supply, and synthetic diamond substrate from Japanese producers. Single-source vulnerability in Chinese tungsten carbide supply exposes manufacturers to export quota disruptions. Distribution runs through power-tool OEM bundling agreements, specialized industrial distributors, and direct e-commerce procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation compliance costs for wet-cutting station retrofits create a barrier-to-entry moat favoring incumbent fabricators with established closed-loop cooling R&D capabilities and regulatory certification infrastructure.
For Market Incumbents: To counter sensor-embedded blade entrants pursuing IoT-enabled predictive wear monitoring, deepen backward integration into carbide tipping facilities in India's PLI-subsidized zones and secure SAMR pre-certification for Chinese market access to compress approval timelines. For New Entrants and Emerging Players: Begin with India's infrastructure contractor segment where diamond blade penetration remains below European benchmarks and BIS standard alignment creates lower compliance entry costs than multi-standard markets. Pursue direct e-commerce technical specification platforms as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-scale bi-metal weld producers facing technical ceiling pressure from diamond alternatives, offering consolidation arbitrage before displacement accelerates. Monitor wet-to-dry cutting transition velocity in China's municipal concrete sector as the inflection indicator for diamond blade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Tipping | Captures margin from Chinese tungsten concentrate volatility through captive Yangtze River Delta facilities. |
| Sensor-Embedded Blade Development | Enables predictive wear monitoring for LEUCO AG's CNC machining center customers in Baden-Württemberg. |
| India PLI Zone Manufacturing Establishment | Localizes production for Gujarat and Maharashtra infrastructure contractor procurement growth. |
| REACH-Compliant Bonding Agent R&D | Satisfies ECHA substance restrictions for diamond segment attachment in European markets. |
| Direct E-Commerce Platform Launch | Captures US Southeast contractor buying group consolidation away from traditional industrial distributors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads validated demand patterns across construction, metal fabrication, and woodworking verticals. SEC 10-K filings, MIIT efficiency standard disclosures, REACH substance restriction updates, and USITC import trade data provided quantitative foundations. Bottom-up blade shipment aggregation and top-down equipment installation rate triangulation converged on segment-level estimates.
Granularity-level modeling distinguished circular saw blade, band saw blade, reciprocating saw blade, jig saw blade, and diamond blade categories by carbide-tipped, diamond-coated, bi-metal, and high-speed steel material compositions across woodworking, metal fabrication, construction, stone masonry, and plastic cutting applications. CAGRs were derived from equipment replacement cycle analysis and regulatory-driven upgrade timing. Projection inputs included CNC machining center penetration rates in German furniture manufacturing and MIIT-mandated wet-to-dry cutting transitions in Chinese municipal infrastructure.
Underlying measurement precision varies by segment; diamond blade growth trajectories carry tighter precision than mature bi-metal band saw replacement rate estimates. Forecasts reflect assumptions on infrastructure investment continuity and regulatory enforcement timelines. Periodic stress-testing of base assumptions is recommended given tungsten carbide price volatility and multi-standard compliance fragmentation risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Chainsaw Market
Tools
Tool Boxes Market
Tools
Tension Tester Market
Tools
Ratchet Wringer Market
Tools
Woodcarving Tool Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Mechanical Puller Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Grabber Pole Market
Tools
Edge Banders Market
Tools
Orbital Recip Saw Market
Tools
Masonry Cleaners Market
Tools
Stand Tile Saw Market
Tools
Power Press Machines Market
Tools
Hand Tools Market
Tools
Dumpy Level Market