
 Chainsaw Market | 2026-2036
Chainsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Chainsaw Market Intelligence
Professional landscaping is repositioning equipment procurement toward quieter, lower-emission systems. Husqvarna AB leverages its battery platform development to capture municipal contracts in noise-restricted zones. Andreas Stihl AG & Co. KG anchors its position through dense dealer networks serving professional arborists. Makita Corporation competes with compact cordless designs targeting residential users with smaller lot sizes.
A chainsaw is a portable mechanical saw powered by gasoline engine, electric motor, or battery pack, utilizing a rotating chain of cutting teeth to sever wood fibers across felling, bucking, and limbing operations. Standard bar lengths range from 12 to 36 inches, with chain pitch and gauge specifications matched to intended material density and cutting speed requirements. Battery-operated systems are capturing the fastest expansion as lithium-ion energy density improvements close the power gap with traditional gasoline units. Gas-powered equipment still dominates margin pools in professional forestry, where runtime demands and raw cutting torque remain decisive. Tree felling applications concentrate the highest equipment utilization rates and replacement part consumption across the installed base.
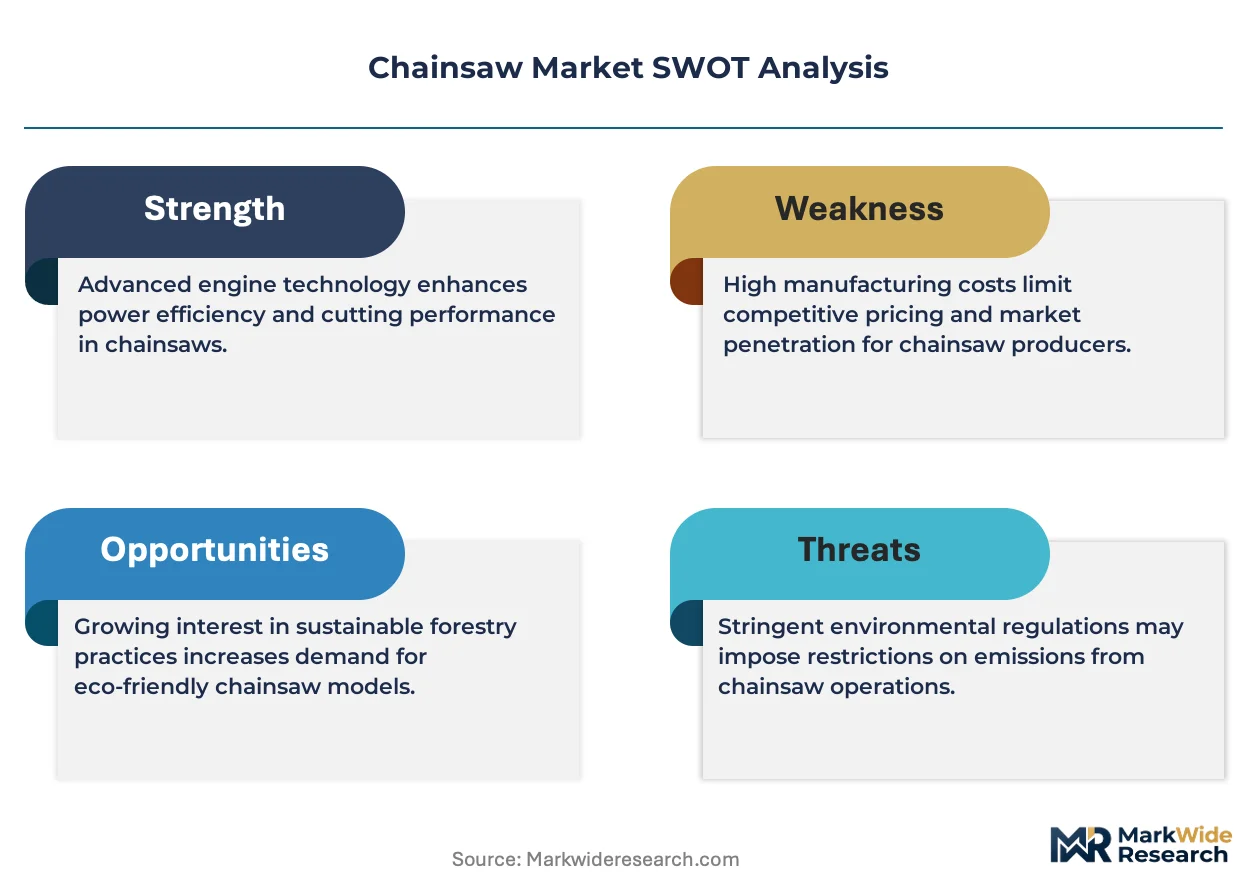
The EPA enforces exhaust emission standards for gasoline-powered outdoor equipment, pushing manufacturers toward catalytic converter integration or electrification pathways. The EU Green Deal and F-Gas Regulation constrain hydrocarbon-based propellants and lubricants in equipment sold across member states, while OSHA mandates personal protective equipment protocols that influence product bundling and training service attachments. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether platform standardization or regional customization offers superior capital efficiency.
Market Dynamics
Urban noise ordinances in Germany, the United States, and Japan are compressing demand for gasoline-powered equipment and accelerating lithium-ion platform investment by professional landscaping contractors.
Growth Catalysts
- EPA emission standards:Exhaust regulations for gasoline outdoor equipment push manufacturers toward catalytic integration or electrification, expanding battery platform R&D budgets.
- Residential tree care services:Homeowner investment in professional arborist maintenance climbs across suburban United States markets, sustaining replacement part consumption.
- Lithium-ion energy density improvements:Battery chemistry advances close the power gap with gasoline units, enabling cordless systems to capture municipal contracts in noise-restricted zones.
Market Restraints
- Runtime limitations:Battery-operated chainsaws face torque and duration constraints in professional forestry where felling operations demand sustained high-load performance.
- Dealer network concentration:Professional arborist equipment distribution concentrates through established networks, creating channel access barriers for new battery-platform entrants.
- EU F-Gas Regulation:Hydrocarbon-based lubricant constraints add compliance costs and formulation complexity for equipment sold across member states.
Strategic Opportunities
- Japan municipal procurement:METI-backed green procurement guidelines create preferential purchasing channels for low-noise, zero-emission equipment in Tokyo and Osaka metropolitan zones.
- Compact cordless residential designs:Smaller lot sizes in dense German suburbs favor lightweight battery systems for homeowner limb-trimming and light bucking tasks.
- OSHA PPE bundling:Personal protective equipment mandates enable manufacturers to attach training services and certified gear packages to equipment sales.
Industry Challenges
- Arborist technician certification:OSHA compliance timelines and specialized training requirements slow workforce scaling for contractors expanding battery fleet operations.
- Legacy gasoline inventory integration:Mixed-fleet maintenance complexity rises as contractors phase in cordless platforms alongside existing two-stroke equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chainsaw Market |
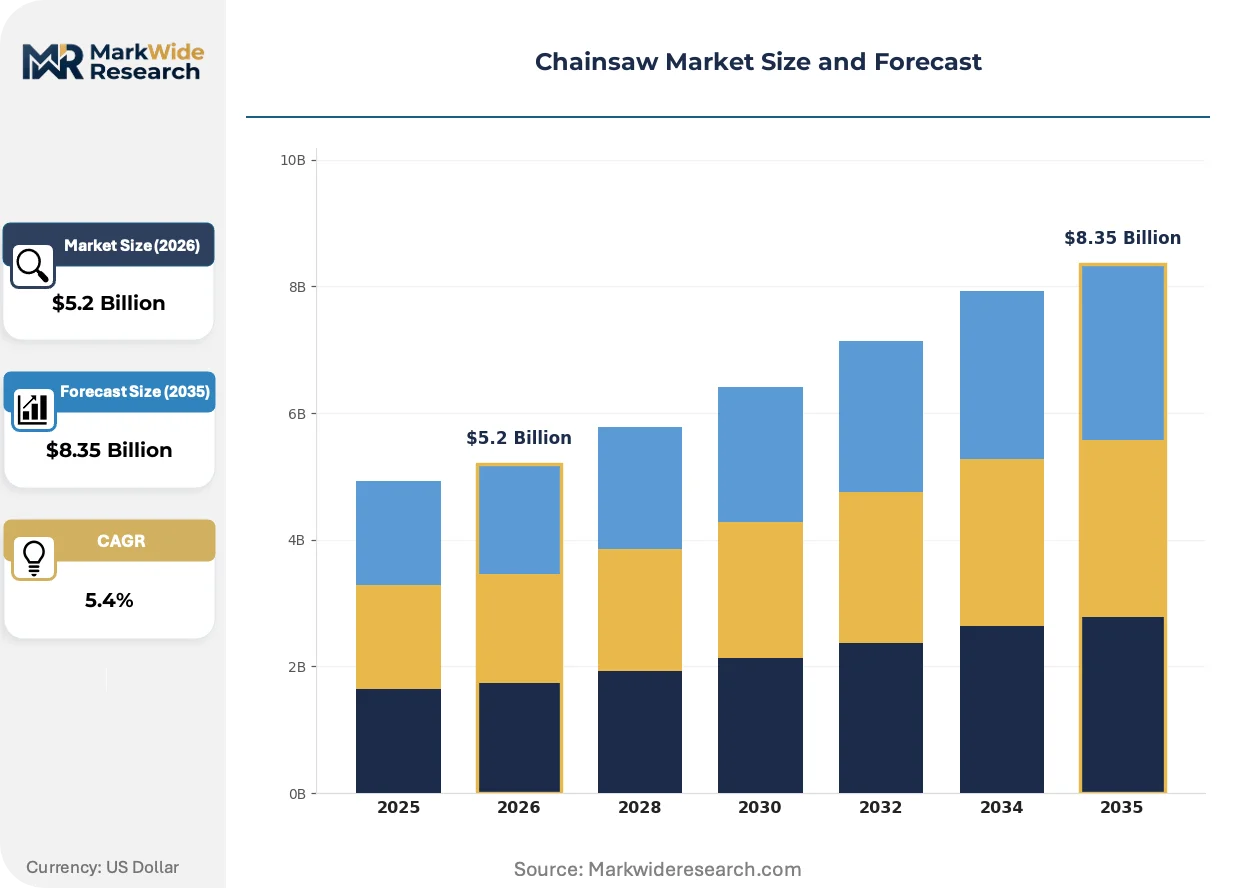
| Market Size in 2026 | $5.2 Billion |
| Market Size in 2035 | $8.35 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Powered, Electric, Battery-Operated, Hydraulic End User: Forestry, Landscaping, Construction, Firefighting Application: Tree Felling, Trimming, Milling, Chopping Sales Channel: Online Retail, Direct Sales, Distributors, Home Improvement Stores |
| Companies Covered | Robert Bosch GmbH, Stanley Black & Decker Inc., Husqvarna AB, Zhejiang Zomax Garden Machinery Co. Ltd., Oregon Tool Inc., Andreas Stihl AG & Co. KG, Echo Incorporated, STIHL Inc., Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chainsaw Market Strategic Shifts & Innovations
Equipment manufacturers are converging battery platform architectures with smart diagnostics and reconfiguring distribution to capture professional and residential segments simultaneously.
Brushless motor controllers paired with high-density lithium-ion cells are expanding into professional-grade cordless chainsaws previously dominated by gasoline engines. Landscaping contractors in noise-restricted German municipalities adopt these systems for routine maintenance contracts. The technology is expanding into tree felling applications as thermal management and peak torque delivery improve.
REACH chemical restrictions and EU Green Deal carbon accounting requirements tighten lubricant and material disclosure obligations for outdoor power equipment. Manufacturers must reformulate chain oils and plastic housings to maintain CE marking access. Professional forestry equipment faces the steepest compliance cost escalation due to higher duty-cycle material exposure.
Service bundling now displaces standalone equipment transactions in North American residential channels. Homeowners purchase annual tree care subscriptions that include equipment access, maintenance, and certified operator dispatch. California and Pacific Northwest metropolitan markets exhibit the fastest contract penetration where labor scarcity drives preference for turnkey solutions.
Chainsaw Market Segmentation
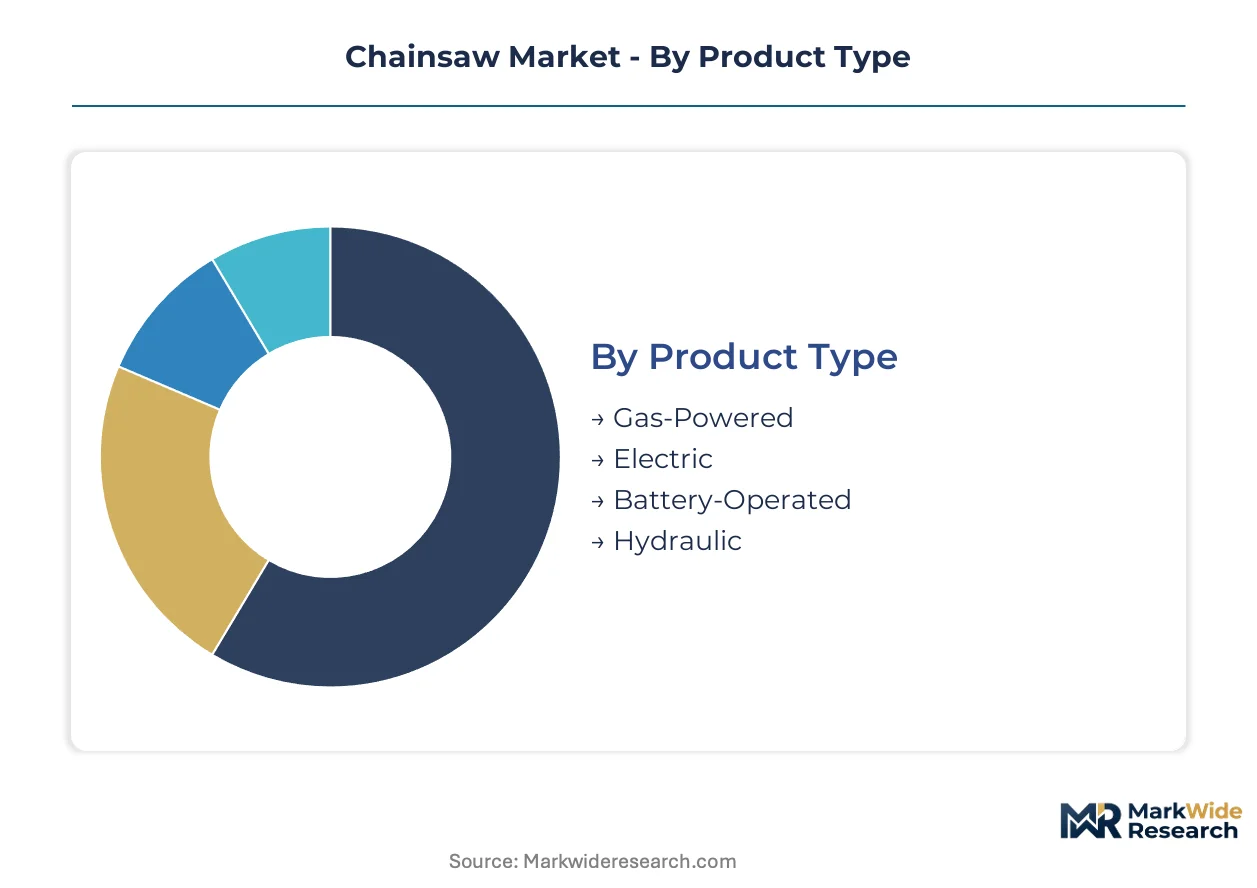
Equipment procurement patterns diverge sharply across professional and residential user bases, with power source selection and distribution channel access determining margin capture. Manufacturers align platform architectures to specific torque requirements and runtime constraints inherent to each operational segment.
Product Type:
Supply concentration in gasoline engine manufacturing still dominates professional-grade output, though battery cell procurement is reshaping component sourcing strategies.
- Gas-Powered:Two-stroke and four-stroke internal combustion engines deliver sustained high-torque output for professional forestry operations. Demand concentrates in Nordic timber harvesting and Pacific Northwest logging where felling cycles exceed eight hours daily and EPA emission compliance costs are absorbed through volume contracts.
- Battery-Operated:Lithium-ion cell packs paired with brushless motor controllers now achieve power parity with 40cc gasoline equivalents. German municipal landscaping contractors in noise-restricted Stuttgart and Munich zones drive procurement volume as urban ordinances tighten decibel limits.
- Electric:Corded systems with continuous AC power suit fixed-site milling operations and workshop environments where mobility constraints are acceptable. Japanese small-scale lumber processors favor these units for dimensional cutting tasks.
- Hydraulic:PTO-driven or standalone hydraulic power units attach to heavy machinery for extreme-duty felling and underwater cutting applications. Specialized arborist contractors in flood-prone US Gulf Coast regions deploy these for storm debris clearance.
Today's leader: Gas-Powered. Tomorrow's challenger: Battery-Operated.
End User:
Cost tier differentiation separates capital-intensive professional fleets from price-sensitive residential purchases, with service bundling emerging as a margin defense mechanism.
- Forestry:Industrial-scale timber harvesting operations demand equipment with 36-inch bar capacity and automated chain lubrication systems. Replacement part consumption and dealer service contracts generate recurring revenue streams for manufacturers with dense technician networks.
- Landscaping:Municipal maintenance contractors and private groundskeeping services prioritize noise compliance and emissions reduction for urban contract eligibility. Battery platform standardization across handheld equipment categories reduces fleet training costs.
- Construction:Rough carpentry and demolition crews utilize compact chainsaws for timber framing and concrete formwork breakdown. OSHA PPE mandates influence procurement specifications for this segment.
- Firefighting:Wildland fire suppression agencies require lightweight, high-reliability units with rapid-start capability and spark-arrestor certification. US Forest Service and Cal Fire specifications drive product development priorities.
Forestry commands the steepest equipment specifications. Landscaping offers the fastest volume expansion trajectory.
Application:
Volume concentration in tree felling applications sustains aftermarket parts revenue, while emerging use cases in precision milling create technology differentiation opportunities.
- Tree Felling:Complete severing of standing timber demands maximum power-to-weight ratios and kickback mitigation engineering. Professional arborist certification requirements slow workforce scaling and equipment turnover cycles.
- Trimming:Limb removal and canopy maintenance favor lightweight, maneuverable systems with top-handle configurations. Compact cordless designs gain share in German suburban residential markets with smaller lot dimensions.
- Milling:Conversion of logs into dimensional lumber using Alaskan mill attachments requires precise chain sharpening and consistent power delivery. Specialty woodworking enthusiasts drive niche demand for electric and battery systems.
- Chopping:Firewood processing for residential heating combines repetitive cutting cycles with moderate torque requirements. Seasonal demand patterns in Northeastern US and Scandinavian markets create inventory planning challenges.
Tree felling anchors installed base economics. Trimming applications are climbing the fastest.
Sales Channel:
Customer type stratification between institutional procurement and individual purchase determines channel investment priorities and margin structure.
- Distributors:Authorized dealer networks provide technical training, warranty service, and replacement part availability for professional contractors. Stihl and Husqvarna have anchored competitive position through multi-decade network density investments.
- Home Improvement Stores:Mass retail placement captures residential homeowner demand for seasonal trimming and light bucking tasks. Private label battery platforms compete on price at the expense of cross-tool compatibility.
- Direct Sales:Manufacturer-owned channels serve municipal fleet procurement and large commercial landscaping contracts with customized service agreements. Online configuration tools and volume pricing portals reduce transaction friction.
- Online Retail:E-commerce platforms aggregate comparison shopping for replacement chains, bars, and maintenance accessories. Amazon and specialized outdoor power equipment sites compete on delivery speed and review transparency.
Distributors defend professional loyalty. Online Retail is gaining share fastest in accessory categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal landscaping contractors anchor the fastest regional transition toward battery-operated equipment procurement. EPA emission enforcement and METI-backed green procurement guidelines in Japan are compressing gasoline-powered sales channels. Urban noise ordinances across Stuttgart, Tokyo, and Portland metropolitan zones now disqualify two-stroke equipment from public contracts.
United States
Residential tree care services drive equipment turnover across suburban markets from Seattle to Atlanta. OSHA mandates personal protective equipment protocols that influence contractor bundling decisions. Pacific Northwest metropolitan zones exhibit the fastest contract penetration for subscription-based equipment access models.
Germany
Stuttgart and Munich municipal contractors prioritize noise-compliant battery platforms for urban maintenance eligibility. EU Green Deal carbon accounting requirements tighten lubricant disclosure obligations for CE marking access. Bavarian landscaping fleets now standardize cordless architectures across handheld equipment categories.
Japan
Tokyo and Osaka metropolitan procurement channels favor low-noise, zero-emission equipment under METI guidelines. Compact lot dimensions in dense suburbs drive demand for lightweight battery systems. Kansai region contractors phase in cordless platforms alongside legacy gasoline inventory.
China
Domestic manufacturers supply cost-optimized battery platforms for export-oriented production. MIIT efficiency standards shape motor controller specifications for brushless designs. Yangtze River Delta industrial clusters concentrate lithium-ion cell procurement and assembly operations.
Sweden
Nordic timber harvesting sustains demand for high-torque gasoline units in extended felling cycles. REACH chemical restrictions constrain chain oil formulations for professional forestry equipment. Stockholm-based contractors balance emission compliance with runtime demands in remote harvesting zones.
Chainsaw Market Key Industry Players
Platform standardization dominates the current landscape as manufacturers converge battery architectures across handheld equipment categories. The vendor base separates into three tiers: established European manufacturers with dense dealer networks, Japanese precision-tool specialists, and Chinese cost-optimized fabricators. Strategic archetypes include full-range platform providers, niche cordless innovators, and component suppliers. M&A activity concentrates on battery technology acquisitions, while geographic expansion targets municipal procurement channels in noise-restricted metropolitan zones.
Among European full-range providers, Husqvarna AB and Andreas Stihl AG & Co. KG exemplify the dealer-network-dependent archetype, anchoring professional arborist loyalty through multi-decade service infrastructure investments. Makita Corporation occupies a position bridging professional and residential segments with compact cordless designs. Zhejiang Zomax Garden Machinery Co. Ltd. represents the Chinese manufacturing tier focused on cost-optimized export production.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Stanley Black & Decker Inc. |
| Husqvarna AB |
| Zhejiang Zomax Garden Machinery Co. Ltd. |
| Oregon Tool Inc. |
| Andreas Stihl AG & Co. KG |
| Echo Incorporated |
| STIHL Inc. |
| Makita Corporation |
| Others |
Cost & Logistics Intelligence
Lithium carbonate price indices cascade through battery cell procurement tiers, compressing margins for cordless platform manufacturers while amplifying cost advantages for gasoline engine suppliers anchored in steel and aluminum commodity markets. This raw-material divergence stratifies end-equipment pricing across professional and residential buyer archetypes.
Pricing Analysis
Input-cost pass-through from battery chemistry volatility drives three-tier pricing structure across premium, standard, and economy levels in cordless equipment, with brand premium and after-sales service bundling separating Husqvarna and Stihl dealer-network offerings from mass-retail private labels. Price differentiation hinges on certification grade—EPA-compliant emission systems command sustained premiums in professional forestry—while cost compression in economy cordless tiers intensifies due to Chinese cell oversupply. Residential homeowners exhibit highest price sensitivity, whereas municipal contractors absorb premium pricing for noise-compliance eligibility.
Supply Chain Analysis
Freight cost escalation from Yangtze River Delta ports to European distribution hubs adds landed-cost pressure for battery pack assemblies, reshaping regional sourcing strategies. Manufacturing concentration in China, Japan, and Germany supplies lithium-ion cells, brushless motor controllers, and precision-machined guide bars respectively. Raw material dependencies span cobalt cathodes, rare-earth magnets, and high-grade alloy steel. Single-source vulnerability in semiconductor motor controllers threatens production continuity. Distribution runs through authorized dealer networks for professional tiers and mass retail for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Chainsaw Market functions as a stable compounder where replacement part consumption and municipal fleet refresh cycles generate predictable revenue streams regardless of macroeconomic volatility.
For Market Incumbents: Hedge battery platform exposure by maintaining parallel gasoline engine development for professional forestry segments where runtime demands resist electrification. Anchor dealer network density in Nordic timber regions to defend against direct-sales disintermediation. Deepen backward integration into brushless motor controller design to reduce semiconductor supply vulnerability. For New Entrants and Emerging Players: E-commerce replacement part channels offer the most penetrable entry vector, with Amazon and specialized outdoor power equipment sites exhibiting lowest incumbent lock-in. Target German suburban residential trimming applications where compact cordless designs face minimal brand loyalty. Pursue white-label manufacturing partnerships with Yangtze River Delta battery pack assemblers to bypass dealer network barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with battery chemistry specialists possessing thermal management IP applicable to professional-grade cordless torque delivery. The five-to-ten year viability window favors platform-agnostic component suppliers over pure-play equipment brands. Watch municipal procurement guideline revisions in Tokyo, Stuttgart, and Portland as inflection indicators for cordless adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Cross-tool compatibility reduces fleet training costs for landscaping contractors in noise-restricted German municipalities. |
| Dealer Network Expansion | Dense service infrastructure anchors professional arborist loyalty against direct-sales encroachment from mass retailers. |
| Backward Integration into Motor Controllers | In-house brushless design capability mitigates semiconductor supply vulnerability and accelerates thermal management iteration. |
| Subscription Service Bundling | Annual tree care contracts with equipment access displace transactional sales in Pacific Northwest metropolitan markets. |
| Regulatory Compliance Certification | EPA emission certification and OSHA PPE bundling sustain premium positioning in professional forestry procurement channels. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with equipment procurement managers at municipal landscaping departments, aftermarket service directors at dealer networks, and product development leads at battery platform manufacturers with secondary validation against customs trade records, SEC filings from listed outdoor power equipment suppliers, and EPA emission certification databases. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Segment-weighting approaches applied differential growth assumptions across power source categories, end-user verticals, and application types throughout the forecast period. CAGRs derived from regression analysis of historical shipment trajectories adjusted for regulatory inflection points. Forecast inputs incorporated lithium-ion energy density improvement curves and municipal noise ordinance adoption timelines.
Battery chemistry breakthroughs, abrupt tariff regime shifts, and accelerated OSHA training mandate rollouts are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions subject to material change in underlying drivers. A model refresh is warranted upon significant revision to METI green procurement guidelines or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gear Cutting Machines Market
Tools
Portable Pressure Washer Market
Tools
Global Flange Fasteners Market
Tools
Screw Fastener Market
Tools
Nut Runner Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Global Staple Gun Market
Tools
Multi-Tasking Machine Tools Market
Tools
Woodpecker Tools Market
Tools
Fixed Cutter Bits Market
Tools
Industrial Ladder Market
Tools
Global Protractor Market
Tools
Tension Tester Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Extensometer Market
Tools
Construction Nails Market