
 Masonry Cleaners Market | 2026-2036
Masonry Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Masonry Cleaners Market Analytics
Maintenance service contracts is decoupling product sales from pure transactional revenue in the masonry cleaners sector. PROSOCO leverages its specification-grade formulations to anchor institutional restoration accounts across North America. Diedrich Technologie specializes in custom-blended acidic systems that dominate historic masonry conservation workflows. EaCo Chem competes through contractor-direct distribution that controls job-site replenishment cycles.
Masonry cleaners comprise formulated chemical solutions—typically hydrochloric, phosphoric, or buffered organic acid blends at concentrations between five and twenty percent active ingredient—designed to dissolve mineral deposits, atmospheric soiling, and construction residues from brick, stone, concrete, and terracotta substrates without substrate degradation. Alkaline cleaners lead volume in new construction degreasing where mortar haze removal drives repeat purchase frequency. Biodegradable cleaners represent the fastest-expanding product class as environmental specifications tighten across public infrastructure tenders. Historic restoration applications command premium pricing due to substrate sensitivity and conservator oversight requirements that limit chemical aggressiveness.
EPA registration requirements under FIFRA govern antimicrobial claims in masonry cleaning formulations sold in the United States, while REACH restrictions on methylene chloride and NMP content reshape solvent-based cleaner viability across European manufacturing. OSHA hazard communication standards mandate GHS-aligned labeling that increases formulation transparency for contractor end users. Stakeholders must monitor evolving state-level VOC thresholds and green procurement mandates that will determine which chemistry platforms retain commercial access.
Market Dynamics
Historic restoration mandates across Italy and France are concentrating procurement toward pH-neutral formulations, while REACH compliance in Europe and contractor certification requirements in Germany reshape supplier qualification criteria.
Growth Catalysts
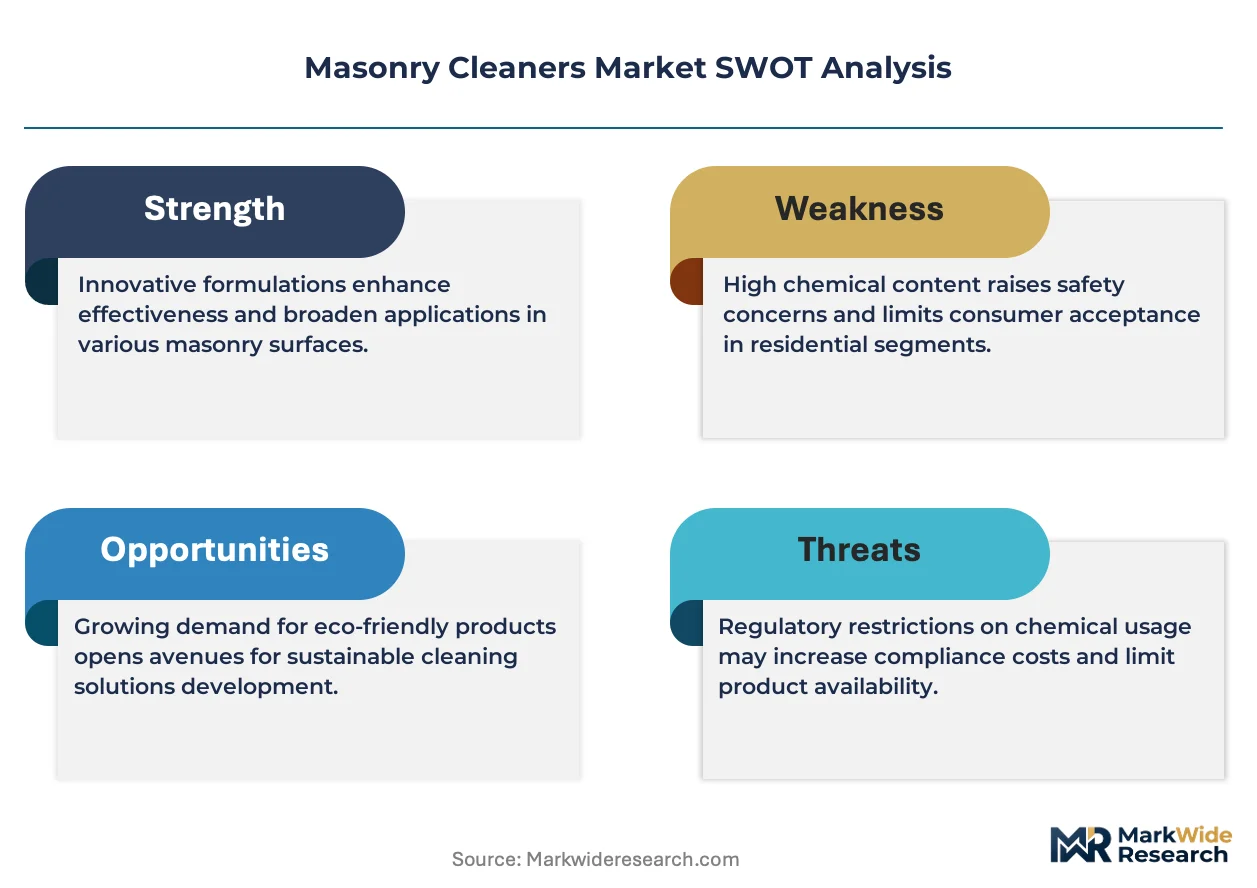
- REACH Phase-Out Schedules:ECHA restrictions on methylene chloride and NMP content are redirecting solvent-based cleaner demand toward certified biodegradable alternatives in European public infrastructure tenders.
- Historic Masonry Conservation:Substrate-sensitive restoration projects in Rome and Paris require conservator-approved formulations that command premium pricing and anchor long-term service contracts.
- Buffered Organic Acid Blends:New construction degreasing workflows favor alkaline cleaners with controlled etching profiles that reduce substrate damage callbacks.
Market Restraints
- Raw Material Concentration:Phosphoric acid supply chains cluster around Chinese and Moroccan phosphate rock processing, exposing formulators to export quota volatility.
- Technical Performance Ceiling:pH-neutral cleaners cannot dissolve heavy carbonate encrustation without extended dwell times that conflict with contractor labor economics.
- FIFRA Registration Friction:EPA antimicrobial claim requirements add 18-24 month approval timelines that block rapid formulation pivots for US market entrants.
Strategic Opportunities
- Maintenance Service Contracts:Institutional restoration accounts in North America are unbundling product sales from labor, creating recurring revenue streams that reduce price sensitivity.
- Green Procurement Mandates:Federal and state-level VOC thresholds in the US are disqualifying legacy solvent platforms from public building maintenance tenders.
- Specification-Grade Positioning:Architect and engineer pre-approval workflows allow qualified suppliers to lock out competitors before bidding begins.
Industry Challenges
- Conservator Certification Bottlenecks:Historic restoration projects require conservator oversight that limits batch sizes and extends quality assurance cycles.
- GHS Labeling Compliance Costs:OSHA hazard communication standards mandate reformulation transparency that exposes proprietary blend compositions to reverse engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Masonry Cleaners Market |
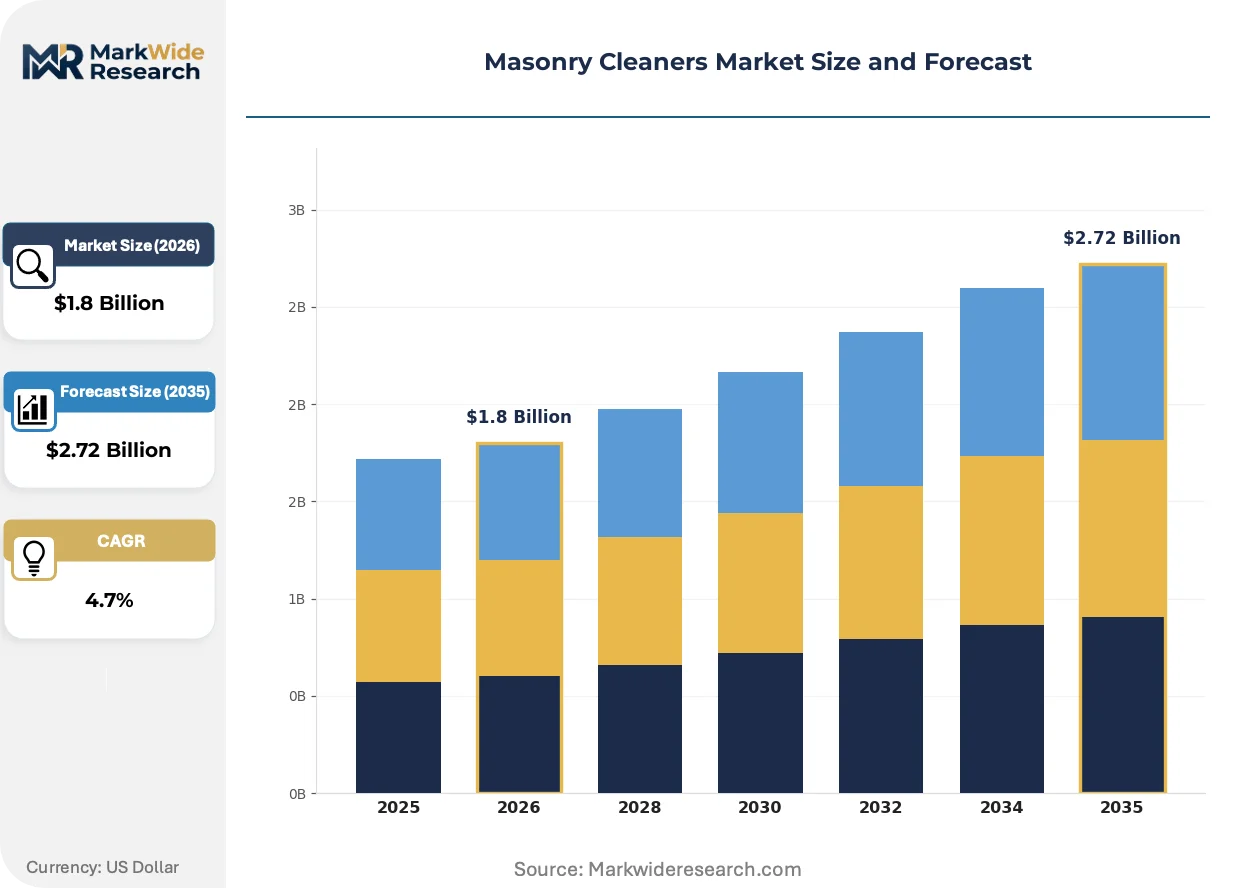
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidic Cleaners, Alkaline Cleaners, Solvent-Based Cleaners, Biodegradable Cleaners Application: Commercial Buildings, Residential Properties, Infrastructure Projects, Historic Restoration End User: Contractors, DIY Enthusiasts, Property Managers, Cleaning Services Distribution Channel: Online Retail, Wholesale Suppliers, Home Improvement Stores, Specialty Shops |
| Companies Covered | PROSOCO, Diedrich Technologie, Miteq, Shore Corporation, Franmar, CarrollCLEAN, EaCo Chem, SGM, Dumond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Masonry Cleaners Market Evolving Landscape
Formulation chemistry is pivoting toward substrate-specific precision as environmental specifications tighten and restoration expertise concentrates in specialized contractor networks.
Enzymatic pre-soak technologies are absorbing mineral deposit dissolution workloads previously handled by aggressive acid etching. Heritage conservation contractors in Florence and Charleston are adopting these systems for terracotta and limestone substrates where pH control is paramount. The shift is absorbing market share from hydrochloric acid blends in sensitive restoration verticals while extending project timelines.
REACH restrictions on methylene chloride and NMP are compressing solvent-based cleaner viability across European manufacturing. ECHA substance evaluation timelines are forcing reformulation investments that favor larger suppliers with dedicated regulatory affairs capacity. German contractor associations are consolidating procurement around pre-certified biodegradable alternatives to avoid job-site compliance liability.
Specification-driven purchasing is displacing open-market spot buying in institutional restoration. Architects and preservation consultants in Boston and Philadelphia are embedding approved product lists into contract documents that exclude non-qualified suppliers. This behavior concentrates volume among specification-grade formulators and fragments price competition in heritage conservation workflows.
Masonry Cleaners Market Segmentation
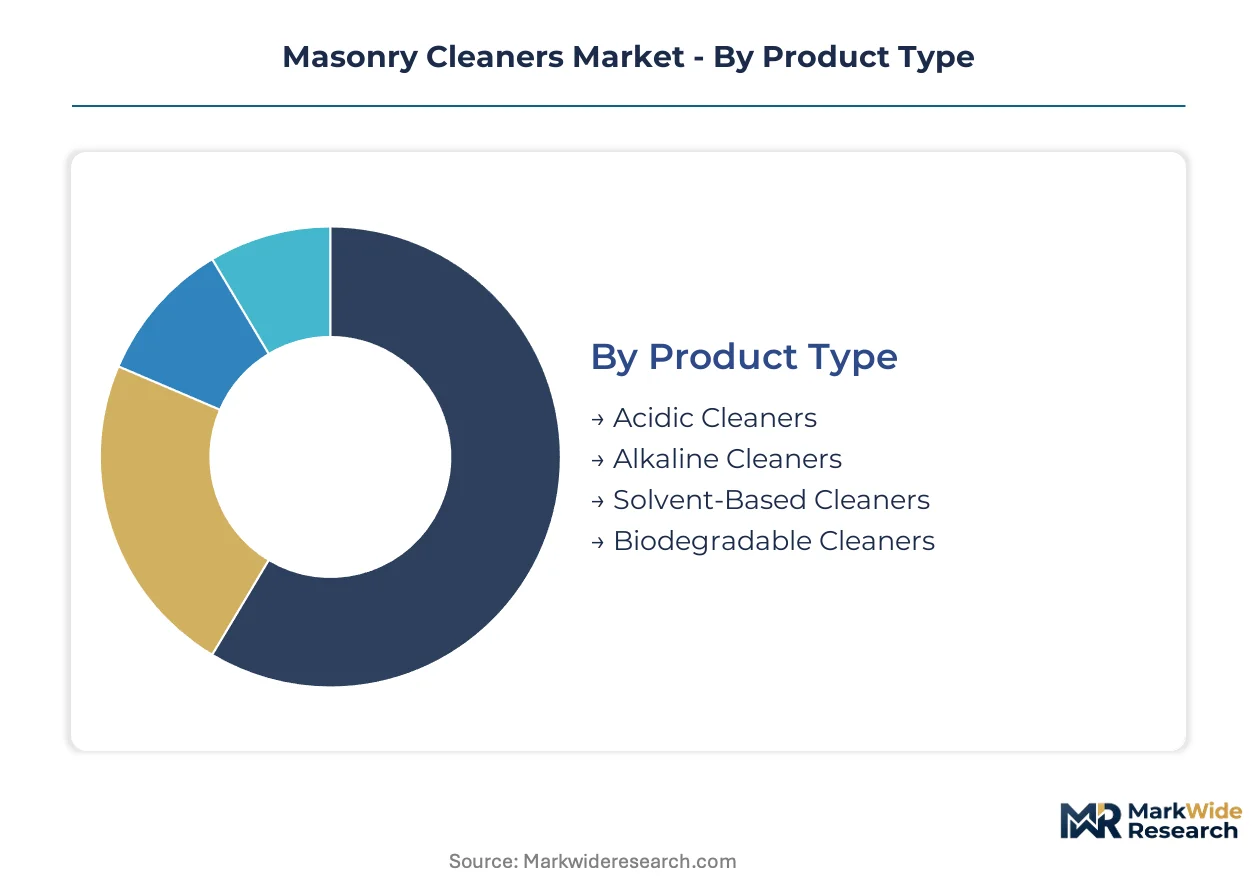
Chemical specification varies sharply across masonry cleaner segments, with substrate sensitivity and environmental compliance driving divergent formulation strategies. Procurement patterns fragment between specification-grade institutional buyers and price-sensitive spot purchasers.
Product Type:
Customization intensity spans from commodity alkaline blends to conservator-certified pH-neutral systems, with regulatory pressure compressing mid-range solvent platforms.
- Acidic Cleaners:Hydrochloric and phosphoric acid formulations at 5-20% concentration dissolve carbonate encrustation and construction residues through controlled etching. Demand concentrates in new construction degreasing across Germany and Poland where mortar haze removal drives repeat purchase cycles.
- Alkaline Cleaners:Buffered organic acid blends with controlled pH profiles reduce substrate damage callbacks on sensitive brick and terracotta. Italian and French historic restoration contractors specify these for terracotta facades in Rome and limestone monuments in Paris where conservator oversight mandates chemical restraint.
- Solvent-Based Cleaners:Methylene chloride and NMP-dependent formulations face ECHA phase-out schedules that disqualify them from European public infrastructure tenders.
- Biodegradable Cleaners:Plant-derived surfactant systems with enzymatic pre-soak capabilities absorb mineral dissolution workloads previously handled by aggressive acids.
Most installed capacity flows through alkaline cleaners. Expansion is steepest in biodegradable cleaners.
Application:
Project scale determines specification rigor, with heritage conservation commanding premium chemistry and extended quality assurance cycles absent from volume construction.
- Commercial Buildings:Routine maintenance contracts on office and retail facades favor alkaline degreasers with rapid dwell times that compress labor economics. Procurement concentrates through facilities management consortia in Frankfurt and Milan that negotiate multi-year supply agreements.
- Historic Restoration:Substrate-sensitive conservation workflows in Florence and Charleston require conservator-approved formulations with batch-level documentation. Italian Ministry of Culture mandates and French ABF (Architectes des Bâtiments de France) approvals create qualification bottlenecks that limit supplier pools.
- Infrastructure Projects:Bridge and tunnel maintenance tenders increasingly specify biodegradable alternatives to satisfy green procurement mandates.
- Residential Properties:DIY and small-contractor spot purchases prioritize shelf-ready acidic cleaners for driveway and patio cleaning.
Volume concentrates in commercial buildings. Pricing power concentrates in historic restoration.
End User:
Technical sophistication divides the buyer base between certified contractors with specification influence and price-driven replenishment purchasers.
- Contractors:Masonry restoration specialists in Boston and Philadelphia maintain approved product lists that lock out non-qualified suppliers before bidding begins. German contractor associations consolidate procurement around pre-certified biodegradable alternatives to avoid job-site compliance liability.
- Property Managers:Institutional portfolios in Chicago and Toronto bundle cleaning chemicals into facilities contracts that unbundle product sales from labor.
- Cleaning Services:Janitorial contractors favor alkaline formulations with simplified application protocols for routine facade maintenance.
- DIY Enthusiasts:Home improvement retail purchasers select ready-to-use acidic cleaners based on shelf visibility and price point.
Contractors control specification-grade volume. Property managers are consolidating procurement fastest.
Distribution Channel:
Channel selection tracks buyer technical competence, with specification-grade sales requiring consultative support absent from transactional retail.
- Wholesale Suppliers:Distributor networks in Germany and the United States anchor contractor-direct relationships that control job-site replenishment cycles. Technical field support and bulk pricing lock in volume accounts.
- Specialty Shops:Heritage conservation suppliers in Rome and Paris stock conservator-approved formulations with batch documentation required for Ministry tenders. Limited shelf space concentrates on pH-neutral and enzymatic systems.
- Online Retail:E-commerce platforms absorb DIY and small-contractor spot purchases with limited technical consultation.
- Home Improvement Stores:Mass retail channels move commodity acidic and alkaline cleaners through high-visibility shelf placement.
Wholesale suppliers capture institutional volume. Specialty shops command margin concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specification-grade formulators anchor institutional restoration volume, while Italian conservator mandates concentrate pH-neutral procurement in Mediterranean heritage clusters.
United States
Federal green procurement mandates and historic tax credit programs drive specification-grade cleaner demand. EPA FIFRA registration requirements govern antimicrobial claims, extending approval timelines for new entrants. Boston and Philadelphia restoration specialists embed approved product lists into contract documents that exclude non-qualified suppliers.
Germany
Contractor certification requirements and REACH compliance reshape supplier qualification criteria across public infrastructure tenders. ECHA restrictions on methylene chloride and NMP redirect solvent-based demand toward biodegradable alternatives. Frankfurt facilities management consortia negotiate multi-year supply agreements that consolidate procurement.
Italy
Ministry of Culture mandates for historic masonry conservation concentrate procurement on conservator-approved formulations. REACH substance evaluation timelines force reformulation investments favoring larger suppliers with regulatory affairs capacity. Florence heritage contractors adopt enzymatic pre-soak systems for terracotta substrates.
France
ABF approval requirements create qualification bottlenecks that limit supplier pools for limestone monument restoration. ECHA phase-out schedules compress solvent-based cleaner viability across manufacturing. Paris conservation workflows command premium pricing due to substrate sensitivity and extended quality assurance cycles.
Canada
Health Canada PMRA registration requirements parallel EPA frameworks for antimicrobial formulations. Provincial green building standards accelerate biodegradable cleaner adoption in commercial facade maintenance. Toronto institutional portfolios bundle cleaning chemicals into facilities contracts that unbundle product from labor.
Masonry Cleaners Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade formulators anchoring institutional restoration accounts while commodity producers serve spot-purchase construction workflows. The vendor base concentrates around three strategic archetypes: heritage conservation specialists with conservator network access, contractor-direct distributors controlling job-site replenishment, and mass-market formulators leveraging retail shelf presence. Dominant competitive moves include specification-driven pre-approval workflows that lock out competitors before bidding, and maintenance service contract bundling that decouples product sales from transactional revenue.
Within the heritage conservation specialist tier, PROSOCO and Diedrich Technologie exemplify specification-grade positioning that anchors institutional restoration accounts across North America. EaCo Chem occupies a position within contractor-direct distribution, controlling job-site replenishment cycles through technical field support relationships. These three companies represent distinct competitive archetypes—specification anchoring, custom formulation expertise, and distribution channel control—rather than direct substitution competitors.
| Leading Market Players |
|---|
| PROSOCO |
| Diedrich Technologie |
| Miteq |
| Shore Corporation |
| Franmar |
| CarrollCLEAN |
| EaCo Chem |
| SGM |
| Dumond |
| Others |
Value Network & Pricing Analysis
Phosphoric acid spot prices on Moroccan and Chinese export markets cascade through masonry cleaner formulation tiers, compressing margins on commodity alkaline blends while insulating specification-grade pH-neutral products from cost pass-through volatility. REACH-driven reformulation investments in Europe and green procurement mandates in North America are stratifying procurement into certified-premium and price-sensitive spot-purchase tiers with divergent supply chain footprints.
Pricing Analysis
Capacity additions in China's phosphate processing sector are reshaping price floors for acidic cleaner feedstocks, forcing mid-tier formulators toward volume-based contract structures to defend margins. Three-tier pricing structure across specification-grade, contractor-certified, and retail-commodity levels separates heritage conservation workflows from new construction degreasing and DIY spot purchases. Cost compression in commodity alkaline blends is intensifying because Moroccan export quota volatility feeds raw material uncertainty. Small-contractor replenishment purchasers exhibit highest price sensitivity, while institutional restoration accounts with embedded specification requirements show lowest elasticity.
Supply Chain Analysis
Wholesale distributor networks handling contractor-direct replenishment anchor institutional demand across Germany and the United States, while specialty conservation suppliers in Italy and France manage low-volume, high-documentation heritage workflows. Phosphoric acid supply chains draw from Chinese and Moroccan phosphate rock processing, with enzymatic pre-soak components increasingly sourced from European biotechnology suppliers. Single-source vulnerability concentrates around Chinese phosphoric acid export quotas, which expose formulators to input cost spikes. Distribution runs through technical field support relationships that lock in volume accounts via bulk pricing and job-site service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The masonry cleaners market functions as a regulatory compounder where ECHA methylene chloride phase-outs and EPA FIFRA registration requirements continuously reshape supplier qualification thresholds and procurement access.
For Market Incumbents: Anticipate enzymatic pre-soak technologies absorbing mineral dissolution workloads from traditional acid blends by accelerating conservator network partnerships that anchor specification-grade positioning. Defensive consolidation around REACH-compliant formulation platforms in Europe and green procurement pre-certification in North America will neutralize emerging biodegradable specialists. Capacity additions in German contractor-direct distribution channels represent the priority lever for locking out replenishment competitors.
For New Entrants and Emerging Players: Small-contractor spot purchasers in residential property maintenance represent the most penetrable buyer archetype currently underserved by specification-grade incumbents. White-space concentration in Canadian provincial green building standard compliance and US state-level VOC threshold alignment offers regulatory-aligned entry paths. A digital-first distribution model with simplified application protocols and rapid dwell-time guarantees can displace legacy alkaline cleaners in price-sensitive construction degreasing segments.
For Investors and Strategic Acquirers: Asymmetric upside sits with heritage conservation specialists possessing conservator network access and batch-documentation capabilities that create procurement bottlenecks for institutional restoration accounts. Long-term viability over a multi-year horizon favors formulators with dedicated regulatory affairs capacity to navigate evolving ECHA substance evaluations and EPA registration timelines. The signal to watch is consolidation velocity among German contractor associations pre-certifying biodegradable alternatives, which will indicate tipping-point adoption timing.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Reformulation Investment | ECHA methylene chloride restrictions redirect solvent-based demand toward certified biodegradable alternatives in European public tenders. |
| Conservator Network Partnership | Italian Ministry of Culture and French ABF approval workflows lock specification-grade suppliers into heritage restoration accounts. |
| Contractor-Direct Distribution Expansion | German and US wholesale technical field support relationships control job-site replenishment cycles and volume lock-in. |
| Enzymatic Pre-Soak Technology Development | Florence and Charleston heritage contractors adopt substrate-sensitive systems that displace aggressive acid etching in terracotta conservation. |
| Maintenance Service Contract Bundling | North American institutional portfolios unbundle product sales from labor, creating recurring revenue streams that reduce price sensitivity. |
Research Methodology
Bottom-up contractor and property manager demand modeling reconciled against top-down formulation capacity and raw material trade tracking forms the analytical core of this study. Primary interviews with heritage conservation specialists, facilities management procurement leads, masonry restoration contractors, and chemical formulator R&D directors combined with secondary validation from ECHA substance evaluation databases, EPA FIFRA registration filings, and European construction chemicals trade data. Triangulation across supply-side manufacturing disclosures and demand-side tender documentation ensures segment-level precision.
Historical trendline analysis of alkaline, acidic, and biodegradable cleaner adoption patterns across commercial building, historic restoration, infrastructure, and residential application segments structured the projection framework. Segmentation dimensions modeled include chemical formulation type, substrate sensitivity tier, project scale category, and regional regulatory cluster throughout the forecast period. CAGRs derived from regression analysis of specification-grade versus commodity volume trajectories, with enzymatic technology penetration rates and REACH phase-out compliance timelines serving as key forecast inputs.
Underlying measurement precision varies by segment; specification-grade heritage restoration and contractor-certified biodegradable categories carry tighter precision than DIY retail spot purchases due to documentation requirements. Forecasts reflect assumptions around ECHA enforcement intensity, state-level VOC threshold adoption velocity, and conservator certification bottleneck persistence in Mediterranean markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mold Racks Market
Tools
Orbital Sanders Market
Tools
Leather Cutting Machine Market
Tools
Cutting Tools Market
Tools
Wood Floor Grinding Machine Market
Tools
Bottle Jack Market
Tools
Screwdriver Market
Tools
Power Tools Market
Tools
Telescopic Tool Boxes Market
Tools
Dumpy Level Market
Tools
Portable Heat Press Machine Market
Tools
Cold and Hot Tool Steel Market
Tools
Digital Laser Levels Market
Tools
Power Press Machines Market
Tools
Entrenching Tool Market
Tools
Handheld Blower Market