
 Woodworking Tools Market | 2026-2036
Woodworking Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Tools Market Analysis
ISO 19030 performance measurement standards for machinery calibration is reorganizing competitive entry in woodworking equipment, forcing smaller fabricators toward certified service networks. HOMAG Group leverages integrated software-to-machine platforms across European and Asian distribution. SCM Group anchors its position through specialized CNC routing systems for solid wood processing. Makita Corp. competes in the cordless segment with battery ecosystems that extend runtime for portable jobsite applications.
Woodworking tools encompass cutting, shaping, joining, and finishing instruments engineered with carbide-tipped edges, hardened steel alloys, and brushless motor architectures operating between 18V and 36V in cordless configurations, serving furniture fabrication, construction trim work, and architectural millwork production. Saws and drills dominate volume shipments due to universal application across rough carpentry and finished joinery. Battery-powered systems represent the fastest-expanding power source category as lithium-ion cell density improves and professional users abandon pneumatic tethering. Professional craftsmen and manufacturing end users concentrate margin pools through recurring blade replacement, software subscription, and maintenance contract attach rates.
Federal EPA emissions guidelines and OSHA workplace noise exposure limits shape product design thresholds for stationary and portable equipment sold in the United States. CE marking requirements under EU machinery directives govern safety interlocks and dust extraction integration for European market access. Stakeholders must monitor how dual carbon goals in China and evolving battery recycling mandates across multiple jurisdictions will alter motor technology roadmaps and supplier qualification criteria.
Market Dynamics
Battery-powered platforms are fragmenting procurement hierarchies in professional woodworking, as cordless system investments now precede brand loyalty decisions rather than follow them.
Growth Catalysts
- OSHA noise exposure limits:Workplace safety mandates in the United States accelerate brushless motor adoption in portable equipment, compressing permissible decibel thresholds and forcing equipment upgrades.
- Furniture manufacturing clusters:Export-oriented wood processing centers in Vietnam and Indonesia expand precision tooling procurement as containerized finished goods demand rises.
- Lithium-ion cell density improvements:Energy storage advances enable 36V cordless architectures to match corded pneumatic torque outputs in heavy joinery applications.
Market Restraints
- Carbide supply concentration:Tungsten carbide cutting edge production concentrates in Chinese smelting facilities, exposing tooling costs to raw material export quota volatility.
- CE marking compliance friction:EU machinery directive safety interlock and dust extraction integration requirements extend product development timelines for non-European fabricators.
- Used equipment substitution:Refurbished CNC routing systems from German and Italian secondary markets satisfy mid-tier furniture producers, compressing new equipment demand.
Strategic Opportunities
- Indian furniture export incentives:Production-linked incentive schemes for wood product manufacturing stimulate precision tooling demand in emerging industrial corridors.
- Battery ecosystem convergence:Cross-platform battery compatibility between power tools and outdoor equipment creates attach rate expansion for charging infrastructure providers.
- Direct-to-contractor digital channels:Bypassing traditional industrial distribution, manufacturers build recurring revenue through blade subscription and predictive maintenance software.
Industry Challenges
- CNC programming skill scarcity:Solid wood processing facilities struggle to recruit operators capable of parametric design-to-machine workflow integration.
- ISO 19030 calibration certification timelines:Performance measurement standard compliance for machinery calibration extends service network qualification periods, constraining smaller fabricator market entry.
- Legacy pneumatic infrastructure integration:Cordless platform migration requires capital reallocation from compressed air systems to battery charging infrastructure at job sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Tools Market |
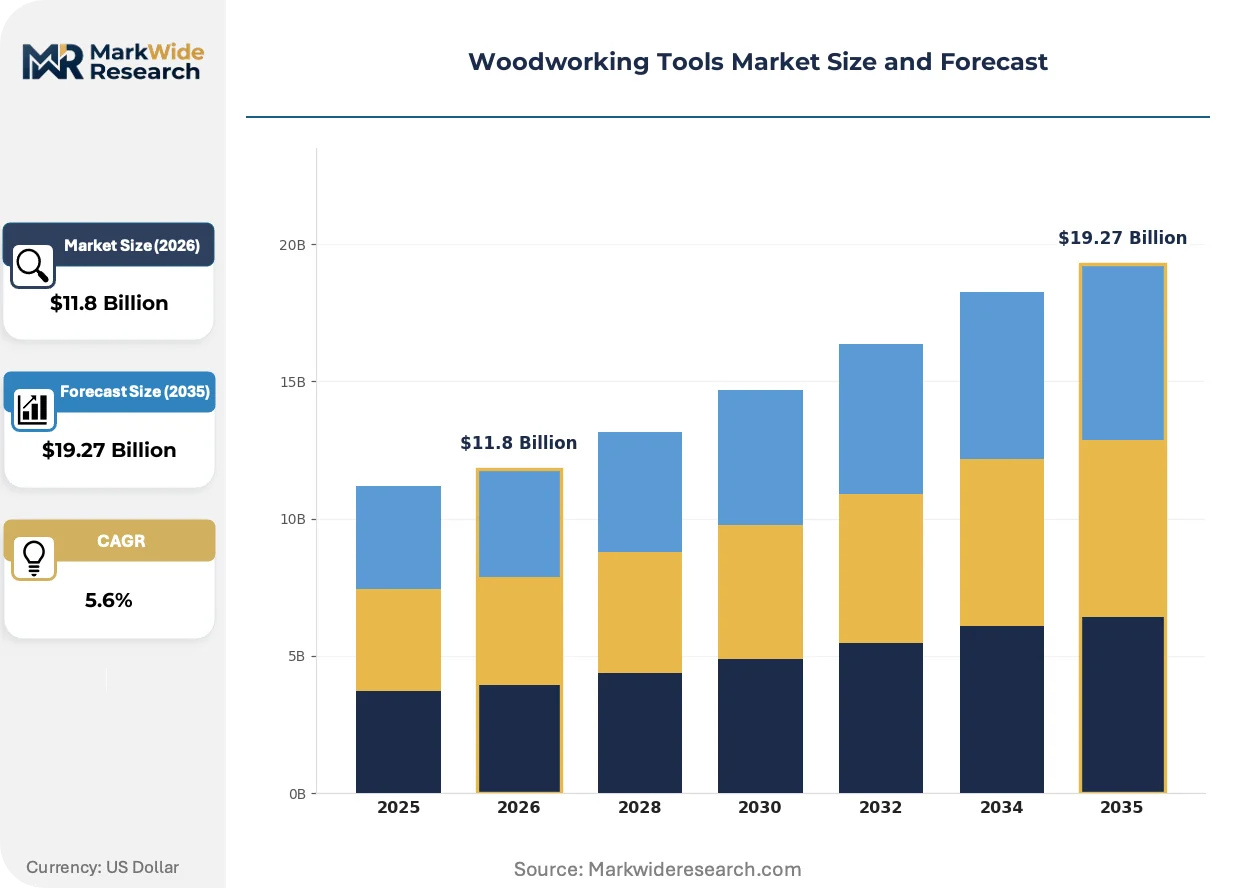
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Saws, Drills, Sanders, Chisels Power Source: Electric, Pneumatic, Manual, Battery End User: Professional Craftsmen, DIY Enthusiasts, Educational Institutions, Manufacturing Material: Wood, Metal, Composite, Plastic |
| Companies Covered | Felder Group, IMA Schelling Group, HOMAG Group, Timesavers, Michael Weinig AG, SCM Group, Holz-Her, Makita Corp., Biesse Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Tools Market Emerging Trajectories
Software-to-machine integration is compressing the traditional boundary between design environments and factory floor execution, enabling real-time toolpath optimization that responds to material variability.
Brushless motor architectures are fragmenting power source categories in professional woodworking equipment. Cabinet shops and architectural millwork contractors now specify cordless miter saws and track saws as primary equipment rather than backup alternatives. This technology is fragmenting the historical corded-pneumatic duopoly in finish carpentry, creating distinct battery ecosystem battlegrounds where runtime and cross-platform compatibility determine vendor selection.
REACH substance restrictions and evolving EU Green Deal industrial emissions frameworks are tightening chemical composition requirements for cutting fluids and surface finishes applied to tooling. Woodworking equipment manufacturers must reformulate lubricant specifications and document supply chain chemical footprints to maintain European market access. German and Italian equipment exporters face the steepest compliance adaptation curves as their domestic regulatory thresholds already exceed baseline EU requirements.
Contractor purchasing behavior is compressing equipment replacement cycles as battery platform obsolescence accelerates. Professional craftsmen now evaluate tool brands primarily through total ecosystem cost rather than individual unit pricing, factoring charger compatibility, battery interchangeability, and software subscription tiers into procurement decisions. This pattern concentrates margin capture in the United States and Germany, where high-velocity residential construction and custom furniture production demand maximum equipment uptime.
Woodworking Tools Market Segmentation
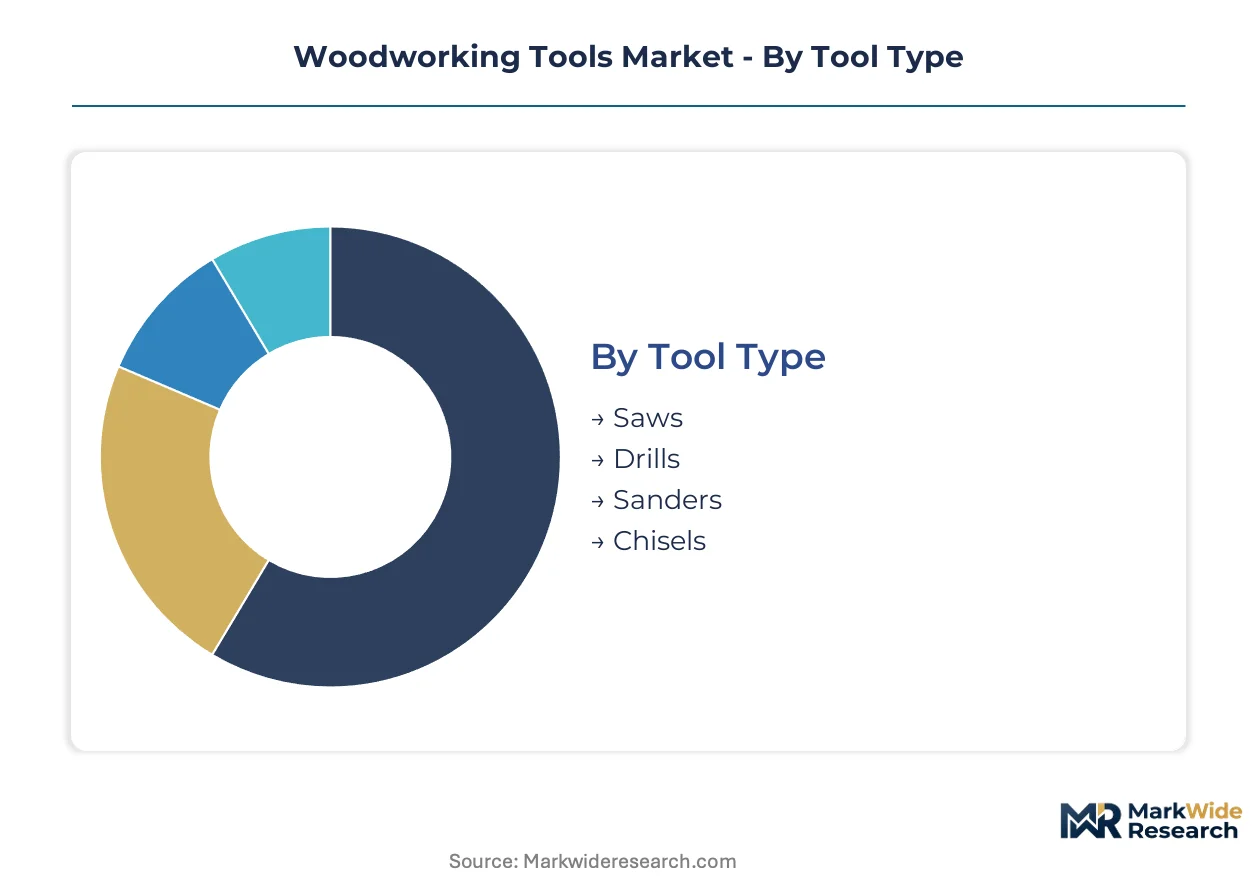
Woodworking tool procurement patterns diverge sharply across user sophistication levels and power source preferences. Battery platform investments now precede brand selection decisions, fragmenting historical loyalty structures. Material processing requirements further stratify demand between rough carpentry and precision millwork applications.
Tool Type:
Export-oriented furniture manufacturing clusters in Vietnam and Indonesia concentrate demand for precision cutting equipment, while domestic residential construction drives volume in rough carpentry tools across Germany, China, and the United States.
- Saws:Circular, miter, and track saw configurations with carbide-tipped blades dominate rough carpentry and finished joinery alike. Demand concentrates in German and Chinese manufacturing hubs where architectural millwork exports require precision cutting tolerance.
- Drills:Brushless motor architectures operating between 18V and 36V now match corded torque outputs in heavy timber applications. Professional craftsmen in the United States specify cordless drill platforms as primary equipment rather than pneumatic alternatives.
- Sanders:Orbital and belt configurations serve finishing operations in furniture fabrication.
- Chisels:Hand-forged and machine-ground edge tools persist in custom joinery and restoration work.
Saws command the established base. The steepest expansion runs through drills as cordless platform migration accelerates.
Power Source:
Cost tier stratification separates premium battery ecosystems from economy corded alternatives, with professional users absorbing charger infrastructure investments that DIY segments resist.
- Electric:Corded AC motor systems retain position in stationary equipment and budget-conscious procurement. Manufacturing end users in China continue specifying corded table saws and jointers where portability is secondary to continuous runtime.
- Battery:Lithium-ion cell density improvements enable 36V architectures to displace pneumatic tethering in finish carpentry. Professional contractors in Germany evaluate total ecosystem cost including battery interchangeability and software subscription tiers.
- Pneumatic:Compressed air systems persist in legacy cabinet shops with existing compressor infrastructure.
- Manual:Hand-powered tools serve educational institutions and restoration specialists requiring traditional technique preservation.
Electric retains the installed base. Battery platforms are climbing the fastest as lithium-ion energy density advances compress replacement cycles.
End User:
Application maturity separates recurring blade replacement revenue in professional settings from one-time procurement in educational and consumer segments.
- Professional Craftsmen:Trim carpenters and custom furniture builders generate recurring margin through blade subscription, predictive maintenance software, and certified calibration service contracts. OSHA noise exposure mandates in the United States accelerate their brushless motor upgrades.
- Manufacturing:Export-oriented wood processing facilities in Vietnam and Indonesia expand CNC routing and precision tooling procurement as containerized finished goods demand rises.
- DIY Enthusiasts:Home improvement segments concentrate in North American and European retail channels.
- Educational Institutions:Vocational training programs in Germany and China maintain manual tool inventories for technique instruction.
Professional craftsmen command the established base. Manufacturing demand is gaining share fastest as export-oriented furniture clusters expand.
Material:
Supply concentration in carbide cutting edge production exposes tooling costs to raw material export quota volatility from Chinese tungsten smelting facilities.
- Wood:Solid hardwood and softwood processing drives primary demand for carbide-tipped cutting edges and hardened steel alloys. German and Italian equipment exporters face REACH substance restriction compliance curves for cutting fluids used in European market access.
- Composite:Engineered wood products and fiber-reinforced materials require specialized dust extraction integration under EU machinery directive safety interlock requirements.
- Metal:Aluminum and steel trimming applications in architectural millwork.
- Plastic:PVC and acrylic edge banding in furniture manufacturing.
Wood commands the established base. Composite processing is expanding most quickly as engineered substrate adoption rises in export furniture production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German production-linked incentive schemes for precision manufacturing equipment are redirecting procurement flows across European distribution networks. China's dual carbon mandates are compressing motor technology roadmaps for export-oriented fabricators. Vietnam's furniture export corridors are expanding tooling demand as containerized finished goods volumes rise.
United States
Residential construction velocity in Texas and Florida is driving brushless motor upgrades among trim carpentry contractors. OSHA noise exposure limits are forcing equipment replacements that exceed baseline decibel thresholds. The Southeast industrial corridor around Atlanta concentrates architectural millwork production requiring precision cutting tolerance.
Germany
Export-oriented machinery fabricators in Baden-Württemberg are integrating CE marking compliance into product development timelines. REACH substance restrictions are tightening chemical composition requirements for cutting fluids used in European market access. The Stuttgart metropolitan area anchors CNC routing system production serving global furniture manufacturing clusters.
China
Tungsten carbide smelting concentration in Hunan and Jiangxi provinces is exposing tooling costs to raw material export quota volatility. MIIT efficiency standards are accelerating battery-powered platform adoption in professional settings. The Yangtze River Delta manufacturing belt around Shanghai concentrates precision wood processing equipment for domestic and export markets.
Vietnam
Furniture manufacturing incentives in Binh Duong and Dong Nai provinces are stimulating precision tooling procurement from European suppliers. The country's national industrial development framework is prioritizing wood product export capacity expansion. Ho Chi Minh City corridor facilities are integrating ISO 19030 calibration standards to qualify for German and Italian equipment service networks.
Indonesia
Containerized finished goods demand from Java-based furniture exporters is expanding CNC routing system installations. Central government manufacturing sector programs are redirecting investment toward precision wood processing capabilities. The Jepara industrial cluster in Central Java maintains specialized joinery production requiring carbide-tipped cutting edge supply security.
Woodworking Tools Market Vendor Landscape
Player mix skews toward integrated machinery-to-software platforms and specialized cutting system fabricators. Market structure concentrates margin capture in European and East Asian headquarters where certification networks and battery ecosystem investments create defensive moats. Strategic archetypes include full-line industrial equipment suppliers, cordless power tool specialists, and precision cutting edge manufacturers. Competitive moves center on battery platform interoperability agreements and predictive maintenance software subscription attach rates.
Within the integrated platform tier, HOMAG Group and SCM Group exemplify machinery-to-software convergence strategies. Makita Corp. occupies the cordless specialist archetype with battery ecosystem investments spanning portable jobsite applications. Michael Weinig AG represents precision cutting system fabrication anchored in German engineering standards. These three companies illustrate how geographic origin and corporate structure correlate with strategic positioning across professional and manufacturing end-user segments.
| Leading Market Players |
|---|
| Felder Group |
| IMA Schelling Group |
| HOMAG Group |
| Timesavers |
| Michael Weinig AG |
| SCM Group |
| Holz-Her |
| Makita Corp. |
| Biesse Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for tungsten carbide cutting edges lock in supply access and price visibility for German and Italian equipment fabricators sourcing from Chinese smelting facilities. These arrangements buffer procurement teams against export quota volatility while compressing margin flexibility for smaller tooling manufacturers without volume leverage.
Pricing Analysis
Certification level (ISO 19030/CE marking-grade) creates the primary spread between premium machinery and standard equipment tiers. Three-tier pricing structure across premium, standard, and economy levels reflects compliance investment differentials, with CE-marked systems commanding substantial premiums in European distribution. Cost compression in economy cordless platforms is intensifying because lithium-ion cell density improvements accelerate obsolescence cycles. DIY enthusiasts exhibit highest price sensitivity, while professional craftsmen absorb ecosystem investments through recurring service contracts.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes are extending lead times for precision cutting equipment destined to Vietnamese furniture manufacturing clusters. Tungsten carbide production concentrates in Chinese Hunan and Jiangxi provinces, while battery cell manufacturing clusters in South Korea and Japan feed cordless platform assembly. Supply chain risk centers on single-source vulnerability for carbide cutting edges subject to Chinese export quota restrictions. Distribution runs through certified service networks for professional-grade equipment and retail channels for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a switching-cost fortress where battery ecosystem investments and ISO 19030 calibration certification create substantial customer captivity. Regulatory entrenchment through CE marking and OSHA compliance further deepens incumbent advantages.
For Market Incumbents: Compound defensive positioning by deepening backward integration into carbide cutting edge production and expanding certified service network density in Vietnamese and Indonesian manufacturing corridors. Battery platform obsolescence acceleration threatens margin stability; counter through predictive maintenance software subscription attach rates that extend customer lifetime value.
For New Entrants and Emerging Players: Anchor in white-space opportunities around cross-platform battery compatibility and direct-to-contractor digital channels bypassing traditional industrial distribution. Indian furniture export incentive zones offer the most penetrable geography, with production-linked incentive schemes stimulating precision tooling demand in emerging industrial corridors. Lead with blade subscription models that capture recurring revenue before equipment procurement decisions solidify.
For Investors and Strategic Acquirers: Precision cutting system specialists with captive carbide supply and established CE marking compliance infrastructure represent the most attractive acquisition archetype. Long-term viability hinges on software-to-machine integration capabilities and battery ecosystem interoperability positions. Monitor lithium-ion raw material export policy shifts from Chinese regulatory authorities as the critical inflection indicator for tooling cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Ecosystem Interoperability Agreement | Cross-platform compatibility between power tools and outdoor equipment expands charging infrastructure attach rates for providers. |
| ISO 19030 Calibration Certification Investment | Performance measurement standard compliance qualifies fabricators for German and Italian equipment service networks. |
| Backward Integration into Carbide Production | Captive tungsten carbide supply insulates cutting edge costs from Chinese export quota volatility. |
| Direct-to-Contractor Digital Channel Launch | Bypassing traditional industrial distribution captures recurring blade subscription and predictive maintenance software revenue. |
| Software-to-Machine Platform Integration | Real-time toolpath optimization responding to material variability compresses design-to-execution boundaries for furniture manufacturers. |
Methodological Framework
A spread of perspectives from plant engineers at furniture manufacturing facilities, procurement leads at export-oriented wood processing clusters, aftermarket service heads at equipment distributors, and technical R&D directors at motor technology suppliers converged on the working assumptions underlying this analysis. Primary interview insights triangulated against customs and trade data, SEC filings from listed equipment manufacturers, MIIT efficiency standard disclosures, and OECD industrial policy documentation. Bottom-up demand modeling from end-user segments combined with top-down supply capacity assessments across Chinese, German, and Italian production hubs.
Segmentation dimensions modeled span tool type, power source architecture, end-user sophistication tier, material processing requirement, and regional regulatory cluster across the analysis window. CAGRs derived from historical shipment trajectories adjusted for technology substitution patterns and policy incentive impacts. Industry-specific forecast inputs incorporate lithium-ion energy density improvement curves and OSHA noise exposure limit compliance timelines.
Decision-makers should treat outputs as directional under assumptions of continued lithium-ion cost reduction and stable Chinese tungsten carbide export policy; material deviation would warrant model refresh. Specific risks include abrupt REACH substance restriction expansion, battery recycling mandate acceleration, and trade lane disruption affecting precision equipment delivery to Southeast Asian manufacturing corridors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Allen Key Market
Tools
Fixed Cutter Bits Market
Tools
Global Diamond Tools Market
Tools
Shape Moulding Machines Market
Tools
Woodworking Sanders Market
Tools
Edge Banders Market
Tools
Fiber Laser Cutting Machines Market
Tools
Sanding Machine Market
Tools
Woodpecker Tools Market
Tools
End Milling Machine Market
Tools
Step Ladder Market
Tools
Overload Protection Tools Market
Tools
Screwdriver Market
Tools
Aluminum Folding Ladders Market
Tools
Global Sandblasting Media Market
Tools
Caulking Gun Market