
 Cordless Impact Wrench Market | 2026-2036
Cordless Impact Wrench Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Impact Wrench Market Analytics
Lithium-ion phosphate cell chemistry is rebalancing cordless impact wrench economics by trimming pack costs while preserving thermal stability. Milwaukee Tool leverages vertical integration into battery platforms to sustain margin control across professional channels. Makita anchors its position through manufacturing scale in Japan and Southeast Asia. DEWALT competes via dense service networks that reduce contractor downtime.
A cordless impact wrench delivers rotational torque through a hammering anvil mechanism powered by rechargeable battery packs, typically operating at 18V to 40V with brushless motor architectures that achieve torque outputs from 150 Nm to over 2,000 Nm for industrial fastening and loosening operations. Battery-powered product types now dominate volume as brushless motor adoption displaces brushed alternatives in medium-torque categories where runtime and thermal efficiency determine contractor preference. High-torque applications in heavy assembly retain premium pricing power, while DIY end-user segments absorb entry-level units through retail channels with compressed margins.
OSHA workplace safety directives in the United States and CE machinery directives in Europe mandate ergonomic thresholds and noise limits that push manufacturers toward vibration-dampening designs. China's GB standards for lithium battery transportation and storage add compliance layers for exporters serving assembly plants in Shenzhen and Shanghai. Stakeholders must monitor cell supply concentration and regulatory divergence between North American and European certification paths.
Market Dynamics
Brushless motor architectures are compressing thermal losses and extending duty cycles, forcing incumbent manufacturers to redesign powertrain assemblies around permanent magnet rotor configurations while lithium-ion cell supply concentrates in East Asian chemical processing hubs.
Growth Catalysts
- OSHA ergonomic mandates:Vibration exposure limits in US manufacturing facilities accelerate replacement of pneumatic tools with battery-powered alternatives that incorporate anti-vibration handles and isolation mounts.
- Automotive lightweighting:Assembly plants in Stuttgart, Wolfsburg, and Detroit deploy high-torque cordless units for aluminum chassis fastening where torque precision prevents galvanic corrosion at joint interfaces.
- Lithium iron phosphate chemistry:Cell thermal stability above 60°C enables continuous high-load operation in foundries and forging operations previously restricted to corded equipment.
Market Restraints
- Neodymium supply concentration:Rare earth magnet processing in Jiangxi and Inner Mongolia creates vulnerability to export quota fluctuations affecting brushless motor cost structures.
- CE machinery directive friction:Noise emission certification timelines extend 8-14 months for new product introductions, delaying revenue recognition across European distribution channels.
- Pneumatic tool residual base:Installed compressed air infrastructure in legacy plants sustains lower total-cost-of-ownership calculations for air-powered fastening in cost-sensitive maintenance operations.
Strategic Opportunities
- Wind turbine maintenance:Offshore nacelle servicing at height restricts pneumatic hose deployment, creating specification pull for 40V platforms with 1,000+ Nm breakaway torque in North Sea installations.
- Rental channel expansion:Equipment rental networks in Texas and Alberta stock battery platforms for seasonal oilfield turnaround contracts, converting capital expenditure to operating lease models.
- EU battery passport requirements:Cell traceability mandates under the EU Green Deal favor manufacturers with captive recycling partnerships, creating compliance-based differentiation.
Industry Challenges
- Firmware integration complexity:Tool-battery communication protocols require recertification when cell suppliers change BMS architectures, extending engineering validation cycles.
- Service technician scarcity:Brushless motor diagnostics and Hall sensor calibration demand electromechanical skill sets that vocational programs in industrial Midwest states have not scaled to match replacement demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cordless Impact Wrench Market |
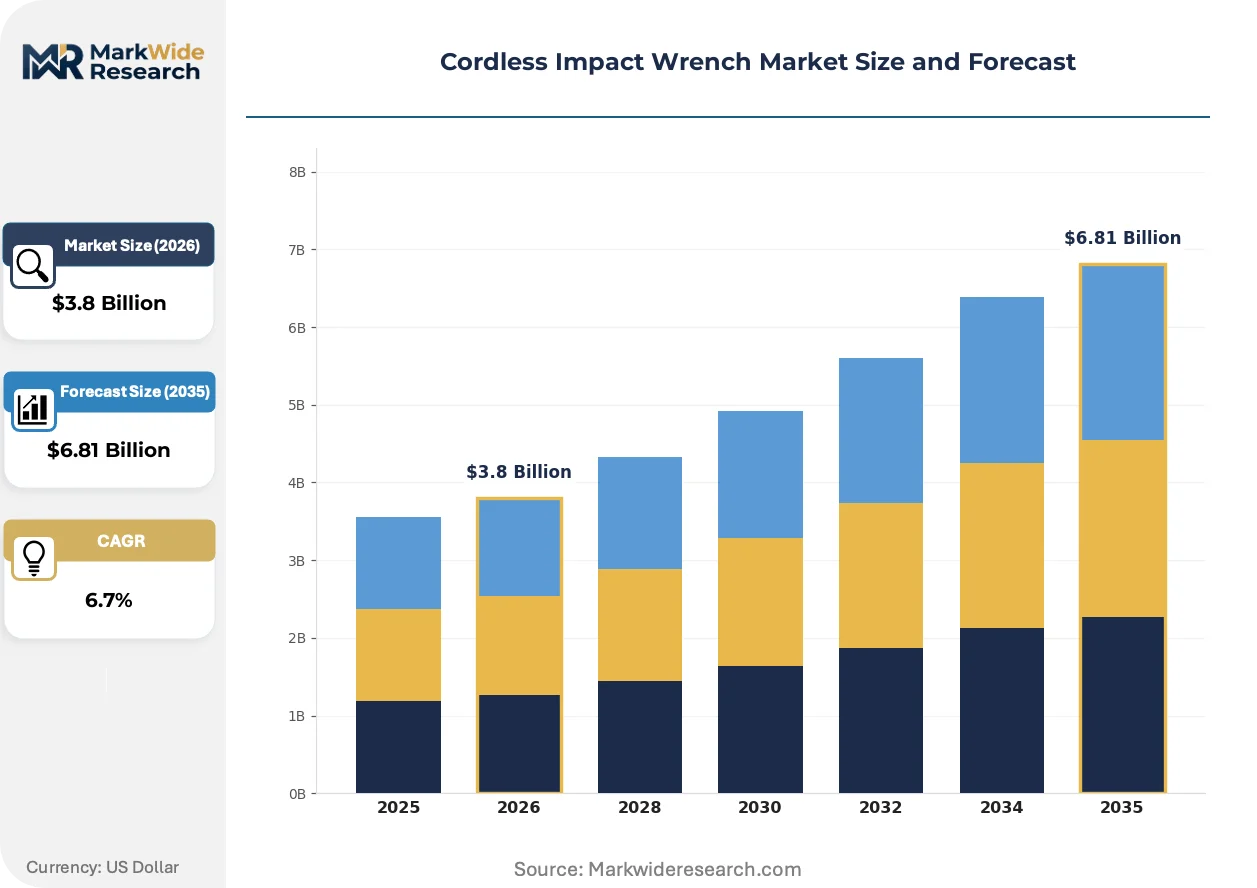
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless, Corded, Pneumatic, Battery-Powered End User: Automotive, Construction, Manufacturing, DIY Application: Tightening, Fastening, Assembly, Disassembly Power Rating: Low Torque, Medium Torque, High Torque, Ultra High Torque |
| Companies Covered | Milwaukee Tool, DEWALT, Makita, Ingersoll Rand, Ryobi, Hilti Aktiengesellschaft, Festool GmbH, Atlas Copco AB, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Impact Wrench Market Evolving Landscape
Power-dense battery architectures are fragmenting application boundaries between cordless and historically corded tool categories, while regulatory pressure on workplace noise and particulate exposure accelerates specification turnover in heavy assembly environments.
Smart torque management systems incorporating Hall-effect sensors and microprocessor-controlled anvil engagement are decentralizing quality control from centralized assembly stations to individual fastening operations. Tier-one automotive suppliers in Lower Saxony and Michigan now specify tools with angle monitoring and data logging for critical structural joints. This capability compression eliminates secondary audit stations and reduces warranty exposure from improper torque sequences.
REACH restrictions on nickel-cadmium battery chemistries are mandating full platform transitions for equipment fleets in EU member states, with Denmark and the Netherlands enforcing earlier compliance deadlines than the 2026 union-wide cutoff. Manufacturers must maintain dual inventory positions during transition windows, compressing margin recovery on legacy nickel-metal hydride stock. The directive's battery waste handling provisions are reshaping reverse logistics requirements for rental and direct-sale channels.
Fleet standardization contracts are consolidating procurement authority from individual job sites to regional equipment managers at general contracting conglomerates, compressing vendor counts and extending contract durations. This concentration shifts negotiation leverage toward volume purchasers who demand cross-platform battery compatibility and unified service response times. The pattern is most pronounced in commercial construction verticals across Florida, Texas, and California where multi-year infrastructure commitments justify dedicated tool crib investments.
Cordless Impact Wrench Market Segmentation
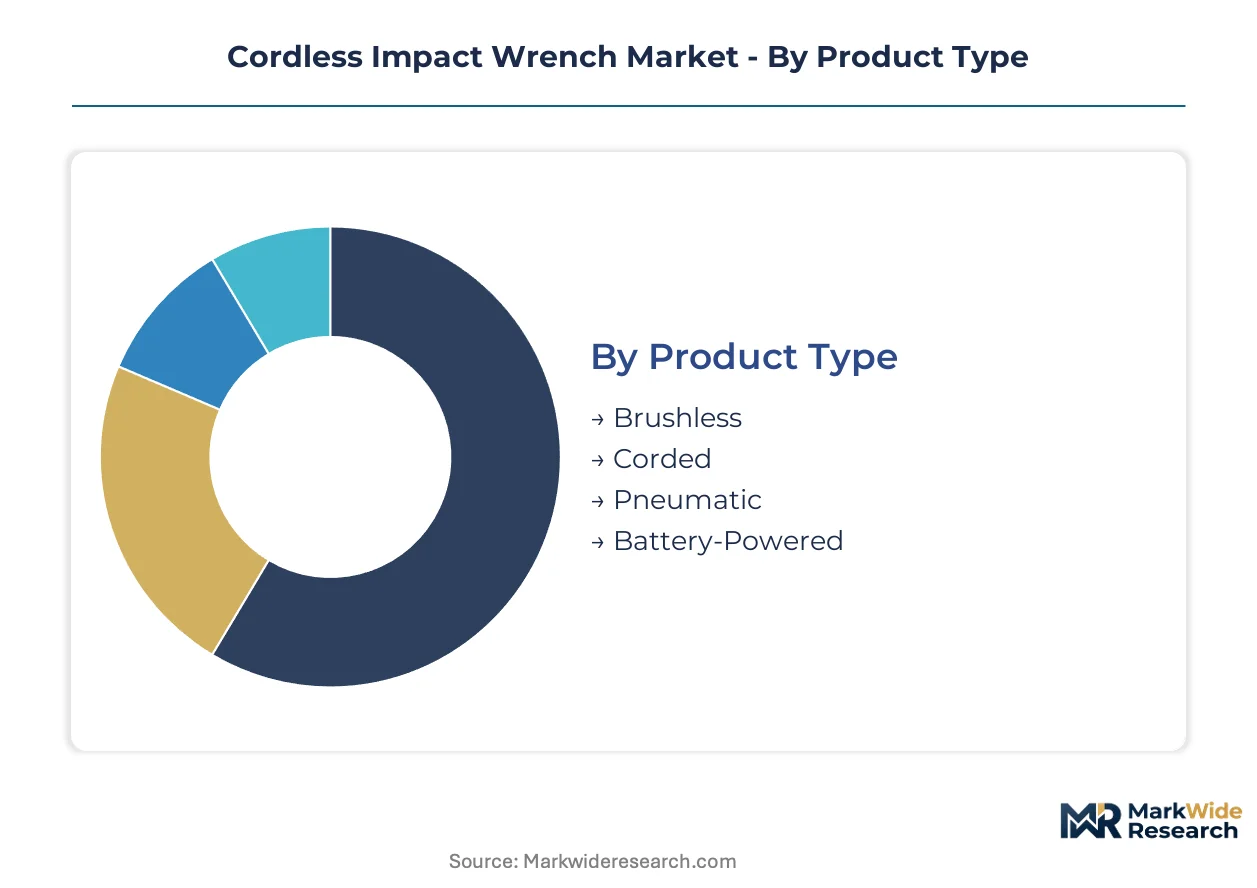
Cordless impact wrench procurement patterns diverge sharply between high-frequency industrial users and intermittent residential operators. Segmentation reveals where battery platform investments concentrate versus where pneumatic legacy equipment retains cost advantages.
Product Type:
Volume distribution tilts toward battery-powered architectures while premium pricing concentrates in brushless motor configurations that extend duty cycles.
- Battery-Powered:Lithium-ion cell packs operating at 18V to 40V dominate contractor preference where mobility eliminates pneumatic hose constraints. Automotive assembly plants in Stuttgart and Detroit specify these units for aluminum chassis fastening where torque precision prevents galvanic corrosion.
- Brushless:Permanent magnet rotor architectures with Hall-effect sensor control achieve thermal efficiencies above 85%, extending runtime in continuous fastening operations. Foundries in Pennsylvania and forging facilities in Ohio deploy these for high-load cycles where brushed motors would fail prematurely.
- Pneumatic:Compressed air systems sustain total-cost-of-ownship advantages in legacy plants with installed infrastructure.
- Corded:Tethered electric units retain niche positioning in fixed workstations with guaranteed power supply.
Mature deployment sits with pneumatic systems in heavy maintenance operations. Newer deployment is concentrated in battery-powered platforms with brushless motor architectures.
End User:
Cost tier stratification separates capital-intensive manufacturing from price-sensitive residential procurement.
- Automotive:Tier-one suppliers in Lower Saxony and Michigan specify smart torque management with angle monitoring and data logging for critical structural joints, eliminating secondary audit stations.
- Manufacturing:OSHA ergonomic mandates in US facilities accelerate replacement of pneumatic tools with anti-vibration battery alternatives.
- Construction:Fleet standardization contracts consolidate procurement authority to regional equipment managers in Florida, Texas, and California.
- DIY:Entry-level units absorb retail channel volume with compressed margins through big-box distribution.
Procurement concentration favors automotive and manufacturing verticals where specification compliance justifies premium positioning.
Application:
Functional differentiation tracks torque precision requirements versus breakaway power demands.
- Assembly:Microprocessor-controlled anvil engagement with torque logging meets automotive structural joint specifications.
- Fastening:Continuous high-load operations in foundries demand lithium iron phosphate cell chemistry for thermal stability above 60°C.
- Tightening:Precision torque delivery prevents fastener galling in stainless steel applications.
- Disassembly:Breakaway torque exceeding 1,000 Nm serves offshore wind turbine maintenance in North Sea installations where pneumatic hoses cannot deploy.
Specification complexity clusters in assembly and fastening where quality documentation is mandatory.
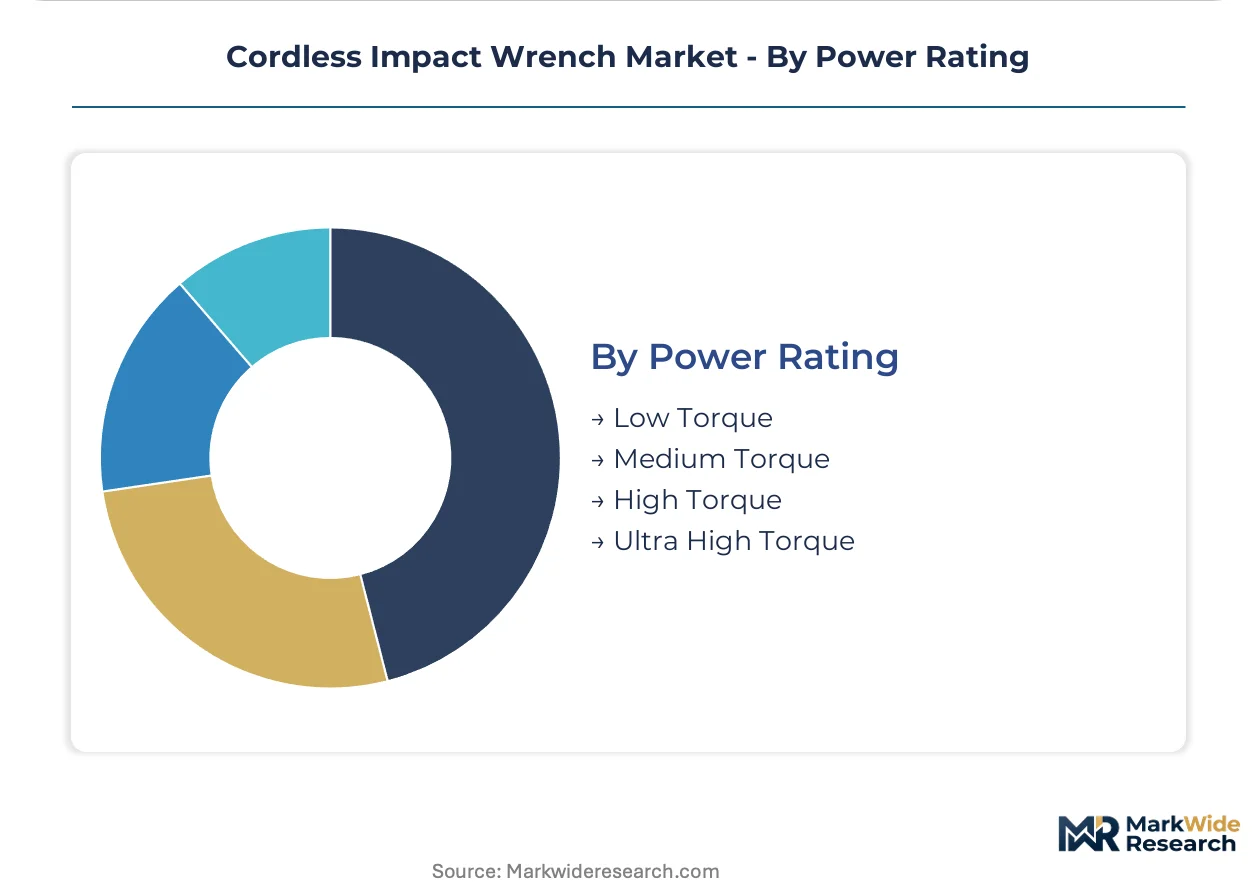
Power Rating:
Margin distribution inverts across the torque spectrum with ultra-high configurations commanding substantial premiums.
- High Torque:500-1,000 Nm output ranges serve heavy equipment maintenance and commercial construction where pneumatic alternatives face mobility constraints.
- Ultra High Torque:Exceeding 1,000 Nm, these platforms target oilfield turnaround contracts in Texas and Alberta where rental networks convert capital expenditure to operating lease models.
- Medium Torque:150-500 Nm segments absorb volume in general automotive and construction applications.
- Low Torque:Below 150 Nm positioning serves light assembly and DIY applications with compressed pricing.
Technology investment concentrates in high and ultra-high torque categories where brushless architectures and advanced cell chemistry justify premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate lithium-ion cell production, attracting cordless tool assembly operations through integrated supply chains and preferential tax treatment. Battery pack manufacturers co-locate with chemical processing facilities to minimize logistics costs and customs friction.
United States
Automotive retooling in Detroit and Spartanburg drives specification demand for high-torque fastening systems with data logging capabilities. OSHA workplace safety directives mandate vibration exposure limits that accelerate pneumatic-to-battery conversion in manufacturing facilities. Assembly plants in Michigan and South Carolina now require cordless platforms for aluminum chassis joining where torque precision prevents galvanic corrosion.
Germany
Tier-one automotive suppliers in Lower Saxony and Baden-Württemberg specify smart torque management for structural joint certification. CE machinery directives enforce noise emission thresholds that extend product introduction timelines by 8-14 months. Industrial clusters around Stuttgart and Wolfsburg deploy battery-powered fastening for electric vehicle lightweighting programs.
China
GB standards for lithium battery transportation and storage impose compliance layers on exporters serving assembly plants in Shenzhen and Shanghai. Manufacturing automation investments in the Yangtze River Delta and Pearl River Delta absorb volume from domestic brushless motor production. Foundries in Jiangsu province specify lithium iron phosphate cell chemistry for thermal stability above 60°C.
Japan
Brushless motor manufacturing scale in Nagoya and Osaka anchors supply for Southeast Asian assembly operations. METI industrial standards shape battery platform interoperability requirements across domestic tool fleets. Precision engineering clusters in Aichi prefecture supply Hall-effect sensor arrays for torque monitoring systems.
India
PLI scheme incentives for advanced cell manufacturing attract joint ventures targeting cordless tool battery packs in Gujarat and Tamil Nadu. BIS certification requirements for power tools create entry barriers for unbranded imports. Construction equipment rental networks in Maharashtra and Karnataka convert capital expenditure to operating lease models for seasonal infrastructure contracts.
Cordless Impact Wrench Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with professional channels consolidating around platform-integrated suppliers while retail channels absorb price-compressed entry-level units. The vendor base organizes into three tiers: captive battery platform operators, motor-technology specialists, and pneumatic-to-battery transition players. Consolidation pressure concentrates in the middle tier where scale advantages determine service network coverage. Competitive moves center on backward integration into cell supply and cross-platform battery compatibility alliances that reduce customer switching costs.
Among Milwaukee-based and Towson-based branded specialists, Milwaukee Tool and DEWALT occupy positions defined by vertical control over battery ecosystems and dense service infrastructure. Makita exemplifies the manufacturing-scale archetype through production concentration in Japan and Southeast Asia. These three anchors represent divergent strategic postures: platform lock-in through battery compatibility, margin defense via upstream integration, and volume leverage through geographic manufacturing distribution.
| Leading Market Players |
|---|
| Milwaukee Tool |
| DEWALT |
| Makita |
| Ingersoll Rand |
| Ryobi |
| Hilti Aktiengesellschaft |
| Festool GmbH |
| Atlas Copco AB |
| Bosch |
| Others |
Value Network & Pricing Analysis
EU battery passport requirements under the EU Green Deal gate qualified supply access and premium-tier pricing power by mandating cell traceability that favors manufacturers with captive recycling partnerships. Compliance-ready producers command pricing premiums while non-compliant inventory faces margin compression across European distribution channels.
Pricing Analysis
Lead-time-driven pricing stratification rewards short-lead-time availability with premiums while spot inventory clears at discounts. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor platforms with data-logging capabilities from basic battery-powered units and entry-level DIY alternatives. Price differentiation rests on CE certification tier and volume scale, with fleet standardization contracts extracting favorable terms. Cost compression in the DIY tier intensifies because big-box retail consolidation concentrates buyer leverage, making automotive and manufacturing verticals least price-sensitive due to specification compliance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive assembly plants in Stuttgart and Detroit, while rental networks in Texas and Alberta absorb volume through operating lease models. Geographic supply concentration centers on China for lithium-ion cell processing, Japan for brushless motor manufacturing, and Germany for precision torque sensor production. Raw material dependencies draw from neodymium rare earth processing in Jiangxi, copper winding stock, and lithium carbonate feedstock. Single-source vulnerability in East Asian chemical processing hubs creates exposure to export quota fluctuations. Distribution runs through professional contractor supply houses, equipment rental networks, and big-box retail channels serving divergent end-user segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into battery cell supply and forward integration into fleet management software represent the decisive levers for sustainable margin control.
For Market Incumbents: To counter firmware integration complexity that extends engineering validation cycles when cell suppliers alter BMS architectures, incumbents should deepen captive cell supply partnerships in East Asian chemical processing hubs and invest in unified service response infrastructure that reduces contractor downtime across multi-year fleet contracts. Certification investment in EU battery passport compliance creates differentiation against regional competitors lacking traceability systems. For New Entrants and Emerging Players: Capture white-space opportunity in offshore wind turbine maintenance segments where pneumatic hose deployment is impossible at height in North Sea installations, and penetrate rental channel expansion in seasonal oilfield markets through operating lease models that convert capital expenditure burdens. A go-to-market angle emphasizing 40V platform compatibility with existing battery ecosystems reduces switching costs for fleet managers. For Investors and Strategic Acquirers: Consolidation of procurement authority to regional equipment managers at general contracting conglomerates is the leading indicator that vendor counts will compress further, extending contract durations and shifting negotiation leverage toward volume purchasers. Over the medium-term horizon, acquisition targets should display captive recycling partnerships for EU compliance, dense service network coverage in industrial Midwest states, and brushless motor manufacturing scale that anchors Southeast Asian supply. The inflection signal to watch is rental network stocking decisions for battery platforms in seasonal turnaround contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Supply | Captive lithium iron phosphate chemistry access insulates margin from rare earth export quota volatility. |
| Smart Torque Management Development | Hall-effect sensor arrays with data logging meet Tier-one automotive supplier certification requirements in Lower Saxony. |
| EU Battery Passport Compliance | Cell traceability mandates favor producers with established recycling partnerships under the EU Green Deal framework. |
| Rental Channel Partnership Expansion | Operating lease models in Texas and Alberta oilfield markets convert capital expenditure to recurring revenue streams. |
| Service Network Density Investment | Unified response times across commercial construction verticals in Florida and California defend platform lock-in against competitors. |
Research Methodology
Document review covered SEC filings from industrial equipment manufacturers, customs trade data for power tool imports, and OSHA regulatory guidance documents, complemented by interviews with plant maintenance directors, OEM procurement teams at Tier-one automotive suppliers, aftermarket service heads, and rental channel operators. Secondary validation drew from CE machinery directive filings, GB standards documentation for lithium battery transportation, and production databases for brushless motor manufacturing. Bottom-up estimates of segment demand triangulated against top-down market sizing from equipment fleet penetration analysis.
Historical shipment data cross-referenced against panel input from industry stakeholders informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, end-user vertical, torque rating tier, and regional manufacturing automation intensity. CAGRs were derived from trend extrapolation of battery platform adoption rates and pneumatic tool replacement cycles. Industry-specific forecast inputs incorporated automotive lightweighting program timelines and wind turbine installation schedules affecting maintenance tool demand.
The model holds under stable lithium carbonate pricing and continued OSHA ergonomic mandate enforcement; deviation in rare earth export quotas or CE certification timeline extensions would shift volume and value outputs. Forecasts reflect assumptions regarding brushless motor cost curves and rental channel penetration rates. Periodic stress-testing of base assumptions is recommended against cell chemistry transition timelines and fleet standardization contract award patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Drill Presses Market
Tools
Air Hammer Market
Tools
Portable Heat Press Machine Market
Tools
Cordless Bandsaw Sander Market
Tools
Adoption of Benelux Power Tools Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Handheld Blower Market
Tools
Cold and Hot Tool Steel Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Rebar Cutter Market
Tools
Foam Engraving Machines Market
Tools
Drywall Tool Market
Tools
Fastening Power Tools Market
Tools
Post Drivers Market
Tools
Automated Plasma Beveller Market
Tools
Tape Measure Market