
 Europe Paint Spray Guns Market | 2026-2036
Europe Paint Spray Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Paint Spray Guns Market Analytics
The EU Green Deal is restructuring paint application equipment procurement across European manufacturing. SATA GmbH & Co. KG leverages its precision engineering heritage to dominate premium manual spray gun segments. Graco Inc. sustains technology leadership in automatic and robotic application systems for high-volume facilities.
Paint spray guns are precision fluid delivery devices that atomize coating materials through controlled air pressure or hydraulic force, typically operating at pressures from 10 to 50 PSI for HVLP systems and up to 3,000 PSI for airless configurations, serving to apply uniform protective and decorative finishes across industrial and commercial substrates. HVLP technology leads the product type landscape due to its transfer efficiency compliance with VOC regulations, while robotic technology represents the fastest-expanding segment as automotive OEMs automate finishing lines to reduce material waste and labor variability. Contractors and OEMs anchor end-user demand, with repair shops representing a concentrated margin pool in the aftermarket refinishing channel.
REACH and the EU F-Gas Regulation shape material compatibility and solvent containment requirements for spray gun manufacturers, while CE marking mandates govern electrical and pneumatic safety standards for equipment placed on the European market. ECHA's ongoing substance evaluations continue to restrict traditional solvent formulations, redirecting R&D investment toward waterborne and powder coating delivery systems. Stakeholders must monitor the interplay between automation technology maturation and evolving VOC thresholds to align product portfolios with enforcement trajectories.
Market Dynamics
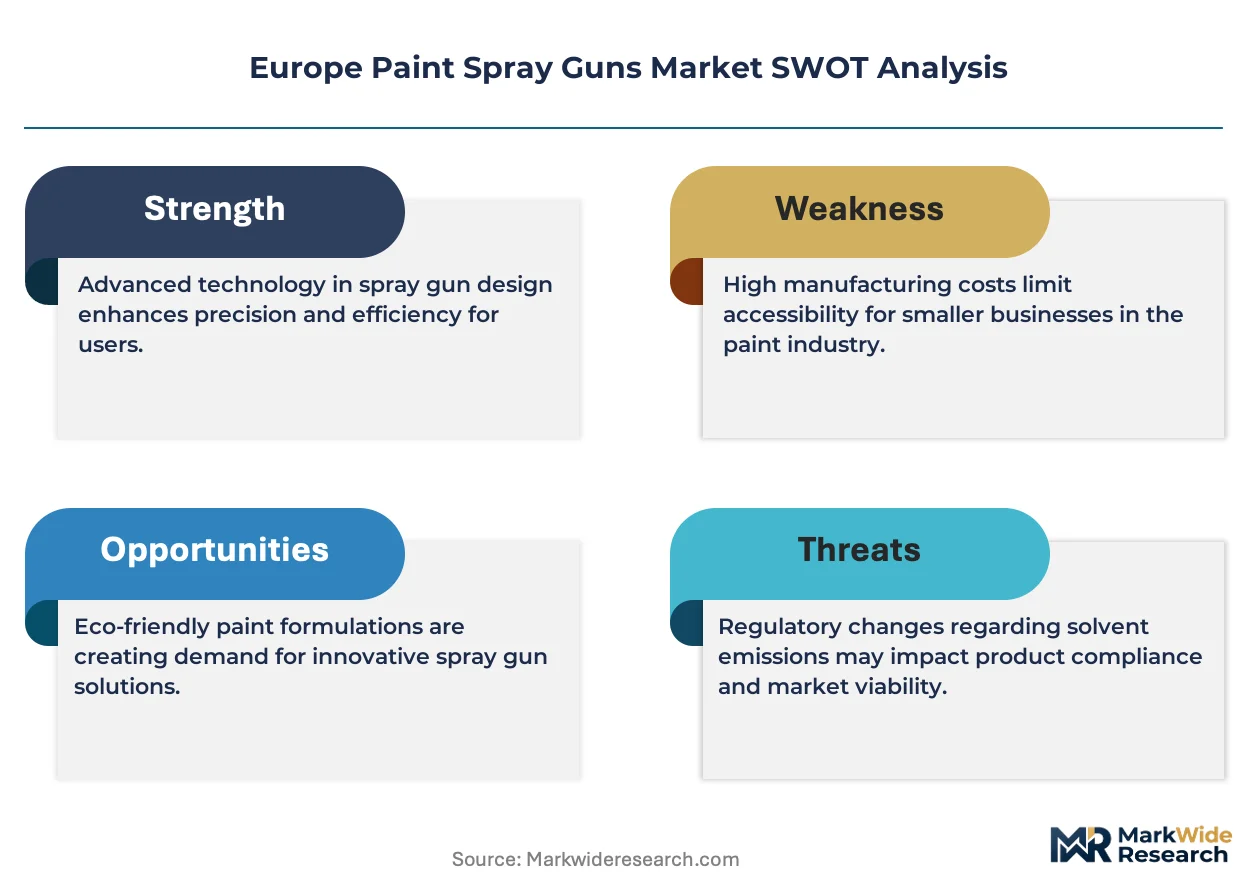
REACH substance restrictions and the EU Green Deal's industrial emissions targets are forcing paint spray gun manufacturers to redesign fluid delivery systems for waterborne and high-solids coatings, compressing development cycles and elevating R&D intensity across the European supply base.
Growth Catalysts
- Automotive refinishing demand:Germany's automotive manufacturing corridor sustains replacement equipment purchases as collision repair networks expand capacity to serve electric vehicle platforms with specialized coating requirements.
- CE marking harmonization:Unified pneumatic and electrical safety standards reduce cross-border certification costs for equipment placed on the European market, accelerating product launches in Eastern European expansion markets.
- Robotic finishing adoption:Automotive OEMs automate paint lines to reduce material waste and labor variability, pulling demand for integrated automatic spray gun systems with real-time film thickness control.
Market Restraints
- Specialized component concentration:Precision air cap and needle manufacturing concentrates among German and Italian machining specialists, creating single-source vulnerability for premium manual gun producers.
- ECHA substance evaluation timeline:Ongoing REACH restrictions on traditional solvent formulations force premature obsolescence of established gun designs optimized for high-VOC coatings.
- Powder coating substitution:Electrostatic powder systems displace liquid spray applications in metal fabrication segments, eroding addressable market for conventional HVLP equipment in industrial maintenance channels.
Strategic Opportunities
- Polish and Romanian industrial clusters:Automotive supplier parks in these markets remain underpenetrated by premium spray gun distributors, offering first-mover positioning for localized service networks.
- EU F-Gas Regulation compliance:Transition to low-GWP propellant systems creates retrofit demand for pneumatic gun architectures compatible with next-generation carrier gases.
- IoT-enabled predictive maintenance:Convergence of fluid sensors and cloud analytics allows equipment-as-a-service models that capture lifetime value from high-volume collision repair chains.
Industry Challenges
- Skilled applicator shortage:European refinishing shops face persistent gaps in certified technicians capable of operating precision HVLP systems for waterborne color-matching protocols.
- Legacy ERP integration:Automated spray line retrofits require costly middleware development to synchronize new robotic controllers with existing manufacturing execution systems in mature German facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Paint Spray Guns Market |
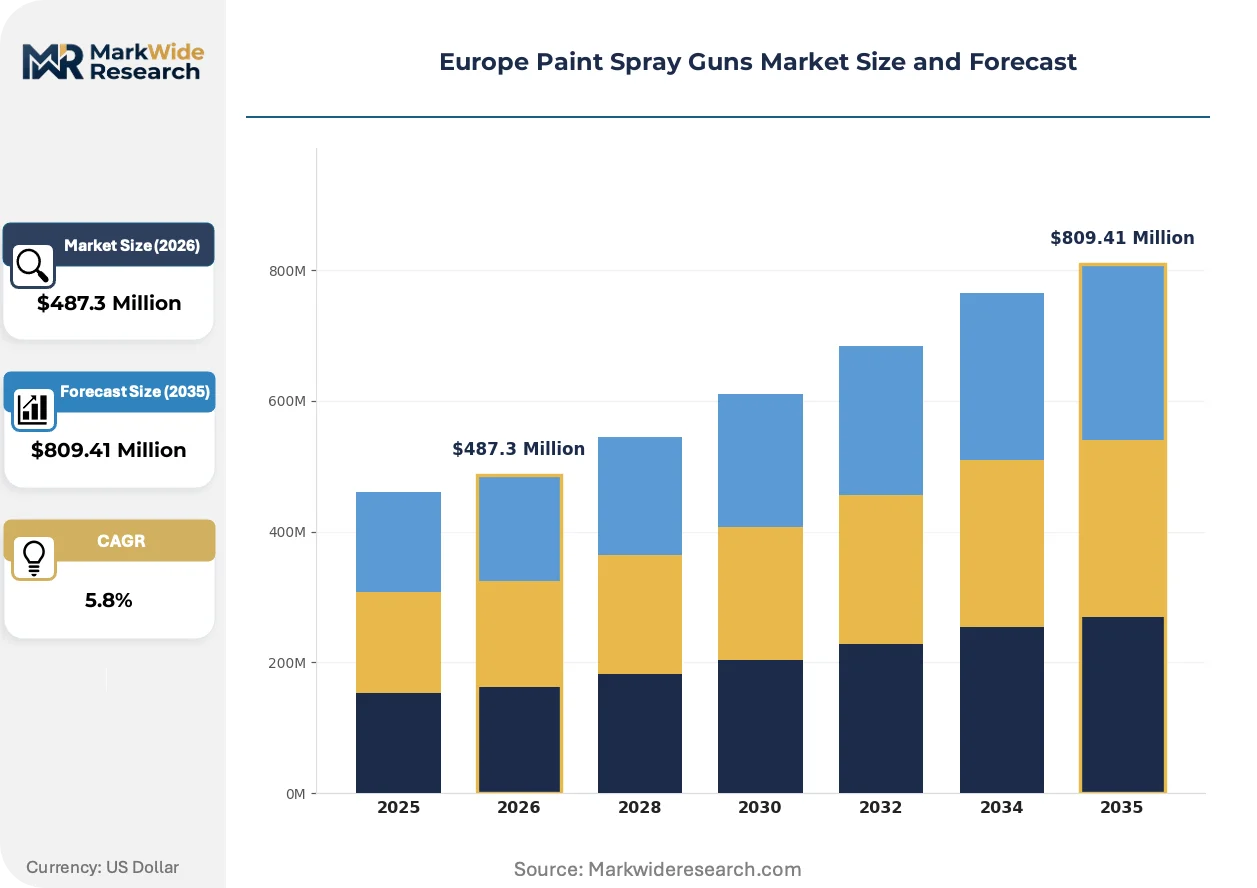
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, HVLP, Airless, Electrostatic Application: Automotive, Furniture, Aerospace, Industrial Coatings Technology: Manual, Automatic, Robotic, Semi-Automatic End User: Contractors, OEMs, DIY Enthusiasts, Repair Shops |
| Companies Covered | 3M Company, Exel Industries, SATA GmbH & Co. KG, Dürr AG, WAGNER Group GmbH, J. Wagner GmbH, ANEST IWATA Corporation, HSM Lackiersysteme GmbH, Graco Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Paint Spray Guns Market Evolving Landscape
Digital fluid monitoring and closed-loop pressure control are compressing the performance gap between manual and automatic application systems, while regulatory chemistry restrictions are redirecting equipment design priorities across European manufacturing.
Electrostatic rotary bell atomizers are absorbing finishing-line volume previously served by conventional air spray systems in automotive OEM plants. Tier-one suppliers in Germany and Spain deploy these systems for basecoat and clearcoat application to achieve transfer efficiency above 85 percent. The technology is absorbing capital budgets that once diversified across multiple application methods, consolidating supplier relationships around integrated system architects.
The EU F-Gas Regulation is phasing down hydrofluorocarbon propellants used in certain specialty coating applications, compelling gun manufacturers to validate alternative pneumatic architectures. Industrial finishers must retrofit or replace equipment to maintain compliance with containment and recovery requirements. Automotive OEMs in France and Italy are responding fastest, embedding F-Gas-compatible specifications into new line procurement tenders ahead of enforcement deadlines.
Collision repair networks are consolidating purchasing through group procurement organizations, displacing traditional distributor relationships with direct manufacturer contracts tied to training and certification bundles. Large multi-shop operators in the United Kingdom and Netherlands negotiate enterprise pricing contingent on technician credentialing through manufacturer academies. This concentration is most visible in premium vehicle brand-certified repair channels where OEM approval requirements lock in equipment specifications.
Europe Paint Spray Guns Market Segmentation
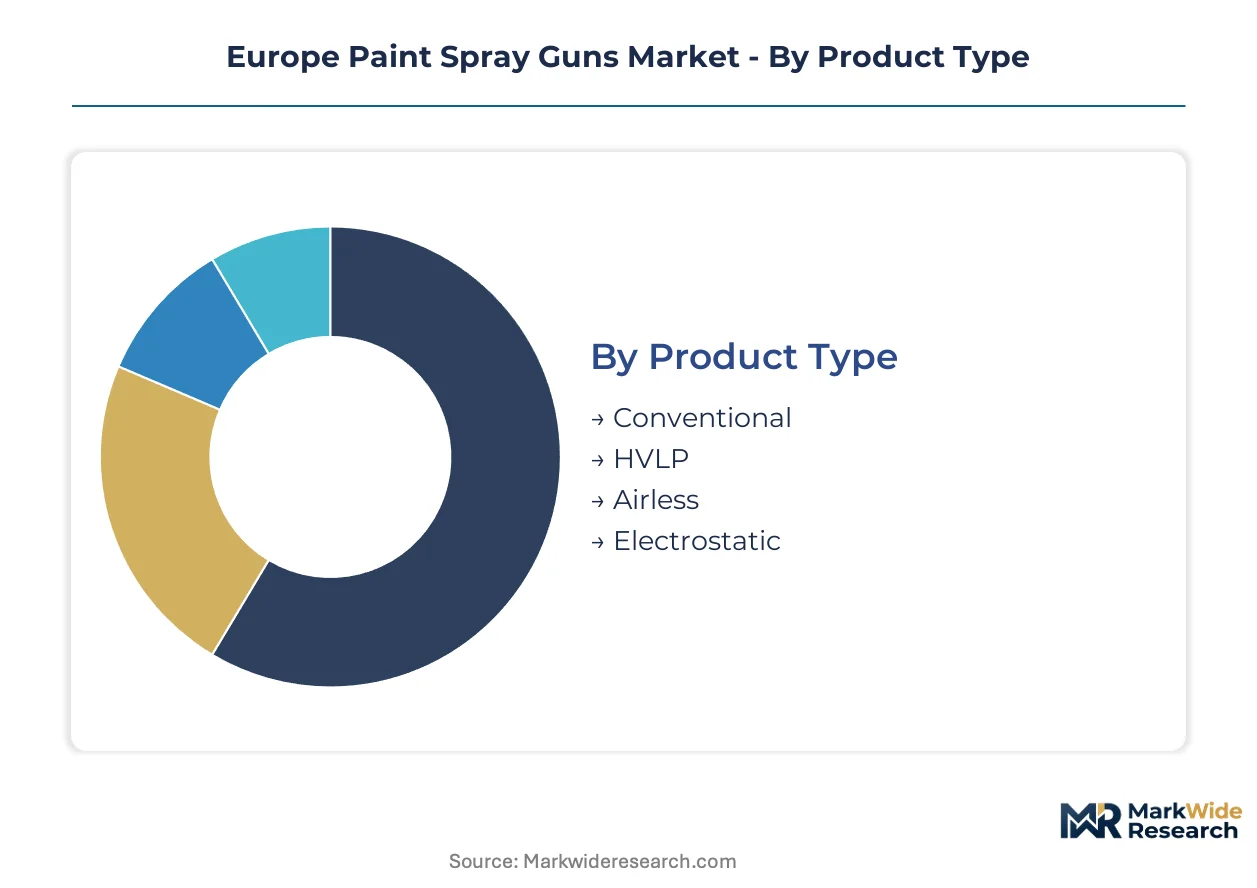
Equipment replacement cycles in Europe's paint spray gun market vary dramatically by segment, with regulatory compliance deadlines and automation investments driving divergent upgrade timelines across product categories. Understanding these temporal patterns enables suppliers to align inventory and service capacity with concentrated demand windows.
Product Type:
Upgrade urgency separates segments as REACH substance restrictions force premature obsolescence of legacy designs optimized for solvent-borne coatings.
- HVLP:High-volume low-pressure systems atomize coatings through controlled air pressure between 10-50 PSI, achieving transfer efficiency above 65 percent to satisfy VOC regulations. Demand concentrates in Germany's collision repair networks as shops replace conventional equipment to maintain environmental operating permits.
- Airless:Hydraulic force drives coating atomization at pressures reaching 3,000 PSI, enabling high-build applications on structural substrates. Industrial maintenance contractors across Poland and Romania favor these systems for protective coating projects on infrastructure assets.
- Conventional:Traditional compressed-air spray guns deliver coating through venturi-based atomization at higher overspray rates. Remaining demand persists among budget-conscious furniture finishers in Southern Europe.
- Electrostatic:Charged particle attraction wraps coating around complex geometries with minimal waste. Automotive OEMs in France deploy rotary bell configurations for basecoat application.
Volume placements concentrate in HVLP; the faster expansion belongs to electrostatic systems.
Application:
Cost tier differentiation shapes procurement patterns as capital intensity separates OEM finishing lines from aftermarket repair operations.
- Automotive:OEM paint shops and collision repair networks drive equipment turnover, with electric vehicle platforms requiring specialized coating protocols for battery enclosure protection. Spain's automotive supplier parks generate concentrated demand for robotic integration.
- Industrial Coatings:Protective finishing of infrastructure, machinery, and metal fabrication absorbs mid-tier equipment volumes. Dutch marine coating contractors sustain replacement purchases for offshore wind tower applications.
- Furniture:Wood finishing operations favor manual HVLP systems for decorative lacquer application. Italian cabinetry manufacturers maintain steady equipment refresh cycles.
- Aerospace:Precision coating of airframe components demands specialized low-pressure systems with film thickness control. Toulouse and Hamburg manufacturing clusters anchor niche demand.
Capital deployment concentrates in automotive OEM lines; aftermarket repair channels deliver steadier replacement revenue.
Technology:
Customer type determines automation depth as high-volume manufacturers separate from job-shop flexibility requirements.
- Robotic:Six-axis articulated arms with integrated spray guns execute programmed coating paths with real-time film monitoring. German automotive OEMs lead adoption to reduce labor variability and material waste.
- Automatic:Fixed-mount reciprocating systems serve high-volume finishing lines with consistent coverage. Spanish appliance manufacturers deploy these for refrigerator and washing machine cabinets.
- Manual:Handheld guns operated by certified technicians dominate refinishing and custom applications. UK collision repair chains invest in training academies to maintain application quality.
- Semi-Automatic:Operator-guided systems with mechanized traverse mechanisms bridge flexibility and consistency. Romanian furniture exporters adopt these for batch production runs.
Installed base concentrates in manual systems; the steepest expansion trajectory belongs to robotic integration.
End User:
Margin structure varies by procurement sophistication as consolidated buyers extract service bundles from manufacturers.
- Repair Shops:Collision repair networks consolidate purchasing through group procurement organizations, negotiating enterprise pricing contingent on technician certification. Netherlands-based multi-shop operators lead this concentration.
- OEMs:Original equipment manufacturers specify integrated finishing systems with predictive maintenance capabilities. French automotive plants embed IoT sensor requirements in procurement tenders.
- Contractors:Industrial painting contractors prioritize equipment durability and field service availability. Polish infrastructure specialists drive demand for portable airless systems.
- DIY Enthusiasts:Consumer-grade HVLP systems serve home improvement applications through retail distribution. UK garden furniture restoration sustains niche volumes.
Revenue concentration sits with repair shop networks; OEM relationships deliver longer contract visibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European paint spray gun demand through its dense automotive manufacturing corridor, where collision repair networks and OEM finishing lines drive equipment turnover across the region.
Germany
Automotive refinishing shops in Baden-Württemberg and Bavaria sustain replacement cycles for HVLP systems as electric vehicle platforms require specialized coating protocols. REACH substance restrictions force premature obsolescence of solvent-optimized gun designs. The Stuttgart manufacturing cluster concentrates precision machining capacity for air cap and needle components.
United Kingdom
Collision repair networks consolidate purchasing through group procurement organizations, negotiating enterprise pricing contingent on technician certification. CE marking harmonization reduces cross-border certification costs for equipment imports. Multi-shop operators in the Midlands and Greater London drive standardization of IoT-enabled predictive maintenance specifications.
France
Automotive OEMs in the Île-de-France and Hauts-de-France regions embed F-Gas Regulation compliance into new line procurement tenders ahead of enforcement deadlines. The EU Green Deal's industrial emissions targets accelerate robotic finishing adoption. Toulouse aerospace manufacturing anchors niche demand for precision low-pressure systems with film thickness control.
Spain
Automotive supplier parks in Catalonia and the Basque Country generate concentrated demand for robotic integration in basecoat and clearcoat application. Appliance manufacturers deploy automatic reciprocating systems for refrigerator and washing machine cabinets. Spanish facilities lead Southern European adoption of electrostatic rotary bell atomizers.
Poland
Industrial painting contractors prioritize portable airless systems for protective coating projects on infrastructure assets. Automotive supplier parks in Silesia and Greater Poland remain underpenetrated by premium spray gun distributors. Polish industrial clusters offer first-mover positioning for localized service networks serving mid-tier equipment volumes.
Europe Paint Spray Guns Market Competitive Landscape
The competitive structure tilts toward precision-engineering specialists with heritage manufacturing credentials. German and Italian machining specialists concentrate production of critical air cap and needle components, creating tiered supplier relationships. Three archetypes dominate: integrated system architects serving automotive OEMs, precision manual gun specialists, and scale-driven automatic equipment fabricators. M&A activity concentrates among automatic system integrators, while geographic expansion targets Eastern European industrial clusters.
Within the precision-engineering tier, SATA GmbH & Co. KG and Dürr AG exemplify divergent strategic positions. SATA represents heritage manual gun craftsmanship serving collision repair networks, while Dürr occupies the integrated system architect role for automotive OEM finishing lines. Graco Inc. anchors the scale-driven archetype with automatic and robotic application systems. Among diversified industrial equipment groups, 3M Company and Exel Industries sit within broader coating and fluid management portfolios.
| Leading Market Players |
|---|
| 3M Company |
| Exel Industries |
| SATA GmbH & Co. KG |
| Dürr AG |
| WAGNER Group GmbH |
| J. Wagner GmbH |
| ANEST IWATA Corporation |
| HSM Lackiersysteme GmbH |
| Graco Inc. |
| Others |
Value Network & Pricing Analysis
Robotic finishing adoption across German automotive OEMs simultaneously compresses per-unit coating costs and concentrates procurement power among integrated system architects. This technology transition elevates capital expenditure thresholds while reducing lifetime operating expenses through material efficiency gains.
Pricing Analysis
Transfer efficiency guarantees anchor value-based pricing for HVLP and electrostatic systems, with automotive OEMs paying premiums for documented coating yield improvements. Price differentiation separates CE-marked precision equipment from uncertified alternatives, while volume scale drives enterprise discounts for collision repair chains. Cost compression in manual gun tiers intensifies as Eastern European suppliers expand machining capacity. DIY enthusiasts exhibit highest price sensitivity, whereas OEMs prioritize total cost of ownership over upfront equipment expenditure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for robotic integration projects, while distributor networks serve fragmented collision repair and contractor segments. Precision air cap and needle manufacturing concentrates in Germany, Italy, and Switzerland, drawing from specialized CNC machining and hard-coating processes. Supply chain risk centers on single-source vulnerability for critical fluid delivery components. Distribution runs through manufacturer-direct relationships for large automotive accounts and regional distributors for aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into precision machining capabilities defines competitive positioning as players seek captive supply of air cap and needle components.
For Market Incumbents: Cement control over critical component supply by acquiring German and Italian machining specialists. Invest in F-Gas-compatible pneumatic architectures ahead of enforcement deadlines to preempt regulatory obsolescence of legacy designs. For New Entrants and Emerging Players: Mid-tier industrial contractors in Poland and Romania represent an underserved buyer archetype with unmet service network needs. Establish localized technical support and rapid spare parts availability to differentiate from distant premium suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated system architects with established automotive OEM relationships. Long-term viability hinges on automation technology maturation and regulatory compliance capabilities. Monitor ECHA substance evaluation timelines as inflection indicators for equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Machining | Captive supply of air caps and needles reduces single-source vulnerability for SATA and Dürr. |
| F-Gas Regulation Compliance Program | Early validation of low-GWP pneumatic systems secures procurement tenders from French automotive OEMs. |
| IoT-Enabled Predictive Maintenance Platform | Cloud analytics integration captures lifetime value from UK collision repair chain consolidation. |
| Polish Service Network Expansion | Localized technical support addresses underpenetrated industrial contractor demand in Silesia. |
| Waterborne Coating System Validation | REACH-aligned fluid delivery designs preempt forced obsolescence of solvent-optimized equipment. |
Research Methodology
Document review covered EU regulatory filings, automotive production databases, and coating technology patents, complemented by interviews with collision repair network managers, OEM finishing line engineers, precision machining specialists, and industrial coating contractors. Secondary sources included ECHA substance evaluations, CE marking directives, and customs trade data. Bottom-up equipment shipment analysis triangulated against top-down automotive production and refinishing market estimates.
Market size and growth projections reflect segmentation across product type, application, technology, and end-user dimensions over the analysis window. Modeled variables included automotive platform transitions, REACH compliance deadlines, and automation adoption curves. CAGRs derived from regression analysis of historical equipment replacement cycles and forward-looking regulatory enforcement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance restriction timelines and automotive OEM automation investment decisions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Shredder Blades Market
Tools
Scroll Saws Market
Tools
Screwdriver Market
Tools
Air Hammer Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Global Flange Fasteners Market
Tools
Power Tool Gears Market
Tools
Vise-Grip Pliers Market
Tools
Europe Power Tools Market
Tools
Handheld Engraving Machine Market
Tools
Grabber Pole Market
Tools
Land Survey Equipment Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Riveting Tools Market
Tools
Europe Woodworking Power Tools Market
Tools
Trim Press Market