
 Paint Spray Guns Market | 2026-2036
Paint Spray Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Spray Guns Market Analytics
REACH compliance is hardening the cost-of-entry calculus for spray gun manufacturers serving European automotive and industrial coatings sectors. Graco Inc. leverages its pneumatic technology leadership to sustain premium positioning across contractor and manufacturing channels. SATA GmbH & Co. KG anchors its competitive stance through precision-engineered RP and HVLP systems purpose-built for automotive refinishing. Exel Industries competes via diversified portfolio breadth spanning agricultural, industrial, and paint application equipment.
Paint spray guns are precision fluid delivery devices that atomize coatings through controlled air pressure or hydraulic force, typically operating at pressures between 20 and 60 PSI for HVLP systems and exceeding 2,000 PSI for airless configurations, designed to achieve uniform film thickness across complex substrate geometries. HVLP technology dominates automotive refinishing due to transfer efficiency mandates, while airless systems command industrial and architectural segments where high-volume throughput outweighs overspray concerns. Battery-operated electric variants represent the fastest-expanding technology category as cordless mobility gains traction among contractors and workshop operators.
EPA National Emission Standards for Hazardous Air Pollutants and EU REACH restrictions on solvent-based formulations directly shape product development trajectories and material compatibility requirements. OSHA ventilation standards and CE marking obligations under the EU Machinery Directive further delineate market access thresholds across North America and Europe. Stakeholders must monitor evolving state-level VOC regulations in California and emerging GB standards in China to anticipate compliance-driven equipment replacement cycles.
Market Dynamics
Waterborne coating mandates under EPA and EU REACH protocols are compressing equipment replacement cycles as workshops face simultaneous transfer efficiency requirements and material compatibility constraints. This regulatory convergence forces capital deployment toward HVLP and compliant airless systems.
Growth Catalysts
- Automotive refinishing standards:OEM collision repair protocols in Germany and the United States mandate precision film thickness control. Workshop operators upgrade to RP and HVLP systems to meet warranty compliance requirements.
- REACH solvent restrictions:ECHA enforcement on solvent-based formulations drives equipment replacement across European automotive and industrial coatings sectors. Manufacturers redesign fluid passages for waterborne chemistry compatibility.
- Battery mobility expansion:Cordless electric variants gain traction among contractor segments. Lithium-ion power density improvements enable portable high-pressure performance previously limited to pneumatic systems.
Market Restraints
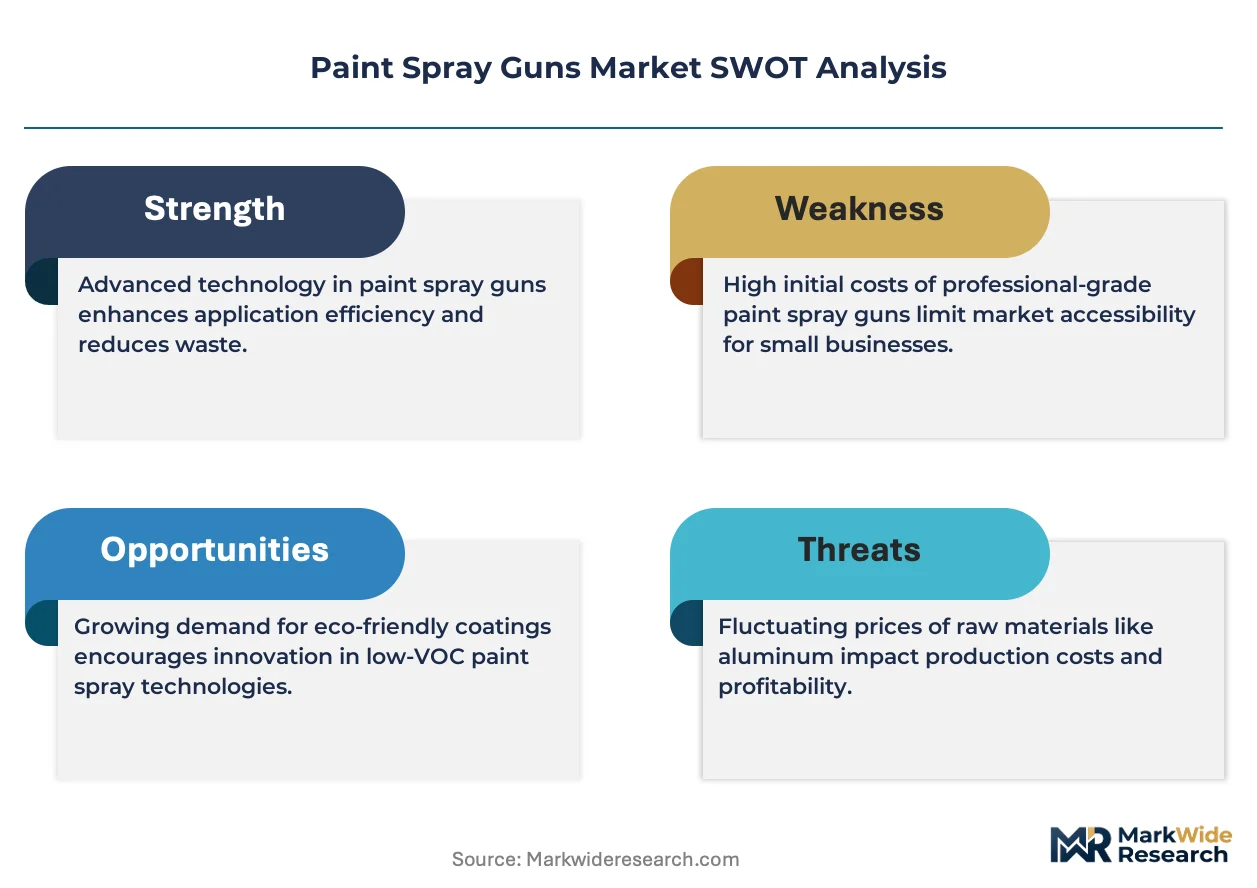
- Specialized alloy costs:Stainless steel and nickel-plated brass components face price volatility from mining supply constraints. Fluid delivery precision requires corrosion-resistant materials unsuited to substitution.
- Precision manufacturing concentration:High-tolerance machining capabilities cluster in southern Germany and northern Italy. Geographic supply concentration creates lead time vulnerability for specialized nozzles and air caps.
- Transfer efficiency ceilings:HVLP technology approaches theoretical maximums around 65% transfer efficiency. Further regulatory tightening may require entirely different atomization physics.
Strategic Opportunities
- Chinese GB standard alignment:Emerging national standards for VOC emissions in automotive refinishing create equipment replacement windows. Domestic manufacturers lack compliant system portfolios.
- Robotic integration:Convergence of collaborative robotics with precision fluid delivery opens automotive OEM paint shop applications. Repeatable trajectory programming eliminates operator variability.
- Rental and service models:Contractor segments in North America experiment with subscription-based equipment access. Maintenance bundling reduces capital barriers for small operators.
Industry Challenges
- Applicator certification complexity:I-CAR and manufacturer-specific training requirements extend technician qualification timelines. Workshop operators face productivity gaps during credentialing periods.
- Legacy pneumatic infrastructure:Compressed air system investments in established facilities create switching friction. Electric and battery alternatives require incompatible power distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Spray Guns Market |
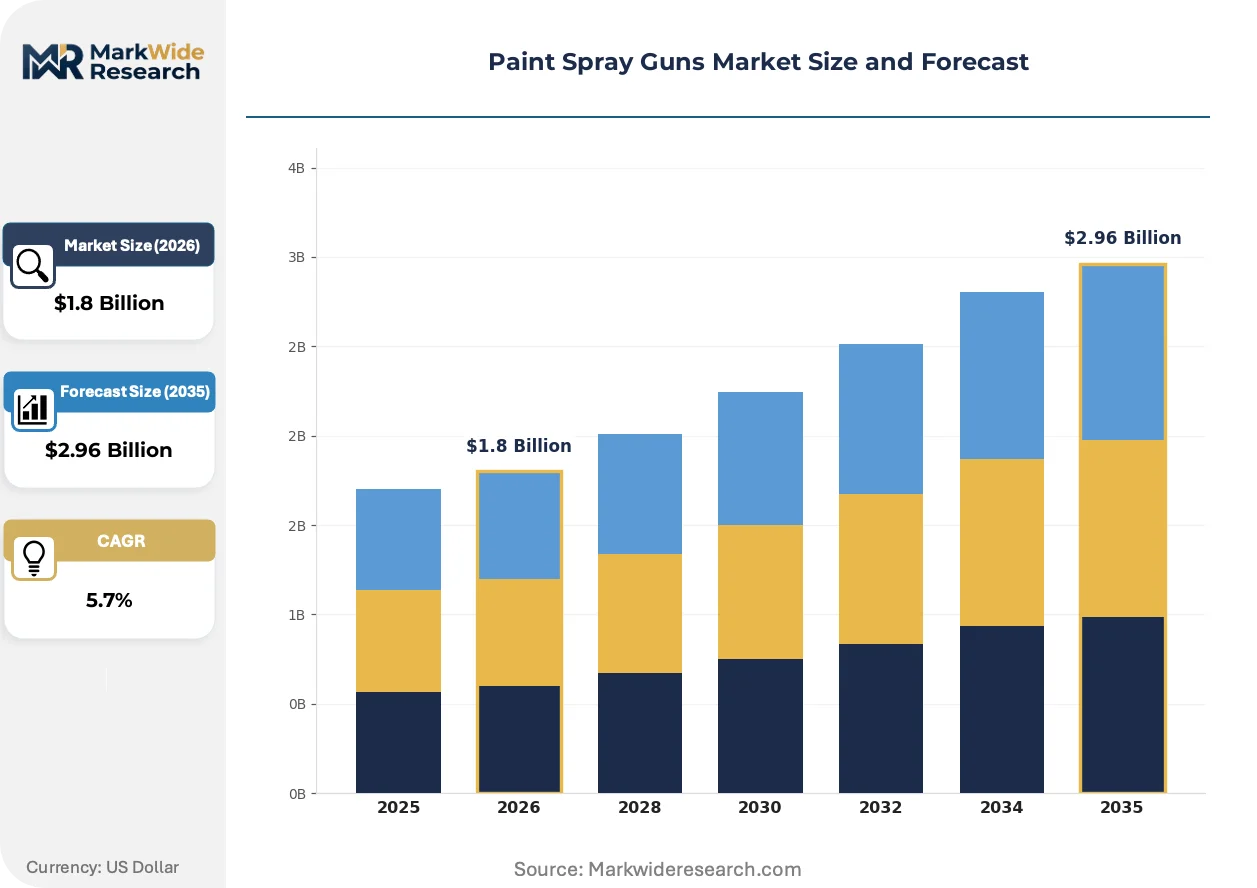
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HVLP, RP, Airless, Electrostatic Application: Automotive, Furniture, Industrial, Architectural End User: Contractors, DIY Enthusiasts, Manufacturers, Workshops Technology: Pneumatic, Electric, Battery-operated, Manual |
| Companies Covered | SATA GmbH & Co. KG, Fuji Spray, Graco Inc., Exel Industries, Wagner SprayTech Corp., Anest Iwata, Devilbiss Automotive Refinishing, Tritech Industries, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Spray Guns Market Evolving Landscape
Atomization technology is converging with digital control systems as manufacturers embed sensors and feedback loops into handheld devices. This integration transforms spray guns from mechanical tools into data-generating assets.
Smart fluid monitoring is consolidating operational visibility across automotive refinishing workflows. Pressure transducers and flow sensors embedded in HVLP handles transmit real-time data to shop management systems. Large collision repair networks in the United States deploy these capabilities to enforce standard operating procedures across distributed locations. The technology is consolidating quality control from individual technician judgment into centralized protocol enforcement.
EPA National Emission Standards for Hazardous Air Pollutants are tightening enforcement on surface coating operations across aerospace and industrial wood finishing segments. Inspection frequency and penalty structures have intensified since protocol amendments. California Air Resources Board regulations extend these requirements with lower VOC thresholds, forcing equipment upgrades in the state's furniture manufacturing corridor.
Certification-driven specification is altering procurement authority within automotive refinishing operations. Insurance carriers and OEM warranty programs now mandate approved equipment lists, shifting purchase decisions from shop owners to network administrators. This concentration is most visible in United States dealer-affiliated collision centers where MSO consolidation accelerates standardization.
Paint Spray Guns Market Segmentation
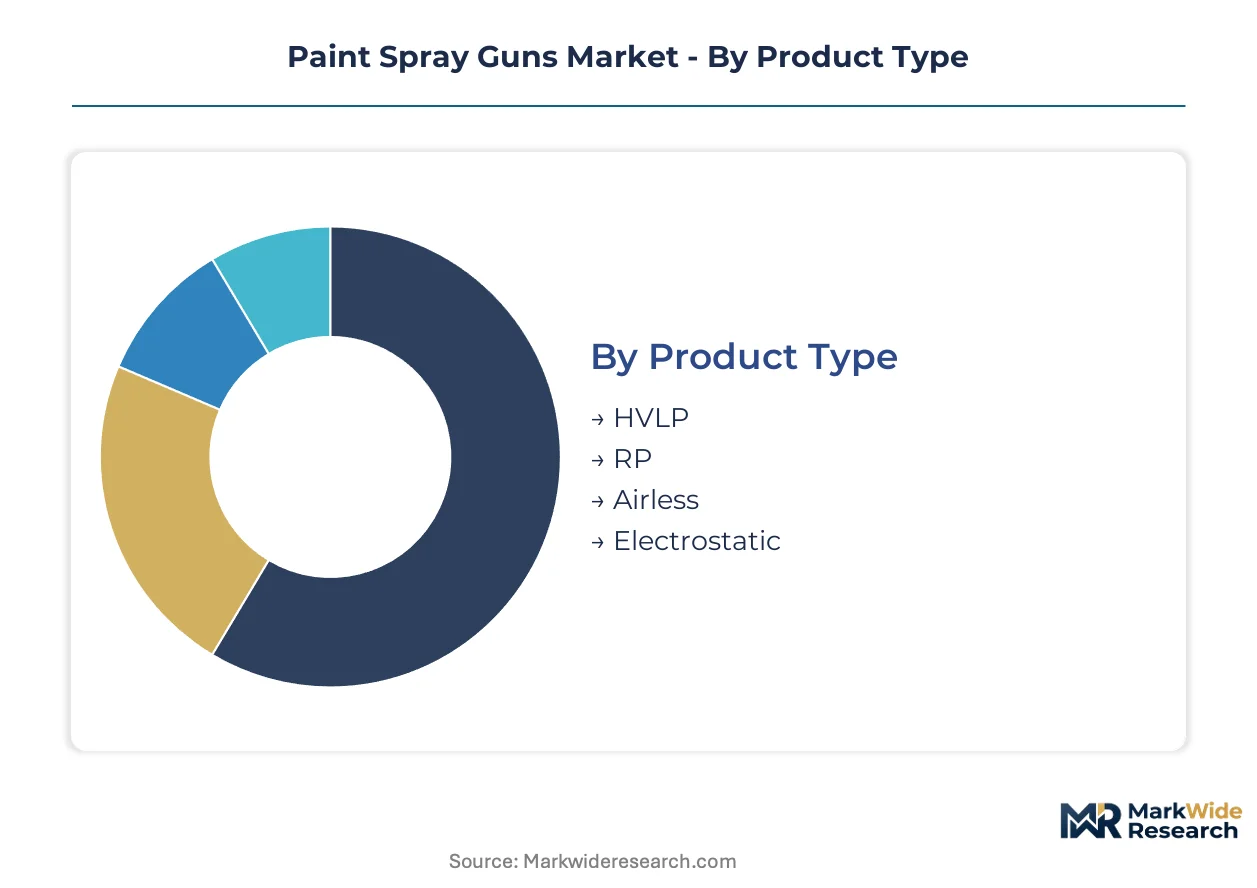
Paint spray gun procurement decisions pivot on coating chemistry compatibility, regulatory compliance thresholds, and mobility requirements across workshop environments. Segment boundaries blur as HVLP systems penetrate industrial applications and battery power challenges pneumatic dominance in contractor fleets.
Product Type:
Workshop operators weigh transfer efficiency mandates against capital outlay and compressed air infrastructure when selecting atomization platforms.
- HVLP:High-volume low-pressure systems atomize coatings at 10 PSI or less at the air cap, achieving transfer efficiency above 65% through reduced overspray. Collision repair networks in Germany and the United States specify HVLP for warranty compliance as OEM protocols harden film thickness precision requirements.
- RP:Reduced pressure technology bridges HVLP efficiency with conventional spray speed, operating at intermediate pressures with optimized air cap geometries. Italian automotive refinishing clusters favor RP systems where technician productivity pressures coexist with solvent reduction mandates under EU REACH enforcement.
- Airless:Hydraulic pressure exceeding 2,000 PSI drives coating through precision orifices without compressed air, dominating architectural and marine applications where surface area throughput outweighs transfer efficiency concerns.
- Electrostatic:Charged particle attraction wraps coatings around complex geometries, concentrating in automotive OEM paint shops and metal furniture manufacturing where uniform edge coverage justifies system complexity.
HVLP leads on scale; RP leads on momentum.
Application:
End-use specifications diverge sharply between controlled environment refinishing and field-deployed architectural coating.
- Automotive:OEM collision repair protocols and insurance carrier mandates drive specification authority toward network administrators rather than individual shop owners. EPA National Emission Standards for Hazardous Air Pollutants and California Air Resources Board thresholds enforce equipment replacement cycles across United States refinishing corridors.
- Furniture:Industrial wood finishing faces intensified inspection frequency under amended EPA protocols, with California's furniture manufacturing corridor experiencing forced equipment upgrades to meet lower VOC thresholds.
- Industrial:Heavy equipment and agricultural machinery coating prioritizes durability and corrosion resistance over atomization finesse, favoring airless and conventional pressure feed systems.
- Architectural:On-site construction and maintenance applications demand portability and rapid setup, creating openings for battery-operated variants as lithium-ion power density improves.
Automotive commands revenue concentration; architectural exhibits the steepest expansion trajectory as cordless mobility gains contractor acceptance.
End User:
Capital availability and technical certification requirements stratify purchasing behavior across user categories.
- Contractors:Mobile painting crews prioritize equipment durability and rapid job-site deployment. North American contractor segments experiment with subscription-based equipment access models that bundle maintenance and reduce capital barriers.
- DIY Enthusiasts:Consumer-grade electric and manual systems dominate, with retail channel distribution through home improvement centers. Price sensitivity limits specification complexity.
- Manufacturers:OEM paint shops demand repeatable trajectory programming and integration with collaborative robotics, eliminating operator variability in high-volume production environments.
- Workshops:Independent collision repair operators face I-CAR and manufacturer-specific training requirements that extend technician qualification timelines, creating productivity gaps during credentialing periods.
Workshops anchor volume demand; manufacturers drive specification innovation through robotic integration requirements.
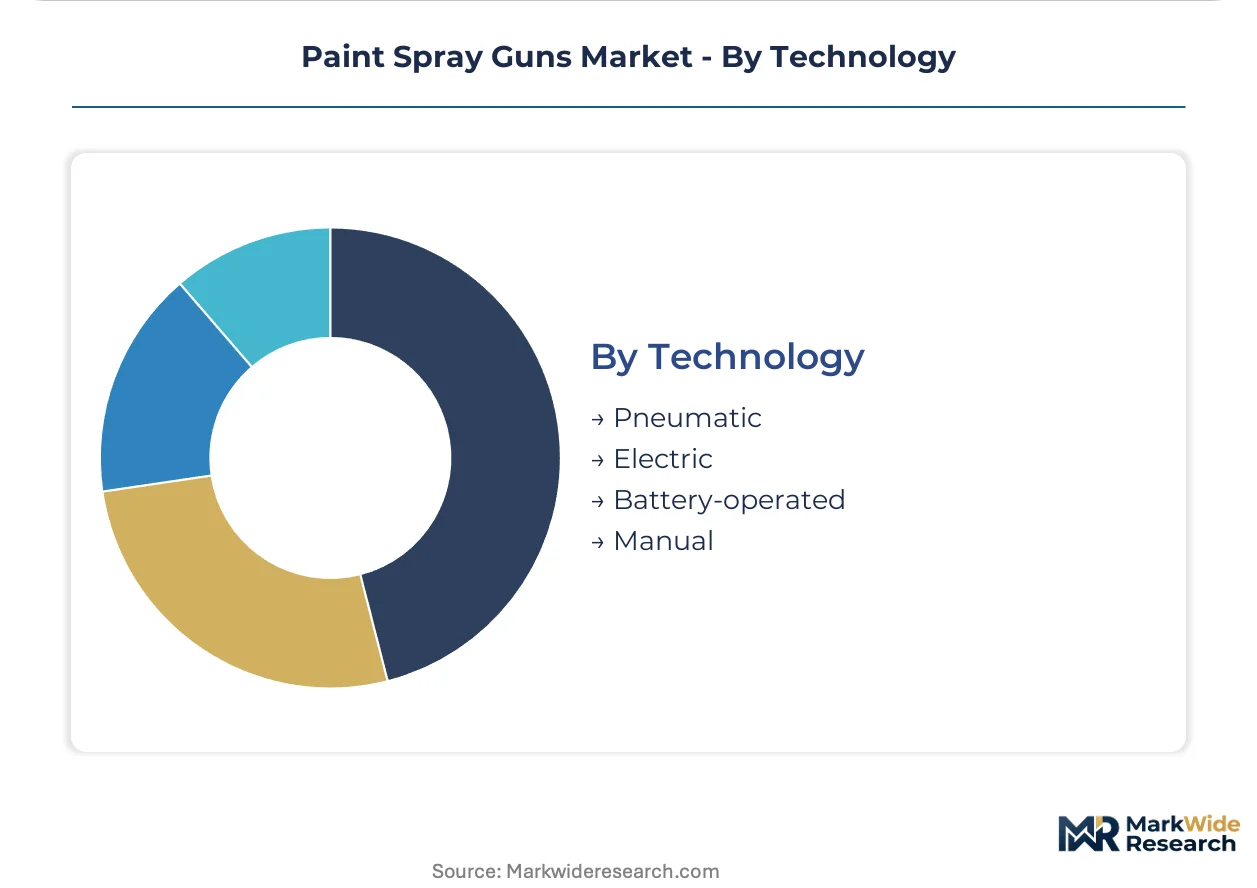
Technology:
Power source selection determines mobility range, pressure consistency, and infrastructure compatibility across operating environments.
- Pneumatic:Compressed air systems deliver consistent pressure and rapid recovery, dominating established automotive refinishing facilities with existing compressor infrastructure. Legacy pneumatic investments create switching friction against electric alternatives.
- Electric:Corded electric variants eliminate compressor dependency while maintaining continuous operation capability, penetrating mid-volume workshops without compressed air distribution.
- Battery-operated:Lithium-ion power density improvements enable portable high-pressure performance previously limited to pneumatic systems. This segment is expanding most quickly among contractor segments seeking job-site mobility without tethering constraints.
- Manual:Hand-pumped pressure pots and siphon feed systems persist in low-volume touch-up applications and developing markets where capital constraints limit technology adoption.
Pneumatic retains installed base dominance; battery-operated technology gains share fastest as cordless performance converges with pneumatic capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled technician concentrations in Germany, the United States, and China anchor paint spray gun demand as regulatory enforcement tightens equipment specifications across automotive refinishing corridors.
United States
Collision repair networks in Michigan and Texas drive specification authority toward MSO administrators under tightening EPA National Emission Standards for Hazardous Air Pollutants. California Air Resources Board thresholds force equipment upgrades across the state's furniture manufacturing corridor. Chicago-area refinishing clusters deploy smart fluid monitoring to enforce standard operating procedures across distributed locations.
Germany
OEM collision repair protocols mandate precision film thickness control across Bavarian and Baden-Württemberg workshop clusters. ECHA enforcement on solvent-based formulations under REACH drives replacement cycles for RP and HVLP systems. Stuttgart's automotive refinishing corridor concentrates precision-engineered equipment demand as warranty compliance hardens.
China
Domestic manufacturers in the Yangtze River Delta lack compliant system portfolios as emerging GB standards for VOC emissions reshape automotive refinishing. MEE oversight accelerates equipment replacement windows in Shanghai and Jiangsu province collision repair networks. Shenzhen's contractor segments experiment with battery-operated variants as cordless mobility gains traction.
Japan
Automotive OEM paint shops in the Kanto region demand repeatable trajectory programming as METI industrial standards converge with collaborative robotics integration. JIS certification requirements stratify procurement behavior across Tokyo-Osaka manufacturing corridors. Nagoya's industrial coating clusters prioritize durability specifications for heavy equipment applications.
Italy
Technician productivity pressures in Emilia-Romagna's automotive refinishing clusters coexist with solvent reduction mandates under EU REACH enforcement. Northern Italian machining capabilities concentrate supply for specialized nozzles and air caps. Milan-area workshops favor RP systems where speed requirements balance transfer efficiency compliance.
Paint Spray Guns Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with pneumatic technology leadership. Market positions cluster around three archetypes: precision-engineered automotive specialists, diversified coating equipment conglomerates, and contractor-focused mobility innovators. Capacity expansion in corrosion-resistant alloy machining and strategic partnerships for robotic integration represent dominant competitive moves as regulatory compliance reshapes specifications.
Within the precision-engineered tier, SATA GmbH & Co. KG and Graco Inc. exemplify divergent strategic positions—one anchored in German automotive refinishing specialization, the other representing diversified industrial fluid handling across manufacturing and contractor channels. Exel Industries occupies a position spanning agricultural, industrial, and paint application equipment, illustrating portfolio breadth as a defensive posture against segment-specific regulatory cycles. These three entities represent distinct archetypes: automotive-dedicated engineering, diversified industrial conglomeration, and multi-sector equipment manufacturing.
| Leading Market Players |
|---|
| SATA GmbH & Co. KG |
| Fuji Spray |
| Graco Inc. |
| Exel Industries |
| Wagner SprayTech Corp. |
| Anest Iwata |
| Devilbiss Automotive Refinishing |
| Tritech Industries |
| 3M |
| Others |
Value Network & Pricing Analysis
Nickel futures volatility on the London Metal Exchange cascades through precision-machined component costs, stratifying spray gun pricing tiers between corrosion-resistant HVLP systems for German automotive refinishing and economy-grade alternatives for developing-market contractors. Stainless steel procurement premiums tethered to mining supply constraints in Indonesia and the Philippines compress margins at the mid-market tier while reinforcing premium positioning for alloy-integrated precision manufacturers.
Pricing Analysis
Bundled maintenance subscriptions versus transactional equipment sales split the market into diverging revenue models. Three-tier pricing structure across premium, standard, and economy levels separates SATA and Graco's warranty-integrated offerings from unbranded Asian imports, with certification grade under EU REACH and EPA NESHAP enforcement driving differentiation. Pricing pressure stems from lithium-ion battery cost curves enabling cordless electric variants to undercut pneumatic infrastructure investments. DIY enthusiasts exhibit highest price sensitivity; OEM-affiliated collision networks show lowest due to warranty compliance mandates.
Supply Chain Analysis
China's emerging GB standards for domestic-content ratios in automotive refinishing equipment reshape sourcing patterns for multinational manufacturers. High-tolerance machining capabilities concentrate in southern Germany, northern Italy, and Japan's Aichi prefecture, drawing from nickel-plated brass bar stock and precision ceramic nozzles. Single-source vulnerability clusters around specialized air cap production in Baden-Württemberg. Distribution runs through authorized dealer networks for automotive tiers and direct e-commerce channels for contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between European workshops and Chinese competitors create geographic-arbitrage opportunities for equipment manufacturers with modular certification architectures. German precision engineering premiums sustain against Asian cost advantages where warranty compliance hardens specification authority.
For Market Incumbents: To counter battery-operated electric displacement in contractor segments, incumbents must deepen captive supply of corrosion-resistant alloys through backward integration into German and Italian machining clusters. Certification investment in emerging Chinese GB standards anchors premium positioning before domestic competitors achieve compliant system portfolios. For New Entrants and Emerging Players: Rental service providers represent the most penetrable channel partner type for subscription-based equipment access models targeting North American contractor price sensitivity. White-space targets cluster around robotic integration for automotive OEM paint shops and cordless mobility for Shenzhen's architectural coating segments. Go-to-market execution should prioritize maintenance bundling to reduce capital barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where precision manufacturing capabilities concentrate geographically and regulatory compliance raises fixed-cost thresholds. Long-term viability favors diversified coating equipment conglomerates with pneumatic technology leadership spanning agricultural, industrial, and paint application verticals. Acquisition target archetype: mid-cap specialists with HVLP engineering depth and underexploited battery-electric R&D pipelines. Signal to watch: Chinese MEE enforcement intensity accelerating equipment replacement windows in Yangtze River Delta collision repair networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Machining | Captive supply of nickel-plated brass components insulates against LME volatility in German manufacturing corridors. |
| Battery-Electric Platform Development | Lithium-ion power density improvements enable cordless performance parity with pneumatic systems for contractor mobility. |
| Robotic Integration Partnerships | Collaborative robotics convergence opens automotive OEM paint shop applications requiring repeatable trajectory programming. |
| GB Standard Certification Investment | MEE-aligned equipment portfolios capture replacement windows as Chinese domestic manufacturers lack compliant systems. |
| Rental and Service Model Launch | Subscription-based access with maintenance bundling reduces capital barriers for small North American operators. |
Research Methodology
Bottom-up collision repair and industrial coating modeling reconciled against top-down pneumatic and battery-electric production tracking forms the analytical core of this study. Primary interviews with collision shop operators, I-CAR certification directors, OEM warranty administrators, and aftermarket distributors combined with secondary validation from EPA NESHAP enforcement records, ECHA REACH substance restrictions, and customs trade data on precision-machined component flows. Triangulation across stakeholder inputs and regulatory filings anchors volume estimates.
Input-output matrices map atomization technology adoption to coating chemistry transitions and regulatory compliance thresholds across the projection horizon. Segmentation dimensions span product type, application vertical, end-user capital availability, and power source technology, with CAGRs derived from equipment replacement cycle analysis and regulatory enforcement intensity scoring. Forecast inputs incorporate REACH solvent restriction timelines and lithium-ion cost curve trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese GB standard implementation pacing and battery-electric performance convergence timelines. Forecasts reflect documented assumptions about regulatory enforcement continuity and raw material supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Leather Embossing Machine Market
Tools
Cordless Long Neck Grinder Market
Tools
Global Construction Camera Market
Tools
Welding Products Market
Tools
Wood-Burning Tool Market
Tools
Global DC Torque Tool Market
Tools
Industrial Ladder Market
Tools
Auger Drill Bits Market
Tools
Grinding Machines Market
Tools
Set Screw Market
Tools
Striking Tools Market
Tools
Bottle Jack Market
Tools
Automated Plasma Beveller Market
Tools
Jade Engraving Machines Market
Tools
Metal Forming Tools Market
Tools
Wire Cutters Market