
 Woodworking CNC Tools Market | 2026-2036
Woodworking CNC Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking CNC Tools Market Outlook
The capital-intensity gap between premium tooling specialists and commoditized competitors is collapsing. Leitz GmbH leverages its integrated tungsten carbide production to sustain margin control across high-precision insert lines. Freud Tools anchors North American distribution through dedicated woodworking channel partnerships, while CMT Orange Tools competes on price-performance ratios in the European hobbyist segment.
Woodworking CNC tools are automated machining systems that rotate cutting instruments along multiple axes to shape solid wood, engineered panels, and composite substrates with repeatability tolerances often below 0.05 millimeters. Their primary purpose is to replace manual joinery and template routing with programmable, scalable fabrication for batch sizes ranging from one-off custom pieces to mass furniture production. CNC routers occupy the largest installed base among product types, reflecting their versatility across cabinet, furniture, and millwork applications. Hybrid systems integrating robotic loading arms are expanding fastest in technology terms as manufacturers seek unattended shift operations. Cutting applications command the deepest margin pools due to consumable tooling replacement cycles and precision-grade bit requirements.
OSHA machine guarding standards in the United States and EU machinery directives enforced by national regulators shape product design mandates, particularly for spindle enclosures and emergency stop integration. REACH compliance through ECHA restricts certain coating chemistries on cutting surfaces, pushing suppliers toward ceramic and diamond alternative formulations. Stakeholders must monitor how dual carbon goals in China and evolving EPA wood dust exposure limits recalibrate capital allocation toward filtration-integrated CNC platforms.
Market Dynamics
Automated production lines in Germany and Italy are compressing the capital-intensity gap between premium tooling specialists and commoditized competitors as EU machinery safety directives tighten compliance requirements for industrial cutting equipment.
Growth Catalysts
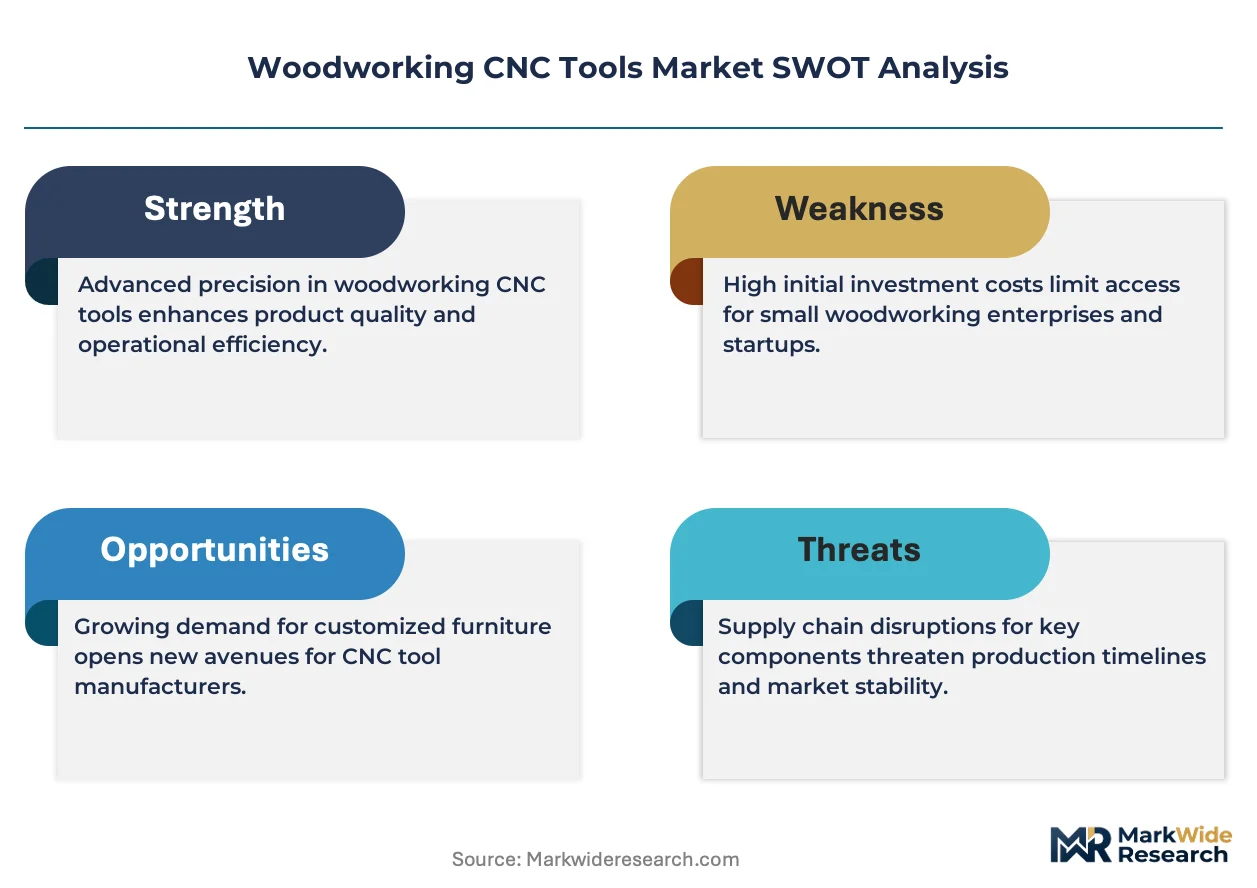
- EU Machinery Directive enforcement:Tighter safety mandates for spindle enclosures and emergency stop integration are forcing furniture manufacturers across Germany and Italy to retrofit facilities with compliant multi-axis systems.
- Guangdong export cluster expansion:Cabinet makers in China's Guangdong province are retrofitting facilities with multi-axis CNC routing systems to serve North American and European contract orders.
- Hybrid robotic integration:Systems combining CNC platforms with robotic loading arms are enabling unattended shift operations as manufacturers pursue continuous production cycles.
Market Restraints
- Tungsten carbide supply concentration:Premium insert production depends on captive supply chains controlled by a narrow base of integrated specialists, creating input vulnerability.
- REACH coating restrictions:ECHA limitations on certain surface chemistries are pushing suppliers toward ceramic and diamond alternatives with higher processing costs.
- Manual joinery substitution ceiling:Artisan furniture segments in Italy and France retain preference for hand-finished components, capping penetration in luxury markets.
Strategic Opportunities
- Filtration-integrated platform demand:Dual carbon goals in China and evolving EPA wood dust exposure limits are recalibrating capital allocation toward CNC systems with built-in extraction.
- North American distribution channel consolidation:Dedicated woodworking channel partnerships offer anchor positions for tooling specialists seeking to bypass commoditized wholesale routes.
- European hobbyist segment price-performance competition:Price-sensitive makers represent an underpenetrated tier between industrial and entry-level equipment categories.
Industry Challenges
- Multi-axis programming talent scarcity:Facilities retrofitting with complex routing systems face shortages of operators capable of CAM programming for five-axis toolpaths.
- Legacy spindle integration complexity:Brownfield installations must reconcile new safety enclosures with existing machine footprints, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking CNC Tools Market |
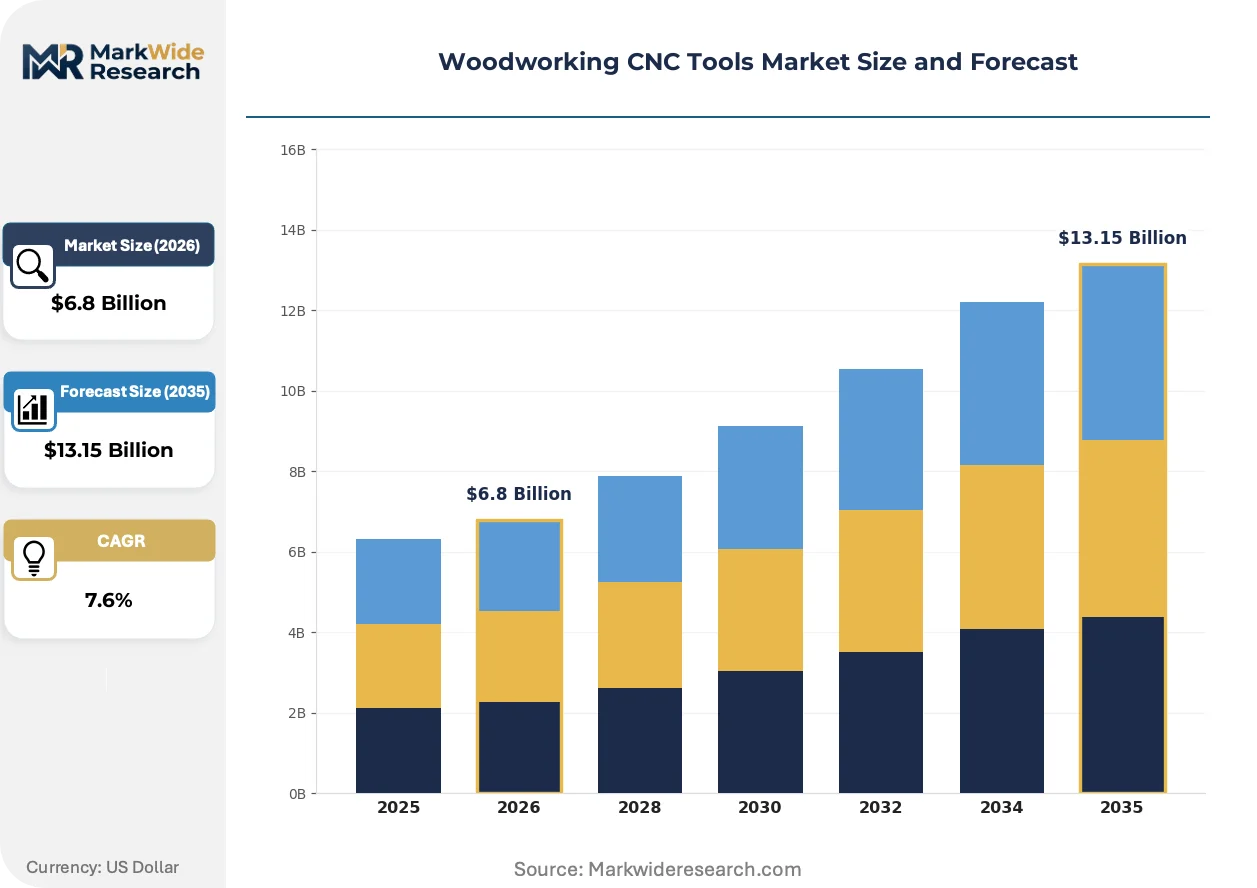
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Routers, CNC Lasers, CNC Mills, CNC Plasma Cutters Technology: Computer Numerical Control, Hybrid Systems, Robotics, Traditional Machine Tools End User: Cabinet Makers, Furniture Manufacturers, Hobbyists, Aerospace Precision Application: Cutting, Drilling, Engraving, Shaping |
| Companies Covered | Leitz GmbH, Amana Tool Corporation, Freud Tools, ONSRUD Cutter, Vortex Tool Company, Dimar Group, Leuco Tool Corporation, CMT Orange Tools, Bosch Rexroth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking CNC Tools Market Strategic Shifts
Tooling technology is converging with environmental compliance and automation architecture, reshaping how manufacturers specify cutting platforms and source consumable inserts.
Diamond-coated cutting surfaces are displacing traditional tungsten carbide in high-wear applications requiring extended tool life between changes. German and Italian cabinet manufacturers are adopting these surfaces fastest for engineered panel processing. This material transition is displacing established resharpening service networks that built revenue on frequent carbide bit replacement cycles.
REACH compliance through ECHA is restricting coating chemistries on cutting surfaces across European supply chains. Industrial tooling manufacturers are reformulating surface treatments to eliminate restricted substances before enforcement deadlines. Cutting applications command the deepest margin pools in this transition because precision-grade bit requirements make coating substitution technically demanding.
After-sales service unbundling is separating tooling supply from maintenance contracts in North American distribution channels. Dedicated woodworking channel partnerships now compete on consumable replacement velocity rather than bundled service agreements. This pattern is most visible in export-oriented cabinet operations serving contract furniture brands with compressed delivery windows.
Woodworking CNC Tools Market Segmentation
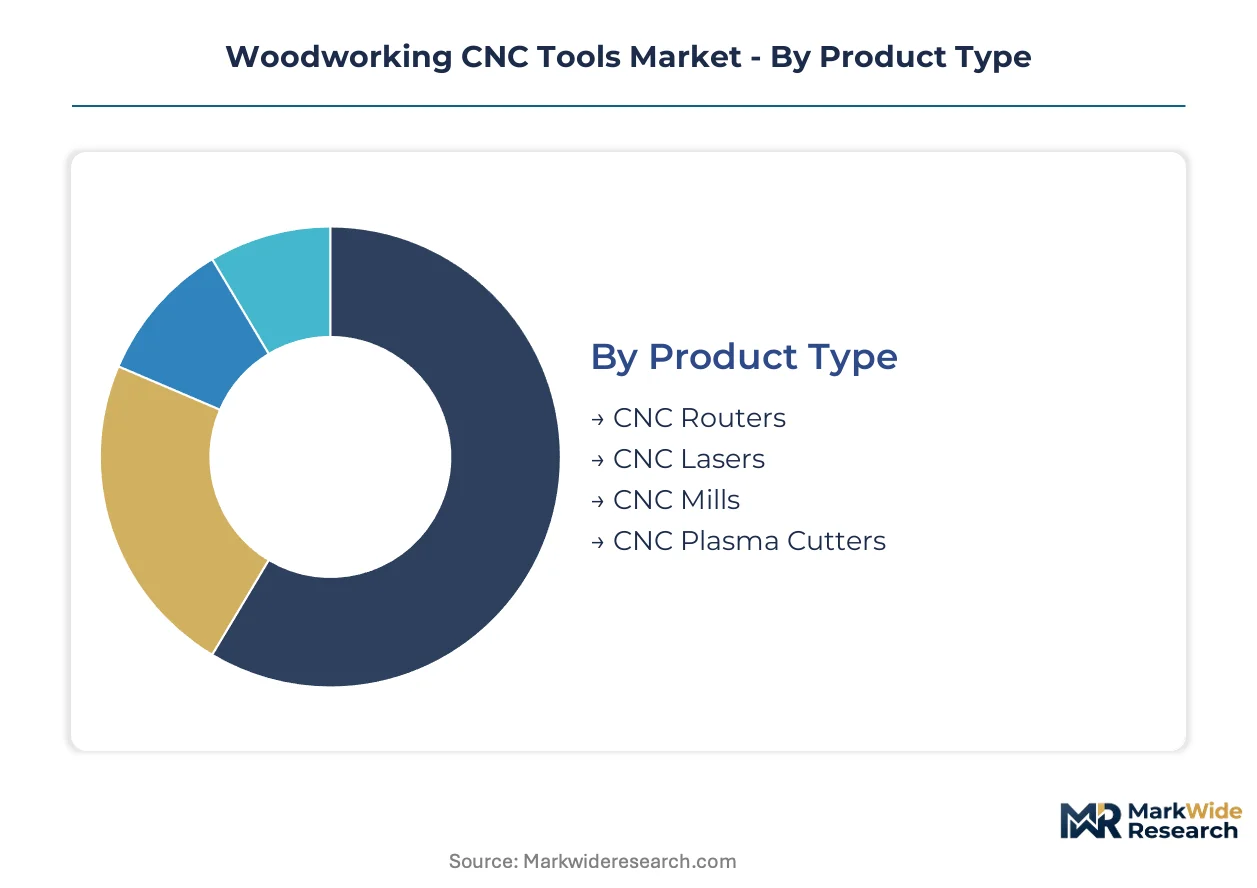
Segmentation in woodworking CNC tools reveals how margin pools concentrate in cutting applications and hybrid automation, while price-performance competition fragments the hobbyist tier. Understanding these divisions clarifies where capital allocation yields defensive positioning versus commoditization risk.
Product Type:
CNC Routers command the deepest margin pools through consumable tooling replacement cycles and precision-grade bit requirements, while CNC Lasers compete on speed and edge quality for engineered panel processing.
- CNC Routers:Multi-axis systems rotate cutting instruments along programmable toolpaths with repeatability tolerances below 0.05 millimeters. Furniture manufacturers across Germany and Italy anchor demand as EU machinery safety directives force retrofitting of legacy manual equipment with enclosed spindle platforms.
- CNC Lasers:CO2 and fiber laser platforms vaporize material along vector paths without mechanical contact, eliminating bit wear. Cabinet makers in China's Guangdong province deploy these systems fastest for export-oriented contract orders requiring clean edge finishes on laminated panels.
- CNC Mills:Rigid gantry structures with high-torque spindles machine hardwoods and aluminum composite materials in single setups.
- CNC Plasma Cutters:Thermal cutting systems process metal fixtures and hardware mounting plates adjacent to wood fabrication workflows.
CNC Routers hold installed capacity. CNC Lasers is rotating up the share rankings.
Technology:
Computer Numerical Control systems dominate volume through proven CAM software ecosystems, though Hybrid Systems are climbing fastest as manufacturers pursue unattended shift operations.
- Computer Numerical Control:Established architectures execute G-code toolpaths through dedicated motion controllers with mature operator training pipelines. Brownfield facilities in Italy and France retain these platforms for artisan furniture segments where hand-finished components still command premium positioning.
- Hybrid Systems:Integrated robotic loading arms transfer workpieces between stations without human intervention. German cabinet manufacturers lead adoption of these platforms to compress cycle times on batch-one contract orders from North American retail brands.
- Robotics:Standalone articulated arms perform material handling, finishing, and quality inspection adjacent to cutting stations.
- Traditional Machine Tools:Manual and semi-automated equipment persists in small-batch custom shops and restoration workshops.
Computer Numerical Control retains the broadest installed base. Hybrid Systems are expanding most quickly through new capacity additions.
End User:
Furniture Manufacturers concentrate capital expenditure in automated lines, while Hobbyists represent an underpenetrated tier between industrial and entry-level equipment categories.
- Furniture Manufacturers:Large-scale producers operate multi-cell CNC departments with centralized programming departments. Facilities across Germany and Italy are retrofitting with compliant multi-axis systems as EU machinery safety directives tighten enforcement timelines.
- Cabinet Makers:Mid-tier fabricators balance batch flexibility with throughput requirements on kitchen and closet contracts. Export-oriented operations in China's Guangdong province anchor regional demand for multi-axis routing systems serving North American and European contract orders.
- Hobbyists:Price-sensitive makers in the European market purchase benchtop and light-industrial equipment through dedicated woodworking channel partnerships.
- Aerospace Precision:Tier-one suppliers machine composite tooling and fixture components to tight tolerances for aircraft interior programs.
Furniture Manufacturers command the largest equipment footprint. Cabinet Makers are rotating up the share rankings through export cluster expansion.
Application:
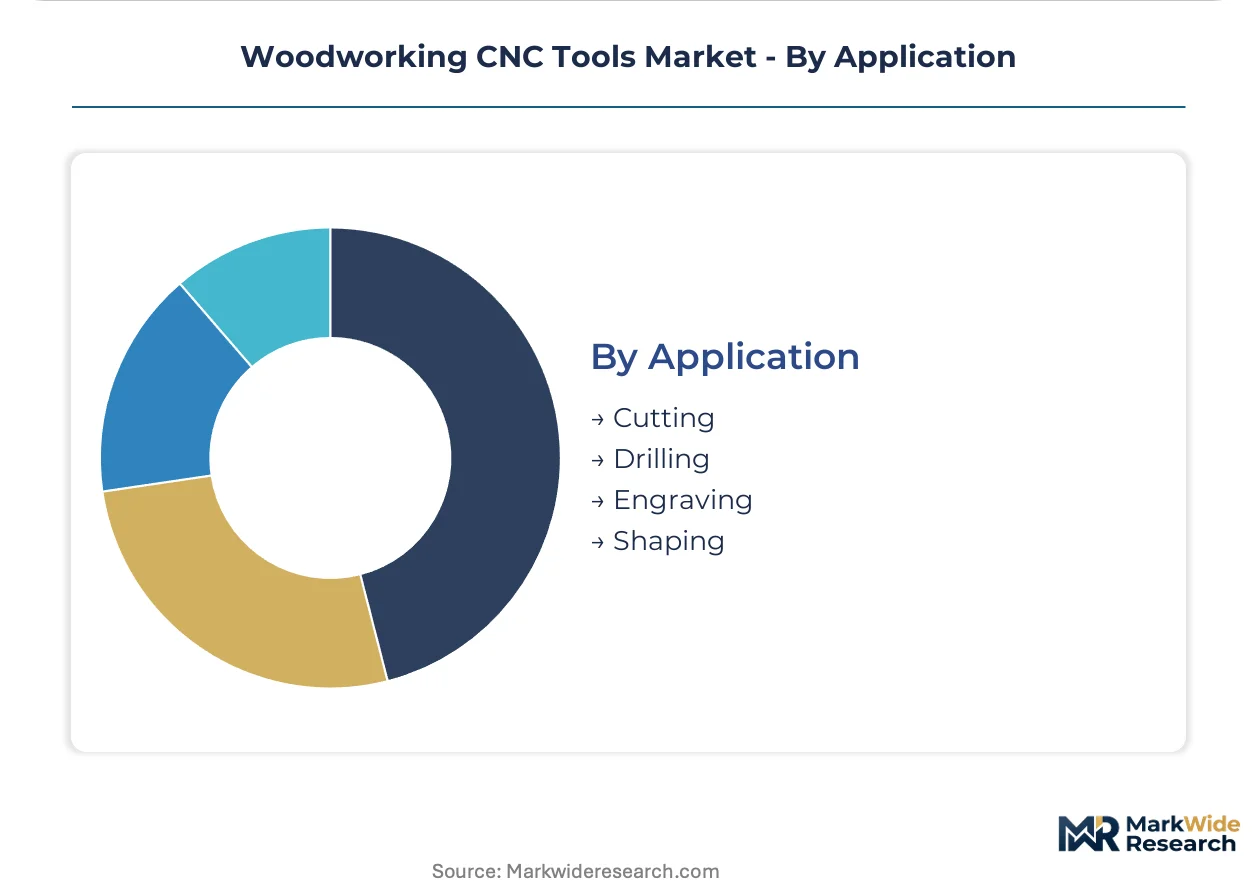
Cutting applications generate the deepest recurring revenue through consumable tooling cycles, while Engraving commands premium positioning in customization workflows.
- Cutting:Profile and contour operations remove material along two-dimensional and three-dimensional paths using end mills, router bits, and saw blades. Diamond-coated cutting surfaces are displacing tungsten carbide fastest in German and Italian engineered panel processing as REACH compliance restricts traditional coating chemistries.
- Engraving:V-bit and ball-nose tools incise decorative patterns, logos, and text at shallow depths with fine detail resolution. North American contract furniture brands specify these capabilities for private-label differentiation on retail display fixtures.
- Drilling:Point-to-point boring heads create dowel, confirmat, and shelf pin holes in panel processing workflows.
- Shaping:Copy milling and turning operations produce curved components for chair backs, table legs, and handrail profiles.
Cutting holds installed capacity. Engraving is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Italian precision tooling while Chinese manufacturers compete on throughput scale for export contract work.
Germany
Furniture manufacturers across Baden-Württemberg and Bavaria are retrofitting automated production lines with multi-axis CNC routing systems. EU machinery safety directives enforced by national regulators mandate tighter spindle enclosure and emergency stop integration standards. The Black Forest cluster anchors demand for diamond-coated cutting surfaces in engineered panel processing.
Italy
Cabinet makers in Lombardy and Veneto balance artisan hand-finishing traditions with automated batch production for North American retail contracts. REACH compliance through ECHA restricts coating chemistries on cutting surfaces, pushing suppliers toward ceramic alternatives. The Brianza furniture district concentrates retrofit activity as manufacturers seek unattended shift operations.
China
Export-oriented cabinet operations in Guangdong province are retrofitting facilities with multi-axis CNC routing systems to serve European and North American contract orders. Dual carbon goals enforced by MEE recalibrate capital allocation toward filtration-integrated CNC platforms. The Pearl River Delta cluster leads adoption of hybrid systems combining robotic loading arms with routing platforms.
United States
Contract furniture brands specify engraving capabilities for private-label differentiation on retail display fixtures. OSHA machine guarding standards shape product design mandates for spindle enclosures and emergency stop integration. North Carolina and Indiana furniture manufacturing corridors anchor demand for dedicated woodworking channel partnerships.
Japan
Precision component fabricators serve aircraft interior programs with tight-tolerance composite tooling requirements. METI industrial standards govern motion controller specifications for multi-axis systems. The Aichi prefecture manufacturing belt concentrates demand for rigid gantry structures with high-torque spindles.
Woodworking CNC Tools Market Competitive Environment
Concentration sits with integrated tungsten carbide producers and dedicated woodworking channel specialists. The vendor base spans three tiers: captive raw material producers controlling insert supply chains, distribution-anchored brands with North American woodworking channel partnerships, and price-performance competitors serving European hobbyist segments. Strategic moves center on backward integration into carbide production and geographic expansion through dedicated regional distributors.
Among German-based integrated specialists, Leitz GmbH and Leuco Tool Corporation exemplify the captive supply chain archetype through in-house tungsten carbide production. Freud Tools anchors North American positioning through woodworking channel partnerships, while CMT Orange Tools occupies the European hobbyist tier. These three company structures represent the dominant competitive vectors: raw material control, distribution anchoring, and price-performance segmentation.
| Leading Market Players |
|---|
| Leitz GmbH |
| Amana Tool Corporation |
| Freud Tools |
| ONSRUD Cutter |
| Vortex Tool Company |
| Dimar Group |
| Leuco Tool Corporation |
| CMT Orange Tools |
| Bosch Rexroth |
| Others |
Value Chain & Pricing Dynamics
Ninety-day tungsten carbide insert inventories sit at German integrated specialists, compressing pricing power for commoditized competitors while amplifying margin control for captive producers. This lead-time concentration shapes how tooling manufacturers allocate capital between premium precision lines and price-competitive hobbyist tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order multi-axis systems from standard three-axis platforms by roughly thirty to fifty percent. Contract-based long-term offtake dominates industrial procurement, with price differentiation driven by ISO 19085 certification tier and after-sales service bundling. Cost compression in the European hobbyist tier intensifies because CMT Orange Tools and similar competitors compete on volume scale without captive carbide supply. Cabinet makers in Guangdong province show highest price sensitivity, while German furniture manufacturers anchored in Baden-Württemberg prioritize precision-grade specifications over unit economics.
Supply Chain Analysis
Germany and China anchor tungsten carbide insert production, with Austria and Japan contributing specialized diamond-coating capabilities. Raw material dependencies center on tungsten ore concentrates, cobalt powder binders, and synthetic diamond substrates. Single-source vulnerability concentrates in Chinese rare earth processing for high-performance magnet materials in spindle motors. Distribution runs through dedicated woodworking channel partnerships in North America, while European routes favor direct technical sales to industrial fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-axis CAM programming talent shortages constrain how quickly facilities absorb new automation capacity, creating a capability-scarcity environment where specialized training providers and captive apprenticeship programs determine competitive speed.
For Market Incumbents: Shield margin pools in precision insert lines by deepening backward integration into tungsten carbide production before REACH coating restrictions fully displace traditional chemistries. Accelerate certification investment in ISO 19085-compliant spindle enclosures to capture retrofit demand from Italian and German manufacturers facing EU Machinery Directive enforcement timelines. Channel control through dedicated woodworking partnerships offers defensive positioning against price-performance competitors. For New Entrants and Emerging Players: After-sales service unbundling in North American distribution channels represents the most penetrable white-space target, where incumbents still bundle maintenance contracts with consumable supply. Target mid-tier cabinet makers in China's Guangdong export cluster with filtration-integrated platform offerings that address dual carbon goals without requiring full hybrid robotic investment. A technical training partnership go-to-market angle accelerates adoption by resolving the CAM programming bottleneck directly. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with under-optimized tooling divisions lacking captive carbide supply or dedicated woodworking channel access. Long-term viability favors integrated specialists controlling raw material through precision finishing, with five-to-ten year windows rewarding upstream consolidation. Watch diamond-coating adoption rates in German engineered panel processing as the inflection signal for material transition tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Production | Captive tungsten supply insulates margin control against raw material volatility and REACH substitution costs. |
| Hybrid Robotic System Deployment | Unattended shift operations compress cycle times for batch-one contract orders from North American retail brands. |
| Filtration-Integrated Platform Development | Dual carbon goals in China and EPA wood dust limits recalibrate capital allocation toward extraction-embedded systems. |
| CAM Programming Training Ecosystem | Multi-axis talent scarcity limits absorption speed; proprietary training pipelines accelerate customer commissioning timelines. |
| Dedicated Woodworking Channel Partnership | North American distribution consolidation favors tooling specialists bypassing commoditized wholesale routes. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across the woodworking CNC tools value chain, including plant engineers at German and Italian furniture manufacturers, procurement leads at Guangdong export-oriented cabinet operations, aftermarket service heads at North American distribution partners, and technical R&D directors at integrated tooling specialists. Secondary validation drew from EU Machinery Directive enforcement notices, ECHA REACH restriction updates, OSHA machine guarding standard revisions, and customs trade data for tungsten carbide insert flows. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure surveys from woodworking industry associations.
Across the analysis window, the analytical framework modeled volume and value outputs through segmentation dimensions spanning product type, technology architecture, end-user scale tier, and application intensity. CAGRs derived from historical installation base growth rates, replacement cycle compression, and technology substitution curves. Industry-specific forecast inputs included EU machinery safety directive compliance deadlines and Chinese dual carbon enforcement trajectories from MEE.
Underlying assumptions cover continued REACH coating restriction enforcement and stable tungsten ore supply conditions, with deviation risk concentrated in tariff exposure on Chinese-manufactured spindle components and accelerated diamond-coating cost reduction curves. Recalibration cycles align with material shifts in EU regulatory enforcement timelines and MEE environmental policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Workholding Tools Market
Tools
Gas Cutting Machine Market
Tools
Global Table Saws Market
Tools
Rocket Wrench Market
Tools
Horizontal Milling Machine Market
Tools
Global Protractor Market
Tools
GCC Machine Tools Market
Tools
Measuring Wheels Market
Tools
Woodpecker Tools Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Engraver Machine Market
Tools
Global Tool Holder Adapters Market
Tools
Hacksaw Blades Market
Tools
US Power Tools Market
Tools
Dumpy Level Market
Tools
Digital Cutting Machine Market