
 Rotary Hammer Drill Market | 2026-2036
Rotary Hammer Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Rotary Hammer Drill Market Outlook
Multi-source motor procurement is decoupling from traditional single-factory dependency as brands diversify electromechanical supply chains across Southeast Asia and Eastern Europe. Robert Bosch GmbH leverages in-house magnet production to sustain margin control on cordless drive systems. Makita Corporation anchors its competitive stance through dense distributor networks across North American metropolitan construction corridors. Hilti AG differentiates via fleet-management subscriptions that embed tool-tracking software directly into contractor workflows.
A rotary hammer drill combines percussive impact mechanism with rotary motion to fracture concrete, masonry, and mineral substrates through hardened carbide-tipped bits operating at 1,500–4,500 blows per minute. The tool's primary industrial purpose centers on anchor-hole drilling, rebar installation, and controlled demolition in reinforced structures where standard rotary drills lack sufficient impact energy. Cordless configurations now lead product-type revenue pools as battery platforms above 18V match corded performance in medium-duty applications. Construction application demand dominates volume while mining represents the fastest-growing segment as underground mechanization expands in copper and lithium extraction zones.
OSHA silica exposure limits and the EU Machinery Directive compel manufacturers to integrate active dust-collection ports and vibration-dampening handles as baseline compliance features. China's GB standards for power-tool electromagnetic compatibility add certification complexity for imported cordless platforms seeking SAMR market access. Stakeholders must monitor battery-platform interoperability wars and evolving dust-extraction mandates as procurement criteria shift from purchase price toward total cost of compliance ownership.
Market Dynamics
Electrification of construction equipment fleets is compressing demand timelines for cordless rotary hammer platforms as lithium-ion energy density thresholds breach 300 Wh/kg, enabling full corded-equipment displacement in medium-duty concrete drilling applications.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants in pneumatic tool cooling systems accelerates contractor migration toward battery-electric alternatives in German and French metropolitan construction corridors.
- Copper extraction mechanization:Underground mining automation in Chilean and Peruvian lithium-copper belts generates demand for dust-sealed rotary hammer configurations rated for continuous-duty rebar installation.
- SAMR electromagnetic compatibility certification:China's GB standards for cordless power-tool RF emissions create compliance moats that favor established battery-platform ecosystems over fragmented import competition.
Market Restraints
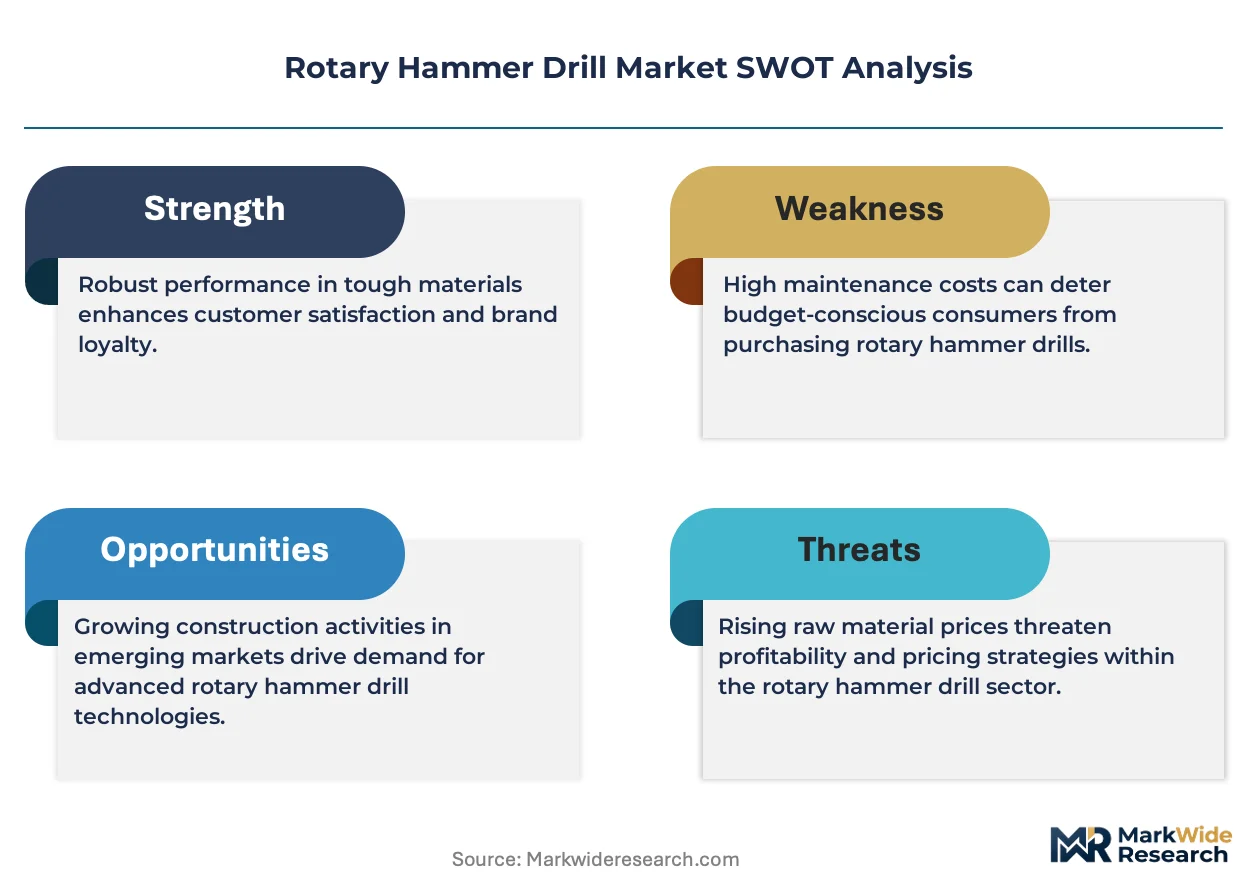
- Neodymium supply concentration:Rare-earth magnet procurement dependency on Chinese processing facilities exposes brushless motor production to export quota volatility and tariff friction.
- Silica exposure compliance costs:OSHA permissible exposure limits for respirable crystalline silica mandate active dust-collection systems that add 15-25% to tool bill-of-materials.
- Pneumatic tool residual preference:Heavy-duty demolition contractors in infrastructure renovation segments retain compressed-air equipment for sustained high-torque applications where battery thermal management limits duty cycles.
Strategic Opportunities
- India PLI scheme for advanced cell chemistry:Domestic battery manufacturing incentives enable localized cordless platform assembly serving South Asian infrastructure build-out.
- Fleet-management software integration:Tool-tracking telemetry embedded in contractor workflows creates recurring revenue streams and locks in platform loyalty through usage-based service models.
- MEA construction acceleration:Saudi giga-project pipeline and UAE commercial tower cycles generate concentrated demand for high-durability rotary hammer configurations rated for desert thermal conditions.
Industry Challenges
- Brushless motor controller firmware certification:Functional safety validation under EU Machinery Directive Annex IV extends product development timelines by 8-14 months for new cordless platform launches.
- Cross-platform battery interoperability:Proprietary cell form factors and communication protocols fragment contractor fleets, forcing rental houses to maintain redundant charger inventories across competing ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotary Hammer Drill Market |
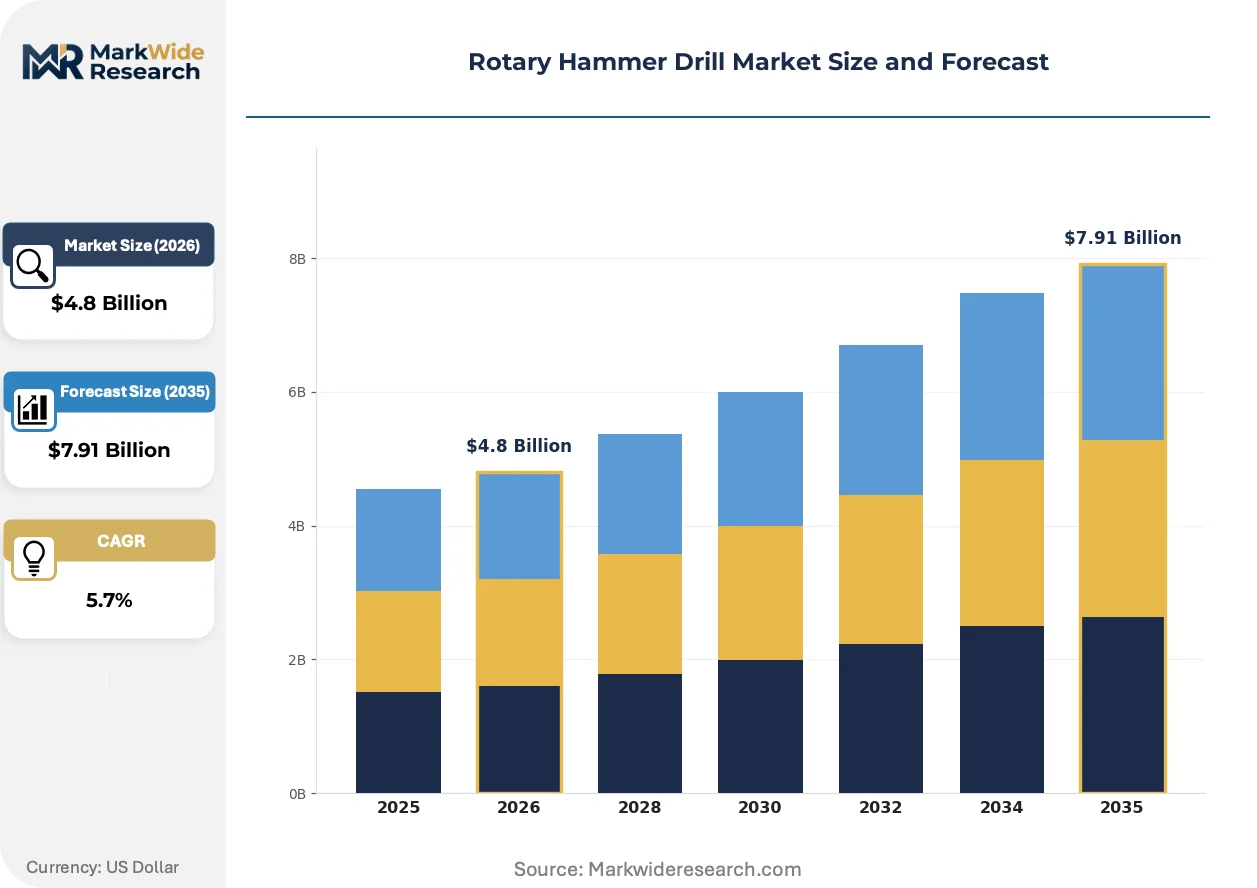
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Pneumatic, Electric Application: Construction, Demolition, Renovation, Mining End User: Contractors, DIY Enthusiasts, Industrial Users, Maintenance Services Drill Size: Small, Medium, Large, Heavy-Duty |
| Companies Covered | Hilti AG, Koki Holdings Co. Ltd., Robert Bosch GmbH, C. & E. Fein GmbH, Metabowerke GmbH, Stanley Black & Decker, Techtronic Industries Co. Ltd., Atlas Copco AB, Makita Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotary Hammer Drill Market Strategic Shifts
Active vibration suppression and dust-extraction integration are redefining baseline product specifications as regulatory exposure limits tighten and contractor injury liability costs escalate across developed markets.
Brushless electronically commutated motors are consolidating rotary hammer drive architectures by eliminating carbon brush maintenance intervals and enabling closed-loop torque control for masonry substrate sensing. German and Japanese construction contractors are specifying brushless platforms for 80% of new cordless fleet acquisitions. The technology is consolidating supplier tiers as in-house magnet winding and controller firmware development become mandatory capabilities for tier-one participation.
EPA emissions guidelines for construction equipment are compelling rental fleet operators to accelerate electric tool substitution in non-attainment zones, particularly California and Texas urban corridors. The regulatory pressure is compressing resale values for gasoline-powered demolition equipment and redirecting capex toward battery-platform standardization. Cordless rotary hammer categories in these states now command procurement preference in municipal infrastructure tenders.
Contractor purchasing departments are unbundling tool acquisition from aftermarket service, forcing manufacturers to compete on transparent parts-availability metrics and depot-repair turnaround guarantees. Independent rental houses in North American metropolitan construction corridors are disintermediating traditional distributor relationships through direct factory procurement portals. This behavioral shift concentrates volume with platforms offering open API integration for fleet management software.
Rotary Hammer Drill Market Segmentation
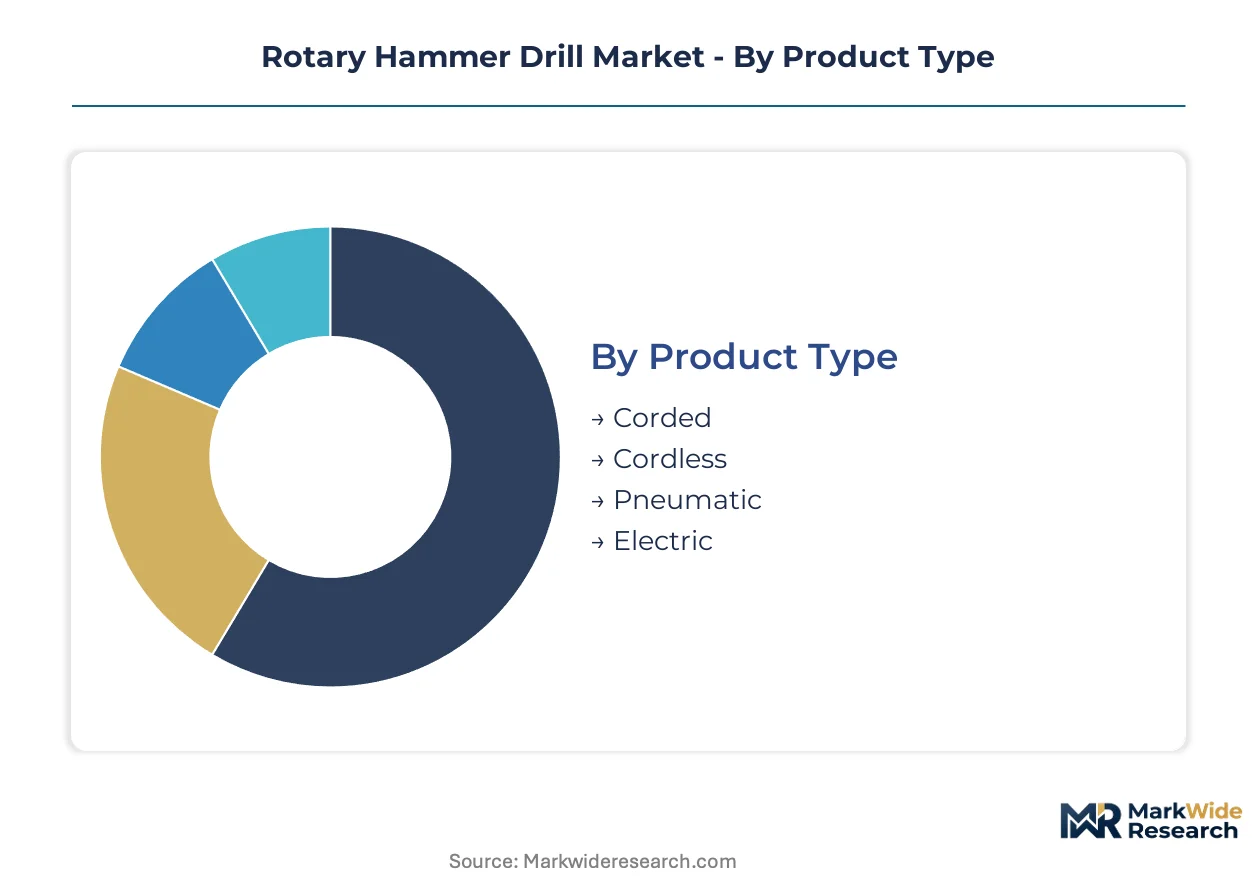
Rotary hammer drill procurement decisions diverge sharply across user workflows, power infrastructure, and substrate hardness requirements. Understanding these segment boundaries clarifies where battery-platform investments concentrate versus where pneumatic legacy equipment retains durable preference.
Product Type:
Contractor fleet electrification timelines hinge on energy density thresholds and thermal management capabilities across power delivery architectures.
- Corded:Sustained high-torque output from grid-connected AC motors serves heavy-duty concrete demolition where uninterrupted duty cycles exceed 45 minutes. German infrastructure renovators specify corded platforms for bridge deck rehabilitation requiring continuous rebar extraction.
- Cordless:Lithium-ion platforms above 18V now match corded impact energy in medium-duty anchor-hole drilling through brushless motor efficiency gains. North American metropolitan contractors are consolidating cordless fleets as OSHA silica compliance mandates active dust-collection portability.
- Pneumatic:Compressed-air drive systems deliver sustained impact without battery thermal derating in mining tunneling applications.
- Electric:AC-powered alternatives bridge corded performance with generator flexibility for remote construction sites lacking permanent grid access.
Corded leads on scale; cordless leads on momentum.
Application:
Substrate hardness and structural load requirements dictate tool specification tiers across vertical construction workflows.
- Construction:Anchor-hole drilling and rebar installation in reinforced concrete frames demand carbide-tipped bits rated for 4,500 blows per minute. Chinese coastal provinces concentrate volume as infrastructure renovation cycles accelerate in Shenzhen and Shanghai metropolitan corridors.
- Demolition:Controlled fracturing of load-bearing walls and foundation removal requires high-impact energy sustained across extended duty cycles. Chilean copper extraction mechanization is expanding demand for dust-sealed configurations in underground rebar cutting.
- Renovation:Precision drilling in existing structures with embedded utilities demands vibration-dampened handles and active dust extraction.
- Mining:Underground lithium and copper belt mechanization in Peru and Chile generates the steepest expansion trajectory for continuous-duty rotary hammer deployment.
Construction dominates volume; mining climbs fastest.
End User:
Procurement authority and total cost of ownership calculations vary fundamentally across organizational scale and equipment utilization intensity.
- Contractors:Fleet-standardization decisions by German and US construction firms concentrate cordless platform adoption as lithium-ion energy density improves.
- DIY Enthusiasts:Home improvement retailers in North American suburbs stock compact cordless configurations for residential anchor and fixture installation.
- Industrial Users:Mining operators and petrochemical maintenance departments specify heavy-duty pneumatic or high-voltage cordless platforms for hazardous environment certification.
- Maintenance Services:Facility management contractors prioritize tool-tracking telemetry integration for usage-based service model participation.
Contractors anchor revenue concentration; industrial users drive specification escalation.
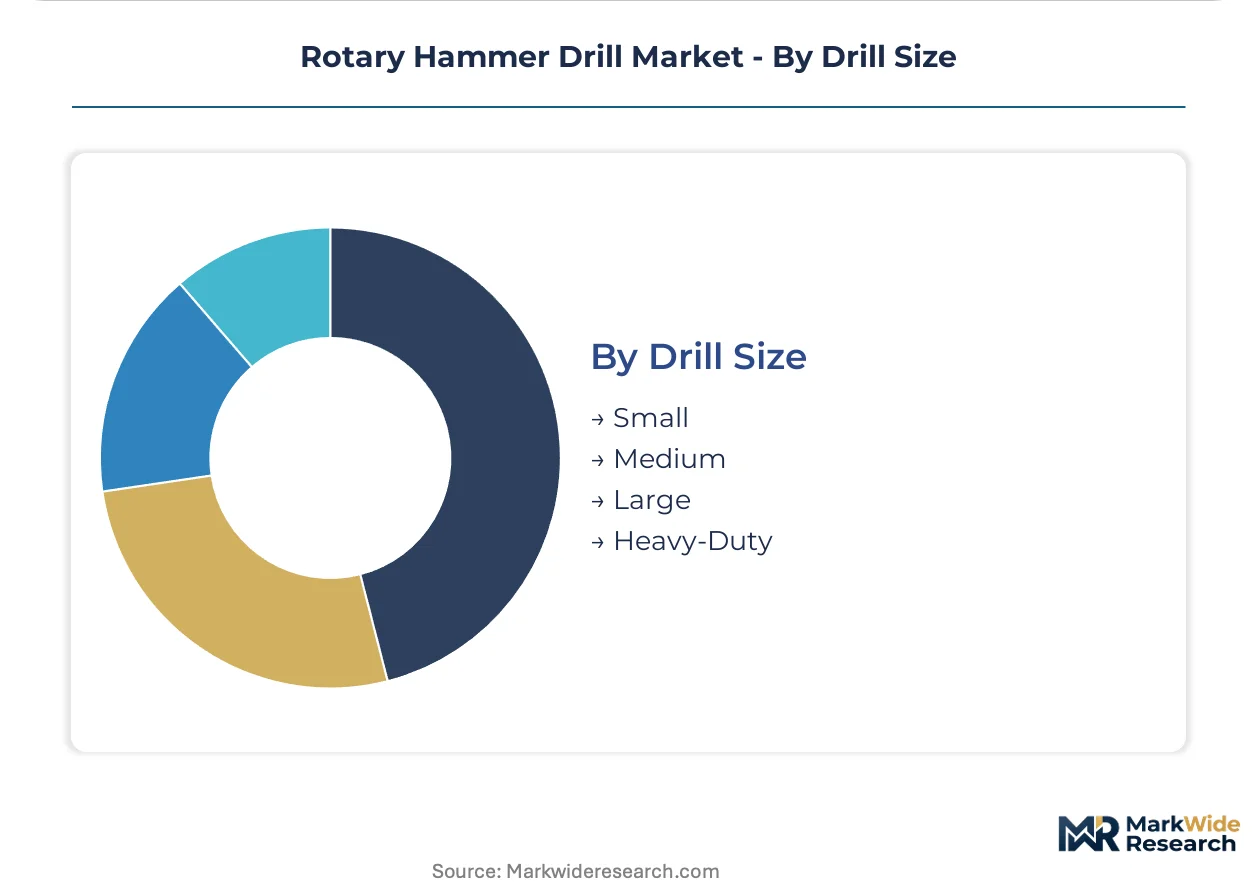
Drill Size:
Bit diameter capacity and impact energy output scale directly with tool mass and operator fatigue management requirements.
- Small:Compact form factors under 3 kg enable overhead drilling and confined-space anchor installation in commercial interior fit-outs.
- Medium:20-28 mm concrete drilling capacity serves general construction framing and mechanical installation across North American metropolitan corridors.
- Large:Sustained 32-40 mm drilling in reinforced structural elements requires active vibration suppression for OSHA compliance.
- Heavy-Duty:50 mm+ capacity for foundation demolition and mining tunneling retains pneumatic preference where battery thermal limits constrain duty cycles.
Medium sizes capture highest shipment volumes; heavy-duty commands premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration patterns trace cost-of-compliance gaps between jurisdictions with tightening silica exposure mandates and regions where cordless platform assembly faces lighter certification burdens. Manufacturers are relocating final assembly to capture these arbitrage windows while maintaining magnet and controller sourcing from established supply corridors.
Germany
Fleet electrification by Hochtief and STRABAG concentrates cordless procurement in metropolitan construction corridors. The EU F-Gas Regulation accelerates phase-down of hydrofluorocarbon-cooled pneumatic systems. North Rhine-Westphalia industrial clusters host brushless motor controller development for export-platform compatibility.
United States
OSHA silica exposure limits compel active dust-collection integration in municipal infrastructure tenders. EPA emissions guidelines compress resale values for gasoline-powered demolition equipment in California and Texas urban corridors. Metropolitan contractors in Chicago and Dallas-Fort Worth consolidate cordless standardization.
China
GB standards for electromagnetic compatibility create certification moats favoring established battery-platform ecosystems. SAMR market access requirements fragment import competition for cordless platforms. Coastal manufacturing provinces in Guangdong and Jiangsu accelerate infrastructure renovation cycles with state-funded equipment refresh programs.
India
PLI scheme incentives for advanced cell chemistry enable localized cordless platform assembly serving South Asian infrastructure build-out. Bureau of Indian Safety certification timelines extend for imported brushless motor controllers. Maharashtra and Gujarat industrial corridors concentrate domestic battery pack integration capacity.
Saudi Arabia
Giga-project pipeline generates concentrated demand for high-durability rotary hammer configurations rated for desert thermal conditions. SFDA equipment safety certification aligns with EU Machinery Directive Annex IV for imported platforms. Riyadh and Eastern Province construction clusters specify dust-sealed configurations for continuous-duty rebar installation.
Rotary Hammer Drill Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue fleet-management software integration and battery-platform interoperability niches. The vendor base stratifies across three tiers: integrated manufacturers with captive magnet supply, distributor-anchored brands with dense metropolitan networks, and subscription-model specialists embedding telemetry into contractor workflows. Strategic moves concentrate on backward integration into rare-earth magnet winding and geographic expansion through direct procurement portals disintermediating traditional distribution.
Among European integrated manufacturers, Robert Bosch GmbH and Hilti AG exemplify divergent archetypes. Bosch leverages in-house magnet production to sustain margin control on cordless drive systems. Hilti occupies a position within the subscription-service tier through fleet-management offerings that embed tool-tracking software directly into contractor workflows. Makita Corporation anchors the distributor-network archetype across North American metropolitan construction corridors. These three entities represent the dominant competitive vectors: captive supply chain control, recurring revenue service models, and dense channel presence.
| Leading Market Players |
|---|
| Hilti AG |
| Koki Holdings Co. Ltd. |
| Robert Bosch GmbH |
| C. & E. Fein GmbH |
| Metabowerke GmbH |
| Stanley Black & Decker |
| Techtronic Industries Co. Ltd. |
| Atlas Copco AB |
| Makita Corporation |
| Others |
Value Chain & Pricing Dynamics
Contractor fleet-standardization mandates in Germany and the United States are compressing procurement timelines for cordless platforms, forcing suppliers to absorb rare-earth magnet cost volatility while maintaining price competitiveness against pneumatic alternatives. This demand-side consolidation is reshaping how manufacturers negotiate magnet procurement contracts and allocate controller firmware development budgets across product tiers.
Pricing Analysis
Input-cost pass-through from neodymium magnet procurement dominates pricing dynamics for brushless motor configurations, with manufacturers partially absorbing volatility to preserve platform loyalty. Three-tier pricing structure across premium, standard, and economy levels separates Hilti-style subscription-bundled offerings from transactional distributor sales and private-label imports. Pricing pressure stems from silica-compliance hardware mandates that add bill-of-materials costs without commensurate feature premiums. DIY enthusiasts through home improvement retailers exhibit highest price sensitivity, while mining operators prioritize dust-sealed certification over unit cost.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and brushless motor controller remanufacturing are emerging as cost centers as warranty periods extend and fleet-management telemetry tracks component degradation. Magnet winding and rare-earth processing concentrates in China, with controller assembly migrating to Vietnam and Poland for tariff arbitrage. Brushless motor production draws from neodymium-iron-boron magnet supply, lithium-ion cell imports, and injection-molded housing polymers. Single-source vulnerability in Chinese rare-earth export quotas exposes margin compression during quota tightening cycles. Distribution runs through distributor-anchored metropolitan construction corridors and direct procurement portals serving rental house consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rotary hammer drill market functions as a stable compounder anchored by infrastructure renovation cycles and regulatory displacement of pneumatic equipment in developed economies.
For Market Incumbents: To counter proprietary battery-platform fragmentation eroding fleet-standardization advantages, prioritize backward integration into magnet winding capacity in Vietnam or Poland, and accelerate functional safety certification under EU Machinery Directive Annex IV to extend compliance moats against Asian imports. For New Entrants and Emerging Players: Independent rental houses in North American metropolitan corridors represent the most penetrable buyer archetype, with fleet-management software integration and open API telemetry offering disintermediation leverage against established distributor relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with brushless motor controller specialists possessing SAMR electromagnetic compatibility pre-certification and established relationships with Chinese lithium-ion cell manufacturers, with long-term viability hinging on battery-platform interoperability wars resolving toward open standards rather than proprietary lock-in.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Winding | Captive neodymium supply insulates Bosch-style margin control from Chinese export quota volatility. |
| Fleet-Management Software Platform Launch | Hilti-style subscription embedding creates recurring revenue and locks contractor loyalty through usage-based telemetry. |
| EU Machinery Directive Annex IV Certification Investment | Functional safety validation extends development timelines but creates compliance moats against uncertified competitors. |
| Direct Procurement Portal Development | Factory-direct channels disintermediate distributors and capture rental house consolidation volume in Dallas-Fort Worth corridors. |
| Desert Thermal Rating Certification | SFDA-aligned durability specifications open Saudi giga-project pipeline and UAE commercial tower procurement. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at German infrastructure contractors, fleet managers at North American rental houses, procurement leads at Chilean mining operators, and aftermarket service heads at distributor networks with secondary validation against SEC filings from listed tool manufacturers, OSHA silica enforcement databases, EU F-Gas Regulation implementation reports, and SAMR electromagnetic compatibility certification registries. Bottom-up shipment data triangulated against top-down construction equipment capex disclosures.
Segment-weighting across product type, application, end user, drill size, and regional regulatory cluster shaped the analytical framework, with CAGRs derived from fitted growth curves against lithium-ion energy density improvement trajectories and infrastructure renovation cycle timing. Forecast inputs incorporated brushless motor adoption rates in metropolitan contractor fleets and pneumatic equipment phase-down timelines under EU F-Gas Regulation mandates.
Underlying measurement precision varies by segment; cordless platform shipment data carries tighter precision than pneumatic mining configurations where informal procurement channels dominate. Forecasts reflect assumptions about battery thermal management thresholds and rare-earth export quota stability. Practitioners should monitor SAMR certification timeline extensions and OSHA silica enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Power Drill Market
Tools
Cordless Wood Planer Market
Tools
Impact Sockets Market
Tools
Fiber Laser Cutting Machines Market
Tools
Gas Cutting Machine Market
Tools
Europe Paint Spray Guns Market
Tools
Workholding Tools Market
Tools
Friction Washer Market
Tools
Portable Rolling Toolbox Market
Tools
Self-Clinching Fasteners Market
Tools
Machining Centers Market
Tools
Metal Cutting Tools Market
Tools
Global Tool Holder Adapters Market
Tools
Edge Bending Machine Market
Tools
Bandsaw Machines Market
Tools
Europe Machine Tools Market