

Cordless Bandsaw Sander Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Bandsaw Sander Market Insights
Lithium-ion battery cell chemistry is broadening the power-to-weight envelope for cordless bandsaw sanders, enabling sustained cutting and sanding cycles that previously required corded units. Milwaukee Tool leverages vertical integration in brushless motor design to control thermal performance across heavy-duty applications. Bosch Power Tools sustains R&D intensity in compact drivetrain architectures that reduce tool footprint without sacrificing blade speed. Festool specializes in dust extraction integration, commanding premium positioning among European woodworking professionals.
A cordless bandsaw sander combines a continuous loop blade with an integrated abrasive surface, typically driven by a brushless motor powered by 18V to 36V lithium-ion battery packs, designed for portable cutting and finishing of metal stock, timber, and composite materials in field and workshop environments. Portable bandsaw sanders dominate volume as mechanical workshops prioritize mobility between job sites, while industrial bandsaw sanders capture concentrated margin pools in fixed metal fabrication lines where sustained duty cycles justify higher capital outlay. Brushless motor technology leads technology segmentation due to efficiency gains and reduced maintenance intervals, with variable speed control gaining traction among prototype developers who machine diverse material densities.
The Occupational Safety and Health Administration sets airborne particulate exposure limits that shape dust collection specifications for cordless bandsaw sanders sold into US mechanical workshops, while the EU Machinery Directive mandates CE conformity assessment for emergency stop functionality and blade guarding. ISO 28927 standards for hand-held power tools further harmonize vibration emission testing protocols that manufacturers must document for professional channel access. Stakeholders should monitor battery platform consolidation trends and regulatory alignment between North American and European safety requirements when allocating product development resources.
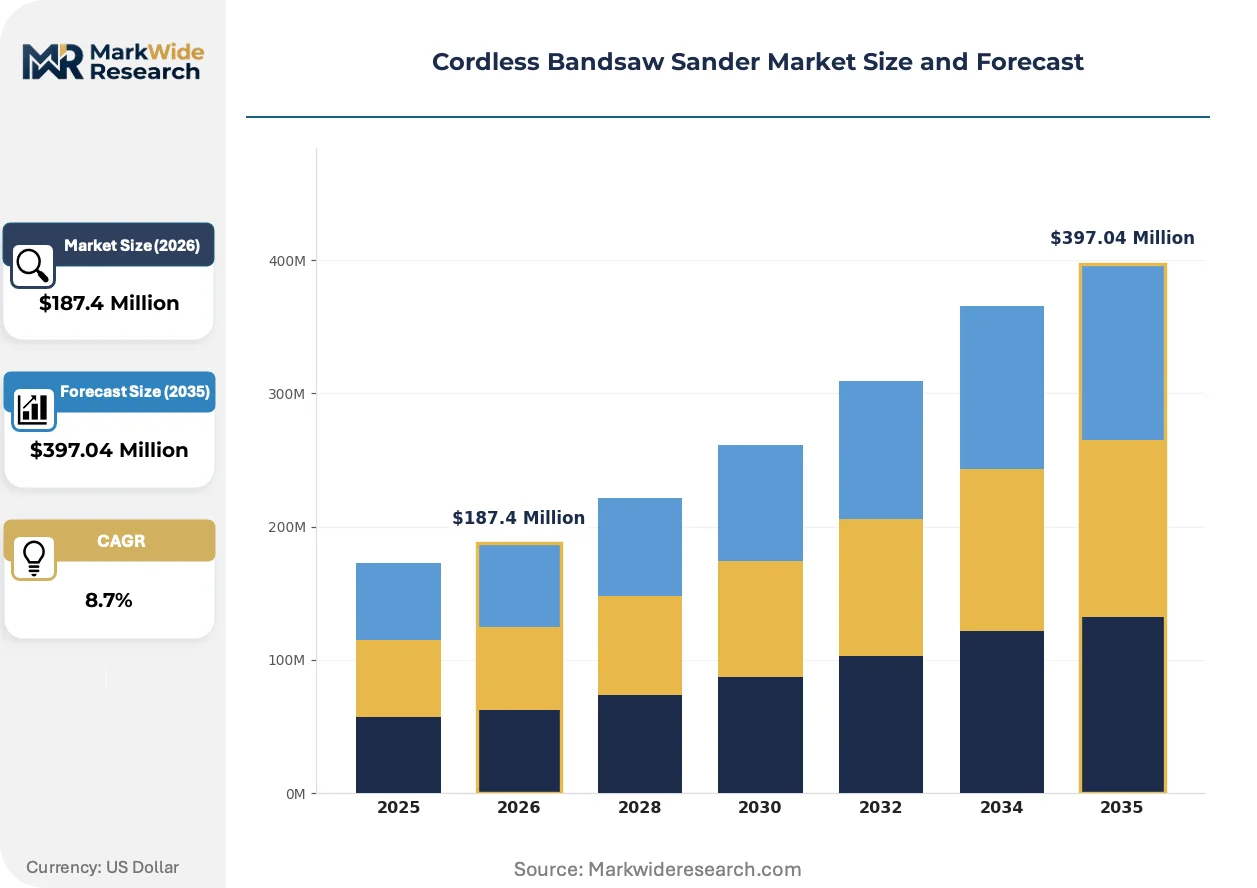
Market Dynamics
Battery platform consolidation among professional tool manufacturers is compressing compatibility fragmentation, forcing cordless bandsaw sander producers to align motor electronics and pack geometries with dominant 18V and 36V ecosystems or risk channel exclusion.
Growth Catalysts
- OSHA Particulate Standards:Tightened airborne dust exposure limits in US mechanical workshops are mandating integrated dust extraction, expanding specification requirements for cordless units with onboard collection systems.
- Lithium-Ion Energy Density Gains:Cell chemistry improvements are extending runtime per charge, enabling cordless bandsaw sanders to displace corded units in sustained metal cutting applications previously requiring fixed power.
- Metal Fabrication Mobility:German and Japanese job-site workflows prioritize setup-time reduction, pulling demand toward cordless platforms that eliminate extension cord management and power source proximity constraints.
Market Restraints
- Battery Pack Cost Concentration:Lithium carbonate and nickel supply volatility concentrates in Chinese cathode processing, inflating pack replacement costs and compressing margin structures for mid-tier manufacturers.
- Brushless Motor Patent Thickets:Thermal management and field-oriented control IP held by Japanese and German motor specialists creates licensing friction for new entrants developing competitive drivetrains.
- Stationary Band Saw Substitution:Fixed industrial bandsaws with continuous feed mechanisms and flood cooling retain cost-per-cut advantages in high-volume metal fabrication lines, capping cordless penetration in capital-intensive shops.
Strategic Opportunities
- Indian Infrastructure Buildout:Central government capital expenditure on rail and metro construction is creating first-time demand for portable metalworking tools among tier-2 and tier-3 fabrication contractors.
- EU Battery Passport Mandates:CSRD-aligned traceability requirements for industrial batteries are opening differentiation paths for manufacturers with verified ethical mineral sourcing and end-of-life collection programs.
- Composite Material Machining:Carbon fiber and glass-reinforced polymer adoption in automotive lightweighting and wind turbine manufacturing is expanding addressable applications beyond traditional metal and timber processing.
Industry Challenges
- Brushless Motor Tuning Expertise:Shortage of firmware engineers capable of optimizing field-oriented control algorithms for variable load conditions is delaying product development cycles and increasing R&D compensation costs.
- Multi-Standard Certification Overhead:Simultaneous CE conformity assessment under the EU Machinery Directive, OSHA compliance documentation for US entry, and ISO 28927 vibration testing creates elongated approval timelines and duplicated testing expenditure.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Bandsaw Sander Market Trends and Innovations
Convergence between cordless power tool architectures and connected field-service ecosystems is redefining how professional trades monitor equipment health and manage consumable replenishment.
Brushless motor-inverter integration is unifying thermal management and torque control within single silicon packages, enabling real-time load sensing that prevents blade stall in dense metal stock. German automotive repair chains are adopting these unified-drive units for chassis fabrication, compressing the performance gap between cordless and historically superior corded platforms.
The EU Machinery Directive's 2023 amendment to emergency stop response-time requirements is forcing blade brake actuator upgrades across cordless bandsaw sander portfolios sold into European professional channels. Manufacturers serving metal fabrication shops in France and Italy are absorbing redesign costs to maintain CE marking access, while US-focused product lines face diverging specification paths.
Rental and tool-sharing platforms are displacing direct ownership among North American mechanical contractors facing intermittent project workloads. Hilti Fleet Management and similar subscription models in the United States are capturing maintenance and calibration responsibilities that previously burdened shop owners, compressing traditional distributor margins while locking in multi-year consumable commitments.
Cordless Bandsaw Sander Market Segmentation
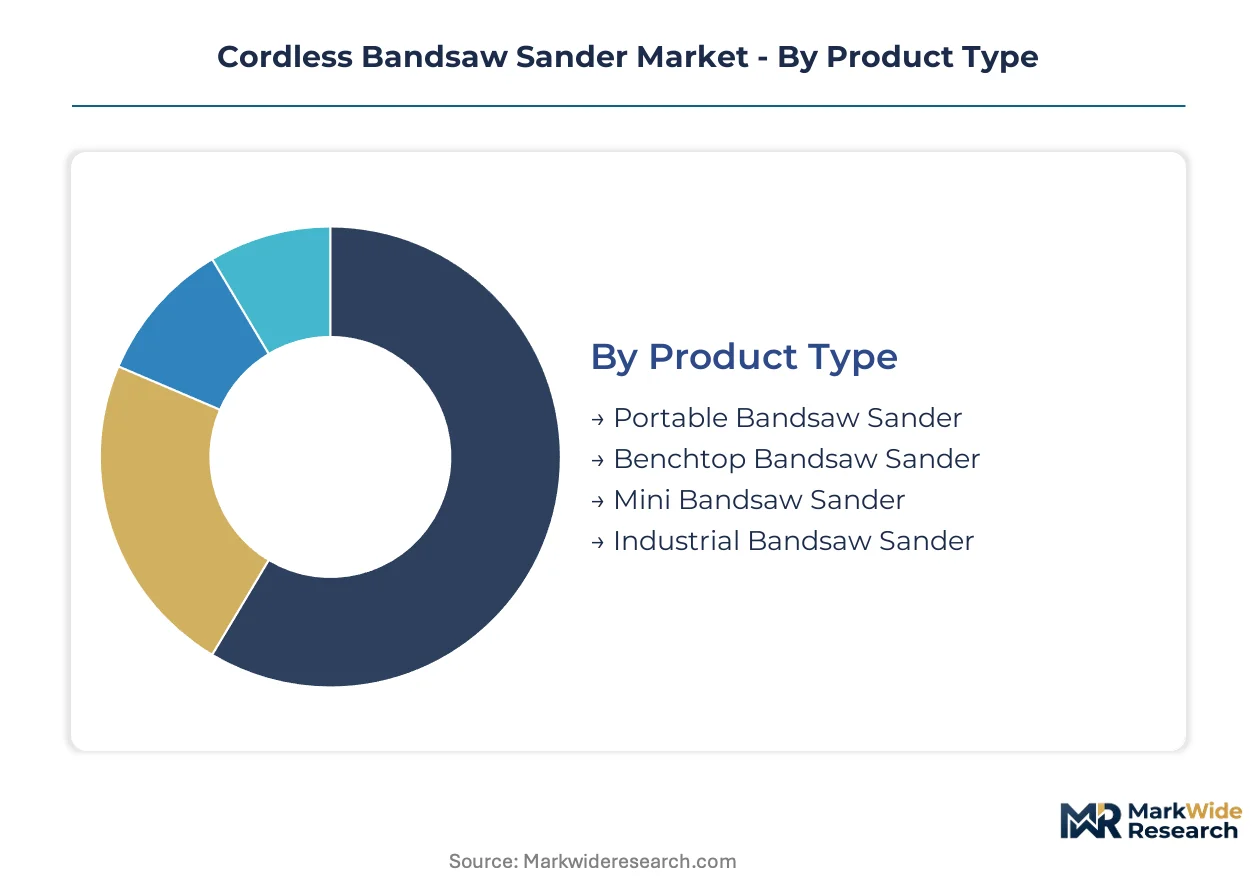
Segmentation in the cordless bandsaw sander market reflects divergent certification burdens, power requirements, and duty-cycle expectations across professional trades. Each dimension shapes procurement priorities, from OSHA compliance in US mechanical workshops to CE marking complexity for European metal fabrication channels.
Product Type:
Certification requirements vary sharply by product type, with industrial units facing the most stringent CE conformity assessment under the EU Machinery Directive for emergency stop functionality and blade guarding, while portable units navigate lighter documentation loads but tighter battery safety protocols.
- Portable Bandsaw Sander:Compact units weighing under 15 pounds integrate 18V to 36V lithium-ion packs with brushless drivetrains for field mobility. Demand concentrates in German and Japanese job-site workflows where setup-time reduction outweighs raw cutting capacity, though runtime constraints limit penetration in sustained metal stock processing.
- Industrial Bandsaw Sander:Fixed-position machines with continuous feed mechanisms and flood cooling systems serve high-volume fabrication lines. US metal fabrication shops in Ohio and Texas deploy these for structural steel processing, where corded alternatives still dominate due to capital intensity and duty-cycle requirements.
- Benchtop Bandsaw Sander:Mid-size units bridge workshop and light industrial use with integrated dust ports and variable speed control.
- Mini Bandsaw Sander:Compact form factors target prototype developers and hobbyist woodworkers with reduced blade capacity and lower price points.
Leading the category by volume: Portable Bandsaw Sander. Expanding most quickly: Industrial Bandsaw Sander in automated fabrication lines.
Technology:
Technology segmentation tracks cost tier differentiation, with premium brushless motor platforms commanding three-to-four times the replacement part revenue of brushed alternatives over tool lifetime.
- Brushless Motor:Electronically commutated designs eliminate brush wear and enable field-oriented control algorithms for thermal management. German automotive repair chains adopt these for chassis fabrication, compressing performance gaps with corded units.
- Lithium Ion Battery:Cell chemistry advances in nickel-manganese-cobalt and lithium-iron-phosphate variants extend runtime per charge. Japanese and South Korean cathode processing concentration creates supply vulnerability, inflating pack replacement costs for mid-tier manufacturers.
- Variable Speed Control:Electronic load sensing prevents blade stall in dense metal stock, gaining traction among prototype developers machining diverse material densities.
- LED Lighting:Integrated work illumination addresses OSHA visibility requirements in US mechanical workshops with poor ambient lighting.
- Rapid Charging:Thermal-managed charge cycles reduce downtime between battery swaps on multi-shift fabrication floors.
Dominant by installed base: Brushless Motor. Gaining share fastest: Rapid Charging as fleet operators prioritize uptime metrics.
Application:
Application segmentation maps to customer maturity, with metal fabrication shops representing the most sophisticated buyers and maintenance departments showing the highest price elasticity.
- Metal Fabrication:Structural steel and aluminum stock cutting drives specification for high-torque brushless drivetrains and integrated dust extraction. German Ruhr Valley fabrication clusters prioritize cordless mobility for on-site structural modifications.
- Woodworking:Timber and composite processing demands precision blade tracking and dust collection integration. Festool's European professional channel dominance stems from extraction system compatibility.
- Construction:Rough-in and framing applications tolerate higher tool weight in exchange for runtime and durability.
- Prototype Development:Low-volume, high-mix machining requires rapid material changeover capability and variable speed flexibility.
- Maintenance & Repair:Intermittent use patterns favor rental and fleet subscription models over direct ownership.
Leading by revenue concentration: Metal Fabrication. Climbing the fastest: Prototype Development as automotive lightweighting expands carbon fiber machining demand.
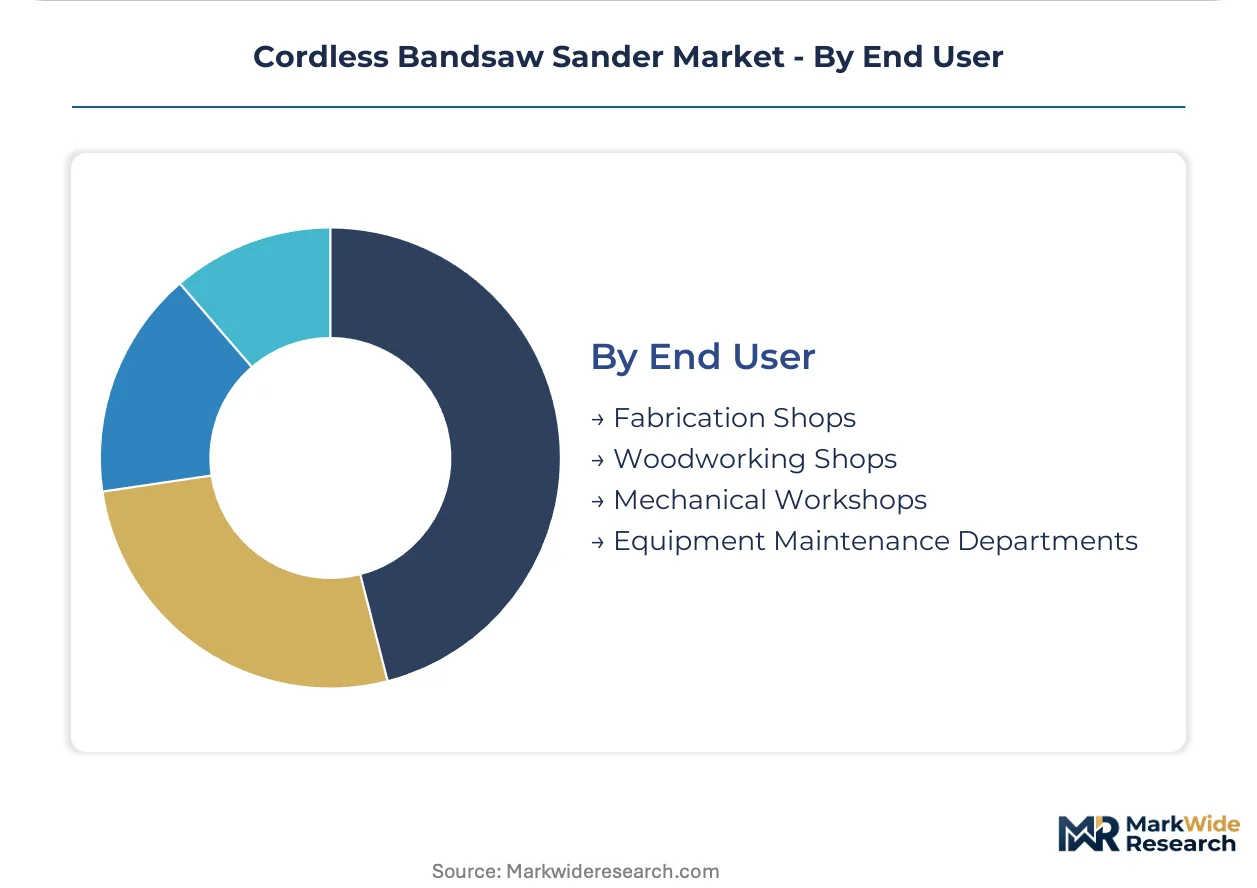
End User:
End user segmentation reveals geographic clustering, with fabrication shops concentrated in industrialized manufacturing regions and mechanical workshops distributed across broader service economies.
- Fabrication Shops:Dedicated metalworking operations in Germany, the United States, and Japan drive premium cordless platform adoption. These buyers prioritize battery ecosystem compatibility and multi-tool fleet standardization.
- Mechanical Workshops:General repair and maintenance facilities face intermittent project workloads, pulling demand toward rental and subscription models like Hilti Fleet Management in North American markets.
- Woodworking Shops:European cabinetry and furniture producers emphasize dust extraction integration and precision finishing.
- Equipment Maintenance Departments:In-house industrial maintenance teams balance capital budgets against uptime requirements, often lagging in cordless adoption due to existing corded infrastructure.
Highest volume segment: Fabrication Shops. Steepest expansion trajectory: Mechanical Workshops as tool-sharing platforms displace direct ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in industrialized manufacturing economies where professional trades favor premium cordless platforms and metal fabrication mobility drives specification. German automotive repair chains, US mechanical workshops, and Japanese job-site workflows pull disproportionate volume. Battery platform consolidation and OSHA particulate standards reshape procurement across these core markets.
United States
Metal fabrication shops in Ohio and Texas deploy cordless units for structural steel processing, prioritizing runtime metrics over raw cutting capacity. OSHA tightened airborne dust exposure limits for mechanical workshops, mandating integrated dust extraction systems on new equipment purchases. Milwaukee Tool anchors midwestern supply chains with vertically integrated motor production serving regional distributor networks.
Germany
Ruhr Valley fabrication clusters prioritize cordless mobility for on-site structural modifications in automotive and heavy machinery supply chains. The EU Machinery Directive mandates CE conformity assessment for emergency stop functionality and blade guarding, forcing actuator upgrades across European product lines. Stuttgart-based repair chains adopt brushless drivetrains for chassis fabrication, compressing performance gaps with corded alternatives.
Japan
Job-site workflows in Osaka and Nagoya emphasize setup-time reduction, pulling demand toward 18V and 36V battery ecosystems that eliminate extension cord management. METI efficiency standards shape motor electronics specifications for professional-grade tools. Japanese cathode processing concentration in Kansai and Kyushu creates supply vulnerability for lithium-ion pack manufacturers serving domestic OEMs.
India
Central government capital expenditure on rail and metro construction creates first-time demand for portable metalworking tools among tier-2 and tier-3 fabrication contractors in Maharashtra and Gujarat. BIS certification requirements for power tool safety slow import clearance for non-compliant manufacturers. Mumbai-Pune industrial corridor fabrication shops trial cordless platforms for intermittent project workloads previously served by rental equipment.
United Kingdom
Midlands-based mechanical workshops face intermittent project workloads, accelerating adoption of fleet subscription models over direct tool ownership. HSE alignment with ISO 28927 vibration emission testing protocols shapes procurement documentation requirements. Birmingham fabrication clusters standardize on battery platforms compatible with existing cordless inventories, prioritizing ecosystem interoperability over standalone tool performance.
Cordless Bandsaw Sander Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium cordless platforms commanding three-to-four times the replacement part revenue of economy alternatives over tool lifetime. The vendor base concentrates around battery ecosystem loyalty, where multi-tool fleet standardization locks in multi-year consumable commitments. Three archetypes dominate: vertically integrated motor specialists, dust extraction integration leaders, and platform-agnostic rental service operators. Competitive moves center on backward integration into brushless motor production and strategic partnerships with cathode processors to secure lithium-ion supply.
Among Japanese and German motor specialists, Makita and Bosch Power Tools exemplify the vertically integrated archetype with captive control over thermal management IP. Milwaukee Tool anchors the premium-tier vector for North American mechanical workshops. Festool occupies a distinct position among European woodworking professionals through extraction system compatibility rather than motor performance differentiation.
| Leading Market Players |
|---|
| Makita |
| Bosch Power Tools |
| Stanley Black & Decker |
| Techtronic Industries |
| Milwaukee Tool |
| Hilti |
| Festool |
| Metabo |
| Ryobi |
| Others |
Pricing and Supply Chain Analysis
German and Japanese fabrication shop procurement concentration anchors a three-tier pricing structure across premium, standard, and economy levels. Metal fabrication mobility requirements and battery ecosystem lock-in determine which tier captures volume versus margin.
Pricing Analysis
Volume concentrates in portable units where mid-tier manufacturers compete on battery pack compatibility, while industrial bandsaw sanders command replacement part premiums three-to-four times higher over tool lifetime. Price differentiation rests on brushless motor thermal management IP and CE certification grade for European channel access. Cost compression in mid-tier portable units is intensifying because lithium carbonate supply volatility inflates pack replacement economics. Rental fleet operators show lowest price sensitivity due to subscription model bundling, whereas tier-2 Indian fabrication contractors exhibit highest elasticity.
Supply Chain Analysis
Container freight rate volatility from Shanghai and Busan to Hamburg and Long Beach compresses landed cost margins for battery pack imports. Lithium-ion cell production draws from South Korean cathode processing and Chinese pack assembly, with Japanese motor electronics feeding brushless drivetrain modules. Single-source vulnerability concentrates in Kansai-region cathode suppliers serving domestic OEMs. Distribution runs through professional tool distributors and rental fleet operators rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cordless bandsaw sander market functions as a vertical-integration race where captive brushless motor production and cathode supply agreements determine who captures replacement revenue streams.
For Market Incumbents: Acquire brushless motor firmware engineering capacity to reduce licensing exposure to Japanese and German thermal management IP holders. Secure long-term offtake agreements with South Korean cathode processors to buffer lithium carbonate price swings. Defend against platform-agnostic rental operators by embedding telemetry-enabled fleet management into battery electronics. For New Entrants and Emerging Players: Rapid-charging thermal management patents offer entry into North American mechanical workshop rental channels where uptime metrics override brand loyalty. Target Indian rail and metro construction contractors in Maharashtra and Gujarat with 18V platform-compatible units priced below premium-tier imports. Partner with domestic distributors holding BIS certification clearance capabilities. For Investors and Strategic Acquirers: The window for entry favors vertically integrated motor specialists with captive cathode relationships over pure-play assemblers. Mid-cap brushless motor houses in Germany and Japan represent consolidation targets as battery platform consolidation accelerates. Monitor EU Battery Passport compliance timelines as inflection indicator for which manufacturers secure CSRD-aligned ethical sourcing differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Motor Production | Milwaukee Tool's captive thermal management IP reduces licensing costs and accelerates product development cycles. |
| Cathode Processor Supply Agreement | Long-term offtake with South Korean suppliers buffers Bosch Power Tools against lithium carbonate price volatility. |
| EU Battery Passport Compliance Program | Festool's verified ethical mineral sourcing opens differentiation paths among CSRD-aligned European woodworking professionals. |
| Rental Fleet Telemetry Integration | Hilti's embedded battery electronics lock in multi-year consumable commitments from North American mechanical contractors. |
| Indian BIS Certification Partnership | Domestic distributor alliances accelerate import clearance for tier-2 fabrication contractors in the Mumbai-Pune corridor. |
Research Methodology
Independent corroboration across fabrication shop maintenance directors, power tool distributor procurement leads, and rental fleet operations managers underwrites the qualitative findings. Primary fieldwork involved structured interviews with OEM product development executives, aftermarket service heads, and cathode processing specialists. Secondary validation drew from SEC 10-K filings of listed tool manufacturers, customs trade data for lithium-ion pack imports, and ISO 28927 vibration testing documentation. Bottom-up unit economics triangulated against top-down market sizing across portable, industrial, and benchtop product categories.
Comparable-period anchoring to historical cordless power tool adoption curves informed the projection horizon across the analysis window. Segmentation modeling incorporated product type, motor technology tier, application vertical, and end-user channel. CAGRs derived from elasticity-adjusted replacement cycle assumptions and fleet penetration rates. Forecast inputs included lithium-ion energy density improvement trajectories and OSHA particulate standard enforcement timelines.
Several conditions sit outside the modeled scope, including abrupt lithium supply disruptions, tariff regime shifts affecting Chinese pack assembly, and unscheduled EU Machinery Directive amendments. Forecasts reflect assumptions about battery platform consolidation velocity and professional trade cordless adoption thresholds. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.