
 Power Nibbler Market | 2026-2036
Power Nibbler Market Size, Share, and Industry Trends Forecast 2026-2036
Power Nibbler Market Analytics
Commercial maintenance services are reorganizing their tool procurement patterns, shifting from pneumatic systems toward battery-powered alternatives for rooftop and confined-space work. Robert Bosch GmbH leverages its cordless platform ecosystem to cross-sell nibblers alongside existing 18V tool inventories. TRUMPF Group dominates high-end industrial segments with precision-engineered electric units targeting sheet-metal processors. Makita Corporation anchors the mid-market through expansive distribution networks in professional construction channels.
A power nibbler is a handheld cutting tool that employs a punch-and-die mechanism to remove small crescent-shaped chips from sheet metal, typically operating at stroke rates between 1,000 and 3,000 cuts per minute with minimal material distortion. The tool serves primary industrial purposes in fabricating complex contours, notching structural steel, and preparing ductwork where shears or saws would cause unacceptable edge deformation. Battery-powered nibblers are capturing the fastest growth trajectory as lithium-ion cell energy density improvements enable cordless performance parity with corded alternatives. Electric nibblers retain the largest installed base in fixed-facility metal fabrication, where continuous power access eliminates portability constraints. Pneumatic variants face structural decline outside heavy shipbuilding and aerospace applications, as compressor infrastructure costs and hose management burden erode their total-cost proposition.
OSHA lockout/tagout standards and NIOSH hand-arm vibration exposure limits shape product design requirements for United States manufacturers, compelling ergonomic redesigns and vibration-damping isolators. CE marking under the EU Machinery Directive, coupled with REACH substance restrictions on coatings and lubricants, governs market access for European-bound equipment. Stakeholders must monitor evolving battery transportation regulations and emerging right-to-repair mandates, as these frameworks will determine warranty structures, spare-part availability, and aftermarket revenue models across major economies.
Market Dynamics
Battery-powered nibblers are decomposing the traditional corded-pneumatic duopoly as lithium-ion energy density improvements enable cordless performance parity in metal fabrication shops and on-site maintenance operations.
Growth Catalysts
- OSHA Lockout/Tagout Standards:Workplace safety mandates in the United States are compelling facility managers to replace pneumatic systems with battery-powered alternatives that eliminate compressor infrastructure hazards during confined-space maintenance.
- Automotive Supplier Demand:Germany's industrial manufacturing belt is driving replacement cycles as Tier-1 sheet metal processors modernize equipment to meet electric vehicle platform tolerances.
- Lithium-Ion Cell Chemistry:Energy density improvements in 21700 cylindrical cells are extending cordless runtime to full-shift capability, removing the primary barrier to battery adoption in high-volume fabrication environments.
Market Restraints
- Raw Material Volatility:Neodymium and copper price swings in rare-earth magnet supply chains are compressing margins for electric motor manufacturers serving the mid-market tool segment.
- REACH Substance Restrictions:ECHA compliance costs for coatings and lubricants are creating regulatory friction for Asian exporters seeking CE marking access to European distribution channels.
- Plasma Cutting Substitution:CNC plasma systems are capturing thick-gauge applications above 3mm where nibblers historically held cost advantages in prototype and short-run production.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for capital goods manufacturing are creating localized assembly opportunities for battery-powered units targeting South Asian construction and HVAC markets.
- Right-to-Repair Mandates:Emerging European legislation on spare-part availability and diagnostic access is enabling aftermarket revenue models for independent service providers and parts distributors.
- IoT-Enabled Predictive Maintenance:Convergence of brushless motor controllers with wireless telemetry is opening subscription-based fleet management contracts for commercial maintenance service operators.
Industry Challenges
- NIOSH Vibration Certification:Hand-arm vibration exposure testing timelines are extending product launch cycles by 8-14 months for manufacturers seeking compliance with revised exposure limit documentation.
- Legacy Pneumatic Infrastructure:Shipyard and aerospace facilities face integration complexity when hybridizing battery units with existing compressor-fed tool cribs and maintenance workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Nibbler Market |
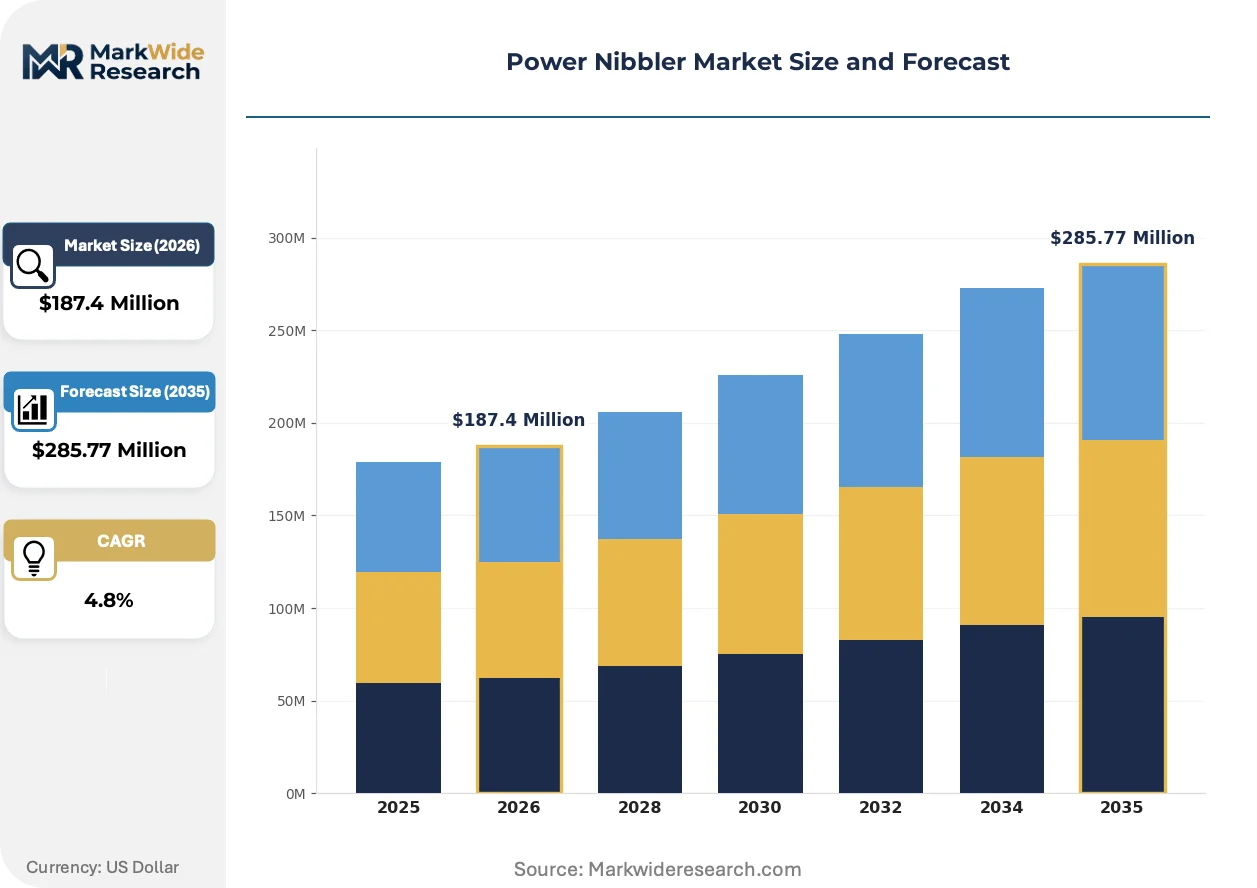
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Nibblers, Pneumatic Nibblers, Manual Nibblers, Battery-Powered Nibblers Application: Metal Fabrication, Automotive Manufacturing, Construction, HVAC Installation End User: Manufacturing Firms, Construction Companies, DIY Enthusiasts, Maintenance Services Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Techtronic Industries, Hilti AG, Robert Bosch GmbH, C. & E. Fein GmbH, TRUMPF Group, Makita Corporation, Metabowerke GmbH, Koki Holdings Co., Ltd., Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Nibbler Market Evolving Landscape
Tool electrification and regulatory compliance automation are compressing product development cycles while expanding the addressable user base beyond traditional metal fabrication into building trades and renewable energy installation.
Brushless DC motor architecture is decomposing the maintenance-intensive brushed motor installed base in professional-grade nibblers. HVAC contractors and commercial roofers are adopting these units at replacement rates exceeding historical 7-year cycles. The technology is decomposing aftermarket brush replacement revenue while extending mean time between failures to 2,000+ operating hours.
CE marking under the EU Machinery Directive is tightening documentation requirements for battery transportation and end-of-life disposal. Manufacturers must now integrate battery management system traceability and recyclability declarations into technical files. The mid-market cordless segment faces the steepest compliance cost escalation as smaller producers lack dedicated regulatory affairs capacity.
Commercial maintenance services are unbundling tool ownership from labor contracts, shifting toward equipment-as-a-service arrangements where distributors retain asset responsibility. National facility management firms are consolidating vendor relationships to single-source cordless platform ecosystems. This pattern is most visible in Germany and the United States, where multi-site operators prioritize fleet standardization over point-tool optimization.
Power Nibbler Market Segmentation
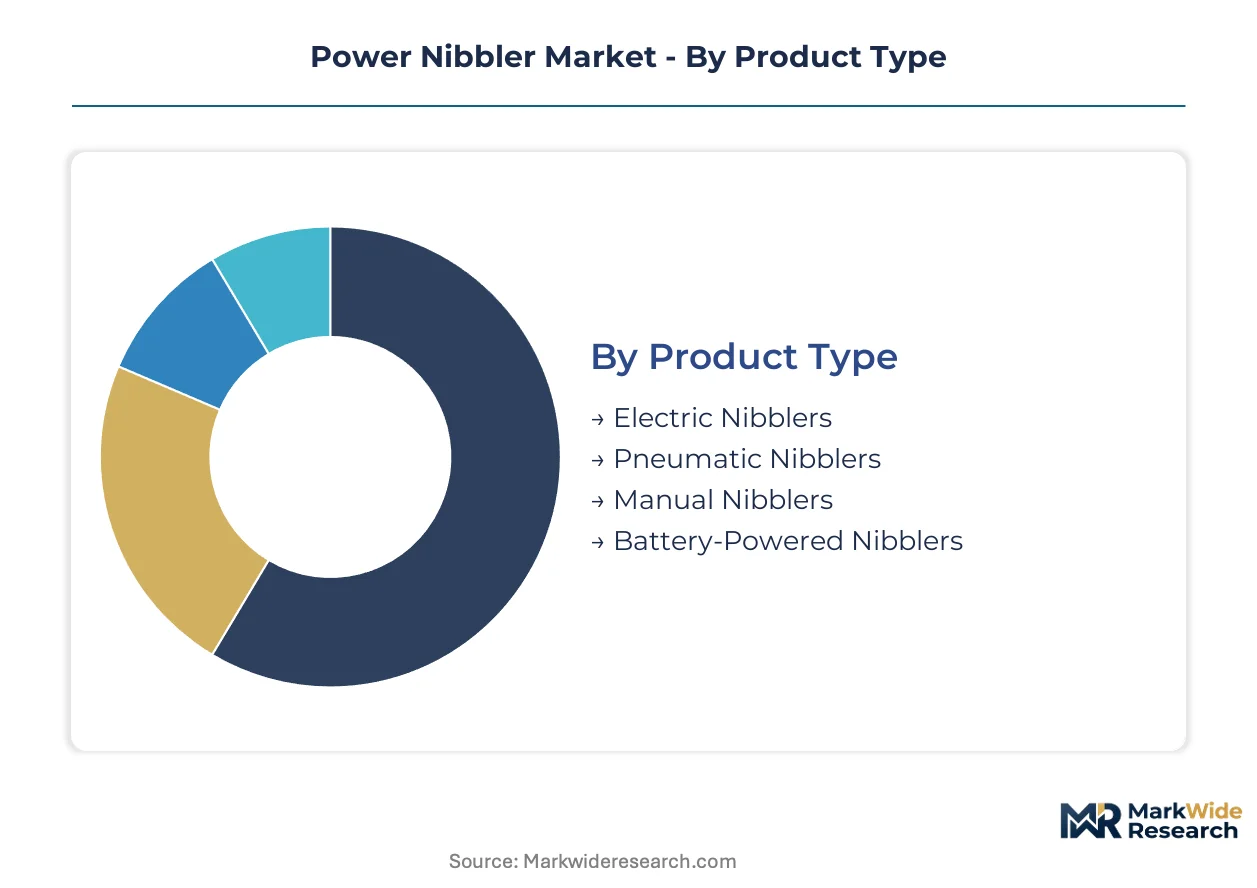
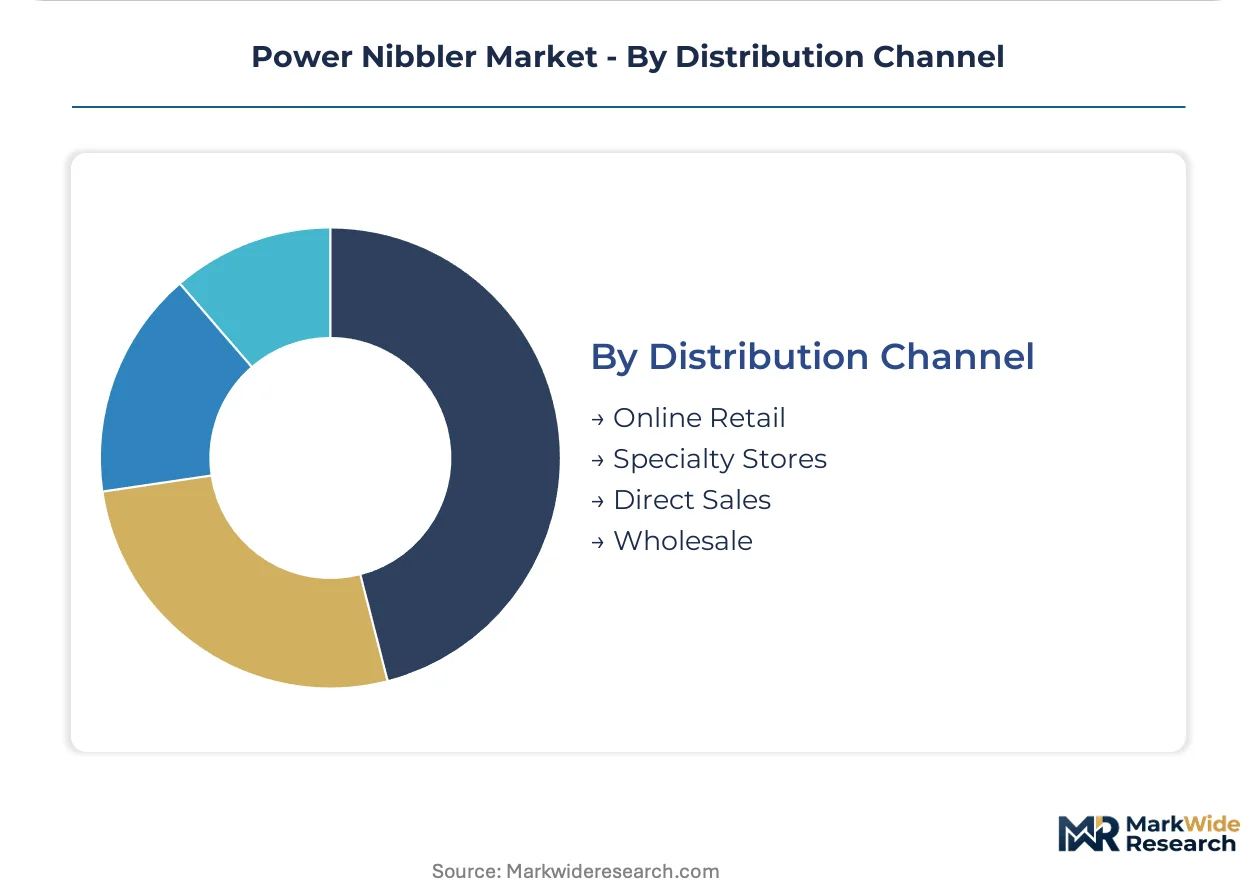
Power nibbler segmentation reveals how lithium-ion electrification, safety mandates, and procurement centralization are redistributing value across product architectures and channel structures. Understanding margin concentration by segment enables targeted positioning against replacement cycles and fleet standardization trends.
Product Type:
Premium margins pool in cordless platforms where battery ecosystem lock-in generates recurring accessory revenue, while pneumatic systems face structural compression from infrastructure burden.
- Battery-Powered Nibblers:Lithium-ion 21700 cell architectures now deliver full-shift runtime parity with corded units. Demand concentrates in Germany's automotive supplier belt and US commercial roofing contractors where OSHA lockout/tagout compliance eliminates compressor hazards.
- Electric Nibblers:Brushless DC motor designs dominate fixed-facility metal fabrication with 2,000+ hour mean time between failures. German sheet-metal processors and US HVAC ductwork shops drive replacement demand as vibration-damping isolators meet NIOSH exposure limits.
- Pneumatic Nibblers:Shipbuilding yards and aerospace maintenance facilities retain limited installed base where existing compressor infrastructure creates switching costs.
- Manual Nibblers:Hobbyist metalworkers and prototype shops in India and Southeast Asia sustain minimal volume for precision notch work without power access.
The dominant share belongs to Electric Nibblers, while Battery-Powered Nibblers is closing the gap fastest.
Application:
Volume concentration tracks capital expenditure cycles in automotive electrification and commercial building HVAC retrofit mandates.
- Metal Fabrication:Tier-1 automotive suppliers in Germany's industrial belt modernize equipment for electric vehicle platform tolerances. Complex contour cutting and structural steel notching demand precision-engineered units with minimal edge deformation.
- HVAC Installation:US commercial roofers and building maintenance contractors adopt cordless platforms for confined-space ductwork preparation. Brushless motor adoption exceeds historical 7-year replacement cycles.
- Automotive Manufacturing:OEM stamping plants and body-in-white operations specify high-stroke-rate units for prototype and short-run production.
- Construction:Steel framing and architectural metalwork contractors in India's PLI-incentivized capital goods sector drive emerging demand.
Metal Fabrication commands the largest revenue pool, though HVAC Installation is expanding most quickly as building electrification accelerates.
End User:
Procurement authority concentrates in fleet managers standardizing cordless platforms across multi-site operations.
- Manufacturing Firms:German automotive suppliers and US metal stampers centralize capital equipment purchasing through technical specifications tied to CE marking and OSHA compliance documentation.
- Maintenance Services:National facility management firms in Germany and the United States consolidate vendor relationships to single-source 18V ecosystems, shifting from tool ownership toward equipment-as-a-service arrangements.
- Construction Companies:Commercial general contractors and specialty steel erectors specify battery-powered units for site mobility.
- DIY Enthusiasts:Home improvement retailers and online marketplaces serve intermittent-use buyers with entry-tier cordless platforms.
Manufacturing Firms retain the deepest penetration, while Maintenance Services is gaining share fastest through fleet outsourcing contracts.
Distribution Channel:
Channel margins fragment between direct technical specification and high-velocity online fulfillment.
- Specialty Stores:Professional tool distributors in Germany and the United States provide application engineering support and fleet management services for commercial maintenance operators.
- Online Retail:Amazon Business and industrial e-procurement platforms capture standard replacement unit volume from price-sensitive mid-market buyers.
- Direct Sales:TRUMPF Group and Robert Bosch GmbH maintain field engineering relationships with high-volume automotive and aerospace accounts.
- Wholesale:Construction supply houses and HVAC distributors bundle nibblers within broader MRO procurement contracts.
Specialty Stores anchors professional-grade volume, while Online Retail is climbing the fastest as procurement digitization penetrates mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European metalworking equipment distribution, while the Union Pacific rail network connects US manufacturing clusters across the Great Plains and Southwest.
Germany
Tier-1 automotive suppliers in Stuttgart and Wolfsburg drive replacement cycles for precision sheet-metal processing equipment. CE marking under the EU Machinery Directive tightens documentation protocols for battery transportation and end-of-life disposal. The industrial manufacturing belt around Munich anchors demand for brushless motor platforms meeting electric vehicle platform tolerances.
United States
Commercial roofing contractors and HVAC maintenance operators across Texas and Florida adopt cordless platforms for confined-space ductwork preparation. OSHA lockout/tagout standards compel facility managers to eliminate compressor infrastructure hazards during rooftop maintenance. The Dallas-Fort Worth metroplex concentrates distribution capacity for battery-powered units serving Southwest construction markets.
China
Shipbuilding yards in Dalian and Guangzhou retain pneumatic nibbler installations where existing compressor infrastructure creates switching costs. GB standards and MIIT regulations govern domestic tool certification and rare-earth magnet supply chain traceability. The Yangtze River Delta manufacturing corridor generates emerging demand for entry-tier cordless platforms in prototype metalworking shops.
India
HVAC contractors in Mumbai and Delhi-NCR expand procurement of battery-powered units for commercial building retrofit mandates. The PLI scheme for capital goods manufacturing creates localized assembly opportunities targeting South Asian construction markets. Gujarat's industrial zones attract component sourcing for mid-market cordless platform production.
Japan
Precision metal stampers in Nagoya and Osaka specify high-stroke-rate electric units for automotive prototype production. METI efficiency standards and JIS certification requirements shape product design for professional-grade equipment. The Kanto region around Tokyo concentrates R&D investment in brushless motor controllers and vibration-damping isolators.
Power Nibbler Market Competitive Landscape
Concentration sits with diversified power-tool conglomerates and precision-engineering specialists. The vendor base spans three tiers: battery-ecosystem platform owners, industrial-grade precision fabricators, and regional mid-market assemblers. Two strategic archetypes dominate competitive positioning: cordless platform ecosystem builders leveraging cross-selling across 18V tool inventories, and precision-engineering houses targeting high-tolerance sheet-metal processors. Capacity expansion and portfolio diversification represent the dominant competitive moves, with players extending battery compatibility across nibbler, shear, and fastening product lines.
Within the diversified conglomerate tier, Robert Bosch GmbH and Stanley Black & Decker exemplify platform-ecosystem strategies, while Makita Corporation anchors mid-market positioning through expansive distribution networks. TRUMPF Group occupies a precision-engineering position targeting industrial-grade applications. Techtronic Industries and Hilti AG represent battery-ecosystem specialists with cross-category cordless portfolios. C. & E. Fein GmbH, Metabowerke GmbH, and Koki Holdings Co., Ltd. sit within regional specialist archetypes serving professional construction channels.
| Leading Market Players |
|---|
| Techtronic Industries |
| Hilti AG |
| Robert Bosch GmbH |
| C. & E. Fein GmbH |
| TRUMPF Group |
| Makita Corporation |
| Metabowerke GmbH |
| Koki Holdings Co., Ltd. |
| Stanley Black & Decker |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85 percent in Chinese lithium-ion cell manufacturing compress unit economics for battery-powered nibbler producers, creating asymmetric pricing power between ecosystem-scale manufacturers and mid-market assemblers. German automotive suppliers and US commercial roofing contractors absorb premium positioning through fleet standardization contracts, while price floors in the economy tier tether to neodymium magnet and copper winding commodity benchmarks.
Pricing Analysis
Volume-discount tiering structures separate OEM fleet contracts from spot-market replacement units, with three-tier pricing stratification across premium brushless platforms, standard brushed-motor units, and economy-grade pneumatic alternatives. Price differentiation hinges on CE marking certification grade and NIOSH vibration compliance documentation, with German Tier-1 automotive suppliers least sensitive and Indian HVAC contractors most responsive to unit-cost fluctuations. Pricing pressure intensifies in the mid-market cordless segment as 21700 cell oversupply from South Korean producers compresses battery pack margins.
Supply Chain Analysis
Strategic-stockpile preferences dominate among German precision-engineering houses buffering against rare-earth magnet supply interruptions, while just-in-time inventory management prevails among US commercial maintenance operators relying on distributor consignment programs. Component sourcing concentrates in China for lithium-ion cells, Japan for brushless motor controllers, and Germany for precision punch-and-die assemblies. Raw material dependencies rest on neodymium from rare-earth processing facilities, copper for motor windings, and cobalt-free cathode formulations. Single-source vulnerability in 21700 cylindrical cell supply chains from Chinese producers poses structural risk. Distribution runs through specialty industrial distributors in Germany and the United States, with online retail capturing standard replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in battery-powered nibbler segments where lithium-ion electrification and right-to-repair mandates destabilize incumbent ecosystem lock-ins, creating acquisition targets and white-space entry points for specialized challengers.
For Market Incumbents: Consolidate aftermarket service networks through predictive maintenance platform acquisitions, capturing IoT-enabled fleet management contracts before independent service providers scale. Deepen backward integration into 21700 cell pack assembly to offset South Korean battery producer margin compression. Prioritize CE marking documentation automation to accelerate European product launch cycles against regulatory friction.
For New Entrants and Emerging Players: CE marking fast-track certification for brushless motor platforms opens immediate access to German automotive supplier procurement channels, bypassing incumbent ecosystem switching costs. Target India's PLI-incentivized capital goods sector where localized assembly gaps persist for mid-market cordless units. Pursue equipment-as-a-service arrangements with national facility management firms seeking vendor consolidation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among battery-ecosystem platform owners with cross-category 18V tool portfolios and captive accessory revenue streams. Five-to-ten-year viability favors precision-engineering specialists with automotive supplier relationships and vibration-damping intellectual property. Monitor right-to-repair legislative progression across European jurisdictions as inflection signal for aftermarket revenue model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive 21700 cell sourcing from Chinese producers insulates margin compression from South Korean supply concentration. |
| Predictive Maintenance Platform Launch | Brushless motor telemetry integration with Bosch and Makita ecosystems enables subscription fleet contracts. |
| CE Marking Automation Investment | Technical file digitization accelerates European market access against REACH substance restriction compliance burdens. |
| Equipment-as-a-Service Model Rollout | Asset-retention structures align with German facility management firm vendor consolidation preferences. |
| India PLI Localization Partnership | Gujarat assembly capacity targets South Asian HVAC contractor demand under capital goods manufacturing incentives. |
Research Methodology
Cross-validation between primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation from SEC filings, customs and trade data, OSHA compliance documentation, and CE marking technical files. Bottom-up demand modeling from individual end-user segments triangulates against top-down market sizing from equipment manufacturer revenue disclosures.
Sensitivity analysis frameworks test forecast robustness across lithium-ion cell price volatility scenarios and regulatory compliance cost escalations throughout the projection horizon. Segmentation dimensions modeled include power source architecture, application category, end-user procurement authority, and distribution channel structure. CAGRs derive from replacement cycle analysis, fleet penetration curves, and technology substitution elasticity estimates. Industry-specific inputs incorporate NIOSH hand-arm vibration exposure limit revisions and evolving battery transportation regulations.
Decision-makers should treat outputs as directional under assumptions of steady-state automotive capital expenditure cycles and continued lithium-ion energy density improvements; material deviation would warrant model refresh. Revision becomes warranted when rare-earth magnet supply chain disruptions or right-to-repair legislative implementation crosses threshold enforcement levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Tapping Machine Market
Tools
Bar Clamp Market
Tools
Welding Guns Market
Tools
Hand Saw Market
Tools
Hand Tools Market
Tools
Global Staple Gun Market
Tools
Hydraulic Torque Wrench Market
Tools
Boring-Milling Machines Market
Tools
Press Machine Market
Tools
Edge Banding Machine Market
Tools
Assembly Fastening Tool Market
Tools
Shredder Blades Market
Tools
Striking Tools Market
Tools
Self-Clinching Fasteners Market
Tools
Construction Anchors Market
Tools
Cordless Blind Rivet Gun Market