
 Woodworking Circular Saw Blades Market | 2026-2036
Woodworking Circular Saw Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Circular Saw Blades Market Outlook
Custom furniture workshops are unwinding their historical preference for general-purpose blades in favor of application-specific cutting tools designed for engineered wood substrates. Freud Tools leverages its Italian carbide-tipping expertise to dominate European hardwood cutting segments. Makita anchors Asia-Pacific distribution through dense dealer networks serving professional carpentry contractors. Bosch differentiates via integrated brushless motor and blade systems that lock buyers into compatible ecosystems.
Woodworking circular saw blades are precision cutting tools manufactured from alloy steel bodies with tipped cutting edges, typically brazed tungsten carbide segments ground to specific hook angles and kerf widths for chip evacuation in timber and composite materials. Tungsten carbide blades command the largest installed base due to their balance of edge retention and cost per cut across softwood and hardwood operations. Diamond-tipped configurations represent the fastest-growing blade type as fiber cement board and aluminum composite panel fabrication expands beyond traditional stone-cutting applications. Ten-inch diameters occupy the core revenue pool, serving the intersection of portable table saw portability and jobsite rip-cutting capacity that drives replacement frequency.
OSHA silica standards and the EU Machinery Directive pressure blade manufacturers to certify noise emission levels and vibration exposure thresholds before market entry. REACH compliance in Europe restricts cobalt content in carbide formulations, forcing reformulation of cutting-edge substrates. Japan's METI energy-efficiency benchmarks for industrial motors indirectly shape blade demand by accelerating upgrades to higher-torque saws requiring matched kerf specifications. Stakeholders must monitor how evolving sustainability disclosure rules in the EU and North America affect raw material sourcing transparency for tungsten and diamond supply chains.
Market Dynamics
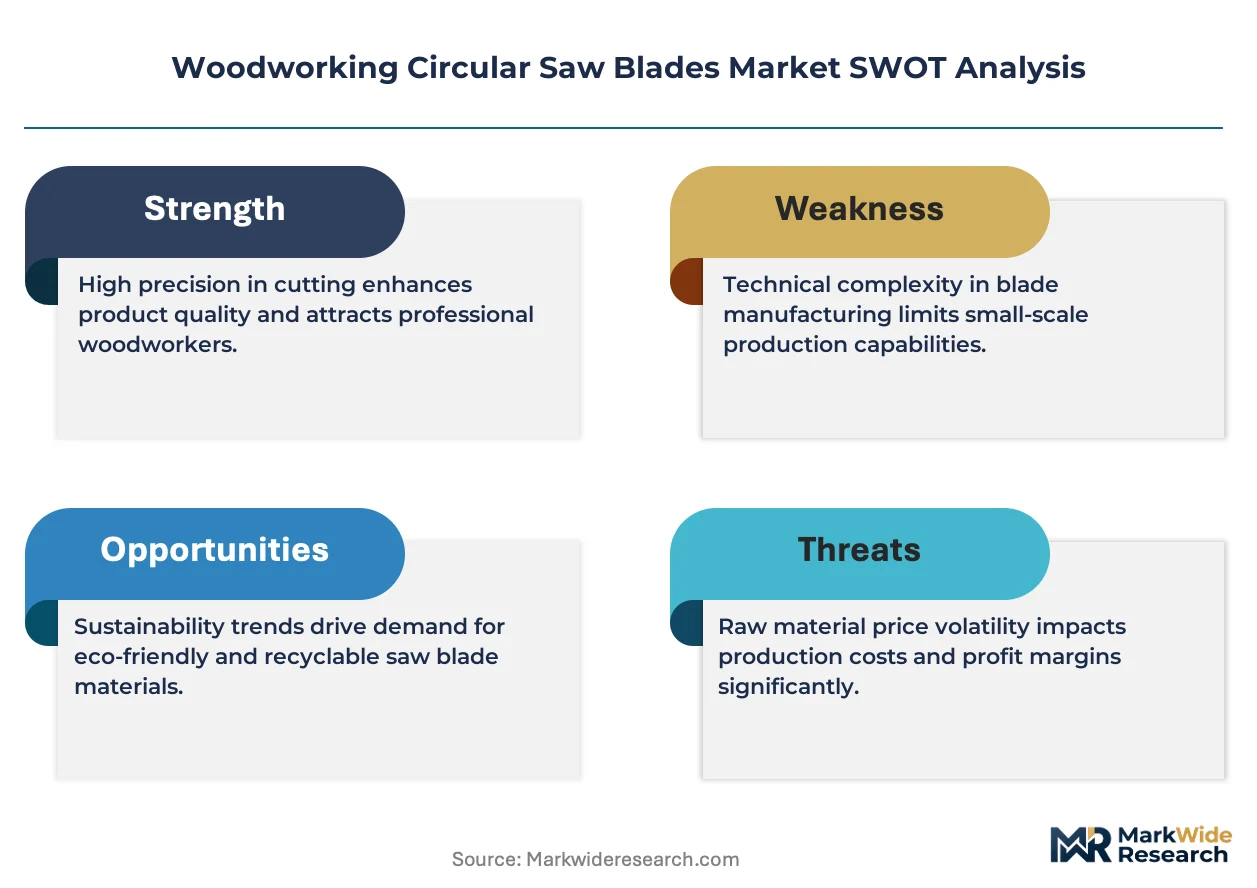
OSHA silica exposure limits and REACH cobalt restrictions are compressing blade replacement cycles while forcing reformulation of carbide-tipped cutting edges across North American and European workshops.
Growth Catalysts
- Engineered wood substrate expansion:Custom furniture workshops in Germany's Black Forest region now specify application-specific blades for hardwood processing, abandoning general-purpose tools.
- OSHA workplace safety enforcement:Stricter silica exposure limits in US woodworking facilities accelerate blade replacement frequency to maintain air quality compliance.
- Diamond-tipped blade migration:Fiber cement board and aluminum composite panel fabrication outside traditional stone-cutting is expanding addressable applications for superhard cutting tools.
Market Restraints
- Tungsten supply concentration:Raw material sourcing for carbide formulations faces transparency pressures from EU sustainability disclosure rules affecting tungsten supply chains.
- REACH cobalt restrictions:European chemical regulations limit cobalt content in cutting-edge substrates, forcing expensive reformulation of established carbide grades.
- Brushless motor ecosystem lock-in:Integrated blade-motor systems from dominant power tool manufacturers create switching costs that constrain independent blade supplier access.
Strategic Opportunities
- Professional carpentry contractor channels:Dense dealer networks serving Asia-Pacific construction markets offer underexploited distribution depth for premium blade portfolios.
- EU Green Deal alignment:Sustainability certification requirements for industrial equipment create preference tailwinds for blades with documented recycled content and reduced energy cutting profiles.
- Brushless motor convergence:Higher-torque saw upgrades driven by Japan METI energy-efficiency benchmarks require matched kerf specifications, opening specification windows for optimized blade designs.
Industry Challenges
- Precision grinding skill scarcity:Specialized carbide-tipping expertise concentrated in Italian manufacturing clusters limits workforce scalability for quality blade production.
- Multi-jurisdiction certification timelines:Simultaneous OSHA noise emission, EU Machinery Directive vibration, and REACH chemical compliance extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Circular Saw Blades Market |
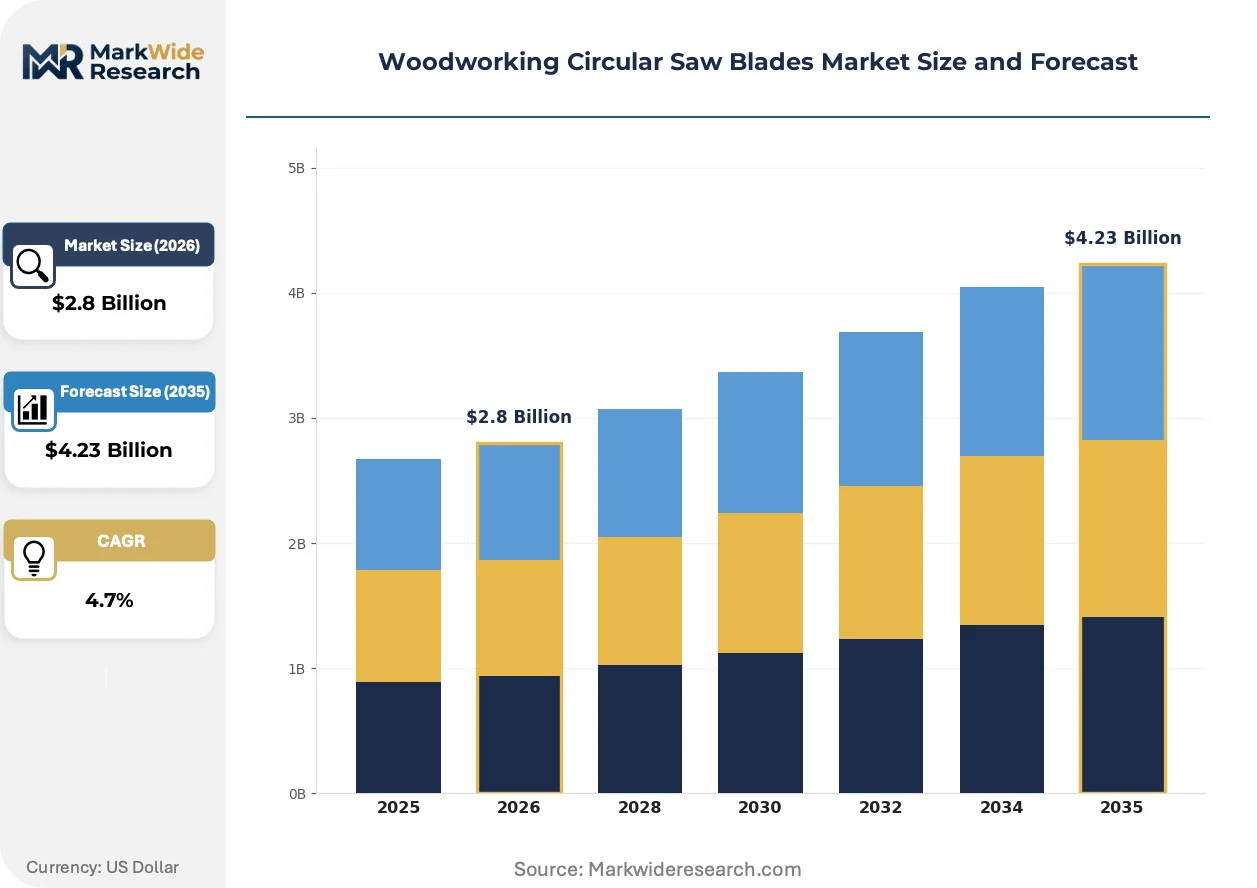
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Blade Type: Tungsten Carbide, High-Speed Steel, Diamond, Bi-metal Application: Crosscutting, Rip Cutting, Miter Cuts, Specialty Cuts Diameter: 7 Inch, 10 Inch, 12 Inch, 14 Inch Tooth Count: 24 Tooth, 40 Tooth, 60 Tooth, 80 Tooth |
| Companies Covered | Makita, Diablo, Freud Tools, Festool, Lenox Tools, DeWalt, Irwin Tools, Amana Tool, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Circular Saw Blades Market Strategic Shifts
Blade engineering is pivoting from universal cutting geometries toward substrate-optimized designs that trade versatility for precision in specific material classes.
Carbide segment geometries are miniaturizing. Micro-grain tungsten carbide tips with sub-micron grain structures now deliver edge retention previously requiring larger cutting segments. High-volume engineered wood processors in North American millwork operations adopt these compact-tip configurations to reduce kerf waste. The technology is miniaturizing blade body profiles while maintaining cut quality, enabling thinner saw plates that reduce motor load and extend cordless runtime.
REACH chemical restrictions are tightening cobalt content ceilings in carbide formulations. European blade manufacturers reformulate cutting substrates with nickel and iron binder alternatives to maintain hardness without restricted elements. German precision woodworking clusters face the steepest compliance burden, driving accelerated R&D partnerships with powder metallurgy specialists to certify replacement grades before enforcement deadlines.
Workshop procurement patterns are fragmenting across application-specific tool portfolios. Custom furniture makers now maintain discrete blade inventories for solid hardwood, particleboard, and aluminum composite materials rather than relying on general-purpose compromise geometries. This specification depth concentrates replacement demand with distributors offering technical selection support. The shift is most visible in German and Austrian cabinet-making regions where material variety in single projects demands rapid blade changeover capability.
Woodworking Circular Saw Blades Market Segmentation
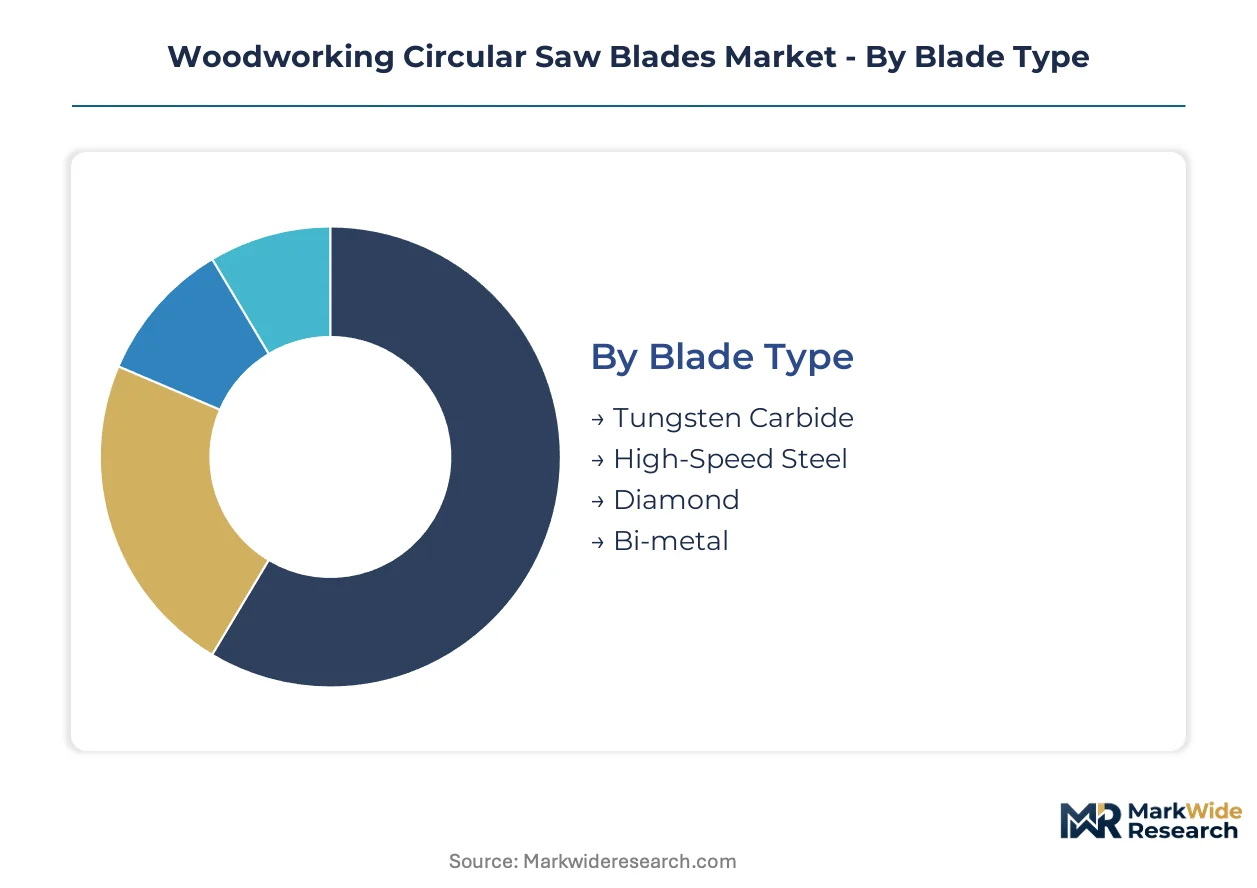
Blade specification diversity creates distinct margin architectures across material technologies, cutting geometries, and dimensional formats. Procurement patterns in professional woodworking operations increasingly favor application-matched configurations over universal compromise designs.
Blade Type:
Tungsten carbide formulations capture the dominant margin pool through volume scale and replacement frequency in hardwood processing clusters.
- Tungsten Carbide:Alloy steel bodies with brazed tungsten carbide segments deliver balanced edge retention and cost efficiency across softwood and hardwood operations. German Black Forest precision workshops specify micro-grain formulations for engineered wood substrates, driving specification depth in European cabinetry manufacturing.
- Diamond:Polycrystalline diamond cutting edges mounted on steel cores handle abrasive fiber cement board and aluminum composite panel fabrication. North American millwork operations outside traditional stone-cutting applications are expanding addressable demand for superhard cutting tools as cladding material diversity increases.
- High-Speed Steel:Solid tool steel constructions suit softwood rough-cutting and budget-conscious hobbyist segments with lower edge retention requirements.
- Bi-metal:Composite steel strip constructions with hardened tooth edges target portable jobsite saws requiring impact resistance and flexibility.
Tungsten carbide holds installed capacity. Diamond is rotating up the share rankings.
Application:
Cutting geometry specialization concentrates replacement demand with distributors offering technical selection support for material-specific operations.
- Crosscutting:High-tooth-count configurations with negative hook angles shear across wood grain for finished surface quality in cabinetry and furniture production. Japanese architectural millwork shops prioritize crosscut blade precision for visible joinery applications.
- Rip Cutting:Aggressive hook angles and deep gullets evacuate chips efficiently along wood grain in dimension lumber processing. US custom furniture workshops accelerate replacement cycles for rip blades to maintain OSHA silica compliance in high-volume cutting operations.
- Miter Cuts:Specialized tooth geometries balance cross-grain shear and chip evacuation for angled compound cuts in trim carpentry.
- Specialty Cuts:Custom grind patterns address dado, rabbet, and non-ferrous metal cutting requirements in diversified material fabrication.
Rip cutting holds installed capacity. Crosscutting is rotating up the share rankings.
Diameter:
Dimensional standardization around portable equipment compatibility shapes volume concentration and cordless runtime optimization priorities.
- 10 Inch:The dimensional sweet spot serves portable table saw portability thresholds while delivering adequate rip capacity for jobsite dimensioning. Professional carpentry contractors in Asia-Pacific markets specify 10-inch configurations as baseline equipment for mixed-material projects.
- 12 Inch:Expanded cutting depth supports heavy timber and engineered beam processing in structural millwork applications. German timber frame construction clusters drive specification for 12-inch miter saw compatibility in precision joinery operations.
- 7 Inch:Compact cordless circular saw formats prioritize runtime extension through reduced kerf and motor load in trim carpentry.
- 14 Inch:Industrial beam saw and panel processing equipment specifications demand maximum cutting depth for thick stock dimensioning.
10-inch holds installed capacity. 12-inch is rotating up the share rankings.
Tooth Count:
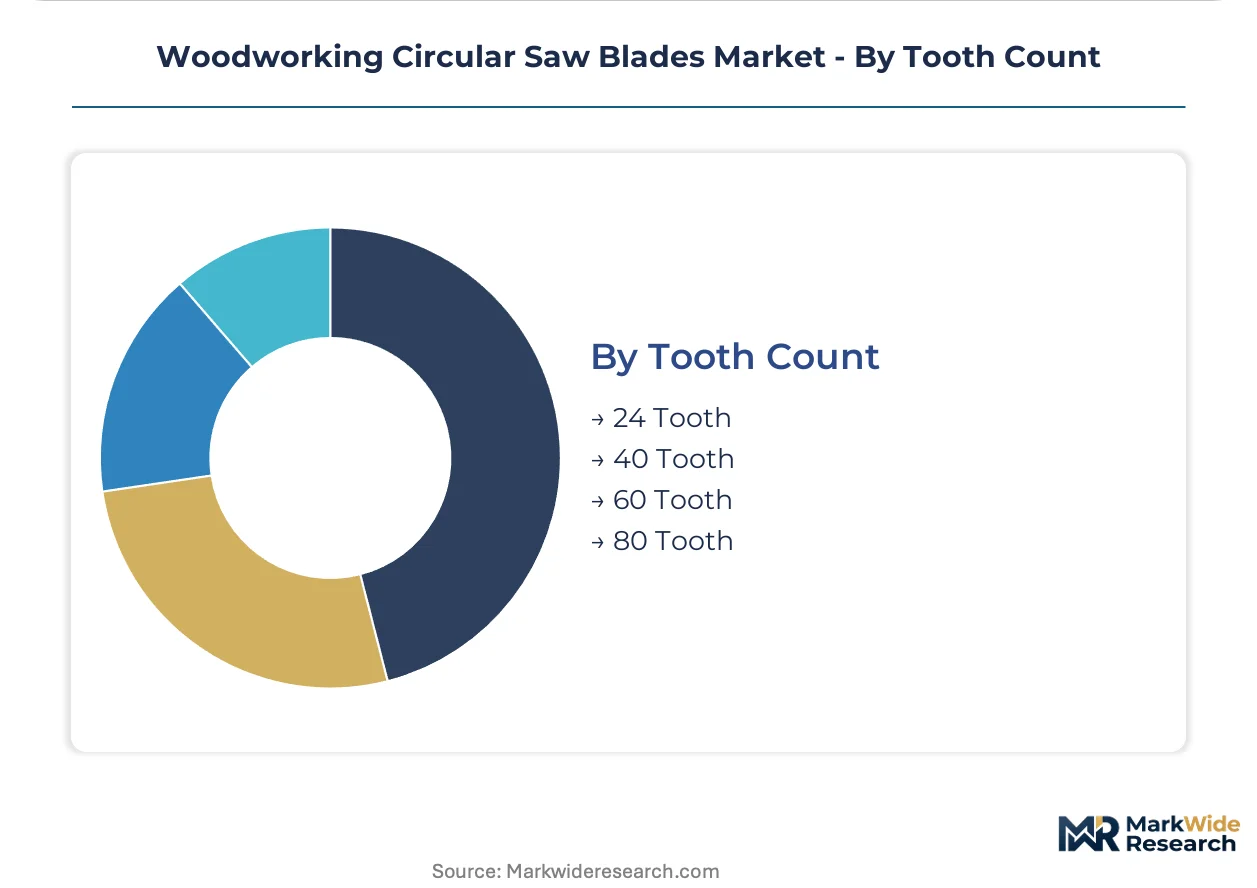
Tooth density selection trades cut speed against surface finish quality across material hardness and visible surface requirements.
- 40 Tooth:The versatile middle ground balances feed rate and finish quality in mixed hardwood and softwood operations. Austrian cabinet-making regions specify 40-tooth configurations as general-purpose inventory for rapid material changeover.
- 80 Tooth:Maximum tooth density delivers mirror finishes on plywood and veneer surfaces where visible quality dictates specification. US architectural millwork contractors specify 80-tooth blades for stain-grade hardwood applications where tear-out visibility is unacceptable.
- 24 Tooth:Aggressive cutting geometry maximizes material removal rate in rough dimensioning and construction lumber processing.
- 60 Tooth:Intermediate density addresses melamine and laminated board cutting where chip-out control meets moderate feed rate requirements.
40-tooth holds installed capacity. 80-tooth is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in precision blade distribution, while the US Interstate highway network enables rapid restocking of jobsite inventory across North American construction corridors.
United States
OSHA silica enforcement drives replacement cycles in millwork operations across the Southeast and Pacific Northwest. The agency's updated permissible exposure limits force workshops to retire blades showing micro-fractures that elevate airborne particulate counts. Chicago's architectural millwork corridor concentrates demand for 80-tooth crosscut configurations serving stain-grade hardwood applications.
Germany
REACH cobalt restrictions compel reformulation of carbide-tipped cutting edges before 2026 enforcement deadlines. The Black Forest precision woodworking cluster sources specialized micro-grain formulations for engineered wood substrates. Bavarian powder metallurgy specialists partner with blade manufacturers to certify nickel-binder alternatives that maintain hardness without restricted elements.
China
MIIT energy-efficiency benchmarks for industrial motors accelerate upgrades to higher-torque saws requiring matched kerf specifications. The Yangtze River Delta manufacturing belt hosts carbide-tipping operations serving both domestic furniture production and export blade assembly. Zhejiang province's tool steel foundries supply alloy body blanks to regional fabricators competing on cordless runtime optimization.
Japan
METI industrial motor standards indirectly shape blade demand by mandating torque-density improvements in professional-grade equipment. Tokyo's architectural millwork shops prioritize crosscut blade precision for visible joinery in high-end residential construction. Osaka's dealer networks distribute premium configurations optimized for the country's dense laminated beam fabrication sector.
Italy
Freud Tools anchors European hardwood cutting segments through concentrated carbide-tipping expertise in the Veneto region. Italian blade manufacturers face accelerated R&D timelines to certify REACH-compliant formulations before cobalt content ceilings tighten. Emilia-Romagna's furniture manufacturing belt drives specification depth for application-specific cutting geometries.
Woodworking Circular Saw Blades Market Competitive Environment
Listed leaders compete with private specialists across distribution density and substrate-specific engineering capabilities. The vendor base separates into consolidated power-tool ecosystems, independent precision specialists, and regional fabricators serving price-sensitive construction segments. Three archetypes dominate: integrated motor-blade system providers, carbide-tipping specialists with metallurgical partnerships, and scale-driven manufacturers optimizing for cordless runtime compatibility. M&A activity concentrates on powder metallurgy capabilities, while geographic expansion targets Asia-Pacific dealer network depth.
Among Japanese and German equipment manufacturers, Makita and Bosch exemplify the integrated ecosystem archetype, locking buyers into compatible motor-blade systems through brushless platform convergence. Freud Tools occupies a position within the precision specialist tier, leveraging Italian carbide-tipping expertise to serve hardwood processing clusters with substrate-optimized geometries. These three anchors illustrate how competitive positioning separates around technical specification depth versus distribution scale versus captive platform integration.
| Leading Market Players |
|---|
| Makita |
| Diablo |
| Freud Tools |
| Festool |
| Lenox Tools |
| DeWalt |
| Irwin Tools |
| Amana Tool |
| Bosch |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day carbide segment lead times from Italian tipping specialists concentrate pricing power with established precision manufacturers while compressing margins for regional fabricators lacking metallurgical partnerships. This inventory bandwidth differential separates premium application-specific blade portfolios from commodity-grade alternatives across German and North American distribution channels.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales technical support bundling. Price differentiation hinges on REACH compliance documentation and micro-grain carbide formulation quality. Cost compression in economy-tier bi-metal segments is intensifying because of cordless runtime optimization demands from Asia-Pacific contractors. Hobbyist segments exhibit highest price sensitivity, while German precision workshops prioritize specification depth over unit cost.
Supply Chain Analysis
China and Germany anchor tungsten carbide powder production and precision grinding operations respectively. Raw material sourcing draws from Zhejiang tool steel foundries, Veneto carbide-tipping facilities, and Bavarian powder metallurgy specialists. Single-source vulnerability concentrates in Italian micro-grain formulation expertise. Distribution runs through dense dealer networks serving professional carpentry contractors across Asia-Pacific construction corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor ecosystem convergence is reshaping this market into a platform-economics inflection where blade-motor interoperability locks determine procurement authority. Bosch and Makita exemplify how integrated system architectures displace independent blade supplier access.
For Market Incumbents: Shield specification windows by deepening captive supply of REACH-compliant nickel-binder carbide formulations before enforcement deadlines tighten. Prioritize certification investment for EU Machinery Directive vibration thresholds to maintain German Black Forest cluster relationships against emerging Asian competitors with faster compliance timelines.
For New Entrants and Emerging Players: Differentiate on cordless runtime optimization for 7-inch compact formats serving trim carpentry segments underserved by premium specialists. Target Asia-Pacific dealer network gaps in secondary Chinese cities where Makita distribution density thins. Lead with technical selection support capabilities that match application-specific procurement fragmentation.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because powder metallurgy capability scarcity will drive acquisition premiums for European specialists with certified cobalt-free formulations. Watch Italian carbide-tipping workforce pipeline constraints as the inflection signal indicating margin expansion windows for automated grinding technology adopters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Powder Production | Bavarian powder metallurgy partnerships reduce REACH compliance cost exposure for German manufacturers. |
| REACH-Compliant Formulation Certification | Nickel-binder alternatives from Italian specialists unlock continued EU market access before cobalt ceilings tighten. |
| Dealer Network Expansion in Asia-Pacific | Dense distribution in China's Yangtze River Delta captures professional carpentry contractor specification authority. |
| Micro-Grain Tip Miniaturization R&D | Sub-micron grain structures from Veneto expertise enable thinner saw plates for cordless runtime extension. |
| Application-Specific Portfolio Fragmentation | Discrete blade inventories for engineered wood substrates align with German custom furniture workshop procurement patterns. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured interviews with plant engineers at German precision woodworking clusters, procurement leads at North American millwork operations, carbide-tipping specialists in Italy's Veneto region, and aftermarket service heads at Asia-Pacific power tool distributors. Secondary validation incorporated customs records for tungsten powder trade flows, SEC filings from listed power tool manufacturers, OSHA enforcement action databases, and REACH pre-registration documentation from ECHA. Bottom-up blade shipment estimates triangulated against top-down construction spending correlations.
Across the analysis window, volume and value outputs reflect segmented modeling across blade type, application geometry, diameter format, and tooth count density. CAGRs were derived from replacement cycle compression factors tied to silica exposure enforcement and cobalt restriction timelines. Industry-specific forecast inputs incorporated METI energy-efficiency benchmark adoption curves and EU Green Deal sustainability certification penetration rates.
Material uncertainties — tungsten supply chain transparency rule revisions, brushless motor platform standardization outcomes, and precision grinding workforce pipeline constraints — sit outside the modeled envelope. Recalibration cycles align with material shifts in regulatory enforcement thresholds and ecosystem lock-in dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Mallets and Sledgehammers Market
Tools
MIG Guns Market
Tools
Drill Presses Market
Tools
Adoption of Benelux Power Tools Market
Tools
Dumpy Level Market
Tools
Horizontal Milling Machine Market
Tools
Land Survey Equipment Market
Tools
Spray Gun Market
Tools
Machine Tools Market
Tools
Measuring Wheels Market
Tools
Cordless Trim Routers Market
Tools
Industrial Cleaning Equipment Market
Tools
Brazing Torch Market
Tools
Woodworking Tools Market
Tools
Collated Screws Market
Tools
Global Cordless Power Tools Market