
 Brazing Torch Market | 2026-2036
Brazing Torch Market Size, Share, and Industry Trends Forecast 2026-2036
Brazing Torch Market Outlook
China's expanding precision manufacturing corridor is reshaping brazing torch supply dynamics. Illinois Tool Works Inc. leverages its diversified industrial portfolio to sustain North American distribution density. ESAB anchors European demand through specialized gas equipment engineering. Miller Electric Mfg. Co. competes on welding-adjacent brand recognition in contractor channels.
A brazing torch is a handheld thermal device that directs a controlled flame—typically fueled by acetylene, propane, or propylene mixtures at temperatures between 1,300°F and 2,200°F—to melt filler metals without liquefying base materials, enabling permanent joints in copper, brass, and steel assemblies. Its primary purpose spans HVAC refrigerant line connections, plumbing potable water systems, and automotive component fabrication. Oxygen-Acetylene configurations dominate commercial contractor use where flame intensity and portability matter most, while automatic technology segments capture margin pools in repetitive industrial settings. Metalworking applications lead volume consumption, though HVAC service channels show the strongest growth trajectory as heat-pump retrofits multiply.
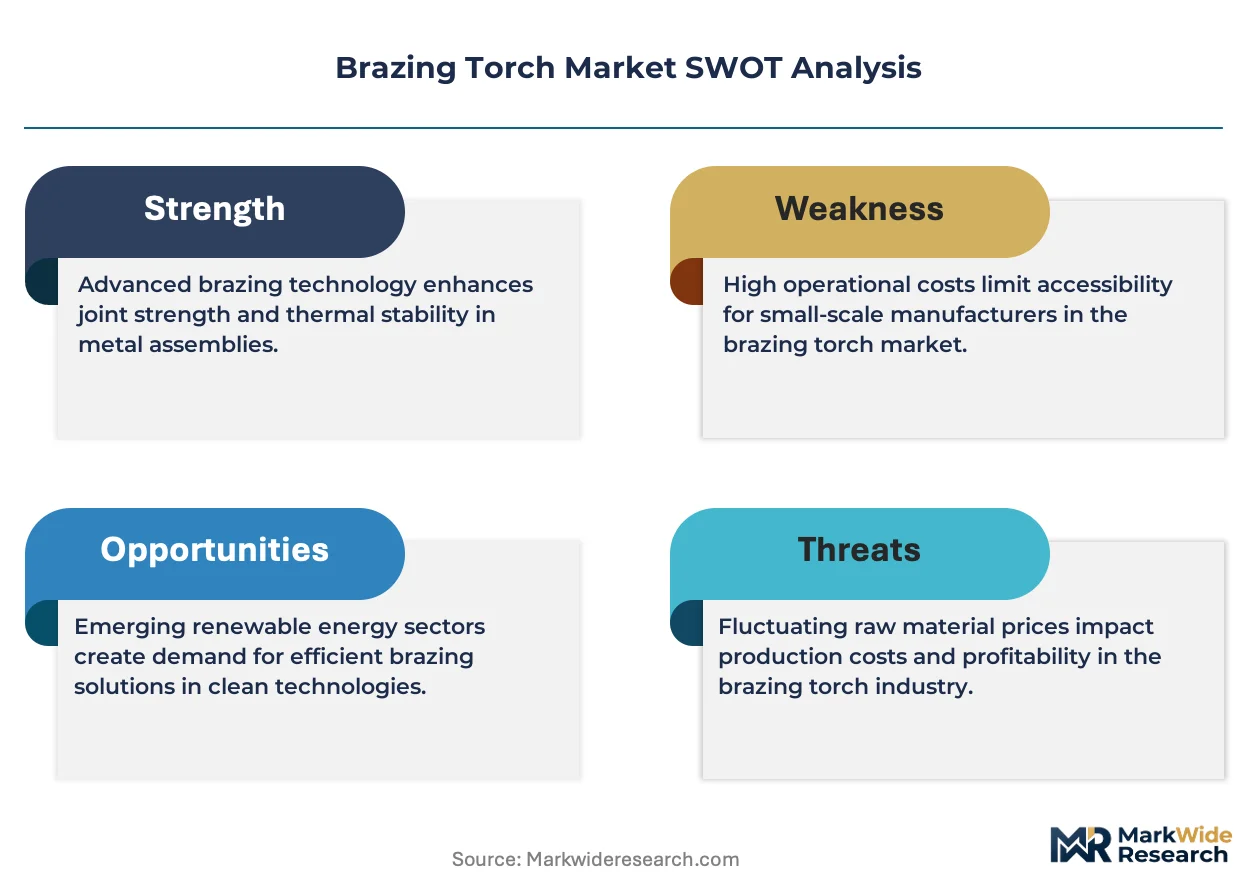
OSHA workplace safety standards and EPA refrigerant handling regulations directly shape product certification requirements and technician training protocols for brazing equipment distribution. The EU F-Gas Regulation and REACH compliance frameworks restrict certain gas compositions and torch component materials sold across European markets. Stakeholders must monitor evolving refrigerant chemistries and regional decarbonization timelines to align torch specification roadmaps with contractor workflow demands.
Market Dynamics
Heat-pump installation mandates across North American jurisdictions are compressing replacement cycles for HVAC infrastructure, forcing contractors to expand brazing torch inventories and accelerating equipment turnover in residential and commercial service channels.
Growth Catalysts
- EPA HFC Phasedown:The EPA's accelerated hydrofluorocarbon refrigerant phasedown under the AIM Act is forcing premature equipment retirement across commercial and residential HVAC systems, generating sustained brazing demand for line-set replacements and compressor swaps.
- Texas-Florida-California Permit Surge:Elevated residential construction permitting in these three states is concentrating HVAC installation volume and driving contractor fleet expansion for brazing-equipped service vehicles.
- Oxygen-Acetylene Intensity:Commercial contractors continue specifying high-flame-intensity oxygen-acetylene configurations for refrigerant line brazing, sustaining premium equipment demand despite alternative fuel availability.
Market Restraints
- Copper Price Volatility:Brazing filler metal formulations depend on copper and silver inputs, exposing torch consumables margins to London Metal Exchange commodity swings and supplier pass-through delays.
- Propane Supply Concentration:Regional propane distribution bottlenecks in the US Gulf Coast create intermittent fuel availability constraints for contractors relying on propylene torch alternatives.
- REACH Material Restrictions:The EU F-Gas Regulation and REACH compliance frameworks restrict certain brass alloy compositions and torch valve materials, fragmenting product certification requirements across Atlantic supply chains.
Strategic Opportunities
- Automatic Torch Integration:Repetitive manufacturing environments in automotive and appliance fabrication present white space for automatic brazing torch adoption, capturing margin pools beyond manual contractor channels.
- Heat-Pump Retrofit Subsidies:US Inflation Reduction Act residential energy efficiency tax credits are accelerating heat-pump conversions in legacy housing stock, expanding addressable brazing work for line-set reconfiguration.
- Plumbing Potable Water Codes:Updated IPC and UPC code adoptions across US municipalities are mandating lead-free brazed joints in domestic water systems, creating specification upgrade cycles.
Industry Challenges
- Brazing Certification Bottlenecks:AWS C3 brazing procedure qualification timelines and technician recertification requirements are constraining contractor workforce scaling in high-demand metropolitan markets.
- Refrigerant Chemistry Fragmentation:The proliferation of A2L mildly flammable refrigerants and CO2 transcritical systems is forcing brazing procedure recalibration and torch specification updates across service fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazing Torch Market |
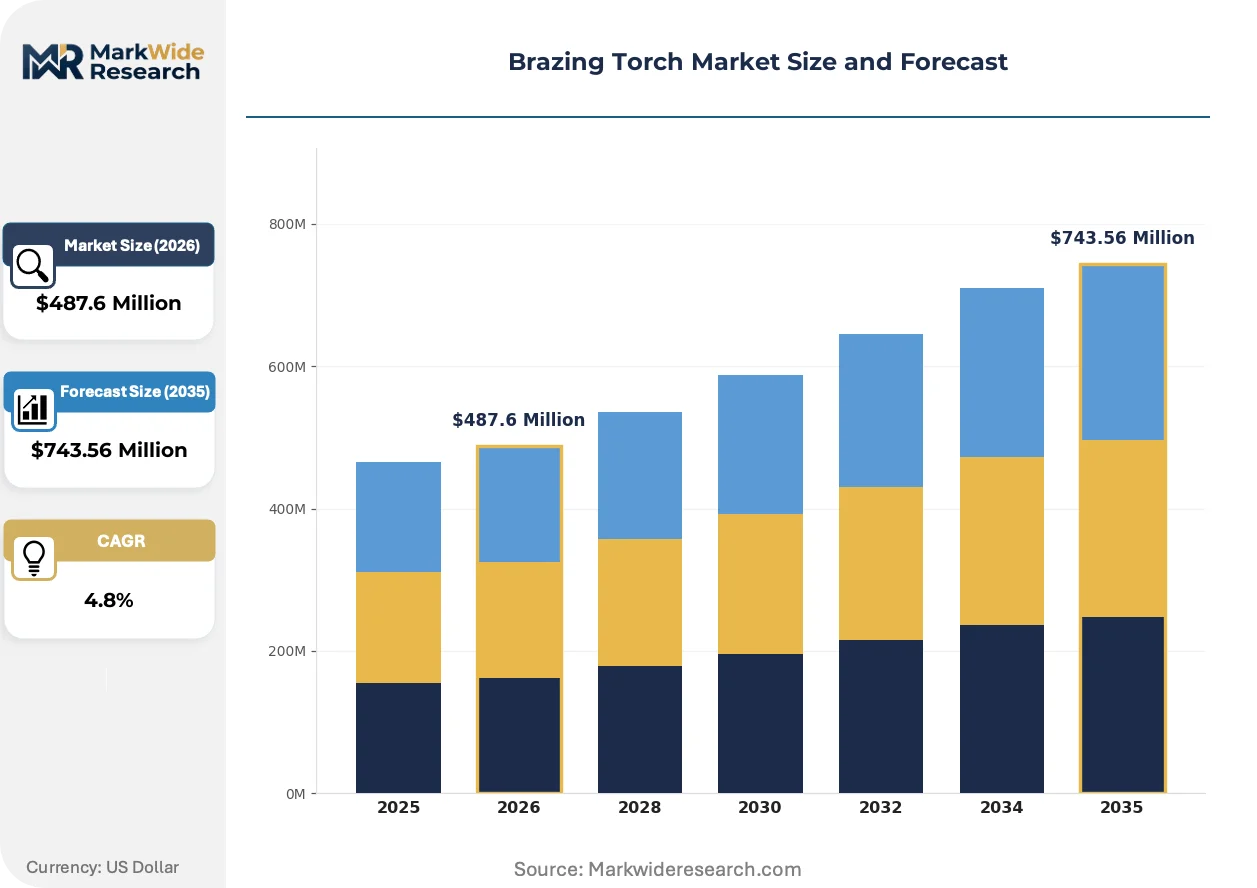
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Acetylene, Oxygen-Acetylene, Propylene, Others Application: Metalworking, Plumbing, HVAC, Tiling End User: Contractors, DIY Enthusiasts, Industrial Fabricators, Maintenance Providers Technology: Manual, Automatic, Semi-Automatic, Plasma |
| Companies Covered | Illinois Tool Works Inc., ESAB, Miller Electric Mfg. Co., Fronius International GmbH, SKS Welding Systems GmbH, EWM GmbH, Parweld LTD, ABICOR BINZEL USA, Inc., DINSE Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazing Torch Market Strategic Shifts
Equipment specification is pivoting toward flame precision and fuel flexibility as contractors face divergent refrigerant chemistries and joint quality requirements across HVAC, plumbing, and metalworking end-uses.
Propylene-air torch systems are migrating from propane-dominant contractor fleets as A2L refrigerant handling requirements demand lower flame temperatures and reduced heat-affected zones during line-set installation. HVAC service technicians in California and Florida are adopting these configurations fastest, with distributors reporting accelerated stock turnover. The technology is migrating from niche plumbing applications into mainstream residential HVAC channels, compressing oxygen-acetylene share in light-duty service work.
The EPA's refrigerant management certification requirements under Section 608 are tightening technician credentialing and equipment traceability mandates. Distributors must now link torch sales to certified technician registries, altering point-of-sale compliance workflows. Commercial HVAC contractors in Texas and the Southeast are responding by consolidating supplier relationships to reduce administrative burden.
Certification-driven supplier consolidation is altering procurement patterns as mid-sized contractors prioritize distributors offering bundled AWS training, EPA 608 exam access, and warranty support. Independent supply houses are losing share to integrated service providers. This behavioral shift is most visible in metropolitan Phoenix, Atlanta, and Dallas-Fort Worth markets where contractor density and regulatory enforcement intensity intersect.
Brazing Torch Market Segmentation
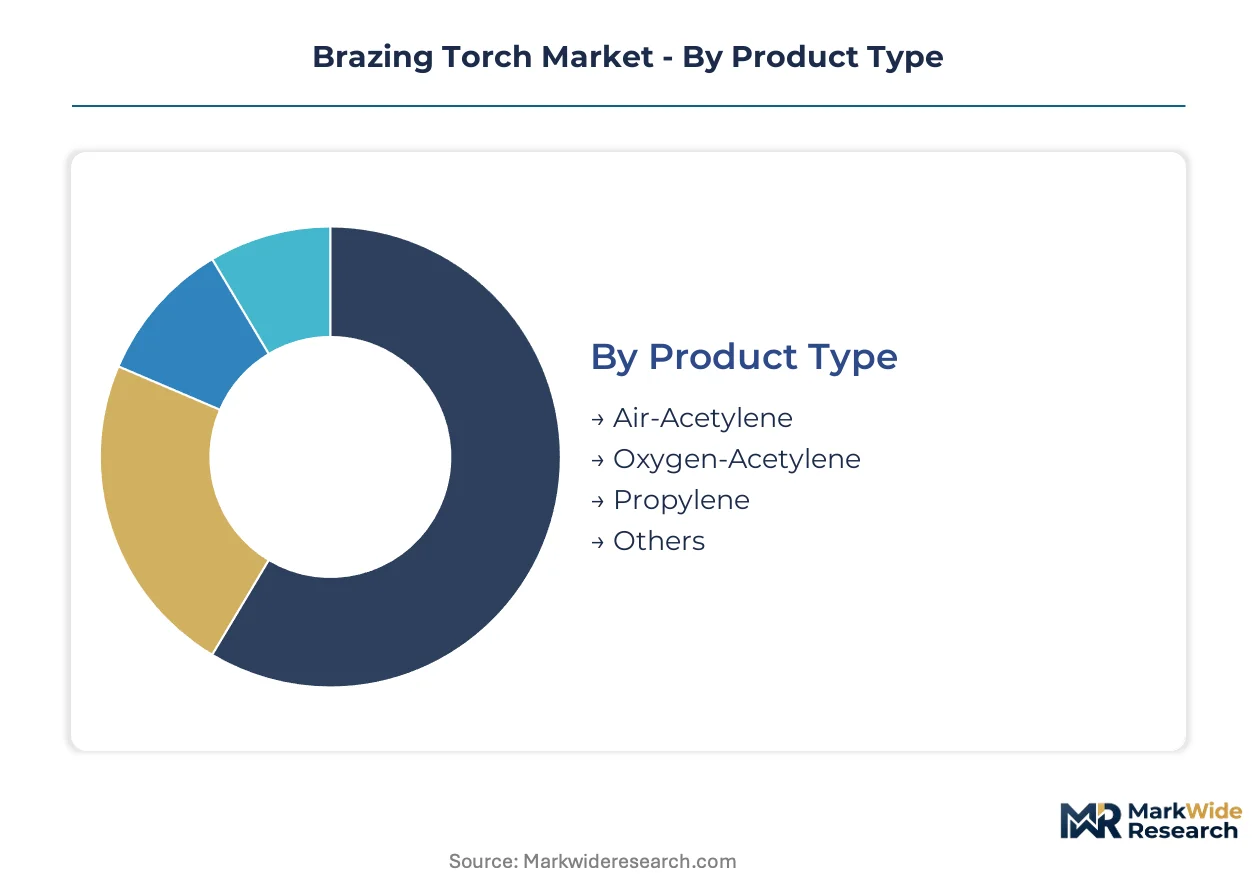
Equipment specification, maintenance protocols, and consumables replenishment vary sharply across brazing torch configurations. After-sales service intensity—spanning technician training, certification compliance, and warranty claim processing—differs fundamentally by product architecture and end-use environment.
Product Type:
Service attachment rates diverge most dramatically across fuel-system architectures, with oxygen-acetylene units demanding intensive recertification support while air-fuel alternatives minimize ongoing technical engagement.
- Oxygen-Acetylene:High-intensity flame systems operating at 2,200°F with dual-gas mixing precision dominate commercial HVAC and industrial metalworking. Demand concentrates among Texas and Florida contractors facing heat-pump installation mandates requiring robust refrigerant line brazing capacity.
- Propylene:Lower-flame-temperature configurations tailored for A2L refrigerant compatibility and reduced heat-affected zones are displacing propane in California residential service fleets. Distributors report accelerated stock turnover as technicians adapt to mild-flammability handling protocols.
- Air-Acetylene:Single-gas simplicity suits light-duty plumbing and portable field repair with minimal calibration overhead.
- Others:Specialty fuel blends and experimental gas combinations serve niche aerospace and electronics fabrication requirements.
Oxygen-Acetylene holds the largest share; momentum sits with Propylene as refrigerant chemistry shifts.
Application:
Margin profiles and replacement cycle timing vary by installation environment, with commercial infrastructure demanding scheduled maintenance contracts versus residential episodic failure response.
- HVAC:Refrigerant line connection work drives the steepest expansion trajectory as EPA HFC phasedown accelerates equipment replacement across Texas, Florida, and California permit-heavy markets. Service contracts now bundle torch recertification with seasonal maintenance.
- Metalworking:Fabrication floor brazing for automotive and appliance assembly sustains volume through repetitive joint production, with automatic torch integration capturing margin pools in high-throughput environments.
- Plumbing:Potable water system jointing faces upgraded IPC and UPC code mandates for lead-free assemblies across US municipalities.
- Tiling:Specialized heat application for surface preparation and material forming occupies a narrow craftsperson niche with limited distributor penetration.
Metalworking maintains volume dominance; HVAC climbs fastest on regulatory-forced equipment turnover.
End User:
Procurement authority and technical specification sophistication fragment sharply between fleet-scale contractors and individual operators.
- Contractors:Commercial HVAC service fleets in Phoenix, Atlanta, and Dallas-Fort Worth consolidate supplier relationships to streamline EPA 608 certification tracking and warranty administration. Consolidation favors distributors bundling training access with equipment procurement.
- Industrial Fabricators:Automotive and appliance manufacturers specify automatic brazing systems for repetitive joint production, demanding integration support and preventive maintenance contracts.
- Maintenance Providers:Facility-based repair operations prioritize equipment standardization across multi-site footprints to reduce technician training burden.
- DIY Enthusiasts:Hobbyist and homeowner segments purchase through retail channels with minimal technical support expectations and price-sensitive specification.
Contractors command the largest procurement volume; Industrial Fabricators offer the steepest margin expansion path.
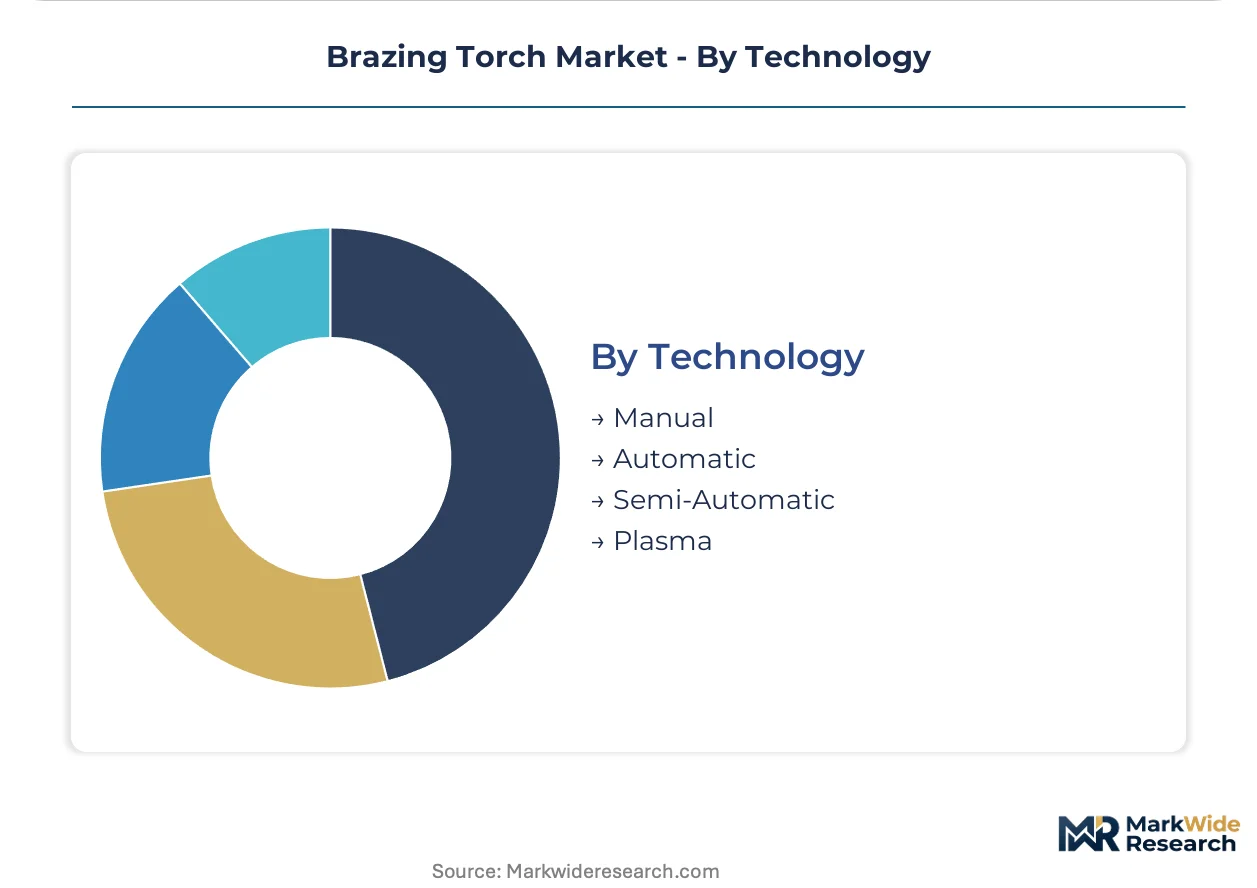
Technology:
Capital intensity and operator skill requirements create distinct competitive arenas across automation levels.
- Manual:Handheld flame control dominates field service work where joint access variability and portability requirements preclude fixed automation. Oxygen-acetylene configurations remain standard for commercial contractor fleets.
- Automatic:Programmable flame positioning and filler metal feed systems capture automotive and appliance manufacturing margin pools through throughput gains and joint consistency. Integration complexity demands specialized distributor technical support.
- Semi-Automatic:Hybrid systems balancing operator oversight with mechanized feed suit mid-volume fabrication environments seeking productivity gains without full automation investment.
- Plasma:High-energy density alternatives serve specialized cutting and surface preparation applications adjacent to traditional brazing workflows.
Manual technology retains the largest installed base; Automatic systems gain share fastest in manufacturing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies, with North American contractors prioritizing portable oxygen-acetylene systems for field HVAC work while Asian manufacturers drive automatic torch adoption for production-line integration.
United States
Heat-pump installation mandates in California and Florida are compressing HVAC replacement cycles and expanding contractor fleet inventories. The EPA's AIM Act phasedown of hydrofluorocarbon refrigerants accelerates equipment turnover requiring brazing work. Dallas-Fort Worth and Phoenix metropolitan clusters show concentrated demand as permitting activity elevates residential construction volume.
Germany
Automotive component fabrication sustains automatic brazing system demand among industrial fabricators serving OEM supply chains. The EU F-Gas Regulation and REACH compliance frameworks restrict brass alloy compositions and valve materials, fragmenting product certification requirements. Bavarian manufacturing corridors around Munich and Nuremberg anchor precision metalworking torch specification.
China
Precision manufacturing expansion across the Yangtze River Delta is reshaping supply dynamics for both manual and automatic torch configurations. The Ministry of Ecology and Environment enforces industrial emissions standards affecting gas equipment certification. Shanghai and Suzhou industrial clusters concentrate demand for high-throughput brazing automation in appliance and electronics fabrication.
Japan
Automotive and electronics manufacturers specify flame-precision equipment for miniaturized component assembly. METI energy efficiency directives influence industrial equipment procurement standards. The Chubu region around Nagoya maintains dense concentrations of tier-one automotive suppliers driving automatic torch integration.
India
HVAC infrastructure expansion amid urban cooling demand growth elevates contractor equipment procurement. The Bureau of Indian Standards mandates product certification for gas-operated equipment entering commercial channels. Maharashtra and Gujarat industrial corridors show emerging adoption of air-fuel torch systems for light-duty fabrication and installation work.
Brazing Torch Market Competitive Environment
Capability concentration sits with specialized gas equipment engineers; scale advantage sits with diversified industrial conglomerates. The vendor base organizes into three tiers: premium specialists commanding technical specification authority, mid-market fabricators competing on distribution density, and value-oriented assemblers serving price-sensitive procurement. Dominant competitive moves include geographic expansion through distributor network consolidation and portfolio diversification into adjacent welding and cutting equipment categories.
Within the premium engineering tier, ESAB and Fronius International GmbH exemplify European gas equipment specialization, while Illinois Tool Works Inc. represents diversified industrial scale with North American distribution density. Miller Electric Mfg. Co. occupies a position bridging welding-adjacent brand recognition and contractor channel penetration. These three anchors illustrate divergent strategic postures: technical leadership through specialized engineering, portfolio breadth enabling cross-selling, and brand equity transfer from complementary equipment categories.
| Leading Market Players |
|---|
| Illinois Tool Works Inc. |
| ESAB |
| Miller Electric Mfg. Co. |
| Fronius International GmbH |
| SKS Welding Systems GmbH |
| EWM GmbH |
| Parweld LTD |
| ABICOR BINZEL USA, Inc. |
| DINSE Inc. |
| Others |
Value Chain & Pricing Dynamics
China's Yangtze River Delta manufacturing clusters anchor global torch component supply, concentrating brass valve and precision nozzle production in a corridor that captures margin pools downstream through distributor certification bundling in North American contractor channels.
Pricing Analysis
Long-term offtake agreements dominate procurement for commercial HVAC fleets, while spot purchasing persists among independent contractors. Three-tier pricing structure across premium, standard, and economy levels separates oxygen-acetylene configurations bundled with AWS recertification from unbranded air-fuel alternatives. Price differentiation hinges on EPA 608 compliance documentation and regional warranty coverage depth. Pricing pressure stems from copper and silver filler metal commodity swings on the London Metal Exchange. DIY enthusiasts exhibit highest price sensitivity; industrial fabricators purchasing automatic systems show least sensitivity due to throughput ROI calculations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for brass alloy components and precision valve assemblies. Manufacturing concentrates in China, Germany, and Mexico for finished torch equipment, with consumables production anchored in China and India. Raw material dependencies center on copper cathodes, silver brazing alloys, and specialty brass formulations. Single-source vulnerability runs through precision nozzle suppliers serving automated torch integrators. Distribution runs through welding supply houses and HVAC wholesaler networks, with consolidated procurement platforms gaining share among multi-site contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AWS C3 certified technician scarcity constrains contractor fleet scaling in high-demand metropolitan markets, creating competitive advantage for distributors embedding training access within equipment procurement relationships.
For Market Incumbents: Entrench position through backward integration into brass valve component production and captive supply of EPA 608 certification tracking systems. Acquire regional welding supply houses in Phoenix, Atlanta, and Dallas-Fort Worth to consolidate distributor density before mid-tier competitors replicate bundled training models. Defend against propylene-air displacement by oxygen-acetylene incumbents through flame-intensity performance guarantees in commercial HVAC specifications. For New Entrants and Emerging Players: Establish a beachhead in automatic brazing system integration for automotive tier-one suppliers around Nagoya and Munich. Target the A2L refrigerant handling retrofit segment in California and Florida residential service fleets, where incumbent oxygen-acetylene positioning creates specification lag. Lead with propylene-air compatibility and reduced heat-affected zone documentation as the go-to-market angle, bypassing entrenched contractor relationships through direct-to-technician digital certification platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed welding equipment distributors lacking AWS training infrastructure or EPA compliance software integration. Long-term viability favors platforms consolidating procurement authority across multi-site commercial HVAC contractors. Watch for inflection signals in A2L refrigerant mandate acceleration across additional North American jurisdictions, which would compress oxygen-acetylene replacement cycles and reward propylene-air inventory positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Components | Captive valve supply secures margin pools against LME copper volatility and REACH compliance fragmentation. |
| AWS Certification Bundling | Embedded technician training locks commercial HVAC contractors into recurring recertification revenue streams. |
| Automatic Torch System Integration | Programmable flame positioning captures automotive OEM margin pools through joint consistency guarantees. |
| Propylene-Air Product Line Expansion | A2L refrigerant compatibility opens California and Florida residential retrofit channels ahead of incumbent response. |
| Distributor Network Consolidation | Multi-site contractor procurement authority concentrates in integrated platforms offering EPA 608 compliance tracking. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with HVAC service fleet managers, welding supply house procurement directors, AWS certification instructors, and EPA compliance officers; and secondary validation through SEC 10-K filings, customs trade records, and EPA refrigerant phasedown documentation. Bottom-up equipment shipment data triangulated against top-down construction permitting analysis across Texas, Florida, and California metropolitan clusters.
Forecast inputs considered fuel-system technology transitions, refrigerant chemistry migration timelines, and regional decarbonization policy intensity across the projection horizon. Segmentation modeling spanned product architecture, application environment, end-user procurement scale, and automation technology tier. CAGRs were derived from equipment replacement cycle compression analysis and contractor fleet expansion patterns. Specific inputs included heat-pump installation mandate adoption curves and A2L refrigerant handling protocol diffusion rates.
Stress conditions across copper price volatility bands, propane supply disruption scenarios, and REACH material restriction expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technician certification bottleneck resolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Water Pump Pliers Market
Tools
Digital Cutting Machine Market
Tools
Global DC Torque Tool Market
Tools
Europe Paint Spray Guns Market
Tools
Nut Runner Market
Tools
Global Sandblasting Media Market
Tools
Floor Polishing Machine Market
Tools
Mechanical Springs Market
Tools
Fastening Power Tools Market
Tools
Global Flange Fasteners Market
Tools
Vise-Grip Pliers Market
Tools
Forging Press Market
Tools
United States Machine Tools Market
Tools
Portable Pressure Washer Market
Tools
Cutting Tools Market
Tools
Pipe Alignment Clamps Market