
 Horizontal Milling Machine Market | 2026-2036
Horizontal Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Horizontal Milling Machine Market Foresight
Multi-axis CNC integration with real-time spindle monitoring is reconfiguring how horizontal milling centers deliver precision in high-volume production environments. DMG MORI CO., LTD. leverages its dual-brand manufacturing footprint across Japan and Germany to dominate premium five-axis installations. Haas Automation, Inc. competes aggressively on cost-standardized platforms that occupy the mid-market segment for job shops and contract manufacturers. Yamazaki Mazak Corporation anchors its position through in-house production of spindle motors and ball screws, sustaining margin control across its global distribution network.
A horizontal milling machine positions a horizontally oriented spindle to remove material from stationary or slowly fed workpieces, typically achieving cutting speeds between 8,000 and 20,000 RPM with through-spindle coolant delivery for deep-cavity machining in hardened steels and titanium alloys. CNC Machines command the largest revenue share as aerospace and automotive OEMs mandate programmable repeatability for complex part families. Manual Machines retain stable demand among maintenance providers and small workshops performing one-off repairs where programming overhead exceeds cycle efficiency. Robotics integration represents the fastest-expanding technology dimension, with automated pallet pools and robotic part loading displacing standalone conventional milling in high-mix, high-volume operations.
The EU Machinery Directive and CE marking requirements enforce interlocked guarding and emergency-stop protocols that shape product design for European-bound equipment, while China's GB standards and MIIT industrial upgrade directives accelerate domestic replacement of imported manual machines with CNC-certified platforms. OSHA lockout/tagout rules and EPA metalworking fluid exposure limits in the United States add compliance layers that favor enclosed, coolant-recirculating horizontal mill architectures over open manual designs. Stakeholders must monitor how evolving carbon-accounting frameworks and energy-efficiency certifications reshape capital equipment procurement criteria across major manufacturing economies.
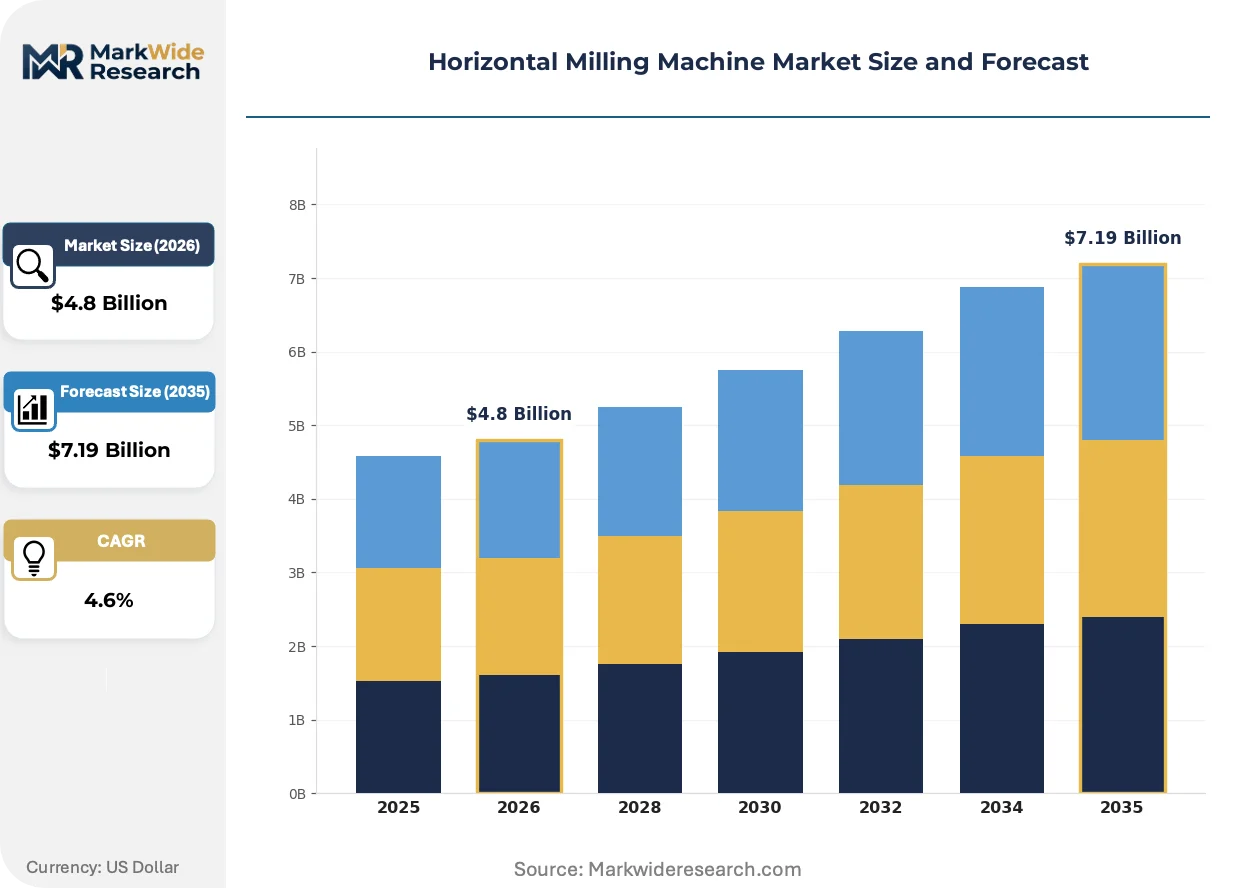
Market Dynamics
Multi-axis CNC horizontal mills with real-time spindle monitoring are compressing setup times and forcing manual equipment obsolescence across aerospace and automotive supplier networks. This technological inflection concentrates procurement power among OEMs capable of absorbing automation capex while marginalizing job shops dependent on legacy platforms.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for interlocked guarding and emergency-stop protocols are accelerating replacement cycles for European-bound equipment, favoring enclosed CNC architectures over open manual designs.
- Aerospace powertrain component production:Titanium alloy machining for turbine housings and transmission cases demands through-spindle coolant delivery at 15,000-plus RPM, specifications that only horizontal configurations reliably achieve.
- Japan's METI industrial upgrade directives:Subsidies for smart factory investments are channeling capital toward robotic pallet pools and automated part loading systems integrated with five-axis horizontal centers.
Market Restraints
- Ball screw and linear guide supply concentration:Japanese and German specialty manufacturers control precision motion component supply, exposing horizontal mill builders to 12-18 month lead time volatility for high-accuracy feed systems.
- OSHA lockout/tagout compliance costs:Enclosed guarding and interlock certification for US-bound equipment adds $15,000-$40,000 per installation, compressing margins on mid-market platforms.
- Wire EDM substitution in deep-cavity hardened steel:Electrical discharge machining achieves finer surface finishes in mold and die applications below 0.4 micron Ra, capturing workpieces previously routed to high-speed horizontal mills.
Strategic Opportunities
- India's PLI scheme for precision engineering:Production-linked incentives for capital goods manufacturing are attracting horizontal mill assembly investments serving domestic automotive and defense supplier networks.
- Carbon-accounting framework integration:EU CSRD disclosure requirements for Scope 3 emissions are creating specification pull for energy-efficient spindle motors and coolant recirculation systems that reduce operational carbon intensity.
- Robotics convergence with machine vision:Automated in-process inspection integrated directly into horizontal mill work envelopes enables lights-out operation for high-mix medical implant production.
Industry Challenges
- CNC programming and five-axis simulation expertise scarcity:Aerospace tier-one suppliers report 8-14 month hiring timelines for operators capable of optimizing tool paths for complex titanium geometries.
- Legacy DNC network integration complexity:Brownfield facilities running RS-232 or Ethernet-based distributed numerical control require costly gateway hardware to connect modern horizontal mills to enterprise MES platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Horizontal Milling Machine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Machines, Manual Machines, CNC Machines, Hybrid Machines Application: Aerospace, Automotive, Metal Fabrication, Woodworking End User: Manufacturers, Workshops, Research Facilities, Maintenance Providers Technology: Conventional Milling, CNC Technology, Advanced Milling, Robotics |
| Companies Covered | DMG MORI CO., LTD., JTEKT Machinery Americas Corporation, Haas Automation, Inc., Yamazaki Mazak Corporation, Okuma Corporation, Hurco Companies, Inc., EMAG GmbH & Co. KG, Doosan Machine Tools Co., Ltd., Hardinge Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Horizontal Milling Machine Market Shifts & Advancements
Digital thread integration from CAD through CAM to machine controller is collapsing engineering-to-production lead times and enabling lot-size-one economics previously uneconomical for horizontal milling operations.
Sensor-embedded spindle cartridges with vibration and temperature telemetry are digitizing predictive maintenance protocols for aerospace manufacturers running titanium alloys at sustained high RPM. Boeing and Airbus tier-one suppliers deploy these systems to eliminate unplanned downtime during critical path production windows. The data streams compress insurance and warranty costs while enabling outcome-based service contracts that shift revenue from equipment sale to uptime guarantee.
China's GB standards for metal-cutting machinery safety and MIIT directives for industrial equipment upgrade are mandating domestic CNC certification for imported horizontal mill platforms. Foreign manufacturers must establish local testing partnerships and documentation in Mandarin to maintain market access. The regulatory friction favors domestic builders like Shenyang Machine Tool while forcing joint venture structures for premium European and Japanese entrants.
Automotive OEM procurement teams now specify total cost of ownership metrics spanning energy consumption, coolant disposal, and spindle rebuild intervals rather than upfront capital expenditure alone. Tier-one powertrain suppliers in Germany and the United States respond with lease-based financing and performance-guaranteed service agreements. This buying-pattern shift compresses equipment vendor margins while extending customer lifetime value for providers capable of delivering remote diagnostics and rapid spare parts logistics.
Horizontal Milling Machine Market Segmentation
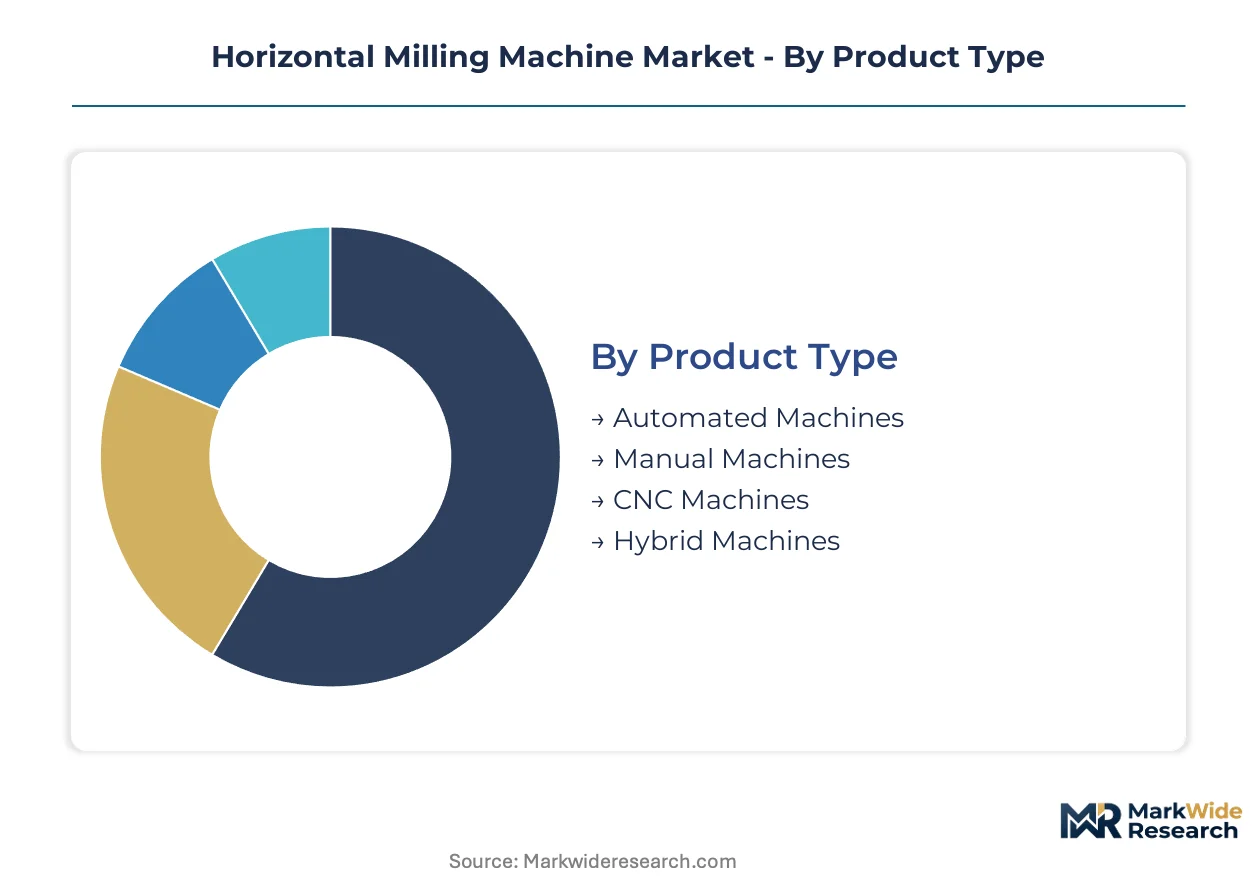
Horizontal milling machine procurement patterns diverge sharply between high-volume aerospace OEMs demanding five-axis CNC repeatability and small workshops performing one-off repairs. Understanding these segment boundaries clarifies where automation capex concentrates versus where manual platforms retain viability.
Product Type:
Workpiece complexity and batch size determine whether operators invest in programmable automation or retain mechanical simplicity for intermittent use.
- CNC Machines:Programmable multi-axis platforms achieve cutting speeds between 8,000 and 20,000 RPM with through-spindle coolant delivery. Aerospace and automotive OEMs in Germany, Japan, and the United States mandate this repeatability for titanium alloy turbine housings and powertrain components.
- Automated Machines:Robotic pallet pools and automated part loading systems integrate with horizontal centers for lights-out operation. Japan's METI subsidies channel capital toward these configurations for high-mix medical implant production.
- Manual Machines:Mechanical feed and spindle control serves maintenance providers and small workshops performing one-off repairs where programming overhead exceeds cycle efficiency.
- Hybrid Machines:Manual-CNC crossover platforms offer programmable positioning with hand-override capability for prototype shops transitioning between development and limited production.
Established volume favors CNC Machines; emerging adoption favors Automated Machines.
Application:
Material hardness and surface finish specifications dictate horizontal mill selection across end-use sectors.
- Aerospace:Titanium alloy machining for turbine housings and transmission cases demands through-spindle coolant at 15,000-plus RPM. Boeing and Airbus tier-one suppliers deploy sensor-embedded spindle cartridges with vibration telemetry to eliminate unplanned downtime.
- Automotive:Powertrain component production favors horizontal configurations for deep-cavity machining in hardened steels. German OEM procurement teams now specify total cost of ownership metrics spanning energy consumption and spindle rebuild intervals.
- Metal Fabrication:General-purpose structural component machining employs mid-market platforms for batch production of industrial equipment frames and enclosures.
- Woodworking:Horizontal spindle orientation serves specialized joinery and millwork applications requiring angled cutting planes on large timber sections.
Aerospace commands premium specification density; automotive delivers highest unit volume.
End User:
Capital availability and technical staffing determine automation tier selection across customer types.
- Manufacturers:Tier-one suppliers with dedicated CAM programming staff absorb multi-axis CNC capex for contract production of complex part families.
- Workshops:Job shops and independent fabricators balance equipment cost against utilization rates, often selecting manual or entry-level CNC platforms.
- Research Facilities:University and government laboratories prioritize flexibility over throughput for materials science and prototype development.
- Maintenance Providers:Field repair operations retain manual machines for on-site component restoration where electrical infrastructure limits automated equipment deployment.
Manufacturers drive technology upgrade cycles; maintenance providers sustain legacy platform demand.
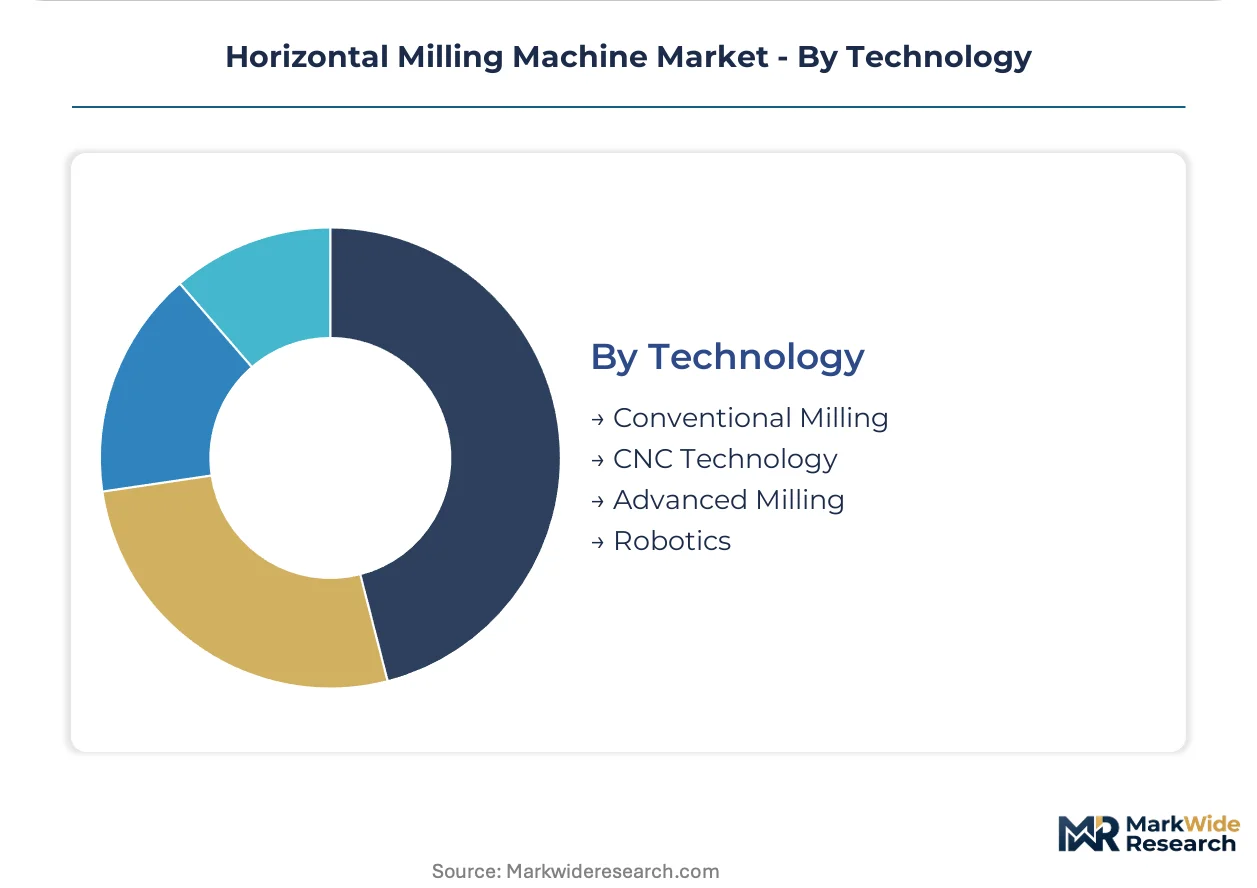
Technology:
Control architecture and motion system sophistication separate conventional mechanical systems from digitally integrated production cells.
- Robotics:Automated in-process inspection with machine vision enables lights-out operation. EU CSRD disclosure requirements for Scope 3 emissions create specification pull for these energy-efficient configurations.
- CNC Technology:Multi-axis programmable control with real-time spindle monitoring compresses setup times and forces manual equipment obsolescence across aerospace supplier networks.
- Advanced Milling:Sensor-embedded spindles with predictive maintenance protocols digitize uptime guarantees for outcome-based service contracts.
- Conventional Milling:Mechanical gear-driven spindles and hand-cranked table feeds persist in emerging markets and maintenance applications with limited technical staffing.
Robotics climbs the fastest; conventional milling retains residual demand in cost-constrained segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement power concentrates with aerospace tier-one suppliers in Germany, Japan, and the United States, while automotive OEMs in these same markets drive standardization toward multi-axis CNC platforms.
Germany
Aerospace powertrain component demand and automotive OEM specification of total cost of ownership metrics dominate procurement patterns. CE marking requirements under the EU Machinery Directive enforce interlocked guarding and emergency-stop protocols. Stuttgart and Munich industrial clusters host dense supplier networks machining titanium alloy turbine housings for Airbus tier-one contracts.
Japan
METI industrial upgrade directives channel subsidy capital toward smart factory investments and robotic pallet pool integration. JIS standards certification and domestic spindle motor production sustain margin control for precision equipment builders. Nagoya and Osaka manufacturing corridors concentrate five-axis horizontal center installations for medical implant production.
United States
Boeing and Airbus tier-one suppliers deploy sensor-embedded spindle cartridges with predictive maintenance protocols to eliminate unplanned downtime. OSHA lockout/tagout rules and EPA metalworking fluid exposure limits favor enclosed, coolant-recirculating architectures. Seattle and Wichita aerospace clusters mandate programmable repeatability for complex titanium geometries.
China
MIIT directives for industrial equipment upgrade accelerate domestic replacement of imported manual machines with CNC-certified platforms. GB standards for metal-cutting machinery safety mandate local testing partnerships and Mandarin documentation. Shenyang and Shanghai manufacturing bases concentrate domestic builder assembly investments serving automotive supplier networks.
India
PLI scheme production-linked incentives for capital goods manufacturing attract horizontal mill assembly investments for domestic automotive and defense applications. BIS certification requirements shape import compliance for precision equipment. Pune and Chennai industrial corridors host expanding supplier networks for powertrain component machining.
Horizontal Milling Machine Market Competitive Landscape
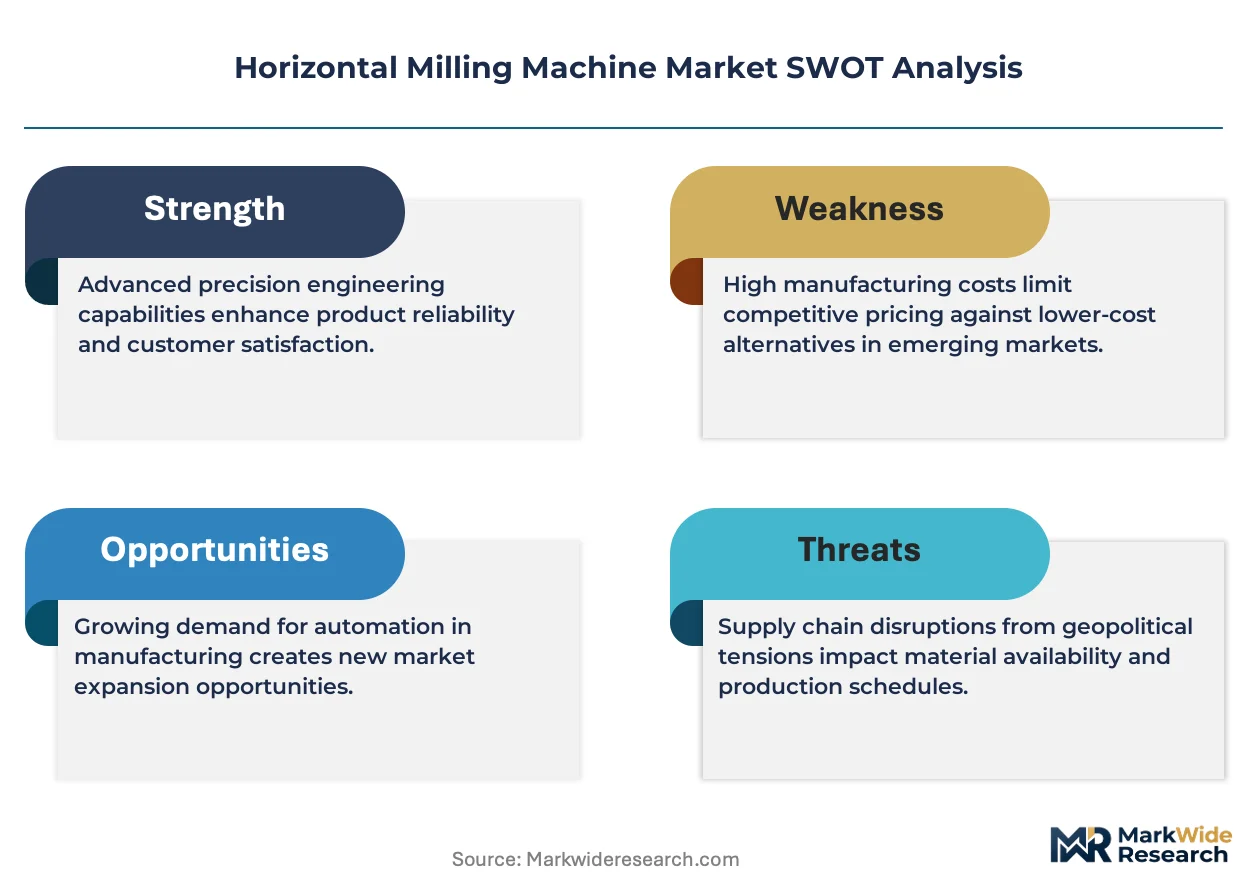
Channel-controlling players compete with product-specialist players across a tiered structure where premium five-axis installations, mid-market standardized platforms, and cost-optimized entry-level systems occupy distinct competitive zones. Japanese and German manufacturers dominate precision motion component supply, exposing builders to feed system lead time volatility. Three archetypes prevail: dual-brand transnational operators, in-house component integrators, and cost-standardized platform specialists. Competitive moves concentrate on geographic manufacturing footprint expansion and strategic technology licensing arrangements.
Among Japanese-headquartered precision equipment builders, DMG MORI CO., LTD. and Yamazaki Mazak Corporation occupy positions representing dual-brand and in-house component integration archetypes respectively. Haas Automation, Inc. exemplifies the cost-standardized platform specialist model competing aggressively in mid-market segments. These three entities anchor the competitive topology without exhausting the vendor landscape.
| Leading Market Players |
|---|
| DMG MORI CO., LTD. |
| JTEKT Machinery Americas Corporation |
| Haas Automation, Inc. |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Hurco Companies, Inc. |
| EMAG GmbH & Co. KG |
| Doosan Machine Tools Co., Ltd. |
| Hardinge Inc. |
| Others |
Supply & Pricing Matrix
Japanese and German specialty manufacturers of ball screws and linear guides anchor upstream precision motion component supply, concentrating margin pools with tier-one equipment builders capable of securing 12-18 month allocation contracts. This feed system bottleneck cascades downstream into pricing power asymmetries between premium five-axis integrators and mid-market platform assemblers.
Pricing Analysis
Cost-plus contracts with steel and rare-earth magnet indexation dominate horizontal mill procurement between aerospace tier-one suppliers and Japanese equipment builders. Three-tier pricing structure across premium five-axis installations, standardized mid-market platforms, and entry-level manual systems separates DMG MORI and Yamazaki Mazak from Haas Automation on specification density. Cost compression in mid-market CNC platforms is intensifying because automotive OEM procurement teams now specify total cost of ownership metrics spanning energy consumption and spindle rebuild intervals. Maintenance providers and small workshops exhibit highest price sensitivity, while aerospace tier-one suppliers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Contract manufacturing concentration rests with DMG MORI's dual-brand facilities across Japan and Germany, Yamazaki Mazak's in-house spindle motor production in Aichi Prefecture, and Haas Automation's Oxnard, California assembly campus. Precision ball screws, linear motion guides, and ceramic spindle bearings draw from concentrated Japanese and German supplier networks. Single-source vulnerability in high-accuracy feed systems exposes builders to allocation constraints during aerospace production ramp-ups. Distribution runs through manufacturer-direct sales engineers serving tier-one OEMs, with regional distributors handling mid-market job shop accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a switching-cost fortress where aerospace tier-one suppliers face 8-14 month requalification timelines to certify alternative equipment builders for titanium alloy turbine housing production. Regulatory entrenchment through CE marking, JIS certification, and OSHA lockout/tagout compliance deepens incumbent moats.
For Market Incumbents: Build captive supply agreements for precision ball screws and linear guides to insulate margin pools from Japanese feed system allocation volatility. Expand spindle rebuild service center footprints in Germany and the United States to capture aftermarket revenue streams. Wire EDM substitution in deep-cavity hardened steel applications threatens horizontal mill share in mold and die segments; counter with through-spindle coolant performance guarantees.
For New Entrants and Emerging Players: India's PLI scheme production-linked incentives for capital goods manufacturing represent the most penetrable entry point for horizontal mill assembly investments serving domestic automotive and defense supplier networks. Carbon-accounting framework integration under EU CSRD disclosure requirements creates specification pull for energy-efficient spindle motors that domestic Chinese builders struggle to certify. Partner with Shenyang Machine Tool or local testing laboratories to navigate GB standards compliance documentation.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic pallet pool integration and automated part loading systems as Japan's METI subsidies channel smart factory investment. Acquisition targets should prioritize equipment builders with in-house spindle motor production and established aerospace tier-one supplier relationships. Monitor quarterly order intake from Boeing and Airbus tier-one contracts as inflection indicator for production capacity utilization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spindle Motors | Yamazaki Mazak's captive production of ball screws insulates margin control from feed system volatility. |
| Robotic Pallet Pool Integration | Japan's METI subsidies accelerate smart factory capital deployment for high-mix medical implant production. |
| Energy-Efficient Spindle Certification | EU CSRD disclosure requirements create specification pull for coolant recirculation systems reducing carbon intensity. |
| Regional Assembly Investment | India's PLI scheme attracts horizontal mill assembly serving domestic automotive and defense supplier networks. |
| Predictive Maintenance Service Contracts | Sensor-embedded spindle cartridges enable outcome-based revenue shifting from equipment sale to uptime guarantee. |
Research Methodology
A standing panel of plant engineers at aerospace tier-one suppliers, aftermarket service directors, OEM procurement managers, and horizontal mill distribution channel partners provided ongoing calibration across the study period. Primary interviews combined with secondary validation from SEC 10-K filings, Japanese Ministry of Economy Trade and Industry subsidy disclosures, EU Machinery Directive compliance databases, and customs trade data for precision machine tool imports. Bottom-up equipment shipment data triangulated against top-down aerospace and automotive capital expenditure surveys.
Scenario-bracketing framed demand projections across the analysis window, modeling conservative, baseline, and accelerated automation adoption pathways. Segmentation dimensions included product type, application sector, end-user capital availability, and technology integration level. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline impacts, and aerospace production ramp schedules. Forecast inputs incorporated METI smart factory subsidy allocation rates and Boeing-Airbus supplier network expansion plans.
Macroeconomic conditions sit as an overlay; deviation in aerospace OEM production schedules, automotive powertrain electrification investment, or Japanese feed system allocation constraints would shift the trajectory. Quarterly review of tier-one supplier capital expenditure announcements and precision motion component lead time indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Planer Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Bar Clamp Market
Tools
Boring Tools Market
Tools
Tension Tester Market
Tools
Pruning Saw Market
Tools
Indexable Inserts Market
Tools
Brazing Torch Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Grabber Pole Market
Tools
Machine Bench Vices Market
Tools
Woodcarving Tool Market
Tools
Engraver Machine Market
Tools
Impact Wrenches Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Power Nibbler Market