
 Chronic Pain Market | 2026-2036
Chronic Pain Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Pain Market Intelligence
Software-defined dosing algorithms in implantable neuromodulation systems is decoupling hardware sales from recurring revenue streams. Medtronic PLC anchors its portfolio through proprietary closed-loop programming that locks clinicians into subscription-based therapy optimization. Pfizer Inc. competes by leveraging its manufacturing scale across oral analgesic portfolios. Abbott Laboratories differentiates through vertical control over both device fabrication and cloud-based patient monitoring infrastructure.
Chronic pain encompasses persistent nociceptive or neuropathic discomfort lasting beyond normal tissue healing time, typically three to six months, measured via visual analog scales and functional impairment indices. The condition originates from peripheral nerve sensitization, central nervous system plasticity, or inflammatory cascade dysregulation, requiring sustained pharmacological or interventional management to restore patient function. Analgesics and neuropathic pain medications capture the dominant share of pharmaceutical spending due to established reimbursement and broad prescriber familiarity. Implantable delivery modes represent the fastest-expanding category as device manufacturers bundle hardware with remote programming services. Oral formulations remain mature with margin compression from generic substitution, while topical segments occupy niche positions in localized musculoskeletal applications.
FDA opioid REMS modifications and EMA pharmacovigilance requirements for central nervous system agents are redirecting development investment toward non-addictive mechanisms. The EU MDR framework imposes stricter clinical evidence thresholds on implantable pain devices, extending approval timelines and favoring incumbents with established PMCF databases. Stakeholders must monitor evolving payer criteria for digital therapy adjuncts as health technology assessment bodies in Germany and Japan weigh software-enabled outcomes against conventional pharmacoeconomic models.
Market Dynamics
FDA opioid REMS modifications and EMA pharmacovigilance mandates are redirecting pharmaceutical investment toward non-addictive analgesic mechanisms, while implantable neuromodulation systems decouple hardware revenue from recurring software subscriptions.
Growth Catalysts
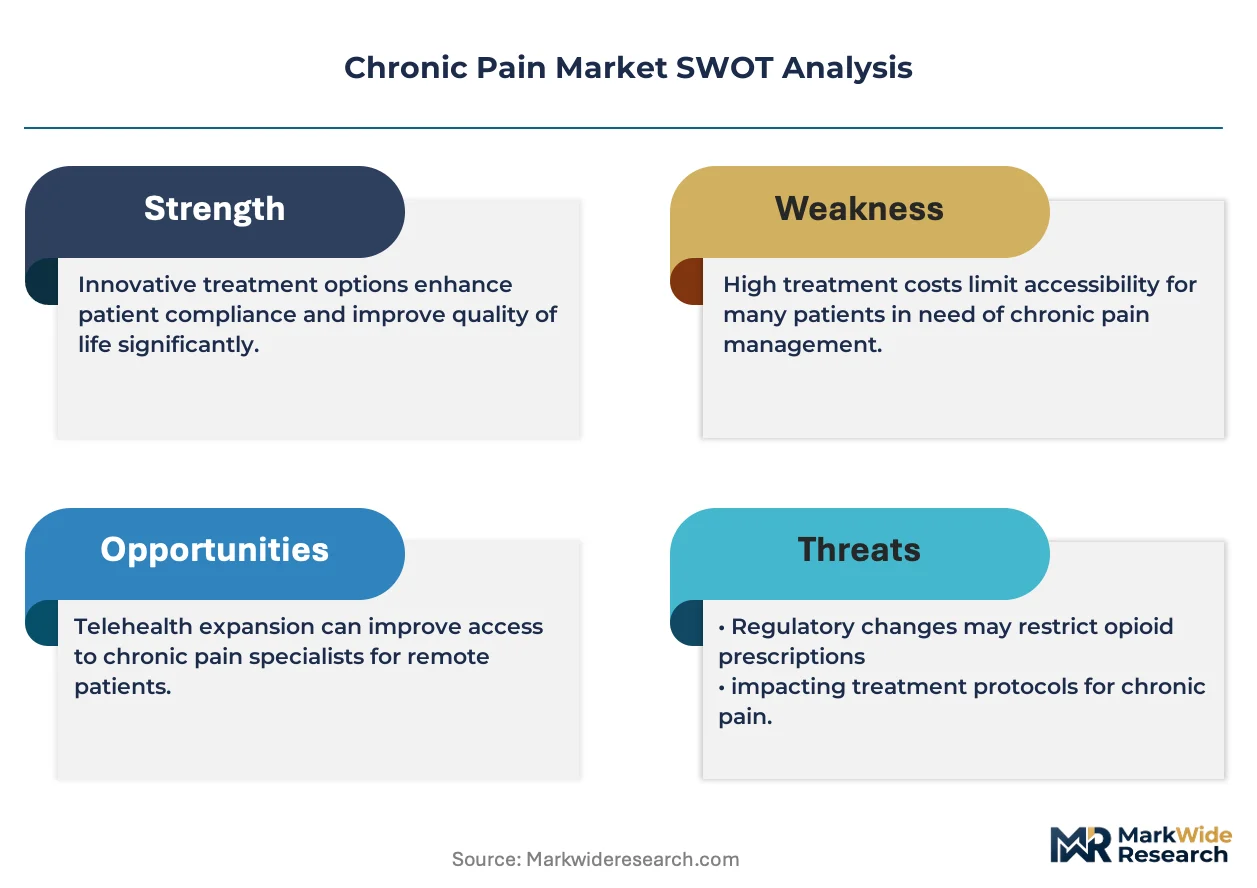
- EU MDR framework:Stricter clinical evidence thresholds on implantable pain devices extend approval timelines and favor incumbents with established PMCF databases, consolidating market position among prepared manufacturers.
- Aging demographics in Japan and Germany:Expanding patient populations with reimbursement access for multimodal pain management programs drive demand for sustained pharmacological and interventional therapies.
- Closed-loop programming technology:Software-defined dosing algorithms in implantable systems create subscription-based therapy optimization, locking clinicians into recurring revenue relationships with device manufacturers.
Market Restraints
- Generic substitution pressure:Oral analgesic formulations face margin compression as patent expirations enable low-cost competitors, constraining branded pharmaceutical profitability.
- Extended EU MDR approval timelines:Stricter clinical evidence requirements delay market entry for novel implantable devices, increasing capital requirements and technical documentation burdens.
- Central nervous system pharmacovigilance:EMA requirements for enhanced safety monitoring increase development costs and regulatory uncertainty for novel neuropathic pain agents.
Strategic Opportunities
- Digital therapy adjuncts:Health technology assessment bodies in Germany and Japan are evaluating software-enabled outcomes against conventional pharmacoeconomic models, creating reimbursement pathways for integrated care platforms.
- Remote programming services:Cloud-based patient monitoring infrastructure bundled with implantable hardware enables geographic expansion beyond traditional clinical settings.
- Topical localized applications:Niche positioning in musculoskeletal pain offers differentiated entry points with reduced systemic safety concerns and simpler regulatory pathways.
Industry Challenges
- PMCF database construction:Post-market clinical follow-up requirements under EU MDR demand substantial investment in real-world evidence collection, straining mid-tier device manufacturers.
- Neuromodulation programming expertise:Closed-loop therapy optimization requires specialized clinical training, creating bottlenecks in patient access and device utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Pain Market |
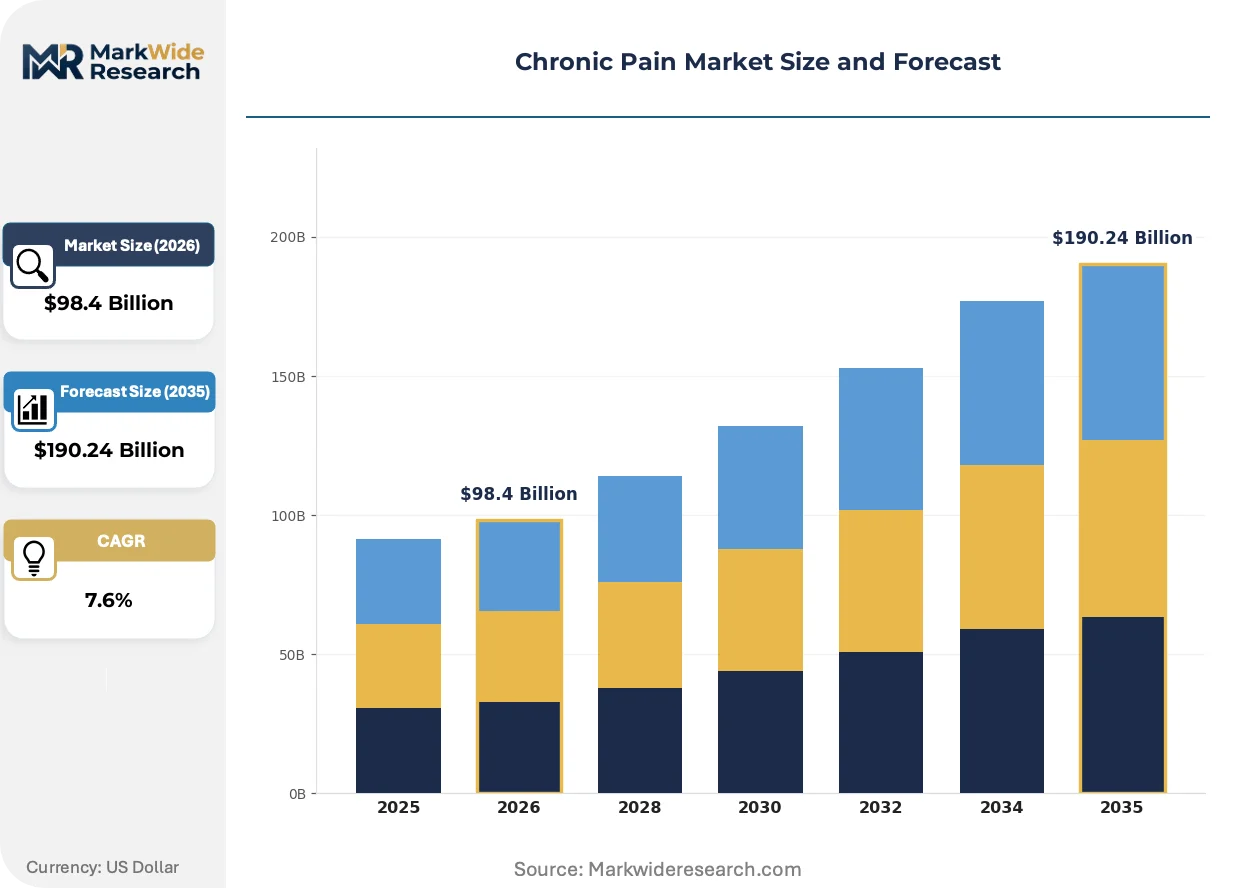
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $190.24 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anti-inflammatories, Neuropathic Pain Medications Therapy Area: Fibromyalgia, Arthritic Pain, Neuropathic Disorders, Headaches Delivery Mode: Oral, Injectable, Topical, Implantable End User: Hospitals, Outpatient Clinics, Home Care, Rehabilitation Centers |
| Companies Covered | Pfizer Inc., Abbott Laboratories, Novartis AG, Medtronic PLC, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd., Johnson & Johnson, Grünenthal GmbH, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Pain Market Strategic Shifts & Innovations
Neuromodulation hardware is converging with software-defined therapy management, while regulatory frameworks on both sides of the Atlantic accelerate the shift away from opioid-centric pain management toward mechanistically novel alternatives.
Closed-loop spinal cord stimulation systems are expanding into chronic pain management through automated adjustment algorithms that respond to patient-specific physiological signals. Hospital systems and ambulatory surgical centers are adopting these platforms to reduce manual programming burden and improve long-term outcomes. The technology is expanding into subscription-based revenue models that decouple device sales from ongoing clinical optimization services.
EMA pharmacovigilance requirements for central nervous system agents are tightening safety monitoring obligations for novel analgesic candidates. Development programs now incorporate extensive real-world evidence collection and adaptive trial designs to satisfy evolving benefit-risk assessments. Small-molecule neuropathic pain programs face heightened scrutiny, redirecting investment toward peripherally restricted mechanisms with cleaner central nervous system profiles.
Hospital procurement committees are unbundling after-sales service contracts from device capital purchases, forcing manufacturers to demonstrate standalone value for programming support and remote monitoring. This shift pressures traditional bundled pricing models and favors vendors with transparent software licensing structures. Germany's hospital procurement reforms and Japan's Diagnosis Procedure Combination system revisions are accelerating this behavioral change among institutional buyers.
Chronic Pain Market Segmentation
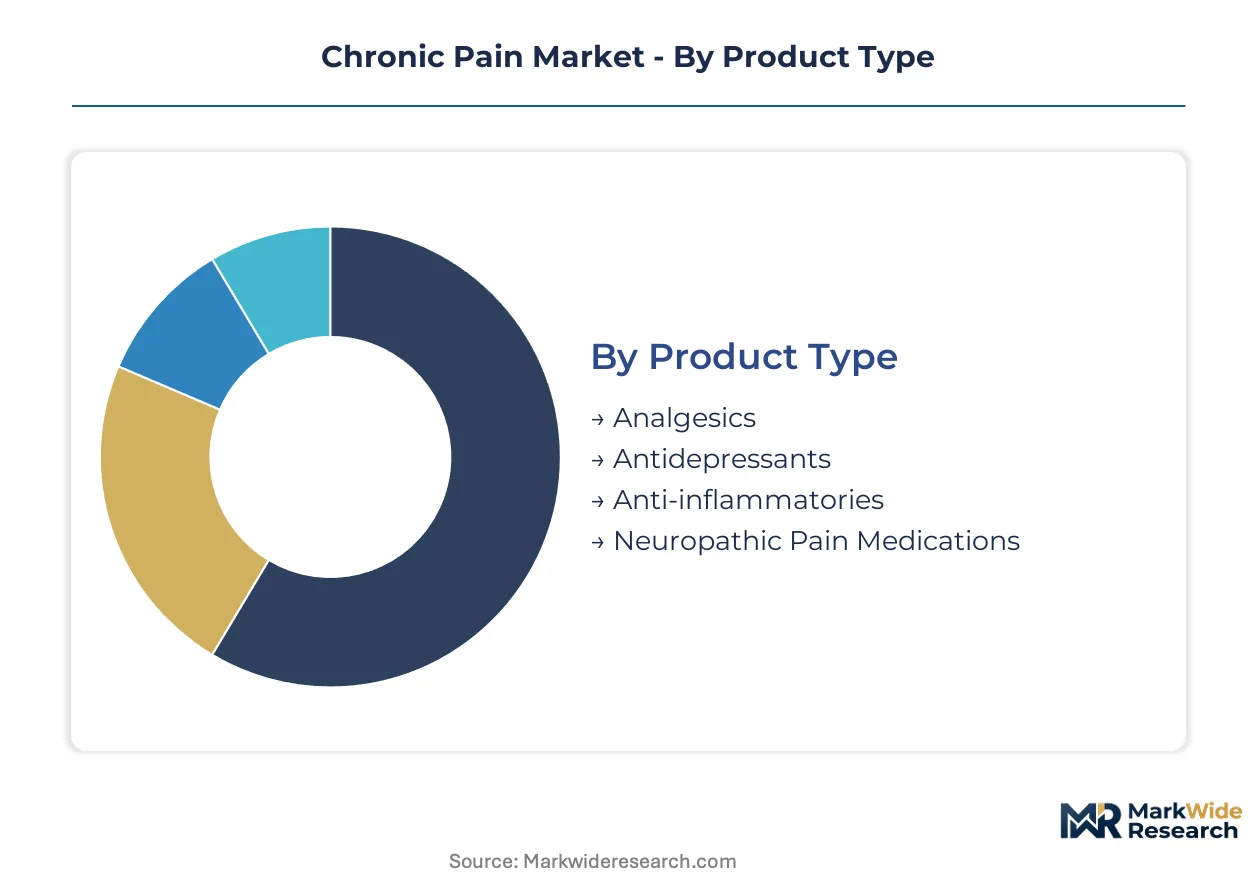
Pain management strategies diverge sharply across patient populations, forcing manufacturers to align R&D investment with distinct reimbursement pathways and clinical settings. Segmentation reveals where hardware-software convergence commands premium pricing versus where generic substitution erodes margins.
Product Type:
Supply concentration clusters around patented mechanisms with regulatory exclusivity, while commoditized categories face margin compression from multi-source competition.
- Analgesics:Comprise opioid and non-opioid small molecules targeting peripheral nociceptors and central pain pathways. Demand concentrates in United States hospital systems adapting to FDA REMS modifications that restrict high-potency opioid prescribing. Branded formulations face accelerating generic substitution as patent cliffs approach.
- Neuropathic Pain Medications:Include gabapentinoids, sodium channel blockers, and NMDA antagonists modulating ectopic nerve firing and central sensitization. Germany's statutory health insurance funds drive volume through prior authorization frameworks favoring established mechanisms over experimental agents.
- Antidepressants:Serotonin-norepinephrine reuptake inhibitors and tricyclic compounds with demonstrated efficacy in centralized pain syndromes.
- Anti-inflammatories:NSAIDs and COX-2 selective inhibitors addressing inflammatory nociception in musculoskeletal conditions.
Today's leader: Analgesics. Tomorrow's challenger: Neuropathic Pain Medications.
Therapy Area:
Reimbursement intensity varies by diagnostic clarity, with objective biomarker-defined conditions commanding stronger payer support than symptom-based diagnoses.
- Neuropathic Disorders:Encompass diabetic peripheral neuropathy, post-herpetic neuralgia, and chemotherapy-induced neuropathy with measurable nerve damage. Japan's aging diabetic population expands addressable cases under PMDA-accelerated pathways for novel mechanisms. Diagnostic specificity enables outcomes-based contracting with institutional purchasers.
- Arthritic Pain:Osteoarthritis and inflammatory arthropathies with structural joint damage visible on imaging. United States Medicare Advantage plans in Florida and Arizona drive utilization through bundled joint replacement episodes that include perioperative pain management.
- Fibromyalgia:Centralized pain syndrome without peripheral tissue damage, challenging traditional pharmacoeconomic models.
- Headaches:Chronic migraine and tension-type disorders with overlapping pathophysiology to centralized pain states.
Neuropathic Disorders command the steepest pricing power. Arthritic Pain offers the deepest volume pool.
Delivery Mode:
Capital intensity and recurring revenue potential determine manufacturer strategic positioning across administration routes.
- Implantable:Spinal cord stimulators, intrathecal pumps, and peripheral nerve stimulators with closed-loop programming capabilities. Germany's university hospitals in Heidelberg and Munich anchor adoption of subscription-based therapy optimization services that decouple hardware from software revenue.
- Oral:Tablets, capsules, and solutions representing the mature baseline with established manufacturing scale and distribution infrastructure.
- Injectable:Parenteral formulations including depot preparations and acute rescue medications in clinical settings.
- Topical:Transdermal patches, gels, and creams for localized musculoskeletal applications with reduced systemic exposure.
Implantable systems are climbing the fastest. Oral formulations defend the widest footprint.
End User:
Procurement authority and patient acuity shape purchasing behavior, with institutional buyers unbundling service contracts from capital equipment.
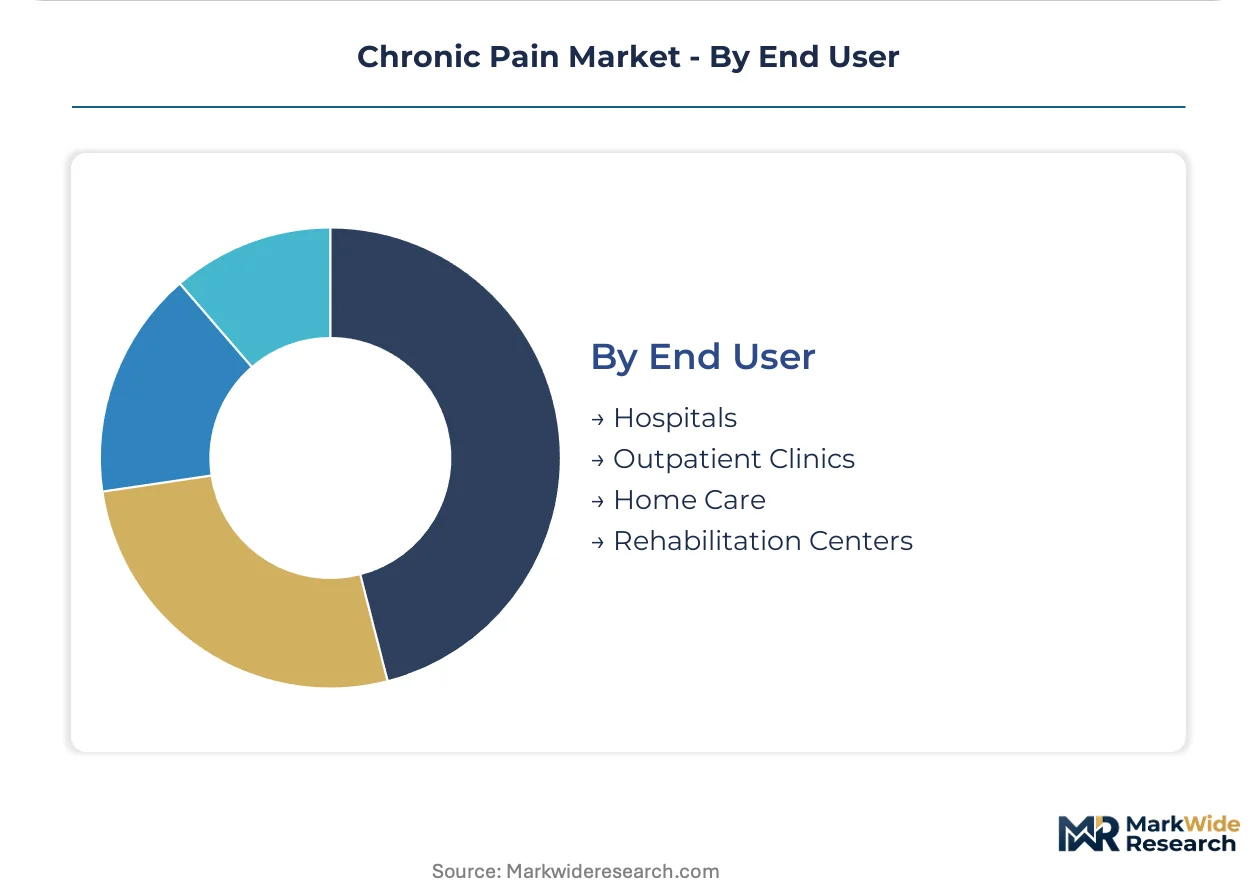
- Hospitals:Acute care institutions with formulary committees controlling pharmaceutical selection and value analysis teams evaluating implantable devices. Japan's Diagnosis Procedure Combination system revisions in Tokyo and Osaka metropolitan areas accelerate behavioral change toward transparent software licensing.
- Outpatient Clinics:Ambulatory settings managing stable chronic pain with lower overhead and faster patient throughput.
- Home Care:Patient-directed administration with remote monitoring integration and direct-to-patient pharmacy distribution.
- Rehabilitation Centers:Multimodal programs combining pharmacological and interventional therapies with physical medicine.
Hospitals control the highest-value transactions. Home Care is gaining share fastest through remote monitoring integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan diverge in chronic pain infrastructure maturity, with the former consolidating university hospital networks around implantable neuromodulation while the latter scales PMDA-accelerated pathways for diabetic neuropathy therapies.
United States
Medicare Advantage bundled payment models in Florida and Arizona drive perioperative pain management utilization alongside orthopedic procedures. FDA REMS modifications restrict high-potency opioid prescribing, redirecting hospital formulary committees toward non-addictive mechanisms. The Cleveland Clinic and Mayo Clinic anchor multimodal program adoption in the Midwest.
Germany
Statutory health insurance funds in North Rhine-Westphalia and Bavaria enforce prior authorization frameworks favoring established analgesic mechanisms. The EU MDR framework imposes stricter clinical evidence thresholds on implantable devices, extending approval timelines. Heidelberg and Munich university hospitals pilot subscription-based therapy optimization services for spinal cord stimulators.
Japan
Aging diabetic populations in Tokyo and Osaka metropolitan areas expand addressable cases for neuropathic pain interventions. PMDA-accelerated pathways prioritize novel mechanisms with demonstrated peripheral restriction. The Diagnosis Procedure Combination system revisions accelerate behavioral change toward transparent software licensing for remote monitoring platforms.
United Kingdom
NICE technology appraisals in England constrain reimbursement for experimental neuropathic agents without real-world evidence portfolios. The NHS long-term plan emphasizes community-based pain management to reduce acute hospital admissions. London and Manchester clinical commissioning groups pilot outcomes-based contracting for digital therapy adjuncts.
Switzerland
Swissmedic maintains stringent benefit-risk assessments for novel CNS-active compounds, favoring peripherally restricted mechanisms. Cantonal hospital networks in Zurich and Geneva concentrate procurement authority for high-value implantable devices. The country's compulsory health insurance framework supports premium pricing for closed-loop neuromodulation systems with demonstrated functional outcomes.
Chronic Pain Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical portfolios facing generic erosion while implantable device vendors capture recurring software revenue. The market structures around three tiers: multinational conglomerates with diversified pain portfolios, mid-cap neuromodulation specialists with vertical control over hardware and cloud infrastructure, and regional generic manufacturers exploiting patent cliffs. Dominant competitive moves include backward integration into proprietary programming platforms and geographic expansion through remote monitoring capabilities that decouple service delivery from physical presence.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Eli Lilly and Company occupy positions exemplifying scale-driven oral analgesic portfolios facing margin compression. Medtronic PLC represents the integrated device archetype, anchoring competitive positioning through closed-loop programming technology that locks clinicians into subscription relationships. Grünenthal GmbH sits within the European specialist tier, reflecting regional concentration in neuropathic pain mechanisms with established reimbursement familiarity.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Abbott Laboratories |
| Novartis AG |
| Medtronic PLC |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd. |
| Johnson & Johnson |
| Grünenthal GmbH |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Neurostimulation programming specialists in Germany's university hospital clusters command wage premiums that widen pricing spreads between closed-loop implantable systems and conventional pharmacological alternatives. Labor-cost differentials between European device optimization centers and Asian manufacturing hubs for oral analgesic APIs stratify end-user pricing across premium subscription tiers and commoditized generic segments.
Pricing Analysis
Capacity additions in India and China for active pharmaceutical ingredients are reshaping price floors for oral analgesic categories. Three-tier pricing structure across premium closed-loop neuromodulation, standard implantable hardware, and economy generic tablets separates reimbursement-eligible device systems from pharmacy-dispensed small molecules. Price differentiation hinges on FDA REMS compliance tier and after-sales programming bundling. Cost compression in oral formulations is intensifying because of patent cliff accelerations, with hospital formulary committees exhibiting highest price sensitivity while ambulatory surgical centers show lowest sensitivity for implantable systems.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologics and high-value implantable electronics strains working capital requirements across distribution networks. Component sourcing concentrates in Germany for precision neuromodulation hardware, Ireland for pharmaceutical excipients, and Switzerland for specialized polymers. Raw material dependencies include lithium-ion cells for rechargeable stimulators, medical-grade titanium for implantable enclosures, and active pharmaceutical ingredients for neuropathic pain mechanisms. Single-source vulnerability in closed-loop algorithm chipsets poses structural risk. Distribution runs through hospital value analysis committees for capital equipment and wholesale pharmacy networks for drug products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Japan's PMDA-accelerated approval timelines for novel neuropathic mechanisms and the EU MDR's extended evidence requirements that delay competitive entry.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary closed-loop programming platforms that lock clinicians into subscription relationships. Consolidate manufacturing scale across oral portfolios to withstand generic substitution pressure from Indian contract manufacturers. Prioritize certification investment in EU MDR PMCF databases to extend approval timeline advantages against mid-tier device competitors. For New Entrants and Emerging Players: Enter via topical localized applications in musculoskeletal pain where regulatory pathways remain streamlined and systemic safety concerns are minimized. Target Germany's statutory health insurance prior authorization frameworks with peripherally restricted mechanisms that bypass central nervous system pharmacovigilance requirements. Pursue hospital system partnership models that unbundle software licensing from hardware capital purchases. For Investors and Strategic Acquirers: Diversified medical device conglomerates are the most active acquirer in this space, seeking neuromodulation specialists with vertical control over cloud-based patient monitoring infrastructure. Long-term viability over the five-to-ten year horizon rests on subscription revenue durability decoupled from hardware replacement cycles. Monitor FDA opioid REMS modification enforcement intensity as the critical inflection signal for non-addictive mechanism investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Programming Platform Development | Medtronic's proprietary algorithms lock clinicians into recurring therapy optimization subscriptions. |
| EU MDR PMCF Database Construction | Heidelberg and Munich university hospitals anchor post-market clinical follow-up infrastructure for incumbent device manufacturers. |
| Peripherally Restricted Mechanism Pipeline | PMDA-accelerated pathways in Tokyo prioritize diabetic neuropathy candidates with cleaner central nervous system profiles. |
| Remote Monitoring Infrastructure Expansion | Abbott's cloud-based patient monitoring enables geographic expansion beyond traditional implanting center footprints. |
| Hospital Procurement Committee Engagement | Germany's Diagnosis Procedure Combination revisions force transparent software licensing unbundled from capital equipment. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with implantable device programming specialists, hospital value analysis directors, pharmaceutical regulatory affairs leads, and statutory health insurance formulary managers informed demand-side assumptions. Secondary sources include FDA 510(k) filings, EMA pharmacovigilance databases, PMDA accelerated approval designations, hospital procurement contract registries, and CMS Medicare claims data. Bottom-up patient population modeling and top-down manufacturer revenue triangulation anchored volume and value estimates.
Granularity-level modeling disaggregated the analysis window across product type, therapy area, delivery mode, and end-user segments with regional regulatory cluster differentiation. Analytical framework projections derived CAGRs through patient population epidemiology, reimbursement intensity scoring, and technology adoption curve positioning. Industry-specific forecast inputs incorporated EU MDR approval timeline distributions and PMDA priority review designation rates.
Inputs from hospital procurement databases and GPO contract repositories were available through the study window; gaps in real-world outcomes data for closed-loop neuromodulation introduce uncertainty bands around therapy adoption assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and reimbursement stability. A model refresh is warranted upon material change in FDA opioid REMS modification scope or EU MDR clinical evidence threshold interpretation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Heat Therapy Market
Pain Management
Neuralgia Treatment Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Bone Pain Treatment Market
Pain Management
Pain Patches Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Migraine Management Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Topical Pain Relief Market
Pain Management
Dyspareunia Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Cold Pain Therapy Market
Pain Management
Global Visceral Pain Treatment Market