
 Advanced Cancer Pain Management Market | 2026-2036
Advanced Cancer Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
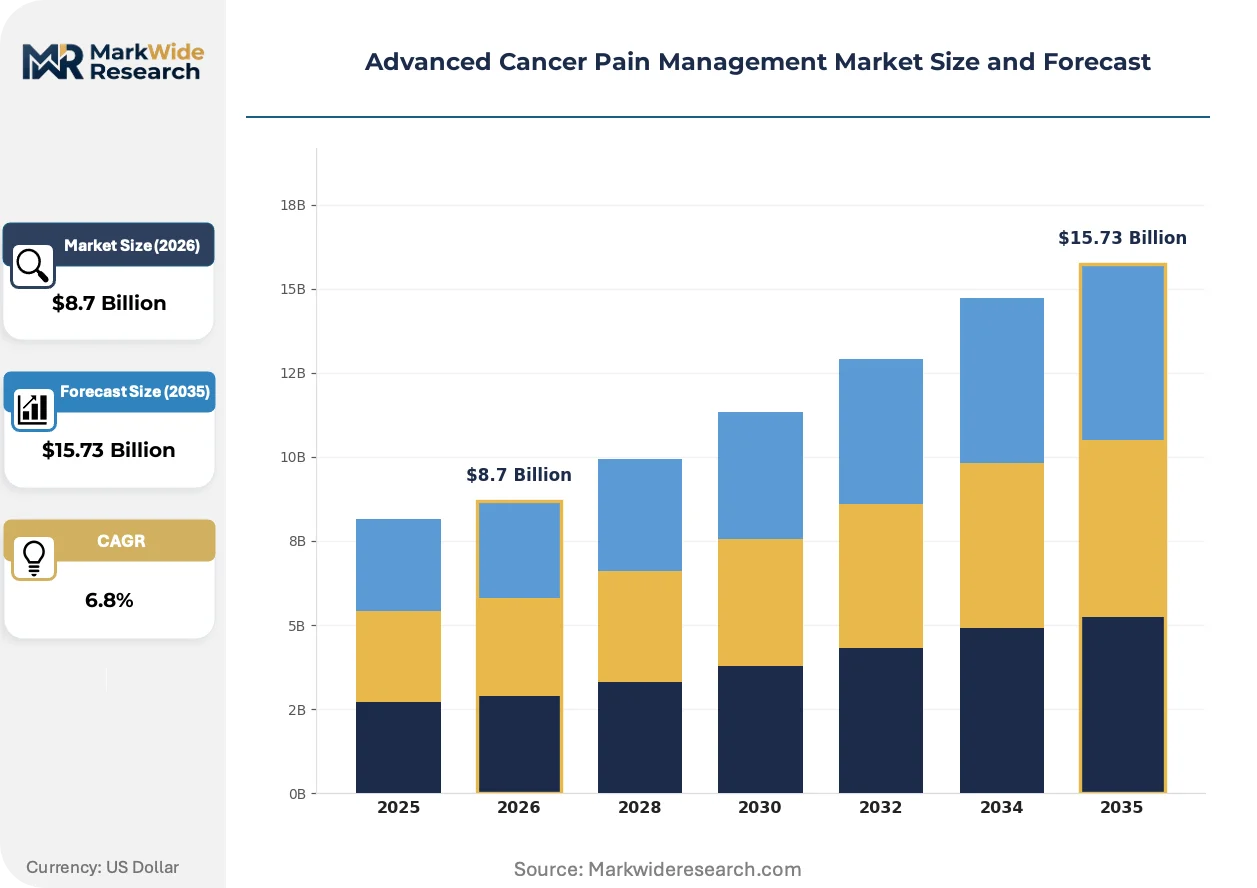
Advanced Cancer Pain Management Market Outlook
Extended-release formulation standards is collapsing the gap between hospital-grade and take-home analgesic reliability. Pfizer leverages its manufacturing scale to sustain dominance in long-acting opioid formulations. Jazz Pharmaceuticals specializes in novel delivery mechanisms for breakthrough cancer pain. Teva Pharmaceuticals competes through geographic breadth across regulated and emerging markets.
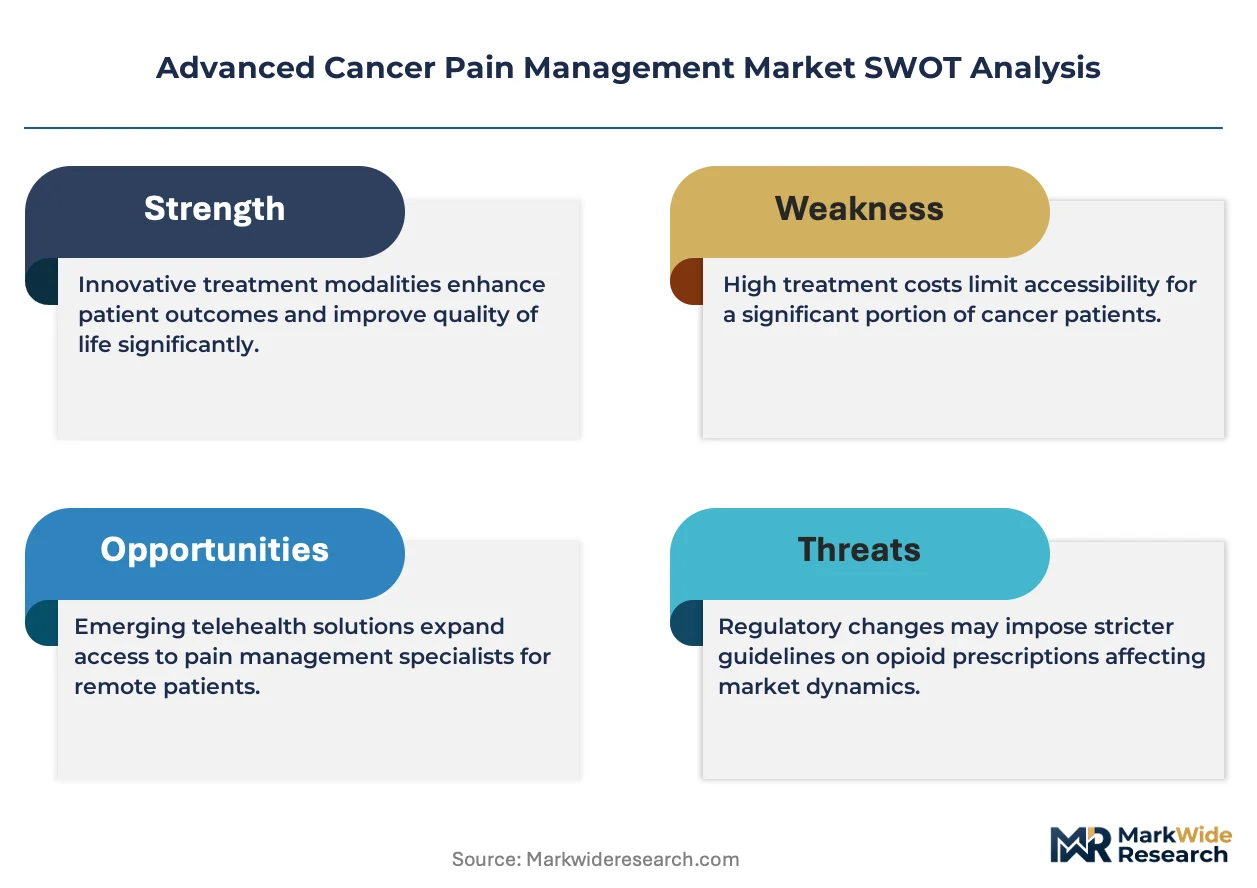
Advanced cancer pain management encompasses pharmacological and interventional therapies targeting moderate-to-severe pain in oncology patients, including sustained-release morphine formulations with 12-24 hour plasma concentration profiles and transdermal fentanyl patches delivering microgram-per-hour dosing precision. Its primary purpose is restoring functional capacity and quality of life during terminal and active treatment phases. Opioids retain the largest revenue pool among product types, though adjuvant analgesics are gaining fastest as combination protocols expand. Transdermal delivery is capturing share from intravenous routes in home care settings due to patient preference and reduced nursing burden. Multi-modal approaches command premium positioning where reimbursement supports integrated therapy billing.
FDA REMS requirements, EMA pharmacovigilance frameworks, and WHO analgesic ladder guidelines collectively determine market access thresholds and product labeling obligations for new entrants. These standards elevate R&D costs but simultaneously protect validated formulations from commoditization. Stakeholders must monitor evolving abuse-deterrence benchmarks and biosimilar erosion timelines across extended-release portfolios.
Market Dynamics
FDA REMS requirements for extended-release opioids are forcing wholesale restructuring of prescribing workflows and product development roadmaps across the pharmaceutical value chain.
Growth Catalysts
- Multi-modal protocol adoption:Palliative care facilities are integrating sustained-release morphine with adjuvant analgesics into standardized care pathways. This combination approach expands addressable patient populations beyond monotherapy limits.
- Home care infusion network expansion:United States-based home health agencies are scaling transdermal delivery capabilities to reduce hospital readmission rates. Patient preference for non-invasive administration accelerates this shift.
- WHO analgesic ladder compliance mandates:National health systems in oncology-heavy markets are embedding step-care protocols into reimbursement frameworks. This elevates access to previously restricted strong opioid categories.
Market Restraints
- Active pharmaceutical ingredient concentration:Global supply of specialized opioid precursors concentrates among a limited set of specialized chemical manufacturers. Any disruption cascades through formulation pipelines.
- Abuse-deterrence R&D cost inflation:FDA REMS compliance requires expensive formulation modifications and post-market surveillance infrastructure. Smaller entrants face prohibitive capital barriers to commercialization.
- Non-opioid substitution pressure:Interventional radiology techniques including celiac plexus block and spinal cord stimulation capture select severe pain cases. These procedures eliminate ongoing pharmaceutical consumption for targeted patients.
Strategic Opportunities
- Rural hospice network penetration:Underserved regions in the United States lack consistent access to specialist pain management services. Telemedicine-integrated delivery models can bridge this geographic gap.
- Biosimilar erosion timing:Patent cliffs on legacy extended-release formulations create temporary windows for differentiated delivery mechanisms. Novel transdermal technologies can capture switching volumes.
- Japan's aging oncology demographic:METI-supported geriatric care infrastructure investments elevate demand for patient-administered analgesics. Transdermal fentanyl aligns with cultural preferences for home-based terminal care.
Industry Challenges
- Pain specialist workforce scarcity:Board-certified palliative medicine physicians remain concentrated in academic medical centers. Community hospital staffing gaps delay protocol implementation.
- Legacy electronic health record integration:REMS-mandated risk assessment documentation requires workflow modifications incompatible with older hospital information systems. Upgrade timelines extend 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Cancer Pain Management Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Adjuvant Analgesics, Opioids, Non-Opioid Medications Delivery Mode: Oral, Intravenous, Transdermal, Subcutaneous End User: Hospitals, Home Care Settings, Pain Management Clinics, Palliative Care Facilities Mode of Action: Central Nervous System Agents, Peripheral Agents, Multi-Modal Approaches, Local Anesthetics |
| Companies Covered | Pfizer, Johnson & Johnson, Novartis, AstraZeneca, Teva Pharmaceuticals, GSK plc, Jazz Pharmaceuticals, Tetra Bio-Pharma, WEX Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Cancer Pain Management Market Strategic Shifts
Extended-release formulation science is collapsing the functional distinction between inpatient and outpatient analgesic reliability. This technical convergence enables new care models that were previously protocol-incompatible.
Implantable intrathecal drug delivery systems are decomposing the traditional hospital-versus-home boundary for severe cancer pain management. Oncology centers in the United States are adopting these programmable pumps for refractory cases previously requiring continuous IV infusion. The technology is decomposing nursing labor requirements while maintaining plasma concentration precision comparable to inpatient parenteral routes.
EMA pharmacovigilance frameworks are tightening post-authorization safety study obligations for all new opioid formulations entering European markets. Manufacturers must now commit to multi-year real-world evidence collection as a condition of marketing authorization. Extended-release portfolios face the steepest compliance burden, with France's ANSM and Germany's BfArM enforcing divergent local reporting standards that fragment regulatory strategy.
Hospital purchasing consortia are consolidating procurement authority for high-cost analgesic categories under centralized pharmacy and therapeutics committees. This buyer concentration compresses price negotiation timelines and elevates formulary exclusion risk for undifferentiated products. The United States health system witnesses the most aggressive consolidation, with integrated delivery networks capturing 60% of oncology drug purchasing decisions in major metropolitan markets.
Advanced Cancer Pain Management Market Segmentation
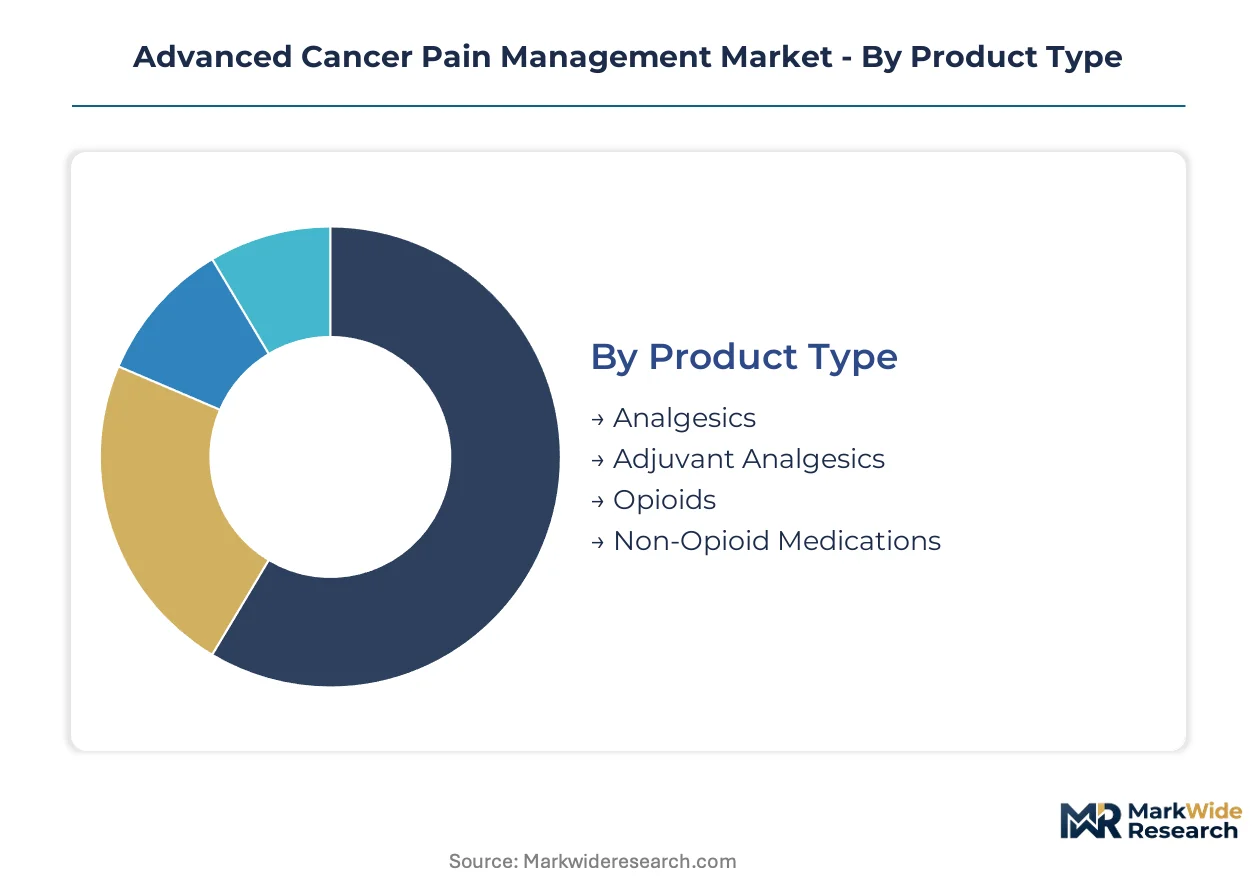
Pain management protocols fragment across delivery mechanisms and care settings, creating distinct procurement channels with incompatible reimbursement codes. Understanding segment boundaries clarifies where formulation investments align with purchasing authority concentration.
Product Type:
Hospital formularies and home care infusion networks route different product categories through separate procurement workflows with distinct clinical oversight requirements.
- Opioids:Extended-release morphine and transdermal fentanyl formulations dominate hospital-based cancer pain protocols with 12-24 hour plasma profiles. United States integrated delivery networks concentrate purchasing decisions for these high-cost categories under centralized pharmacy committees, compressing price negotiation timelines for undifferentiated entrants.
- Adjuvant Analgesics:Anticonvulsants and antidepressants function as combination therapy anchors in multi-modal protocols. Palliative care facilities in the United States are embedding these into standardized care pathways, expanding addressable populations beyond monotherapy limits and elevating access through WHO analgesic ladder compliance mandates.
- Analgesics:Non-opioid pharmaceutical options serve as step-care foundation therapies under national reimbursement frameworks.
- Non-Opioid Medications:NSAIDs and acetaminophen formulations occupy formulary tiers with generic substitution pressure.
Opioids dominate installed base revenue. Adjuvant analgesics are where expansion concentrates.
Delivery Mode:
Route selection determines nursing labor intensity and patient autonomy, with cost tiers separating institutional from take-home administration.
- Transdermal:Fentanyl patches deliver microgram-per-hour dosing precision through skin permeation technology. Home care agencies across the United States are scaling these capabilities to reduce hospital readmission rates, with patient preference for non-invasive administration accelerating channel shift from intravenous routes.
- Oral:Sustained-release tablets and capsules provide the foundation for outpatient cancer pain management with established bioavailability profiles. Japan's METI-supported geriatric care infrastructure elevates demand for these patient-administered formats, aligning with cultural preferences for home-based terminal care.
- Intravenous:Parenteral routes maintain inpatient dominance for acute breakthrough pain and perioperative oncology care.
- Subcutaneous:Continuous infusion pumps serve hospice settings requiring steady plasma concentration without vascular access.
Oral formulations retain the broadest geographic penetration. Transdermal routes are climbing the fastest as home care networks mature.
End User:
Facility type determines protocol standardization depth and specialist physician availability, with margin concentration varying by care intensity.
- Hospitals:Academic medical centers and community oncology units deploy the full spectrum of pharmacological and interventional therapies. The United States witnesses the most aggressive purchasing consolidation, with integrated delivery networks capturing the majority of oncology drug purchasing decisions in major metropolitan markets.
- Home Care Settings:Hospice agencies and visiting nurse organizations manage transdermal and oral regimens with telemedicine oversight. Rural network penetration gaps in the United States create temporary windows for differentiated delivery mechanisms that bridge geographic access constraints.
- Pain Management Clinics:Interventional radiology and anesthesiology practices offer celiac plexus block and spinal cord stimulation alternatives.
- Palliative Care Facilities:Dedicated units integrate multi-modal approaches with psychosocial support services.
Hospitals anchor procurement volume concentration. Home care settings are gaining share fastest as reimbursement shifts toward readmission reduction incentives.
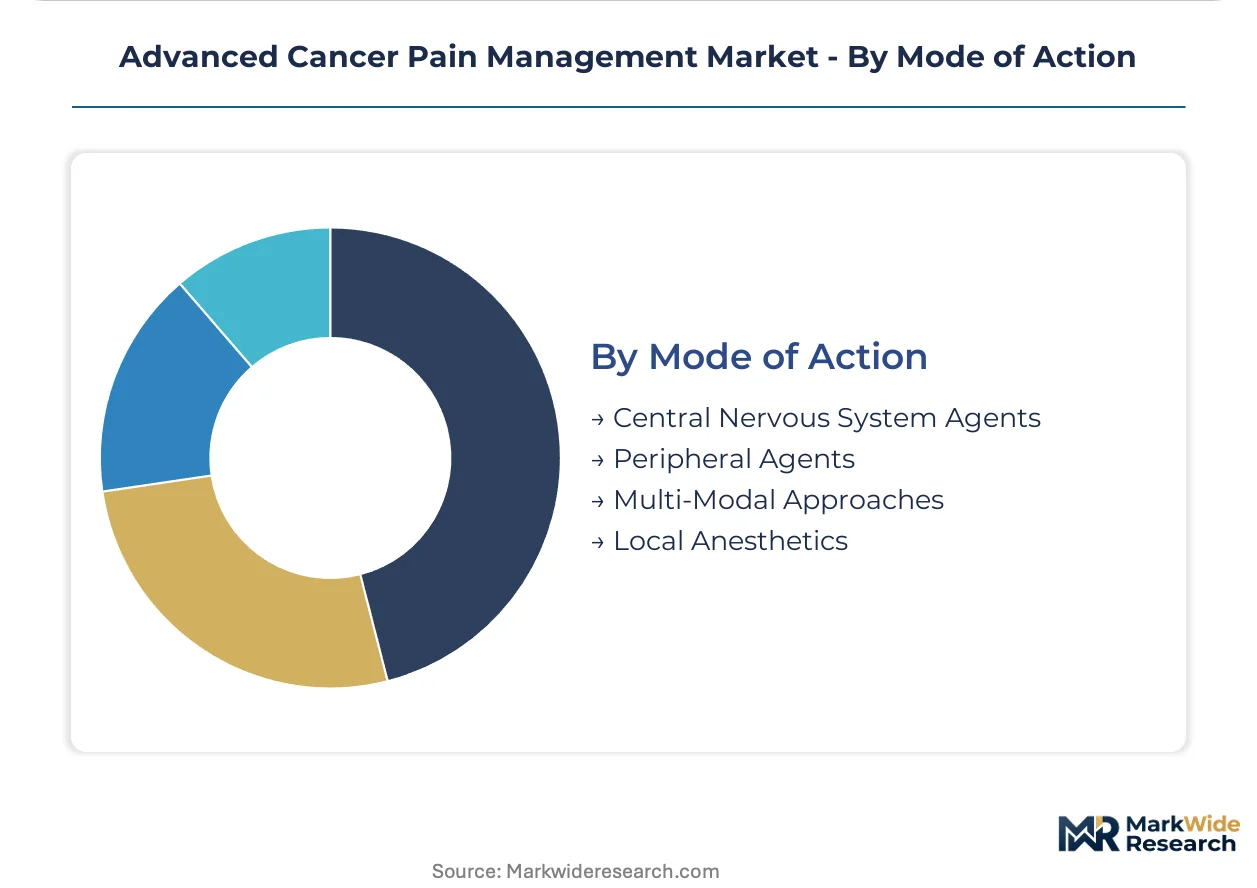
Mode of Action:
Mechanism-based categorization determines formulary placement relative to WHO analgesic ladder steps and combination therapy eligibility.
- Multi-Modal Approaches:Simultaneous targeting of nociceptive and neuropathic pathways through coordinated opioid and adjuvant deployment. These command premium positioning where United States reimbursement supports integrated therapy billing, with palliative care facilities expanding their use as core treatment pathways.
- Central Nervous System Agents:Opioids and selected adjuvants modulate pain perception through mu-receptor agonism and descending pathway inhibition. FDA REMS requirements for extended-release formulations force wholesale restructuring of prescribing workflows across pharmaceutical value chains.
- Peripheral Agents:NSAIDs and local therapies target inflammation and tissue-level nociception.
- Local Anesthetics:Regional block techniques serve interventional pain management procedures.
Central nervous system agents dominate current prescribing volumes. Multi-modal approaches are expanding most quickly as protocol standardization deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized opioid precursor manufacturing clusters in Germany, Switzerland, and the United States dominate upstream supply. Finished formulation capacity concentrates near major oncology centers. Regulatory divergence between FDA REMS and EMA pharmacovigilance frameworks fragments commercial strategy.
United States
Hospital-based pain management services and home care infusion networks scale fastest here. FDA REMS requirements for extended-release opioids force restructuring of prescribing workflows and product development roadmaps. The Texas Medical Center in Houston and Memorial Sloan Kettering in New York anchor multi-modal protocol adoption.
Germany
BfArM enforces divergent local reporting standards that fragment regulatory strategy for extended-release portfolios. The country's palliative care infrastructure supports integrated therapy billing for multi-modal approaches. Heidelberg and Munich academic medical centers lead interventional radiology technique adoption including celiac plexus block procedures.
Japan
METI-supported geriatric care infrastructure investments elevate demand for patient-administered analgesics. PMDA oversight aligns with cultural preferences for home-based terminal care. The Kansai region around Osaka and the Kanto region around Tokyo concentrate transdermal fentanyl utilization in hospice networks.
United Kingdom
NHS reimbursement frameworks embed WHO analgesic ladder compliance into oncology care pathways. The Medicines and Healthcare products Regulatory Agency maintains post-authorization surveillance for novel delivery mechanisms. London's integrated cancer centers and Manchester's palliative care units drive centralized pharmacy committee purchasing consolidation.
Switzerland
Swissmedic marketing authorization conditions require multi-year real-world evidence collection for new opioid formulations. The country's precision manufacturing base supports novel transdermal technology development. Basel's pharmaceutical cluster and Zurich's clinical research organizations anchor abuse-deterrence formulation R&D.
Advanced Cancer Pain Management Market Competitive Environment
Concentration sits with large-cap pharmaceutical manufacturers possessing extended-release formulation expertise and REMS compliance infrastructure. The market structure tiers across global diversified players, regional generics specialists, and novel delivery mechanism innovators. Two strategic archetypes dominate: scale-driven manufacturers leveraging purchasing committee relationships, and technology specialists capturing biosimilar switching volumes through differentiated transdermal platforms. Competitive moves center on geographic expansion into Japan's aging demographic and strategic partnerships with home care infusion networks.
Among diversified pharmaceutical manufacturers, Pfizer and Johnson & Johnson occupy positions anchored by manufacturing scale and hospital formulary penetration. Teva Pharmaceuticals exemplifies the geographic breadth archetype competing across regulated and emerging markets. Jazz Pharmaceuticals represents the novel delivery mechanism specialist tier targeting breakthrough cancer pain indications.
| Leading Market Players |
|---|
| Pfizer |
| Johnson & Johnson |
| Novartis |
| AstraZeneca |
| Teva Pharmaceuticals |
| GSK plc |
| Jazz Pharmaceuticals |
| Tetra Bio-Pharma |
| WEX Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between specialized opioid precursor manufacturers and finished formulation producers lock in supply access while stabilizing price visibility across extended-release portfolios. These contracts insulate German and Swiss API suppliers from spot market volatility while committing United States-based pharmaceutical manufacturers to minimum volume thresholds that shape procurement planning cycles.
Pricing Analysis
FDA REMS dictates the pricing tier structure across extended-release opioid formulations, separating abuse-deterrent certified products from standard generic equivalents. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and REMS compliance infrastructure investment. Cost compression in standard-tier extended-release morphine is intensifying because integrated delivery networks consolidate purchasing authority under centralized pharmacy committees. Hospital formularies exhibit the highest price sensitivity due to reimbursement pressure, while home care infusion networks prioritize reliability over unit cost.
Supply Chain Analysis
Specialized alkaloid extraction capacity in Tasmania, Turkey, and India underwrites global morphine precursor availability. Active pharmaceutical ingredient production draws from poppy straw concentrate, thebaine derivatives, and synthetic opioid precursors. Single-source vulnerability concentrates in Tasmanian poppy cultivation regions exposed to climate disruption. Distribution runs through pharmaceutical wholesaler networks with cold-chain requirements for transdermal patch formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rural hospice networks and home care infusion channels creates niche entry points for differentiated delivery mechanisms. The shift toward telemedicine-integrated pain management decentralizes procurement authority away from academic medical centers.
For Market Incumbents: Consolidate manufacturing scale advantages through backward integration into specialized opioid precursor supply. Lock in exclusive supplier relationships with Tasmanian and Turkish alkaloid processors before patent cliffs on legacy extended-release formulations accelerate. Defend hospital formulary positioning by pre-empting biosimilar erosion with novel abuse-deterrent certification investments. For New Entrants and Emerging Players: FDA 505(b)(2) regulatory pathways offer accelerated approval timelines for differentiated transdermal delivery mechanisms. Rural United States hospice networks represent the most penetrable geography due to specialist physician scarcity and inconsistent multi-modal protocol access. Partner with telemedicine platforms to bypass traditional hospital purchasing committee gatekeeping. For Investors and Strategic Acquirers: Novel transdermal technology specialists with proprietary skin permeation patents represent the highest-conviction acquisition archetype. Long-term viability hinges on positioning ahead of Japan's aging oncology demographic inflection and Medicare reimbursement shifts toward home-based care. Monitor FDA abuse-deterrence guideline updates as the critical signal for portfolio revaluation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Abuse-Deterrent Formulation Development | FDA REMS compliance elevates barriers against generic erosion for certified products. |
| Telemedicine Platform Partnership | Rural hospice network penetration bypasses traditional hospital formulary gatekeeping. |
| Japanese PMDA Regulatory Submission | METI-supported geriatric care infrastructure creates premium positioning for transdermal formats. |
| Specialized API Supplier Acquisition | Tasmanian and Turkish alkaloid processing capacity secures precursor supply visibility. |
| Home Care Infusion Network Integration | United States reimbursement shifts toward readmission reduction incentivize channel control. |
Study Parameters
Desk research of FDA REMS documentation, EMA pharmacovigilance filings, and WHO analgesic ladder implementation guidelines preceded structured interviews with palliative care physicians, hospital pharmacy directors, home care agency administrators, and regulatory affairs specialists at extended-release formulation manufacturers. Secondary validation drew from ClinicalTrials.gov entries, Medicare reimbursement code databases, and integrated delivery network procurement disclosures. Bottom-up patient volume estimates and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across product type, delivery mode, end user facility, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Modeled inputs included palliative care bed expansion trajectories, REMS compliance cost inflation, and transdermal patch adoption curves in home care settings.
Decision-makers should treat outputs as directional under stable FDA REMS enforcement and continued Medicare hospice benefit coverage assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as abuse-deterrence certification requirements and opioid litigation settlement impacts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Arthralgia Management Market
Pain Management
Ketorolac Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
Pain Patches Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Opioid Withdrawal Management Market
Pain Management
Chronic Pain Market
Pain Management
OTC Painkiller Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Neuralgia Treatment Market
Pain Management
Heat Therapy Market
Pain Management
Cancer Pain Management Market
Pain Management
Global Visceral Pain Treatment Market
Pain Management
Over-The-Counter Pain Medication Market
Pain Management
Topical Pain Relief Market