
 Menkes Syndrome Market | 2026-2036
Menkes Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Menkes Syndrome Market Analysis
Subscription-based genetic counseling and remote patient monitoring services is recalibrating how Menkes syndrome care gets monetized beyond one-time drug sales. Fortress Biotech leverages its rare disease platform infrastructure to anchor clinical trial execution across multiple ATP7A programs. Ultragenyx Pharmaceutical Inc. specializes in ultra-rare metabolic disorders, positioning its regulatory expertise for Menkes therapeutic development. Thermo Fisher Scientific Inc. controls diagnostic supply chains, extending its reagent and assay dominance into copper metabolism testing.
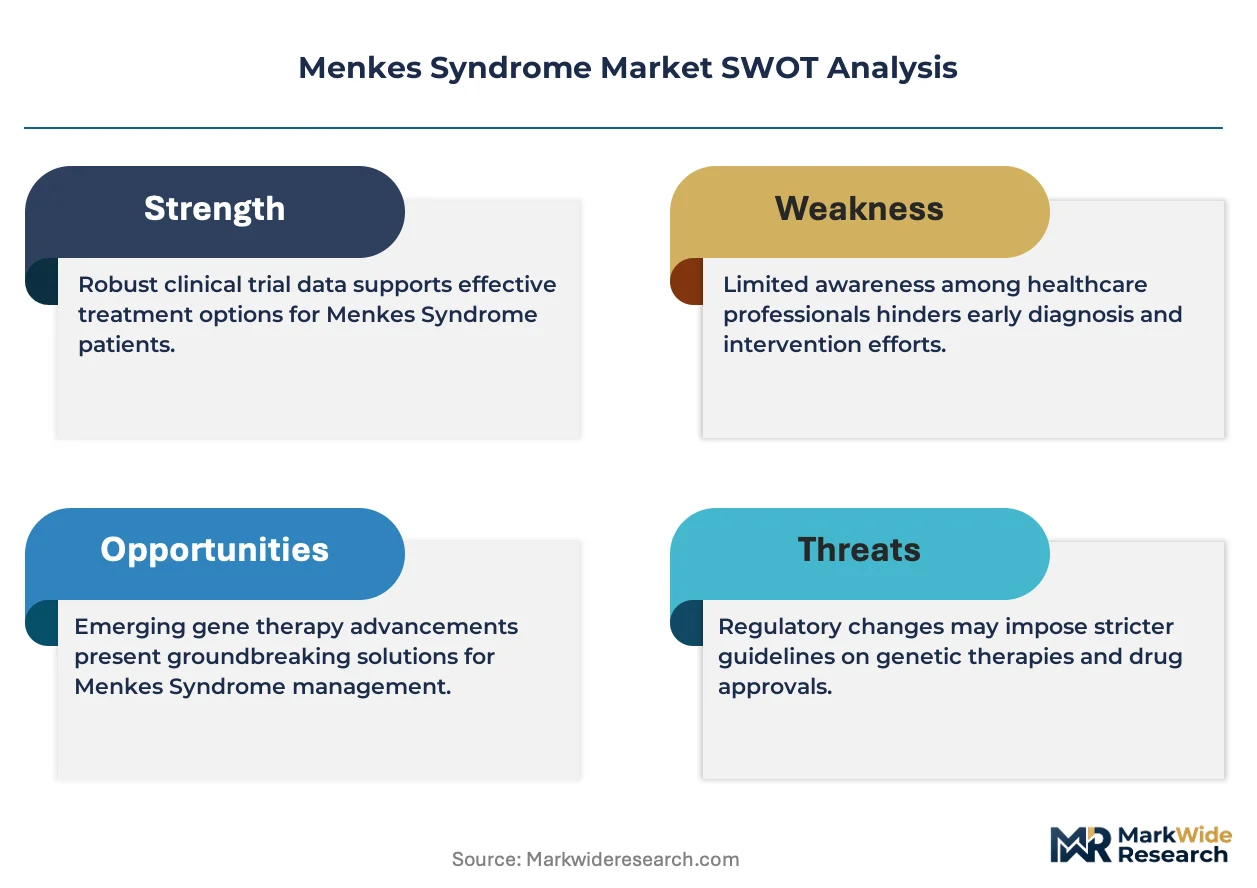
Menkes syndrome is an X-linked recessive disorder caused by mutations in the ATP7A gene, which encodes a copper-transporting P-type ATPase essential for delivering copper to dopamine beta-hydroxylase, lysyl oxidase, and other cuproenzymes; defective copper transport produces kinky hair, neurological deterioration, and connective tissue abnormalities, with symptom severity correlating to residual ATP7A activity. The condition primarily serves pediatric critical care and metabolic genetics, where early copper histidine or copper chloride intervention can modify neurodevelopmental outcomes if initiated before irreversible white matter injury. Diagnostics and genetic testing command premium margins due to compulsory newborn screening integration and confirmatory sequencing workflows, while gene therapy within treatment strategy represents the fastest-expanding investment category as AAV and lentiviral ATP7A delivery platforms advance through preclinical stages. Copper supplementation maintains volume leadership across delivery modes, though intravenous formulations sustain higher per-patient economics due to hospital administration requirements.
FDA orphan drug incentives and EMA's priority medicines scheme shape Menkes therapeutic development, with both agencies offering protocol assistance and fee waivers that reduce barriers for ultra-rare indications. The country's national pharmaceutical regulator in Japan, PMDA, applies sakigake designation pathways that compress review timelines for pediatric rare diseases, creating competitive registration arbitrage for sponsors with global development strategies. Stakeholders must monitor CRISPR-based ATP7A correction progress and copper chaperone small-molecule advances, as these modalities could redefine the standard of care and displace existing supplementation paradigms without warning.
Market Dynamics
Gene therapy vectors are compressing development timelines for ATP7A-targeted interventions while newborn screening mandates pull diagnostics demand forward in pediatric metabolic centers.
Growth Catalysts
- FDA Orphan Drug Incentives:Protocol assistance and fee waivers reduce regulatory barriers for ultra-rare disease sponsors, accelerating IND-to-NDA pathways for copper transport modulators.
- Copper Histidine Supplementation:Early intervention protocols in neonatal intensive care units demonstrate measurable neurodevelopmental preservation when administered before white matter injury becomes irreversible.
- Japan's Sakigake Pathway:PMDA's compressed review timelines for pediatric rare diseases create registration arbitrage opportunities for sponsors with global development strategies.
Market Restraints
- Copper Formulation Instability:Intravenous copper chloride requires cold-chain logistics and hospital administration, limiting outpatient treatment expansion and concentrating volume in tertiary pediatric centers.
- Diagnostic Supply Concentration:Thermo Fisher Scientific controls reagent and assay supply chains for ATP7A sequencing, creating single-source dependency for confirmatory testing workflows.
- Gene Therapy Manufacturing Bottlenecks:AAV vector production capacity constraints and lentiviral packaging cell line scarcity extend preclinical-to-clinical transition timelines for ATP7A delivery platforms.
Strategic Opportunities
- Subscription-Based Care Models:Genetic counseling and remote patient monitoring services create recurring revenue streams beyond one-time drug sales, anchoring long-term patient relationships.
- EMA Priority Medicines Scheme:Accelerated assessment pathways for rare disease therapies reduce time-to-market for ATP7A modulators targeting European pediatric populations.
- CRISPR-Copper Chaperone Convergence:Combination approaches pairing base editing with small-molecule copper trafficking correctors could displace supplementation paradigms entirely.
Industry Challenges
- Neonatology-Genetics Coordination Gap:Screening-positive newborns require rapid handoff from birth hospitals to metabolic genetics centers, but referral pathway standardization remains incomplete across health systems.
- Biomarker Validation Delays:Surrogate endpoints for neurodevelopmental outcomes in ultra-rare diseases lack regulatory precedent, complicating trial design and label expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Menkes Syndrome Market |
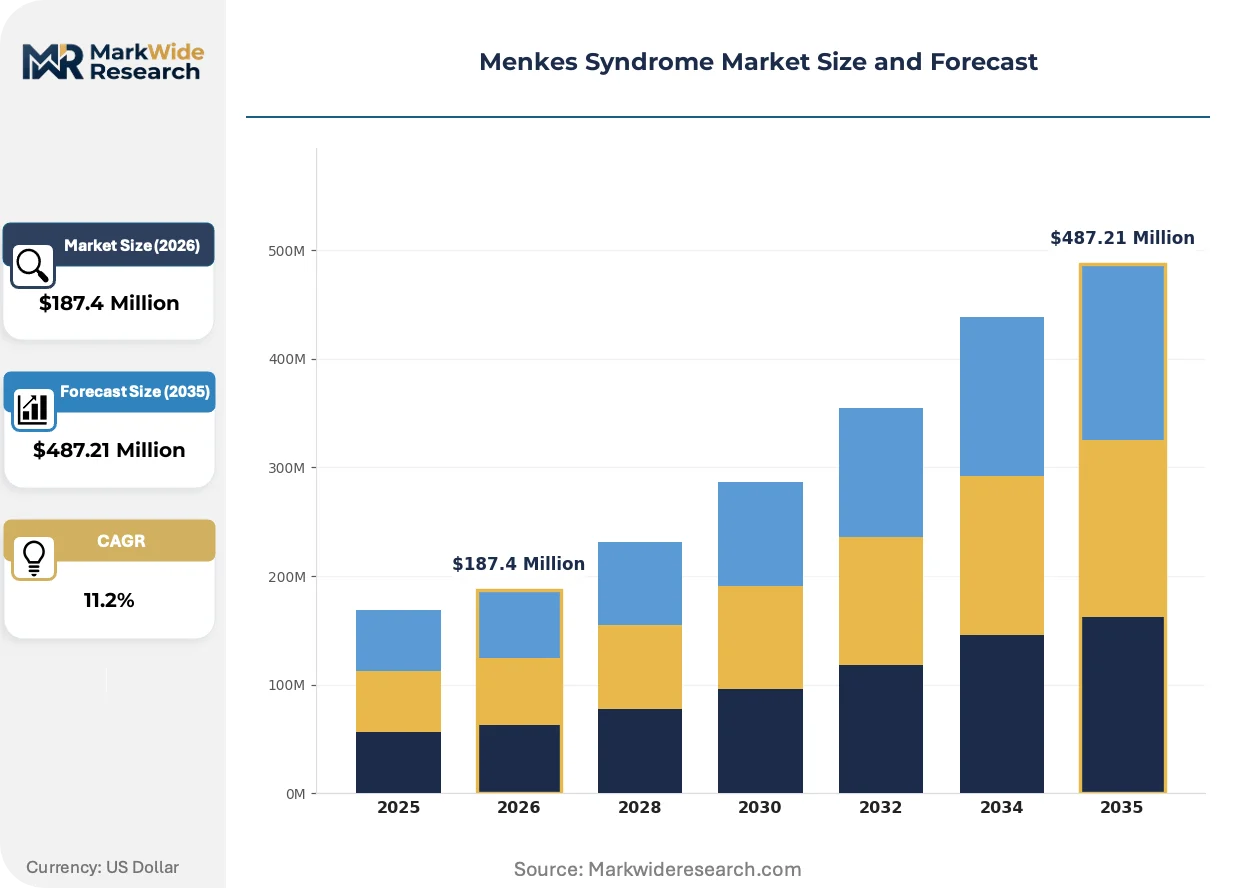
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $487.21 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostics, Therapies, Genetic Testing, Supportive Care End User: Pediatrics, Geneticists, Neurologists, Healthcare Providers Delivery Mode: Oral, Intravenous, Subcutaneous, Topical Treatment Strategy: Enzyme Replacement, Copper Supplementation, Gene Therapy, Symptomatic Management |
| Companies Covered | Fortress Biotech, Teva Pharmaceutical Industries Ltd., Amerigen Pharmaceuticals Limited, Mylan N.V., Bausch Health, H. Lundbeck A/S, Ultragenyx Pharmaceutical Inc., Thermo Fisher Scientific Inc., Sentynl Therapeutics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Menkes Syndrome Market Emerging Trajectories
ATP7A-targeted modalities are bifurcating the treatment landscape between chronic copper supplementation maintenance and curative gene editing approaches, with diagnostic workflows adapting to stratify patients by mutation severity.
AAV-mediated ATP7A gene delivery is expanding into preclinical programs as the dominant vector for hepatocyte and neuronal transduction, with academic medical centers in the United States and Japan establishing dedicated manufacturing partnerships to secure supply. Pediatric metabolic specialists are prioritizing early-treated cohorts for gene therapy eligibility screening, compressing the window between diagnosis and intervention. This modality is enabling curative claims that threaten to displace lifelong copper histidine dependence in severe phenotypes.
EMA's priority medicines scheme and FDA's rare pediatric disease priority review voucher program are reshaping sponsor incentives, with both agencies offering rolling review and scientific advice that truncates traditional regulatory timelines. Sponsors are front-loading pediatric investigation plans to capture these benefits, redirecting development resources toward neonatal indication expansion. European reference pricing systems are responding by establishing distinct reimbursement tiers for gene therapies versus chronic supplementation.
Remote patient monitoring platforms are displacing quarterly in-person metabolic clinic visits for stable patients, with telemetry-enabled copper level tracking and video-based neurodevelopmental assessment becoming standard in academic medical center networks. Pediatric metabolic practices are unbundling acute crisis management from longitudinal care coordination, creating distinct service lines. This shift is most visible in United States children's hospitals with established rare disease center of excellence designations.
Menkes Syndrome Market Segmentation
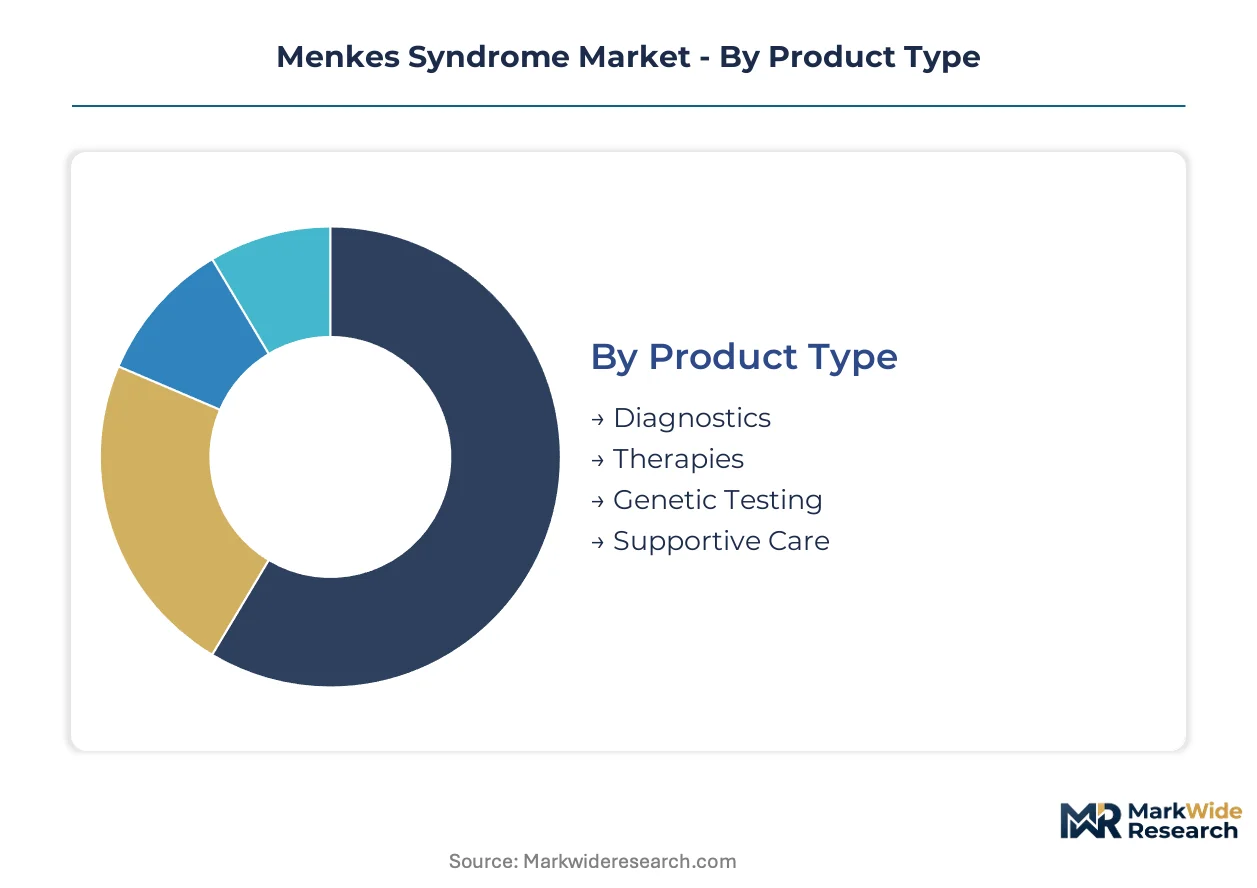
Menkes syndrome care stratifies sharply between acute intervention modalities and longitudinal management systems. Segmentation reveals how copper transport biology, delivery logistics, and specialist access patterns concentrate value across distinct product and service categories.
Product Type:
Therapies command premium economics through hospital administration requirements, while diagnostics sustain volume through mandatory newborn screening integration.
- Therapies:Intravenous copper histidine and copper chloride formulations require cold-chain distribution and tertiary pediatric center administration. Demand concentrates in United States academic medical centers with established metabolic genetics programs, driven by early intervention protocols that modify neurodevelopmental outcomes before irreversible white matter injury.
- Diagnostics:ATP7A sequencing workflows and biochemical copper assays anchor confirmatory testing pathways. United States newborn screening expansion and European reference laboratory networks concentrate demand, with reagent supply chains controlled by dominant diagnostic platform vendors creating single-source dependencies.
- Genetic Testing:Carrier screening and prenatal ATP7A mutation analysis serve family planning decisions in known pedigree contexts.
- Supportive Care:Nutritional optimization, physical therapy, and developmental interventions address connective tissue and neurological sequelae.
Mature deployment sits with Diagnostics. Newer deployment is concentrated in Therapies.
End User:
Specialist concentration determines access patterns, with pediatric metabolic centers serving as gatekeepers to advanced interventions.
- Pediatrics:Neonatal intensive care units and pediatric metabolic clinics coordinate acute copper supplementation initiation and long-term monitoring. United States children's hospitals with rare disease center of excellence designations concentrate the deepest treatment infrastructure, driven by newborn screening expansion and academic medical center clustering.
- Neurologists:Pediatric neurologists manage seizure disorders, movement abnormalities, and neurodevelopmental trajectory assessment. Japanese academic medical centers with dedicated pediatric neurology departments are expanding specialized Menkes screening protocols, leveraging PMDA sakigake designation pathways for rapid therapeutic access.
- Geneticists:Metabolic genetics specialists direct ATP7A sequencing interpretation and family counseling.
- Healthcare Providers:Primary care and community hospital networks handle initial screening positivity and urgent referral coordination.
Established care relationships sit with Pediatrics. Emerging coordination models are concentrating in Neurologists.
Delivery Mode:
Route selection tracks disease severity and treatment phase, with parenteral options sustaining higher per-patient economics.
- Intravenous:Copper chloride and histidine formulations administered through central venous access in hospital settings. Tertiary pediatric centers in the United States and Japan concentrate demand, driven by neonatal intensive care unit protocols requiring immediate intervention before neurological injury progression.
- Oral:Maintenance copper supplementation for stabilized patients with residual ATP7A activity. Outpatient metabolic clinics and home care programs are gaining share, though bioavailability limitations constrain efficacy in severe phenotypes.
- Subcutaneous:Investigational depot formulations and gene therapy vector delivery under evaluation.
- Topical:Copper-based wound care and hair/skin symptom management in supportive protocols.
Volume leadership sits with Intravenous. Steepest expansion trajectory is concentrated in Oral.
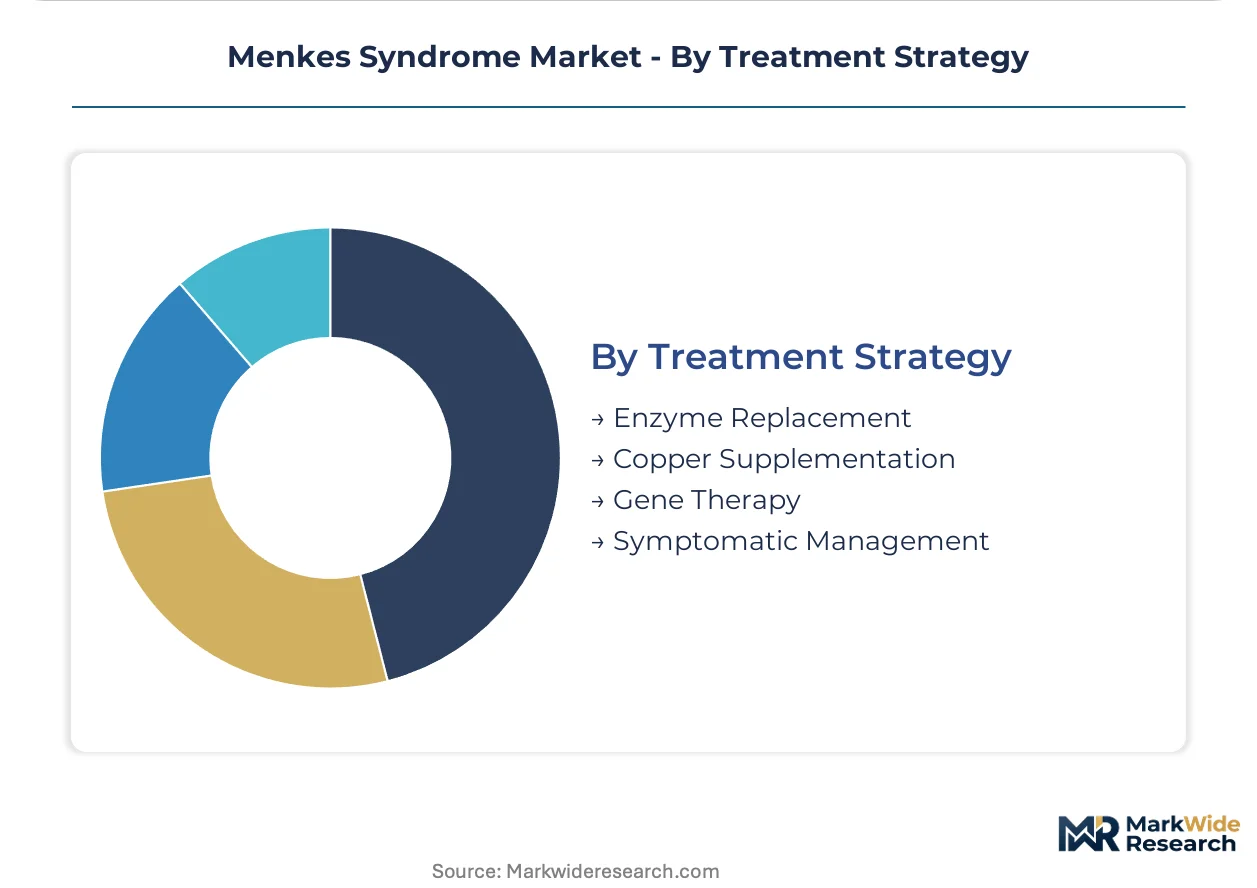
Treatment Strategy:
Curative versus chronic paradigms are bifurcating investment and clinical trial resources.
- Copper Supplementation:Chronic histidine or chloride administration maintains volume leadership across delivery modes. Hospital-based administration in United States academic centers sustains premium economics, though outpatient transition pressure is intensifying.
- Gene Therapy:AAV and lentiviral ATP7A delivery platforms represent the fastest-expanding investment category. Preclinical programs in United States and Japanese academic medical centers are advancing through dedicated manufacturing partnerships, with curative claims threatening to displace lifelong supplementation dependence.
- Enzyme Replacement:Recombinant cuproenzyme approaches remain investigational with limited clinical data.
- Symptomatic Management:Seizure control, nutritional support, and developmental therapies address non-correctable disease manifestations.
Established standard of care sits with Copper Supplementation. Newer deployment is concentrated in Gene Therapy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of ATP7A-targeted therapies concentrates in United States and Japanese academic medical centers, while diagnostic demand spreads across newborn screening networks in Germany, France, and the United Kingdom. Consumption patterns track specialist pediatric metabolic center density.
United States
FDA orphan drug designations and rare pediatric disease priority review vouchers accelerate therapeutic development timelines for ATP7A programs. Newborn screening expansion in state public health laboratories drives diagnostic volume concentration. Academic medical centers in Boston and Philadelphia anchor the deepest treatment infrastructure for copper histidine intervention protocols.
Japan
PMDA sakigake designation pathways compress review timelines for pediatric rare disease therapies, creating registration arbitrage for global sponsors. Specialized pediatric neurology departments in Tokyo and Osaka academic hospitals are expanding dedicated Menkes screening protocols. Domestic manufacturing partnerships secure AAV vector supply for preclinical gene therapy programs.
Germany
EMA priority medicines scheme incentives attract ATP7A therapeutic development through accelerated assessment pathways. Reference laboratory networks in Munich and Heidelberg concentrate confirmatory ATP7A sequencing workflows. University hospital metabolic genetics departments coordinate European clinical trial site activation.
United Kingdom
NHS England's specialized commissioning framework routes Menkes cases to designated pediatric metabolic centers in London and Manchester. Genomics England infrastructure supports research sequencing integration with clinical diagnostics. Academic partnerships in Cambridge advance CRISPR-based ATP7A correction preclinical programs.
France
ANSM early access programs provide regulatory pathways for innovative copper transport modulators before formal marketing authorization. Reference centers for rare diseases in Paris coordinate national care networks for ATP7A-related disorders. Lyon-based academic hospitals participate in European gene therapy manufacturing consortia.
Menkes Syndrome Market Vendor Landscape
Top-tier vendors anchor rare disease platform infrastructure, while mid-tier specialists concentrate on diagnostic supply chains and copper formulation manufacturing. The competitive structure stratifies between integrated rare disease developers controlling clinical trial execution and reagent suppliers dominating ATP7A testing workflows. Strategic archetypes include platform-based rare disease sponsors, diagnostic supply chain controllers, and metabolic specialty pharmaceutical manufacturers. Dominant competitive moves involve manufacturing partnerships for gene therapy vector supply and newborn screening assay integration contracts.
Within the rare disease platform tier, Fortress Biotech and Ultragenyx Pharmaceutical Inc. occupy positions as integrated development sponsors with ATP7A program pipelines. Thermo Fisher Scientific Inc. anchors the diagnostic supply segment through reagent and sequencing platform dominance. Among specialty pharmaceutical manufacturers, Teva Pharmaceutical Industries Ltd. exemplifies generic and specialty copper formulation production capacity. These three archetypes collectively span therapeutic development, diagnostic enablement, and commercial manufacturing functions across the Menkes syndrome care continuum.
| Leading Market Players |
|---|
| Fortress Biotech |
| Teva Pharmaceutical Industries Ltd. |
| Amerigen Pharmaceuticals Limited |
| Mylan N.V. |
| Bausch Health |
| H. Lundbeck A/S |
| Ultragenyx Pharmaceutical Inc. |
| Thermo Fisher Scientific Inc. |
| Sentynl Therapeutics, Inc. |
| Others |
Supply Flow & Price Mechanics
United States academic medical centers and Japanese pediatric metabolic specialists concentrate procurement authority for Menkes syndrome therapeutics, anchoring a hospital-administered pricing model where intravenous copper formulations command premium economics against outpatient alternatives. This buyer concentration enables sustained per-patient revenue capture while cold-chain logistics and tertiary center requirements create natural pricing segmentation between acute intervention and maintenance protocols.
Pricing Analysis
Margin tightening in intravenous copper histidine reflects cold-chain distribution costs and hospital administration requirements that sustain premium positioning against oral alternatives. Three-tier pricing structure across gene therapy curative protocols, hospital-based infusion regimens, and outpatient maintenance supplementation differentiates segments by intervention intensity and neurological preservation potential. Pricing pressure stems from outpatient transition demands and gene therapy curative claims that threaten lifelong supplementation dependence. Pediatric metabolic clinics demonstrate highest price sensitivity due to bundled reimbursement constraints, while gene therapy candidates show lowest sensitivity given curative outcome valuation.
Supply Chain Analysis
Dual-sourcing requirements for AAV vector production compel sponsors to qualify multiple manufacturing partnerships across United States and Japanese academic medical centers. Reagent supply for ATP7A sequencing concentrates in United States and German diagnostic platform vendors, while copper chloride API production centers on United States and Israeli specialty pharmaceutical manufacturers. Single-source vulnerability pervades confirmatory testing workflows where Thermo Fisher Scientific controls assay supply chains. Distribution runs through hospital-based specialty pharmacy networks and academic medical center metabolic genetics departments rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Menkes syndrome therapeutics stand at a transition point where AAV-mediated ATP7A gene delivery threatens to displace chronic copper supplementation as the standard of care, compressing investment timelines for legacy modality sponsors.
For Market Incumbents: Cement control over hospital-administered copper formulation supply chains through exclusive metabolic center partnerships before gene therapy curative protocols reach clinical validation. Secure newborn screening assay integration contracts with state public health laboratories to anchor diagnostic workflow capture against emerging CRISPR-based testing alternatives. Prioritize manufacturing partnerships with Japanese academic medical centers to exploit PMDA sakigake pathway acceleration for ATP7A program expansion. For New Entrants and Emerging Players: FDA's rare pediatric disease priority review voucher program in the United States opens a window for gene therapy sponsors to compress regulatory timelines and capture premium reimbursement positioning ahead of European reference pricing adoption. Target preclinical-stage ATP7A delivery platforms with dedicated AAV manufacturing partnerships as the most penetrable entry point. Pursue academic medical center licensing arrangements rather than de novo clinical trial infrastructure buildout to accelerate proof-of-concept generation. For Investors and Strategic Acquirers: The window for entry favors platform-based rare disease developers with existing ATP7A pipelines and established regulatory relationships with FDA and EMA. Gene therapy manufacturing capacity scarcity and lentiviral packaging cell line bottlenecks create acquisition value for sponsors with secured vector supply partnerships. Watch CRISPR-copper chaperone convergence progress as the inflection signal that could obsolete supplementation paradigms without warning.| Strategic Initiative | Industry Significance |
|---|---|
| Newborn Screening Assay Integration | State public health laboratory contracts in the United States lock in diagnostic workflow capture and early patient identification. |
| AAV Manufacturing Partnership | Academic medical center alliances in Boston and Tokyo secure constrained vector production capacity for ATP7A programs. |
| PMDA Sakigake Registration | Japan's compressed review pathway accelerates pediatric rare disease therapeutic access and creates regulatory arbitrage. |
| Gene Therapy Curative Protocol | Preclinical hepatocyte and neuronal transduction programs threaten to displace lifelong copper histidine dependence. |
| Remote Patient Monitoring Platform | Telemetry-enabled copper tracking and video-based neurodevelopmental assessment unbundle acute from longitudinal care. |
Methodological Framework
FDA orphan drug designations, EMA priority medicines scheme submissions, and ClinicalTrials.gov ATP7A program records formed the secondary backbone for therapeutic development pipeline mapping. Primary interviews with pediatric metabolic specialists, neonatal intensive care unit directors, and diagnostic platform commercial leads combined with secondary validation to triangulate treatment protocol adoption patterns. Bottom-up demand modeling across newborn screening expansion trajectories and top-down regulatory incentive valuation anchored market size estimation.
Historical trendline analysis of copper supplementation utilization and gene therapy investment flows informed projection frameworks across the analysis window. Segmentation modeling incorporated treatment strategy bifurcation, delivery mode economics, and regional regulatory cluster differentiation. CAGRs derived from patient identification rate acceleration and therapeutic modality transition assumptions. Forecast inputs included newborn screening mandate expansion timelines and AAV manufacturing capacity buildout trajectories.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based ATP7A correction or small-molecule copper chaperone advances would alter the outlook substantially. Forecasts reflect assumptions regarding regulatory approval timelines and reimbursement persistence for chronic supplementation protocols. Deviation in gene therapy clinical trial readouts or vector manufacturing scale-up success would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Spina Bifida Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Down Syndrome Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Atypical Hemolytic Uremic Syndrome (Ahus) Treatment Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Edward’s Syndrome Treatment Market
Rare Diseases
Europe Rett Syndrome Market
Rare Diseases
Alzheimer Disease Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Global Gaucher Disease Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market