
 Fusion Inhibitors Market | 2026-2036
Fusion Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
Fusion Inhibitors Market Foresight
North American biopharmaceutical capacity is narrowing as contract manufacturing organizations expand viral vector and peptide synthesis capabilities. Bristol-Myers Squibb Company leverages its integrated discovery infrastructure to sustain long-cycle development programs for fusion-targeting compounds. ViiV Healthcare anchors its portfolio through deep specialization in HIV therapeutic regimens. Gilead Sciences competes by controlling distribution networks that reach high-burden infectious disease centers.
Fusion inhibitors are synthetic or biologic molecules that block viral envelope proteins from merging with host cell membranes, typically functioning through gp41-targeting peptide sequences or small-molecule allosteric modulation of viral surface glycoproteins. Their primary purpose is preventing viral entry rather than intracellular replication, which creates a mechanistically distinct therapeutic class with resistance profiles that complement reverse transcriptase or protease inhibitors. Peptide-based fusion inhibitors retain established clinical positions in salvage HIV therapy where multidrug resistance limits oral regimen options. Small molecule candidates within the pipeline are attracting development investment due to superior bioavailability and reduced injection burden relative to enfuvirtide-class agents. Monoclonal antibodies targeting RSV fusion proteins command premium positioning in pediatric and geriatric prophylaxis segments where hospitalization avoidance drives payer value assessments.
FDA accelerated approval designations and EMA conditional marketing authorizations create divergent market access timelines that shape regional launch sequencing for novel fusion inhibitors. The WHO prequalification program governs procurement eligibility for low-income country access through multilateral purchasing mechanisms. Stakeholders must monitor how CMS reimbursement coding for long-acting injectable antivirals evolves relative to oral standard-of-care benchmarks.
Market Dynamics
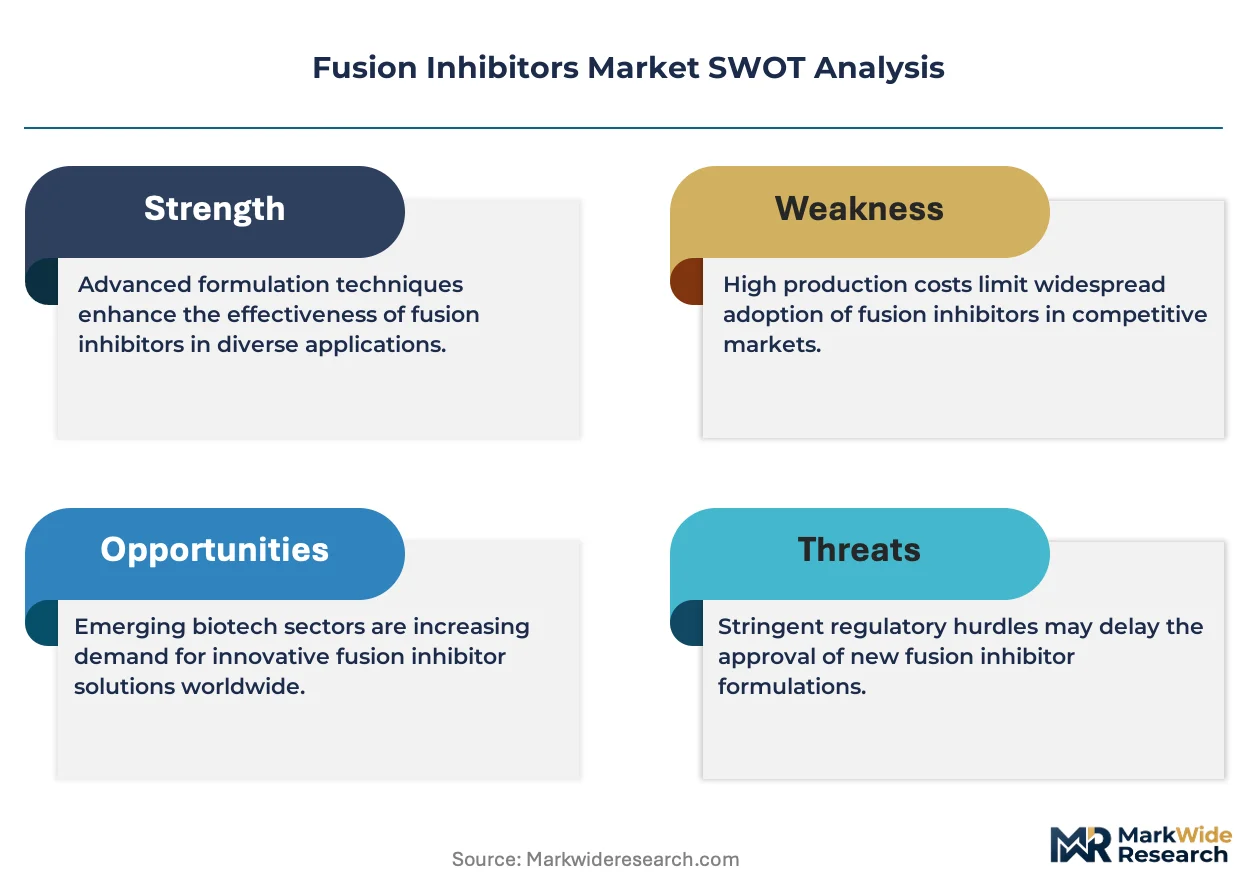
FDA accelerated approval pathways for antiviral therapies are compressing development timelines for new molecular entities, while hospital procurement of HIV therapeutics maintains consistent volume commitments in the United States. Contract manufacturing organizations are expanding viral vector and peptide synthesis capabilities, narrowing North American biopharmaceutical capacity.
Growth Catalysts
- FDA Accelerated Approval:Compressed review timelines for antiviral therapies enable faster market entry for novel fusion-targeting compounds, reducing capital lock-up periods for developers.
- Specialty Clinic Expansion:Rising patient volumes at infectious disease centers expand the addressable base for fusion inhibitor administration and long-acting injectable delivery.
- WHO Prequalification:Eligibility through multilateral purchasing mechanisms governs procurement access for low-income country programs, opening volume channels outside branded markets.
Market Restraints
- Peptide Manufacturing Concentration:Synthesis of gp41-targeting sequences depends on specialized contract manufacturers concentrated in Switzerland and Singapore, creating supply vulnerability.
- Enfuvirtide-class Bioavailability Limits:Poor oral absorption of first-generation peptide inhibitors necessitates subcutaneous injection, restricting patient adherence relative to small-molecule alternatives.
- EMA Conditional Authorization Friction:Divergent evidence requirements between FDA and European pathways delay parallel launch sequencing, fragmenting revenue recognition timelines.
Strategic Opportunities
- Small-Molecule Pipeline Conversion:Allosteric modulators of viral surface glycoproteins promise superior bioavailability and reduced injection burden, capturing patients lost to adherence failures.
- RSV Prophylaxis Expansion:Monoclonal antibodies targeting respiratory syncytial virus fusion proteins command premium positioning in pediatric and geriatric segments where hospitalization avoidance drives payer value.
- Long-Acting Injectable Reimbursement:CMS coding evolution for extended-interval antivirals creates pricing headroom above oral standard-of-care benchmarks.
Industry Challenges
- Peptide Synthesis Talent Scarcity:Viral vector and solid-phase manufacturing expertise concentrates at a handful of specialized facilities, constraining workforce mobility.
- Resistance Surveillance Infrastructure:Multidrug-resistant HIV strain monitoring requires continuous genotypic testing investment, adding fixed cost layers to salvage therapy programs.
- Legacy Formulation Integration:New molecular entities must demonstrate compatibility with existing cold-chain distribution networks reaching high-burden infectious disease centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fusion Inhibitors Market |
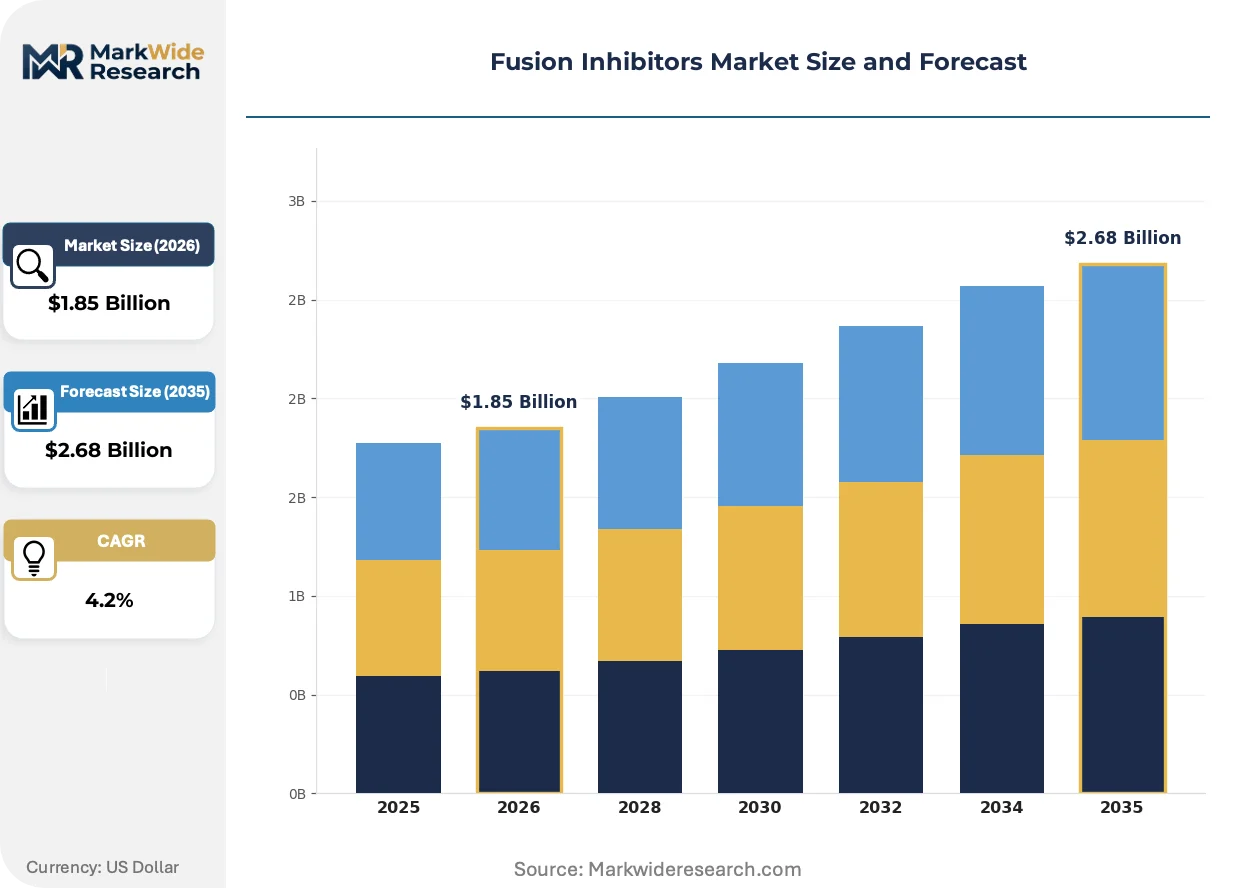
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peptide-Based, Small Molecule, Monoclonal Antibodies, Synthetic Inhibitors Therapy Area: HIV/AIDS, Respiratory Syncytial Virus, Influenza, Hepatitis C End User: Hospitals, Specialty Clinics, Diagnostic Laboratories, Research Institutes Delivery Mode: Injectable, Oral, Nasal Spray, Transdermal Patch |
| Companies Covered | Bristol-Myers Squibb Company, ViiV Healthcare, AstraZeneca, Incyte, PeptidePharma, Gilead Sciences, Merck & Co., Genentech, Biogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fusion Inhibitors Market Shifts & Advancements
Small-molecule allosteric modulators are collapsing the technical barriers that have restricted fusion inhibitors to injectable formats, while regulatory pathways diverge across major jurisdictions. Procurement patterns for antiviral therapies are compressing switching cycles as hospital formularies prioritize long-acting options.
Oral bioavailability engineering is collapsing the dominance of subcutaneous peptide delivery in HIV salvage therapy. Medicinal chemistry programs at specialized biopharmaceutical firms are advancing small-molecule gp41 antagonists with permeability profiles matching protease inhibitors. Hospital infectious disease departments are accelerating formulary reviews to capture these candidates, compressing the historical 18-month adoption lag for new antiviral classes.
REACH authorization requirements for novel peptide constructs are extending European development timelines relative to FDA pathways. ECHA substance registration mandates for imported synthetic intermediates add documentation layers that compress competitive windows for first movers. Contract manufacturers with dual US-EU certification are capturing disproportionate volume as developers prioritize single-source qualification to avoid parallel regulatory tracks.
Hospital procurement committees are consolidating antiviral purchasing through integrated delivery networks, displacing independent pharmacy decision-making. Specialty distributors with cold-chain capabilities are capturing volume previously fragmented across wholesale channels, concentrating margin with logistics-integrated suppliers. This consolidation is most visible in United States metropolitan markets where academic medical centers anchor regional formularies.
Fusion Inhibitors Market Segmentation
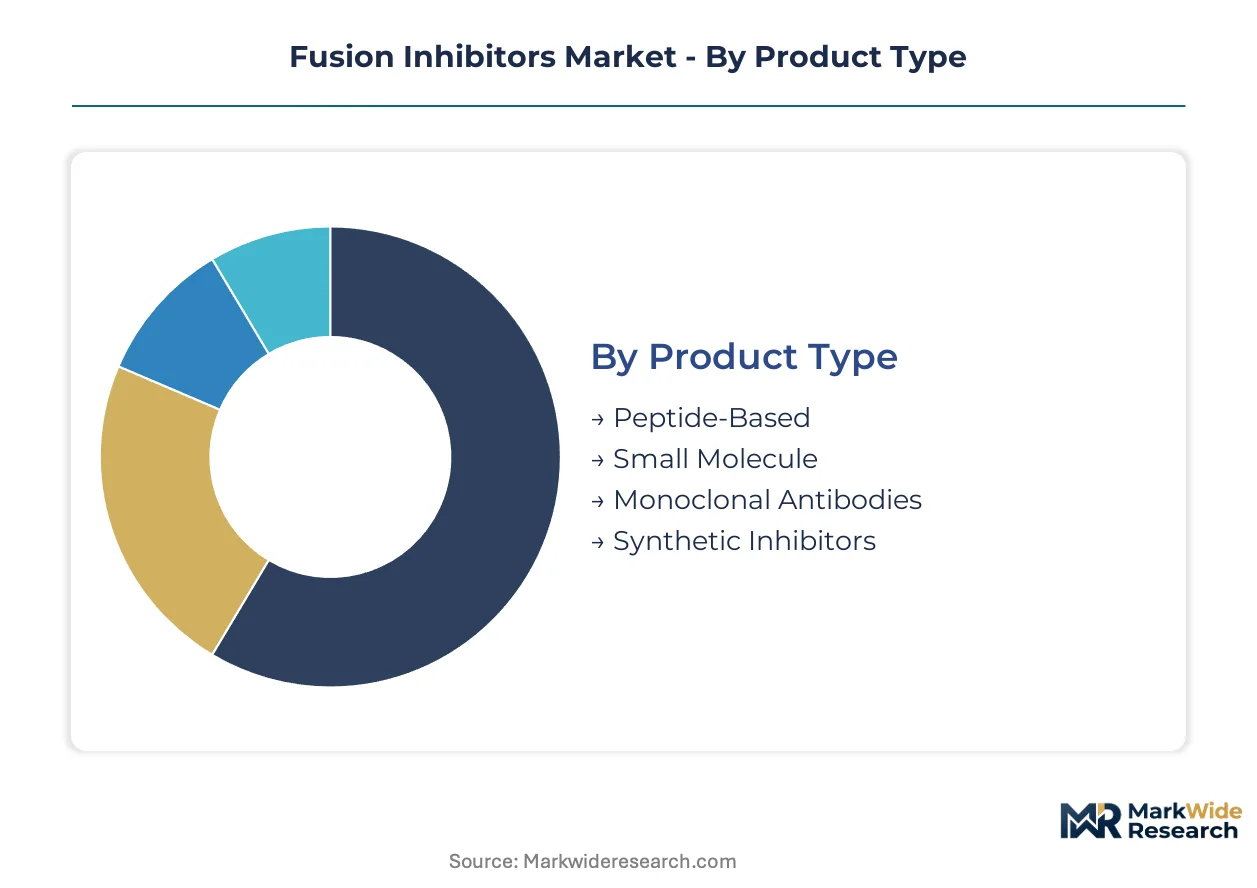
Fusion inhibitors fragment across mechanistic classes, therapeutic applications, and delivery modalities that each impose distinct development constraints. Understanding these segment boundaries clarifies where capital allocates and where regulatory pathways diverge.
Product Type:
Mature peptide formats anchor current revenue while emerging small-molecule platforms promise route-of-administration breakthroughs.
- Peptide-Based:Synthetic gp41-targeting sequences disrupt viral envelope fusion through helical bundle interference. United States hospital procurement maintains consistent volume commitments for enfuvirtide-class agents in multidrug-resistant salvage regimens. Injectable delivery burdens restrict outpatient adoption despite established clinical utility.
- Small Molecule:Allosteric modulators of viral surface glycoproteins achieve oral bioavailability through permeability engineering. Medicinal chemistry programs at specialized biopharmaceutical firms are advancing candidates with absorption profiles matching protease inhibitors. FDA accelerated approval pathways compress development timelines for these next-generation entities.
- Monoclonal Antibodies:Engineered immunoglobulins target RSV fusion proteins with extended half-lives enabling seasonal prophylaxis.
- Synthetic Inhibitors:Chemically optimized non-peptide constructs bridge bioavailability and specificity requirements.
Peptide-Based handles the majority of throughput; Small Molecule is expanding most quickly on share.
Therapy Area:
Volume concentrates in infectious disease categories with established reimbursement infrastructure versus emerging antiviral applications.
- HIV/AIDS:Fusion inhibitors serve as mechanistically distinct salvage therapy where reverse transcriptase and protease resistance limits oral regimen options. United States specialty clinics administer the bulk of injectable fusion inhibitor doses through infectious disease center networks. Continuous genotypic testing investment adds fixed cost layers to multidrug-resistant strain monitoring programs.
- Respiratory Syncytial Virus:Monoclonal antibodies targeting fusion proteins command premium positioning in pediatric and geriatric prophylaxis segments. Hospitalization avoidance drives payer value assessments for infant and elderly populations during seasonal circulation periods.
- Influenza:Hemagglutinin-targeting fusion inhibitors address pandemic preparedness stockpiling requirements.
- Hepatitis C:Entry inhibition remains investigational as direct-acting antivirals dominate curative regimens.
HIV/AIDS absorbs the dominant share of current development investment; Respiratory Syncytial Virus is climbing the fastest on commercial priority.
End User:
Procurement authority is consolidating through integrated delivery networks that displace independent pharmacy decision-making.
- Hospitals:Academic medical centers anchor regional formularies in United States metropolitan markets, consolidating antiviral purchasing through integrated delivery networks. Infectious disease departments accelerate formulary reviews to capture small-molecule candidates, compressing historical adoption lags for new therapeutic classes. Cold-chain distribution capabilities concentrate procurement with logistics-integrated suppliers.
- Specialty Clinics:Rising patient volumes at infectious disease centers expand the addressable base for long-acting injectable delivery. Outpatient administration infrastructure supports peptide-based fusion inhibitor protocols requiring subcutaneous injection.
- Diagnostic Laboratories:Resistance surveillance testing supports therapeutic selection for salvage regimens.
- Research Institutes:Early-stage discovery programs advance novel gp41 antagonist chemistries.
Hospitals control the bulk of commercial volume; Specialty Clinics are gaining share fastest on patient migration to outpatient settings.
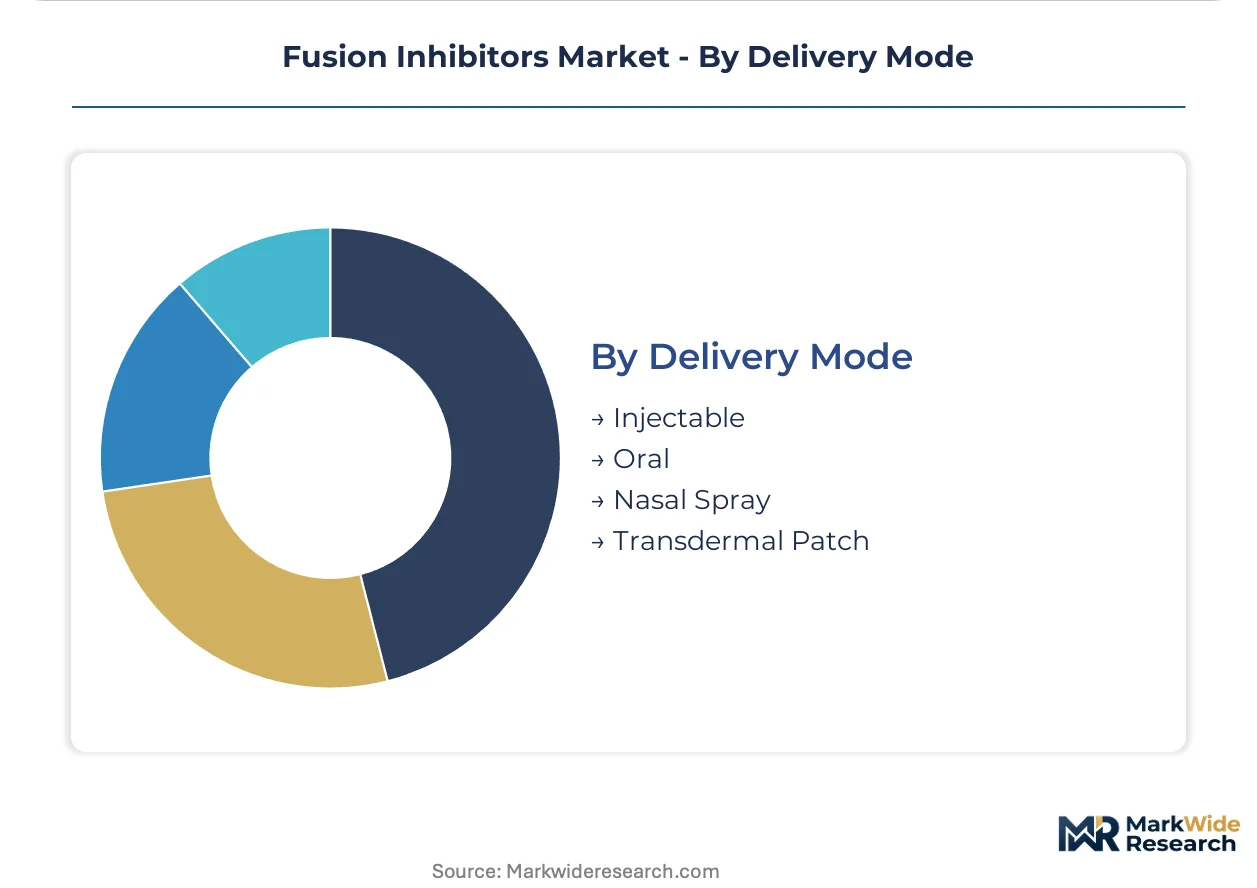
Delivery Mode:
Route-of-administration differentiation creates adherence advantages that reshape competitive positioning across patient populations.
- Injectable:Subcutaneous and intravenous formats dominate peptide-based and monoclonal antibody fusion inhibitors requiring high bioavailability. Long-acting depot formulations extend dosing intervals, with CMS reimbursement coding evolution creating pricing headroom above oral standard-of-care benchmarks. Cold-chain requirements constrain distribution to specialty pharmacy channels.
- Oral:Small-molecule allosteric modulators collapse technical barriers that restricted earlier fusion inhibitors to parenteral delivery. Medicinal chemistry programs engineer permeability profiles matching protease inhibitor absorption characteristics.
- Nasal Spray:Mucosal delivery targets respiratory virus prophylaxis at portal of entry.
- Transdermal Patch:Sustained release formats remain developmental for peptide size and stability challenges.
Injectable maintains current revenue concentration; Oral is the steepest expansion trajectory on bioavailability engineering advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals administer fusion inhibitors through distinct procurement channels compared to European specialty clinics or Asian research hospitals, creating divergent access patterns across major markets.
United States
FDA accelerated approval pathways compress development timelines for novel antiviral therapies, enabling faster market entry for fusion-targeting compounds. CMS reimbursement coding for long-acting injectable antivirals creates pricing headroom above oral standard-of-care benchmarks. Boston and San Francisco anchor infectious disease research clusters where academic medical centers drive formulary adoption.
Germany
EMA conditional marketing authorizations impose divergent evidence requirements that delay parallel launch sequencing with FDA pathways. REACH authorization mandates for peptide constructs extend European development timelines through ECHA substance registration requirements. The Rhine-Ruhr and Munich regions concentrate contract manufacturing organizations with dual US-EU certification.
Switzerland
Specialized peptide synthesis capabilities concentrate among contract manufacturers serving gp41-targeting sequence production. Swissmedic regulatory frameworks govern marketing authorization for biologic fusion inhibitors. Basel anchors pharmaceutical development infrastructure with integrated viral vector manufacturing expertise.
Japan
PMDA review pathways for antiviral therapies maintain distinct evidentiary standards for fusion inhibitor approval. METI industrial policy supports domestic biopharmaceutical capacity expansion through targeted R&D incentives. The Kanto region around Tokyo concentrates hospital procurement authority for infectious disease therapeutics.
Singapore
Solid-phase peptide manufacturing expertise supports regional supply chains for injectable fusion inhibitor production. The country's national pharmaceutical regulator aligns with WHO prequalification standards for multilateral procurement eligibility. Biopolis research cluster advances medicinal chemistry programs for small-molecule gp41 antagonists.
Fusion Inhibitors Market Competitive Landscape
Capability concentration sits with specialized biopharmaceutical developers; scale advantage sits with integrated pharmaceutical conglomerates. The market structure tiers across peptide synthesis specialists, small-molecule discovery platforms, and monoclonal antibody developers. Strategic archetypes include long-cycle R&D sustainers, viral entry mechanism specialists, and distribution-integrated therapeutics suppliers. Dominant competitive moves encompass strategic partnerships for manufacturing capacity access and portfolio diversification into long-acting injectable formats.
Among integrated pharmaceutical developers, Bristol-Myers Squibb Company and Gilead Sciences occupy positions representing distinct competitive vectors within the market. ViiV Healthcare exemplifies the specialized HIV therapeutic developer archetype. These entities anchor industry-level patterns through their respective approaches to fusion inhibitor development and commercial infrastructure.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| ViiV Healthcare |
| AstraZeneca |
| Incyte |
| PeptidePharma |
| Gilead Sciences |
| Merck & Co. |
| Genentech |
| Biogen |
| Others |
Supply & Pricing Matrix
Single-source dependency on Swiss and Singaporean peptide synthesis facilities determines both the premium commanded by dual-certified manufacturers and the geographic concentration of supply chain nodes. FDA accelerated approval pathways compress development timelines, yet EMA REACH authorization requirements extend European qualification periods, creating pricing tier spreads between rapid-US-launch and delayed-EU-entry products.
Pricing Analysis
United States pricing for long-acting injectable fusion inhibitors runs above European benchmarks, reflecting CMS reimbursement coding that creates headroom above oral standard-of-care therapies. Three-tier pricing structure across premium monoclonal antibodies, standard peptide-based salvage therapies, and economy-positioned small-molecule candidates differentiates by bioavailability profile and administration burden. Pricing pressure stems from hospital procurement consolidation through integrated delivery networks, which squeezes margin on legacy enfuvirtide-class products. Specialty clinics exhibit highest price sensitivity due to outpatient budget constraints, while academic medical centers anchor premium tier absorption.
Supply Chain Analysis
Extended payment terms from integrated delivery networks strain contract manufacturer working capital, particularly for solid-phase peptide synthesis specialists. Supply concentrates in Switzerland, Singapore, and the Rhine-Ruhr region, where dual US-EU certification capabilities command disproportionate volume. Raw material dependencies span protected amino acids, viral vector production media, and specialized chromatography resins. Single-source vulnerability at Swiss peptide synthesis facilities threatens continuity for gp41-targeting sequence production. Distribution runs through cold-chain specialty pharmacies reaching high-burden infectious disease centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion inhibitor commercialization increasingly attaches value through resistance surveillance testing and long-acting formulation services, where recurring diagnostic and administration-protocol revenue expands faster than molecule-specific sales. Service-layer integration now determines competitive positioning.
For Market Incumbents: Harden manufacturing capacity access through exclusive partnerships with dual-certified contract organizations in Switzerland and Singapore, insulating against peptide synthesis talent scarcity. Deepen backward integration into viral vector production to capture margin from monoclonal antibody prophylaxis expansion. Defend against small-molecule pipeline displacement by accelerating oral bioavailability programs through medicinal chemistry acquisitions. For New Entrants and Emerging Players: Pursue white-space positioning in RSV prophylaxis segments, where hospitalization-avoidance value propositions command premium pricing with limited incumbent saturation. Target pediatric and geriatric prophylaxis applications as the most penetrable therapeutic application layer. Establish go-to-market presence through specialty distributor partnerships with existing cold-chain capabilities rather than building de novo hospital access infrastructure. For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion reshapes the acquisition landscape toward clinical-stage assets with compressed regulatory timelines. Long-term viability centers on platform durability across multiple viral entry targets rather than single-molecule dependency. Monitor CMS reimbursement coding evolution for long-acting injectables as the critical inflection signal for pricing power sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Dual US-EU certification at Swiss facilities captures volume from developers avoiding parallel regulatory tracks. |
| Pipeline Diversification | Small-molecule gp41 antagonist programs reduce injection burden and expand addressable patient populations. |
| Regulatory Approval Pathway | FDA accelerated approval compresses capital lock-up periods for novel fusion-targeting compounds. |
| Strategic Partnership | Integrated delivery network alliances consolidate hospital procurement authority and displace independent pharmacy channels. |
| Clinical Trial Advancement | Resistance surveillance infrastructure investment adds fixed cost layers that deepen salvage therapy moats. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-volume modeling across therapy areas and top-down revenue triangulation against disclosed pharmaceutical segment sales anchored quantitative outputs.
Forecast inputs span mechanistic class adoption curves, regional regulatory cluster differentiation, and administration route migration patterns across the projection horizon. Segmentation dimensions modeled include product type, therapeutic application, end-user channel, and delivery modality. CAGRs derive from trend extrapolation against historical antiviral class launch trajectories, adjusted for bioavailability engineering advances and long-acting formulation penetration.
Sensitivities concentrate around FDA review timeline variability, EMA conditional authorization friction, and WHO prequalification eligibility shifts. Forecasts reflect documented assumptions regarding regulatory pathway convergence and hospital procurement consolidation velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
AI in Pharma Market
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Prescription Transdermal Patches Market
Pharmaceuticals
Iron Deficiency Injectables Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Global Adult Vaccines Market
Pharmaceuticals
Global HPMC Capsules Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market