
 Pain Patches Market | 2026-2036
Pain Patches Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Patches Market Analysis
Transdermal manufacturing capacity in South Korea is recalibrating as domestic producers expand hydrogel and matrix adhesive lines to serve export contracts. Hisamitsu Pharmaceutical leverages its proprietary ketoprofen patch technology to sustain premium positioning across Asian and North American hospital channels. Teva Pharmaceutical Industries anchors its portfolio through complex generic fentanyl patches that compete on bioequivalence credentials with reference-listed drugs. Johnson & Johnson differentiates via consumer-facing lidocaine patches that dominate pharmacy shelf space through brand recognition and direct-to-consumer marketing scale.
Pain patches are medicated adhesive systems designed for percutaneous drug delivery, typically incorporating active pharmaceutical ingredients such as nonsteroidal anti-inflammatory drugs, local anesthetics, or opioids within a polymer matrix or reservoir layer at specified release rates measured in micrograms per hour. These devices serve the primary commercial purpose of providing sustained analgesia while bypassing hepatic first-pass metabolism and reducing systemic adverse effects associated with oral or parenteral routes. Chronic pain applications command the largest revenue pool due to recurring prescription patterns among osteoarthritis and lower-back pain patients, while home care end users represent the fastest-expanding channel as reimbursement frameworks shift toward ambulatory management. Online retail distribution is capturing incremental share through subscription models that bypass traditional pharmacy intermediaries.
The FDA enforces bioequivalence requirements under ANDA pathways for generic transdermal systems, while the EMA's MDR framework imposes clinical evidence standards for active-device combination patches marketed in Europe. Japan's PMDA maintains distinct dissolution testing protocols that create separate technical barriers for foreign manufacturers seeking market access. Stakeholders must monitor evolving pharmacovigilance requirements for opioid-containing patches and anticipate how real-world evidence mandates will reshape post-market surveillance obligations across major health authorities.
Market Dynamics
FDA bioequivalence tightening for generic transdermal systems is forcing manufacturers to retool dissolution testing protocols and abandon cost-driven formulation shortcuts that previously sustained margin compression.
Growth Catalysts
- Opioid-Sparing Prescribing Mandates:US clinical guidelines now prioritize non-invasive analgesics for chronic pain, expanding hospital formulary inclusion of lidocaine and diclofenac patches.
- Hydrogel Matrix Advances:Korean producers have scaled adhesive manufacturing lines that enable 72-hour release profiles previously limited to reservoir designs.
- Home Care Reimbursement Expansion:Medicare Advantage plans in the United States now cover transdermal systems for ambulatory osteoarthritis management, bypassing prior authorization requirements.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Fentanyl precursor supply chains cluster in three Indian bulk chemical districts, creating single-source vulnerability for opioid patch manufacturers.
- EMA MDR Clinical Evidence Burden:Active-device combination patches face expanded post-market surveillance obligations that extend regulatory timelines by 18-24 months.
- Oral NSAID Substitution:Generic ibuprofen and naproxen remain the default first-line therapy for acute musculoskeletal pain in cost-sensitive health systems.
Strategic Opportunities
- Pediatric Indication White Space:Japan's PMDA has signaled pathway openness for fever-reducing patches in children under 12, a segment with zero approved transdermal entrants.
- Subscription Direct-to-Consumer Channels:Online platforms now capture recurring revenue from chronic pain patients who bypass pharmacy intermediaries for lidocaine 4% patches.
- Biologic-Compatible Adhesives:Convergence of peptide drug stability research with microneedle array manufacturing opens delivery pathways for monoclonal antibodies previously limited to injection.
Industry Challenges
- Formulation Chemist Scarcity:The specialized expertise required for transdermal permeation enhancer selection remains concentrated among retiring scientists at legacy Japanese and European firms.
- ANDA Bioequivalence Study Costs:FDA requirements for replicate design pharmacokinetic trials now demand $4-8 million per generic submission, excluding smaller manufacturers from fentanyl and buprenorphine markets.
- Cold Chain Integration Complexity:Temperature-sensitive hydrogel patches require reconfigured last-mile logistics that conflict with existing ambient pharmaceutical distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Patches Market |
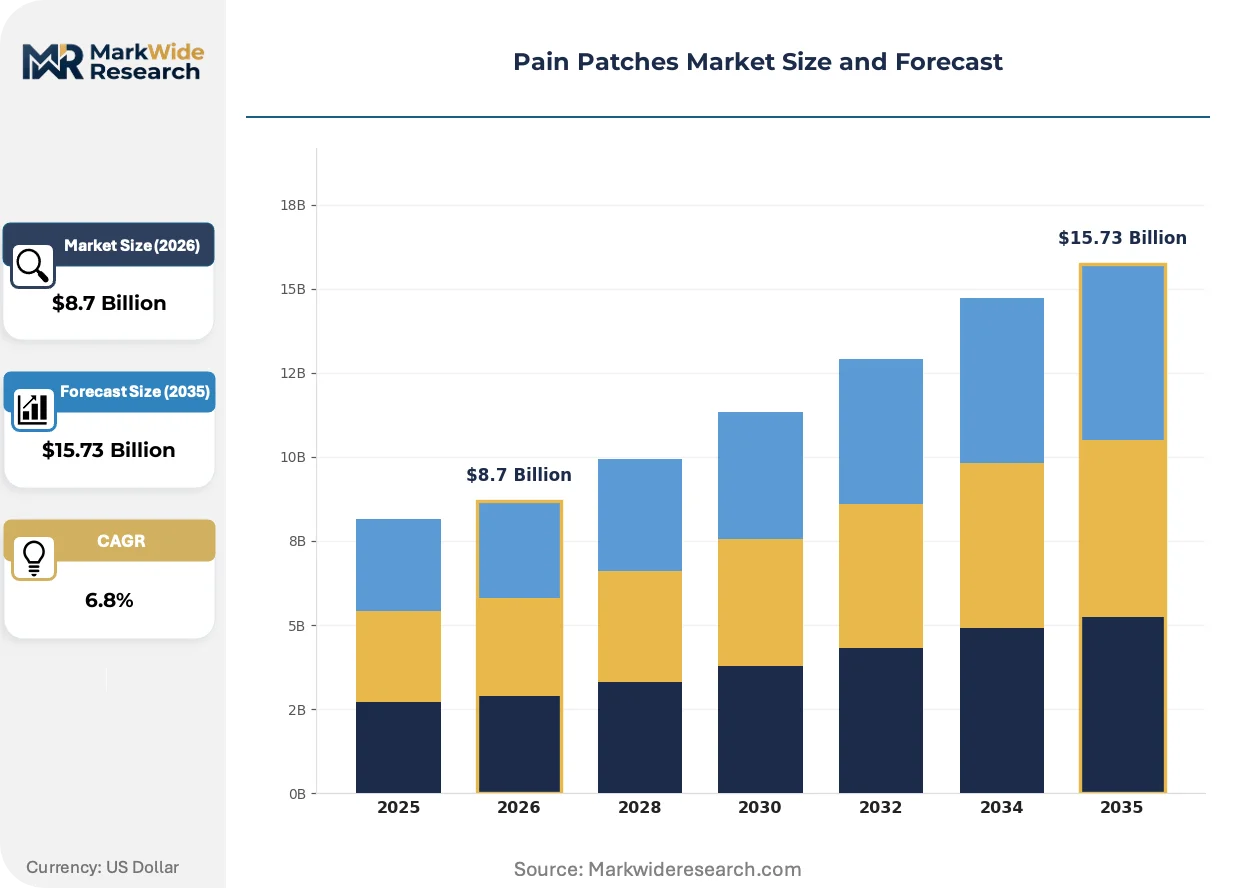
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Chronic Pain, Acute Pain, Postoperative Pain, Muscular Pain Therapy Area: Arthritis, Neuropathic Pain, Cancer Pain, Sports Injuries End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Teva Pharmaceutical Industries, Sanofi, Hisamitsu Pharmaceutical, GSK, Novartis, Johnson & Johnson, Viatris, Endo Pharmaceuticals, Teikoku Seiyaku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Patches Market Emerging Trajectories
Microneedle arrays and iontophoretic delivery systems are displacing passive diffusion as the dominant research frontier, while regulatory agencies simultaneously tighten equivalence standards and expand indication pathways.
Iontophoretic patch technology uses low-level electrical current to drive charged drug molecules through the stratum corneum, enabling dose titration via patient-controlled intensity settings. Hospital pain management units in Germany and the United States are piloting these devices for post-surgical analgesia where rapid onset matters. This active delivery mechanism is converging with smartphone connectivity to enable real-time adherence monitoring and remote dose adjustment by prescribing physicians.
The EMA's Medical Device Regulation framework now classifies many advanced transdermal systems as active-device combinations, triggering clinical evidence requirements that exceed traditional pharmaceutical pathways. Manufacturers must submit biocompatibility data for adhesives and electrical components alongside drug stability documentation. European patch producers are responding by segregating R&D pipelines into pharmaceutical-only and device-combination tracks to manage regulatory risk and timeline uncertainty.
Patients with chronic lower-back pain are abandoning monthly pharmacy visits in favor of automated subscription services that deliver 90-day patch supplies directly to residences. This channel shift bypasses pharmacist counseling and formulary restrictions that previously steered patients toward oral generics. The United States exhibits the most pronounced migration, where high-deductible health plans create cash-pay incentives for patients seeking predictable out-of-pocket costs.
Pain Patches Market Segmentation
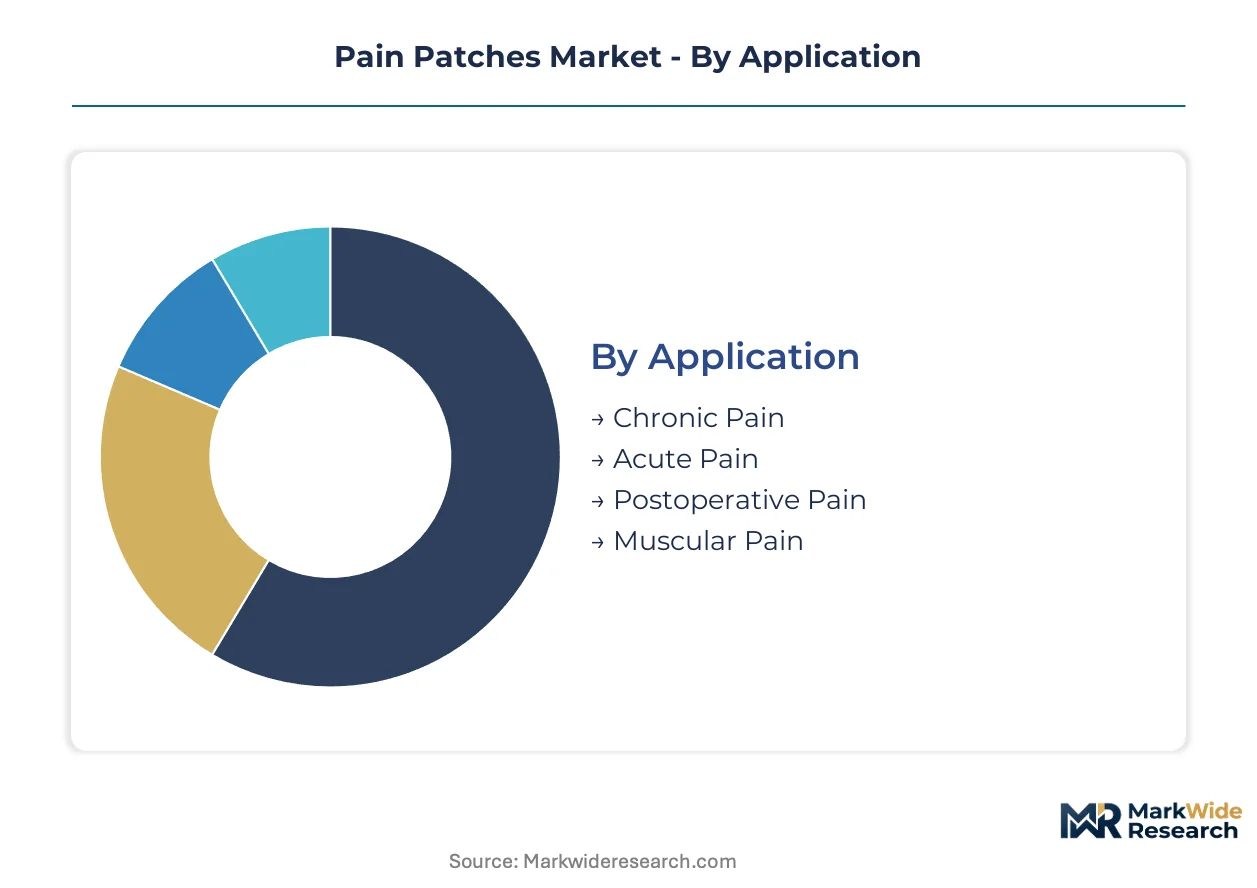
Pain patch segmentation reveals divergent purchasing logics across clinical and consumer channels. Hospital procurement teams prioritize bioequivalence documentation and formulary compliance, while home care buyers respond to subscription convenience and cash-pay pricing transparency.
Application:
Buyers in this category differentiate by treatment duration and prescriber specialty, with chronic pain patients generating recurring revenue streams distinct from acute episode management.
- Chronic Pain:Sustained-release formulations delivering 72-hour analgesia dominate this segment, with osteoarthritis and lower-back pain patients in the United States driving volume through Medicare Advantage reimbursement expansion.
- Acute Pain:Rapid-onset lidocaine and diclofenac patches serve emergency departments and urgent care facilities where oral NSAID contraindications exist, though generic ibuprofen substitution limits pricing power in cost-sensitive systems.
- Postoperative Pain:Iontophoretic delivery systems enable patient-controlled dosing in German and US hospital recovery units.
- Muscular Pain:Over-the-counter 4% lidocaine patches capture pharmacy shelf space through brand recognition and direct-to-consumer marketing scale.
Chronic Pain leads volumes today; Acute Pain is gaining share fastest.
Therapy Area:
Segment differentiation tracks prescriber training depth and reimbursement complexity, with oncology and rheumatology specialists commanding premium positioning over primary care channels.
- Arthritis:Ketoprofen and diclofenac matrix patches target osteoarthritis patients seeking hepatic-sparing alternatives to oral NSAIDs, with Japanese PMDA dissolution protocols creating technical barriers for foreign manufacturers.
- Neuropathic Pain:Lidocaine 5% patches serve diabetic peripheral neuropathy and post-herpetic neuralgia indications where systemic medication adverse effects drive transdermal preference.
- Cancer Pain:Fentanyl reservoir patches require cold chain distribution and DEA-controlled substance handling protocols.
- Sports Injuries:Hydrogel-based cooling patches compete with topical creams in athletic training facilities.
Arthritis commands the largest revenue pool; Neuropathic Pain shows steepest expansion trajectory.
End User:
Purchasing authority varies sharply across this category, with centralized hospital formularies negotiating bulk contracts while home care patients exercise individual brand preference.
- Hospitals:Inpatient pain management units in Germany and the United States pilot iontophoretic devices for post-surgical analgesia, requiring biocompatibility documentation under EMA MDR active-device combination frameworks.
- Home Care:Automated 90-day subscription services bypass pharmacy intermediaries, with US high-deductible health plan enrollees driving cash-pay migration toward predictable out-of-pocket costs.
- Clinics:Outpatient facilities balance formulary restrictions against patient convenience preferences.
- Pharmacies:Retail shelf space competition pits Johnson & Johnson consumer brands against private-label alternatives.
Hospitals anchor institutional procurement volumes; Home Care is climbing the fastest.
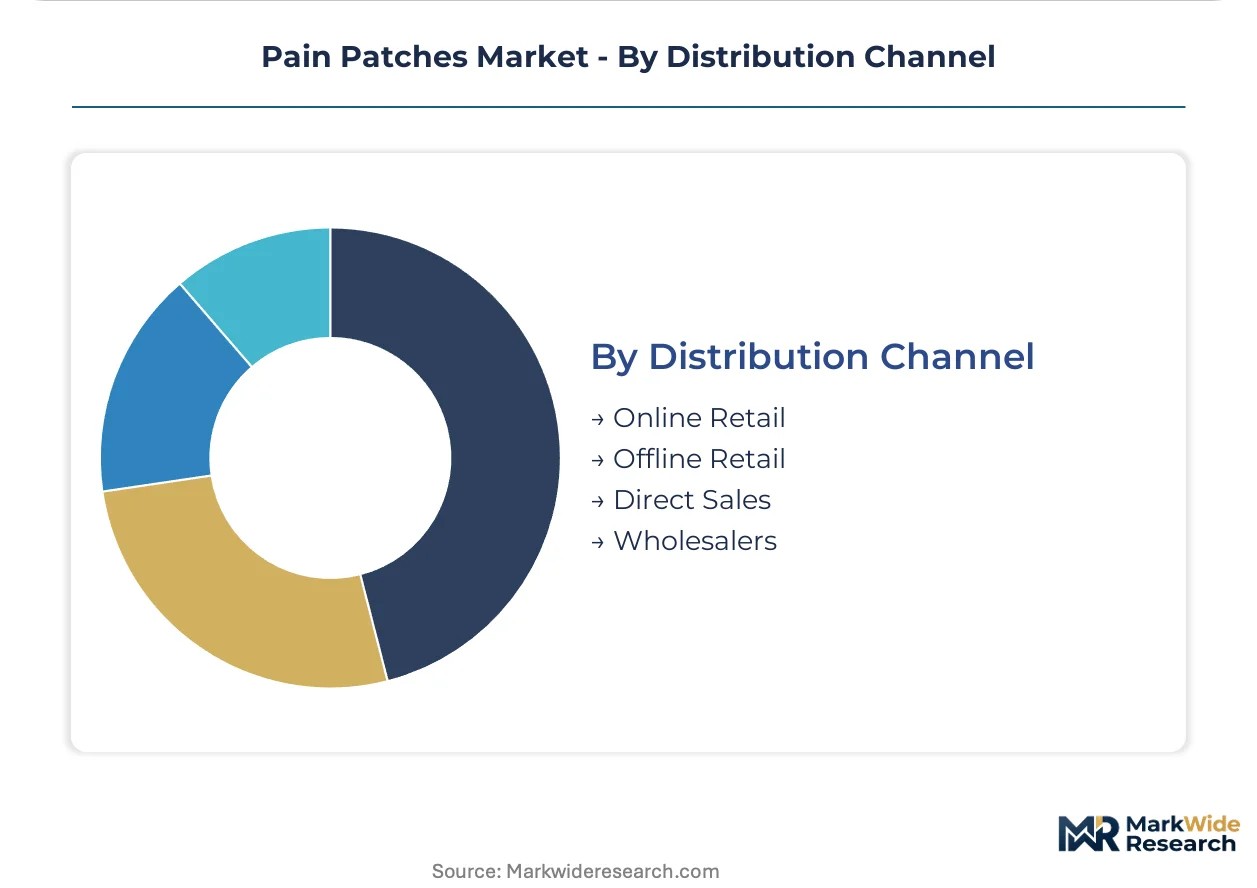
Distribution Channel:
Channel selection reflects patient mobility constraints and insurance architecture, with digital platforms capturing chronic patients who prioritize convenience over pharmacist counseling.
- Online Retail:Subscription models for lidocaine 4% patches capture recurring revenue from US chronic pain patients, bypassing prior authorization requirements that steer formulary decisions in traditional pharmacy channels.
- Offline Retail:Brick-and-mortar pharmacies maintain formulary gatekeeper status for prescription opioid patches and hospital discharge medications.
- Direct Sales:Manufacturer field forces serve hospital systems and specialty clinics with complex bioequivalence documentation requirements.
- Wholesalers:Temperature-sensitive hydrogel patch distribution requires reconfigured last-mile logistics conflicting with ambient pharmaceutical infrastructure.
Offline Retail retains the largest transaction volume; Online Retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement expansion outpaces Japanese regulatory complexity, while South Korean manufacturing scales export capacity faster than European clinical evidence frameworks allow.
United States
Medicare Advantage plans now cover transdermal systems for ambulatory osteoarthritis management without prior authorization, accelerating physician preference for topical analgesics. The FDA enforces tightened bioequivalence requirements under ANDA pathways that force generic manufacturers toward replicate design pharmacokinetic trials. Manufacturing clusters in North Carolina and New Jersey concentrate hydrogel adhesive production for 72-hour release profiles.
Germany
Hospital pain management units pilot iontophoretic delivery systems for post-surgical analgesia where rapid onset drives procurement decisions. The EMA's Medical Device Regulation framework classifies advanced transdermal systems as active-device combinations, extending regulatory timelines by 18-24 months. Industrial concentration in Baden-Württemberg anchors biocompatibility documentation capabilities for European market access.
Japan
PMDA dissolution testing protocols create technical barriers for foreign manufacturers seeking entry, while domestic ketoprofen patch technology sustains premium hospital channel positioning. METI signaling toward pediatric fever-reducing patch pathways opens indication white space for entrants targeting children under 12. Osaka-based producers maintain specialized formulation expertise for permeation enhancer selection.
South Korea
Domestic hydrogel and matrix adhesive line expansion serves export contracts to North American and European buyers seeking 72-hour release alternatives to reservoir designs. The MFDS maintains alignment with international bioequivalence standards while enabling faster generic approval timelines than the FDA. Seoul Capital Area manufacturing clusters recalibrate capacity toward temperature-sensitive cold chain integration.
India
Fentanyl precursor supply chains cluster in three bulk chemical districts, creating single-source vulnerability for opioid patch manufacturers serving export markets. The CDSCO enforces pharmacovigilance requirements for controlled substance patches that mirror DEA protocols. Gujarat and Maharashtra chemical corridors concentrate active pharmaceutical ingredient production for transdermal systems.
Pain Patches Market Vendor Landscape
United States producers anchor one tier; Japanese specialists hold proprietary formulation expertise that resists commoditization. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with hospital formulary leverage, regional patch specialists with adhesive manufacturing depth, and emerging direct-to-consumer brands bypassing pharmacy intermediaries. Dominant competitive moves include capacity expansion in Korean hydrogel lines and strategic technology licensing for iontophoretic delivery systems.
Within the multinational tier, Teva Pharmaceutical Industries and Johnson & Johnson occupy positions that exemplify divergent strategic vectors. Hisamitsu Pharmaceutical represents the regional specialist archetype with concentrated expertise in ketoprofen matrix technology. These three anchors illustrate how competitive positioning splits between bioequivalence-driven generic substitution and consumer-facing brand recognition.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Sanofi |
| Hisamitsu Pharmaceutical |
| GSK |
| Novartis |
| Johnson & Johnson |
| Viatris |
| Endo Pharmaceuticals |
| Teikoku Seiyaku |
| Others |
Supply Flow & Price Mechanics
Active pharmaceutical ingredient spot prices for fentanyl precursors originating from Indian bulk chemical districts cascade through contract manufacturing tiers into three distinct pricing bands: premium reservoir patches, standard matrix designs, and economy hydrogel alternatives. This cost transmission mechanism concentrates margin pressure on mid-tier manufacturers lacking backward integration into adhesive production.
Pricing Analysis
Retailer markup layers in offline pharmacy channels absorb 35-45 percent of ex-manufacturer pricing, while direct-to-consumer subscription models bypass these intermediaries entirely. Pricing stratifies across premium, standard, and economy tiers based on bioequivalence certification status and release duration claims. Cost compression in generic fentanyl segments is intensifying because FDA replicate-study requirements exclude smaller ANDA filers. Hospital procurement teams exhibit lowest price sensitivity due to formulary lock-in, whereas cash-pay home care patients demonstrate highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from German hospital systems and US group purchasing organizations require qualification of at least two adhesive suppliers per patch program, driving consolidation among Korean and Japanese hydrogel specialists. Manufacturing gravity centers on South Korea, Japan, and the United States for finished patches, while active pharmaceutical ingredients draw from India and China. Fentanyl precursor supply chains face single-source vulnerability concentrated in three Gujarat and Maharashtra chemical districts. Distribution runs through temperature-controlled logistics networks that conflict with existing ambient pharmaceutical infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA bioequivalence tightening and EMA MDR active-device classification collectively elevate compliance costs above thresholds that smaller competitors can sustain.
For Market Incumbents: Anticipate margin compression in generic fentanyl segments by securing captive supply of hydrogel adhesives through Korean manufacturing partnerships. Prioritize biocompatibility documentation investments that satisfy EMA MDR requirements before European competitors complete their regulatory filings.
For New Entrants and Emerging Players: Japan's PMDA signaling toward pediatric fever-reducing patch pathways opens a window for first-mover positioning in the under-12 segment with zero approved transdermal entrants. Target direct-to-consumer subscription channels for lidocaine 4% patches where cash-pay patients bypass formulary restrictions entirely.
For Investors and Strategic Acquirers: Asymmetric upside sits with regional patch specialists possessing proprietary permeation enhancer expertise concentrated among Osaka-based formulation chemists. Five-to-ten year viability hinges on adhesive manufacturing capabilities that resist commoditization. Watch for iontophoretic device approvals as inflection indicators signaling active-delivery technology maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Korean hydrogel line expansion serves export contracts requiring 72-hour release profiles. |
| Regulatory Approval Pathway | PMDA pediatric indication submissions address the zero-entrant fever-reducing patch segment. |
| Licensing Agreement | Iontophoretic technology partnerships enable smartphone-connected dose titration capabilities. |
| Backward Integration | Captive adhesive production insulates margins from API price volatility in Indian chemical districts. |
| Reimbursement Strategy | Medicare Advantage formulary inclusion eliminates prior authorization friction for osteoarthritis patients. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with regulatory affairs directors, hospital formulary managers, transdermal manufacturing executives, and pain management specialists alongside secondary validation. FDA ANDA filings, EMA MDR technical documentation, PMDA dissolution protocols, and Medicare Advantage reimbursement databases provided foundational data. Bottom-up patient-volume modeling and top-down pharmaceutical expenditure triangulation anchored market sizing.
Granularity extends to therapy-area level for arthritis, neuropathic pain, cancer pain, and sports injuries, with cross-segment analysis of chronic versus acute application patterns. CAGRs were derived from regression analysis of historical prescription volume trends against demographic and reimbursement drivers. Forecast inputs incorporated opioid-sparing prescribing protocol adoption curves and hydrogel manufacturing capacity expansion timelines.
Revisions become necessary when FDA bioequivalence study cost thresholds shift materially, EMA MDR enforcement intensity deviates from current guidance, or fentanyl precursor supply chain disruptions emerge from Indian chemical district regulatory actions. Deviation in Medicare Advantage transdermal coverage policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chemotherapy Induced Pain Market
Pain Management
Spine Pain Market
Pain Management
Visceral Pain Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Arthralgia Management Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Postoperative Pain Market
Pain Management
Global Morphine Market
Pain Management
Dyspareunia Market
Pain Management
Palliative Care Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Migraine Management Market
Pain Management
Global Pain Management Market