
 Neuralgia Treatment Market | 2026-2036
Neuralgia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neuralgia Treatment Market Intelligence
Specialized neuromodulation device foundries in Ireland and Minnesota are decoupling from legacy pharmaceutical supply chains to serve direct-to-hospital procurement channels. Pfizer Inc. leverages its analgesic portfolio breadth to sustain formulary positioning across integrated delivery networks. Medtronic anchors the implantable neurostimulation segment through manufacturing scale and direct sales infrastructure in major metropolitan hospital systems. Eli Lilly competes in the emerging biologics-for-pain space with differentiated antibody development programs targeting nerve growth factor pathways.
Neuralgia treatment encompasses pharmacological and interventional modalities directed at pathological nerve signaling, including anticonvulsant compounds that modulate voltage-gated calcium channels, local anesthetic nerve blocks using bupivacaine or lidocaine formulations, and implanted pulse generators delivering electrical stimulation at frequencies between 40 and 100 Hz to interrupt nociceptive transmission. Medications remain the dominant product category due to established reimbursement and primary care prescribing patterns, though nerve blocks represent a concentrated margin pool in ambulatory surgery centers where procedure-based billing yields higher per-episode economics. The oral delivery mode occupies the largest volume position, while infusion systems for intrathecal drug delivery represent the fastest-growing delivery segment driven by refractory case complexity in tertiary referral centers.
The FDA's premarket notification and PMA pathways govern device commercialization, while the DEA controls scheduled analgesic distribution, creating dual compliance burdens for combination therapy providers. The EMA's Medical Device Regulation and REACH chemical safety standards shape European market access for both implantable devices and topical formulations. Stakeholders must monitor reimbursement coding decisions for novel neuromodulation indications, as Category III CPT code transitions to permanent status determine whether hospital capital committees approve acquisition of next-generation spinal cord stimulation platforms.
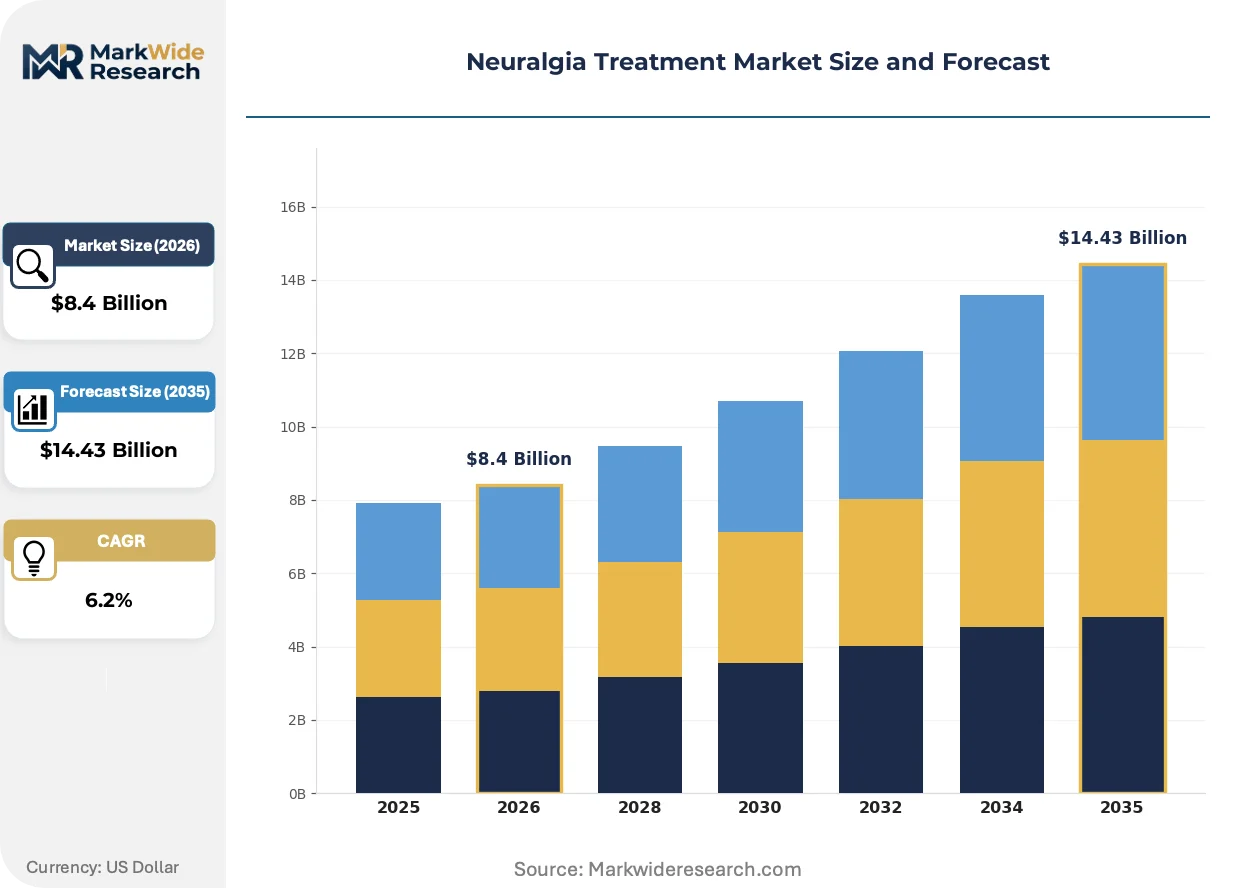
Market Dynamics
Implantable pulse generators are absorbing volume from oral analgesics as Medicare reimbursement revisions in the United States tilt hospital capital committees toward neuromodulation hardware procurement over pharmaceutical formulary expansion.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated pathway compresses clinical trial timelines for neuropathic pain candidates, enabling faster commercialization of novel voltage-gated calcium channel modulators.
- Spinal Cord Stimulation Reimbursement:Medicare coverage expansion across United States metropolitan hospital systems broadens patient access to interventional procedures previously restricted to cash-pay or commercial insurance populations.
- Peripheral Nerve Field Stimulation:Ambulatory surgery centers in Germany and Japan are adding these service lines to capture higher per-episode economics compared to medication management protocols.
Market Restraints
- DEA Scheduling Friction:Controlled substance distribution requirements impose dual compliance burdens on combination therapy providers integrating scheduled analgesics with device-based interventions.
- Ireland-Minnesota Supply Concentration:Specialized neuromodulation foundries in these two geographies create single-source vulnerability for implantable pulse generator component supply.
- Intrathecal Delivery Complexity:Refractory case management requires tertiary referral center infrastructure unavailable in most community hospital settings, limiting addressable patient populations.
Strategic Opportunities
- Japan's Aging Demographics:METI-targeted healthcare infrastructure investments create procurement channels for next-generation spinal cord stimulation platforms in Tokyo and Osaka metropolitan hospital networks.
- Direct-to-Hospital Procurement:Irish and Minnesota device foundries are bypassing legacy pharmaceutical distributors to establish captive supply relationships with integrated delivery networks.
- EMA MDR Compliance:REACH chemical safety standard adherence for topical lidocaine and bupivacaine formulations creates competitive moats for European manufacturers against non-compliant imports.
Industry Challenges
- Category III CPT Code Transition:Novel neuromodulation indications face reimbursement uncertainty until temporary billing codes achieve permanent status, freezing hospital capital committee approvals.
- Intrathecal Pump Specialist Scarcity:Tertiary referral centers report insufficient trained pain medicine physicians to manage complex drug delivery system programming and complication triage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuralgia Treatment Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Physical Therapy, Surgery, Nerve Blocks Delivery Mode: Oral, Injectable, Topical, Infusion End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Treatment Approach: Pharmacological, Surgical, Alternative, Combination |
| Companies Covered | Johnson & Johnson, Pfizer Inc., Novartis AG, GSK plc, Biogen, Medtronic, Eli Lilly, Astellas, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuralgia Treatment Market Strategic Shifts & Innovations
Neuromodulation hardware specifications are converging with pharmaceutical delivery modalities as manufacturers engineer device-drug combination systems. This convergence demands simultaneous mastery of electrical engineering and biopharmaceutical formulation.
Closed-loop spinal cord stimulation systems incorporating evoked compound action potential feedback are absorbing development resources from open-loop programmable platforms. United States academic medical centers are piloting these responsive neurostimulators for trigeminal neuralgia cases refractory to conventional gamma knife intervention. The technology is absorbing market positioning previously held by radiofrequency ablation equipment, compressing procedural volumes in interventional pain clinics.
The FDA's breakthrough therapy designation pathway for neuropathic pain candidates is compressing Phase II-to-III transition timelines. Device manufacturers now face accelerated comparator trial requirements that strain biostatistical consulting capacity. United States-based pain management programs are restructuring clinical trial operations to capture these expedited approval opportunities.
Hospital procurement committees are unbundling after-sales neuromodulation programming services from device capital purchases. Ambulatory surgery centers in Germany now contract independent clinical specialists for spinal cord stimulation parameter optimization rather than relying on manufacturer field clinical engineers. This pattern is most visible in Bavaria and North Rhine-Westphalia, where integrated delivery networks have consolidated implantable device purchasing across multiple facility sites.
Neuralgia Treatment Market Segmentation
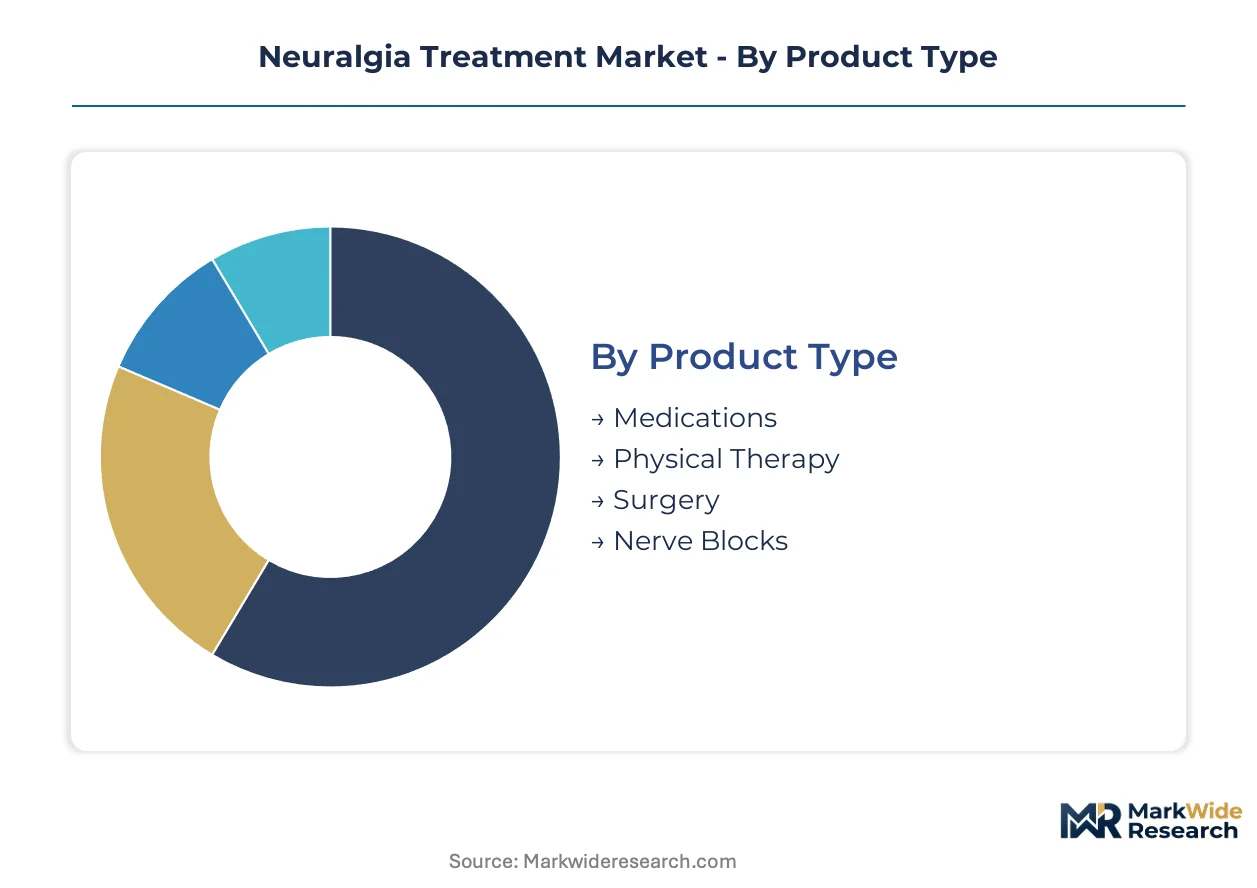
Neuralgia treatment segmentation reflects divergent reimbursement economics and patient acuity tiers. Hospital capital committees weigh device procurement against pharmaceutical formulary costs, while ambulatory settings prioritize procedure-based billing models.
Product Type:
Procurement committees segment spend by recurring pharmaceutical costs versus capital-intensive device investments.
- Medications:Anticonvulsant compounds modulating voltage-gated calcium channels dominate prescribing patterns. United States Medicare reimbursement for gabapentinoids and tricyclic antidepressants sustains primary care volume, though formulary restrictions tighten in integrated delivery networks.
- Nerve Blocks:Bupivacaine and lidocaine formulations delivered via ultrasound-guided injection capture premium per-episode economics. Ambulatory surgery centers in Germany and Japan are expanding these service lines to offset declining medication management margins.
- Physical Therapy:Desensitization protocols and transcutaneous electrical nerve stimulation units address neuropathic pain without invasive intervention.
- Surgery:Microvascular decompression and neurectomy procedures concentrate in tertiary referral centers with specialized neurosurgical infrastructure.
Medications lead on scale; nerve blocks lead on momentum.
Delivery Mode:
Route selection hinges on refractory case complexity and prescriber specialty concentration.
- Oral:Tablet and capsule formulations occupy the largest volume position due to established primary care prescribing pathways. United States retail pharmacy networks sustain this dominance through 90-day supply automation.
- Infusion:Intrathecal drug delivery systems represent the steepest expansion trajectory, driven by refractory case referrals to tertiary pain centers with specialized pump programming capabilities.
- Injectable:Depot formulations and nerve block solutions serve interventional pain clinics with procedure-based revenue models.
- Topical:Lidocaine patches and compounded creams address localized neuralgia without systemic absorption concerns.
Oral delivery leads on scale; infusion leads on momentum.
End User:
Facility type determines capital allocation authority and reimbursement capture mechanisms.
- Hospitals:Metropolitan hospital systems in the United States anchor implantable neurostimulation volume through direct sales relationships with manufacturers. Medicare reimbursement revisions for spinal cord stimulation tilt capital committees toward device procurement.
- Clinics:Interventional pain clinics concentrate nerve block procedures and spinal cord stimulation trials.
- Homecare:External neurostimulation devices and transcutaneous units serve post-acute patients.
- Rehabilitation Centers:Multidisciplinary programs integrate physical therapy with medication taper protocols.
Hospitals lead on scale; clinics lead on momentum.
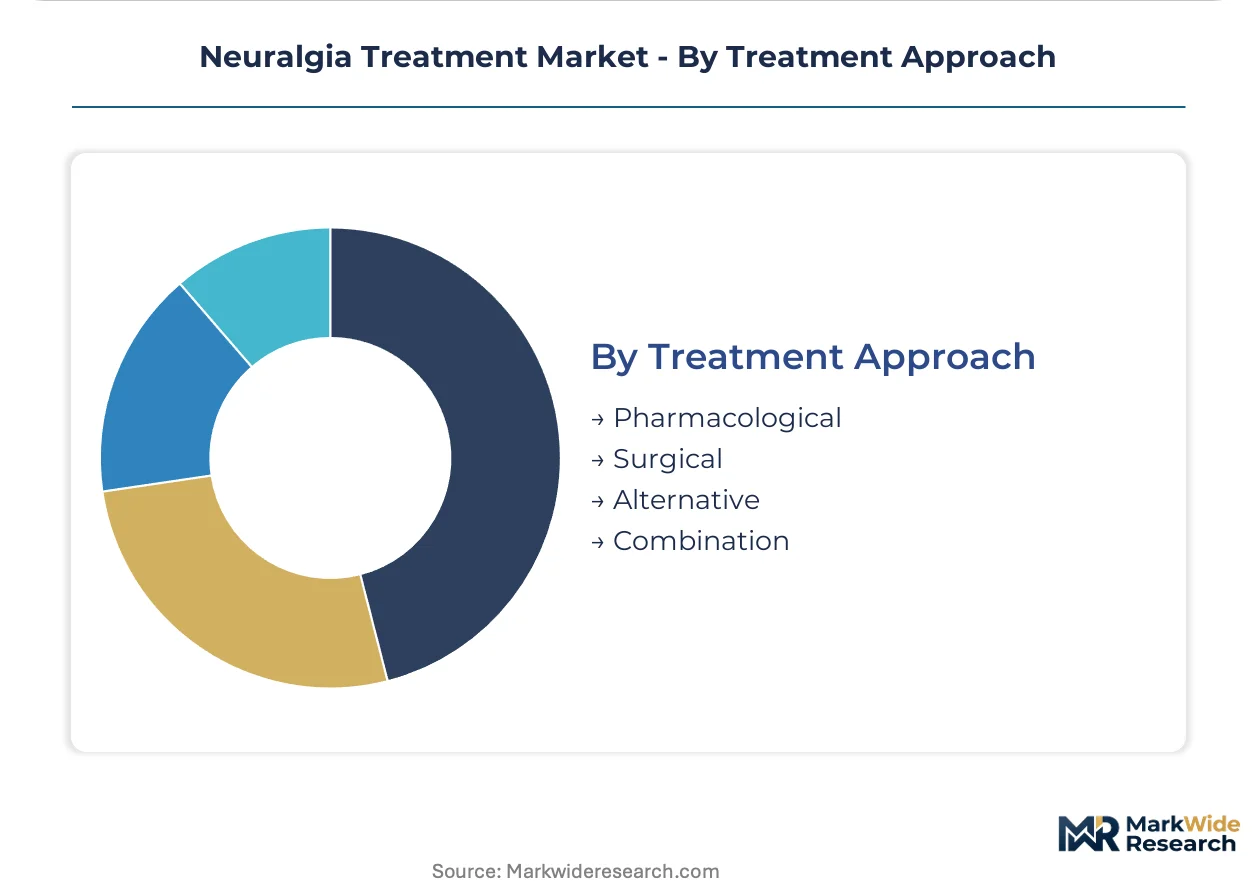
Treatment Approach:
Clinical pathway design reflects payer prior authorization requirements and specialist availability.
- Pharmacological:First-line protocols emphasize anticonvulsants and antidepressants with established FDA indications for neuropathic pain.
- Combination:Integrated device-drug regimens are gaining share fastest as manufacturers engineer closed-loop systems with concurrent pharmaceutical delivery.
- Surgical:Reserved for trigeminal neuralgia and refractory cases with identifiable neurovascular compression.
- Alternative:Acupuncture and biofeedback occupy cash-pay market segments outside mainstream reimbursement.
Pharmacological approaches lead on scale; combination therapies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as specialized neuromodulation foundries migrate toward jurisdictions with streamlined medical device approval pathways and favorable reimbursement climates.
United States
Medicare reimbursement expansion for spinal cord stimulation and peripheral nerve field stimulation is accelerating hospital capital committee approvals across metropolitan hospital systems. The FDA's breakthrough therapy designation pathway compresses clinical trial timelines for neuropathic pain candidates. Minnesota hosts concentrated implantable pulse generator manufacturing operations serving direct-to-hospital procurement channels.
Germany
Ambulatory surgery centers in Bavaria and North Rhine-Westphalia are expanding neuromodulation service lines to capture higher per-episode economics than medication management protocols. The EMA's Medical Device Regulation and REACH chemical safety standards shape market access for implantable devices and topical formulations. Integrated delivery networks have consolidated implantable device purchasing across multiple facility sites in these western states.
Japan
METI-targeted healthcare infrastructure investments are creating procurement channels for next-generation spinal cord stimulation platforms in Tokyo and Osaka metropolitan hospital networks. The PMDA governs device commercialization alongside pharmaceutical approval pathways. Aging demographics are driving demand concentration in Kanto and Kansai regions where specialized pain management programs are restructuring clinical trial operations.
Ireland
Specialized neuromodulation device foundries are decoupling from legacy pharmaceutical supply chains to serve direct-to-hospital procurement channels across European and North American markets. The EMA's MDR compliance requirements create competitive positioning for REACH-adherent manufacturers. Dublin and Cork host concentrated manufacturing operations for implantable pulse generator components.
India
CDSCO regulatory pathways for medical devices and pharmaceuticals are attracting contract manufacturing investment for generic anticonvulsant compounds and topical formulations. The PLI scheme incentivizes domestic production of active pharmaceutical ingredients. Maharashtra and Gujarat host expanding formulation capabilities serving export markets for neuropathic pain medications.
Neuralgia Treatment Market Key Industry Players
United States producers anchor one tier; Irish and Swiss specialists hold manufacturing scale advantages in implantable device segments. The market exhibits consolidated structure in neuromodulation hardware with three dominant manufacturers controlling hospital procurement relationships, while pharmaceutical segments retain fragmented competition among generic and branded analgesic providers. Strategic archetypes include diversified healthcare conglomerates with analgesic portfolio breadth, pure-play neurostimulation device manufacturers with direct sales infrastructure, and emerging biologics developers targeting nerve growth factor pathways. Dominant competitive moves encompass backward integration into specialized foundry operations and strategic partnerships with integrated delivery networks for exclusive procurement contracts.
Among diversified healthcare conglomerates, Johnson & Johnson and Pfizer Inc. occupy positions spanning pharmaceutical and device segments, with the former representing integrated medical technology-to-pharmaceutical breadth and the latter exemplifying analgesic portfolio scale across primary care and specialty prescribing channels. Medtronic anchors the implantable neurostimulation tier through manufacturing scale and metropolitan hospital system relationships. Eli Lilly sits within the emerging biologics-for-pain archetype with differentiated antibody development positioning.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc. |
| Novartis AG |
| GSK plc |
| Biogen |
| Medtronic |
| Eli Lilly |
| Astellas |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Pain medicine specialists concentrated in Minnesota and Ireland command wage premiums that widen spreads between premium neuromodulation systems and economy-tier alternatives. Labor-cost differentials between these specialized foundry regions and generic pharmaceutical manufacturing hubs in India directly shape three-tier pricing structures across hospital procurement channels.
Pricing Analysis
Distributor margins on implantable pulse generators absorb 15-25 points before hospital capital committees evaluate acquisition costs. Pricing stratifies across premium closed-loop systems, standard programmable platforms, and economy-tier external stimulators based on FDA breakthrough designation status and after-sales programming bundling. Cost compression in the oral analgesic tier intensifies as Indian API producers expand gabapentinoid supply. Integrated delivery networks exhibit lowest price sensitivity for capital equipment with permanent Category I CPT codes, while ambulatory surgery centers negotiate aggressively on per-procedure nerve block formulations.
Supply Chain Analysis
Lithium niobate crystal supply for implantable pulse generator capacitors rests on Japanese and German specialty material producers. The neuromodulation device chain draws from Ireland and Minnesota for final assembly, India for generic anticonvulsant APIs, and Japan for precision electronic components. Single-source vulnerability concentrates in Minnesota-based foundries serving Medtronic and Abbott's neurostimulation divisions. Distribution runs through direct-to-hospital procurement channels that bypass legacy pharmaceutical wholesalers for capital equipment, while medication flows retain multi-tier distributor involvement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The neuralgia treatment market compounds as a regulatory-driven demand engine, with Medicare reimbursement expansion for spinal cord stimulation serving as the pivotal demand catalyst reshaping hospital capital allocation.
For Market Incumbents: Deepen backward integration into specialized neuromodulation foundries to secure component supply against Ireland-Minnesota concentration risk. Fortify hospital system partnerships through exclusive programming service contracts that resist unbundling trends in German and United States ambulatory markets. Prioritize FDA breakthrough therapy designation pursuit for next-generation voltage-gated calcium channel modulators to compress competitor trial timelines. For New Entrants and Emerging Players: Begin with intrathecal pump programming services in tertiary referral centers where specialist scarcity creates immediate attach opportunities for device-drug combination platforms. Target Japan's Kanto and Kansai metropolitan networks where METI infrastructure investments are expanding procurement channels for pain management technologies. Pursue EMA MDR compliance for topical lidocaine formulations to establish REACH-adherent positioning against non-compliant imports. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with device-to-pharmaceutical breadth represent the most active acquirer category in this space, seeking analgesic portfolio scale and neurostimulation manufacturing capabilities. The five-to-ten year viability window favors targets with captive foundry relationships and permanent Category I CPT code positioning. Watch Category III code transition decisions as the inflection signal determining whether hospital capital committees freeze or accelerate next-generation platform approvals.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Therapy Pursuit | Compresses Phase II-to-III timelines for neuropathic pain candidates against standard review pathways. |
| Direct-to-Hospital Procurement Channel | Bypasses pharmaceutical distributor markups for implantable pulse generator capital sales. |
| Category I CPT Code Conversion | Secures permanent reimbursement status that unlocks hospital capital committee approvals. |
| EMA MDR Compliance Investment | Creates REACH-adherent competitive moats for topical formulations in European markets. |
| Closed-Loop System Development | Absorbs market positioning from radiofrequency ablation through responsive neurostimulation technology. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture both prescription volume patterns and procurement decision dynamics. Primary engagement spanned pain medicine physicians, hospital purchasing committee chairs, biomedical engineers at neuromodulation device foundries, GPO contracts managers, and regulatory affairs leads at analgesic developers. Secondary validation drew from FDA PMA filings, EMA MDR registration databases, ClinicalTrials.gov neuropathic pain protocol listings, and CMS Medicare reimbursement coding decisions. Bottom-up prescription and procedure volume estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting approaches distributed value across product type, delivery mode, end user facility, and treatment approach dimensions. The analytical framework modeled growth trajectories across the projection horizon by calibrating therapy adoption curves to reimbursement policy shifts and regulatory approval milestones. CAGRs derived from logistic diffusion patterns for novel modalities and linear extrapolation for mature pharmaceutical segments. Key inputs included Medicare coverage determination timelines, Category III-to-I CPT code transition probabilities, and tertiary referral center capacity expansion plans.
Caveats apply where DEA scheduling revisions, single-source foundry disruptions, or Category III code stagnation could materially shift the outlook. Forecasts embed assumptions regarding reimbursement policy continuity and regulatory pathway efficiency that may not hold under administrative transition or legislative overhaul. A small set of named triggers—CPT code conversion decisions, breakthrough therapy award velocity, and foundry concentration events—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cancer Pain Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Migraine Management Market
Pain Management
Global Pain Management Market
Pain Management
Cancer Pain Management Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Visceral Pain Market
Pain Management
Global Non-Opioid Pain Patch Market
Pain Management
Global Morphine Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Cold Pain Therapy Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Lumbosacral Radicular Pain Management Market