
 Global Nausea Medicine Market | 2026-2036
Global Nausea Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nausea Medicine Market Foresight
Plant-derived phytochemicals are rebalancing active pharmaceutical ingredient sourcing as synthetic alkaloid costs fluctuate. GlaxoSmithKline plc leverages its vertically integrated supply chain for 5-HT3 receptor antagonists across oncology networks. Novartis AG anchors its position through sustained investment in intravenous formulation capacity. Merck & Co., Inc. differentiates via controlled-release transdermal platforms for motion sickness applications.
Nausea medicines comprise pharmacological agents that antagonize dopamine, histamine, serotonin, or neurokinin receptors to suppress vomiting center activation, typically formulated with bioavailability-enhancing excipients for rapid gastrointestinal absorption or sustained plasma concentration maintenance. Serotonin antagonists command the largest revenue pool due to entrenched chemotherapy protocol adoption, while transdermal delivery systems represent the fastest-expanding route of administration segment driven by pediatric and geriatric compliance advantages. Home healthcare end users are gaining share as postoperative antiemetic protocols shift toward outpatient recovery models.
The FDA enforces bioequivalence standards under 505(b)(2) submissions that shape generic entry timelines for established antiemetics, while the EMA's MDR framework imposes clinical evidence requirements on novel drug-device combination therapies. Health Canada and the PMDA maintain aligned pharmacovigilance reporting standards that influence multinational trial design and labeling harmonization. Stakeholders must monitor evolving pharmacogenomic guidance from the FDA's Clinical Pharmacogenomics Implementation Consortium, as CYP2D6 polymorphism data increasingly dictates ondansetron dosing protocols in pediatric populations.
Market Dynamics
The FDA's 505(b)(2) pathway compresses approval timelines for reformulated antiemetics while oncology clinics expand procurement budgets to match multiplying chemotherapy protocols. This regulatory acceleration intersects with hospital formulary consolidation favoring broad-spectrum serotonin antagonists.
Growth Catalysts
- Oncology Protocol Expansion:Chemotherapy administration volumes rise across United States hospital networks, driving procurement of 5-HT3 receptor antagonists for acute and delayed emesis prevention.
- 505(b)(2) Regulatory Streamlining:The FDA's abbreviated approval framework reduces clinical evidence burdens for established molecules, accelerating generic entry and price competition.
- Transdermal Delivery Innovation:Pediatric and geriatric compliance requirements pull investment toward controlled-release patch technologies for motion sickness applications.
Market Restraints
- Active Pharmaceutical Ingredient Volatility:Synthetic alkaloid cost fluctuations force reformulators toward plant-derived phytochemical sourcing with unproven scale economics.
- Supply Concentration Risk:Vertically integrated manufacturers control intravenous formulation capacity, limiting contract manufacturing access for mid-tier entrants.
- Pharmacogenomic Complexity:CYP2D6 polymorphism data requirements under FDA pediatric guidance extend labeling negotiations and dosing protocol development.
Strategic Opportunities
- Home Healthcare Penetration:Postoperative antiemetic protocols shift toward outpatient recovery models in United States ambulatory surgical centers, creating demand for patient-administered formulations.
- EMA MDR Alignment:The European Medical Device Regulation framework creates first-mover advantage for drug-device combination therapies with harmonized clinical evidence packages.
- Pediatric Formulation Gaps:Ondansetron dosing standardization for CYP2D6 variant populations remains unresolved, opening development space for pharmacogenomic-guided therapeutics.
Industry Challenges
- Formulary Access Barriers:Hospital purchasing consortiums consolidate vendor lists, squeezing mid-tier manufacturers without broad-spectrum portfolios.
- Multinational Trial Harmonization:Health Canada and PMDA pharmacovigilance alignment demands redundant safety database structures, inflating clinical program costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nausea Medicine Market |
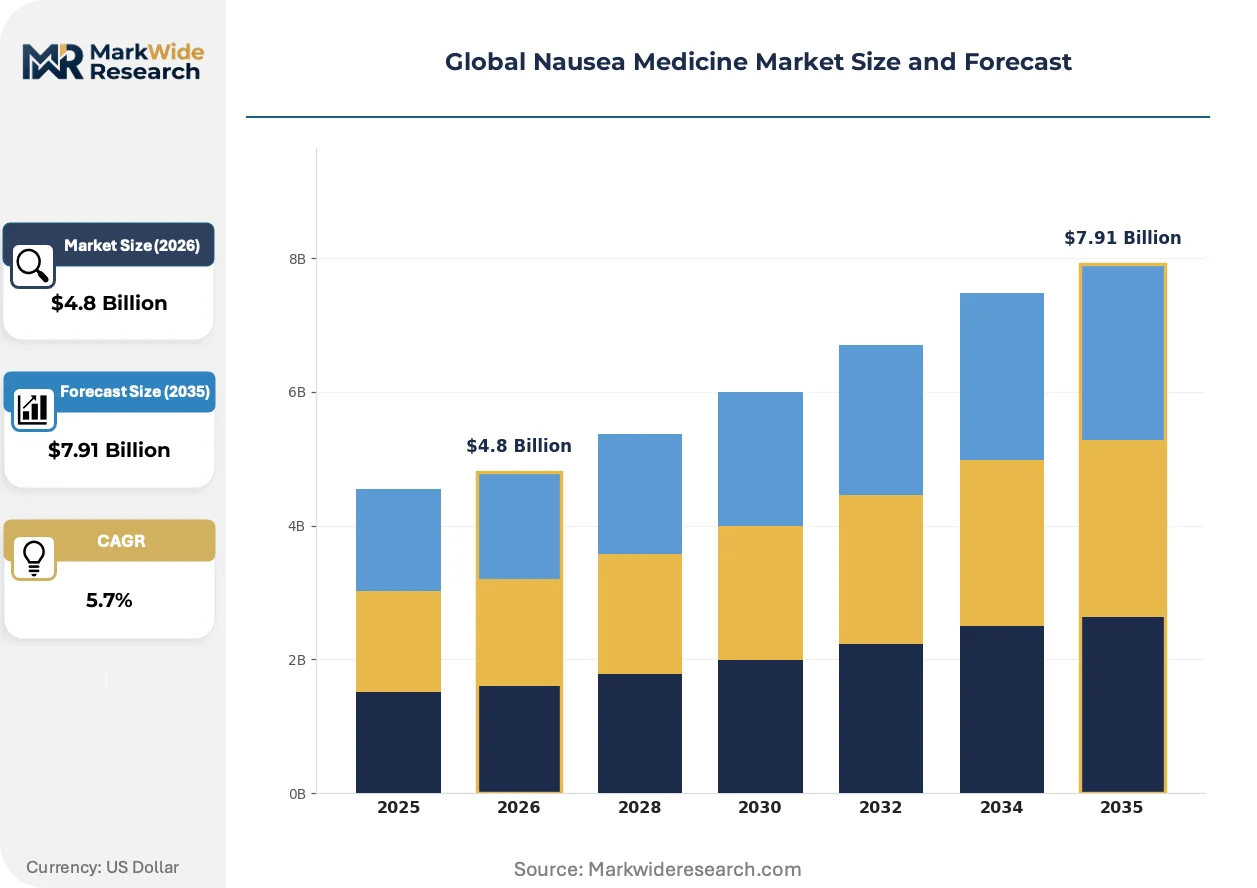
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiemetics, Antihistamines, Phenothiazines, Serotonin Antagonists, Dopamine Antagonists Therapy Area: Postoperative Nausea, Motion Sickness, Chemotherapy-Induced Nausea, Pregnancy-Related Nausea, Vertigo-Related Nausea End User: Hospitals, Clinics, Ambulatory Care Centers, Specialty Care Facilities, Home Healthcare Route of Administration: Oral, Intravenous, Intramuscular, Sublingual, Transdermal |
| Companies Covered | GlaxoSmithKline plc, Johnson & Johnson, Novartis AG, Bayer Aktiengesellschaft, AstraZeneca PLC, Merck & Co., Inc., Sanofi S.A., Helsinn Healthcare SA, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nausea Medicine Market Shifts & Advancements
Antiemetic delivery platforms are fragmenting across administration routes as patient compliance requirements diverge by age cohort and care setting. Formulation chemistry and device engineering are converging to reshape competitive positioning.
Transdermal patch technology is unifying controlled-release pharmacokinetics with motion sickness prophylaxis. Cruise operators and aviation medicine programs adopt these systems for crew and passenger populations requiring sustained plasma concentration without gastrointestinal absorption variables. The technology is unifying previously separate acute and preventive dosing regimens into single-application protocols.
REACH chemical registration requirements in Europe are tightening excipient sourcing documentation for imported formulations. Manufacturers must demonstrate supply chain transparency for bioavailability-enhancing compounds or face market withdrawal. Intravenous generic entrants targeting EMA centralized procedures face the steepest compliance cost escalations.
Postoperative recovery models now specify take-home antiemetic kits rather than inpatient-only administration. Ambulatory surgical centers in the United States negotiate bundled pricing for procedure-plus-recovery medication packages. This channel compression disadvantages traditional hospital pharmacy distributors without direct-to-patient fulfillment infrastructure.
Global Nausea Medicine Market Segmentation
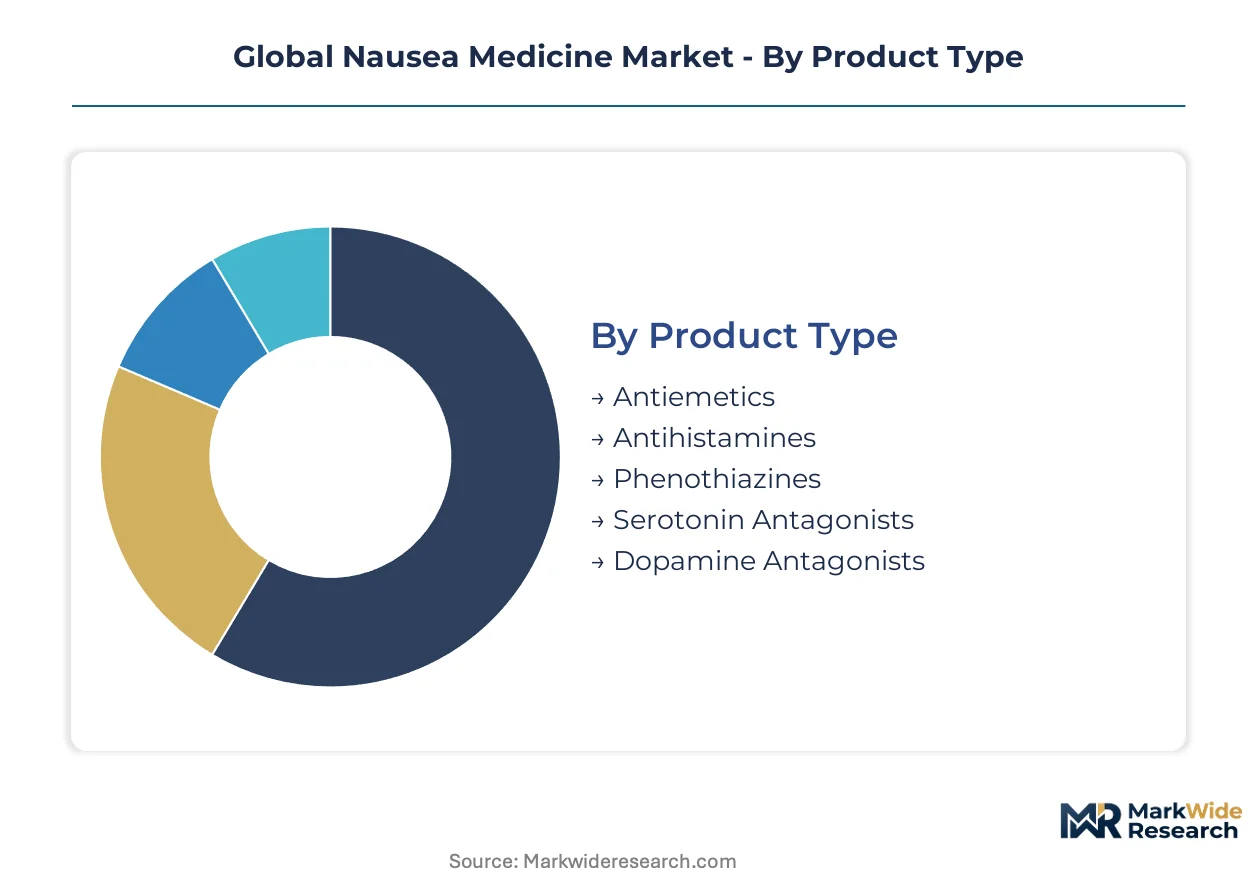
Segmentation in the nausea medicine market reveals how regulatory pathways, clinical settings, and patient demographics fragment procurement patterns. Each dimension carries distinct certification burdens and reimbursement codes that shape manufacturer positioning and formulary access.
Product Type:
FDA 505(b)(2) submissions cluster heavily among serotonin antagonists and reformulated phenothiazines, while novel antihistamine combinations face full NDA requirements. EMA centralized procedures favor intravenous dopamine antagonists with established bioequivalence packages.
- Serotonin Antagonists:These 5-HT3 receptor blockers dominate oncology procurement with intravenous and oral formulations standardized across chemotherapy protocols. United States hospital networks anchor demand as carboplatin and cisplatin administration volumes expand.
- Antiemetics:Broad-spectrum agents targeting multiple receptor classes command premium positioning in postoperative recovery kits. Ambulatory surgical centers in the United States drive procurement for same-day discharge protocols.
- Dopamine Antagonists:Metoclopramide-based formulations serve acute emesis with established generic substitution economics.
- Antihistamines:Meclizine and dimenhydrinate compounds anchor motion sickness prophylaxis for aviation and maritime applications.
- Phenothiazines:Prochlorperazine formulations retain niche positioning in emergency department settings for refractory cases.
Serotonin antagonists sit at the top of the volume ranking, with transdermal delivery formats climbing the fastest.
Therapy Area:
Reimbursement intensity varies sharply across therapy areas, with chemotherapy-induced nausea commanding the highest per-patient pharmaceutical spend and pregnancy-related applications facing the most restrictive safety labeling.
- Chemotherapy-Induced Nausea:Acute and delayed emesis prevention drives 5-HT3 antagonist and NK1 receptor blocker combination therapy. Oncology clinics in the United States, Germany, and Japan anchor procurement volumes as protocol diversity expands.
- Postoperative Nausea:Ambulatory surgery recovery models shift demand toward patient-administered oral and sublingual formats. United States ambulatory surgical centers negotiate bundled procedure-plus-medication pricing.
- Motion Sickness:Transdermal scopolamine and oral antihistamines serve aviation, maritime, and space medicine programs.
- Pregnancy-Related Nausea:Doxylamine-pyridoxine combinations face restrictive FDA pregnancy category labeling that limits formulary placement.
- Vertigo-Related Nausea:Meclizine and benzodiazepine adjuncts target otolaryngology and neurology clinic prescribing.
Chemotherapy-induced nausea generates the highest revenue concentration per treated patient, while postoperative applications are expanding most quickly through outpatient channel migration.
End User:
Procurement authority concentrates differently across settings: hospital pharmacy and therapeutics committees control broad-spectrum formularies, while home healthcare relies on prescriber discretion and retail pharmacy fulfillment.
- Hospitals:Inpatient oncology and surgical units drive intravenous serotonin antagonist consumption through centralized pharmacy compounding. United States health systems consolidate vendor lists around broad-spectrum portfolios.
- Home Healthcare:Postoperative take-home kits and chronic condition management shift demand toward oral, sublingual, and transdermal patient-administered formats. United States Medicare reimbursement codes increasingly cover these outpatient transitions.
- Clinics:Community oncology and gastroenterology practices rely on buy-and-bill models for injectable antiemetics.
- Ambulatory Care Centers:Same-day surgery facilities prioritize rapid-onset oral formulations with minimal sedation carryover.
- Specialty Care Facilities:Motion sickness clinics and vestibular rehabilitation centers prescribe transdermal and extended-release formats.
Hospitals retain the largest absolute procurement volume, with home healthcare gaining share fastest through recovery model restructuring.
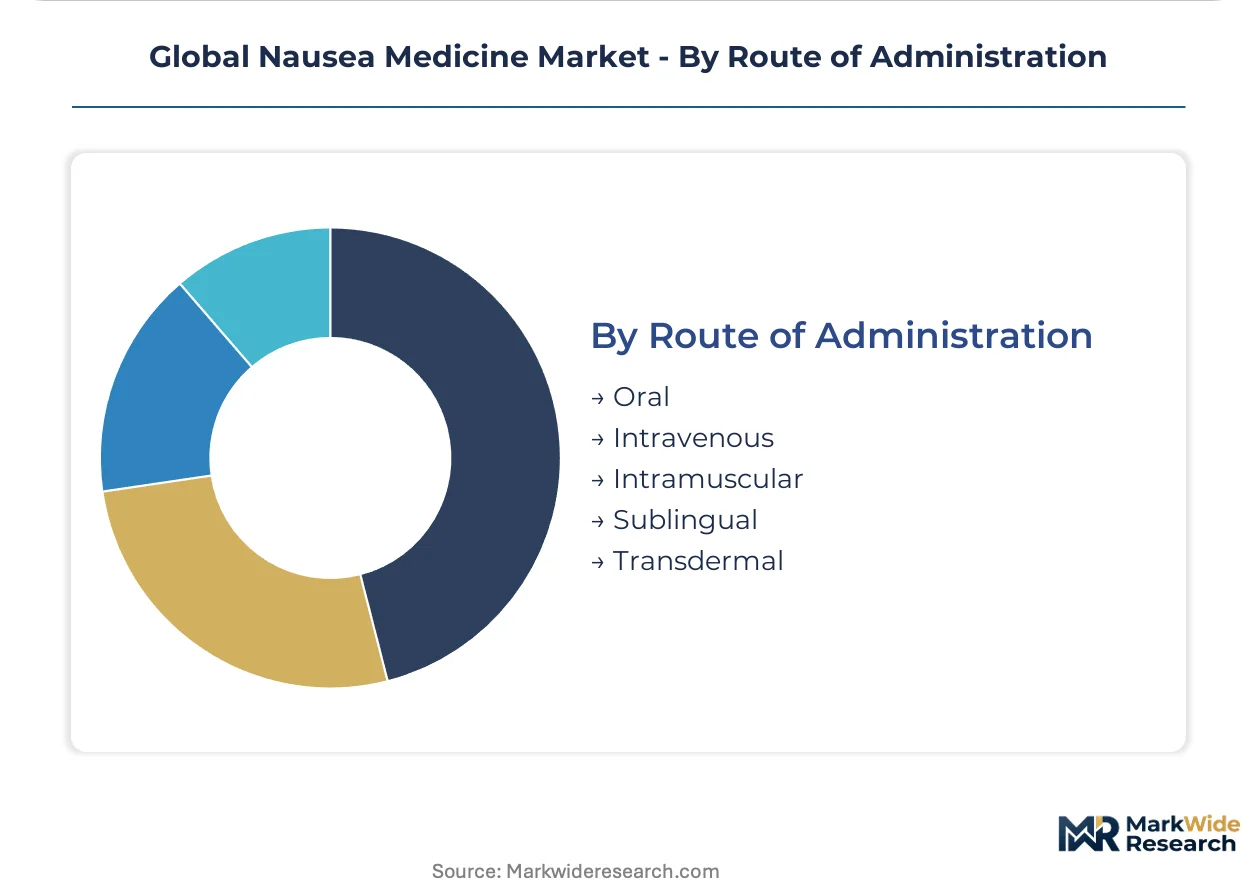
Route of Administration:
Formulation technology investments track compliance requirements by age cohort: pediatric populations drive taste-masked oral and transdermal innovation, while geriatric adherence favors patch-based sustained delivery.
- Transdermal:Scopolamine and granisetron patches unify controlled-release pharmacokinetics with motion sickness and chemotherapy prophylaxis. Cruise operators and aviation medicine programs in Norway, Singapore, and the United States adopt these for crew populations requiring sustained plasma concentration.
- Intravenous:Hospital oncology units depend on IV ondansetron and palonosetron for acute emesis control during chemotherapy administration. GlaxoSmithKline plc and Novartis AG control manufacturing capacity for these formulations.
- Oral:Rapid-disintegrating tablets and taste-masked suspensions serve pediatric and geriatric compliance requirements.
- Sublingual:Ondansetron orally disintegrating tablets target postoperative patients with swallowing difficulties or nil-per-os restrictions.
- Intramuscular:Emergency department settings retain IM prochlorperazine for refractory cases with contraindications to IV access.
Intravenous administration holds the highest current volume, with transdermal delivery demonstrating the steepest expansion trajectory across pediatric and geriatric compliance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotechnology corridor anchors pharmaceutical innovation for antiemetic development, with United States hospital networks driving procurement volumes through consolidated oncology formularies. Regulatory pathways in Germany and Japan shape multinational trial designs, while India's contract manufacturing sector expands active pharmaceutical ingredient capacity for generic entrants.
United States
Oncology clinics in Houston, Texas and New York City expand 5-HT3 antagonist procurement as carboplatin administration volumes rise across hospital networks. FDA 505(b)(2) submissions accelerate reformulation approvals for established molecules like ondansetron. The Research Triangle Park cluster in North Carolina anchors clinical pharmacogenomics research for CYP2D6-guided pediatric dosing protocols.
Germany
EMA centralized procedures in Frankfurt attract intravenous dopamine antagonist filings from manufacturers seeking EU-wide market authorization. REACH chemical registration requirements tighten excipient sourcing documentation for imported formulations. The Rhine-Main metropolitan region concentrates pharmacovigilance database operations serving multinational trial harmonization.
Japan
PMDA pharmacovigilance alignment with Health Canada standards influences safety database structures for antiemetic clinical programs. Tokyo-based oncology centers drive demand for NK1 receptor blocker combination therapies in delayed emesis prevention. The Kansai region's pharmaceutical manufacturing corridor expands controlled-release formulation capacity for transdermal patch exports.
India
CDSCO regulatory pathways enable accelerated generic entry for serotonin antagonists targeting domestic oncology expansion. Hyderabad and Ahmedabad clusters scale plant-derived phytochemical extraction for alkaloid replacement in reformulated products. Maharashtra's pharmaceutical manufacturing belt attracts backward integration investments from mid-tier API producers.
United Kingdom
MHRA post-Brexit regulatory autonomy shapes divergent bioequivalence requirements for 505(b)(2)-style abbreviated approvals. London-based hospital trusts consolidate vendor lists around broad-spectrum antiemetic portfolios. The Cambridge life sciences cluster advances taste-masked pediatric formulations for postoperative nausea applications.
Global Nausea Medicine Market Competitive Landscape
Global majors compete with regional champions across intravenous formulation capacity and transdermal delivery innovation. The vendor base stratifies into three tiers: vertically integrated pharmaceutical conglomerates controlling oncology procurement channels, mid-tier generic houses specializing in 505(b)(2) reformulations, and niche device-engineering firms advancing patch-based sustained release. Dominant competitive moves include backward integration into active pharmaceutical ingredient supply and strategic partnerships with ambulatory surgical center networks for bundled procedure-plus-medication pricing.
Within the integrated pharmaceutical tier, GlaxoSmithKline plc and Novartis AG exemplify archetypes of intravenous formulation capacity control. Merck & Co., Inc. occupies a distinct position representing transdermal platform specialization for motion sickness applications. These three entities anchor competitive dynamics across the United States, European, and Japanese oncology networks where hospital formulary consolidation favors broad-spectrum serotonin antagonist portfolios.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Novartis AG |
| Bayer Aktiengesellschaft |
| AstraZeneca PLC |
| Merck & Co., Inc. |
| Sanofi S.A. |
| Helsinn Healthcare SA |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Formulation-grade tier divergence separates intravenous oncology biologics from commodity oral generics, with that split manifesting in both procurement premiums and captive manufacturing footprints. FDA 505(b)(2) reformulators command price stability through abbreviated clinical pathways, while plant-derived API sourcing introduces cost volatility that reshapes supplier selection across the value chain.
Pricing Analysis
Active pharmaceutical ingredient cost pass-through dominates pricing dynamics, with synthetic alkaloid fluctuations forcing reformulators toward phytochemical alternatives. Three-tier pricing structure across premium intravenous formulations, standard oral generics, and economy antihistamine tablets reflects certification intensity and bioequivalence burden. Cost compression in the generic oral tier intensifies because of 505(b)(2) pathway congestion, while hospital procurement committees show lowest price sensitivity for oncology-grade serotonin antagonists with established formulary placement.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Mumbai, and Ahmedabad anchor hub-and-spoke patterns for API consolidation before final formulation. India, China, and the United States concentrate active pharmaceutical ingredient production, with synthetic alkaloid extraction drawing from controlled botanical cultivation and chemical synthesis streams. Single-source vulnerability concentrates in intravenous formulation capacity controlled by vertically integrated majors. Distribution runs through hospital pharmacy consortia and ambulatory surgical center networks with direct-to-patient fulfillment emerging in postoperative recovery channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nausea medicine market compounds steadily as chemotherapy protocol expansion across oncology networks sustains demand for 5-HT3 receptor antagonists with limited therapeutic substitution risk.
For Market Incumbents: Extend intravenous formulation capacity control through captive API sourcing for serotonin antagonists, defending against mid-tier 505(b)(2) entrants. Deepen hospital formulary relationships via bundled procedure-plus-medication pricing with ambulatory surgical center networks. Regulatory acceleration under FDA pediatric pharmacogenomics guidance threatens labeling delays for competitors without CYP2D6 data packages. For New Entrants and Emerging Players: Direct-to-patient digital pharmacy channels offer the lowest barrier entry for postoperative take-home kit penetration, bypassing consolidated hospital vendor lists. Target home healthcare reimbursement codes for oral and transdermal formats where formulary access constraints are weakest. Pediatric formulation gaps for CYP2D6-variant populations present the most penetrable white space with pharmacogenomic-guided development as the primary go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where intravenous manufacturing capacity scarcity intersects with oncology procurement concentration. The five-to-ten year viability window favors platforms with backward integration into API supply and established EMA MDR harmonization for drug-device combinations. Acquisition target archetypes include mid-tier reformulators with 505(b)(2) approval momentum and transdermal patch engineering specialists. Watch FDA pediatric guidance implementation timelines as the signal for dosing protocol standardization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | CYP2D6 pharmacogenomic studies for pediatric ondansetron dosing protocols accelerate FDA labeling negotiations. |
| Regulatory Approval Pathway | EMA MDR alignment for transdermal drug-device combinations creates first-mover advantage in European markets. |
| Manufacturing Scale-Up | Intravenous formulation capacity expansion in United States oncology networks secures formulary placement against generic entrants. |
| Pipeline Diversification | Plant-derived phytochemical sourcing reduces synthetic alkaloid cost exposure across reformulated product lines. |
| Strategic Partnership | Ambulatory surgical center bundled pricing agreements bypass traditional hospital pharmacy distribution chokepoints. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA 505(b)(2) filings, EMA centralized procedure submissions, ClinicalTrials.gov protocols, and hospital procurement database extracts. Bottom-up modeling of therapy-area demand and top-down reconciliation against manufacturer capacity disclosures ensured cross-verification.
Segment-weighting approaches anchored the analytical framework, with revenue and volume outputs disaggregated across product type, therapy area, end user, and route of administration dimensions over the projection horizon. CAGRs derived from protocol expansion trajectories in oncology and surgical settings incorporated administration volume forecasts, reimbursement code evolution, and regulatory pathway acceleration effects.
The model assumes a particular technology adoption path for transdermal delivery platforms; alternative pathways for controlled-release patch formulations would alter the outlook if pediatric compliance advantages fail to materialize. Forecasts reflect documented assumptions regarding chemotherapy protocol standardization and pharmacogenomic guidance implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Extended Release Drugs Market
Pharmaceuticals
North America Glucagon-Like Peptide-1 Agonists Market
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Global Colorectal Cancer Therapeutics Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Bone Degeneration Therapeutics Market
Pharmaceuticals
Europe Meglitinide Market
Pharmaceuticals
Global Hedgehog Pathway Inhibitors Market
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
North America Travel Vaccines Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Smoking Cessation Drugs Market
Pharmaceuticals
Opioid Analgesics Market