
 Dyspareunia Market | 2026-2036
Dyspareunia Market Size, Share, and Industry Trends Forecast 2026-2036
Dyspareunia Market Foresight
Gynecological specialist capacity is rotating toward outpatient and digital-first care models, easing access bottlenecks that previously delayed diagnosis. Pfizer Inc. leverages its established pain and women's health portfolios to sustain formulary presence across institutional channels. Duchesnay Inc. specializes in pregnancy and female sexual health, anchoring its competitive position in hormone-focused therapeutics. Novo Nordisk A/S extends its metabolic and endocrine expertise into adjacent women's health indications where hormonal dysregulation intersects with pain syndromes.
Dyspareunia refers to persistent or recurrent genital pain experienced before, during, or after sexual intercourse, typically classified as superficial or deep based on anatomical location and etiology involving vulvovaginal atrophy, pelvic floor dysfunction, or neuropathic sensitization. The condition drives clinical demand for multimodal interventions spanning pharmacological desensitization, hormonal restoration, and pelvic floor rehabilitation. Hormonal therapy dominates current prescription volume due to its mechanistic targeting of estrogen-deficiency-related mucosal changes, while telehealth services represent the fastest-growing access channel as asynchronous consultation and remote prescription fulfillment reduce geographic and stigma barriers to care. Local anesthetics occupy a mature niche for acute procedural or peri-coital symptom management with limited expansion potential.
FDA oversight of topical and transdermal drug formulations shapes bioequivalence requirements and labeling standards for dyspareunia products seeking US market entry, while EMA's MDR and REACH frameworks govern device-drug combination products and excipient safety profiles in Europe. Health Canada and Australia's TGA impose additional pharmacovigilance obligations that influence clinical trial design for multinational development programs. Stakeholders must monitor evolving reimbursement coding for telehealth-delivered sexual medicine and the integration of patient-reported outcome measures into regulatory submissions as payers and agencies converge on value-based access criteria.
Market Dynamics
Telehealth infrastructure expansion is compressing diagnostic latency and redistributing patient volume from specialist clinics to asynchronous digital platforms, fundamentally altering how dyspareunia care is accessed and reimbursed.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's abbreviated review track for topical hormonal formulations is accelerating time-to-market for mucosal restoration therapies, reducing clinical trial burden for sponsors targeting estrogen-deficiency etiologies.
- Pelvic floor physical therapy digitization:Remote biofeedback devices and app-guided exercise protocols are extending specialist reach into rural and underserved populations previously excluded from hands-on rehabilitation access.
- Germany's Diagnosis-Related Group recalibration:Updated DRG coding for sexual medicine consultations is institutionalizing reimbursement for multidisciplinary dyspareunia assessment within statutory health insurance frameworks.
Market Restraints
- Topical excipient supply concentration:European manufacturing of specialized transdermal penetration enhancers clusters in Switzerland and southern Germany, creating single-source vulnerability for formulation sponsors.
- EMA MDR device-drug classification ambiguity:Uncertainty over whether vaginal laser or energy-based devices qualify as medicinal products or medical devices is prolonging regulatory timelines and deterring capital commitment.
- Behavioral substitution by over-the-counter lubricants:Widely available silicone and hyaluronic acid-based products address superficial symptoms without prescription, limiting progression to reimbursed hormonal or neuromodulatory interventions.
Strategic Opportunities
- Japan's aging demographic tailwind:METI's prioritization of femtech solutions within its healthcare innovation strategy opens public-private partnership channels for menopause-related dyspareunia platforms targeting the world's oldest population.
- Asynchronous prescription fulfillment:Direct-to-patient pharmacy integration with telehealth platforms is eliminating the clinic visit as a care bottleneck, capturing patients who delay treatment due to stigma or geographic isolation.
- Bioidentical hormone compounding convergence:Synthesis of precision-compounded estradiol with validated delivery mechanisms is bridging the gap between standardized pharmaceuticals and personalized medicine demand in cash-pay segments.
Industry Challenges
- Pelvic medicine specialist training pipeline:Fellowship programs in female sexual pain medicine graduate fewer than fifty physicians annually across the United States, constraining clinical trial site activation and post-market surveillance capacity.
- Patient-reported outcome validation:FDA's evolving expectations for PRO instrument qualification in sexual function indications is extending endpoint development timelines and increasing eCOA platform costs for phase III programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dyspareunia Market |
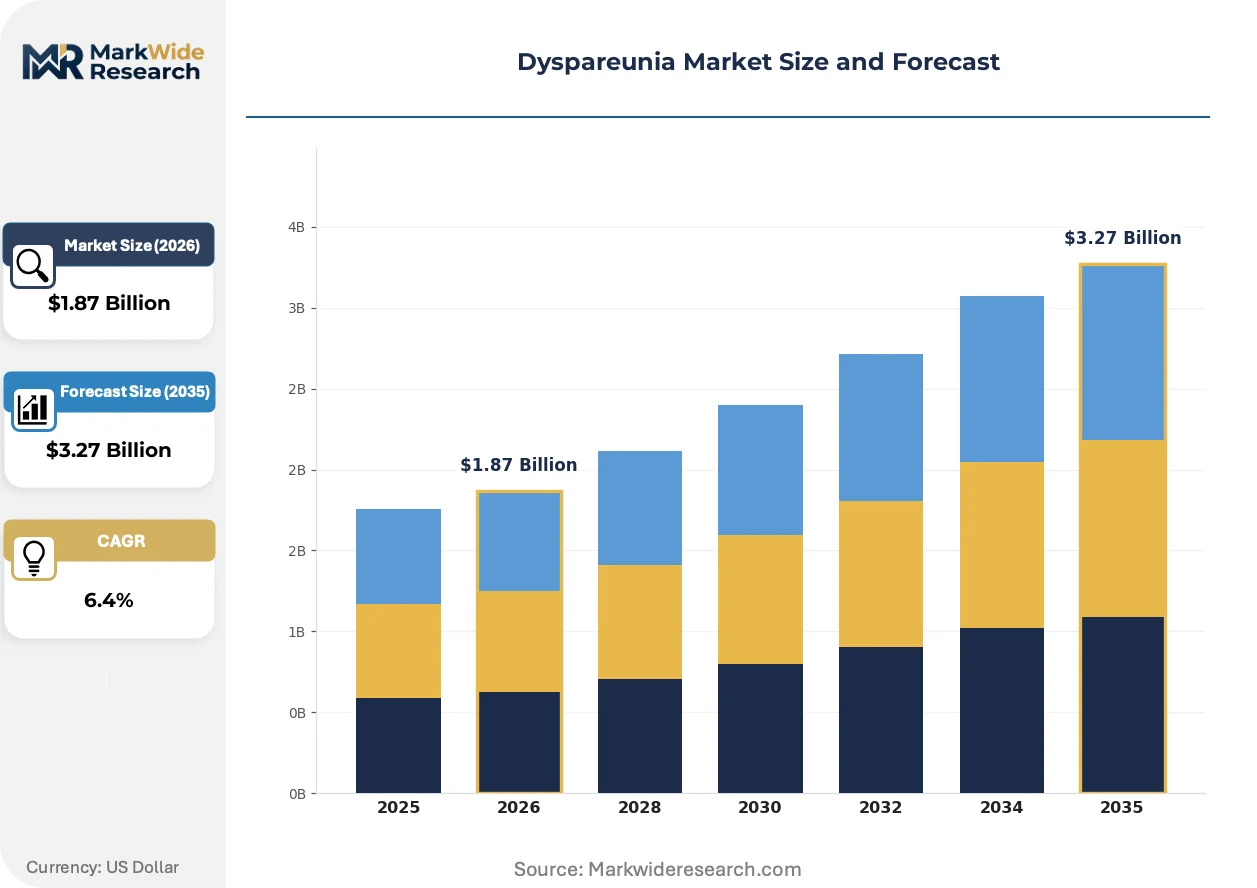
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Local Anesthetics, Hormonal Therapy, Lubricants, Antidepressants End User: Clinics, Hospitals, Telehealth Services, Homecare Delivery Mode: Injectable, Topical, Oral, Transdermal Treatment Duration: Short-term, Long-term, Acute, Preventive |
| Companies Covered | Pfizer Inc., AbbVie Inc., Duchesnay Inc., AMAG Pharmaceuticals, Inc., Amneal Pharmaceuticals LLC, TherapeuticsMD, Inc., Lupin, Myovant Sciences, Novo Nordisk A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dyspareunia Market Shifts & Advancements
Digital diagnostic triage and algorithmic symptom mapping are displacing traditional referral patterns, compressing the interval between symptom onset and specialist engagement while generating novel data assets for predictive modeling.
Low-dose vaginal estrogen micro-dosing technology is decomposing the historical trade-off between systemic exposure risk and local efficacy that constrained long-term adherence to hormonal restoration therapy. Gynecology practices in the Netherlands and Denmark are piloting these formulations for post-menopausal patients with cardiovascular comorbidities who were previously excluded from standard-dose protocols. This decomposition of the safety-efficacy frontier is expanding the addressable patient pool beyond prior risk-stratified limitations.
EMA's Medical Device Regulation recast is forcing reclassification of laser and radiofrequency devices previously marketed under lighter-touch conformity assessment routes. Manufacturers with CE-marked vulvovaginal energy devices face supplemental clinical evidence requirements to maintain market access, with German notified bodies imposing the strictest interpretation of intended purpose claims. The aesthetic medicine segment, which historically cross-sold these devices for dyspareunia indications without rigorous trial data, is retreating to purely cosmetic positioning.
Direct primary care and concierge gynecology models are unbundling sexual medicine from institutional obstetrics networks, creating dedicated subscription channels where dyspareunia management is a core retention driver rather than a referral outlier. These practices in Texas and Florida are negotiating carve-out reimbursement with regional payers for comprehensive pelvic pain management, bypassing the prior authorization friction that delayed treatment initiation in traditional fee-for-service structures.
Dyspareunia Market Segmentation
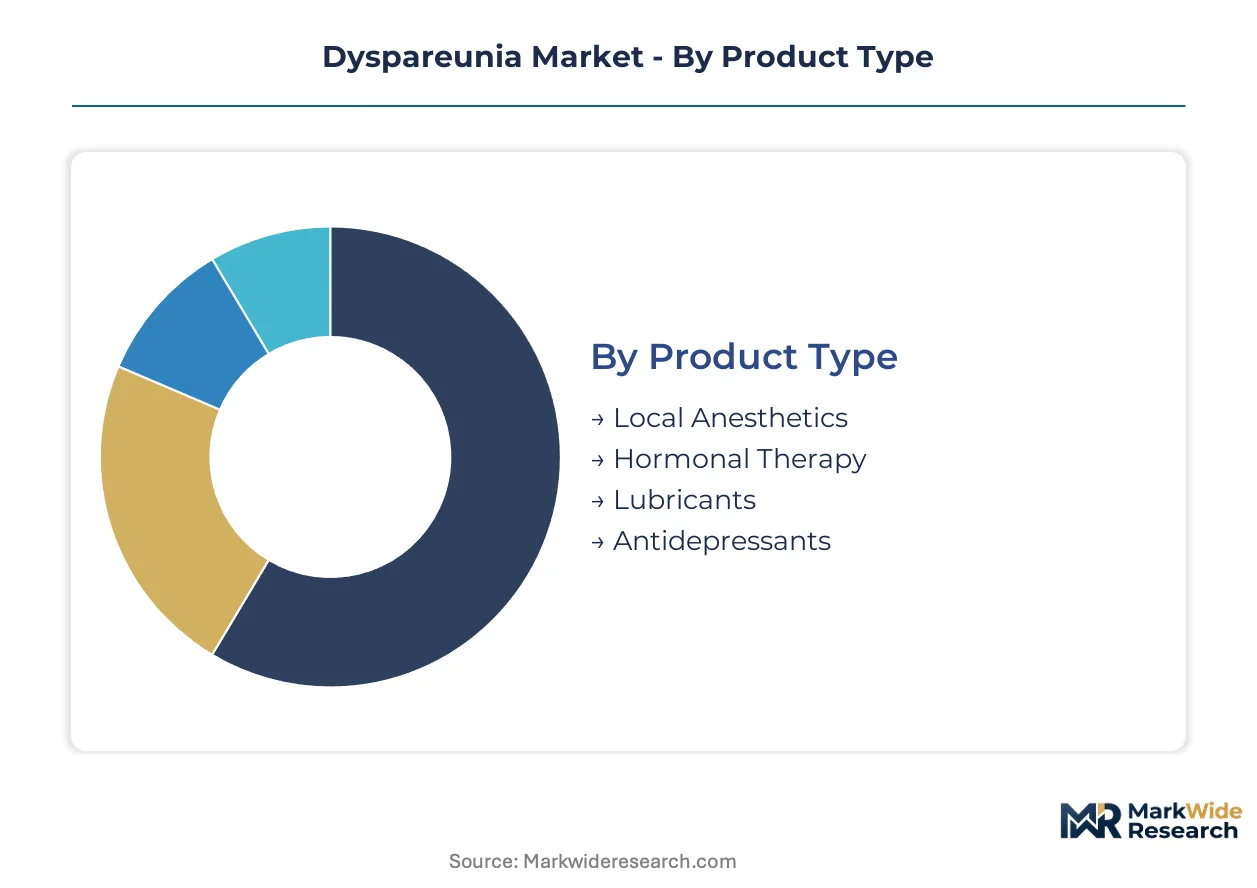
Dyspareunia treatment selection hinges on etiology mapping—whether pain originates from mucosal atrophy, pelvic floor dysfunction, or neuropathic sensitization. Segmentation reveals where hormonal restoration dominates versus where procedural or digital interventions capture patient volume. Substitution dynamics between over-the-counter and prescription channels reshape competitive boundaries across every category.
Product Type:
Hormonal therapy faces intensifying substitution pressure from silicone-based lubricants and hyaluronic acid formulations that address superficial symptoms without prescription requirements, compressing the addressable pool for reimbursed interventions.
- Hormonal Therapy:Low-dose vaginal estrogen micro-dosing decomposes the historical safety-efficacy trade-off for post-menopausal patients with cardiovascular comorbidities. Demand concentrates in the United States and Germany where reimbursement frameworks support long-term mucosal restoration protocols, though EMA bioequivalence requirements for transdermal penetration enhancers create formulation bottlenecks.
- Local Anesthetics:Lidocaine and prilocaine formulations target acute peri-coital symptom management through transient nerve desensitization. The Netherlands and Denmark pilot these for procedural pain control, yet limited expansion potential stems from narrow indication scope and OTC cannibalization of superficial pain presentations.
- Lubricants:Silicone and hyaluronic acid-based products capture first-line self-treatment, diverting patients from clinical channels.
- Antidepressants:Duloxetine and venlafaxine address centralized pain sensitization in neuropathic dyspareunia subtypes.
Hormonal therapy retains volume leadership; telehealth-integrated delivery holds the steepest expansion curve.
End User:
Cost tier stratification separates institutional reimbursement models from cash-pay digital channels, with concierge gynecology practices in Texas and Florida unbundling sexual medicine from obstetrics networks to capture premium segments.
- Telehealth Services:Asynchronous consultation and remote prescription fulfillment eliminate geographic and stigma barriers, redistributing patient volume from specialist clinics. Japan's METI femtech prioritization opens public-private partnership channels for menopause-related platforms targeting the world's oldest population.
- Clinics:Dedicated pelvic medicine practices deploy algorithmic triage and digital biofeedback to compress diagnostic latency. German DRG recalibration for sexual medicine consultations institutionalizes multidisciplinary assessment within statutory health insurance.
- Hospitals:Academic medical centers anchor clinical trial site activation for phase III hormonal programs.
- Homecare:App-guided pelvic floor exercise protocols extend specialist reach into rural populations previously excluded from hands-on rehabilitation.
Telehealth services are climbing the fastest; hospital-based care maintains procedural complexity premiums.
Delivery Mode:
Application-driven selection prioritizes local efficacy against systemic exposure risk, with topical formulations gaining share in cardiovascular-compromised populations previously excluded from standard-dose protocols.
- Topical:Vaginal creams, gels, and rings deliver estradiol directly to atrophic mucosa with minimal systemic absorption. FDA 510(k) pathway streamlining accelerates time-to-market for mucosal restoration therapies, reducing clinical trial burden for sponsors.
- Transdermal:Patches and sprays extend hormone delivery to patients with hepatic metabolism concerns, though European manufacturing concentration of penetration enhancers in Switzerland and southern Germany creates single-source vulnerability.
- Oral:Systemic antidepressants and hormonal tablets address centralized pain and endocrine dysfunction.
- Injectable:Depot formulations serve long-acting hormonal maintenance in adherence-challenged populations.
Topical delivery retains volume leadership; transdermal innovation shows the steepest expansion trajectory.
Treatment Duration:
Maturity gradients separate acute symptom suppression from preventive maintenance protocols, with long-term adherence programs capturing lifetime value in chronic atrophic presentations.
- Long-term:Continuous low-dose hormonal restoration prevents recurrent mucosal atrophy in post-menopausal patients. Germany and Japan lead prescription volume where specialist networks and reimbursement stability support multi-year adherence.
- Preventive:Pre-emptive pelvic floor rehabilitation and peri-menopausal hormone initiation target progression delay. Australia's TGA pharmacovigilance frameworks influence trial design for multinational preventive programs.
- Short-term:Limited-course local anesthetics and acute antidepressant titration address episodic presentations.
- Acute:Peri-coital interventions manage procedural or situational pain without ongoing commitment.
Long-term protocols retain volume leadership; preventive positioning gains share fastest among newly diagnosed patients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pathways for topical hormonal formulations anchor the United States as the dominant geography, while EMA device-drug classification rules and Japan's METI femtech strategy reshape competitive access across developed markets.
United States
Specialist network density and telehealth reimbursement expansion drive prescription volume for hormonal restoration therapies. FDA 510(k) streamlining for vaginal estrogen micro-dosing accelerates sponsor time-to-market. Boston and San Francisco academic medical centers anchor phase III clinical trial activation for mucosal restoration programs.
Germany
Statutory health insurance DRG recalibration institutionalizes multidisciplinary sexual medicine consultations. EMA MDR device-drug ambiguity prolongs regulatory timelines for energy-based vaginal therapies. Munich and Heidelberg clusters concentrate notified body activity and pelvic medicine specialist training capacity.
Japan
METI femtech prioritization within healthcare innovation strategy opens public-private partnership channels for menopause-related platforms. PMDA pharmacovigilance frameworks influence trial design for multinational hormonal programs. Tokyo and Osaka metropolitan areas concentrate gynecological specialist capacity and telehealth infrastructure deployment.
United Kingdom
NHS England integrated care system reforms redistribute sexual medicine referrals from hospital trusts to community-based digital platforms. MHRA post-Brexit regulatory autonomy creates divergence from EMA bioequivalence standards for transdermal formulations. London and Manchester anchor private concierge gynecology models unbundling from obstetrics networks.
Australia
TGA pharmacovigilance obligations extend endpoint development timelines for preventive hormonal protocols targeting peri-menopausal initiation. Rural access gaps drive demand for asynchronous telehealth prescription fulfillment. Sydney and Melbourne academic centers concentrate pelvic floor rehabilitation research and remote biofeedback device validation.
Dyspareunia Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated pharmaceutical portfolios commanding formulary presence against fragmented device and digital entrants. Large-cap diversified players leverage pain and women's health cross-selling infrastructure, while mid-scale hormone-focused specialists defend niche positions through regulatory exclusivity and compounding relationships. Two competitive moves dominate: M&A to capture digital diagnostic platforms and strategic partnerships with telehealth providers to secure prescription fulfillment channels.
Within the integrated pharmaceutical tier, Pfizer Inc. and Novo Nordisk A/S occupy positions anchored by metabolic and endocrine expertise extending into adjacent women's health indications. Duchesnay Inc. exemplifies the hormone-focused specialist archetype, with its Inc. suffix indicating North American incorporation and concentration in pregnancy and female sexual health segments. These three entities collectively represent the span from diversified portfolio breadth to targeted therapeutic depth that characterizes competitive positioning in reimbursed dyspareunia interventions.
| Leading Market Players |
|---|
| Pfizer Inc. |
| AbbVie Inc. |
| Duchesnay Inc. |
| AMAG Pharmaceuticals, Inc. |
| Amneal Pharmaceuticals LLC |
| TherapeuticsMD, Inc. |
| Lupin |
| Myovant Sciences |
| Novo Nordisk A/S |
| Others |
Supply & Pricing Matrix
Silicone-based lubricant substitution for prescription hormonal therapies simultaneously redraws manufacturing geography toward consumer chemical hubs and compresses margin structures for reimbursed pharmaceutical tiers. This displacement forces sponsors to defend value through bioequivalence differentiation and telehealth service bundling.
Pricing Analysis
Price spreads between United States and German markets for vaginal estrogen formulations exceed those for transdermal alternatives due to FDA 510(k) pathway efficiency and EMA penetration-enhancer bottlenecks. Three-tier pricing structure across premium micro-dosed formulations, standard vaginal creams, and economy oral generics separates patient risk profiles and reimbursement tiers. Pricing pressure stems from OTC lubricant substitution in superficial dyspareunia presentations. Cash-pay telehealth channels exhibit lowest price sensitivity; statutory insurance segments in Germany and Japan face tightening formulary scrutiny.
Supply Chain Analysis
Swiss and southern German manufacturing clusters for specialized transdermal penetration enhancers create single-source chokepoints for European formulation sponsors. Active pharmaceutical ingredient production for estradiol derivatives concentrates in India, China, and the United States; device-drug combination products draw from German laser component suppliers and Japanese precision electronics. Supply chain risk centers on EMA MDR reclassification uncertainty for energy-based vaginal devices. Distribution runs through hospital procurement networks in reimbursed segments and direct-to-patient pharmacy platforms in cash-pay channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dyspareunia management represents a service-attach opportunity where asynchronous telehealth consultation and remote prescription fulfillment expand faster than pharmaceutical product sales alone.
For Market Incumbents: Shield formulary position by deepening vertical integration into telehealth prescription fulfillment platforms and securing exclusive agreements with pelvic floor biofeedback device manufacturers. FDA 510(k) pathway streamlining offers a lever to accelerate generic defense through differentiated micro-dosing formulations. For New Entrants and Emerging Players: Lead with asynchronous diagnostic triage tools targeting rural and stigma-delayed patient populations in Australia and Japan's aging prefectures. Japan's METI femtech prioritization provides the most penetrable public-private partnership channel for menopause-related platforms. For Investors and Strategic Acquirers: EMA MDR device-drug classification resolution reshapes the acquisition landscape for energy-based vaginal therapy manufacturers awaiting regulatory clarity. Long-term viability favors platforms combining pharmaceutical intervention with digital adherence monitoring. The signal to watch is German notified body precedent on laser device reclassification.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Asynchronous consultation eliminates geographic and stigma barriers to specialist access. |
| FDA 510(k) Pathway Streamlining | Abbreviated review accelerates time-to-market for vaginal estrogen micro-dosing therapies. |
| Pelvic Floor Biofeedback Partnership | Remote device validation extends specialist reach into underserved rural populations. |
| EMA MDR Reclassification Strategy | Clinical evidence investment preserves market access for energy-based vaginal devices. |
| Bioidentical Hormone Compounding Convergence | Precision-compounded estradiol bridges standardized pharmaceuticals and personalized medicine demand. |
Research Methodology
Initial hypotheses were tested against primary input from gynecology practice administrators, formulary directors at US payers, EMA regulatory affairs consultants, and pelvic floor physical therapy clinic operators and refined through secondary validation against FDA 510(k) filings, EMA MDR guidance documents, ClinicalTrials.gov protocol registries, and German statutory health insurance DRG coding updates. Bottom-up prescription volume modeling and top-down epidemiological prevalence estimates were triangulated to anchor market sizing.
Variance-decomposition across etiology segments, treatment duration protocols, and delivery mode preferences structured the analytical framework. CAGRs were derived from log-linear trend fitting across the projection horizon. Modeled inputs included patient-reported outcome instrument adoption rates, telehealth reimbursement code expansion, and specialist fellowship graduation volumes.
Forecasts assume regulatory continuity in FDA 510(k) review standards and EMA MDR implementation timelines; material policy shifts would require re-modeling of sponsor time-to-market assumptions. Practitioners should keep alternative scenarios live as PMDA pharmacovigilance frameworks and Health Canada telehealth coding evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cold Pain Therapy Market
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Visceral Pain Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Ketorolac Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Global Morphine Market
Pain Management
Cluster Headache Market
Pain Management
OTC Painkiller Market
Pain Management
Spine Pain Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Bone Pain Treatment Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Global Analgesic Infusion Pumps Market